
 Lumbar Puncture Trays and Needles Market | 2026-2036
Lumbar Puncture Trays and Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Lumbar Puncture Trays and Needles Market Intelligence
Specialized neuraxial anesthesia training among certified nurse anesthetists is redrawing the competitive landscape for lumbar puncture tray suppliers. Becton Dickinson leverages its vertically integrated needle manufacturing to sustain cost advantages across hospital purchasing contracts. Cardinal Health competes through extensive distribution networks that anchor same-day delivery capabilities for emergency departments.
Lumbar puncture trays and needles comprise sterile-configured instrument sets and spinal access devices designed for cerebrospinal fluid extraction or intrathecal drug delivery, typically featuring 20-22 gauge pencil-point or cutting-tip needles with introducer stylets and manometers. Single-use trays dominate hospital procurement due to infection control protocols, while specialty needles command premium positioning among academic medical centers performing complex neuraxial anesthesia. Stainless steel needle segments maintain structural leadership despite growing interest in non-latex tray configurations addressing latex-sensitive patient populations.
FDA 510(k) clearance pathways and ISO 80369 small-bore connector standards govern product design and interoperability requirements for U.S. market participants. The EU MDR's enhanced clinical evaluation obligations for Class IIa spinal devices are reshaping documentation burdens for tray and needle exporters targeting European health systems. Stakeholders must monitor evolving CMS reimbursement coding for lumbar puncture procedures alongside state-level scope-of-practice expansions permitting advanced practice providers to perform independent spinal taps.
Market Dynamics
Neuraxial anesthesia training expansion among advanced practice providers is redrawing procedural authority boundaries, concentrating tray procurement decisions within hospital anesthesia departments rather than general surgery supply chains.
Growth Catalysts
- EU MDR clinical evaluation mandates:Class IIa spinal device documentation requirements are filtering out marginal European suppliers, consolidating procurement toward manufacturers with robust biocompatibility testing infrastructure.
- Tertiary hospital neurology expansion:Academic medical centers are embedding lumbar puncture protocols into multiple sclerosis and autoimmune encephalitis diagnostic pathways, embedding recurring tray demand into standardized care bundles.
- Pencil-point needle technology:Atraumatic tip designs are reducing post-dural puncture headache incidence, accelerating replacement cycles for legacy cutting-tip inventories across emergency departments.
Market Restraints
- Stainless steel price volatility:Needle cannula raw material exposure to nickel and chromium commodity swings compresses margin predictability for manufacturers without captive metallurgy contracts.
- FDA 510(k) pathway congestion:Biocompatibility documentation backlogs are extending clearance timelines for novel tray configurations, freezing product pipeline velocity for mid-tier developers.
- Regional supplier concentration:German and Japanese precision needle manufacturers control high-gauge spinal access device production, creating single-source vulnerability for academic medical centers requiring 25-27 gauge specialty sets.
Strategic Opportunities
- Non-latex tray configurations:Latex-sensitive patient population protocols are opening premium positioning for silicone-component tray assemblers serving pediatric and immunocompromised segments.
- Same-day surgical center expansion:Ambulatory settings performing intrathecal chemotherapy administration are creating decentralized demand nodes outside traditional hospital purchasing cooperatives.
- ISO 80369-6 small-bore connector harmonization:Neuraxial-specific connector standardization is enabling cross-manifold compatibility investments that reduce institutional switching costs.
Industry Challenges
- CRNA neuraxial certification bottlenecks:Specialized lumbar puncture training program capacity constraints are limiting procedure volume growth despite expanded scope-of-practice legislation.
- Tray sterilization validation complexity:Ethylene oxide alternative compliance timelines for pre-packaged instrument sets are requiring capital-intensive irradiation infrastructure retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lumbar Puncture Trays and Needles Market |
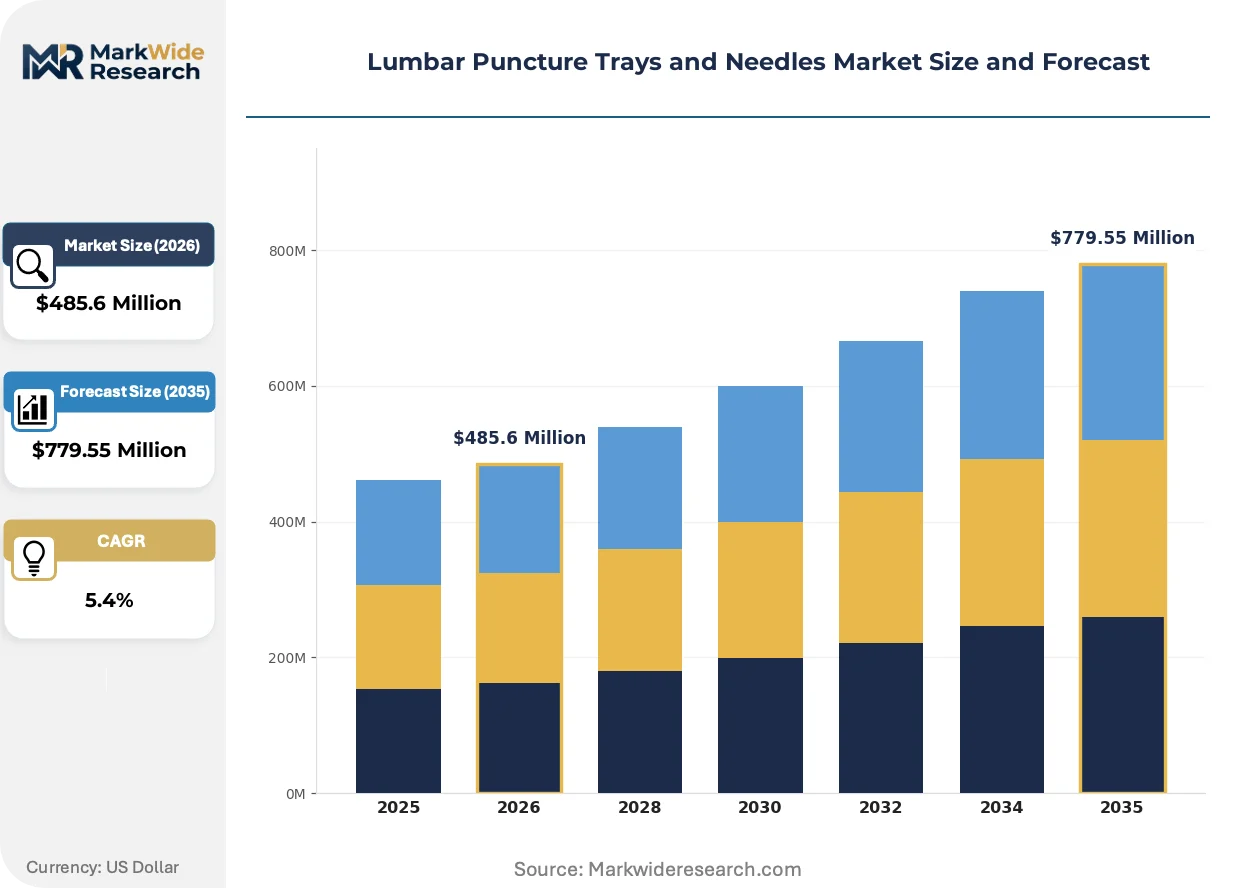
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $779.55 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-use Trays, Reusable Trays, Standard Needles, Specialty Needles Material: Plastic, Stainless Steel, Latex, Non-latex End User: Hospitals, Clinics, Diagnostic Laboratories, Home Care Application: Diagnostic Testing, Anesthesia, Chemotherapy, Research |
| Companies Covered | ICU Medical, Avanos Medical, Becton Dickinson, Busse Hospital Disposables, Rocket Medical, Cardinal Health, Pajunk Medical, Medline Industries, Teleflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lumbar Puncture Trays and Needles Market Strategic Shifts & Innovations
Ultrasound-guided neuraxial access is compressing technical failure rates and procedural time, embedding imaging compatibility requirements into next-generation needle design specifications.
Integrated manometer-needle systems are miniaturizing cerebrospinal fluid pressure monitoring into single-handled devices. Tertiary hospital anesthesia departments are piloting these configurations for obese patient populations where landmark-based access fails. This convergence is compressing tray component count and sterilization validation burdens for manufacturers with integrated design capabilities.
The FDA's updated 510(k) biocompatibility documentation requirements are extending premarket notification timelines for spinal needle modifications. Manufacturers are responding by front-loading cytotoxicity and sensitization testing into early-stage product development rather than terminal validation phases. Small developers without in-house toxicology expertise are facing partnership or acquisition pressure from larger device firms.
Hospital purchasing cooperatives are consolidating lumbar puncture tray procurement into anesthesia-centric category management, displacing general surgery supply chain ownership. Academic medical centers with high neuraxial anesthesia volumes are negotiating direct manufacturer relationships that bypass distributor markups. This concentration is most visible in the United States, where group purchasing organization consolidation has reduced independent hospital negotiating leverage.
Lumbar Puncture Trays and Needles Market Segmentation
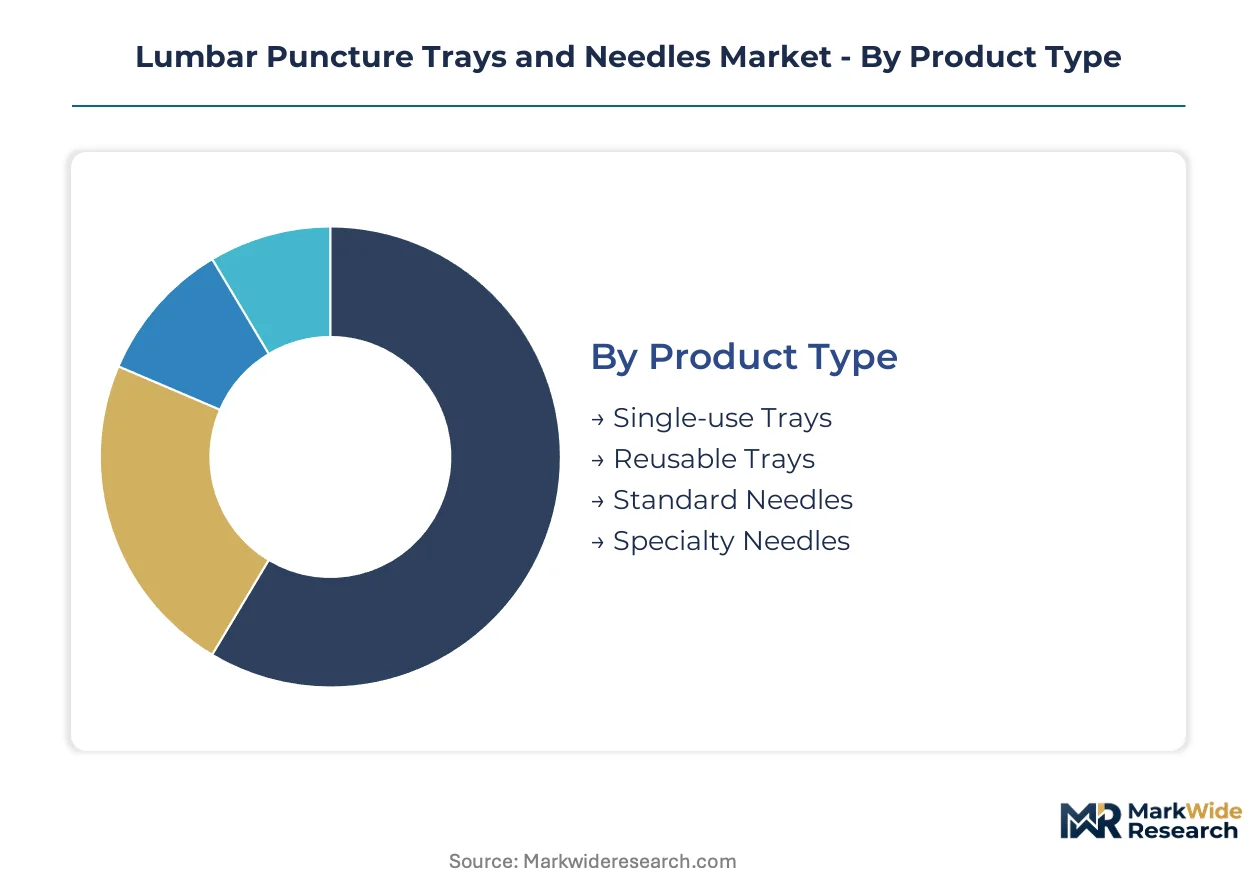
Segmentation in lumbar puncture trays and needles reveals distinct margin architectures across product configurations, with infection control mandates and procedural specialization driving purchasing behavior. Understanding these divides helps manufacturers align R&D investment with where hospitals actually concentrate procurement authority.
Product Type:
Margin pools concentrate in pre-configured sterile sets where infection control liability and labor cost reduction justify premium positioning over component sourcing.
- Single-use Trays:Pre-packaged sterile configurations containing needles, manometers, collection tubes, and drapes eliminate reprocessing labor and liability. Tertiary hospital anesthesia departments in the United States embed these into neuraxial anesthesia bundles, with FDA 510(k) clearance serving as a procurement gatekeeper that filters out unvalidated suppliers.
- Specialty Needles:Pencil-point atraumatic tip designs and ultra-high-gauge configurations (25-27G) command pricing premiums for post-dural puncture headache prevention. Academic medical centers performing complex spinal anesthesia on obese populations drive specification requirements here, with German and Japanese precision manufacturers controlling supply.
- Standard Needles:Cutting-tip Quincke designs in 20-22G sizes serve emergency departments and general diagnostic applications where cost sensitivity dominates.
- Reusable Trays:Metal instrument sets requiring sterilization infrastructure persist in resource-constrained settings and select research environments.
Single-use trays hold installed capacity. Specialty needles are rotating up the share rankings.
Material:
Raw material selection traces directly to patient population risk profiles and sterilization validation requirements.
- Stainless Steel:Nickel-chromium alloy cannulas provide structural rigidity for needle insertion torque and stylet compatibility. Hospital procurement contracts specify metallurgical certificates due to nickel sensitivity protocols, with commodity price volatility compressing margin predictability for manufacturers lacking captive supply agreements.
- Non-latex:Silicone and synthetic elastomer components address pediatric, immunocompromised, and repeat-procedure patient populations where latex sensitization risk triggers institutional liability concerns. This segment expands most quickly as hospital protocols harden around allergy documentation.
- Plastic:Polypropylene tray bodies and collection vessels balance cost with disposability requirements.
- Latex:Legacy rubber components face phased elimination across EU and US health systems.
Stainless steel dominates unit economics. Non-latex configurations are climbing the fastest.
End User:
Procurement authority concentrates where procedural volume and specialization create category management leverage.
- Hospitals:Tertiary academic centers and community hospital systems generate the bulk of tray demand through anesthesia department purchasing. Group purchasing organization consolidation in the United States has shifted negotiation power toward standardized bundle contracts.
- Diagnostic Laboratories:Cerebrospinal fluid analysis outsourcing creates recurring demand for sterile collection systems, with reference labs in Germany and the United States driving volume.
- Clinics:Outpatient neurology and pain management practices perform lumbar punctures for multiple sclerosis monitoring and intrathecal drug delivery.
- Home Care:Limited intrathecal chemotherapy administration in select markets requires specialized training and regulatory waivers.
Hospitals anchor volume commitments. Diagnostic laboratories are gaining procurement sophistication.
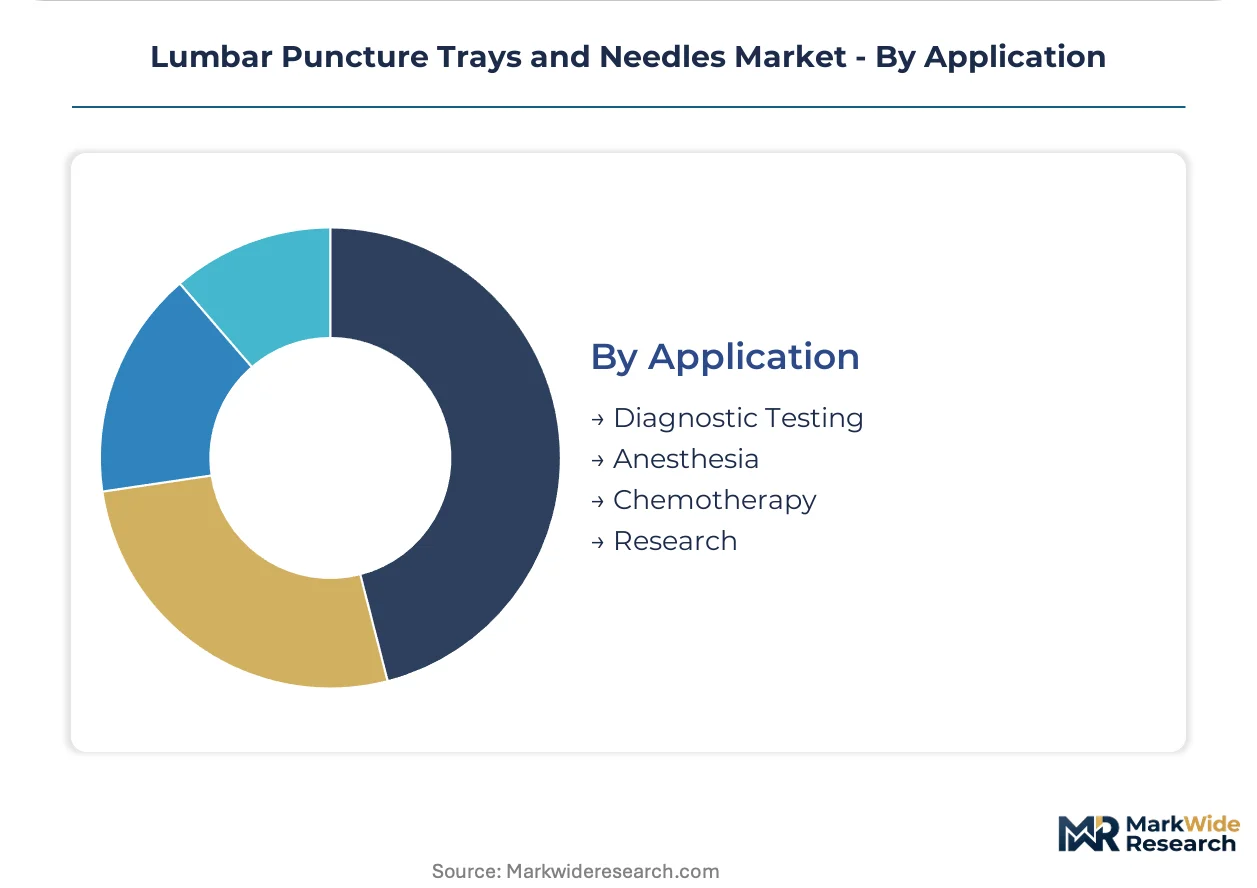
Application:
Clinical indication determines needle specification complexity and tray component count.
- Diagnostic Testing:Cerebrospinal fluid extraction for infectious disease, autoimmune, and oncological evaluation requires manometer integration and multi-chamber collection. Neurology department expansion for multiple sclerosis protocols in US academic centers concentrates demand here.
- Anesthesia:Neuraxial block placement for obstetric and surgical applications demands atraumatic tip designs and introducer needle systems. CRNA scope-of-practice expansion is redrawing purchasing authority toward anesthesia department supply chains.
- Chemotherapy:Intrathecal drug delivery for central nervous system lymphoma and prophylaxis requires specialized access protocols and pharmacy coordination.
- Research:Academic and pharmaceutical clinical trials generate irregular, specification-intensive demand.
Diagnostic testing holds procedure frequency. Anesthesia is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor United States procurement standards, while EU MDR documentation burdens reshape European supplier participation. German precision manufacturers and Japanese high-gauge needle specialists concentrate regional production capabilities.
United States
Tertiary hospital neurology departments and CRNA scope-of-practice expansion drive procedure volume acceleration. CMS reimbursement coding updates for lumbar puncture procedures influence hospital purchasing cooperative negotiations. The Boston-Cambridge medical corridor anchors academic medical center demand for specialty atraumatic needle configurations.
Germany
Diagnostic laboratory outsourcing for cerebrospinal fluid analysis creates recurring sterile collection system demand. EU MDR Class IIa clinical evaluation obligations filter marginal suppliers from European health system procurement. The Baden-Württemberg precision engineering cluster concentrates high-gauge spinal access device manufacturing for academic export markets.
Japan
Aging demographics and multiple sclerosis diagnostic protocol expansion accelerate hospital lumbar puncture frequency. PMDA medical device quality management system requirements govern domestic manufacturer participation. The Osaka-Kobe medical device production corridor specializes in ultra-high-gauge needle fabrication for neuraxial anesthesia applications.
United Kingdom
NHS procurement consolidation into anesthesia-centric category management shifts tray purchasing authority from general surgery supply chains. MHRA post-Brexit regulatory alignment with EU MDR standards maintains documentation burdens for spinal device exporters. The Oxford-Cambridge-London research triangle generates specification-intensive clinical trial demand for integrated manometer-needle systems.
India
CDSCO medical device registration requirements for Class B spinal access devices are formalizing import substitution pressures. Government hospital neurology department expansion for infectious disease diagnostics concentrates tray demand in metropolitan tertiary centers. The Hyderabad-Bangalore medical technology corridor attracts contract manufacturing investments from global needle suppliers seeking cost-competitive production bases.
Lumbar Puncture Trays and Needles Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the lumbar puncture trays and needles market. Consolidated procurement through United States group purchasing organizations favors manufacturers with vertically integrated needle production and established FDA 510(k) clearance portfolios. Three archetypes dominate: diversified medical device conglomerates with anesthesia department relationships, precision needle specialists with German or Japanese metallurgy heritage, and distribution-anchored suppliers competing through same-day delivery capabilities. Competitive moves concentrate on direct manufacturer contracting with academic medical centers and irradiation infrastructure investments for ethylene oxide sterilization alternatives.
Among diversified medical device conglomerates, Becton Dickinson and Cardinal Health exemplify contrasting positioning strategies. Becton Dickinson anchors the technology-intensive tier through captive needle manufacturing capabilities that sustain cost advantages across hospital purchasing contracts. Cardinal Health occupies the distribution-anchored position, leveraging extensive logistics networks to secure emergency department same-day delivery commitments. ICU Medical represents the mid-tier specialist archetype, competing through pre-configured tray configurations that reduce institutional sterilization validation burdens. These three companies illustrate how FDA clearance depth, manufacturing integration, and supply chain velocity separate competitive positions in anesthesia department procurement decisions.
| Leading Market Players |
|---|
| ICU Medical |
| Avanos Medical |
| Becton Dickinson |
| Busse Hospital Disposables |
| Rocket Medical |
| Cardinal Health |
| Pajunk Medical |
| Medline Industries |
| Teleflex |
| Others |
Cost & Logistics Intelligence
FDA 510(k) clearance pathways gate both supplier qualification and price differentiation in lumbar puncture trays and needles, creating a bifurcated market where cleared manufacturers command premium positioning over unvalidated competitors while hospital purchasing cooperatives exploit documentation burdens to compress margins on standard configurations.
Pricing Analysis
Price spreads between United States and European hospital systems reach multiples for identical tray configurations due to reimbursement coding disparities and GPO consolidation effects. Pricing stratifies across premium, standard, and economy tiers, with FDA 510(k) certification grade and volume scale driving differentiation. Cost compression in standard cutting-tip needles is intensifying because of stainless steel commodity exposure and distributor markup competition. Emergency departments exhibit highest price sensitivity, while academic medical centers performing complex neuraxial anesthesia show lowest sensitivity due to outcome prioritization.
Supply Chain Analysis
Inventory lead times for 25-27 gauge specialty needles extend substantially due to single-source dependencies on German and Japanese precision manufacturers. Supply concentrates in the United States for tray assembly, Germany for high-gauge cannula fabrication, and Japan for atraumatic tip metallurgy. Raw material draws from nickel-chromium alloy suppliers, silicone elastomer producers, and polypropylene resin manufacturers. Single-source vulnerability for ultra-high-gauge spinal access devices creates structural risk. Distribution runs through hospital purchasing cooperatives and anesthesia-centric category managers rather than general surgery supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as pencil-point needle technology penetrates emergency department inventories and CRNA scope-of-practice legislation unlocks procedural volume growth previously constrained by physician-only access protocols.
For Market Incumbents: Fortify captive needle manufacturing capabilities to defend against German and Japanese precision specialists encroaching on high-margin atraumatic tip segments. Deepen backward integration into nickel-chromium alloy supply to buffer stainless steel price volatility. Anchor hospital purchasing cooperative relationships through same-day delivery infrastructure investments that emerging entrants cannot replicate.
For New Entrants and Emerging Players: Differentiate on non-latex tray configurations targeting pediatric and immunocompromised segments where institutional liability protocols create procurement stickiness. Penetrate ambulatory surgical centers performing intrathecal chemotherapy administration, a white-space node outside consolidated hospital purchasing. Pursue direct contracting with academic medical centers seeking to bypass distributor markups.
For Investors and Strategic Acquirers: EU MDR Class IIa clinical evaluation mandates reshape the acquisition landscape toward manufacturers with pre-built biocompatibility testing infrastructure. Target mid-tier tray assemblers lacking in-house toxicology expertise but holding FDA 510(k) clearance portfolios. Watch for irradiation infrastructure retrofit completion as signal of sterilization validation readiness and ethylene oxide alternative compliance.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Biocompatibility documentation depth determines hospital procurement eligibility and premium tier positioning. |
| CE Marking Pathway | EU MDR clinical evaluation obligations filter marginal suppliers from European health system access. |
| Hospital System Partnership | Direct manufacturer relationships with academic medical centers bypass distributor markup compression. |
| Backward Integration into Metallurgy | Captive nickel-chromium alloy supply insulates margin predictability from commodity price swings. |
| Reimbursement Strategy | CMS coding alignment for lumbar puncture procedures shapes GPO negotiation leverage and volume commitments. |
Research Approach
A spread of perspectives from anesthesia department supply chain managers, CRNA training program directors, hospital GPO contract specialists, and biomedical engineering procurement leads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, CMS Medicare reimbursement filings, EU MDR clinical evaluation documentation, and hospital purchasing cooperative contract records. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market sizing.
Segmentation dimensions modeled include product type hierarchy, material composition tiers, end-user procurement authority structures, and application-specific needle complexity grades across the projection horizon. CAGRs derived from procedure frequency trajectories, replacement cycle dynamics for legacy cutting-tip inventories, and penetration curves for pencil-point atraumatic designs. Forecast inputs incorporated CRNA certification program capacity constraints and tertiary hospital neurology department expansion rates.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) pathway velocity, stable stainless steel commodity pricing, and unimpaired EU MDR supplier participation would require recalibration. Forecasts reflect documented assumptions regarding procedure volume drivers and regulatory clearance timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
China Hospital Supplies Market
Medical Supplies
Nursing Breast Pads Market
Medical Supplies
Global Hemostats Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Nitrile Gloves Market
Medical Supplies
Skin Tac Market
Medical Supplies
South America Syringe Market
Medical Supplies
Global Disposable Syringes Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Global Burn Ointment Market
Medical Supplies
Compression Garments and Stockings Market
Medical Supplies
Flexible Packaging for Healthcare Market
Medical Supplies
Global Chromatography Syringes Market
Medical Supplies
Healthcare Cleanroom Consumables Market
Medical Supplies
Asia-Pacific N95 Mask Market
Medical Supplies
Syringes and Cannulas Market