
 Prefillable Inhalers Market | 2026-2036
Prefillable Inhalers Market Size, Share, and Industry Trends Forecast 2026-2036
Prefillable Inhalers Market Analytics
MDR and the EU AI Act are rebalancing the cost-of-entry calculus for prefillable inhaler manufacturers seeking European market access. GlaxoSmithKline plc leverages its vertically integrated respiratory portfolio to sustain manufacturing scale across multiple device platforms. AstraZeneca anchors its position through deep specialization in biologic-compatible inhaler architectures. Boehringer Ingelheim competes by controlling distribution channels across hospital and pharmacy networks in regulated European markets.
A prefillable inhaler is a drug-device combination product comprising a pre-metered reservoir, actuation mechanism, and patient-interface designed for single or multi-dose pulmonary delivery of aerosolized or powdered APIs, typically manufactured through precision molding, laser welding, and siliconization processes to ensure dose uniformity and particle size distribution within specific aerodynamic diameter ranges. Its primary commercial purpose is to enable consistent, reproducible drug deposition in the lower respiratory tract for chronic disease management. Metered Dose Inhalers dominate current volume due to established clinical familiarity and broad formulary inclusion, while Smart Inhalers represent the fastest-expanding technology segment as connected sensors enable adherence monitoring and real-world evidence generation. Dry Powder Inhalers occupy a mature but stable position where margin pools concentrate in patented particle engineering and device-reservoir compatibility.
FDA, EMA, and ISO 20072 collectively govern device performance validation, human factors testing, and quality management systems for prefillable inhalers, with FDA's evolving guidance on combination products and EMA's Medical Device Regulation convergence creating layered compliance obligations that shape R&D prioritization and market access timelines. Stakeholders must monitor how emerging pharmacovigilance requirements for connected devices will reshape post-market surveillance investments and partnership structures across the value chain.
Market Dynamics
Smart inhaler sensor integration is restructuring competitive advantage around real-world evidence generation, forcing manufacturers to reallocate R&D expenditure toward connected drug-device combinations that satisfy FDA combination product guidance and EMA MDR convergence requirements.
Growth Catalysts
- Aging respiratory patient demographics:Japan, Germany, and the United States face expanding chronic obstructive pulmonary disease and asthma prevalence that drives clinical uptake of prefillable inhaler systems in home care settings.
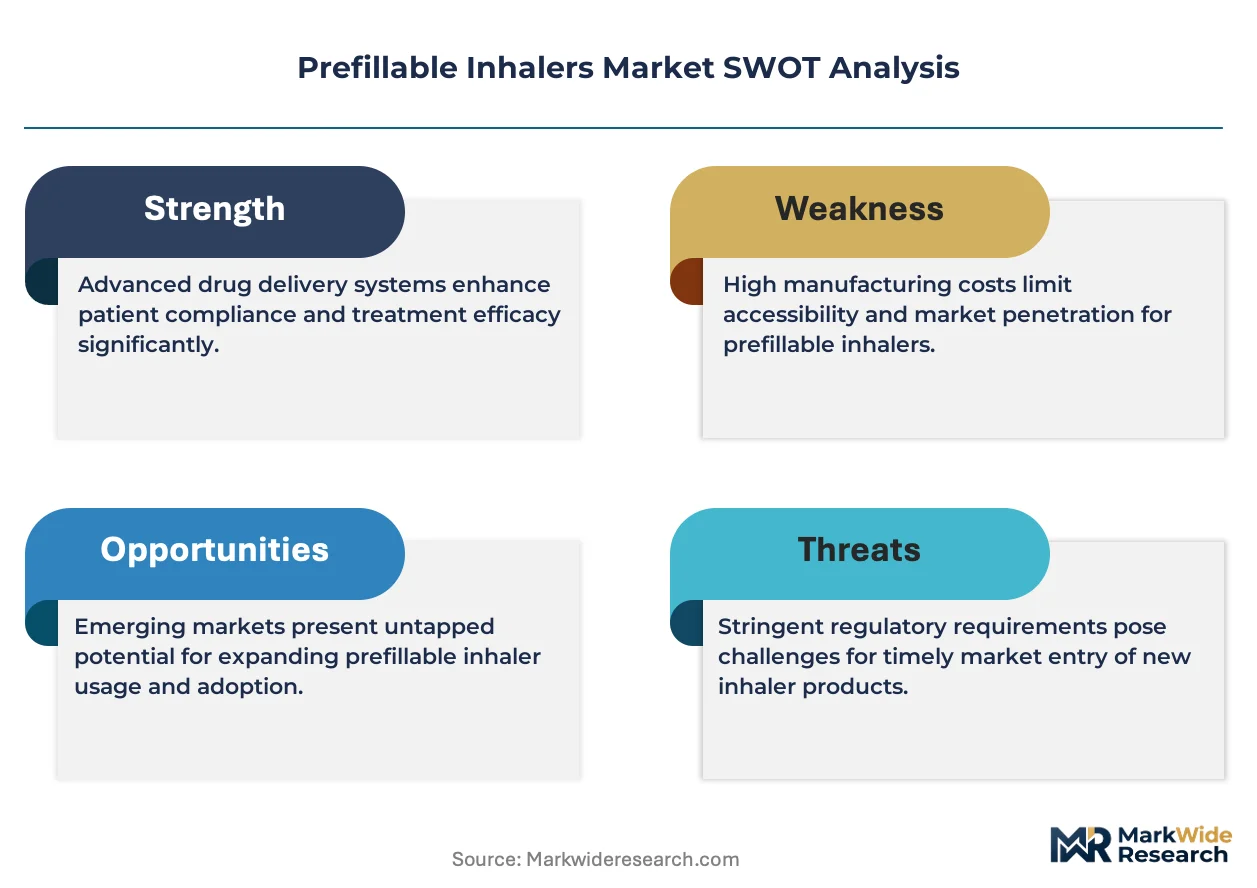
- EMA MDR and EU AI Act compliance frameworks:Stricter device performance validation standards create competitive moats for manufacturers with established quality management systems and human factors testing capabilities.
- Siliconization and laser welding processes:Precision manufacturing advances enable dose uniformity and particle size distribution control that supports biologic-compatible inhaler architectures.
Market Restraints
- Polymer resin and electronic component cost volatility:Precision-molded reservoirs and integrated dosage sensors face input price instability that compresses margin pools at the device platform level.
- Specialized contract manufacturing concentration:Precision molding and laser welding capabilities cluster among a limited supplier base in regulated European markets, creating supply bottleneck risk.
- FDA combination product review timeline uncertainty:Evolving guidance on drug-device submissions extends market access timelines and defers revenue recognition for novel platform introductions.
Strategic Opportunities
- Underpenetrated home care channels in Japan:Reimbursement clarity for connected drug-device combinations remains incomplete, creating first-mover advantage for manufacturers navigating PMDA consultation pathways.
- Biologic-compatible reservoir architectures:Protein and peptide formulation stability requirements open white space for specialized device-reservoir engineering beyond small-molecule dominance.
- ISO 20072 harmonization with FDA quality systems:Converging international standards reduce duplicate validation expenditure and accelerate multi-territory registration strategies.
Industry Challenges
- Human factors engineering talent scarcity:Specialized expertise in patient-interface design and usability testing for pulmonary delivery systems commands premium compensation and extends recruitment cycles.
- Post-market surveillance infrastructure for connected devices:Emerging pharmacovigilance requirements for sensor-enabled inhalers demand new data architecture investments and partnership structures across the value chain.
- Legacy device platform obsolescence risk:Manufacturers maintaining established metered dose inhaler portfolios face capital allocation tension between sustaining current production and migrating to smart inhaler architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prefillable Inhalers Market |
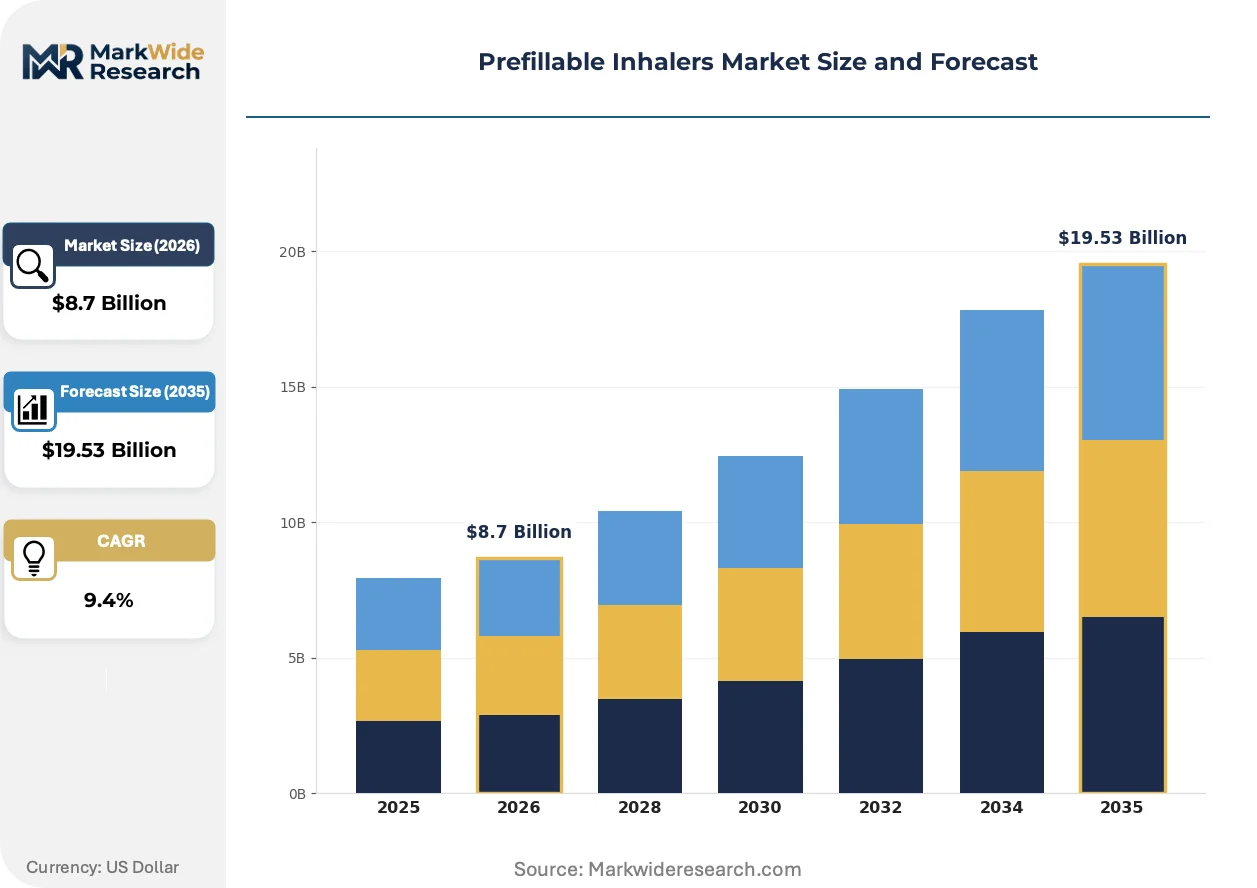
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metered Dose Inhalers, Dry Powder Inhalers, Nebulizers, Soft Mist Inhalers Technology: Smart Inhalers, Electronic Inhalers, Dosage Sensors, Material Monitoring End User: Hospitals, Home Care Settings, Pharmacies, Clinics Therapy Area: Chronic Obstructive Pulmonary Disease, Asthma, Allergic Rhinitis, Respiratory Infections |
| Companies Covered | GlaxoSmithKline plc, AstraZeneca, Cipla Inc., Boehringer Ingelheim, Teva Pharmaceutical Industries, Novartis AG, AptarGroup, Chiesi Farmaceutici, Lupin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prefillable Inhalers Market Evolving Landscape
Digital biomarker capture and closed-loop adherence monitoring are repositioning inhaler devices from passive delivery mechanisms to active therapeutic management tools, compressing the traditional separation between pharmaceutical and medical device value chains.
Integrated dosage sensors with Bluetooth connectivity and cloud-based data transmission are consolidating market structure around manufacturers capable of delivering validated software-as-medical-device components alongside mechanical platforms. Hospital systems and pharmacy benefit managers in the United States are prioritizing connected inhaler procurement to support outcomes-based contracting with respiratory biologic manufacturers. This consolidation is compressing competitive position for pure-play mechanical device suppliers lacking digital development capabilities or partnership networks.
EMA MDR Article 117 and the EU AI Act risk classification framework are reshaping regulatory submission requirements for prefillable inhalers with algorithmic components. Manufacturers must now demonstrate clinical validation for adherence prediction algorithms and data security for patient-generated health data. The Dry Powder Inhaler segment faces particular scrutiny where connected cap technologies trigger higher-risk device classification and extended notified body review timelines.
Hospital procurement committees are unbundling device selection from pharmaceutical formulary decisions, creating separate evaluation tracks for mechanical performance and digital service capabilities. Pharmacy networks in Germany are responding by establishing dedicated respiratory device specialists who advise patients on sensor activation and mobile application onboarding. This behavioral shift is most visible in integrated delivery networks where pharmacy and clinical operations report to unified administrative structures.
Prefillable Inhalers Market Segmentation
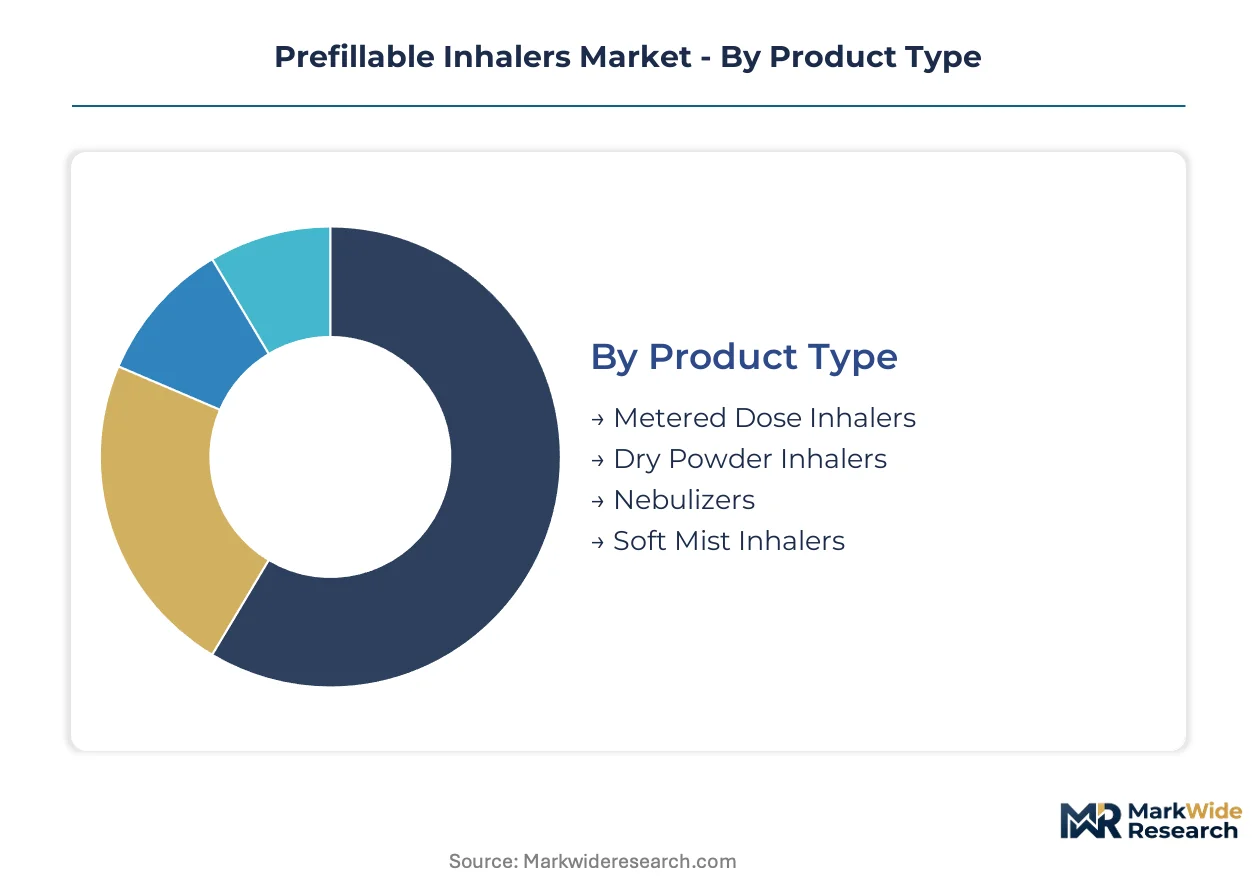
Segmentation in prefillable inhalers reveals distinct margin pools and regulatory pathways. Product architecture determines manufacturing complexity, while technology integration shapes competitive moats and reimbursement access.
Product Type:
Standalone mechanical platforms dominate current volume, though embedded sensor compatibility increasingly influences procurement decisions across German hospital networks and Japanese home care channels.
- Metered Dose Inhalers:Pressurized canister systems with propellant-driven aerosol generation deliver precise dose volumes through standardized actuation mechanics. Demand concentrates in United States pharmacy networks where formulary inclusion and patient familiarity sustain replacement cycles despite polymer resin cost volatility.
- Dry Powder Inhalers:Breath-actuated reservoirs rely on patient inspiratory flow for powder deagglomeration and lung deposition. German outpatient clinics favor these devices for corticosteroid combinations where particle engineering patents protect margin pools.
- Nebulizers:Compressor or mesh-based systems generate continuous aerosol for acute exacerbation management in institutional settings.
- Soft Mist Inhalers:Spring-mechanized liquid propulsion produces slow-moving aerosol clouds with reduced oropharyngeal deposition.
Metered Dose Inhalers lead volumes today; Smart Inhalers is gaining share fastest.
Technology:
Cost tier separation distinguishes premium connected platforms from basic mechanical alternatives, with reimbursement clarity determining accessible price bands in Japan and Germany.
- Smart Inhalers:Bluetooth-enabled devices with integrated dosage sensors and mobile application connectivity capture adherence data for real-world evidence generation. United States integrated delivery networks prioritize procurement of these platforms to support outcomes-based contracting with respiratory biologic manufacturers.
- Electronic Inhalers:Battery-powered actuation systems with programmable dose delivery and feedback mechanisms serve patients with compromised manual dexterity.
- Dosage Sensors:Add-on or embedded components tracking actuation events and timing for clinical monitoring.
- Material Monitoring:Sensors detecting temperature, humidity, or remaining drug volume in reservoir chambers.
Smart Inhalers command premium pricing; Dosage Sensors show steepest expansion trajectory as retrofit demand accelerates.
End User:
Application context shapes device specification, with home care settings demanding portable simplicity while institutional procurement emphasizes data integration and infection control.
- Home Care Settings:Patient-managed environments drive demand for portable, intuitive devices with minimal training requirements. Japan's aging COPD population and incomplete PMDA reimbursement clarity for connected combinations create first-mover opportunity for manufacturers navigating consultation pathways.
- Hospitals:Acute care facilities require nebulizer and ventilator-compatible platforms with disposable patient interfaces.
- Pharmacies:German pharmacy networks employ dedicated respiratory device specialists advising on sensor activation and mobile application onboarding.
- Clinics:Outpatient pulmonary practices balance diagnostic capability with patient self-management transition.
Home Care Settings expand most quickly; Hospitals retain largest absolute volume.
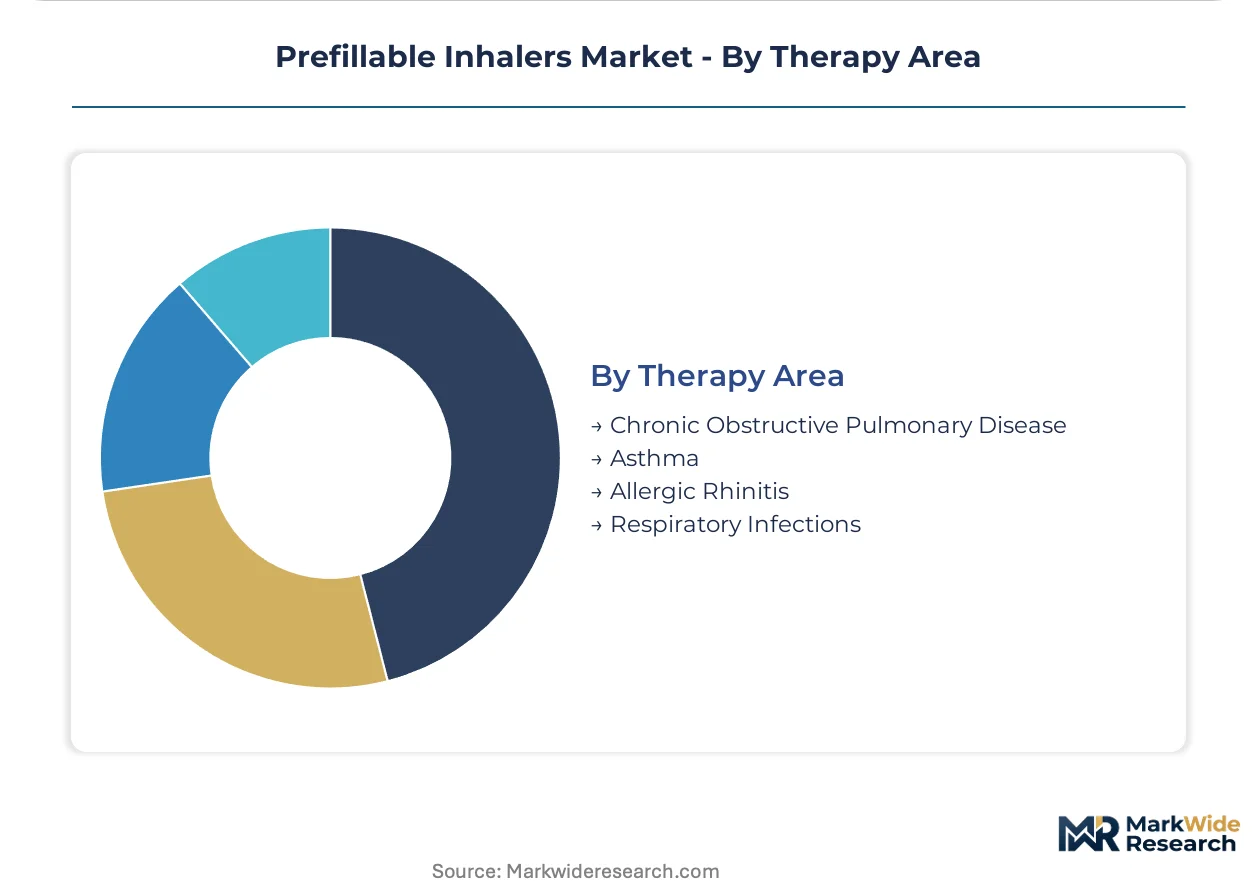
Therapy Area:
Patient population size and treatment duration determine addressable market scope, with chronic conditions sustaining recurring device replacement cycles.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation requiring long-acting bronchodilator maintenance therapy drives highest device utilization intensity. United States Medicare reimbursement for connected inhalers in COPD management accelerates clinical uptake.
- Asthma:Reversible airway obstruction with variable severity creates demand for both rescue and controller medication delivery platforms.
- Allergic Rhinitis:Nasal and ocular symptom management occasionally employs inhaler-adjacent delivery systems.
- Respiratory Infections:Acute antibiotic or antiviral aerosol delivery in institutional settings.
Chronic Obstructive Pulmonary Disease leads device volumes; Asthma shows strongest connected platform penetration growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized human factors engineering talent concentrates in Germany's medical device corridor and Japan's precision manufacturing clusters, anchoring regional innovation capacity for connected inhaler development.
United States
Medicare reimbursement clarity for connected drug-device combinations and integrated delivery network procurement consolidation drive demand concentration. FDA combination product guidance evolution creates compliance complexity that favors established quality management systems. Boston and Research Triangle Park host dense clusters of contract research organizations supporting human factors validation studies.
Germany
Hospital procurement committee unbundling of device from pharmaceutical decisions and pharmacy network respiratory specialist deployment reshape channel dynamics. EMA MDR Article 117 implementation extends notified body review timelines for algorithmic device components. Baden-Württemberg's precision molding supplier base concentrates laser welding capabilities serving European device manufacturers.
Japan
Aging COPD patient demographics and incomplete PMDA reimbursement pathways for connected combinations create first-mover opportunity windows. METI industrial policy supports domestic medical device manufacturing scale-up. Osaka-Kobe manufacturing belt hosts siliconization process specialists supplying reservoir component fabricators.
United Kingdom
NHS England outcomes-based contracting pilots for respiratory biologics accelerate connected inhaler evaluation in integrated care systems. MHRA convergence with EMA MDR post-Brexit creates dual-track registration requirements. Cambridge life sciences cluster attracts digital health talent for adherence algorithm development.
India
Domestic pharmaceutical manufacturing scale and CDSCO streamlined medical device registration attract contract manufacturing investment. Government PLI scheme incentives for medical electronics support sensor component assembly capacity. Hyderabad and Ahmedabad pharmaceutical corridors expand inhaler device engineering capabilities.
Prefillable Inhalers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressure concentrates around connected device capabilities and regulatory compliance infrastructure. Three archetypes dominate: vertically integrated respiratory portfolios, specialized biologic-compatible device engineers, and precision component contract manufacturers. Competitive moves center on strategic partnerships for sensor integration and geographic expansion into underpenetrated reimbursement markets.
Among diversified pharmaceutical conglomerates, GlaxoSmithKline plc and AstraZeneca occupy positions exemplifying vertical integration across drug and device platforms. Boehringer Ingelheim represents the European-focused distribution control archetype. These three anchors demonstrate how regulatory compliance scale and therapeutic area depth create defensive positioning against pure-play mechanical device suppliers lacking digital development pathways.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| AstraZeneca |
| Cipla Inc. |
| Boehringer Ingelheim |
| Teva Pharmaceutical Industries |
| Novartis AG |
| AptarGroup |
| Chiesi Farmaceutici |
| Lupin Ltd. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up contract manufacturing specialists in Germany's precision molding corridor have consolidated laser welding and siliconization capabilities, tightening supply discipline while enabling premium pricing for FDA-validated reservoir components. This ownership concentration links directly to pricing power: manufacturers with captive quality management systems command spreads over generic mechanical device suppliers, while hospital procurement committees in the United States unbundle device selection from pharmaceutical formulary decisions, forcing pure-play mechanical suppliers toward volume-discount positioning.
Pricing Analysis
Bundled sensor-enabled platforms with SaaS-tiered adherence analytics separate from unbundled mechanical replacements on pure transactional per-unit terms. Pricing stratifies across connected biologic-compatible architectures, ISO 20072-certified standard devices, and economy mechanical alternatives without human factors validation. Cost compression in the economy tier intensifies because polymer resin and electronic component volatility squeezes margin pools at the device platform level. Pharmacy benefit managers show highest price sensitivity for mechanical alternatives, while integrated delivery networks absorb premium connected platform costs to secure outcomes-based contracting leverage with respiratory biologic manufacturers.
Supply Chain Analysis
Domestic-content mandates under Japan's METI industrial policy and India's PLI scheme for medical electronics are reshaping sourcing patterns for sensor component assembly and precision reservoir fabrication. Manufacturing gravity centers on Germany for laser-welded reservoir systems, Japan for siliconization process specialization, and India for emerging contract assembly capacity. Raw material dependencies draw from specialized polymer resins for pressurized canisters, Bluetooth-enabled sensor modules, and precision-molded actuation mechanisms. Single-source vulnerability concentrates in European notified body certification capacity for MDR Article 117 algorithmic device reviews. Distribution runs through German pharmacy networks with dedicated respiratory device specialists, United States integrated delivery network procurement committees, and Japanese hospital procurement channels navigating incomplete PMDA reimbursement pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The prefillable inhalers market reads as a late-cycle quality story where demand concentrates toward smart inhaler platforms with validated software-as-medical-device components, displacing undifferentiated mechanical device suppliers lacking digital development pathways or partnership networks.
For Market Incumbents: Anticipate regulatory convergence between FDA combination product guidance and EMA MDR Article 117 implementation to extend compliance timelines for algorithmic device components, threatening revenue recognition deferrals for novel platform introductions. Prioritize backward integration into precision molding and laser welding capabilities to reduce single-source supplier concentration risk in Germany's Baden-Württemberg corridor. Deepen human factors engineering talent pools through acquisition of specialized usability testing consultancies in Boston and Research Triangle Park clusters. For New Entrants and Emerging Players: Enter via underpenetrated home care channels in Japan where PMDA reimbursement clarity for connected drug-device combinations remains incomplete, creating first-mover windows for manufacturers navigating consultation pathways. Target biologic-compatible reservoir architectures where protein and peptide formulation stability requirements open white space beyond small-molecule dominance. Pursue partnership-led go-to-market models with established respiratory biologic manufacturers seeking validated device platforms for outcomes-based contracting with United States integrated delivery networks. For Investors and Strategic Acquirers: Pharmaceutical conglomerates with vertically integrated respiratory portfolios are the most active acquirer in this space, seeking to consolidate connected device capabilities and regulatory compliance infrastructure. Over the medium-term horizon, acquisition value concentrates in specialized contract manufacturers with ISO 20072 quality systems and established FDA/EMA submission track records. Monitor EMA notified body capacity allocation for MDR Article 117 reviews as the critical inflection signal for market access timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Inhaler Sensor Integration | Bluetooth-enabled dosage tracking satisfies FDA combination product guidance for real-world evidence generation. |
| Biologic-Compatible Reservoir Development | Siliconization process control enables protein stability for AstraZeneca's respiratory biologic pipeline. |
| EMA MDR Article 117 Compliance Pathway | Algorithmic component validation secures notified body approval for German hospital procurement. |
| Hospital System Partnership | Integrated delivery network contracting locks in procurement preference for United States Medicare reimbursement. |
| Human Factors Engineering Acquisition | Specialized usability testing talent commands premium compensation in Boston medical device clusters. |
Research Methodology
Bottom-up home care setting and hospital procurement modeling reconciled against top-down precision manufacturing capacity tracking forms the analytical core. Primary interviews with regulatory affairs leads at device manufacturers, hospital procurement committee members, pharmacy benefit managers, and biomedical engineers specialized in pulmonary delivery systems combined with secondary validation against FDA 510(k) filings, EMA MDR Article 117 submissions, CMS Medicare reimbursement databases, and ISO 20072 quality system registries. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of metered dose inhaler replacement cycles and smart inhaler adoption curves informed projection frameworks across the analysis window. Segmentation dimensions modeled include product architecture, technology integration tier, end-use setting, and therapy area, with regional regulatory cluster effects layered as overlay variables. CAGRs derived from fitted growth curves applied to base-year market sizing, with cross-checks against pharmaceutical company respiratory segment disclosures and contract manufacturer revenue attribution.
The model holds under stable FDA combination product review timelines and EMA MDR convergence pace; deviation in notified body capacity constraints or polymer resin cost volatility would shift trajectory assumptions. Forecasts reflect documented base conditions with explicit sensitivity to reimbursement pathway completion in Japan and human factors engineering talent availability in German medical device corridors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cranial Implants Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
IV Equipment Market
Medical Devices
Breathing Exercise Devices Market
Medical Devices
Uterine Fibroid Embolization Devices Market
Medical Devices
Global Dry Powder Inhaler (DPI) Market
Medical Devices
Subperiosteal Implants Market
Medical Devices
Global Smart Implantable Pumps Market
Medical Devices
Double-Lumen Biliary Catheters Market
Medical Devices
Global Vascular Embolization Devices Market
Medical Devices
Human Augmentation in Healthcare Market
Medical Devices
IOL Delivery Systems Market
Medical Devices
Liver-On-Chip Market
Medical Devices
Education Microscope Market
Medical Devices
Chest Drainage System Market
Medical Devices
Global Hernia Repair Devices and Consumables Market