
 Middle East and Africa Surgical Sutures Market | 2026-2036
Middle East and Africa Surgical Sutures Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Surgical Sutures Market Foresight
Ethiopian and Kenyan medical device distributors is expanding regional warehousing for surgical consumables. Medtronic leverages its Addis Ababa logistics hub to reach East African hospital networks. Johnson & Johnson anchors its presence through long-term supply contracts with Gulf Cooperation Council health systems. B. Braun Melsungen AG differentiates via specialized training programs for laparoscopic suturing techniques.
Surgical sutures are sterile, thread-like medical devices manufactured from natural or synthetic polymers, designed to approximate wound edges and maintain tensile strength ranging from 7 to 28 days depending on material composition. Absorbable sutures dominate volume demand across cardiac and general surgery applications where internal tissue closure eliminates removal procedures. Non-absorbable polypropylene segments command premium positioning in orthopedic and plastic surgery due to permanent tensile retention and minimal tissue reactivity. Hospitals remain the primary procurement channel, though ambulatory surgical centers are gaining share as same-day procedures expand across the Middle East.
SAHPRA, Saudi Food and Drug Authority (SFDA), and the UAE's Ministry of Health and Prevention (MOHAP) enforce medical device registration and quality standards that determine market access for imported sutures. These regulators require biocompatibility testing and manufacturing facility audits that favor established suppliers with dedicated regulatory affairs teams. Stakeholders must monitor harmonization efforts between Gulf standardization organizations and African Medicines Agency protocols to anticipate future compliance burdens.
Market Dynamics
Vision 2030 health infrastructure investments across Saudi Arabia are accelerating surgical capacity expansion, triggering procurement scale-ups that ripple through distributor networks and reshape competitive positioning across the entire Middle East and Africa region.
Growth Catalysts
- SFDA registration harmonization:Saudi Food and Drug Authority streamlines medical device approvals, reducing time-to-market for compliant manufacturers and expanding accessible supplier pools.
- Cardiac surgery volumes:Absorbable suture demand concentrates in tertiary hospital cardiac departments performing coronary artery bypass grafting at rising frequency.
- Ethiopia:Addis Ababa logistics infrastructure upgrades enable regional distribution hub consolidation, cutting delivery lead times to East African hospital networks.
Market Restraints
- Polypropylene raw material concentration:Synthetic polymer feedstock supply clusters with Gulf petrochemical producers, exposing manufacturers to regional price volatility and single-source risk.
- SAHPRA audit backlog:South African Health Products Regulatory Authority manufacturing facility inspection queues extend registration timelines, freezing market entry for pending applicants.
- Staple substitution in laparoscopy:Surgical staplers displace running suture techniques in minimally invasive procedures, compressing addressable volume in premium general surgery segments.
Strategic Opportunities
- Kenya:Underpenetrated county hospital networks outside Nairobi present first-mover expansion potential for distributor warehousing investments.
- Barbed suture technology:Knotless closure systems converge with laparoscopic training protocols, enabling premium positioning in same-day discharge procedures.
- MOHAP fast-track pathway:UAE Ministry of Health and Prevention accelerated review for innovative devices rewards early regulatory investment with priority market access.
Industry Challenges
- Laparoscopic suturing certification:Specialized training program development requires sustained capital commitment and clinical partnership cultivation.
- Biocompatibility testing capacity:ISO 10993 compliant laboratory availability constrains registration preparation timelines for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Surgical Sutures Market |
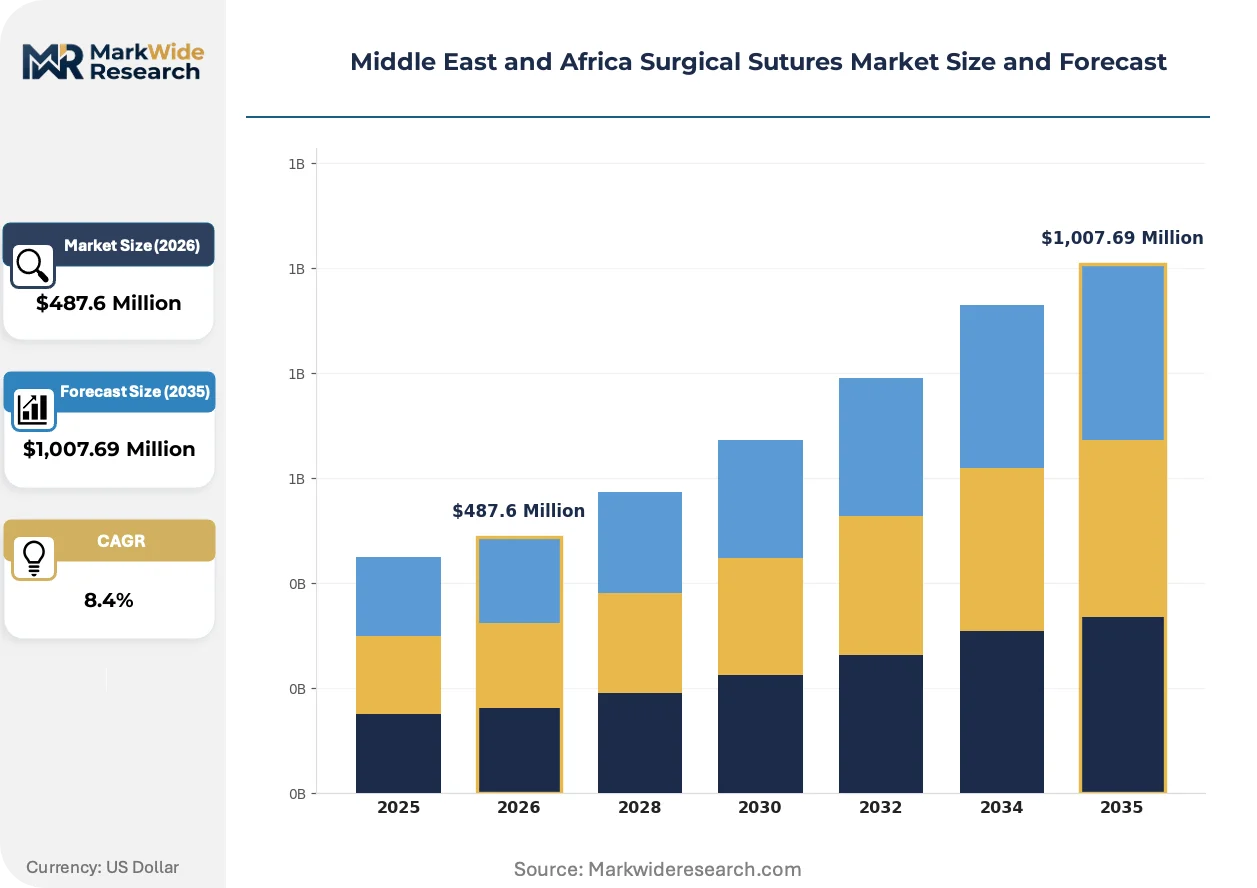
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,007.69 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable, Non-Absorbable, Ligating, Surgical Tape Material: Silk, Nylon, Polyester, Polypropylene Application: Cardiac, Orthopedic, Plastic Surgery, General Surgery End User: Hospitals, Clinics, Outpatient Facilities, Ambulatory Surgical Centers |
| Companies Covered | Medtronic, Johnson & Johnson, B. Braun Melsungen AG, Smith & Nephew, Ethicon, CONMED Corporation, DemeTECH Corporation, Surgical Specialties Corporation, Sutures India, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Surgical Sutures Market Shifts & Advancements
Antibacterial suture coatings are reshaping infection prevention protocols across orthopedic and general surgery departments, while regulatory convergence and procurement centralization simultaneously compress competitive timelines and expand contract scale requirements.
Triclosan-coated polyglactin 910 is consolidating market share in contaminated wound closure applications where surgical site infection reduction drives protocol mandates. Tertiary hospital procurement committees across Saudi Arabia and the UAE are standardizing antibacterial suture specifications in high-risk procedure bundles. This specification tightening is consolidating supplier rosters toward manufacturers with dedicated coating technology capabilities and established SFDA registration histories.
MDR-equivalent frameworks are propagating through Gulf standardization organizations, extending European medical device regulation compliance expectations to Middle East market access requirements. Manufacturers must now maintain technical documentation and post-market surveillance systems that satisfy both EMA-aligned reviewers and national Gulf regulators. Absorbable suture categories face the steepest documentation burden increases, forcing portfolio rationalization among smaller exporters.
Ambulatory surgical centers are compressing suture inventory cycles through consignment arrangements that transfer working capital burden to distributors. Same-day procedure expansion across Dubai and Riyadh drives this channel shift, with multispecialty day surgery units replacing inpatient wards for hernia repair and arthroscopy cases. Kenya's private hospital chains are piloting comparable vendor-managed inventory models for orthopedic consumables.
Middle East and Africa Surgical Sutures Market Segmentation
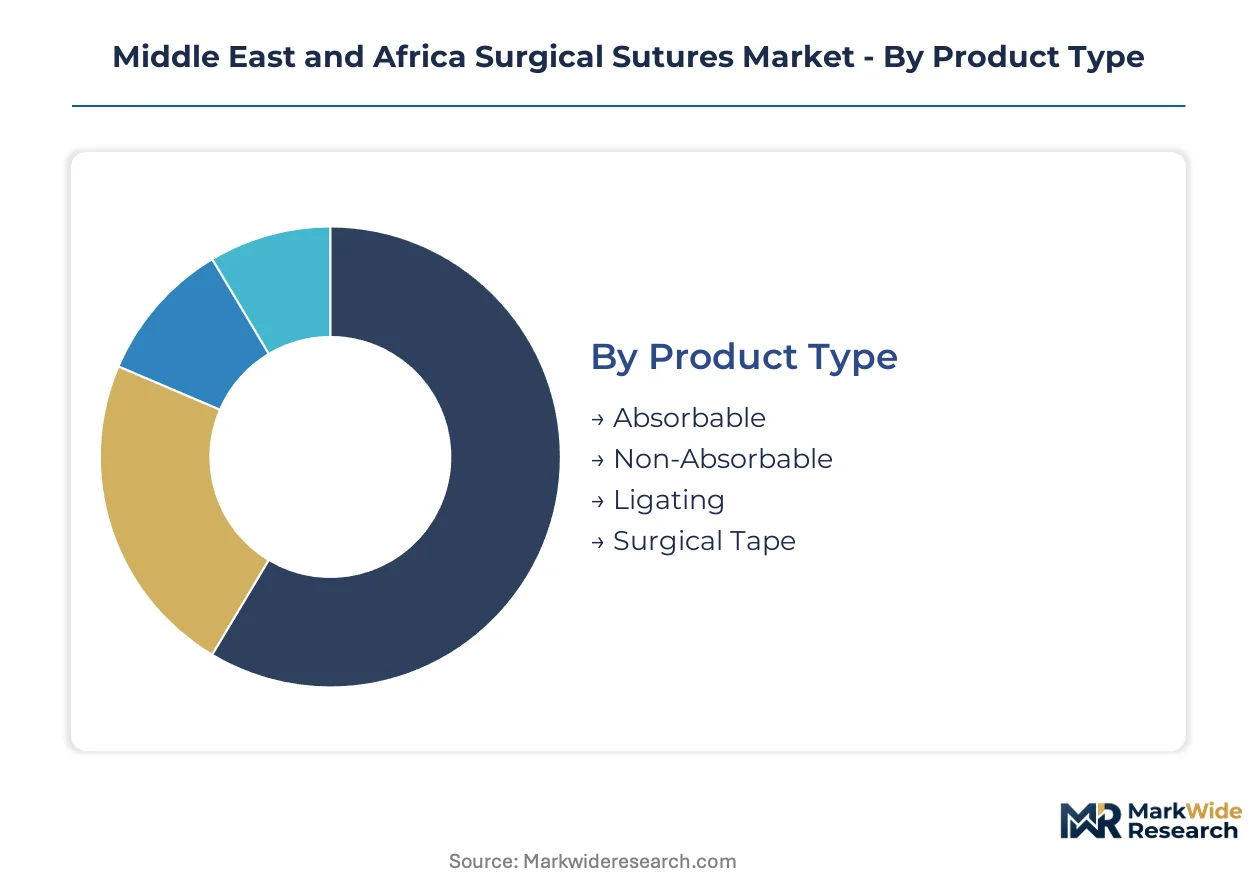
Suture procurement patterns diverge sharply across clinical settings and material specifications. Understanding these fracture lines reveals where pricing power concentrates and which technology investments yield access to high-volume accounts.
Product Type:
Procurement committees weight infection risk against removal logistics when selecting closure systems.
- Absorbable:Polyglactin 910 and poliglecaprone 25 formulations hydrolyze within 60-90 days, eliminating suture removal visits. Tertiary hospital cardiac departments across Saudi Arabia specify absorbable lines for coronary artery bypass grafting where sternal closure demands predictable tensile decay.
- Non-Absorbable:Polypropylene and polyester monofilaments retain permanent tensile strength. Orthopedic fixation and hernia mesh attachment in South African academic medical centers drive specification of these lines where long-term mechanical support outweighs removal cost.
- Ligating:Pre-tied loop configurations accelerate vessel occlusion in laparoscopic nephrectomy and splenectomy. Kenyan referral hospitals are standardizing ligating suture kits for emergency trauma procedures.
- Surgical Tape:Adhesive skin closure strips supplement sutures in low-tension dermatological closures. Dubai ambulatory surgical centers deploy tape for cosmetic procedure finishing where scar minimization protocols prioritize non-invasive approximation.
Volume sits with absorbable lines across cardiac and general surgery; growth tilts toward barbed and antibacterial-coated absorbable variants in same-day discharge settings.
Material:
Raw material sourcing geography and polymer processing capabilities determine supplier eligibility for government tenders.
- Silk:Natural protein fiber with excellent handling characteristics but inflammatory tissue response. Ethiopian ophthalmic surgery units maintain silk specifications for cataract wound closure where suture feel outweighs biocompatibility concerns.
- Nylon:Polyamide monofilament with high tensile strength and minimal tissue drag. Plastic surgery departments across UAE private hospital chains specify nylon for rhinoplasty and blepharoplasty where precise dermal approximation demands low-friction passage.
- Polyester:Braided polyethylene terephthalate with permanent strength retention. Cardiac valve repair procedures in Cairo tertiary centers rely on polyester pledgeted sutures for annuloplasty band fixation.
- Polypropylene:Isotactic polypropylene monofilament with minimal tissue reactivity and indefinite strength. Orthopedic ligament reconstruction and hernia repair across Gulf Cooperation Council health systems standardize on polypropylene where permanent fixation is required.
Procurement volume clusters with polypropylene across orthopedic and cardiovascular applications; specification momentum is climbing fastest for coated and dyed variants that enhance intraoperative visibility.
Application:
Procedure reimbursement tiers and complication liability exposure shape suture budget allocation across surgical departments.
- Cardiac:Sternotomy closure and valve repair demand high-tensile braided sutures with predictable absorption profiles. Saudi Arabia's expanding cardiac surgery program under Vision 2030 is scaling absorbable sternal wire alternatives and pledgeted polyester lines.
- Orthopedic:Tendon repair and ligament reconstruction require permanent monofilament fixation. South African public hospital orthopedic departments are consolidating vendor contracts around polypropylene and polyester braided lines for arthroscopy and open procedures.
- Plastic Surgery:Aesthetic and reconstructive procedures prioritize fine-gauge monofilaments with minimal tissue reactivity. Lebanon's cosmetic surgery tourism sector specifies nylon and polypropylene micro-sutures for rhinoplasty and facelift procedures.
- General Surgery:Abdominal wall closure and gastrointestinal anastomosis consume the broadest suture portfolio. Kenyan county hospitals are expanding absorbable synthetic inventory for emergency laparotomy cases.
Revenue concentration tracks cardiac and orthopedic segments where procedure complexity supports premium pricing; volume expansion is gaining share fastest in general surgery as hernia and cholecystectomy procedures shift to ambulatory settings.
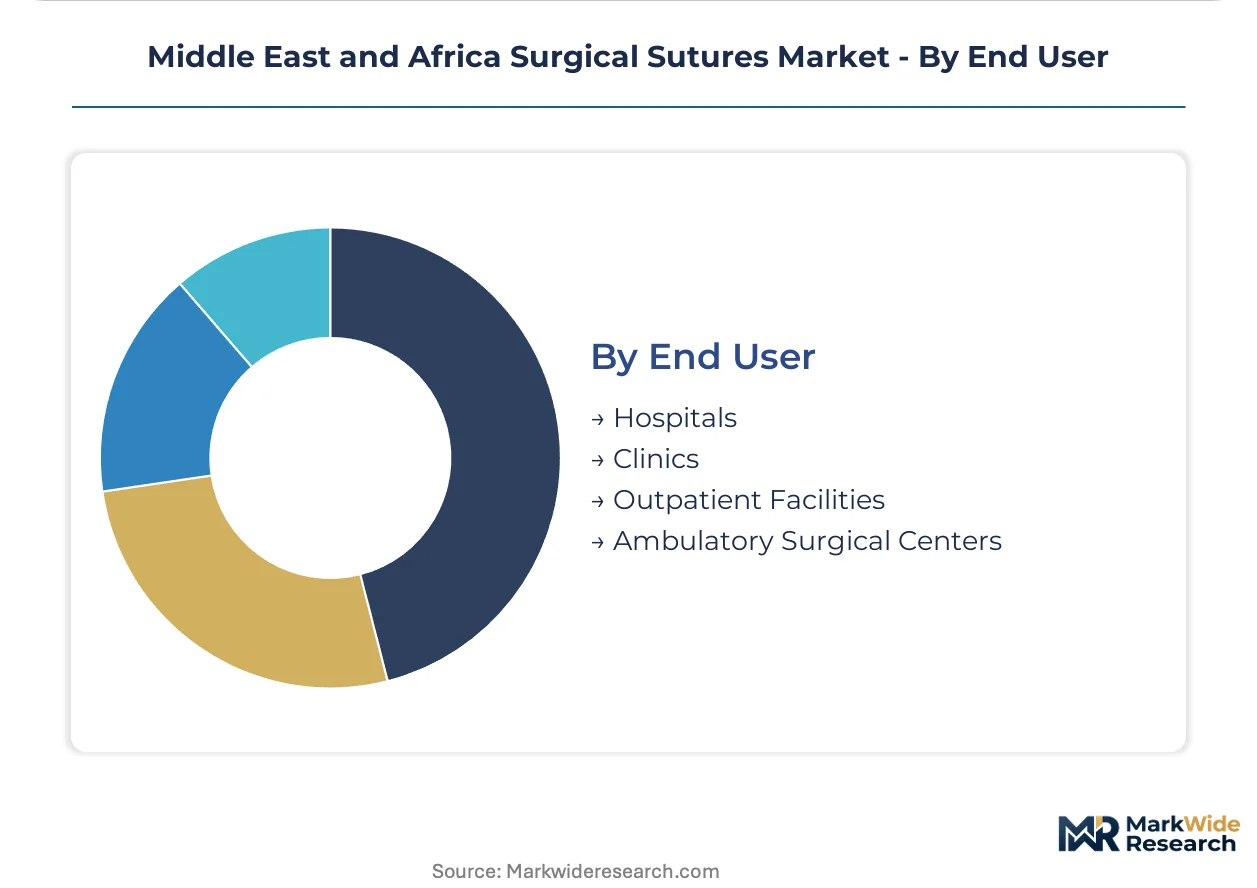
End User:
Capital intensity and inventory carrying capacity separate procurement behaviors across care delivery sites.
- Hospitals:Tertiary and secondary acute care facilities with centralized sterilization services and 24-hour surgical capacity. Saudi Arabia's Ministry of Health hospital networks negotiate multi-year suture supply agreements with volume-based pricing tiers.
- Clinics:Primary care and specialty outpatient settings with limited procedure rooms. Ethiopian urban clinics are piloting consignment inventory models for minor surgical consumables.
- Outpatient Facilities:Dedicated procedure centers without overnight admission capacity. UAE dermatology and ophthalmology day units specify pre-packaged suture kits to minimize sterilization overhead.
- Ambulatory Surgical Centers:Medicare-equivalent same-day surgery units with compressed case turnaround requirements. Riyadh and Dubai multispecialty day surgery centers are adopting vendor-managed inventory for orthopedic and general surgery suture lines.
Contract value concentrates with hospital procurement committees; patient volume is migrating fastest toward ambulatory surgical centers where consignment terms and just-in-time delivery reshape distributor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf petrochemical clusters supply polypropylene feedstock that anchors synthetic suture manufacturing across the region. Vision 2030 infrastructure commitments and East African logistics upgrades are redrawing procurement geography.
Saudi Arabia
Cardiac surgery program expansion under Vision 2030 is scaling absorbable sternal closure demand. SFDA registration harmonization reduces time-to-market for compliant manufacturers. Riyadh tertiary hospital networks negotiate multi-year supply agreements with volume-based pricing tiers.
UAE
Dubai ambulatory surgical centers are compressing inventory cycles through consignment arrangements. MOHAP fast-track pathways reward early regulatory investment with priority market access. Multispecialty day surgery units across Dubai and Abu Dhabi replace inpatient wards for hernia and arthroscopy cases.
South Africa
SAHPRA manufacturing facility audit backlogs extend registration timelines for pending applicants. Orthopedic departments in academic medical centers consolidate vendor contracts around permanent monofilament lines. Cape Town and Johannesburg hospital procurement committees enforce biocompatibility documentation standards.
Kenya
County hospital networks outside Nairobi present first-mover expansion potential for distributor warehousing investments. Emergency laparotomy cases drive absorbable synthetic inventory expansion. Mombasa logistics corridors enable regional distribution reach into neighboring East African markets.
Ethiopia
Addis Ababa logistics infrastructure upgrades enable regional distribution hub consolidation. Urban clinics pilot consignment inventory models for minor surgical consumables. Ophthalmic surgery units maintain natural fiber specifications for cataract wound closure procedures.
Middle East and Africa Surgical Sutures Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized coating and barbed suture niches. The vendor base stratifies across multinational medical device conglomerates with dedicated regulatory affairs teams and regional distributors with localized logistics capabilities. Three archetypes dominate: Gulf-anchored supply contract holders, East African logistics specialists, and antibacterial technology licensors. Competitive moves concentrate on strategic partnerships with health system procurement committees and backward integration into polymer processing.
Among diversified medical technology conglomerates, Medtronic, Johnson & Johnson, and B. Braun Melsungen AG exemplify scale-driven archetypes with established SFDA registration histories. Medtronic leverages its Addis Ababa logistics hub to reach East African hospital networks. Johnson & Johnson anchors presence through long-term supply contracts with Gulf Cooperation Council health systems. B. Braun Melsungen AG occupies a position within the specialized training tier, differentiating via laparoscopic suturing technique programs.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| B. Braun Melsungen AG |
| Smith & Nephew |
| Ethicon |
| CONMED Corporation |
| DemeTECH Corporation |
| Surgical Specialties Corporation |
| Sutures India |
| Others |
Supply & Pricing Matrix
Polypropylene feedstock costs cascade through three distinct pricing tiers as Gulf petrochemical producers supply synthetic suture manufacturers serving Saudi tertiary hospitals and East African distributors. Procurement committees at Riyadh academic medical centers negotiate multi-year contracts that lock in volume-based discounts, while Kenyan county hospitals absorb higher per-unit costs due to fragmented distributor markups and currency exposure.
Pricing Analysis
Service bundling separates premium-tier suppliers from commodity competitors, with laparoscopic training programs and regulatory filing support included in Gulf Cooperation Council health system contracts. Pricing stratifies across premium, standard, and economy tiers based on SFDA registration history and antibacterial coating technology. Cost compression in the standard tier is intensifying as Ethiopian distributors consolidate warehousing networks. Public hospital procurement committees across Kenya and South Africa exhibit the highest price sensitivity, while UAE private hospital chains prioritize compliance documentation over unit cost.
Supply Chain Analysis
SFDA and SAHPRA facility certifications gate market access, favoring manufacturers with dedicated regulatory affairs teams and ISO 10993 compliant testing partnerships. Manufacturing capacity clusters in Germany, the United States, and India, with raw material supply anchored in Saudi Arabian and UAE petrochemical complexes. Single-source vulnerability runs through polypropylene monofilament feedstock concentrated with Gulf producers. Distribution runs through Addis Ababa and Mombasa logistics hubs serving East African hospital networks, with Dubai and Riyadh anchoring Gulf supply corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a backward integration race as manufacturers pursue captive control over polymer processing and coating technology to defend margin structures against regulatory documentation burdens.
For Market Incumbents: Acquire specialized coating technology capabilities and ISO 10993 compliant laboratory assets to preempt SAHPRA audit backlogs and SFDA documentation requirements. Consolidate distributor relationships in Kenya and Ethiopia through equity stakes or exclusive territory arrangements. Surgical stapler substitution in laparoscopic procedures threatens absorbable suture volumes; counter with barbed suture training program investments that embed product specifications in hospital protocols. For New Entrants and Emerging Players: Antibacterial suture coatings offer the most penetrable technology wedge for securing initial procurement contracts with UAE and Saudi tertiary hospitals. Target underpenetrated Kenyan county hospital networks outside Nairobi with consignment inventory models that transfer working capital risk from buyers. Partner with Addis Ababa logistics specialists to bypass established distributor markups and achieve cost parity with incumbent supply contracts. For Investors and Strategic Acquirers: MOHAP fast-track pathway approvals for innovative devices are the leading indicator that regulatory investment intensity is separating viable acquisition targets from stranded assets. Focus on mid-cap manufacturers with established SFDA registration histories and proprietary coating technology portfolios. A model refresh is warranted upon material change in Gulf standardization organization harmonization timelines or African Medicines Agency protocol adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Harmonization | Streamlined Saudi approvals reduce time-to-market for compliant manufacturers expanding Gulf supply contracts. |
| Antibacterial Coating Development | Triclosan and alternative antimicrobial formulations consolidate procurement specifications in high-risk surgery bundles. |
| East African Logistics Hub Consolidation | Addis Ababa and Mombasa warehousing investments cut delivery lead times to underpenetrated county hospital networks. |
| Laparoscopic Training Program Partnerships | Specialized suturing certification embeds product specifications in hospital protocols and defends against staple substitution. |
| Backward Integration into Polymer Processing | Captive polypropylene feedstock supply insulates margins from Gulf petrochemical price volatility and single-source risk. |
Research Methodology
Multi-period observation of SFDA registration timelines, SAHPRA audit queue lengths, and Gulf hospital procurement contract values anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, biomedical engineers, regulatory affairs specialists, and distributor operations managers. Secondary validation drew from SFDA medical device registration databases, SAHPRA facility inspection records, Gulf Cooperation Council health system procurement disclosures, and customs trade data for polymer feedstock imports. Bottom-up suture volume estimates by hospital tier and top-down market sizing by manufacturer revenue were triangulated to constrain forecast variance.
Input-output matrices mapped polypropylene feedstock costs through manufacturing, regulatory compliance, and distribution stages to generate segment-specific pricing trajectories across the projection horizon. Segmentation dimensions modeled include absorbable versus non-absorbable material composition, cardiac versus orthopedic versus general surgery application, and tertiary hospital versus ambulatory surgical center end-user channel. CAGRs were derived from procedure volume growth assumptions tied to Vision 2030 infrastructure commitments and East African hospital network expansion plans, cross-referenced against suture consumption intensity benchmarks from comparable emerging markets.
Several conditions sit outside the modeled scope, including abrupt currency devaluations in East African markets, sudden SFDA regulatory framework revisions, and technological substitution breakthroughs in surgical closure systems. Forecasts reflect assumptions about sustained Gulf health infrastructure investment and gradual African Medicines Agency protocol harmonization. A model refresh is warranted upon material change in SAHPRA audit processing capacity or MOHAP fast-track pathway eligibility criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Auto-Disable Syringes Market
Medical Supplies
Medical Gloves Market
Medical Supplies
Trach Care Trays Market
Medical Supplies
Powder-Free Disposable Medical Gloves Market
Medical Supplies
Specimen Transport Bags Market
Medical Supplies
Disposable Face Mask Market
Medical Supplies
Nasal Oxygen Cannula Market
Medical Supplies
Premixed IV Minibags Market
Medical Supplies
Cell Culture Media Storage Containers Market
Medical Supplies
UAE Hospital Supplies Market
Medical Supplies
Global Non-PVC IV Bags Market
Medical Supplies
Tattoo Needles Market
Medical Supplies
Ampoules and Syringes Market
Medical Supplies
Europe Ostomy Drainage Bags Market
Medical Supplies
Bleeding Control Kit Market
Medical Supplies
Empty IV Bags Market