
 Sterile Lids Market | 2026-2036
Sterile Lids Market Size, Share, and Industry Trends Forecast 2026-2036
Sterile Lids Market Outlook
Preventive maintenance contracts for sealing equipment is decoupling hardware sales from recurring revenue streams across sterile packaging supply chains. Amcor plc leverages its global thermoforming footprint to control polymer lid supply for pharmaceutical blow-fill-seal lines. West Pharmaceutical Services, Inc. specializes in elastomeric closure-lid combinations for high-value biologic containers. Schott AG dominates borosilicate glass lid formats for freeze-dried drug vials, anchoring premium segment positioning.
Sterile lids are barrier closure systems engineered to maintain aseptic integrity for pharmaceuticals, biologics, and medical devices, typically manufactured from polypropylene, polyethylene, or borosilicate glass with validated gamma or steam sterilization compatibility. Their primary function is to seal containers against microbial ingress while permitting compatible access mechanisms for end-user administration. Screw caps lead volume across oral solid and liquid dosage formats, while snap caps capture faster growth in single-use diagnostic and point-of-care applications where rapid assembly matters. Polypropylene lids concentrate margin pools due to chemical resistance and steam sterilization tolerance, though glass retains pricing power in parenteral and lyophilized drug segments where extractables control is paramount.
FDA enforces sterility assurance level validation under 21 CFR 211 for pharmaceutical closures, while EU MDR and REACH constrain material composition and migration limits for lids contacting drug products. The country's national pharmaceutical regulator in India and CDSCO impose parallel sterilization documentation requirements for imported closure components, shaping supplier qualification timelines. Stakeholders must monitor evolving extractables testing protocols and polymer recycling mandates, as regulatory convergence on sustainable materials will force reformulation decisions before sterilization validation cycles complete.
Market Dynamics
Gamma sterilization validation cycles are compressing supplier qualification timelines, forcing lid manufacturers to front-load extractables documentation before contract awards from biologics packagers.
Growth Catalysts
- EU MDR Annex I:Tightened sterility assurance requirements for closure systems are mandating redundant barrier validation, expanding demand for pre-sterilized lid formats in parenteral drug packaging.
- Cell therapy cold chain:Cryogenic storage protocols for CAR-T and stem cell products require borosilicate glass lids with validated thermal shock resistance, pulling premium material specifications through the supply chain.
- German pharmaceutical cluster:Concentrated injectable drug manufacturing around Frankfurt and Munich is generating dedicated demand for regional sterilization service capacity and just-in-time lid logistics.
Market Restraints
- Propylene feedstock volatility:Polymer lid margins compress when naphtha-cracker output disruptions spike polypropylene resin costs, particularly affecting high-volume oral solid dosage formats.
- Gamma irradiation capacity concentration:Sterilization service providers cluster in Belgium and the Netherlands, creating single-point-of-failure exposure for European lid suppliers without redundant electron-beam alternatives.
- Glass-to-polymer substitution ceiling:Extractables-sensitive biologics cannot migrate to polymer lids regardless of cost pressure, capping addressable market expansion for polypropylene formats in parenteral segments.
Strategic Opportunities
- India CDSCO import substitution:Domestic pharmaceutical packaging growth is creating openings for local lid sterilization and molding capacity to displace European imports in generic injectable supply chains.
- Single-use diagnostic assembly:Point-of-care molecular testing platforms are adopting snap-cap lid formats for rapid cartridge sealing, diverting volume from traditional screw-cap pharmaceutical applications.
- EU Green Deal packaging mandates:Recycled content thresholds for pharmaceutical plastics will reward early movers with validated post-consumer polypropylene feedstock streams before compliance deadlines tighten.
Industry Challenges
- Extractables toxicologist scarcity:Specialized analytical chemists capable of designing lid-leachable study protocols for biologics compatibility are concentrated at contract research organizations, extending validation timelines.
- Legacy steam sterilization asset stranding:Pharmaceutical packagers with sunk capital in autoclave infrastructure face retrofit costs to accommodate newer polymer lid grades with lower thermal tolerance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterile Lids Market |
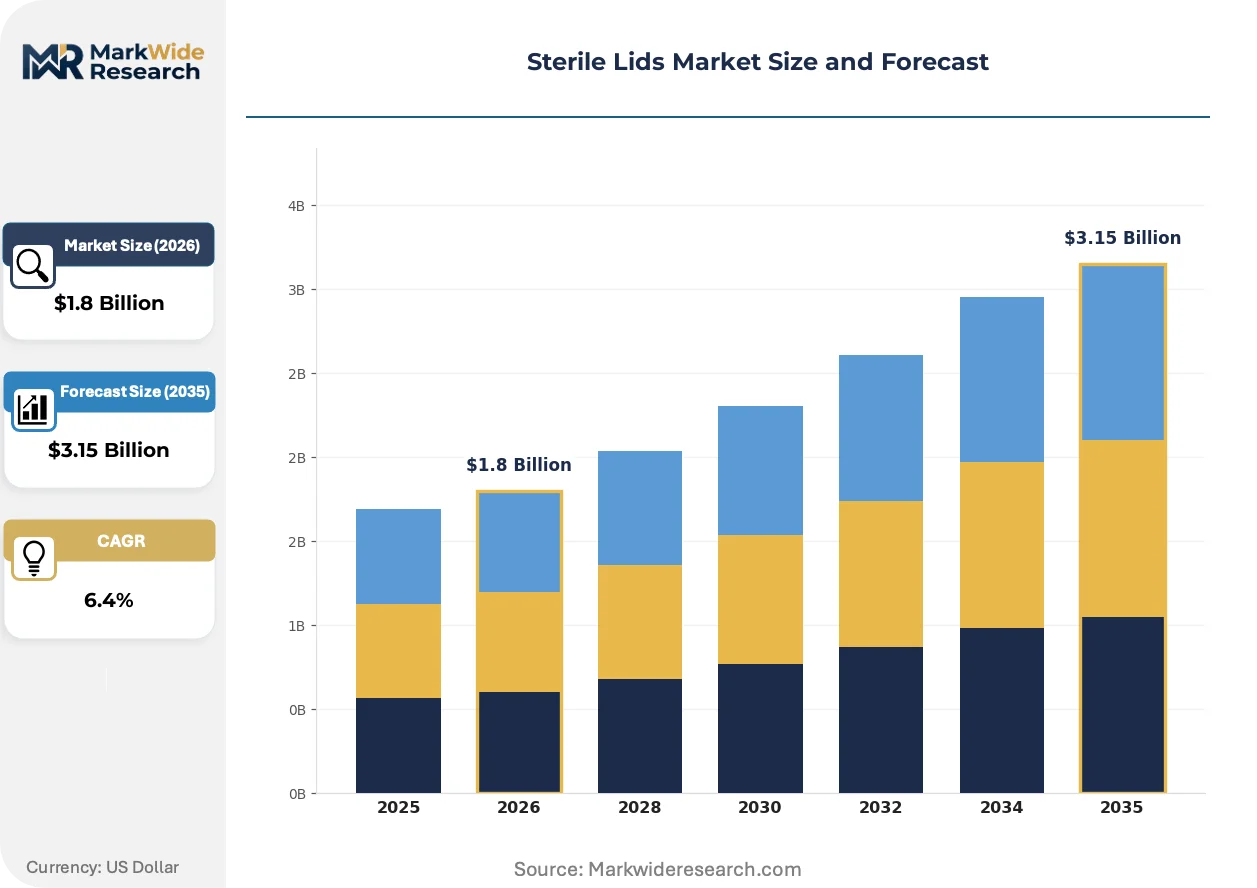
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Snap Caps, Twist-Off Caps, Dropper Caps Material: Polypropylene, Polyethylene, Glass, Aluminum End User: Pharmaceuticals, Biotechnology, Laboratories, Hospitals Application: General Packaging, Medical Devices, Biologics, Diagnostics |
| Companies Covered | Amcor plc, DuPont de Nemours, Inc., West Pharmaceutical Services, Inc., Berry Global, Inc., SteriPack Group, Gerresheimer AG, Schott AG, Sonoco Products Company, Placon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterile Lids Market Strategic Shifts
Laser-etched traceability features and smart packaging integration are redefining sterile lid value propositions beyond basic barrier function. Material science advances and regulatory digitization are compressing development cycles.
Cyclic olefin polymer (COP) lid formats are absorbing demand from glass in protein-based biologic applications where break resistance and low extractables profiles converge. Contract development and manufacturing organizations (CDMOs) are specifying COP for high-value vial closures at accelerated rates. This absorption is compressing traditional borosilicate glass lid growth trajectories in freeze-dried drug segments.
FDA's evolving guidance on container closure integrity testing is mandating probabilistic detection methods over deterministic alternatives for sterile barrier validation. Pharmaceutical packagers are reconfiguring quality control lines to accommodate vacuum decay and high-voltage leak detection systems for lid-sealed containers. Parenteral drug manufacturers with legacy dye-ingress protocols face capital-intensive line upgrades to maintain compliance.
Consolidated buying groups at hospital networks and group purchasing organizations are unbundling lid procurement from vial contracts, forcing standalone price transparency. Generic injectable manufacturers are responding with specification standardization across multiple lid suppliers to leverage volume aggregation. This unbundling is most visible in United States acute care pharmacy procurement, where formulary committees now evaluate closure components independently.
Sterile Lids Market Segmentation
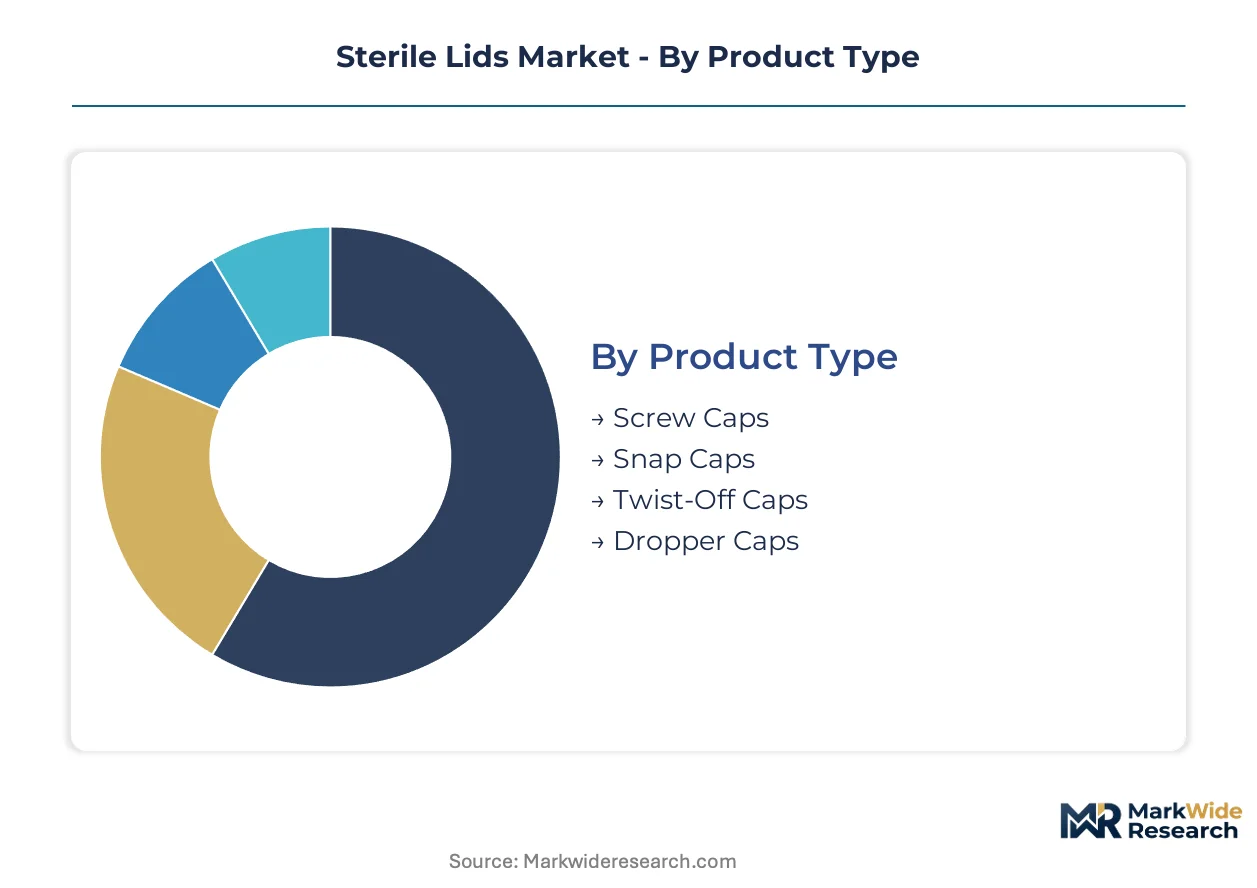
Sterile lid procurement decisions hinge on sterilization compatibility matrices and regulatory filing requirements that vary sharply across product formats and end-use environments. Segmentation reveals where FDA 21 CFR 211 validation burdens concentrate versus where EU MDR Annex I sterility assurance levels dominate supplier qualification.
Product Type:
FDA 21 CFR 211 closure validation requirements fall heaviest on screw-cap formats for oral solid dosages, while EU MDR Annex I redundant barrier mandates reshape snap-cap specifications for single-use diagnostics.
- Screw Caps:Threaded closure systems manufactured from polypropylene or glass with validated torque specifications for pharmaceutical vials and bottles. Demand concentrates in German injectable manufacturing clusters around Frankfurt, where Gerresheimer operates dedicated sterilization lines for high-volume parenteral formats. FDA sterility assurance level documentation requirements extend supplier qualification timelines.
- Snap Caps:Push-fit closure mechanisms enabling rapid assembly in point-of-care diagnostic cartridges and single-use medical devices. Growth accelerates in United States molecular testing platforms where Becton Dickinson and Abbott specify snap-cap formats for COVID-19 and respiratory panel cartridges. EU MDR Annex I redundant barrier validation is compressing development cycles.
- Twist-Off Caps:Metal-composite closures for serum and plasma collection tubes requiring controlled break-seal functionality.
- Dropper Caps:Integrated closure-dispenser combinations for ophthalmic and liquid dosage formats with calibrated orifice control.
Screw caps sit at the top of the volume ranking, with snap caps climbing the fastest.
Material:
Cost tiers separate steam-sterilizable polypropylene premium grades from gamma-compatible polyethylene standard offerings, with glass and aluminum occupying specialized high-margin niches.
- Polypropylene:Crystalline thermoplastic with validated steam sterilization tolerance to 121°C and broad chemical resistance against pharmaceutical solvents. Margin pools concentrate here due to biologics packaging demand in Basel and Boston clusters where Novartis and Moderna specify polypropylene for protein-based drug containers. Propylene feedstock volatility from naphtha-cracker disruptions compresses margins unpredictably.
- Glass:Borosilicate and soda-lime formulations for parenteral and lyophilized drug segments where extractables control overrides cost considerations. Schott AG anchors premium positioning in German vial lid production for freeze-dried biologics. Glass retains pricing power despite polymer substitution pressure in protein-based applications.
- Polyethylene:Lower-density alternative for gamma-sterilized diagnostic and general packaging with reduced thermal tolerance.
- Aluminum:Metal closure systems for serum tubes and cryogenic storage where thermal conductivity and mechanical strength matter.
Polypropylene commands the largest volume position, with glass expanding most quickly in high-value biologic segments.
End User:
Customer type determines whether procurement flows through consolidated hospital group purchasing organizations or fragmented biotechnology startup supply chains.
- Pharmaceuticals:Large-scale manufacturers of oral solid and liquid dosages with validated supplier audits and long-term sterilization service contracts. Demand concentrates in Indian generic injectable producers where CDSCO import substitution policies are displacing European lid sources.
- Biotechnology:Cell therapy and gene therapy developers requiring cryogenic-compatible borosilicate glass lids with thermal shock validation. CAR-T manufacturing in Philadelphia and San Diego clusters specifies premium closure systems for cryopreserved product logistics.
- Laboratories:Research and clinical testing facilities with fragmented procurement and lower volume per SKU.
- Hospitals:Acute care pharmacy and compounding operations where formulary committees unbundle lid procurement from vial contracts.
Pharmaceuticals generate the highest absolute volume, with biotechnology posting the steepest expansion trajectory.
Application:
Maturity gradients separate established general packaging formats from emerging diagnostics and biologics segments with unvalidated sterilization protocols.
- General Packaging:Oral solid and liquid pharmaceutical containers with standardized screw-cap specifications and commoditized pricing. Volume concentrates in high-throughput oral dosage manufacturing where polymer lid margins face continuous compression.
- Biologics:Protein-based therapeutics, vaccines, and cell therapies requiring extractables-controlled closure systems with documented leachable study protocols. FDA container closure integrity testing guidance is forcing probabilistic detection method adoption across parenteral drug manufacturers.
- Medical Devices:Sterile barrier systems for implantable and surgical products with ISO 11607 validation requirements.
- Diagnostics:Molecular testing cartridges and point-of-care platforms adopting snap-cap formats for rapid assembly.
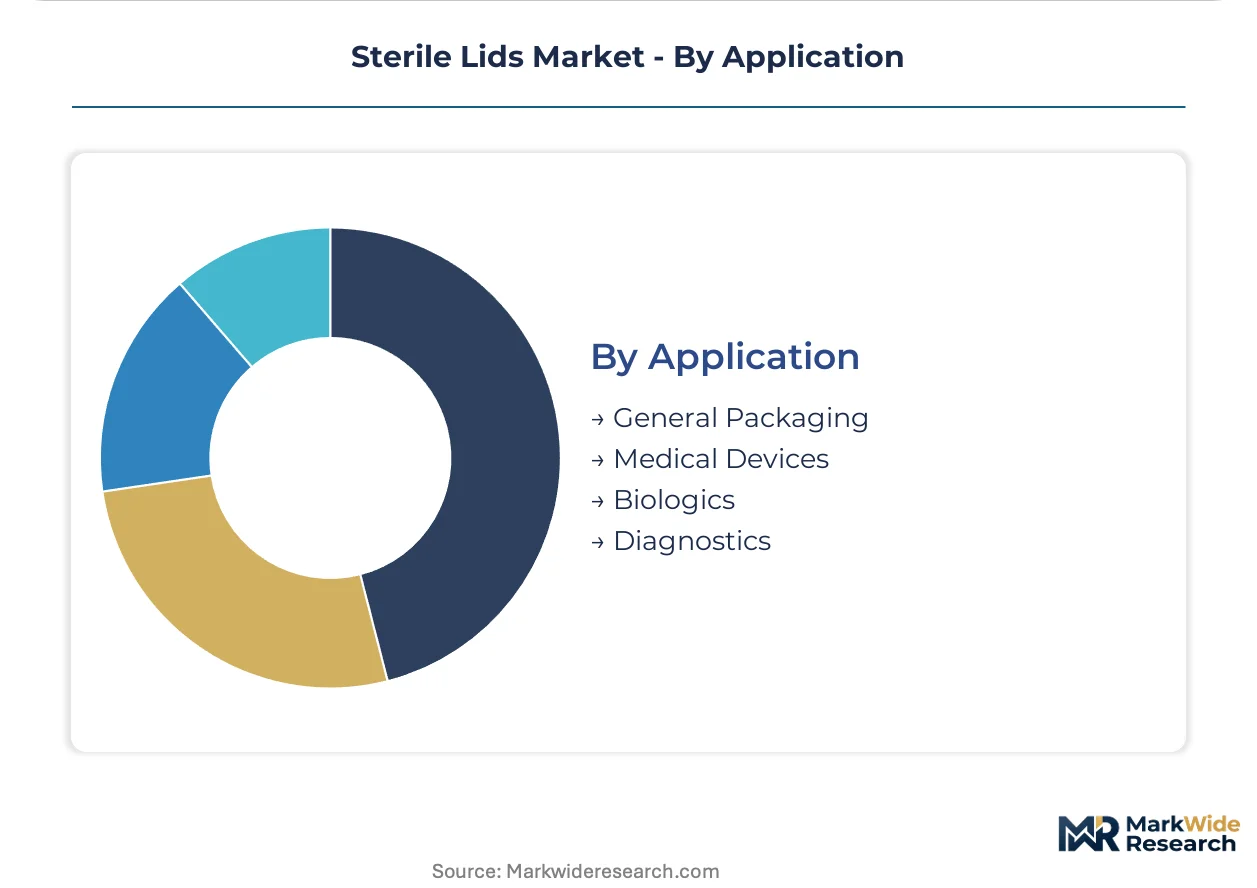
General packaging holds the volume lead, with biologics gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium sterile lid production for parenteral drug formats, while India scales domestic capacity to displace European imports in generic injectable supply chains.
United States
CAR-T manufacturing clusters in Philadelphia and San Diego drive demand for cryogenic-compatible borosilicate glass lids with thermal shock validation. FDA 21 CFR 211 sterility assurance requirements extend supplier qualification timelines for domestic biologics packagers. Consolidated hospital group purchasing organizations in the Midwest and Southeast are unbundling lid procurement from vial contracts, forcing standalone price transparency.
Germany
Injectable drug manufacturing concentrates around Frankfurt and Munich, generating dedicated demand for regional sterilization service capacity and just-in-time lid logistics. EU MDR Annex I tightened sterility assurance requirements mandate redundant barrier validation for closure systems. Gerresheimer and Schott anchor specialized glass and polymer lid production in the Rhine-Main and Upper Bavaria industrial corridors.
India
Domestic pharmaceutical packaging growth creates openings for local lid sterilization and molding capacity to displace European imports in generic injectable supply chains. CDSCO imposes parallel sterilization documentation requirements for imported closure components, shaping supplier qualification timelines. Manufacturing clusters in Maharashtra and Gujarat are attracting polymer lid molding investments to serve export-oriented formulation units.
China
Biologics manufacturing expansion in the Yangtze River Delta and Pearl River Delta is pulling premium material specifications for protein-based drug containers. NMPA container closure integrity testing guidance is converging toward probabilistic detection methods, forcing quality control line upgrades. Domestic COP lid production is scaling to serve local cell therapy developers with break-resistant, low-extractables closure alternatives.
Japan
Precision pharmaceutical packaging demand in the Kanto and Kansai regions sustains specialized borosilicate glass lid consumption for lyophilized drug formats. PMDA sterilization validation protocols align with ICH guidelines, creating regulatory familiarity for Western suppliers. Tokyo-Osaka logistics corridors enable just-in-time delivery of pre-sterilized closure systems to biologics manufacturing sites.
Sterile Lids Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated packaging conglomerates controlling polymer lid supply for high-volume oral dosage formats while glass specialists dominate parenteral and biologic applications. The vendor base organizes around three archetypes: global thermoforming conglomerates with pharmaceutical-dedicated divisions, German glass-ceramic specialists with sterilization service integration, and regional polymer molders serving diagnostic and point-of-care segments. Competitive moves center on backward integration into sterilization service capacity and geographic expansion into Indian and Southeast Asian pharmaceutical manufacturing clusters.
Among German glass-ceramic specialists, Schott AG and Gerresheimer AG exemplify the premium-tier archetype with integrated borosilicate production and validated sterilization lines. West Pharmaceutical Services, Inc. occupies a distinct position in elastomeric closure-lid combinations for high-value biologic containers. These three entities anchor the supply-side structure for extractables-sensitive parenteral applications where regulatory filing requirements concentrate procurement decisions.
| Leading Market Players |
|---|
| Amcor plc |
| DuPont de Nemours, Inc. |
| West Pharmaceutical Services, Inc. |
| Berry Global, Inc. |
| SteriPack Group |
| Gerresheimer AG |
| Schott AG |
| Sonoco Products Company |
| Placon Corporation |
| Others |
Value Chain & Pricing Dynamics
Propylene feedstock benchmarks cascade through naphtha-cracker output disruptions into polypropylene lid margins, compressing pricing power for high-volume oral solid dosage formats while crystalline thermoplastic grades retain premium positioning in biologics segments. German sterilization service concentration around Frankfurt and Munich reinforces regional cost differentials against Asian molding capacity expansion.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for commodity-grade polymer lids, forcing European suppliers toward three-tier pricing structure across premium, standard, and economy levels. Certification grade under EU MDR Annex I and FDA 21 CFR 211 separates validated sterilization documentation tiers, with biologics packagers showing least price sensitivity due to extractables-controlled requirements. Cost compression in oral solid dosage screw caps intensifies because of propylene resin volatility, while glass lid pricing holds firm in parenteral segments.
Supply Chain Analysis
Borosilicate glass supply rests on German and Japanese specialty ceramic producers, with polymer lid molding anchored in China, India, and Germany. Raw material dependencies span propylene monomer from naphtha crackers, gamma-irradiation isotope sourcing, and elastomeric compound formulations. Single-source vulnerability concentrates in Belgium and Netherlands sterilization service clusters. Distribution runs through pharmaceutical CDMO procurement channels and hospital group purchasing organization contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sterile lids market represents a late-cycle quality story as CAR-T and stem cell therapy cold chains pull premium borosilicate glass specifications through supply chains. Extractables validation burdens are concentrating procurement decisions among qualified suppliers with redundant barrier documentation.
For Market Incumbents: Anticipate cyclic olefin polymer substitution pressure in protein-based biologic applications by deepening backward integration into sterilization service capacity and securing validated post-consumer polypropylene feedstock streams ahead of EU Green Deal compliance deadlines. Defend margin position through captive supply of elastomeric closure-lid combinations for high-value containers. For New Entrants and Emerging Players: Domestic Indian pharmaceutical packagers present the most penetrable buyer archetype, with CDSCO import substitution policies creating white-space for local sterilization and molding capacity. Target point-of-care diagnostic cartridge manufacturers adopting snap-cap formats for rapid assembly. Pursue contract development and manufacturing organization qualification pathways as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap polymer molders possessing validated gamma sterilization partnerships and geographic expansion capability into Southeast Asian pharmaceutical clusters. Long-term viability hinges on regulatory filing support infrastructure and extractables toxicologist access. Watch FDA container closure integrity testing guidance evolution as the inflection indicator for probabilistic detection method adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sterilization Services | Captures margin pools from gamma irradiation capacity concentrated in Belgium and Netherlands. |
| Validated Post-Consumer Polypropylene Sourcing | Positions suppliers ahead of EU Green Deal recycled content thresholds for pharmaceutical plastics. |
| Cyclic Olefin Polymer Lid Production Scale-Up | Absorbs demand from glass in protein-based biologics where break resistance and low extractables converge. |
| Regional Molding Capacity in Maharashtra and Gujarat | Serves CDSCO import substitution policies displacing European lid sources in generic injectables. |
| Probabilistic Leak Detection System Integration | Aligns quality control lines with FDA container closure integrity testing guidance for parenteral manufacturers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sterilization service providers, pharmaceutical packaging procurement leads, regulatory affairs directors at biologics manufacturers, and contract research organization analytical chemists. Secondary validation drew from FDA 21 CFR 211 filings, EMA MDR submission databases, CDSCO import registration records, and EU REACH compliance documentation. Bottom-up polymer resin consumption modeling and top-down pharmaceutical packaging value chain analysis provided triangulation.
Historical reference periods anchored volume and value outputs to pre-pandemic baseline sterilization validation cycles, with projection horizons extending through regulatory convergence timelines. Segmentation dimensions modeled include lid material grade, sterilization compatibility matrix, end-use therapeutic category, and regional regulatory cluster. CAGRs derived from sterilization service capacity expansion curves and biologics manufacturing footprint growth. Forecast inputs incorporated propylene feedstock price elasticity and gamma irradiation facility utilization rates.
Inputs from pharmaceutical packaging trade associations and sterilization service provider disclosures were available through the study window; gaps in real-time extractables study protocol standardization introduce uncertainty bands around biologics segment penetration assumptions. Forecasts reflect documented sterilization validation cycle durations and polymer substitution elasticity parameters. Regulatory timeline acceleration or delay, naphtha-cracker supply disruptions, and CDSCO enforcement intensity on import documentation constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Tear-Tab Lids Market
Caps and Closures
Drum Plugs Market
Caps and Closures
Twist Dispensing Closures Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
Bar Top Corks Market
Caps and Closures
Hinged Dual Flap Caps Market
Caps and Closures
Australia and New Zealand Plastic Caps and Closures Market
Caps and Closures
Hinged Dispensing Caps Market
Caps and Closures
Crown Caps Market
Caps and Closures
Plunger Stopper Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
Elastomeric Closures Market
Caps and Closures
Non-Aerosol Overcaps Market
Caps and Closures
Bag Closure Clips Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
Cuvette Caps Market