
 Coated Wet Glue Label Market | 2026-2036
Coated Wet Glue Label Market Size, Share, and Industry Trends Forecast 2026-2036
Coated Wet Glue Label Market Analytics
Asset-light leasing models for coating and converting equipment is narrowing the capital barrier for mid-tier entrants, allowing regional converters to challenge established suppliers. Ahlstrom-Munksjö leverages its integrated pulp-to-label substrate chain to secure raw material certainty. Sappi anchors its position through specialized wet-strength paper grades engineered for high-speed rotary labeling lines. CCL Industries Inc. competes via global manufacturing scale across multiple continents.
Coated wet glue labels are paper-based substrates treated with clay or synthetic binders to achieve controlled absorbency and smooth print surfaces, then applied with water-based adhesives on rotary or linear labeling machines at speeds exceeding 40,000 bottles per hour. Their primary purpose is to deliver premium aesthetic finishes and regulatory compliance information on glass and PET containers in beverage and pharmaceutical packaging. Litho labels occupy the mature volume core of the product mix, while digital labels represent the fastest-growing technology segment as brand owners shorten print runs for seasonal and limited-edition SKUs. Food and beverage applications generate the dominant share of demand, though pharmaceutical labeling commands premium margin pools due to serialization and anti-counterfeiting requirements.
FDA food-contact substance notifications and EU REACH compliance for coating chemistries shape substrate formulation decisions for suppliers serving North American and European brand owners. China's SAMR enforces GB standards for paper materials in direct food contact, creating separate certification pathways for export-oriented versus domestic-label production. India's FSSAI labeling rules for packaged foods are tightening declaration requirements, pulling coated wet glue demand toward compliant pre-printed formats. Stakeholders must monitor how diverging national packaging waste regulations reshape adhesive and substrate specifications across their customer geographies.
Market Dynamics
SKU proliferation among beverage bottlers is fragmenting order volumes and compressing print runs, forcing substrate suppliers to reconfigure coating lines for rapid changeover while maintaining rotary-labeling compatibility.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightening substrate compliance requirements are pulling converters toward certified pre-printed formats that guarantee recyclability and food-contact safety.
- Digital printing adoption:Brand owners are shortening production cycles for seasonal and limited-edition SKUs, expanding addressable demand for shorter-run coated wet glue labels.
- Vietnam and Indonesia manufacturing clusters:Multinational FMCG brands relocating bottling operations to Southeast Asia are expanding regional procurement of coated wet glue labels.
Market Restraints
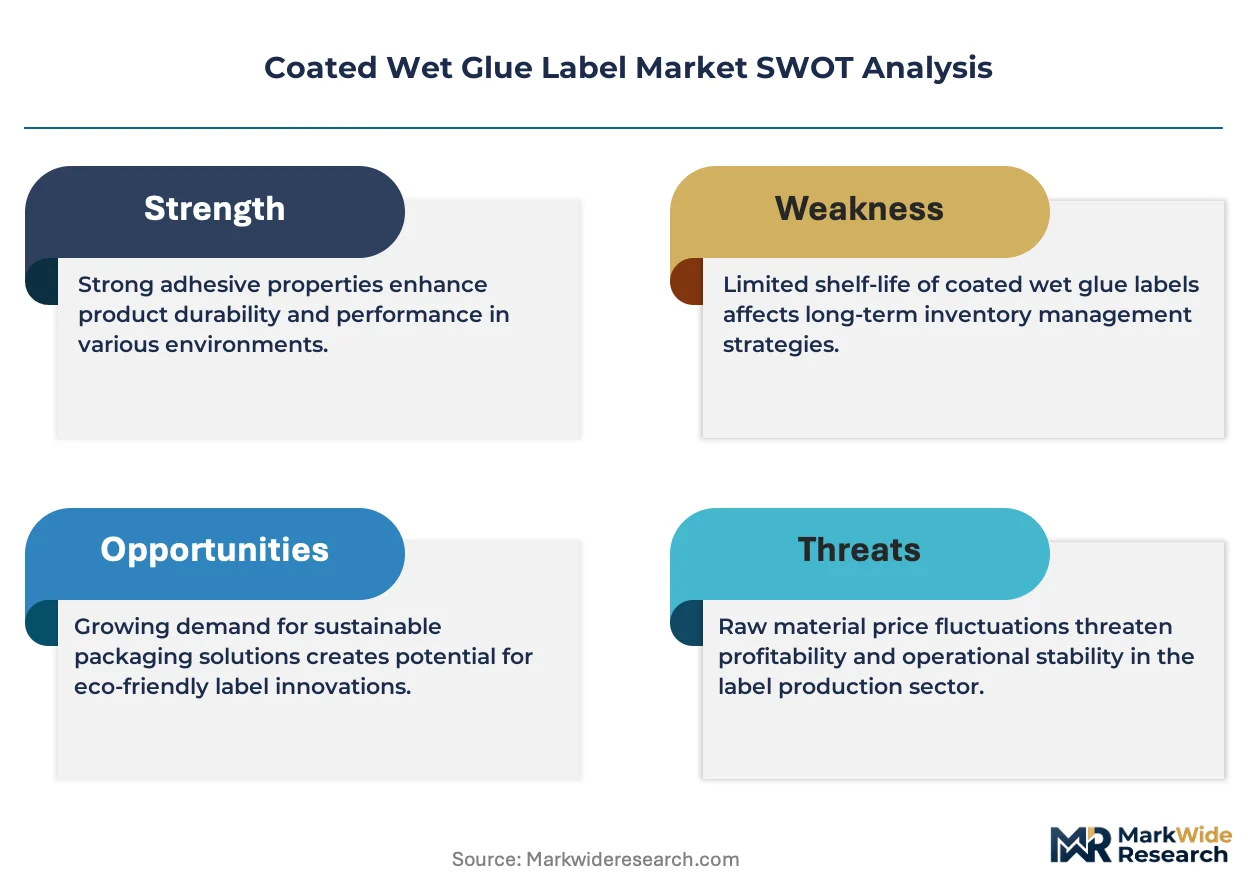
- Pulp price volatility:Integrated pulp-to-label substrate chains provide insulation, but mid-tier converters face margin compression when hardwood pulp markets tighten.
- Coating chemistry certification costs:EU REACH compliance for synthetic binders and clay treatments adds fixed regulatory overhead per substrate formulation.
- Pressure-sensitive adhesive substitution:Self-adhesive labels are capturing share in premium cosmetic and pharmaceutical segments where application speed is secondary to repositionability.
Strategic Opportunities
- India FSSAI labeling mandate expansion:Tightening declaration requirements for packaged foods are accelerating demand for compliant pre-printed coated wet glue formats.
- Serialization integration:Pharmaceutical anti-counterfeiting requirements are creating premium margin pools for labels combining wet-glue adhesion with track-and-trace functionality.
- Asset-light equipment leasing:Regional converters are narrowing capital barriers to challenge established suppliers through coating and converting equipment rental models.
Industry Challenges
- Rotary-labeling line integration:High-speed bottling equipment exceeding 40,000 bottles per hour demands precise absorbency calibration that legacy coating lines struggle to achieve.
- Dual certification pathways:China's SAMR enforces separate GB standards for export-oriented versus domestic-label production, complicating inventory management for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coated Wet Glue Label Market |
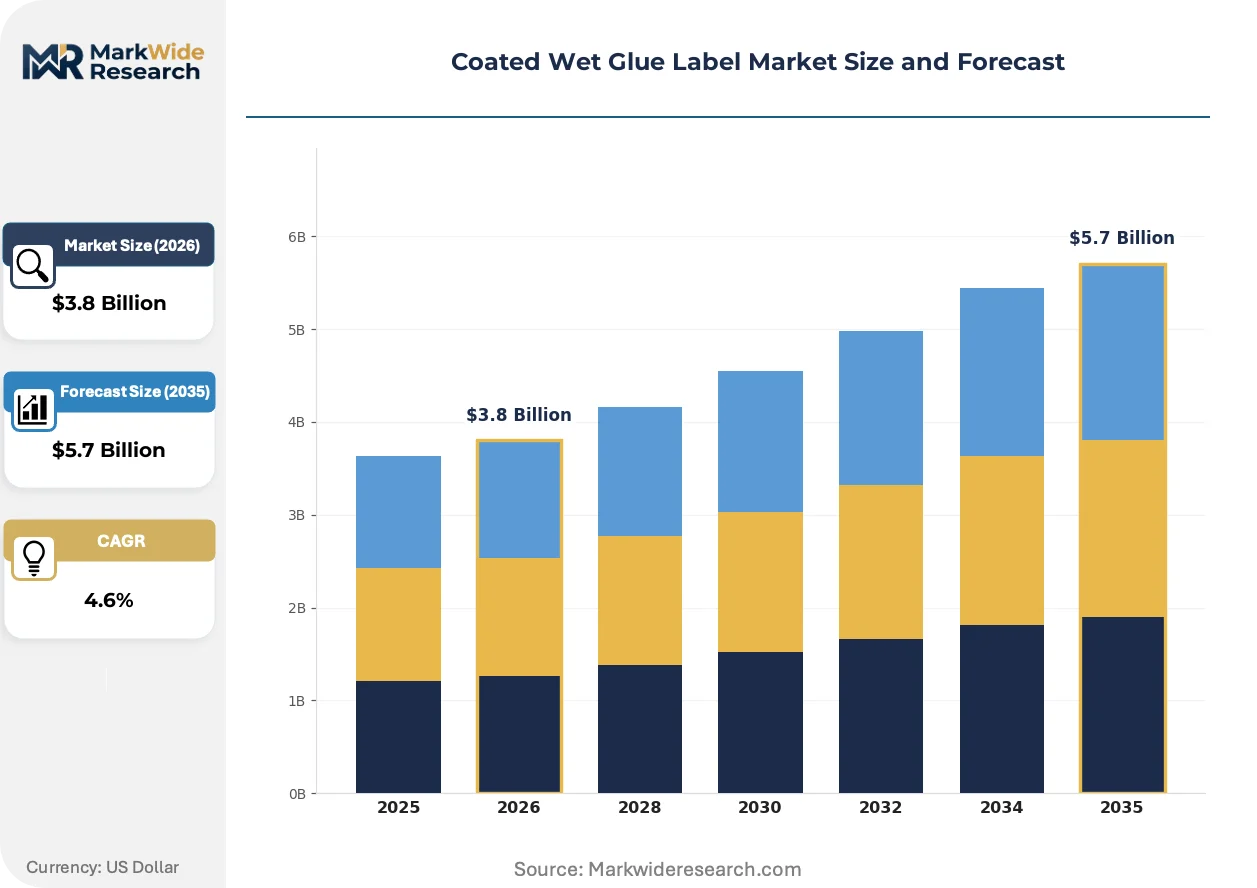
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive Labels, Direct Thermal Labels, Digital Labels, Litho Labels Application: Food & Beverage, Personal Care, Pharmaceuticals, Logistics Technology: Flexographic Printing, Offset Printing, Gravure Printing, Screen Printing End User: Manufacturers, Retailers, Distributors, Brand Owners |
| Companies Covered | Ahlstrom-Munksjö, Sappi, Darley, Royal SENS, Papico, CCL Industries Inc., Avery Dennison Corporation, LINTEC Corporation, UPM Raflatac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coated Wet Glue Label Market Evolving Landscape
Print technology migration and regulatory chemistry mandates are reshaping substrate formulation priorities, while procurement patterns reorient around speed-to-market rather than volume-scale efficiency.
Digital inkjet coating systems are migrating from narrow-format proofing equipment to full-width production lines. Beverage brand owners with seasonal SKU calendars are adopting these systems for runs below 10,000 linear meters. Lithographic label volumes are compressing as digital workflows enable same-day turnaround on promotional labels.
EU REACH restrictions on specific coating chemistries are forcing reformulation of clay and synthetic binder systems. Industrial consequence includes extended certification timelines for new substrate grades. Pharmaceutical labeling segments are responding fastest, prioritizing pre-qualified coating platforms to avoid serialization compliance delays.
Brand owner procurement is fragmenting across multiple regional converters rather than consolidating at single-source suppliers. This pattern disrupts traditional volume-based pricing structures and elevates logistics coordination capabilities. Vietnam and Indonesia bottling clusters exhibit this behavior most acutely, where multinational FMCG procurement teams maintain qualified supplier panels across three to five converters per region.
Coated Wet Glue Label Market Segmentation
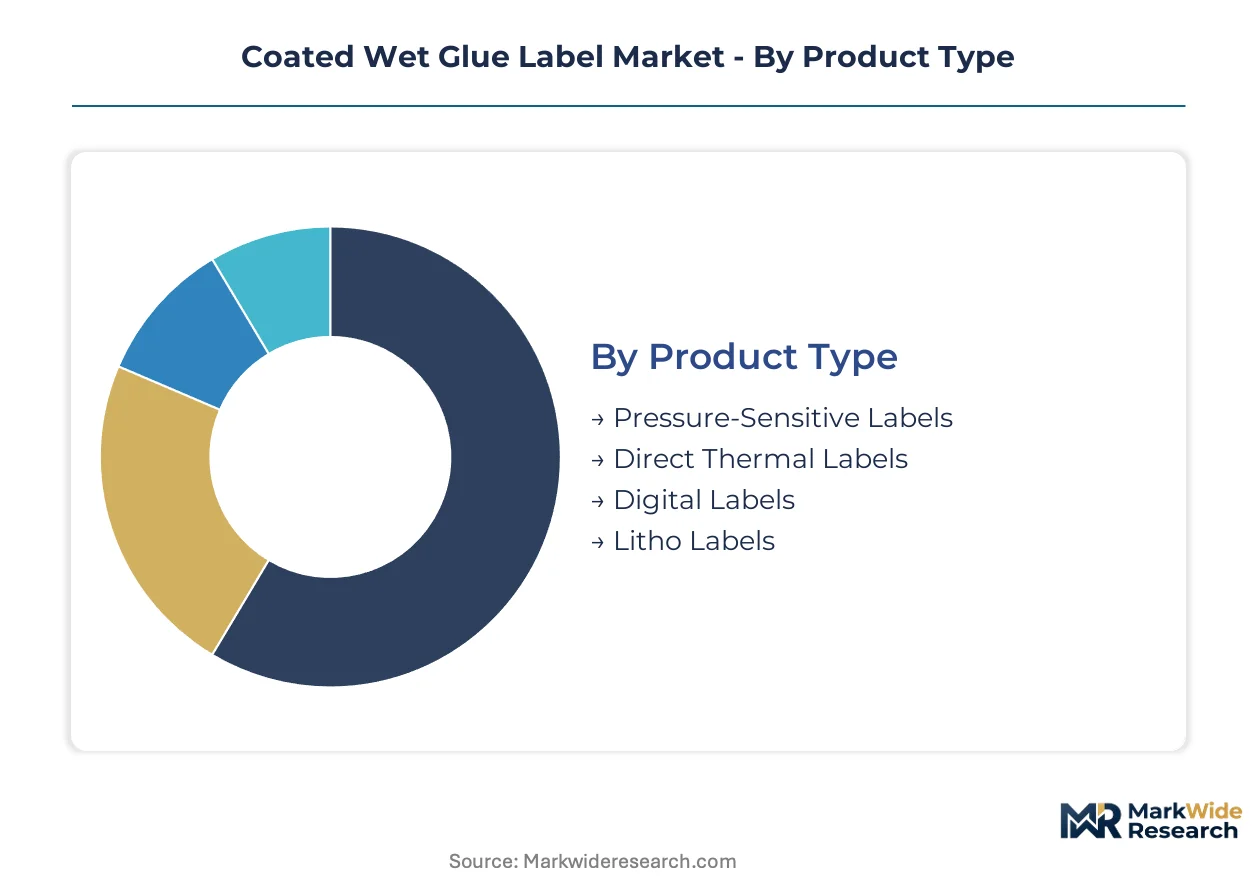
Coated wet glue labels serve distinct operational requirements across substrate technologies, end-use applications, and production methods. Procurement patterns diverge sharply between high-volume beverage bottlers and precision pharmaceutical packagers. Understanding these segment boundaries clarifies where coating specifications, certification burdens, and speed requirements reshape supplier positioning.
Product Type:
The maturity spectrum spans established lithographic formats against emerging digital workflows that compress turnaround times.
- Litho Labels:Clay-coated paper substrates optimized for high-volume rotary application on glass and PET containers. Beverage bottlers in Vietnam and Indonesia procurement clusters specify these grades for runs exceeding 50,000 linear meters, prioritizing unit cost over flexibility.
- Digital Labels:Synthetic binder formulations engineered for variable-data inkjet systems with rapid changeover capability. Seasonal SKU proliferation among multinational FMCG brands concentrates demand here, as same-day turnaround requirements displace traditional plate-based workflows.
- Pressure-Sensitive Labels:Self-adhesive constructions competing at the premium cosmetic margin tier where repositionability outweighs application speed.
- Direct Thermal Labels:Heat-sensitive coatings for short-life logistics applications with minimal aesthetic requirements.
Litho Labels retain volume leadership; Digital Labels hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity beverage procurement from serialization-mandated pharmaceutical specifications.
- Food & Beverage:Dominant demand concentration spanning carbonated soft drinks, bottled water, and alcoholic beverages. China's SAMR GB standards and EU REACH coating compliance create dual certification pathways that fragment supplier qualification.
- Pharmaceuticals:Anti-counterfeiting serialization requirements under FDA and EMA track-and-trace mandates command premium margin pools. Wet-strength paper grades with pre-qualified coating platforms avoid compliance delays that disrupt supply security.
- Personal Care:Premium cosmetic segments where aesthetic finish quality drives substrate selection toward specialized clay treatments.
- Logistics:Functional barcode applications with minimal coating sophistication and compressed procurement cycles.
Food & Beverage anchors procurement volume; Pharmaceuticals generates the highest margin per square meter.
Technology:
Volume concentration favors flexographic and offset platforms while digital adoption reshapes shorter-run economics.
- Flexographic Printing:Rotary letterpress-derived systems dominating beverage label production at speeds exceeding 40,000 bottles per hour. Southeast Asian manufacturing clusters specify flexo-compatible absorbency calibration as a non-negotiable substrate requirement.
- Offset Printing:Lithographic plate systems retaining share in premium spirit and wine labeling where color fidelity and metallic effects justify longer setup times.
- Gravure Printing:Cylinder-engraved methods for ultra-high-volume runs with extended print campaigns and minimal SKU variation.
- Screen Printing:Stencil-based application for heavy ink deposits and tactile varnishes in specialty cosmetic packaging.
Flexographic Printing maintains installed base dominance; digital inkjet migration is accelerating most quickly in seasonal promotional work.
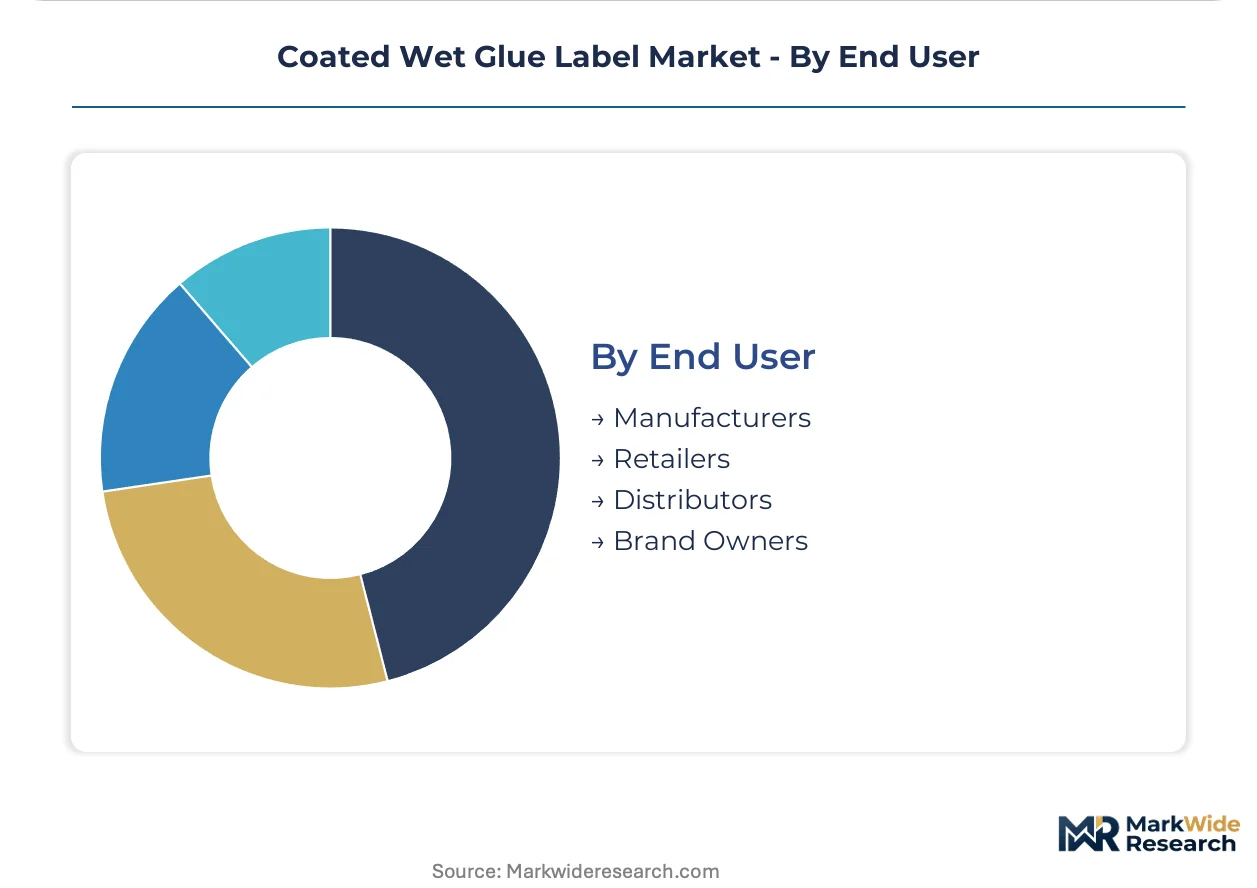
End User:
Customer type segmentation separates capital-intensive manufacturers from asset-light brand owners reconfiguring procurement geography.
- Brand Owners:Multinational FMCG companies fragmenting supplier panels across three to five qualified converters per region. Relocation of bottling operations to Vietnam and Indonesia manufacturing clusters is reshaping regional procurement mandates.
- Manufacturers:Integrated bottling and packaging facilities with captive label specification authority and long-term substrate contracts.
- Distributors:Intermediary procurement channels serving smaller beverage brands without direct converter relationships.
- Retailers:Private-label food and beverage chains with consolidated specification power and price-sensitive substrate requirements.
Brand Owners are driving geographic reconfiguration of demand; Manufacturers retain the largest single-contract volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Packaging and Packaging Waste Regulation revisions are redirecting converter investment toward certified recyclable substrates across multiple geographies. SAMR enforcement of GB standards in China and FSSAI mandate expansion in India are fragmenting compliance pathways. Vietnam and Indonesia bottling clusters are absorbing relocated FMCG production capacity.
China
Beverage bottlers in Yangtze River Delta manufacturing zones are scaling procurement of food-contact-compliant coated wet glue labels. SAMR enforces separate GB certification pathways for export-oriented versus domestic-label production, complicating inventory management for multi-market suppliers. Shanghai and Jiangsu province converters are reconfiguring coating lines to handle rapid changeover requirements.
United States
Pharmaceutical serialization mandates under FDA track-and-trace regulations are pulling demand toward pre-qualified wet-strength paper grades. Beverage brand owners in California and Texas are shortening print runs for seasonal SKU proliferation. Midwest coating facilities are upgrading absorbency calibration to maintain rotary-labeling compatibility above 40,000 bottles per hour.
Germany
EU REACH compliance costs for synthetic binders are compressing margins at mid-tier converters serving premium spirit labeling. North Rhine-Westphalia and Bavaria host integrated pulp-to-label substrate chains that insulate against hardwood pulp volatility. ECHA regulatory timelines are extending certification cycles for new coating formulations.
India
FSSAI labeling rule tightening for packaged foods is accelerating demand for compliant pre-printed formats in Maharashtra and Gujarat. Domestic beverage brands are fragmenting supplier panels across three to five qualified converters per region. Karnataka pharmaceutical packagers are integrating anti-counterfeiting serialization into wet-glue label specifications.
Vietnam
Multinational FMCG relocation of bottling operations to Ho Chi Minh City and Binh Duong provinces is expanding regional procurement of rotary-compatible coated wet glue labels. Asset-light equipment leasing models are narrowing capital barriers for emerging regional converters. Procurement teams maintain qualified supplier panels across multiple domestic coating facilities.
Coated Wet Glue Label Market Competitive Landscape
On the supply side, the industry is tiered between integrated pulp-to-label substrate chains, specialized wet-strength paper producers, and asset-light regional converters. Three strategic archetypes dominate: backward-integrated fiber suppliers controlling raw material certainty, coating specialists engineering absorbency calibration for high-speed lines, and global manufacturing scale players spanning multiple continents. Dominant competitive moves include coating line reconfiguration for rapid digital changeover and strategic partnerships with bottling equipment OEMs.
Among integrated substrate suppliers, Ahlstrom-Munksjö and Sappi exemplify archetypes anchoring distinct competitive positions. CCL Industries Inc. occupies a position representing global manufacturing scale across multiple continents. These three names illustrate how supply-side configuration varies from captive fiber control through specialized paper engineering to geographic diversification.
| Leading Market Players |
|---|
| Ahlstrom-Munksjö |
| Sappi |
| Darley |
| Royal SENS |
| Papico |
| CCL Industries Inc. |
| Avery Dennison Corporation |
| LINTEC Corporation |
| UPM Raflatac |
| Others |
Value Network & Pricing Analysis
Overcapacity in European coating facilities is compressing margins for mid-tier converters while tightening hardwood pulp markets in Southeast Asia reward integrated fiber suppliers with pricing power. This utilization divergence is fragmenting procurement leverage across the coated wet glue label value chain.
Pricing Analysis
Certification level creates the primary spread between substrate tiers, with EU REACH-compliant and FDA food-contact-grade formulations commanding premiums over standard industrial grades. Contract-based long-term offtake dominates volume procurement for beverage bottlers, while spot purchasing persists for seasonal promotional runs. Price differentiation reflects both regulatory compliance burden and wet-strength calibration precision for high-speed rotary lines. Brand owners in Vietnam and Indonesia manufacturing clusters exhibit highest price sensitivity, whereas pharmaceutical packagers prioritize supply security over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced coating chemistry formulations limit technology transfer to emerging converters in Vietnam and Indonesia. Supply concentrates in Finland, South Africa, and China for specialty pulp grades, with coating chemical dependencies drawing from German and Swiss specialty chemical producers. Single-source vulnerability runs through hardwood pulp supply contracts tied to Nordic forestry operations. Distribution runs through regional converter networks rather than direct mill-to-brand relationships, elevating logistics coordination requirements for multinational FMCG procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coated wet glue label demand is recovering from cyclical lows as beverage bottlers restock inventories ahead of seasonal SKU proliferation cycles. This restocking pattern favors suppliers with rapid changeover capabilities.
For Market Incumbents: Entrench position by securing captive pulp supply through backward integration into Nordic or South African fiber assets. Invest in pre-qualified coating platforms for pharmaceutical serialization compliance to defend against pressure-sensitive adhesive substitution in premium segments. Prioritize equipment leasing partnerships that lock emerging regional converters into proprietary substrate specifications.
For New Entrants and Emerging Players: Mid-market beverage converters in Vietnam and Indonesia represent the most penetrable entry point, where asset-light leasing models narrow capital barriers. Target seasonal promotional label segments with digital inkjet coating capabilities that established litho-focused suppliers underserve. Pursue qualified supplier panel status with multinational FMCG procurement teams through rapid turnaround demonstrations.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated pulp-to-label substrate chains with long-term beverage contracts. Five-to-ten-year viability favors specialists with wet-strength paper engineering capabilities and dual certification pathways for Chinese export and domestic markets. Monitor EU Packaging and Packaging Waste Regulation implementation timelines as inflection indicators for certified recyclable substrate demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Coating Line Digitalization | Enables same-day turnaround for seasonal SKUs under 10,000 linear meters. |
| Backward Integration into Pulp | Insulates margin from hardwood price volatility through captive fiber supply. |
| Pre-Qualified Coating Platforms | Avoids EMA serialization compliance delays for pharmaceutical label contracts. |
| Regional Converter Partnerships | Secures qualified supplier panel status with relocated FMCG bottling operations. |
| Asset-Light Equipment Leasing | Lowers capital barriers for mid-tier entrants challenging established suppliers. |
Research Methodology
Operator-level perspectives from coating line engineers, beverage procurement managers, pharmaceutical packaging specialists, and regulatory compliance officers anchored the qualitative base. These primary insights were cross-referenced with customs trade data for pulp and paper substrates, SEC filings from integrated fiber suppliers, SAMR GB standard documentation, and EU REACH regulatory databases. Bottom-up volume estimates from individual converter capacities were triangulated against top-down demand projections from beverage bottling expansion announcements.
Scenario-bracketing framed the analytical approach across the projection horizon, with baseline, upside, and downside cases reflecting divergent pulp price trajectories and regulatory implementation timelines. Segmentation dimensions modeled include substrate technology, end-use application, print technology, and geographic production cluster. CAGRs were derived from weighted average growth rates across these segments, incorporating rotary-labeling line speed requirements and digital inkjet adoption curves as industry-specific forecast inputs.
Practitioners should monitor hardwood pulp futures, EU REACH restriction list updates, and FSSAI labeling mandate expansion for early signals of forecast revision. Forecasts reflect assumptions about continued SKU proliferation, stable rotary-labeling equipment installed base, and gradual digital print migration. Material shifts in China SAMR enforcement intensity or sudden pulp supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Global Laminated Labels Market
Labels
Global Sensormatic Labels Market
Labels
Healthcare and Laboratory Labels Market
Labels
Wet Glue Labels Market
Labels
Laser Printable Wristbands Market
Labels
Global Pressure Labels Market
Labels
Global Waterproof Labels Market
Labels
Wrap Around Labels Market
Labels
United States Print Label Market
Labels
Glue Applied Automotive Labels Market
Labels
Retro-Reflective Labels Market
Labels
Shipping Label Market
Labels
ESD Protective Signage Labels Market
Labels
BOPP Labels Market
Labels
Industrial Label Printers Market
Labels
Roll-fed Wraparound Label Substrates Market