
 Single Serve Packaging Market | 2026-2036
Single Serve Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Single Serve Packaging Market Outlook
Multi-source resin procurement is shifting toward captive polymer supply as converters seek margin protection against petrochemical volatility. Amcor plc leverages its global film extrusion footprint to secure polyethylene terephthalate supply chains across three continents. Berry Global anchors North American dairy cup production through in-house thermoforming capacity. Huhtamaki differentiates in fiber-based single-serve lids, responding to brand owner sustainability mandates.
Single serve packaging denotes individually portioned containers designed for one-time consumption, typically ranging from 50 milliliters to 500 milliliters in fill volume, constructed through thermoforming, blow molding, or pouch converting processes to maximize shelf stability and minimize contamination risk. The format serves food service operators and retail channels requiring hygiene assurance, inventory precision, and waste reduction at point of use. Stand-up pouches capture the fastest expansion in flexible single serve formats as retortable barrier films displace metal cans for ready meals. Sachets dominate pharmaceutical unit-dose delivery where moisture barrier properties determine compliance rates in tropical climates. Rigid plastic bottles retain volume leadership in beverage single serve, though margin compression from recycled content mandates intensifies.
The FDA regulates direct food contact substances under 21 CFR 177, while the EPA administers per- and polyfluoroalkyl substance restrictions affecting grease-resistant coatings on paper-based single serve items. The EU F-Gas Regulation phases down hydrofluorocarbon use in foam insulation for temperature-controlled single serve packaging. Stakeholders must monitor evolving extended producer responsibility fee structures to determine whether centralized collection infrastructure or material redesign delivers lower total compliance cost.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are forcing converters to redesign material stacks around mechanical recyclability, compressing legacy multilayer structures and rewiring resin procurement relationships across the value chain.
Growth Catalysts
- Ready-to-drink beverage demand:Portion-controlled formats align with on-the-go consumption patterns in urban transit corridors. Single-serve bottles and pouches displace fountain dispensers in convenience retail.
- EU F-Gas Regulation phase-down:Hydrofluorocarbon restrictions on foam insulation accelerate investment in alternative temperature-control technologies for chilled single-serve distribution.
- Retortable barrier films:Polymer metallization advances enable shelf-stable ready meals in flexible pouches, capturing food service and military ration contracts previously served by metal cans.
Market Restraints
- Recycled content mandates:FDA 21 CFR 177 compliance timelines for post-consumer PET in direct food contact lag mechanical recycling capacity expansion, creating qualification bottlenecks.
- Resin supply concentration:Gulf Coast petrochemical corridor disruptions transmit volatility to polyethylene and polypropylene pricing within North American converter networks.
- PFAS restrictions:EPA per- and polyfluoroalkyl substance limits on grease-resistant paper coatings eliminate incumbent barrier solutions before fluorine-free alternatives achieve equivalent performance.
Strategic Opportunities
- German coffee pod penetration:Household single-serve brewing system saturation creates aftermarket service and private-label pod manufacturing demand across Central Europe.
- Pharmaceutical unit-dose sachets:Tropical climate moisture barrier requirements drive specification upgrades in Southeast Asian and Sub-Saharan African distribution.
- Extended producer responsibility fee structures:EU member state collection infrastructure investments may lower total compliance cost for fiber-based lid formats versus plastic alternatives.
Industry Challenges
- Thermoforming tool qualification:In-house mold fabrication capacity scarcity delays new product launches as converters internalize production previously outsourced to specialized toolmakers.
- Legacy filling line integration:Retrofitting high-speed rotary equipment for lightweighted container geometries requires mechanical and controls engineering coordination across OEM and converter teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Serve Packaging Market |
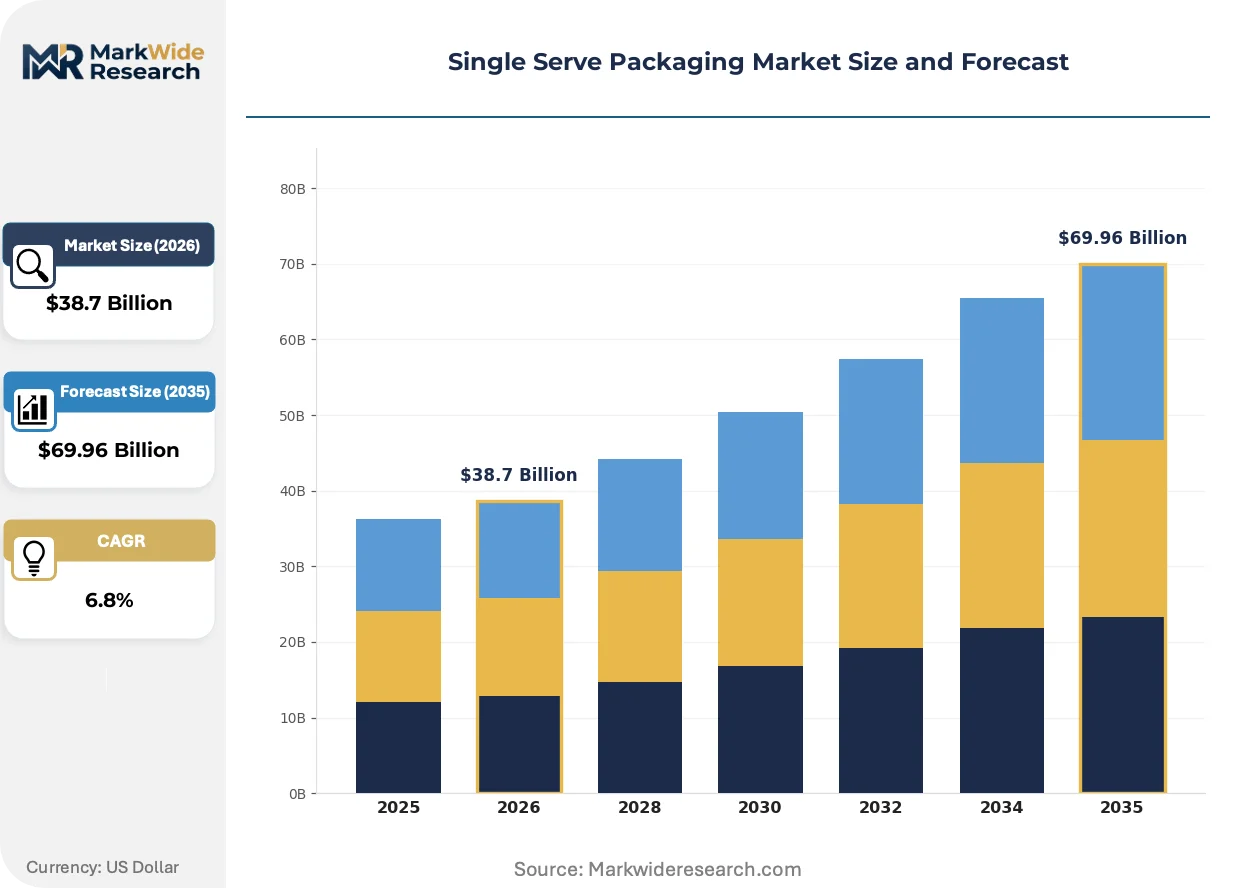
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Bottles, Cups, Sachets Material: Plastic, Glass, Aluminum, Paper End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Packaging Type: Flexible Packaging, Rigid Packaging, Composite Packaging, Others |
| Companies Covered | Sealed Air, Constantia Flexibles, Berry Global, Tetra Pak, Winpak, Amcor plc, Huhtamaki, ProAmpac, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Serve Packaging Market Strategic Shifts
Material science advances and regulatory compression are rewriting the technical specification landscape for single-serve formats, with barrier performance, end-of-life fate, and line speed compatibility now jointly optimized rather than sequentially traded off.
High-barrier ethylene vinyl alcohol copolymer films are converging with polyethylene sealant layers in coextruded structures that maintain oxygen transmission specifications while enabling mechanical recycling stream compatibility. Dairy and ready-meal processors in Germany and France are qualifying these materials for retort applications at accelerated timelines. The convergence is compressing incumbent aluminum foil lamination demand in segments where microwaveability and sustainability claims carry procurement weight.
EU F-Gas Regulation hydrofluorocarbon phase-down mandates are eliminating incumbent foam-in-place insulation for temperature-controlled pharmaceutical and food single-serve distribution. Vacuum-insulated panel and phase-change material alternatives require redesigned pack-out geometries and qualification testing protocols. Cold-chain logistics providers serving Nordic and Alpine markets are piloting these substitutions ahead of 2030 reduction targets.
Food service operators are consolidating procurement around approved supplier lists that pre-qualify packaging formats for corporate sustainability scorecards. Broadline distributors are responding with private-label single-serve SKUs specified to chain-level material recovery commitments. The shift is most visible in US quick-service restaurant networks where franchisee purchasing cooperatives negotiate system-wide format standardization.
Single Serve Packaging Market Segmentation
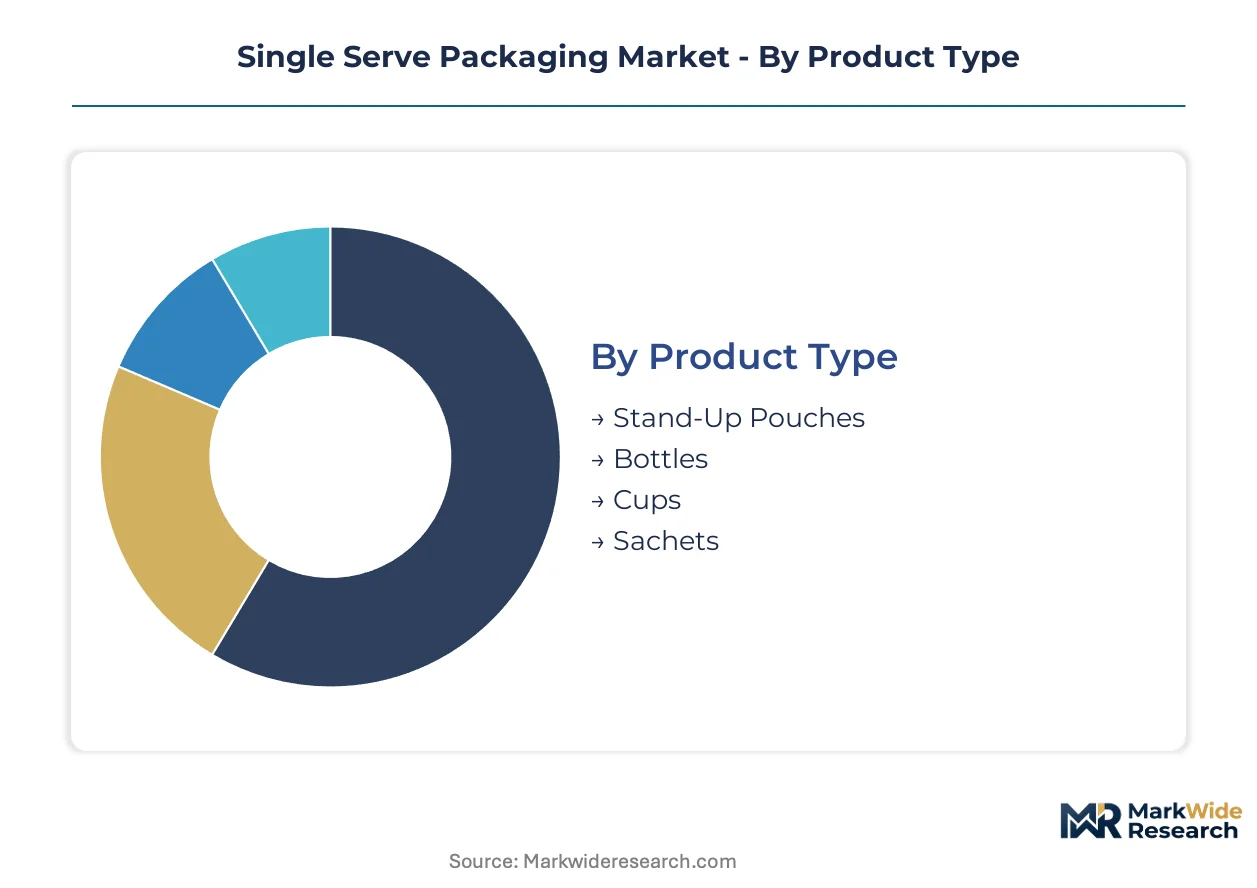
Single serve packaging segmentation reveals how format selection locks in manufacturing investment and end-use compatibility. Product geometry determines filling line configuration, while material choice predetermines regulatory qualification pathways and recovery infrastructure requirements.
Product Type:
Stand-alone formats operate independently of dispensing systems, while embedded formats require proprietary brewing or dosing equipment to function.
- Stand-Up Pouches:Flexible multilayer structures with gusseted bases enable vertical shelf presentation and efficient pallet utilization. Retortable barrier films from German converters are displacing metal cans in ready-meal applications where microwaveability drives procurement decisions.
- Bottles:Blow-molded polyethylene terephthalate containers dominate beverage single serve through compatibility with high-speed rotary filling equipment. FDA 21 CFR 177 compliance timelines for post-consumer recycled content create qualification bottlenecks for brand owners targeting sustainability commitments.
- Cups:Thermoformed polypropylene or polystyrene vessels serve dairy and ready-to-drink applications with precision portion control.
- Sachets:Small-format flexible pouches deliver pharmaceutical unit doses and condiment portions where moisture barrier properties determine shelf stability in tropical distribution.
Volume placements concentrate in Bottles; the faster expansion belongs to Stand-Up Pouches.
Material:
Cost tiers separate commodity resins from performance substrates requiring specialized recovery infrastructure.
- Plastic:Polyethylene terephthalate, polypropylene, and polyethylene resins offer tunable barrier properties through coextrusion and metallization. EU Packaging and Packaging Waste Regulation mechanical recyclability mandates are compressing multilayer structures toward monomaterial designs.
- Glass:Borosilicate and soda-lime containers provide inert contact surfaces for premium beverage and pharmaceutical applications. Weight penalties limit adoption in e-commerce distribution where dimensional pricing dominates.
- Aluminum:Drawn or impact-extruded metal delivers absolute oxygen and light barriers for sensitive formulations.
- Paper:Fiber-based substrates with aqueous or biopolymer coatings respond to brand owner sustainability scorecards. PFAS restrictions under EPA regulations eliminate incumbent grease-resistant barriers before fluorine-free alternatives achieve equivalent performance.
Plastic captures the largest installed base; paper substrates are climbing the fastest as EPR fee structures favor fiber recovery.
End User:
Application maturity separates established food service procurement from emerging pharmaceutical specifications.
- Food & Beverage:Quick-service restaurant networks and convenience retail channels drive standardization around portion-controlled formats. Broadline distributors consolidate procurement through approved supplier lists tied to corporate sustainability commitments.
- Pharmaceuticals:Unit-dose sachets and blister packs require moisture barrier validation for tropical climate distribution. Southeast Asian regulators are tightening stability testing protocols for polymer-based single serve formats.
- Personal Care:Single-use sample sachets and ampoules serve trial-size marketing and travel retail segments.
- Household:Pre-measured detergent pods and cleaning concentrates embed water-soluble films for safe handling.
Food & Beverage maintains volume dominance; Pharmaceuticals shows the steepest expansion trajectory as unit-dose compliance requirements spread.
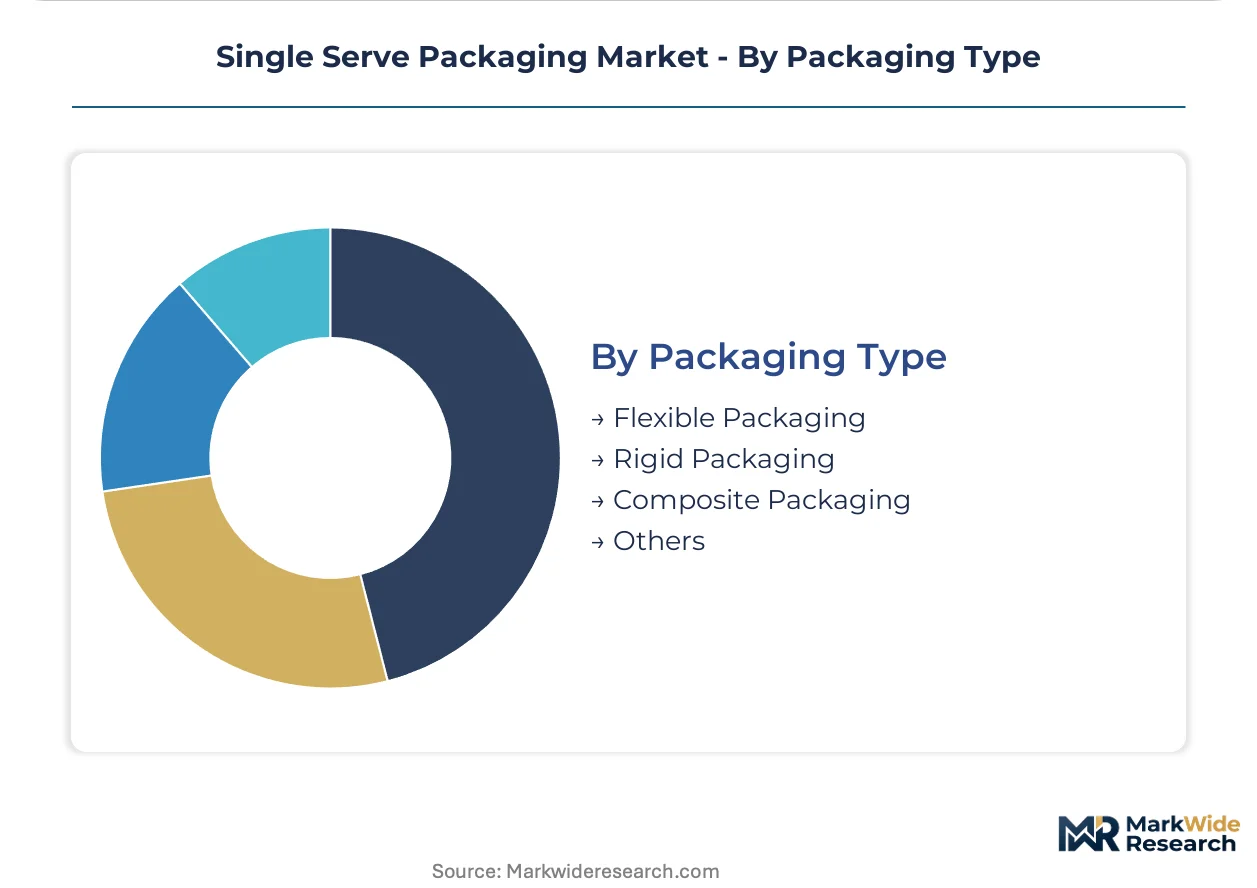
Packaging Type:
Structural rigidity determines supply chain handling requirements and shelf presence intensity.
- Flexible Packaging:Pouches, sachets, and films minimize material weight and cube utilization in distribution. Retortable barrier advances enable shelf-stable protein formats previously requiring rigid metal containment.
- Rigid Packaging:Bottles, cups, and jars provide structural protection and premium tactile properties. German dairy processors are qualifying lightweighted thermoformed cups with in-mold labels for mechanical recycling stream compatibility.
- Composite Packaging:Paperboard-plastic or metal-plastic laminates combine barrier performance with printability. EU member state extended producer responsibility schemes impose higher fees on non-recyclable multilayer structures.
- Others:Vacuum-insulated panels and phase-change material systems address temperature-controlled pharmaceutical distribution. EU F-Gas Regulation hydrofluorocarbon phase-down accelerates adoption of these alternatives in Nordic cold-chain networks.
Rigid formats hold the largest installed equipment base; flexible structures are gaining share fastest as retortable film technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability along the US Gulf Coast and polymer conversion clusters in Germany's Rhine-Ruhr corridor anchor regional supply networks for single-serve packaging materials.
United States
Quick-service restaurant chains and convenience retail channels drive portion-controlled beverage format procurement. FDA 21 CFR 177 compliance timelines for post-consumer recycled PET create qualification bottlenecks for brand owners. Houston-area resin producers supply polyethylene and polypropylene to converters across the Southeast and Midwest dairy processing belts.
Germany
Household single-serve coffee brewing system saturation generates aftermarket pod manufacturing demand. EU Packaging and Packaging Waste Regulation mechanical recyclability mandates compress multilayer structures toward monomaterial designs. The Rhine-Ruhr industrial corridor hosts thermoforming operations serving Central European dairy and ready-meal processors.
China
E-commerce beverage distribution and on-the-go consumption in tier-one cities accelerate flexible pouch adoption. NMPA stability testing protocols for polymer-based pharmaceutical unit-dose formats tighten qualification requirements. Yangtze River Delta converters supply retortable barrier films to domestic and Southeast Asian food processors.
India
Tropical climate pharmaceutical distribution drives moisture barrier specification upgrades for unit-dose sachets. FSSAI food contact material regulations align with evolving ASEAN harmonization frameworks. Gujarat and Maharashtra polymer processing clusters expand thermoforming capacity for dairy and beverage single-serve applications.
Brazil
Ready-to-drink juice and dairy beverage penetration in urban transit corridors supports rigid bottle demand. ANVISA pharmaceutical packaging stability requirements influence regional specification patterns. São Paulo-state converters serve Southeast Brazilian food service and retail distribution networks.
Single Serve Packaging Market Competitive Environment
Global majors compete with regional champions across resin supply security and converter network density. The vendor base stratifies into integrated resin-to-package conglomerates, specialized film and thermoforming converters, and equipment-integrated solution providers. Three archetypes dominate: captive polymer supply operators, barrier technology specialists, and food service channel consolidators. Capacity expansion and strategic material partnerships represent the primary competitive vectors as converters secure feedstock access against petrochemical volatility.
Within the integrated multinational tier, Amcor plc and Berry Global exemplify scale-driven resin security and geographic footprint strategies. Huhtamaki occupies a position among fiber-based format specialists responding to sustainability procurement mandates. These three entities represent distinct competitive archetypes—global film extrusion integration, North American dairy cup manufacturing concentration, and molded fiber lid differentiation—without implying specific strategic actions or market share positions.
| Leading Market Players |
|---|
| Sealed Air |
| Constantia Flexibles |
| Berry Global |
| Tetra Pak |
| Winpak |
| Amcor plc |
| Huhtamaki |
| ProAmpac |
| Sonoco Products Company |
| Others |
Value Chain & Pricing Dynamics
Tool-and-die engineering talent concentration in Germany's Rhine-Ruhr corridor compresses thermoforming mold lead times, widening the pricing spread between premium custom formats and standard off-the-shelf single-serve containers.
Pricing Analysis
Service bundling separates converter pricing tiers, with in-house mold fabrication and filling line integration support commanding premiums over bare component supply. Three-tier pricing structure across premium, standard, and economy levels reflects barrier performance grades and FDA 21 CFR 177 compliance certification status. Cost compression in economy-tier PET bottles intensifies as recycled content mandates force qualification investments. Quick-service restaurant procurement cooperatives exhibit highest price sensitivity; pharmaceutical brand owners prioritize barrier validation over unit cost.
Supply Chain Analysis
Skilled thermoforming technician availability constrains capacity expansion in Germany, the United States, and China's Yangtze River Delta. Resin supply draws from Gulf Coast petrochemical complexes, Rhine-Ruhr polymer producers, and Sinopec integrated refineries. Single-source vulnerability concentrates in specialty barrier film substrates where EVOH copolymer production clusters in Japan and South Korea. Distribution runs through broadline foodservice distributors and OEM direct procurement channels serving dairy and beverage processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
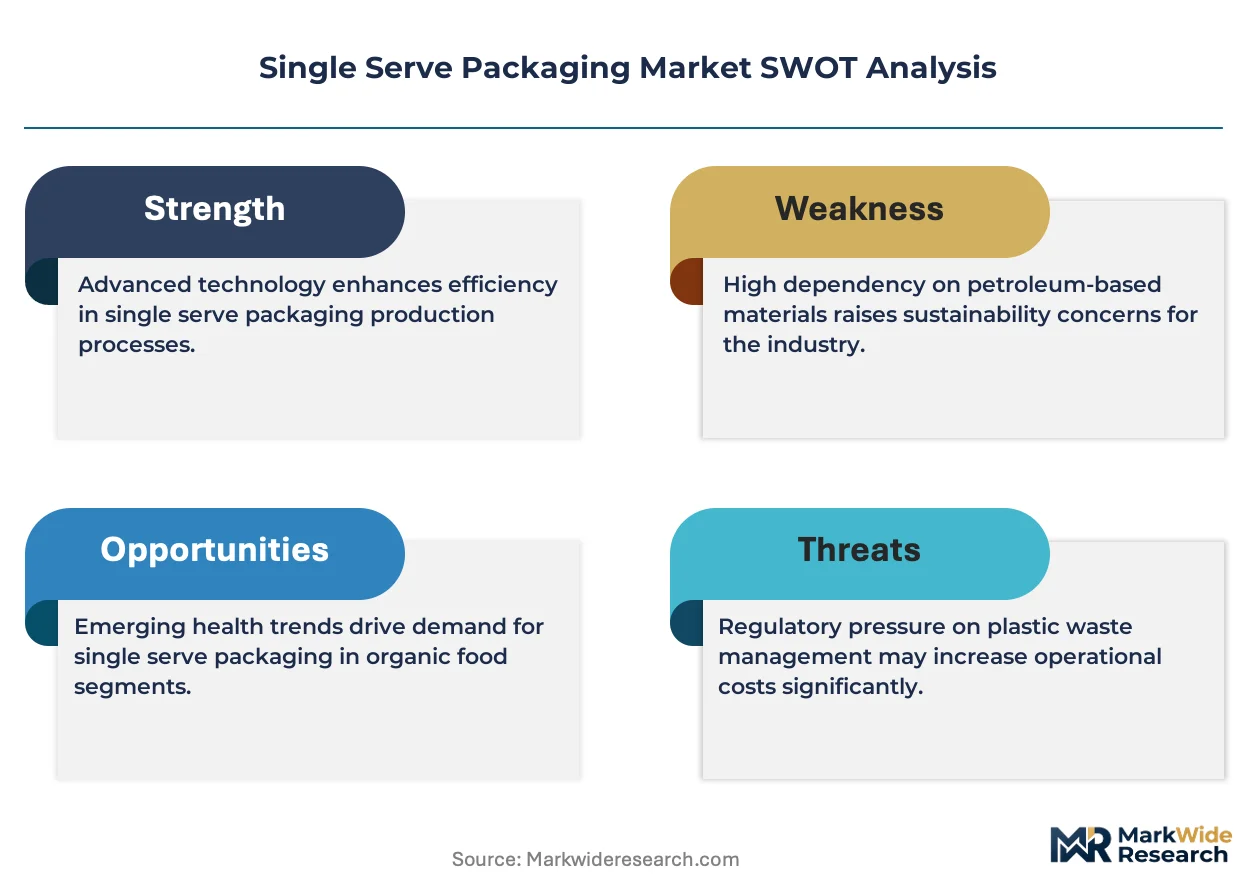
The EU Packaging and Packaging Waste Regulation's mechanical recyclability mandates erect capital-intensive compliance barriers that protect incumbents with qualified monomaterial platforms while filtering out undercapitalized converters.
For Market Incumbents: Hedge resin cost exposure through captive polymer supply arrangements or long-term offtake contracts with Gulf Coast and Rhine-Ruhr producers. Expand in-house thermoforming tool fabrication capacity to compress new product launch timelines against specialized moldmaker bottlenecks. Prioritize EVOH-PE coextrusion qualification for retort applications to defend position against aluminum foil lamination substitutes. For New Entrants and Emerging Players: Capture private-label pod manufacturing demand in Germany's aftermarket coffee brewing segment where household penetration saturation creates volume anchor contracts. Target pharmaceutical unit-dose sachet specifications for tropical climate distribution in Southeast Asia, where moisture barrier upgrades outpace incumbent converter capacity. Lead with fiber-based lid formats that align with EU extended producer responsibility fee structures favoring fiber recovery. For Investors and Strategic Acquirers: Re-rating potential sits with barrier technology specialists given retortable film displacement of metal cans across ready-meal and military ration applications. Long-term viability favors converters with demonstrated FDA 21 CFR 177 qualification timelines and established brand owner sustainability scorecard relationships. Watch EU member state collection infrastructure investment announcements as inflection signals for fiber-based format competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Monomaterial Platform Qualification | FDA 21 CFR 177 compliance for post-consumer PET unlocks brand owner sustainability procurement. |
| In-House Thermoforming Capacity | Rhine-Ruhr and Yangtze Delta tool fabrication compresses lead times against specialized moldmakers. |
| Retortable Barrier Film Scale-Up | EVOH-PE coextrusion captures ready-meal contracts from incumbent aluminum foil laminators. |
| Fiber-Based Lid Manufacturing | Huhtamaki-format molded fiber responds to quick-service restaurant sustainability scorecard mandates. |
| Pharmaceutical Sachet Validation | Tropical climate moisture barrier testing opens Southeast Asian and Sub-Saharan African distribution. |
Study Parameters
Independent corroboration across converter plant managers, brand owner packaging engineers, and foodservice distributor procurement leads underwrites the qualitative findings. Primary fieldwork included technical directors at German thermoforming operations, sustainability officers at US quick-service restaurant chains, and regulatory affairs specialists navigating FDA and EU F-Gas compliance. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation documents, FDA 21 CFR 177 guidance updates, and SEC filings of publicly traded packaging converters. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Rate-of-change decomposition separates volume growth from value expansion across the analysis window. Segmentation dimensions include product geometry (stand-up pouch, bottle, cup, sachet), material substrate (plastic, paper, aluminum, glass), and end-use vertical (food and beverage, pharmaceutical, personal care, household). CAGRs derive from fitted trend extrapolation adjusted for regulatory phase-in timelines and recycling infrastructure buildout assumptions. Forecast inputs incorporate EU F-Gas Regulation hydrofluorocarbon reduction schedules and post-consumer PET mechanical recycling capacity expansion curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU member state extended producer responsibility fee structure variations and FDA recycled content qualification timeline shifts. Assumptions reflect current regulatory trajectories without anticipating unannounced rulemakings. A small set of triggers warrants ongoing watch: Gulf Coast petrochemical disruption events, breakthrough fluorine-free grease-resistant coating performance, and German coffee pod system replacement cycle timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Middle East and Africa Aerosol Cans Market
Packaging Containers
Euro Box Market
Packaging Containers
Dispensing Trays Market
Packaging Containers
Child Resistant Bottles Market
Packaging Containers
Wide Mouth Bottles Market
Packaging Containers
Wrist Watch Packaging Market
Packaging Containers
North America Food Cans Market
Packaging Containers
Bottles Market
Packaging Containers
Self - Locking Trays Market
Packaging Containers
Double Seam Bowl Market
Packaging Containers
Pump Dispenser Market
Packaging Containers
Portion Packs Market
Packaging Containers
Plasma Bottle Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
Correx Trays Market
Packaging Containers
Monobloc Aerosol Cans Market