
 PP Film Blowing Machine Market | 2026-2036
PP Film Blowing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
PP Film Blowing Machine Market Analytics
A capital-intensity divergence between integrated European builders and Asian volume suppliers is rotating competitive dynamics across the PP film blowing machine landscape. Reifenhäuser Group leverages captive component foundries in Germany to sustain margin on multi-layer co-extrusion lines. JWELL Extrusion Machinery anchors its position through standardized platform architectures that compress delivery cycles for mid-tier packaging converters. Rajoo Engineers differentiates via localized aftermarket service density across South Asian agricultural film markets.
A PP film blowing machine extrudes polypropylene resin through a circular die, inflates the molten tube with controlled air pressure to achieve gauge uniformity, and collapses the bubble for winding into rolls typically ranging from 0.5 to 3 meters in width. This equipment produces biaxially oriented film with tailored barrier properties for applications demanding moisture resistance and heat sealability. Multi-layer co-extrusion configurations command premium positioning because converters require discrete layer control for oxygen barrier and puncture resistance in food packaging. Single-layer systems retain volume dominance in agricultural film segments where cost-per-hectare metrics govern procurement decisions. Biodegradable-capable lines represent the fastest-growing installation category as brand owners mandate compostable packaging commitments.
China's SAMR enforces GB standards that restrict volatile organic compound emissions from extrusion heating zones, compelling equipment redesigns with closed-loop thermal management. The EU REACH framework and F-Gas Regulation constrain coolant selection for blown film cooling rings, favoring machinery suppliers with refrigerant-transition engineering capabilities. India's BIS certification requirements for electrical safety on imported industrial equipment create compliance friction for non-local manufacturers. Stakeholders must monitor how divergent energy-efficiency mandates across these jurisdictions reshape total cost-of-ownership calculations for fleet replacement decisions.
Market Dynamics
Multi-layer co-extrusion specifications from Southeast Asian flexible packaging converters are compressing order cycles for machinery builders while China's GB standards on melt-flow uniformity force design recalibration on imported equipment.
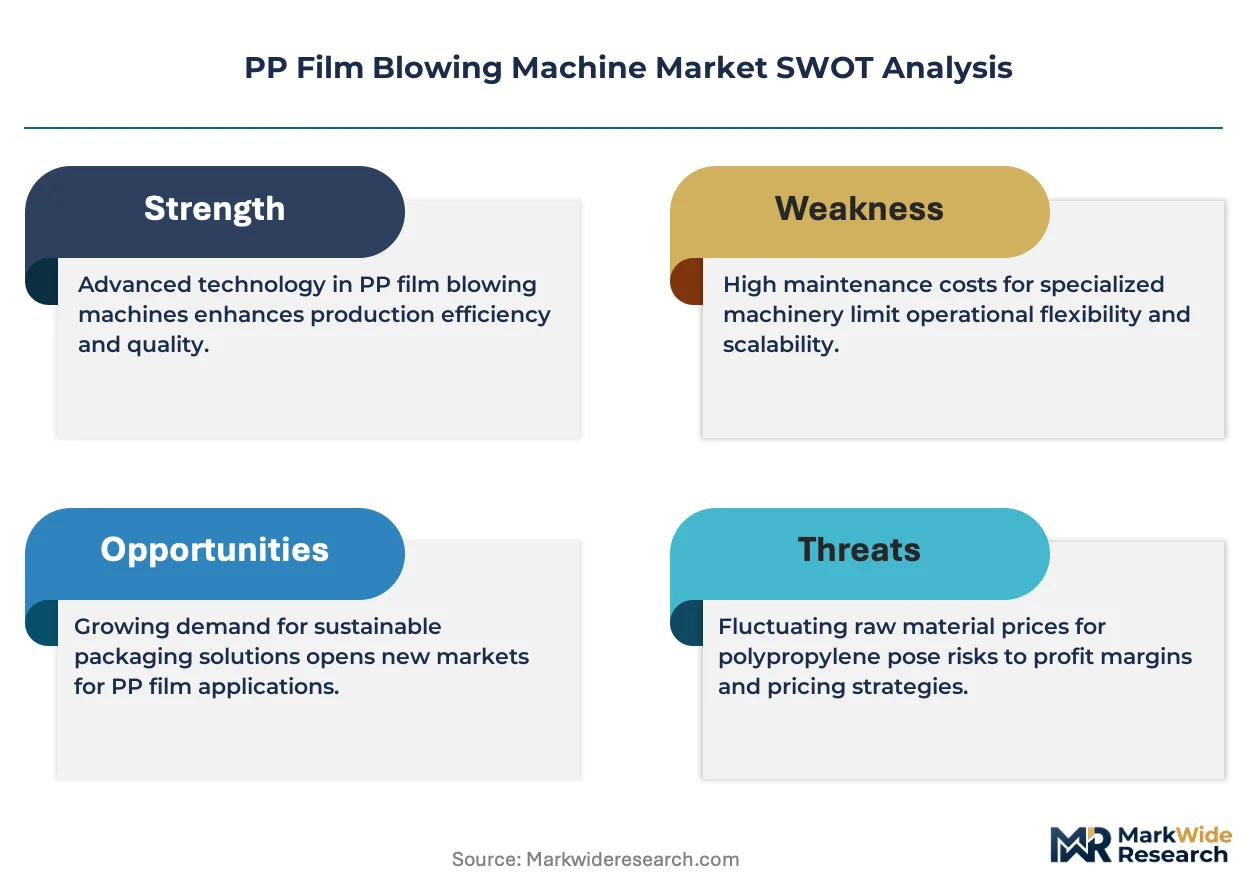
Growth Catalysts
- Food-grade barrier film specifications:Japanese packaging multinationals operating in Vietnam's northern industrial provinces are mandating discrete layer control for oxygen barrier properties, pulling co-extrusion line orders from equipment suppliers.
- Biodegradable-capable line mandates:Brand owner compostable packaging commitments are accelerating installation demand for PLA-compatible screw and die configurations.
- REACH F-Gas refrigerant transition:Machinery suppliers with refrigerant-transition engineering capabilities for blown film cooling rings are capturing replacement cycles as EU coolant constraints tighten.
Market Restraints
- Polypropylene resin price volatility:Feedstock cost swings compress converter margins and delay capital equipment procurement decisions in agricultural film segments.
- Component supply concentration:High-precision die and air ring manufacturing concentrates in German captive foundries, creating delivery bottlenecks for non-integrated Asian builders.
- Melt-flow uniformity technical ceiling:China's SAMR GB standards on recyclability enforce uniformity tolerances that legacy single-screw designs cannot meet without full mechanical redesign.
Strategic Opportunities
- India agricultural film aftermarket density:Localized service networks for screw refurbishment and die cleaning command premium positioning in South Asian markets where downtime costs govern supplier selection.
- Closed-loop thermal management convergence:Integration of heat recovery systems with VOC capture technology creates compliance bundling advantages under China's SAMR emissions enforcement.
- Mid-tier converter platform standardization:Compressible delivery cycles through modular extruder architectures address the 8-12 week tender windows common in Indonesian and Thai packaging cooperatives.
Industry Challenges
- Multi-layer process engineering skill scarcity:Co-extrusion die gap adjustment and layer ratio calibration require specialized technicians that vocational pipelines in Vietnam and Indonesia have not yet scaled.
- BIS electrical safety certification timelines:India's Bureau of Indian Standards testing protocols for imported industrial equipment add 14-18 week pre-shipment delays that disrupt converter project schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PP Film Blowing Machine Market |
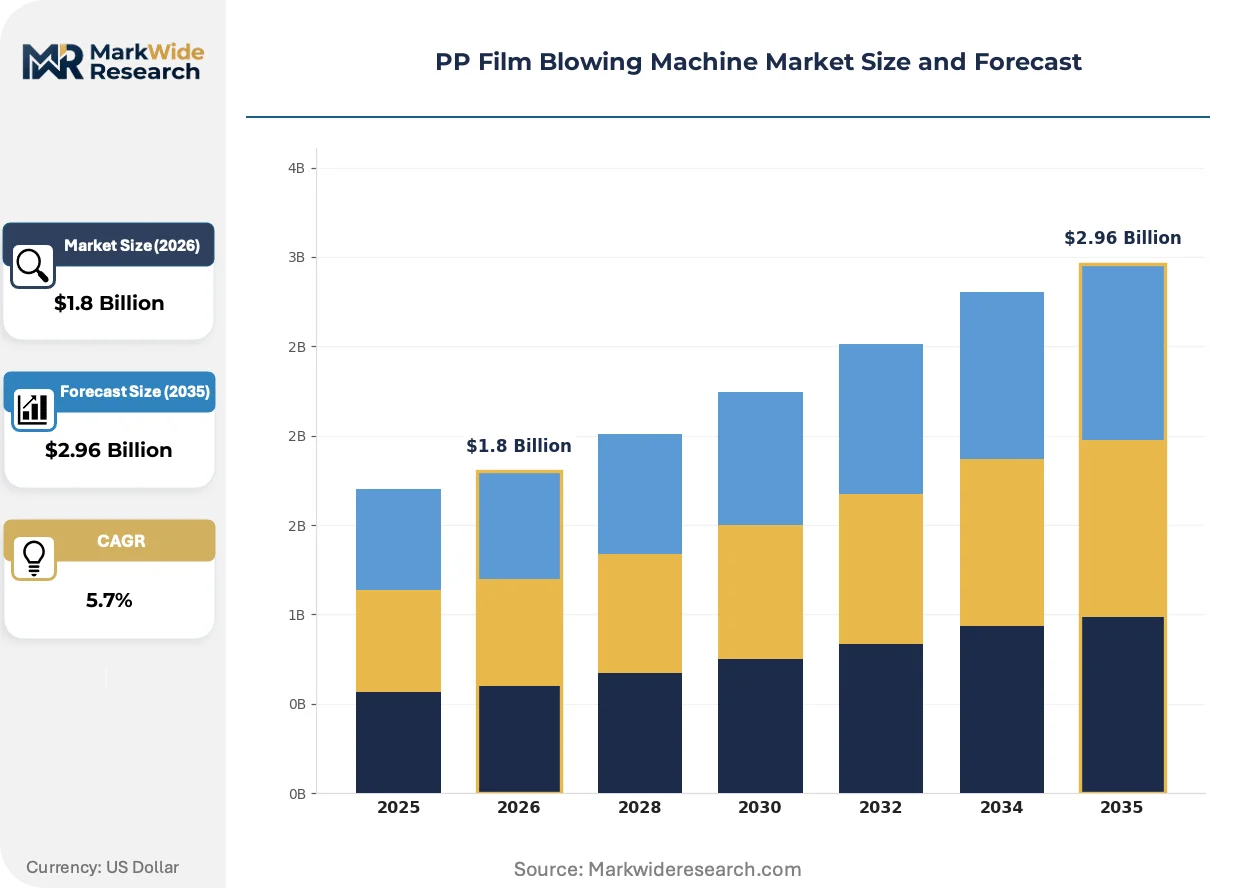
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Layer, Multi-Layer, Co-Extrusion, Biodegradable Technology: Blown Film Process, Extrusion, Cooling, Spooling End User: Packaging, Agriculture, Construction, Consumer Goods Application: Flexible Packaging, Agricultural Films, Protective Covers, Industrial Liners |
| Companies Covered | Polystar Machinery, Reifenhäuser Group, W&H Group, Davis-Standard, Macchi S.p.A., Hosokawa Alpine, JWELL Extrusion Machinery, Rajoo Engineers, Zhejiang Zhuxin Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PP Film Blowing Machine Market Evolving Landscape
Active recalibration of equipment specifications is compressing development cycles across three vectors: extrusion hardware architecture, thermal management compliance, and converter procurement behavior.
Multi-layer co-extrusion technology is bifurcating the installed base between food-grade barrier configurations and commodity agricultural systems. Premium converters in Vietnam and Thailand are specifying seven-layer dies with EVOH oxygen barrier cores for snack packaging contracts. Standardized three-layer platforms retain volume dominance in mulch and greenhouse film where cost-per-hectare metrics govern equipment selection.
China's SAMR GB standards on volatile organic compound emissions from extrusion heating zones are forcing closed-loop thermal management retrofits on existing installed capacity. Machinery suppliers must redesign barrel insulation and fume extraction architectures to maintain import eligibility. European and Japanese builders with pre-certified low-emission configurations are capturing replacement demand ahead of domestic Chinese compliance deadlines.
Converter procurement committees are unbundling after-sales service contracts from initial equipment purchases. Vietnamese and Indonesian mid-tier packaging cooperatives now negotiate screw refurbishment, die cleaning, and preventive maintenance as separate annual agreements rather than bundled warranties. This shift compresses upfront capital outlays while creating recurring revenue concentration for suppliers with localized technical teams.
PP Film Blowing Machine Market Segmentation
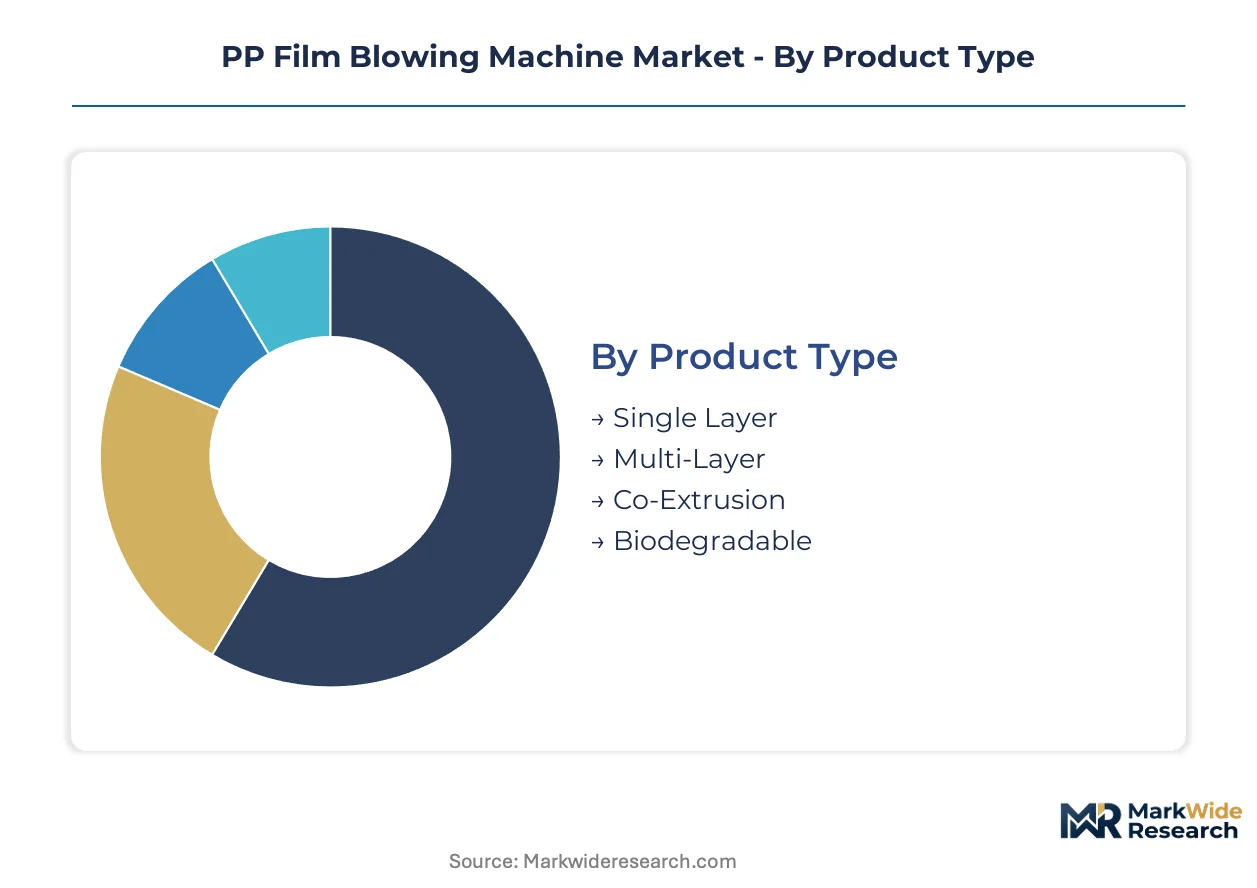
Equipment specification choices in the PP film blowing machine market determine compliance trajectories, aftermarket revenue potential, and vulnerability to substitute technologies. Converters segment procurement across layer complexity, thermal management architecture, and end-use performance requirements.
Product Type:
Substitution pressure from cast film lines and stretch-blow molding systems weighs most heavily on single-layer configurations, while multi-layer and biodegradable-capable equipment builds defensive moats through technical complexity.
- Single Layer:Basic mono-extrusion systems process homopolymer PP through a single die channel for commodity applications. Agricultural film converters in Vietnam's northern industrial provinces favor these units for mulch and greenhouse coverage where cost-per-hectare metrics dominate procurement decisions, though resin price volatility compresses replacement cycles.
- Multi-Layer:Three-to-seven layer architectures enable discrete barrier properties through co-extruded structures with EVOH or PA cores. Japanese packaging multinationals operating integrated film-to-bag facilities mandate these specifications for oxygen-sensitive snack packaging, pulling premium equipment orders despite longer delivery timelines from German captive foundries.
- Co-Extrusion:Specialized die designs synchronize multiple melt streams for functional layer distribution. China's SAMR GB standards on melt-flow uniformity force mechanical redesigns for import eligibility.
- Biodegradable:PLA-compatible screw geometries and modified die heads process compostable resins. Brand owner sustainability commitments are accelerating installation demand ahead of regulatory mandates in EU member states.
Single Layer retains volume leadership; Biodegradable holds the steepest expansion curve.
Technology:
Cost tier differentiation separates thermal management sophistication from basic mechanical functions, with cooling ring engineering commanding premium positioning.
- Blown Film Process:Circular die extrusion with controlled air inflation produces biaxially oriented film. The core process architecture governs gauge uniformity and optical clarity specifications for flexible packaging converters.
- Extrusion:Barrel, screw, and drive systems determine throughput capacity and melt homogeneity. European builders with captive component foundries sustain margin through precision machining capabilities that Asian volume suppliers cannot replicate.
- Cooling:Air ring and internal bubble cooling systems regulate frost line height and crystallization rates. EU F-Gas Regulation constraints on refrigerant selection favor machinery suppliers with refrigerant-transition engineering capabilities.
- Spooling:Winding and tension control mechanisms handle roll widths from 0.5 to 3 meters. Surface treatment integration for corona or plasma activation occurs at this stage for converters serving high-performance lamination contracts.
Extrusion captures the largest capital allocation; Cooling generates the highest margin premium.
End User:
Customer type segmentation reveals diverging procurement behaviors between specification-driven multinationals and price-sensitive domestic converters.
- Packaging:Flexible packaging converters mandate discrete layer control for oxygen barrier and puncture resistance. Southeast Asian operations of Japanese and Korean multinationals specify seven-layer dies with automated gauge control systems.
- Agriculture:Mulch film and greenhouse cover producers prioritize equipment uptime and localized aftermarket service. Rajoo Engineers and similar regional suppliers command premium positioning through screw refurbishment density across South Asian markets.
- Construction:Protective membrane and geomembrane applications require thicker gauge capabilities and reinforced edge winding. Project-based demand ties procurement to infrastructure investment cycles.
- Consumer Goods:Personal care and household product packaging converters balance printability with seal strength requirements. Mid-tier cooperatives in Indonesia and Thailand compress tender windows to 8-12 weeks.
Packaging absorbs the highest equipment value; Agriculture shows the most price elasticity.
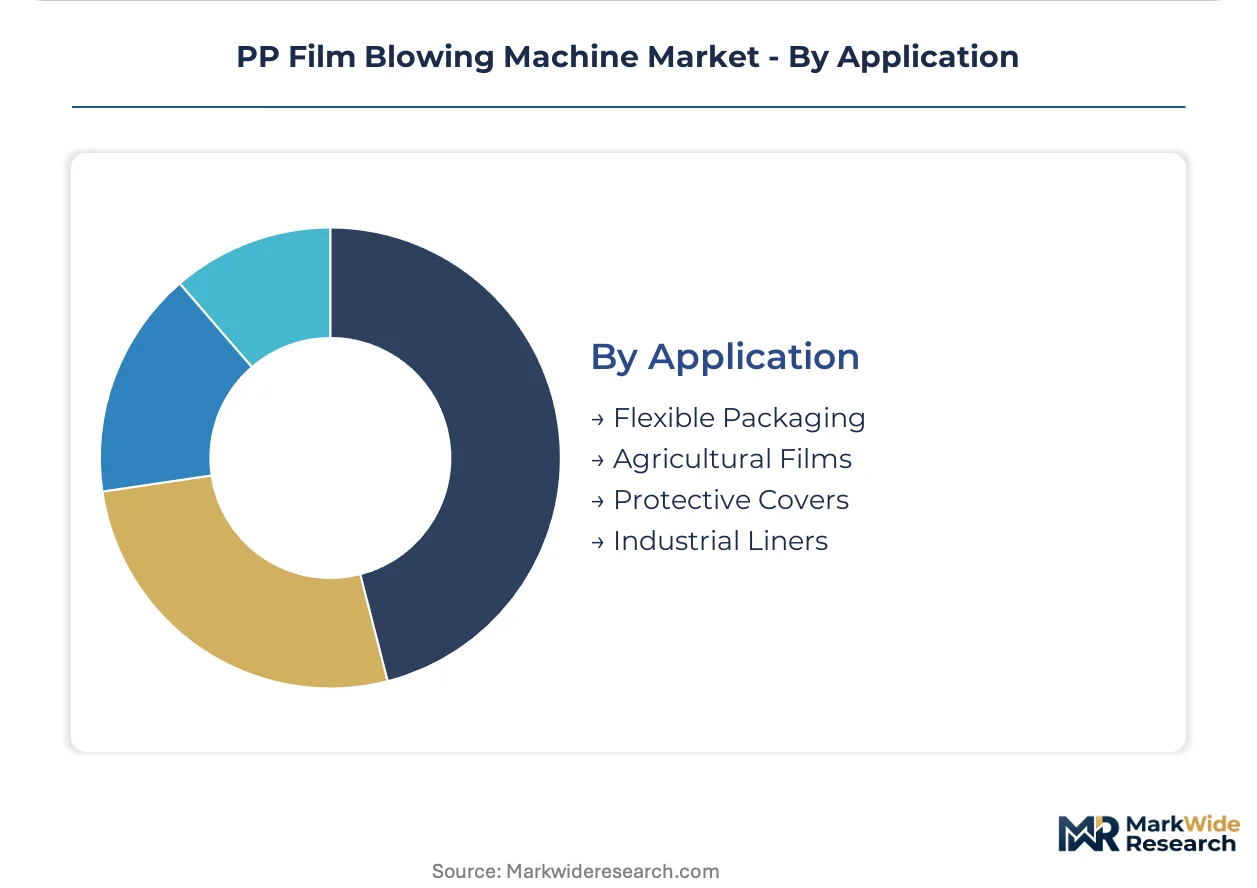
Application:
Volume concentration in agricultural films contrasts with margin capture in specialized barrier applications.
- Flexible Packaging:Food-grade barrier specifications from snack and ready-meal producers drive co-extrusion line orders. Oxygen transmission rate requirements below 5 cm³/m²/day necessitate EVOH core layers and precision die gap control.
- Agricultural Films:Mulch, greenhouse, and silage cover applications dominate unit installations. Cost-per-hectare metrics govern equipment selection, with standardized three-layer platforms retaining volume dominance.
- Protective Covers:Construction and industrial wrapping applications prioritize tear resistance and UV stabilization. Thicker gauge requirements favor high-output extrusion configurations.
- Industrial Liners:Chemical containment and bulk packaging applications demand puncture resistance and weld strength consistency. Specialized resin formulations require screw designs with enhanced mixing sections.
Agricultural Films retains volume leadership; Flexible Packaging commands the highest unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in PP film blowing equipment tilt toward net-importing industrial clusters where flexible packaging converters expand capacity faster than domestic machinery builders can supply. Export strength concentrates among German and Italian engineering groups serving premium co-extrusion specifications across Southeast Asian growth markets.
China
Domestic equipment demand softens as GB standards on melt-flow uniformity and VOC emissions force redesign cycles on imported machinery. SAMR enforcement of closed-loop thermal management requirements accelerates replacement of legacy single-screw installations. Yangtze River Delta converters in Jiangsu and Zhejiang provinces upgrade to seven-layer co-extrusion lines for export-oriented food packaging contracts.
Vietnam
Japanese packaging multinationals operating integrated film-to-bag facilities in Bac Ninh and Hai Duong provinces pull premium co-extrusion orders with discrete layer control specifications. The Ministry of Industry and Trade's circular economy roadmaps anticipate extended producer responsibility rules for plastic packaging by 2026. Northern industrial provinces concentrate capacity additions as European machinery suppliers establish technical service partnerships with local distributors.
Germany
Captive component foundries in Bavaria and Baden-Württemberg sustain margin on precision-machined dies and air rings for multi-layer systems. REACH F-Gas Regulation constraints on cooling ring refrigerants favor domestic builders with refrigerant-transition engineering capabilities. Engineering clusters around Munich and Stuttgart supply seven-layer configurations to Southeast Asian flexible packaging converters compressing tender windows.
India
Agricultural film demand in Maharashtra and Gujarat drives aftermarket service density for screw refurbishment and die cleaning. BIS certification timelines for electrical safety on imported industrial equipment add 14-18 week pre-shipment delays that disrupt converter project schedules. Rajoo Engineers anchors regional positioning through localized technical teams across South Asian mulch and greenhouse film markets.
Indonesia
Mid-tier packaging cooperatives in Java and Sumatra compress procurement cycles to 8-12 weeks for standardized three-layer platforms. The Ministry of Industry's domestic content incentives for capital goods procurement create compliance friction for non-local machinery suppliers. Surabaya and Jakarta industrial zones concentrate demand for biodegradable-capable line configurations ahead of anticipated regulatory mandates.
PP Film Blowing Machine Market Competitive Landscape
Concentration sits with integrated European engineering groups controlling precision component supply chains. The vendor base stratifies across three tiers: captive-foundry builders commanding premium positioning on multi-layer specifications, standardized-platform suppliers compressing delivery cycles for mid-tier converters, and regional aftermarket specialists dominating agricultural film service density. Competitive moves center on refrigerant-transition engineering capabilities for EU compliance and localized technical team deployment for Southeast Asian maintenance contracts.
Within the integrated European tier, Reifenhäuser Group and W&H Group exemplify engineering-intensive positioning through precision die manufacturing. JWELL Extrusion Machinery occupies a position among standardized-platform suppliers addressing compressed tender windows in Indonesian and Thai markets. Rajoo Engineers anchors the regional aftermarket specialist archetype through service network density across South Asian agricultural film segments.
| Leading Market Players |
|---|
| Polystar Machinery |
| Reifenhäuser Group |
| W&H Group |
| Davis-Standard |
| Macchi S.p.A. |
| Hosokawa Alpine |
| JWELL Extrusion Machinery |
| Rajoo Engineers |
| Zhejiang Zhuxin Machinery |
| Others |
Value Network & Pricing Analysis
EU REACH F-Gas Regulation constraints on cooling ring refrigerants gate both import eligibility for machinery suppliers and tiered price positioning across the European and Southeast Asian installed base. Equipment configurations with pre-certified low-emission thermal management architectures command configured-to-order premiums, while standard platforms without refrigerant-transition engineering face cost compression.
Pricing Analysis
Configured-to-order pricing for seven-layer co-extrusion lines with EVOH barrier cores spreads 40-60% above standardized three-layer agricultural platforms. Pricing stratifies across premium, standard, and economy tiers based on layer complexity and certification grade under China's SAMR GB standards. Cost compression in mid-tier segments is intensifying because Indonesian and Thai packaging cooperatives unbundle after-sales service contracts from initial equipment purchases. Agricultural film converters in Vietnam's northern provinces exhibit the highest price sensitivity, while Japanese packaging multinationals operating integrated film-to-bag facilities demonstrate the lowest.
Supply Chain Analysis
Germany and Italy anchor precision die and air ring manufacturing through captive component foundries in Bavaria and Baden-Württemberg. Chinese and Taiwanese volume suppliers feed standardized extruder platforms and drive systems. The supply chain rests on high-precision machining capabilities for multi-layer die gaps, specialized screw geometries for PLA-compatible configurations, and refrigerant-transition engineering for EU compliance. Single-source vulnerability concentrates in German captive foundries for seven-layer die assemblies. Distribution runs through technical service partnerships with local distributors in Vietnam and Indonesia, direct sales to Japanese multinationals, and aftermarket service networks for screw refurbishment across South Asian agricultural markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward mid-tier packaging cooperatives in Southeast Asia as procurement committees unbundle service contracts and compress tender windows to 8-12 weeks. This fragmentation among domestic converters contrasts with consolidation among Japanese and Korean multinational film-to-bag operators.
For Market Incumbents: Shield installed base margins by deepening refrigerant-transition engineering capabilities ahead of EU F-Gas Regulation enforcement deadlines. Prioritize backward integration into precision die manufacturing or exclusive partnerships with German captive foundries to defend against Asian volume suppliers compressing delivery cycles on standardized platforms. The priority lever sits with localized technical team deployment for aftermarket service density in Vietnam and Indonesia. For New Entrants and Emerging Players: Differentiate on biodegradable-capable line configurations with PLA-compatible screw geometries, targeting Indonesian packaging cooperatives ahead of anticipated Ministry of Industry regulatory mandates. The most penetrable segment lies in mid-tier agricultural film converters in India's Maharashtra and Gujarat seeking localized screw refurbishment and die cleaning services. A direct go-to-market angle through technical service partnerships with established local distributors bypasses BIS certification timeline disadvantages. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-layer co-extrusion configurations as seven-layer die complexity and closed-loop thermal management requirements raise mechanical engineering thresholds. Long-term viability favors integrated builders with captive component supply chains or standardized-platform suppliers with compressible delivery cycles for Southeast Asian mid-tier converters. The acquisition target archetype encompasses regional aftermarket specialists with dense service networks in agricultural film segments. The signal to watch is converter procurement committee unbundling of after-sales contracts from initial equipment purchases.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant-Transition Engineering Investment | EU F-Gas Regulation compliance secures replacement demand cycles ahead of domestic Chinese deadlines. |
| Localized Technical Service Partnership | Vietnamese distributor alliances capture unbundled aftermarket contracts from Japanese multinational operators. |
| Biodegradable-Capable Line Configuration | PLA-compatible screw geometries address brand owner compostable packaging commitments in Indonesia. |
| Backward Integration into Die Manufacturing | Captive precision machining capabilities defend margin against Asian volume supplier compression. |
| Platform Standardization for Compressed Delivery | Modular extruder architectures serve 8-12 week tender windows in Thai and Indonesian cooperatives. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with flexible packaging procurement directors, agricultural film plant managers, aftermarket service heads, and extrusion machinery OEM technical directors. Secondary validation drew from customs and trade data on equipment imports, SEC filings of listed machinery builders, BIS certification records for electrical safety compliance, and EU REACH regulatory submissions. Bottom-up and top-down triangulation cross-checked regional installation estimates against converter capacity expansion announcements.
Across the analysis window, volume and value outputs reflect segmentation modeling by layer complexity, thermal management architecture, end-use performance requirements, and geographic regulatory cluster. CAGRs were derived from equipment order pipeline analysis and replacement cycle timing under emissions enforcement deadlines. Forecast inputs incorporated resin price volatility impacts on agricultural segment procurement delays and biodegradable-capable line installation acceleration from brand owner sustainability mandates.
The analysis sits within stated boundaries; outcomes outside sustained GB standard enforcement in China, EU F-Gas Regulation implementation timelines, or Southeast Asian flexible packaging capacity expansion would require recalibration. Forecasts reflect documented assumptions on melt-flow uniformity technical ceilings and component supply concentration risks. Recalibration cycles align with material shifts in regulatory enforcement intensity, resin price volatility regimes, and converter procurement committee unbundling behavior.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
North America Plastic Film Packaging Market
Poly film
Polyolefin Battery Separator Films Market
Poly film
Biaxially Oriented Polyethylene Terephthalate (BOPET) Films Market
Poly film
PP Laminating Films Market
Poly film
India Plastic Packaging Film Market
Poly film
Timber Wrap Films Market
Poly film
Co Extruded Films Market
Poly film
Embossed Film Market
Poly film
Global EVOH Films for Packaging Market
Poly film
Bio-PET Film Market
Poly film
Polyolefin (POF) Shrink Film Market
Poly film
PET Lidding Films Market
Poly film
UAE Plastic Packaging Films Market
Poly film
Thermoforming Films Market
Poly film
US Cleanroom Film and Bags Market
Poly film
Nylon Films Market