
 Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market | 2026-2036
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market Outlook
Buyer concentration among Japanese and South Korean food processors is restructuring procurement dynamics across the Asia-Pacific EVOH films supply base. Kuraray Co., Ltd. leverages its proprietary resin-to-film vertical chain to secure long-term supply agreements with major chilled-food distributors. Mitsubishi Chemical Corporation anchors high-barrier coextrusion capacity serving pharmaceutical blister packs throughout East Asia. SK Geo Centric differentiates through ethylene feedstock integration at its Daesan petrochemical complex.
Ethylene-vinyl alcohol copolymer packaging films constitute multilayer structures incorporating mol% ethylene ratios between 32% and 44%, manufactured via cast coextrusion or blown film processes to achieve oxygen transmission rates below 1 cc/m²/day at 20°C and 65% relative humidity. These films function primarily as oxygen barrier layers within laminated or coextruded packaging architectures for oxygen-sensitive goods. Coextruded films dominate volume throughput due to processing efficiency in high-speed form-fill-seal lines, while laminated films command premium positioning in retort and modified-atmosphere pharmaceutical applications. Flexible films sustain faster expansion than rigid formats as pouch formats displace trays in single-serve food segments across Southeast Asian retail channels.
Japan's Ministry of Health, Labour and Welfare enforces food-contact positive list requirements that restrict unapproved substances in multilayer barrier films, while China's SAMR administers GB 4806 series standards governing overall migration limits for plastic food-contact materials. South Korea's MFDS mandates oxygen barrier performance disclosures for extended-shelf-life meat packaging, directly shaping film thickness specifications and ethylene-content formulations. Stakeholders must monitor evolving recyclability mandates under Japan's Plastic Resource Circulation Act and China's dual carbon policy framework, as these will determine whether mechanical recycling-compatible EVOH grades or chemical recycling pathways become the compliance default for post-consumer multilayer packaging streams.
Market Dynamics
Buyer consolidation among Japanese and South Korean chilled-food processors is compressing supplier margins while favoring resin-to-film integrated producers capable of locking in multi-year oxygen barrier specifications.
Growth Catalysts
- GB 4806 compliance mandates:China's SAMR enforcement of overall migration limits for multilayer food-contact materials is forcing domestic converters toward certified EVOH barrier grades.
- Modified-atmosphere meat packaging:South Korea's MFDS oxygen barrier disclosure rules are extending shelf-life requirements for retail protein segments.
- Yangtze River Delta concentration:China's packaging manufacturing cluster generates density economies for cast coextrusion lines serving regional form-fill-seal operations.
Market Restraints
- Ethylene feedstock volatility:Naphtha-derived ethylene cost swings at Daesan and Ulsan petrochemical complexes compress film margin stability.
- Resin supply concentration:Kuraray's captive EVOH resin production creates dependency risk for non-integrated film converters across East Asia.
- Mechanical recycling incompatibility:EVOH's thermoplastic incompatibility with standard polyolefin recycling streams blocks circular packaging claims under Japan's Plastic Resource Circulation Act.
Strategic Opportunities
- Southeast Asian pouch conversion:Vietnam and Thailand's nascent high-barrier flexible packaging sectors remain underpenetrated by oxygen-scavenging film technologies.
- Dual carbon policy alignment:China's chemical recycling infrastructure investments may unlock EVOH recovery pathways for post-consumer multilayer streams.
- Pharmaceutical blister expansion:Mitsubishi Chemical's East Asian coextrusion capacity positions for oxygen-sensitive generic drug packaging growth.
Industry Challenges
- Coextrusion die engineering scarcity:Thin-layer distribution expertise for sub-micron EVOH barriers remains concentrated among Japanese equipment specialists.
- JIS certification timelines:Japan's Ministry of Health, Labour and Welfare positive list approvals for new barrier additives extend product development cycles by 18-24 months.
- Legacy line retrofit costs:Southeast Asian converters face capital intensity upgrading blown film assets to seven-layer coextrusion configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market |
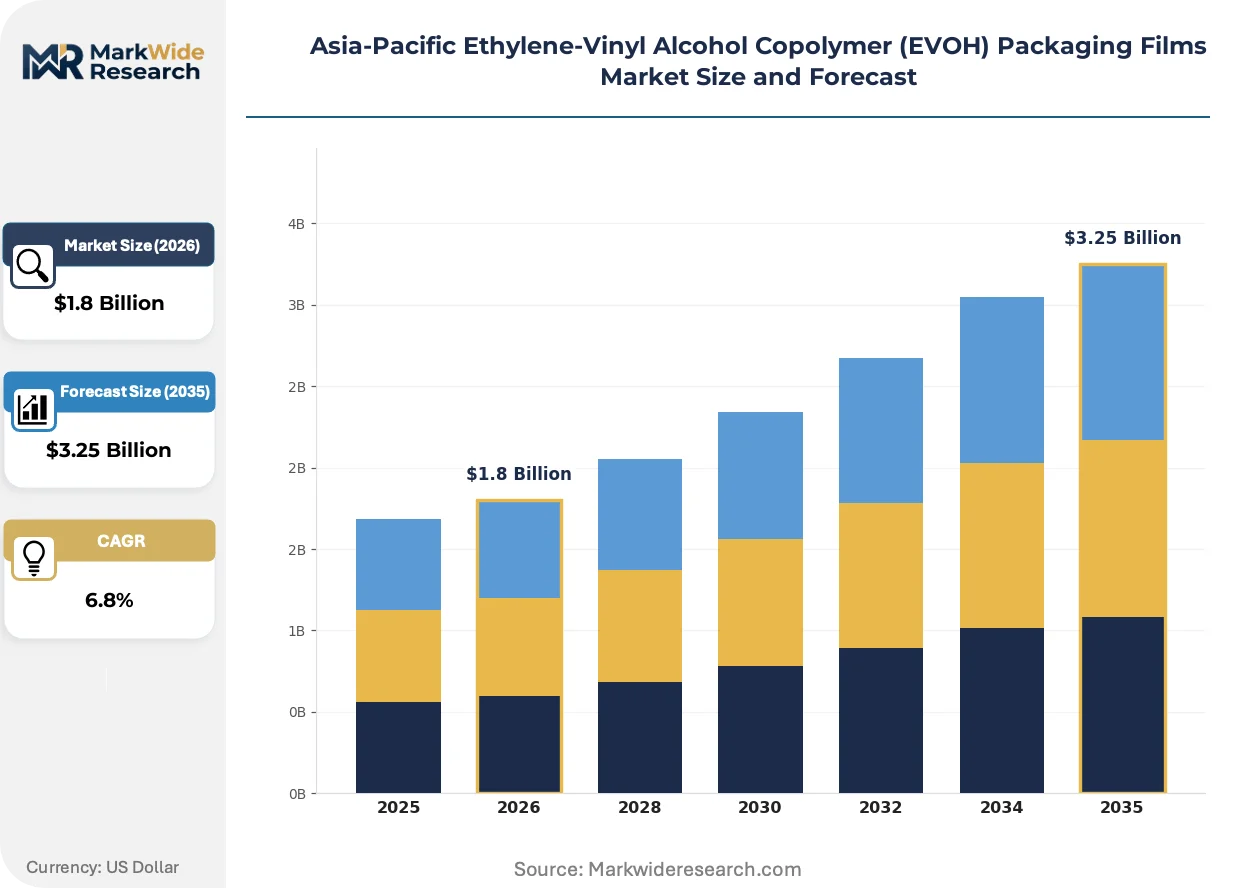
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Films, Flexible Films, Laminated Films, Coextruded Films End User: Food Packaging, Pharmaceutical Packaging, Industrial Packaging, Cosmetic Packaging Packaging Type: Rolls, Pouches, Bags, Sheets Thickness: Below 30 Microns, 30-50 Microns, Above 50 Microns, Others |
| Companies Covered | Shanghai Chuangfa Packaging Materials Co., Ltd., Chang Chun Group, Kuraray Co., Ltd., SK Geo Centric, China Petrochemical Corporation, Nippon Gohsei, Luoyang Jinyu New Material Technology Co., Ltd., Formosa Plastics Corporation, Mitsubishi Chemical Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market Strategic Shifts
Active developments across materials science, regulatory compliance architecture, and procurement models are restructuring how oxygen barrier films are specified, validated, and sourced across Asia-Pacific packaging value chains.
High-vinyl alcohol EVOH grades with 44 mol% ethylene content are expanding into pharmaceutical blister pack applications requiring sub-0.5 cc/m²/day oxygen transmission rates. Japanese generic drug manufacturers are accelerating qualification timelines for these ultra-high-barrier specifications. The technology is expanding into retort pouch segments previously dominated by aluminum foil laminates.
Japan's Plastic Resource Circulation Act enforcement is mandating design-for-recycling disclosures across multilayer packaging submissions. Film converters must now document EVOH layer thickness and position within substrate stacks to qualify for extended producer responsibility credits. Pharmaceutical and chilled-food segments are responding by specifying mechanically separable barrier architectures.
Japanese food processors are consolidating annual EVOH film volumes into single-source procurement frameworks with resin-integrated suppliers. Regional trading houses and independent distributors are losing share to direct mill relationships. South Korea's major retail meat packers are most advanced in this shift, having completed supplier base rationalization during 2023-2024 contract cycles.
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market Segmentation
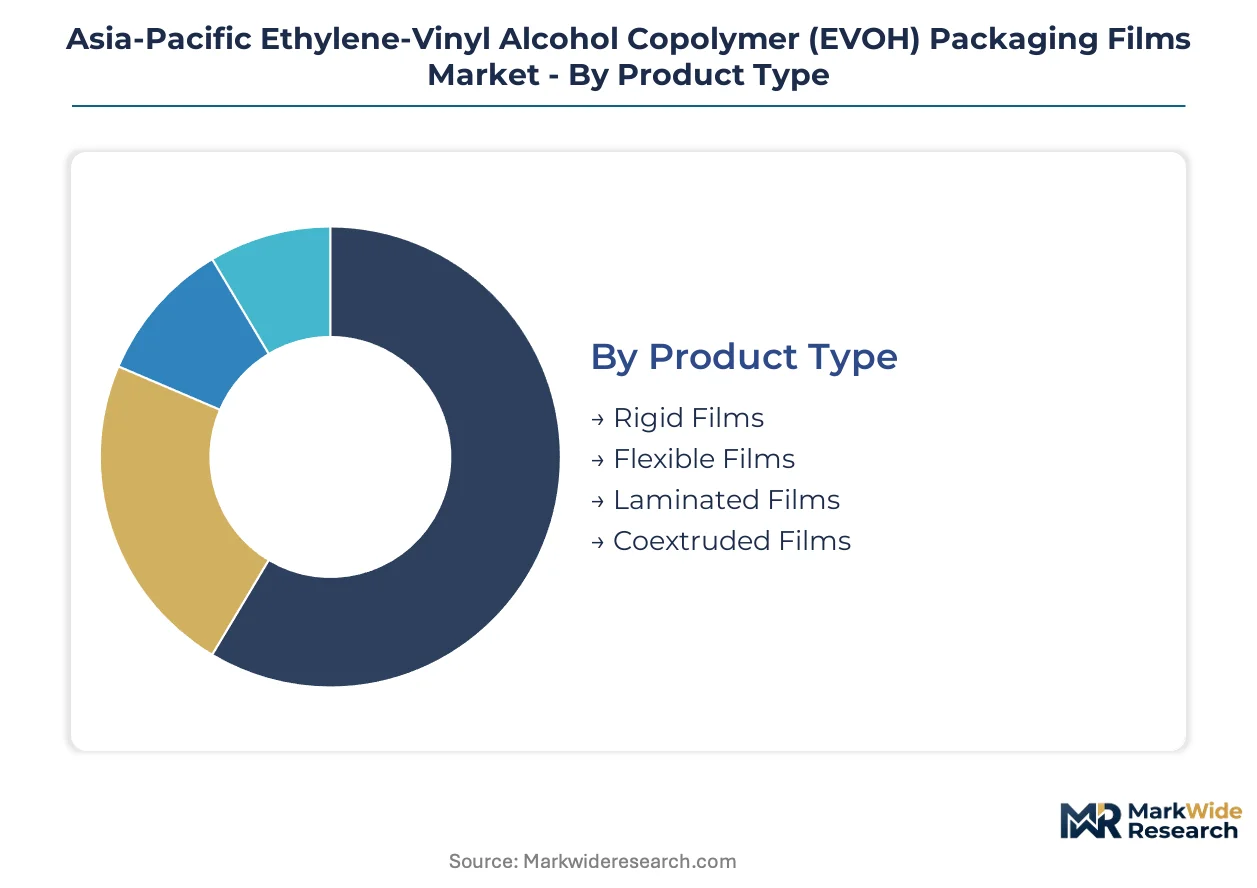
Segmentation in the Asia-Pacific EVOH packaging films market reveals how oxygen barrier specifications vary dramatically by integration depth. Films embedded within multilayer coextrusions face fundamentally different qualification protocols than standalone laminated formats.
Product Type:
Integration depth separates standalone barrier films from those permanently bonded within substrate architectures, with profound implications for recyclability mandates and equipment compatibility.
- Coextruded Films:Manufactured via simultaneous extrusion of EVOH core layers between polyolefin skins, these structures achieve sub-1 cc/m²/day oxygen transmission rates through precise mol% ethylene control. Demand concentrates in China's Yangtze River Delta manufacturing cluster, where high-speed form-fill-seal lines at chilled-food processors favor the processing efficiency of five- to seven-layer coextruded formats. Japan's Plastic Resource Circulation Act is forcing converters to document layer thickness and position for extended producer responsibility credits.
- Laminated Films:EVOH barrier layers adhesively bonded to PET, PA, or PP substrates through solvent-based or solventless lamination, enabling precise thickness control for pharmaceutical blister packs requiring sub-0.5 cc/m²/day performance. South Korea's MFDS oxygen barrier disclosure rules for extended-shelf-life meat packaging are extending qualification timelines for these premium specifications.
- Flexible Films:Thin-gauge formats under 100 microns dominating pouch applications across Southeast Asian retail channels, where single-serve food segments are displacing rigid trays.
- Rigid Films:Thermoformed sheets and semi-rigid structures serving tray-based modified-atmosphere packaging for premium protein segments in Japanese and South Korean supermarkets.
Volume placements concentrate in coextruded formats; the faster expansion belongs to laminated films in pharmaceutical applications.
End User:
Cost tier stratification separates commodity food applications from premium pharmaceutical specifications, with regulatory burden intensity rising steeply across the value ladder.
- Food Packaging:Modified-atmosphere and vacuum-packaged proteins, ready meals, and dairy applications requiring 7-21 day shelf-life extension through oxygen barrier performance. China's SAMR enforcement of GB 4806 overall migration limits is forcing domestic converters toward certified EVOH grades. Buyer consolidation among Japanese and South Korean chilled-food processors is compressing supplier margins while favoring resin-to-film integrated producers.
- Pharmaceutical Packaging:Blister packs, sachets, and cold-form foil replacements for oxygen-sensitive generic drugs demanding sub-0.5 cc/m²/day transmission rates and JIS-compliant additive positive lists. Mitsubishi Chemical's East Asian coextrusion capacity anchors supply for this specification-intensive segment.
- Industrial Packaging:Barrier films for agrochemical concentrates, automotive fluids, and electronics moisture protection, where cost sensitivity limits EVOH penetration to high-value formulations.
- Cosmetic Packaging:Premium personal care sachets and sample packs requiring fragrance retention and oxidation stability, representing a niche but margin-rich application in South Korean and Japanese markets.
Revenue concentration sits with food packaging; the steepest expansion trajectory belongs to pharmaceutical specifications.
Packaging Type:
Supply chain configuration directly determines format prevalence, with roll-fed operations dominating converter economics and finished pouch demand rising fastest in emerging channels.
- Rolls:Master rolls and slit rolls supplying downstream converters with unprinted EVOH barrier substrates, dominating volume throughput through economies of scale in cast coextrusion operations.
- Pouches:Pre-formed or form-fill-seal compatible pouch structures gaining share in Vietnam and Thailand's nascent high-barrier flexible packaging sectors as retail modernization accelerates.
- Bags:Side-seal and bottom-gusset configurations for bulk industrial and agricultural applications, where EVOH barriers command premium positioning against metallized alternatives.
- Sheets:Cut-sheet formats for manual packaging operations and small-batch pharmaceutical runs, serving specialty compounders and regional drug manufacturers.
Roll formats anchor current volume; pouches are gaining share fastest across Southeast Asian retail modernization.
Thickness:
Performance tier stratification separates economy specifications from premium barrier grades, with regulatory disclosure requirements tightening most aggressively at thickness extremes.
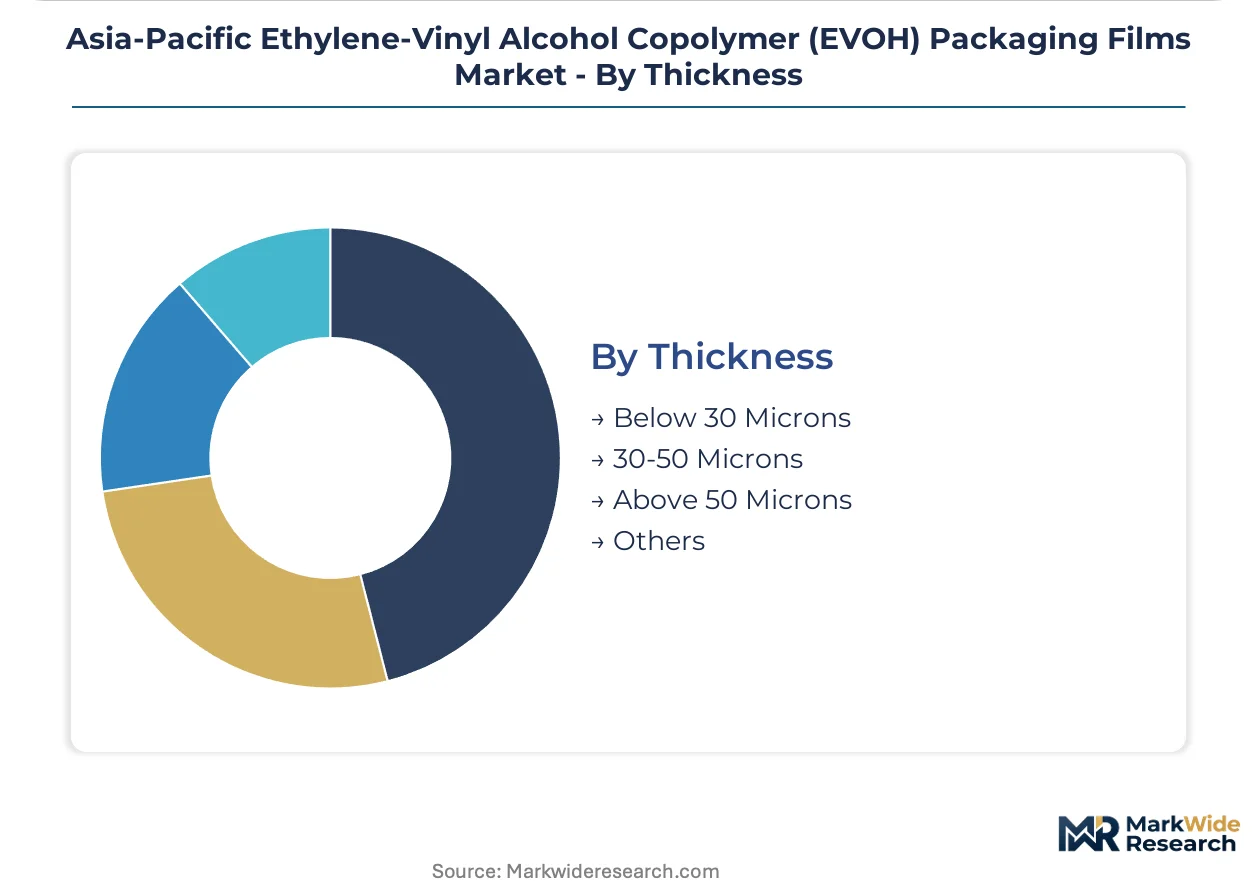
- 30-50 Microns:The workhorse specification balancing oxygen barrier performance with material efficiency, dominating coextruded food packaging applications across East Asian manufacturing clusters. South Korea's MFDS mandates oxygen barrier performance disclosures for extended-shelf-life meat packaging, directly shaping specifications in this thickness band.
- Below 30 Microns:Ultra-thin barrier layers for cost-optimized pouch applications and downgauging initiatives, where sub-micron EVOH distribution expertise remains concentrated among Japanese equipment specialists.
- Above 50 Microns:Heavy-gauge specifications for pharmaceutical blister packs and industrial chemical containment, where JIS certification timelines for new barrier additives extend product development cycles.
- Others:Custom thickness profiles for specialty applications including retort pouches and aseptic packaging, requiring tailored coextrusion die engineering.
Volume concentrates in the 30-50 micron band; below-30-micron formats are expanding most quickly through downgauging initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilled-food processors in Japan and South Korea are consolidating procurement volumes, while China's Yangtze River Delta manufacturing cluster generates density economies for high-speed coextrusion lines serving regional form-fill-seal operations.
China
Domestic converters face SAMR enforcement of GB 4806 overall migration limits, forcing adoption of certified EVOH barrier grades. The dual carbon policy framework shapes chemical recycling infrastructure investments that may unlock EVOH recovery pathways. Yangtze River Delta packaging manufacturers anchor cast coextrusion capacity for regional food processors.
Japan
Generic drug manufacturers accelerate qualification timelines for ultra-high-barrier pharmaceutical specifications. METI's Plastic Resource Circulation Act mandates design-for-recycling disclosures across multilayer packaging submissions. Kanto-based chilled-food distributors consolidate annual volumes into direct mill relationships with resin-integrated suppliers.
South Korea
Retail meat packers completed supplier base rationalization during 2023-2024 contract cycles. MFDS oxygen barrier disclosure rules extend shelf-life requirements for extended-shelf-life protein packaging. Busan-Ulsan petrochemical complexes anchor ethylene feedstock integration for film producers.
Vietnam
Nascent high-barrier flexible packaging sectors remain underpenetrated by oxygen-scavenging film technologies. Import-dependent converters face capital intensity upgrading blown film assets to seven-layer coextrusion configurations. Ho Chi Minh City packaging distributors serve regional retail modernization in single-serve food segments.
Thailand
Pouch formats displace rigid trays across Southeast Asian retail channels, driving demand for thin-gauge flexible films. Bangkok-based converters source master rolls from East Asian suppliers for downstream form-fill-seal operations. Local processors navigate JIS certification timelines for barrier additive approvals in pharmaceutical applications.
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market Competitive Environment
Japanese producers anchor the premium-tier specification market; South Korean and Chinese fabricators hold volume-driven positions in standard-grade supply. The vendor base stratifies across resin-integrated multinationals, regional petrochemical conglomerates, and specialized film converters. Three archetypes dominate: captive resin-to-film vertical chains, ethylene feedstock-integrated petrochemical players, and independent converters dependent on merchant resin supply. Capacity expansion and strategic partnerships constitute the dominant competitive vectors as buyers consolidate procurement volumes.
Within the resin-integrated tier, Kuraray Co., Ltd. and Mitsubishi Chemical Corporation exemplify Japanese specialists with captive EVOH production. SK Geo Centric occupies a position among South Korean petrochemical players with upstream ethylene control. These three anchors illustrate how backward integration into resin production separates premium-tier suppliers from merchant-resin-dependent converters across East Asian supply chains.
| Leading Market Players |
|---|
| Shanghai Chuangfa Packaging Materials Co., Ltd. |
| Chang Chun Group |
| Kuraray Co., Ltd. |
| SK Geo Centric |
| China Petrochemical Corporation |
| Nippon Gohsei |
| Luoyang Jinyu New Material Technology Co., Ltd. |
| Formosa Plastics Corporation |
| Mitsubishi Chemical Corporation |
| Others |
Value Chain & Pricing Dynamics
Japan's Plastic Resource Circulation Act enforcement gates both qualified supply and premium-tier pricing access, as film converters must document EVOH layer thickness and position to qualify for extended producer responsibility credits. Buyers lacking certified barrier architectures face exclusion from chilled-food and pharmaceutical procurement frameworks, concentrating pricing power among resin-integrated suppliers with compliant product lines.
Pricing Analysis
Volume throughput concentrates in standard-grade coextruded films while margin capture belongs to laminated pharmaceutical specifications. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified blister-pack grades from GB 4806-compliant food-contact films and uncertified industrial barrier applications. Cost compression in standard-grade supply is intensifying because buyer consolidation among Japanese and South Korean chilled-food processors compresses supplier margins. Industrial packaging buyers exhibit highest price sensitivity; pharmaceutical generic drug manufacturers show lowest sensitivity due to oxygen barrier performance requirements.
Supply Chain Analysis
Workforce availability for thin-layer coextrusion die engineering concentrates in Japan's equipment specialist clusters, constraining capacity expansion in Vietnam and Thailand. Manufacturing gravity centers on China's Yangtze River Delta, Japan's Kanto region, and South Korea's Busan-Ulsan corridor. Resin supply draws from naphtha-derived ethylene at Daesan and Ulsan petrochemical complexes alongside Kuraray's captive EVOH production. Single-source vulnerability from Kuraray's resin concentration creates dependency risk for non-integrated converters. Distribution runs through master roll supply to downstream converters for form-fill-seal and pouch fabrication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story: China's SAMR enforcement of GB 4806 overall migration limits creates a barrier-to-entry moat for certified EVOH barrier grade suppliers, excluding merchant-resin-dependent converters from premium procurement frameworks.
For Market Incumbents: Deploy backward integration into captive EVOH resin production to lock in multi-year oxygen barrier specifications with consolidating Japanese and South Korean chilled-food processors. Add coextrusion capacity in the Yangtze River Delta to capture density economies from regional form-fill-seal operations. Resin supply concentration among non-integrated competitors presents acquisition opportunity to deepen specification control. For New Entrants and Emerging Players: The 40-60% price-point gap between premium pharmaceutical laminates and economy industrial films opens white-space targeting in Vietnam and Thailand's nascent high-barrier flexible packaging sectors. Southeast Asian pouch conversion for single-serve food segments offers most penetrable entry point. Partner with Japanese equipment specialists for seven-layer coextrusion line commissioning to bypass die engineering scarcity. For Investors and Strategic Acquirers: Completion of South Korean retail meat packer supplier base rationalization during 2023-2024 contract cycles is the leading indicator that resin-integrated film converters have secured durable pricing power. Long-term viability over 5-10 year windows favors backward-integrated specialists with pharmaceutical certification pipelines. Monitor China's dual carbon policy chemical recycling infrastructure investments as signal for EVOH recovery pathway economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Resin Production | Kuraray's proprietary resin-to-film chain secures long-term supply agreements with major chilled-food distributors. |
| Seven-Layer Coextrusion Capacity Expansion | Yangtze River Delta manufacturing clusters achieve density economies for high-speed form-fill-seal line supply. |
| JIS Pharmaceutical Certification Investment | Mitsubishi Chemical anchors high-barrier coextrusion capacity serving oxygen-sensitive generic drug packaging. |
| Chemical Recycling Infrastructure Partnership | China's dual carbon policy investments may unlock EVOH recovery pathways for post-consumer multilayer streams. |
| Southeast Asian Converter Joint Venture | Vietnam and Thailand's underpenetrated high-barrier sectors offer first-mover positioning in pouch conversion growth. |
Study Parameters
Document review covered customs and trade flow databases, GB 4806 and JIS regulatory filings, SEC 10-K disclosures from petrochemical conglomerates, and MFDS oxygen barrier performance guidelines, complemented by interviews with plant managers at East Asian coextrusion facilities, procurement leads at Japanese chilled-food distributors, technical R&D directors at barrier film converters, and channel partners in Southeast Asian packaging distribution. Bottom-up demand modeling from end-use application volumes and top-down supply validation from resin production capacities were triangulated to cross-verify market sizing.
Output modeling generated segment-level value and volume trajectories across the projection horizon through integrated price-volume elasticity functions and capacity utilization assumptions. Segmentation dimensions included product integration depth, end-use cost tier, packaging format, thickness performance band, and regional manufacturing cluster. CAGRs were derived from regression analysis against macroeconomic indicators and industry-specific demand drivers including SAMR enforcement intensity, retail meat packer procurement consolidation, and pharmaceutical generic drug packaging expansion.
Underlying measurement precision varies by segment; coextruded food packaging films with established Yangtze River Delta production bases carry tighter precision than emerging Southeast Asian pouch conversion applications. Forecasts reflect documented assumptions regarding regulatory enforcement timelines, ethylene feedstock cost stability, and chemical recycling infrastructure development. Material deviation in SAMR GB 4806 audit intensity, Kuraray resin supply allocation, or Japan's Plastic Resource Circulation Act disclosure requirements warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Stretch Films Packs Market
Poly film
Japan Plastic Packaging Film Market
Poly film
Global PVDC Coated Films Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
Tube Laminating Films Market
Poly film
Isotropic Film Market
Poly film
MDO-PE Films Market
Poly film
EVOH Encapsulation Film Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
Craft Plastic Films Market
Poly film
Polystyrene Films Market
Poly film
APET Film Market
Poly film
Soft Touch Film Market
Poly film
MOPP Packaging Films Market
Poly film
Latin America Plastic Packaging Films Market
Poly film
Polyethylene Film Market