
 Spain Plastic Packaging Films Market | 2026-2036
Spain Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Plastic Packaging Films Market Insights
Food packaging buyers are bifurcating from industrial users as the dominant demand archetype in Spain's plastic packaging films landscape. Amcor Plc anchors its position through vertical integration across extrusion and conversion stages. Berry Global Inc. competes via R&D intensity in sustainable film formulations. Mondi PLC differentiates through geographic dominance in Iberian barrier film supply.
Spain plastic packaging films comprise polymeric sheet structures typically ranging from 12 to 150 micrometers in thickness, manufactured through cast or blown extrusion processes and engineered for containment, preservation, and unitization of goods. Barrier films command premium positioning due to oxygen and moisture transmission rate specifications demanded by protein and dairy processors. Stretch films sustain volume leadership in industrial palletization, while shrink films capture share in retail-ready multi-pack configurations. Polyethylene occupies the broadest material footprint, though polypropylene gains in microwaveable and retort applications where thermal resistance thresholds exceed 120 degrees Celsius.
Spain's national packaging regulator enforces EU Packaging and Packaging Waste Directive transpositions that mandate recyclability targets and minimum recycled content thresholds for plastic films placed on the market. The Spanish Ministry for Ecological Transition coordinates with ECHA REACH compliance obligations to restrict substances of very high concern in food-contact film layers. Stakeholders must monitor how forthcoming Spanish royal decrees on extended producer responsibility will alter cost structures for imported versus domestically converted film substrates.
Market Dynamics
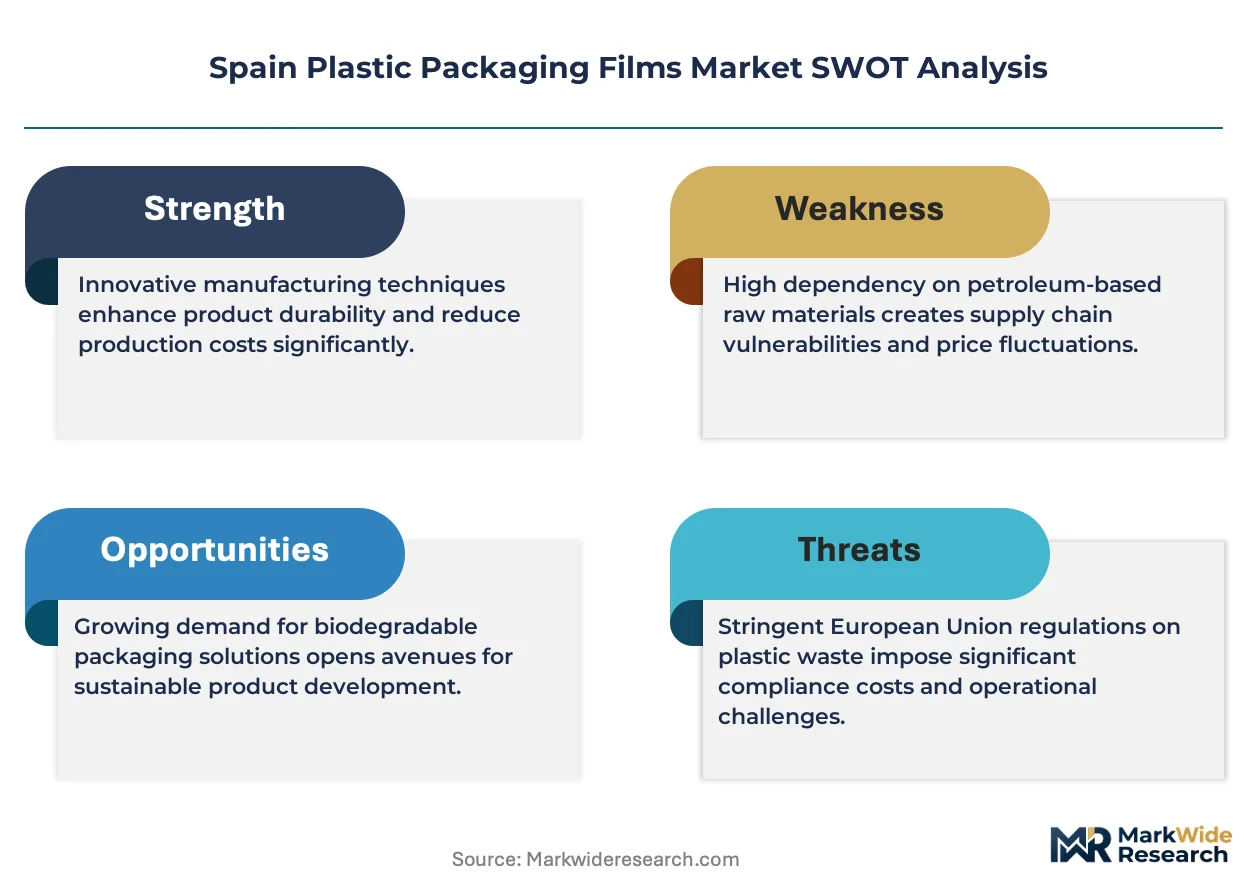
Spain's extended producer responsibility framework under EU packaging directives is redirecting capital flows toward recyclable mono-material film structures and away from legacy multi-layer laminates that dominate existing installed capacity.
Growth Catalysts
- EU Packaging and Packaging Waste Directive transposition:Spain's national implementation mandates recyclability targets that accelerate converter investment in polyethylene and polypropylene mono-material lines.
- High-barrier film specification:Protein and dairy processors in Valencia and Catalonia corridors demand oxygen transmission rates below 1 cc/m²/day, pulling capacity toward ethylene vinyl alcohol coextrusion.
- Food processing hub clustering:Flexible packaging converters concentrate within 50 kilometers of meat, seafood, and prepared meal facilities to reduce logistics costs and enable just-in-time delivery.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracker margins fluctuate with Brent crude pricing, compressing extrusion margins for polyethylene film producers serving industrial stretch applications.
- Multi-layer technical lock-in:Existing barrier film assets configured for polyethylene-polyamide-polyethylene structures cannot be economically retrofitted for mono-material output without full line replacement.
- German and Italian import competition:Specialized high-barrier films from Bavarian and Lombardy converters capture premium segments through established EFSA compliance documentation.
Strategic Opportunities
- Andalusia agricultural packaging:Underpenetrated fresh produce export corridors from Almería and Huelva require modified atmosphere packaging films with specific permeability curves for asparagus and berries.
- Chemical recycling feedstock partnerships:Pyrolysis infrastructure development in Tarragona petrochemical complex creates offtake agreements for post-industrial film scrap.
- Digital printing convergence:Inkjet and electrophotographic technologies enable short-run customized packaging for regional food brands without plate costs.
Industry Challenges
- Mono-material certification timelines:EFSA food-contact approval for novel barrier coatings extends 18-24 months, delaying commercialization of recyclable high-performance structures.
- Skilled extrusion technician scarcity:Blown film line operators with coextrusion die experience command wage premiums in Valencia industrial corridor.
- Legacy solvent-based lamination assets:Converters face stranded equipment risk as water-based and solventless adhesive technologies displace toluene-based systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Plastic Packaging Films Market |
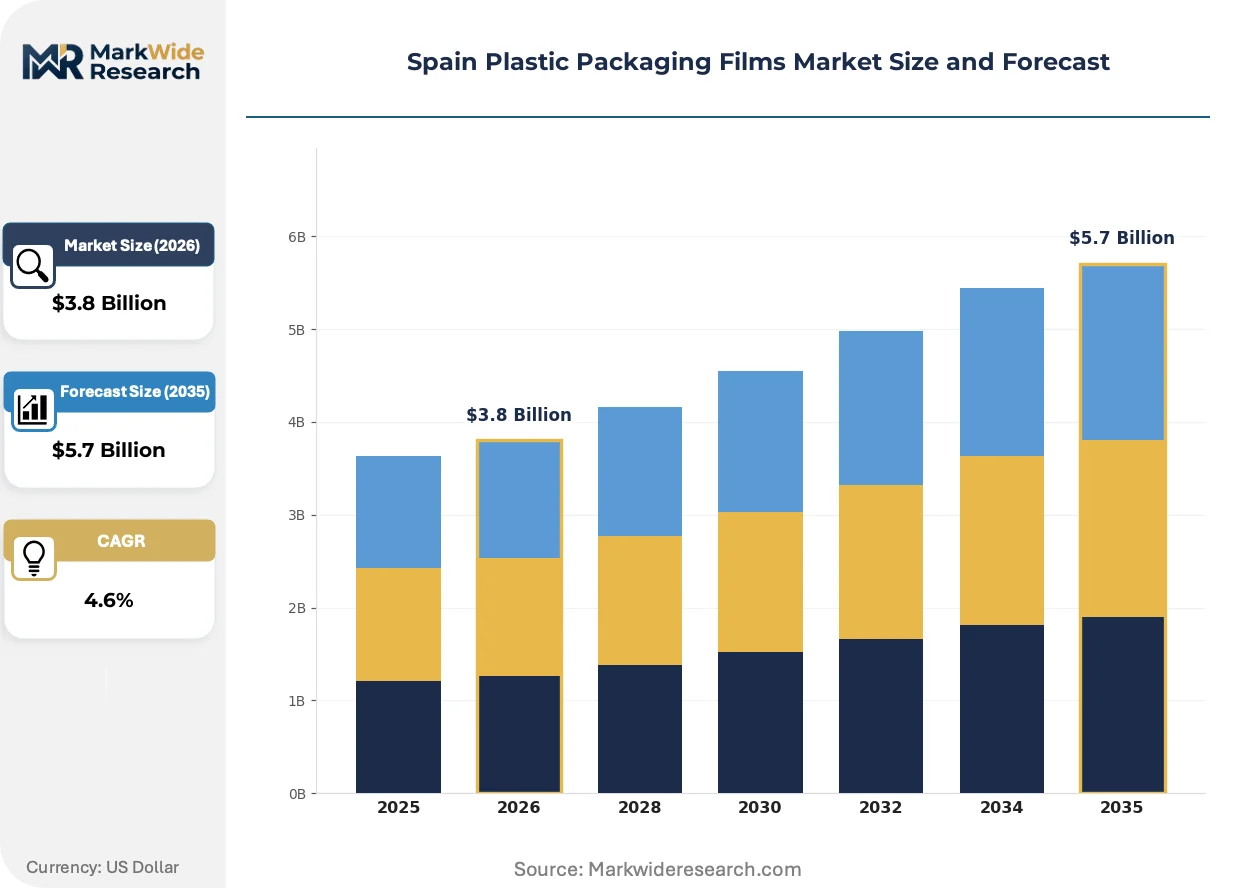
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Films, Shrink Films, Barrier Films, Rigid Films End Use Industry: Food Packaging, Pharmaceutical Packaging, Personal Care, Industrial Packaging Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polyester Thickness: Thin Gauge, Medium Gauge, Heavy Gauge, Ultra-Thin |
| Companies Covered | Berry Global Inc., Klöckner Pentaplast, Taghleef Industries, Luigi Bandera SpA, Amcor Plc, Constantia Flexibles, Mondi PLC, IFLEX Flexible Packaging SA, COVINIL SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Plastic Packaging Films Market Trends and Innovations
Digital printing integration and regulatory compliance automation are compressing product development cycles while reshaping how converters compete on customization speed versus unit cost.
Barrier coating technology is bifurcating the high-performance segment. Silicon oxide and aluminum oxide vapor-deposited films deliver oxygen barrier properties competitive with ethylene vinyl alcohol at reduced material thickness. Premium meat and cheese packagers in Catalonia are adopting these structures to reduce packaging weight and meet retailer sustainability scorecards. This technology is bifurcating the barrier film market into commodity coextrusion and premium vapor-deposited tiers with distinct margin profiles.
Spain's Ministry for Ecological Transition is enforcing ECHA REACH restrictions on per- and polyfluoroalkyl substances in food-contact films. Fluoropolymer-based grease barriers face phase-out timelines that force reformulation toward bio-based alternatives. Barrier film converters serving microwaveable popcorn and fast-food packaging segments are accelerating migration testing for polysaccharide and clay-based replacements.
Brand-led specification tightening is altering procurement patterns. Major Spanish retail chains now require recycled content verification through third-party mass balance certification. This behavioral shift concentrates purchasing power among converters with ISCC PLUS or equivalent accreditation, marginalizing smaller extruders lacking audit infrastructure. The Basque Country and Navarre food manufacturing clusters demonstrate this concentration most visibly.
Spain Plastic Packaging Films Market Segmentation
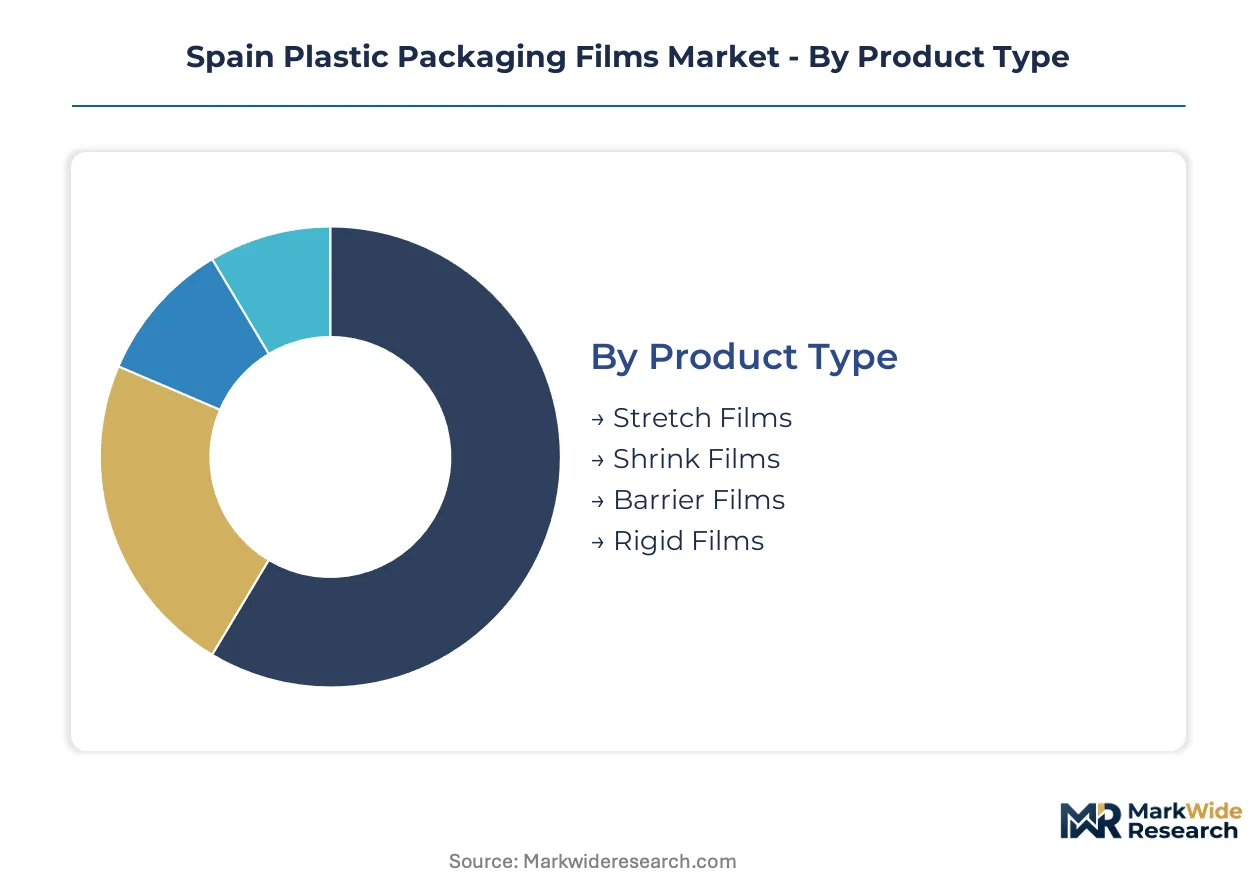
Spain's plastic packaging films market fragments across four distinct dimensions that shape procurement patterns and channel economics. Each segmentation axis reveals how converters align production capabilities with end-user specifications and regulatory compliance requirements.
Product Type:
Stretch films dominate industrial distribution channels serving Valencia and Catalonia logistics hubs, while barrier films flow through specialized food-contact converters with EFSA certification.
- Stretch Films:Linear low-density polyethylene formulations engineered for 200-300% elongation characteristics. Demand concentrates at automotive and ceramic exporters in Castellón and Tarragona corridors where pallet unitization volumes exceed 50 million units annually. EPR compliance costs are compressing margins for non-mono-material suppliers.
- Barrier Films:Multi-layer coextrusions incorporating ethylene vinyl alcohol or polyamide cores to achieve oxygen transmission rates below 1 cc/m²/day. Meat and cheese processors in Girona and Lleida specify these structures for modified atmosphere packaging, driving converter investment in seven-layer blown film lines.
- Shrink Films:Biaxially oriented polyethylene terephthalate or polyolefin formulations for retail multi-pack collation. Beverage bottlers in Barcelona metropolitan area represent the primary offtake channel.
- Rigid Films:Thermoformable polystyrene or polyester sheet structures for tray and blister applications. Pharmaceutical packagers in Madrid's Alcobendas corridor source these through audited medical-grade converters.
By volume, stretch films leads. By growth pace, barrier films is ahead.
End Use Industry:
Cost tier differentiation separates commodity film buyers from premium specification markets, with certification requirements creating distinct procurement strata.
- Food Packaging:Modified atmosphere and vacuum skin structures for protein, dairy, and prepared meals. Valencia's Mercadona supplier ecosystem and Catalonia's independent meat processors generate concentrated demand for high-barrier coextrusions with ISCC PLUS chain-of-custody documentation.
- Pharmaceutical Packaging:Blister lidding and cold-form foil laminates requiring EU GMP Annex 1 compliance. Barcelona and Madrid host the primary converting capacity serving domestic drug manufacturers.
- Personal Care:Flow-wrap and stand-up pouch films for cosmetics and hygiene products. Lower barrier requirements permit thinner gauge polyethylene structures.
- Industrial Packaging:Stretch hood and manual wrap films for construction materials and agricultural outputs. Price-sensitive procurement favors recycled content blends from post-industrial scrap.
Food packaging commands margin premiums. Industrial packaging captures volume leadership.
Material:
Application thermal requirements and recyclability mandates are reconfiguring material selection across converter portfolios.
- Polyethylene:Low-density and linear low-density grades for stretch, shrink, and general-purpose barrier applications. Mono-material PE structures are displacing legacy laminates as EPR rules harden.
- Polypropylene:Cast and oriented films for retort pouches and microwaveable applications exceeding 120°C thermal thresholds. Castellón converters specialize in metallized BOPP for snack packaging.
- Polyvinyl Chloride:Shrink films for pharmaceutical and consumer goods bundling. Regulatory pressure on chlorine chemistry is narrowing growth prospects.
- Polyester:Biaxially oriented polyethylene terephthalate for high-clarity lidding and thermoforming. Premium meat and cheese applications in Basque Country favor PET/PE laminates pending mono-material alternatives.
Polyethylene retains installed base dominance. Polypropylene is expanding most quickly in thermal-resistant segments.
Thickness:
Customer type stratification separates high-volume industrial buyers from specialty food processors with precise gauge tolerances.
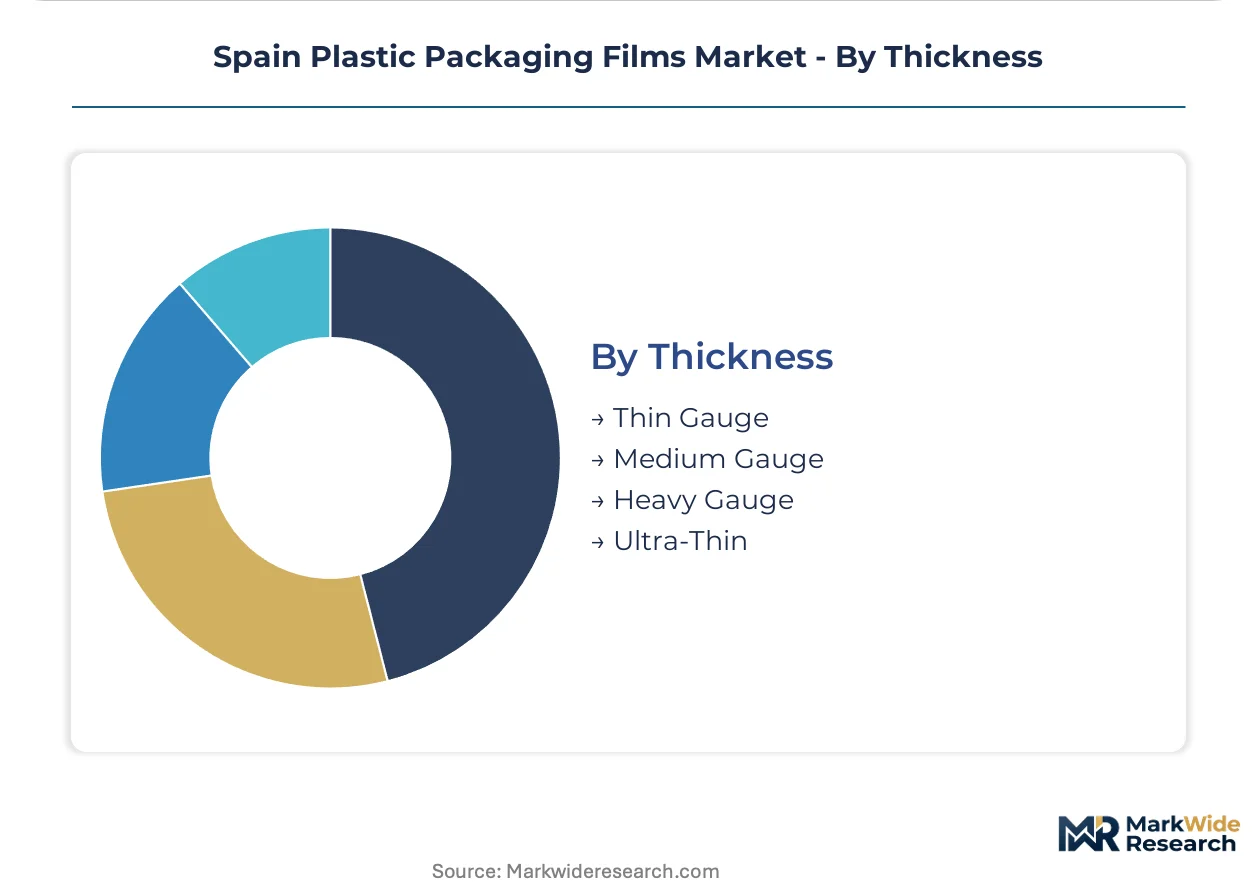
- Thin Gauge:12-25 micrometer structures for lightweight barrier and overwrap applications. Berry and vegetable exporters in Almería specify permeability-calibrated thin films for respiring produce.
- Medium Gauge:25-50 micrometer range for general-purpose food and industrial packaging. Represents the volume core of extruder output.
- Heavy Gauge:50-100 micrometer films for deep-draw thermoforming and industrial stretch hoods. Agricultural palletization in Huelva and Seville provinces drives seasonal demand spikes.
- Ultra-Thin:Below 12 micrometer vapor-deposited oxide barrier layers. Premium meat packagers in Catalonia adopt these for source-reduction compliance with retailer sustainability scorecards.
Medium gauge leads in tonnage terms. Ultra-thin films are gaining share fastest in premium barrier segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Valencia anchors Iberian film distribution, handling polyethylene resin imports and converted film exports that supply food processors across the western Mediterranean basin.
Catalonia
Meat and cheese packagers in Girona and Lleida specify oxygen transmission rates below 1 cc/m²/day for modified atmosphere packaging. ECHA REACH compliance obligations restrict per- and polyfluoroalkyl substances in food-contact layers, forcing reformulation toward bio-based grease barriers. Seven-layer blown film lines cluster in Barcelona's industrial belt to serve Mercadona's supplier ecosystem.
Valencia
Stretch film demand concentrates at automotive and ceramic exporters in Castellón and Tarragona corridors where pallet unitization exceeds 50 million units annually. Spain's Ministry for Ecological Transition enforces extended producer responsibility rules that redirect investment toward recyclable mono-material structures. Blown film line operators with coextrusion die experience command wage premiums throughout this industrial corridor.
Basque Country
Food manufacturing clusters in Navarre and the Basque Country demonstrate concentrated purchasing power among converters with ISCC PLUS chain-of-custody documentation. Major Spanish retail chains now require recycled content verification through third-party mass balance certification. Premium meat and cheese applications favor PET/PE laminates pending mono-material alternatives.
Andalusia
Fresh produce export corridors from Almería and Huelva require modified atmosphere packaging films with specific permeability curves for asparagus and berries. Berry and vegetable exporters specify permeability-calibrated thin films for respiring produce. Agricultural palletization in Huelva and Seville provinces drives seasonal demand spikes for heavy-gauge stretch hoods.
Madrid
Pharmaceutical packagers in Madrid's Alcobendas corridor source thermoformable polystyrene and polyester sheet structures through audited medical-grade converters. EU GMP Annex 1 compliance requirements govern blister lidding and cold-form foil laminates for domestic drug manufacturers. Barcelona and Madrid host the primary converting capacity serving this regulated segment.
Spain Plastic Packaging Films Market Competitive Landscape
Concentration sits with vertically integrated multinationals that control extrusion and conversion stages. The vendor base spans three tiers: global packaging conglomerates with Iberian manufacturing footprints, regional specialists in barrier film formulations, and commodity extruders serving industrial stretch applications. Strategic moves center on capacity expansion in mono-material lines and technology licensing for vapor-deposited oxide barriers.
Among the multinational tier, Amcor Plc and Mondi PLC exemplify geographic dominance in barrier film supply, while Berry Global Inc. occupies a position in sustainable film formulation development. Constantia Flexibles and Klöckner Pentaplast represent European-based converters with established EFSA compliance documentation. Taghleef Industries anchors the regional specialist segment with metallized BOPP capabilities in Castellón.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Klöckner Pentaplast |
| Taghleef Industries |
| Luigi Bandera SpA |
| Amcor Plc |
| Constantia Flexibles |
| Mondi PLC |
| IFLEX Flexible Packaging SA |
| COVINIL SA |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between polyethylene resin suppliers and Valencia corridor converters lock in supply access and price visibility for 12-24 month windows. These arrangements insulate food packaging buyers from naphtha-cracker margin volatility while embedding EPR compliance cost pass-through clauses.
Pricing Analysis
Volume-discount tiering structures separate Mercadona-scale buyers from independent meat processors in Girona. Three-tier pricing stratifies across premium barrier films with EVOH cores, standard coextrusions for general food contact, and economy-grade stretch films for industrial palletization. Certification premiums for ISCC PLUS chain-of-custody documentation add margin capture for audited converters. Price erosion runs through industrial stretch segments as recycled-content blends from post-industrial scrap compress differentiation. Food packaging buyers exhibit lowest price sensitivity due to shelf-life performance requirements, while construction material distributors drive hardest bargain negotiations.
Supply Chain Analysis
Just-in-time inventory preferences dominate converter-processor relationships within 50 kilometers of Valencia and Catalonia food hubs. Raw material sourcing draws from Saudi ethylene crackers, Belgian polymer distributors, and Tarragona petrochemical complex outputs. Blown film line operators with seven-layer coextrusion expertise represent a single-source vulnerability for high-barrier capacity. Distribution runs through Port of Valencia for resin imports and converted film exports serving western Mediterranean processors. Strategic stockpiling of EVOH barrier resins occurs only among multinational converters with working capital depth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mono-material coextrusion capability sits in scarce supply relative to regulatory mandate velocity, creating acquisition premiums for converters with certified lines and EFSA-approved barrier coatings.
For Market Incumbents: Compound geographic dominance in Iberian barrier film supply through captive production of metallized BOPP in Castellón and backward integration into resin compounding. Defend against German and Italian import competition by accelerating EFSA documentation for novel oxide barrier coatings. Prioritize certification investment in ISCC PLUS mass balance auditing infrastructure to capture Mercadona supplier ecosystem concentration. For New Entrants and Emerging Players: Anchor in Andalusia agricultural packaging corridors where modified atmosphere specifications for asparagus and berries remain underpenetrated by established converters. Target fresh produce exporters in Almería with permeability-calibrated thin films engineered for respiring commodities. Pursue digital printing convergence as go-to-market angle, enabling short-run customization without plate costs for regional food brands. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with long-term offtake agreements to protein and dairy processors in Valencia and Catalonia corridors. Five-to-ten year viability favors assets with mono-material line configurations and established EPR compliance infrastructure. Monitor Spanish royal decrees on extended producer responsibility implementation timelines as inflection signal for stranded multi-layer asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Line Conversion | EPR compliance mandates under EU Packaging Directive accelerate capital redeployment from multi-layer laminates. |
| Barrier Coating Technology Licensing | Vapor-deposited oxide films from silicon and aluminum sources displace EVOH cores in premium meat packaging. |
| Chemical Recycling Feedstock Partnership | Pyrolysis infrastructure in Tarragona creates offtake agreements for post-industrial film scrap streams. |
| Digital Printing Platform Integration | Inkjet and electrophotographic technologies compress product development cycles for regional brand customization. |
| Extended Producer Responsibility Compliance Investment | Spain's Ministry for Ecological Transition enforcement redirects procurement toward audited mass balance certification. |
Research Methodology
Operator-level perspectives from blown film line supervisors, flexible packaging procurement managers at Mercadona suppliers, EFSA regulatory affairs specialists, and resin distribution account managers anchored the qualitative base. Secondary validation drew from Spanish customs polyethylene trade data, ECHA REACH substance restriction notifications, EU Packaging Directive transposition documents, and SEC filings of listed packaging conglomerates. Bottom-up extruder capacity counts and top-down food processing demand estimates were triangulated to constrain volume outputs.
Sensitivity analysis tested forecast outputs against ethylene feedstock price volatility scenarios and EPR implementation timing variations. Segmentation dimensions modeled include product type, end-use industry, material chemistry, and thickness gauge across the analysis window. CAGRs were derived from installed capacity expansion announcements and food processor packaging specification trends. Forecast inputs incorporated EFSA approval timelines for novel barrier coatings and skilled technician wage premium trajectories in Valencia corridor.
Decision-makers should treat outputs as directional under base assumptions of EPR rule enforcement by 2027 and sustained naphtha-cracker margin compression; material deviation in regulatory timelines or feedstock cost structures would warrant model refresh. Practitioners should keep alternative scenarios live as Spanish royal decree specifics on extended producer responsibility fee structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Peelable and Resealable Films Market
Poly film
Global EVOH Films for Packaging Market
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
India Plastic Packaging Film Market
Poly film
North America BOPP Films Market
Poly film
Global Polyethylene Packaging Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
Stretch Films Packs Market
Poly film
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
PCR Lidding Films Market
Poly film
Polyethylene Furanoate Films Market
Poly film
Co Extruded Films Market
Poly film
Polytetrafluoroethylene (PTFE) Films Market
Poly film
China BOPP Film Market
Poly film
Cast Stretch Packaging Films Market