
 Bio-PET Film Market | 2026-2036
Bio-PET Film Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-PET Film Market Analysis
Modular packaging configurations is shifting how converters specify film grades, with buyers unbundling traditional monolayer contracts into separate substrate and functional coating procurements. Toray Industries leverages its biaxial orientation expertise to anchor premium barrier film supply in Asia. DuPont Teijin Films sustains North American converter relationships through captive resin-to-film integration. Indorama Ventures Public Company Limited dominates upstream bio-monomer supply, positioning its film affiliates with captive feedstock access.
Bio-PET film is a biaxially oriented polyester substrate manufactured partially or wholly from bio-based terephthalic acid or ethylene glycol derived from renewable feedstocks such as sugarcane ethanol, exhibiting optical clarity, mechanical strength, and thermal stability comparable to petroleum-derived PET. Its primary purpose is to replace conventional PET in packaging and industrial applications where brand owners and regulators mandate reduced fossil-carbon content without sacrificing performance. Flexible packaging leads volume absorption as snack and fresh-produce brands seek transparent, heat-sealable bio-based barriers. Medical Applications represents the fastest-growing end-user segment, driven by sterilization-grade film demand and hospital sustainability procurement protocols. Thermal Lamination occupies the mature margin pool, with converters accepting thinner gauges to offset bio-based raw material premiums.
The EU Green Deal and REACH chemical registration frameworks constrain petroleum-based additive use while rewarding bio-based content claims with reduced regulatory burden. FDA food-contact notification requirements in the United States shape migration testing protocols for bio-based monomers entering food packaging film. Japan's METI bioplastics certification and the country's national plastics recycling mandates create dual compliance pathways that film exporters must navigate. Stakeholders must monitor whether bio-monomer capacity expansions outpace converter qualification timelines, as feedstock availability without certified film capacity will strand investment and delay brand-owner packaging transitions.
Market Dynamics
Converter qualification timelines for bio-monomer grades lag resin capacity expansions by 18-24 months, stranding upstream investment and forcing brand owners to maintain dual petroleum-bio film inventories during transition periods.
Growth Catalysts
- EU Green Deal packaging mandates:The EU Green Deal's waste reduction directives enforce minimum recycled and bio-based content thresholds, compelling food brands to specify bio-PET barrier layers for compliance.
- Sterilization-grade medical film demand:Hospital procurement protocols now require sustainability credentials alongside performance, pulling bio-PET into surgical tray and device packaging applications.
- Sugarcane ethanol feedstock scale:Brazilian and Thai sugarcane processing clusters supply cost-competitive bio-ethylene glycol, anchoring raw material economics for film converters.
Market Restraints
- Bio-ethylene glycol price volatility:Agricultural feedstock costs fluctuate with sugar and ethanol commodity cycles, compressing converter margins against fixed petroleum-PET benchmarks.
- Asia-Pacific resin concentration:Over 60 percent of bio-monomer capacity clusters in Thailand and India, exposing buyers to single-source geographic risk and freight cost spikes.
- Optical clarity limitations:Early-generation bio-PET exhibits slight yellowing versus petroleum grades, restricting adoption in premium cosmetic and display packaging segments.
Strategic Opportunities
- Japan METI bioplastics certification pathway:The METI framework offers dual compliance routes that reduce testing burden for certified bio-PET film exporters entering Japanese medical and food packaging channels.
- Fresh-produce breathable film applications:Modified atmosphere packaging for berries and leafy greens demands precisely tuned oxygen transmission rates that bio-PET coextrusions can engineer.
- Digital printing substrate compatibility:Water-based and UV-curable ink adhesion on bio-PET surfaces matches petroleum grades, enabling converter migration without press reconfiguration.
Industry Challenges
- Food-contact migration testing timelines:FDA notification protocols for novel bio-based monomers extend 12-18 months, delaying brand owner packaging transitions and locking converters into legacy resin approvals.
- Biaxial orientation technician scarcity:Specialized machine operators capable of tuning stretch ratios for bio-PET's slightly different rheology command premium wages and limited geographic availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-PET Film Market |
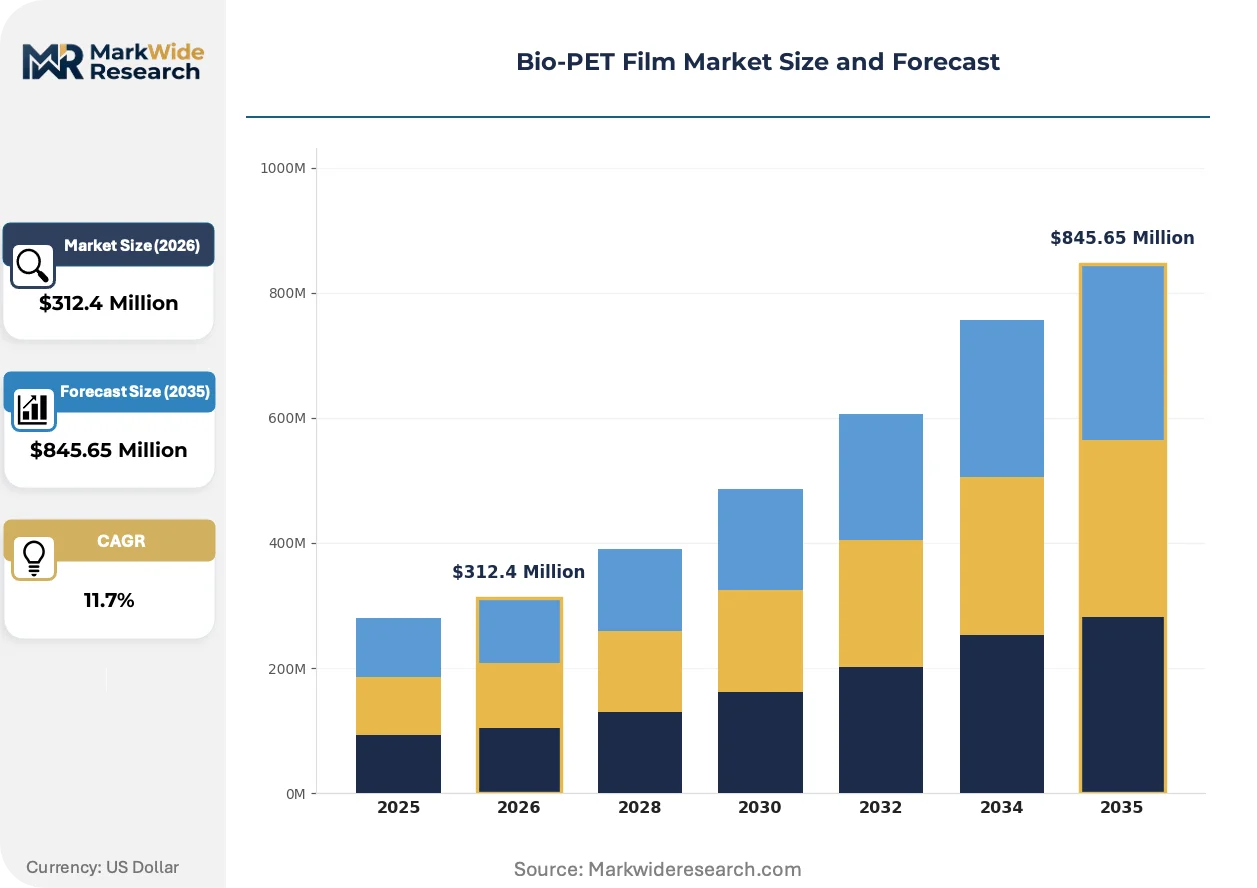
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Lamination, Flexible Packaging, Rigid Packaging, Specialty Films End User: Food Packaging, Beverage Packaging, Consumer Goods, Medical Applications Thickness: Below 100 Micron, 100-200 Micron, 200-300 Micron, Above 300 Micron Application: Labeling, Wrapping, Coating, Printing |
| Companies Covered | Polyplex Corporation Limited, Teijin Limited, Toray Industries, Uflex Ltd., DuPont Teijin Films, Indorama Ventures Public Company Limited, Kuraray, LOTTE Chemical Corporation, Mitsubishi Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-PET Film Market Emerging Trajectories
Active film functionalization and substrate-coating unbundling are compressing traditional converter margins while opening specialty chemical attachment points. Material science advances now enable property tuning at the molecular level.
Barrier coating deposition is converging with atomic layer deposition techniques to achieve sub-micron oxygen and moisture barriers on bio-PET substrates. Medical device manufacturers are adopting these films for sterile barrier systems at accelerated qualification paces. This convergence is compressing the performance gap between bio-based and metallized petroleum-PET in high-value pharmaceutical packaging.
REACH chemical registration frameworks now require comprehensive substance dossiers for petroleum-derived additives used in conventional PET films. The regulatory burden is shifting converter specification toward bio-based additive packages with simpler registration pathways. Flexible packaging converters in Germany and the Netherlands are responding fastest, locking in bio-PET supply contracts ahead of 2027 compliance deadlines.
Brand owner sustainability scorecards now weight packaging carbon intensity as heavily as unit cost in supplier selection criteria. Major snack and beverage buyers are unbundling traditional film procurement into separate substrate and functional layer contracts, enabling bio-PET substitution without disrupting established converter relationships. This pattern concentrates in Northern European markets where retailer environmental reporting mandates are most stringent.
Bio-PET Film Market Segmentation
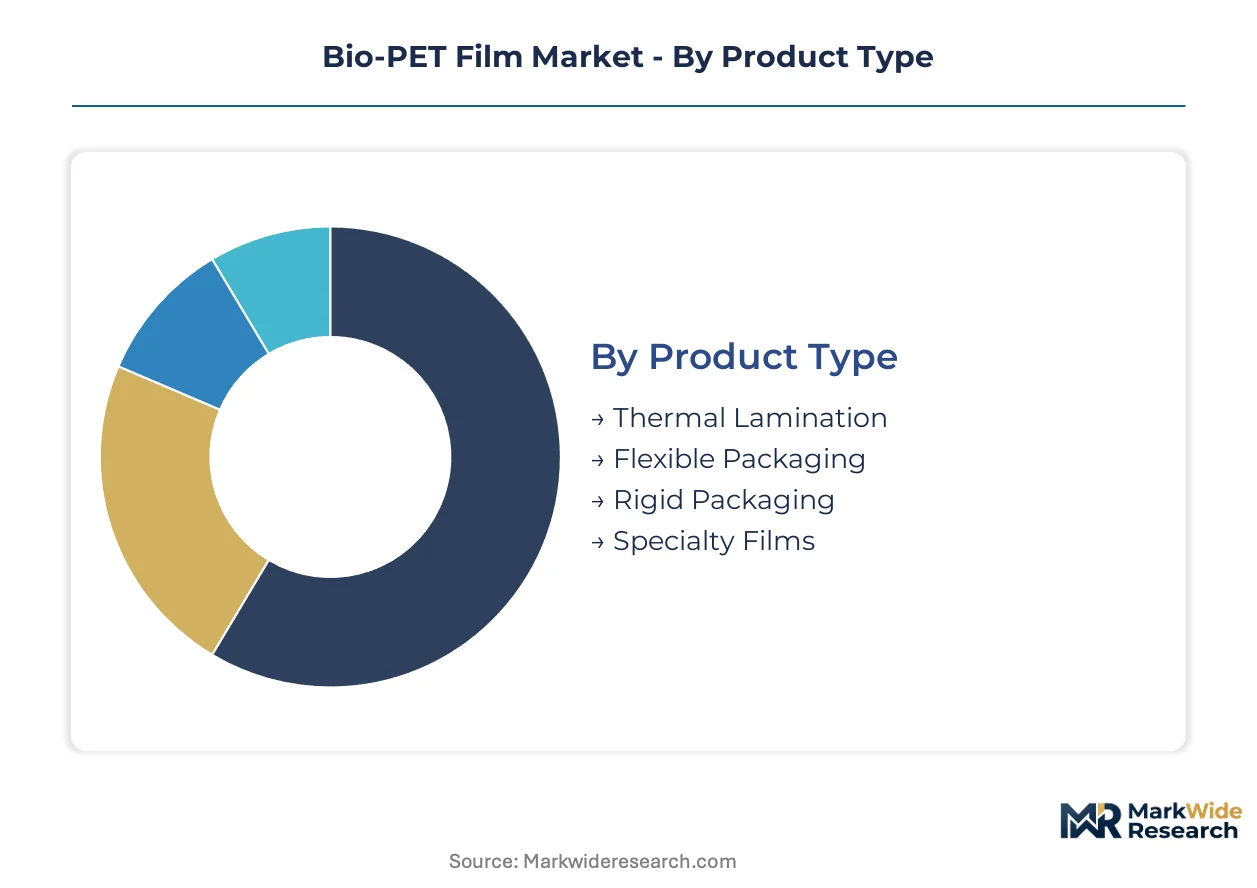
Segmentation in bio-PET film markets reveals how capital deployment, technical specifications, and regulatory compliance intersect. Converter procurement strategies diverge sharply across thickness grades and end-use certifications, reshaping supplier competitive positioning.
Product Type:
Capital intensity varies dramatically by orientation line configuration and barrier functionalization requirements.
- Flexible Packaging:Coextruded and coated bio-PET films engineered for heat-seal layers and oxygen barriers. Demand concentrates in German snack and fresh-produce supply chains where EU Green Deal mandates accelerate material substitution timelines.
- Thermal Lamination:Thinner-gauge bio-PET substrates bonded to paper and board through heated nip systems. Japanese converters favor these grades for textbook and commercial document protection under METI bioplastics certification pathways.
- Rigid Packaging:Thermoformable bio-PET sheet for tray and clamshell applications. Pharmaceutical blister packs in North America drive qualification activity.
- Specialty Films:Surface-treated grades for holographic and security applications. Limited volume but premium pricing in tax stamp and authentication markets.
Flexible packaging absorbs the bulk of installed capacity; specialty films are expanding most quickly.
End User:
Customer procurement protocols determine margin structure and certification burden.
- Medical Applications:Sterilization-grade bio-PET films for surgical tray lidding and device packaging. Hospital sustainability mandates in Germany and Japan pull supply through dual compliance frameworks.
- Food Packaging:Barrier films for modified atmosphere packaging of proteins and produce. EU packaging waste directives enforce minimum bio-based content thresholds.
- Beverage Packaging:Shrink sleeve and label substrates for bottled water and soft drinks. Brand-owner carbon scorecards weight packaging intensity heavily.
- Consumer Goods:Cosmetic and electronics packaging where optical clarity specifications restrict adoption of early-generation bio-PET grades.
Food packaging commands the largest revenue pool; medical applications climb the fastest.
Thickness:
Line speed and yield economics shift nonlinearly across gauge boundaries.
- Below 100 Micron:Ultra-thin bio-PET for flexible lidding and label face stocks. High line speeds in Thai and Indian production clusters compress unit costs.
- 100-200 Micron:Mid-gauge films balancing stiffness and conformability. Thermal lamination converters in the Netherlands specify these grades for premium document finishing.
- 200-300 Micron:Heavy-duty films for thermoformed trays and deep-draw applications. Medical device manufacturers in Germany qualify these for sterile barrier systems.
- Above 300 Micron:Structural grades for display and point-of-sale applications. Limited bio-PET penetration due to raw material cost premiums against petroleum-PET.
Sub-100 micron gauges dominate volume throughput; 200-300 micron brackets gain share fastest in medical channels.
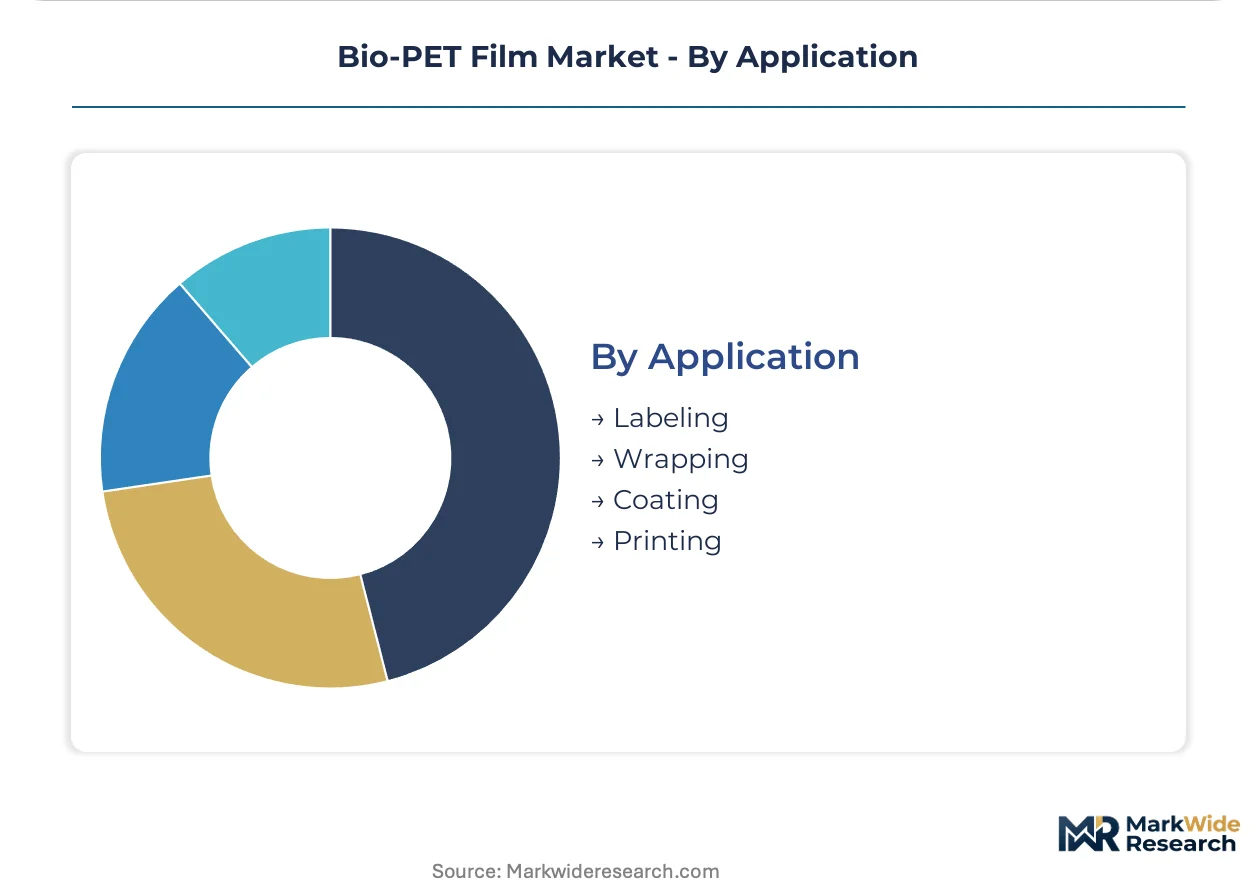
Application:
Downstream process compatibility determines surface treatment and coating specifications.
- Wrapping:Bio-PET films for overwrap and bundle shrink applications. Fresh-produce breathable films in berry and leafy green supply chains tune oxygen transmission rates precisely.
- Labeling:Pressure-sensitive and glue-applied label face stocks. Water-based and UV-curable ink adhesion matches petroleum-PET performance.
- Coating:Substrates receiving vapor-deposited or solution-coated barrier layers. Atomic layer deposition techniques achieve sub-micron oxygen barriers.
- Printing:Direct-print bio-PET for flexible packaging graphics. Digital press compatibility enables converter migration without equipment reconfiguration.
Wrapping applications anchor baseline demand; coating applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai and Indian production clusters supply most bio-monomer feedstock, while German and Japanese converters absorb premium film grades. This geographic split strands upstream capacity when converter qualification lags.
Germany
Snack brands and hospital procurement networks drive bio-PET film absorption. EU Green Deal packaging waste directives enforce minimum bio-based content thresholds from 2027. The Ruhr converter belt hosts qualification facilities linking resin imports to flexible packaging output.
United States
Pharmaceutical blister pack manufacturers and beverage label converters specify bio-PET substrates. FDA food-contact notification protocols extend 12-18 months for novel bio-monomers. New Jersey and Massachusetts medical device clusters pilot sterilization-grade film adoption.
Japan
Surgical tray lidding demand pulls bio-PET through hospital sustainability mandates. METI bioplastics certification offers reduced testing burden for compliant film exporters. The Nagoya medical packaging corridor concentrates qualification activity for high-barrier grades.
Thailand
Sugarcane ethanol processing anchors bio-ethylene glycol supply for Asian film production. The country's national bioplastics roadmap incentivizes downstream conversion investment. Rayong and Map Ta Phut industrial zones host integrated resin-to-film operations serving export markets.
Netherlands
Thermal lamination converters specify mid-gauge bio-PET for premium document finishing applications. REACH chemical registration frameworks constrain petroleum-derived additive use in conventional films. The Eindhoven-Tilburg corridor links coating specialists to German brand-owner supply chains.
Bio-PET Film Market Vendor Landscape
The competitive structure tilts toward resin-integrated conglomerates with captive bio-monomer supply. Japanese and Thai industrial groups dominate upstream positions while European and North American affiliates control converter relationships. Three archetypes define positioning: petrochemical majors with film divisions, specialized polyester converters, and integrated packaging conglomerates. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players bridge feedstock-to-film gaps.
Among Japanese industrial groups, Teijin Limited and Toray Industries exemplify the resin-to-film integration archetype. DuPont Teijin Films occupies a position spanning North American converter access with technical service depth. Indorama Ventures Public Company Limited anchors the upstream-centric model with Thai bio-monomer production feeding affiliated film operations.
| Leading Market Players |
|---|
| Polyplex Corporation Limited |
| Teijin Limited |
| Toray Industries |
| Uflex Ltd. |
| DuPont Teijin Films |
| Indorama Ventures Public Company Limited |
| Kuraray |
| LOTTE Chemical Corporation |
| Mitsubishi Chemical Corporation |
| Others |
Supply Flow & Price Mechanics
Brand-owner carbon scorecard mandates are forcing converters to split substrate and functional layer contracts, compelling suppliers to restructure pricing models around bio-based content certification tiers rather than integrated film bundles.
Pricing Analysis
Margin tightening in standard-grade bio-PET reflects sugarcane ethanol commodity cycles compressing converter spreads against fixed petroleum-PET benchmarks. Three-tier pricing structure across medical-grade, food-contact, and industrial lamination levels differentiates by FDA notification status and METI certification completion. Pricing pressure intensifies in sub-100 micron gauges as Thai and Indian production clusters scale output. Beverage label converters exhibit highest price sensitivity due to thin-margin sleeve applications, while medical device manufacturers accept premiums for sterilization-grade barrier properties.
Supply Chain Analysis
EU Green Deal domestic-content thresholds are reshaping sourcing patterns for German and Dutch converters who must document bio-based origin through certified supply chains. Bio-monomer production clusters in Thailand and India feed film orientation lines, while German and Japanese converters control premium grade qualification. Raw material flows draw from sugarcane ethanol processing, bio-terephthalic acid refining, and specialized additive packages. Single-source geographic concentration in Southeast Asia exposes buyers to freight cost volatility. Distribution runs through converter belt networks in the Ruhr and Nagoya corridors linking resin imports to brand-owner specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bio-PET film market is becoming a vertical-integration race where captive bio-monomer supply determines margin sustainability and converter relationship durability.
For Market Incumbents: Deepen backward integration into bio-ethylene glycol production to offset agricultural feedstock volatility threatening converter margin stability. Lock in multi-year offtake agreements with German snack brands ahead of EU packaging waste directive deadlines. Secure biaxial orientation technician pipelines through apprenticeship partnerships with technical institutes in Thailand and India. For New Entrants and Emerging Players: Mid-gauge thermal lamination converters in the Netherlands represent an underserved buyer archetype seeking REACH-compliant alternatives to petroleum-PET with shorter qualification cycles than medical grades. Target fresh-produce breathable film applications where oxygen transmission rate engineering creates specification gaps incumbent suppliers have not filled. Enter through coating-specialist partnerships rather than capital-intensive orientation line investments. For Investors and Strategic Acquirers: The window for entry favors resin-integrated conglomerates with Thai or Indian bio-monomer positions and dormant film conversion capacity awaiting qualification. Long-term viability hinges on converter network control rather than upstream scale alone. Watch for FDA food-contact notification backlog clearance as the signal indicating accelerated brand-owner packaging transitions and stranded capacity absorption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Monomer Production | Captive sugarcane ethanol supply insulates converter margins from commodity cycle volatility. |
| Medical-Grade Certification Investment | FDA notification completion unlocks surgical tray lidding demand from German hospital networks. |
| Converter Belt Geographic Expansion | Ruhr and Nagoya corridor presence secures brand-owner specification influence in premium segments. |
| Atomic Layer Deposition Partnership | Sub-micron barrier coating convergence enables pharmaceutical blister pack substitution against metallized films. |
| Long-Term Supply Agreement with Snack Brands | EU Green Deal compliance deadlines force committed volume absorption ahead of 2027 thresholds. |
Methodological Framework
Independent corroboration across resin plant managers, flexible packaging procurement leads at German snack brands, medical device technical directors, and distribution channel partners in the Netherlands underwrites the qualitative findings. Secondary validation draws from EU packaging waste directive filings, FDA food-contact notification databases, Thai customs export records, and METI bioplastics certification registries. Bottom-up capacity estimates from bio-monomer production clusters triangulate against top-down brand-owner procurement disclosures.
Rate-of-change decomposition across thickness grades, end-use certifications, and regional regulatory clusters structures the projection framework. Segmentation dimensions include product type, application method, and converter qualification status. CAGRs derive from supply-demand balance modeling incorporating bio-monomer capacity expansion timelines and converter qualification lag assumptions. Key inputs encompass sugarcane ethanol price forecasting and EU packaging directive implementation pacing.
Revisions become necessary when FDA notification processing accelerates or delays materially, bio-monomer capacity outpaces film orientation line investment, or EU member state transposition of packaging waste directives diverges from baseline assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
Cellulose Film Packaging Market
Poly film
EVOH Encapsulation Film Market
Poly film
Global BOPET Packaging Films Market
Poly film
Cast Stretch Packaging Films Market
Poly film
Soft Touch Film Market
Poly film
Metallized Film Market
Poly film
Silicone Release Films Market
Poly film
Foamed Polypropylene Films Market
Poly film
Resealable Films Market
Poly film
North America BOPP Films Market
Poly film
Global Polycarbonate Sheets and Films Market
Poly film
Spain Plastic Packaging Films Market
Poly film
Twist Wrap Film Market
Poly film
Packaging Film Market
Poly film
Craft Plastic Films Market