
 Polybag Mailers Market | 2026-2036
Polybag Mailers Market Size, Share, and Industry Trends Forecast 2026-2036
Polybag Mailers Market Outlook
Third-party logistics providers are redrawing procurement patterns in the polybag mailers space as e-commerce fulfillment volumes surge. Sealed Air Corporation leverages its global manufacturing footprint to serve cross-border parcel networks. Pregis LLC specializes in cushioned mailer technologies for fragile goods segments. Intertape Polymer Group Inc. anchors North American supply through its integrated film extrusion and converting operations.
Polybag mailers are lightweight, flexible shipping envelopes manufactured from polyethylene films or paper-based laminates, typically featuring adhesive closures and dimensional stability for automated sortation systems. Low-density polyethylene dominates material type selection due to its tear resistance and cost efficiency in high-volume parcel operations. Application demand tilts heavily toward e-commerce and logistics channels where dimensional weight pricing and automated handling requirements favor standardized mailer formats over corrugated alternatives.
EPA guidelines on recycled content thresholds and FDA food-contact material standards shape film composition choices for mailers entering pharmaceutical and consumer goods supply chains. The EU Green Deal's packaging waste reduction targets and California's extended producer responsibility frameworks are forcing reformulation toward post-consumer recycled content and mono-material structures. Stakeholders must monitor evolving state-level recycling infrastructure investments to align product specifications with actual recovery capabilities rather than theoretical recyclability claims.
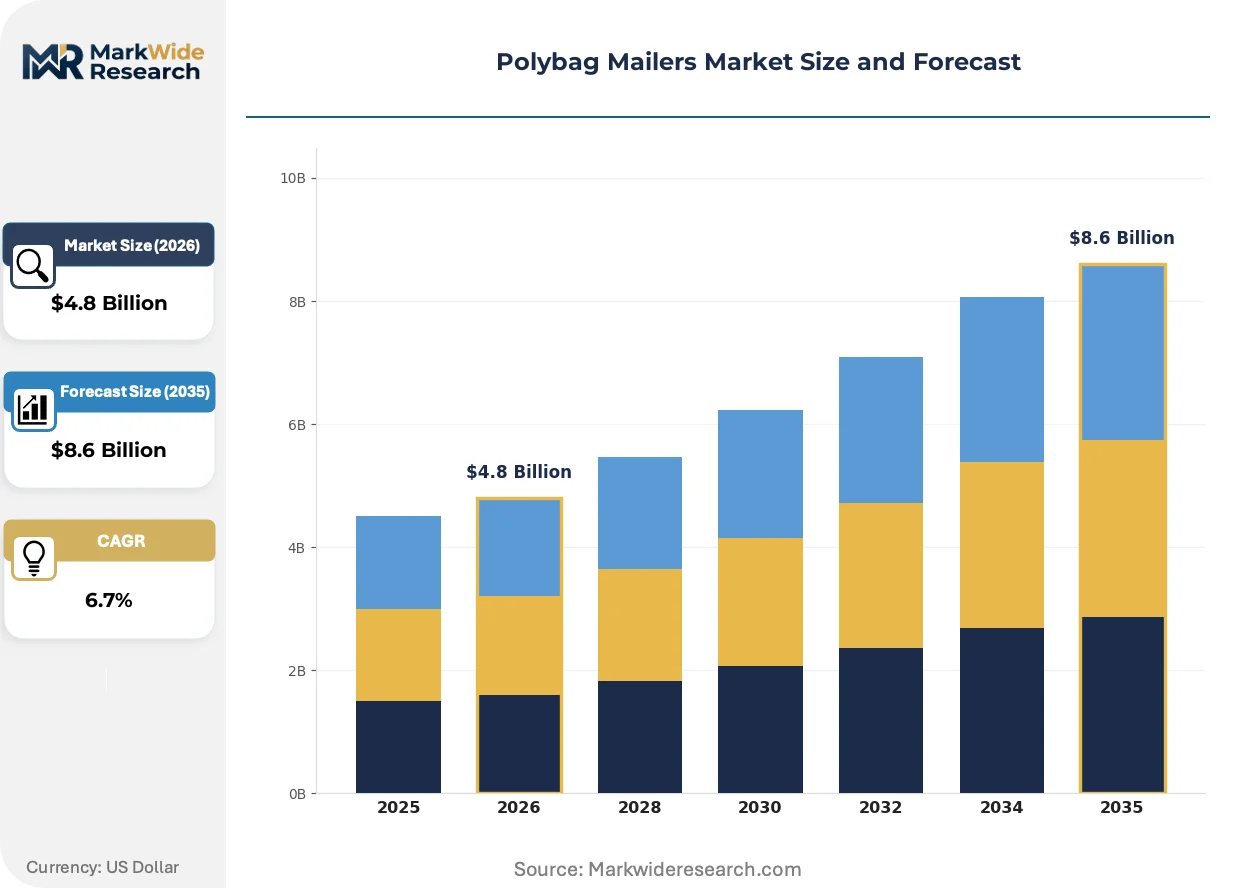
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing formulation timelines for mono-material structures while e-commerce fulfillment networks demand tamper-evident closure systems at scale. This dual pressure is restructuring supplier relationships and capital allocation across the value chain.
Growth Catalysts
- EU Green Deal packaging targets:Mandated post-consumer recycled content thresholds are pulling investment into film reprocessing infrastructure across member states.
- Automated sortation compatibility:Dimensional stability specifications for high-speed parcel handling are standardizing mailer formats in logistics corridors.
- Germany's logistics density:The Düsseldorf-Frankfurt corridor concentrates fulfillment demand, creating procurement pull for regional film converters.
Market Restraints
- LDPE resin price volatility:Feedstock cost swings compress converter margins and destabilize long-term contract pricing.
- Recycling infrastructure gaps:Actual recovery capabilities lag theoretical recyclability claims, creating stranded asset risk for reformulated products.
- Corrugated substitution in heavy goods:Dimensional weight pricing thresholds favor rigid packaging above certain density thresholds.
Strategic Opportunities
- California EPR frameworks:Extended producer responsibility implementation creates first-mover advantage for compliant mono-material structures.
- Pharmaceutical cold chain expansion:Temperature-stable mailer laminates for biologics distribution represent underpenetrated application space.
- Direct-to-consumer brand verticals:Unboxing experience requirements are opening premium mailer segments outside traditional logistics procurement.
Industry Challenges
- Multi-layer film delamination:Separating barrier coatings from PE substrates at industrial scale remains technically unproven for post-consumer waste streams.
- FDA food-contact certification timelines:Recycled content approval pathways for pharmaceutical and consumer goods applications extend product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polybag Mailers Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Low-Density Polyethylene, High-Density Polyethylene, Biodegradable Films, Kraft Paper, Bubble Lined, Compostable Films Application: E-commerce, Logistics, Subscription Boxes, Pharmaceutical Packaging, Apparel Shipment, Document Delivery Closure Style: Self-Seal, Recyclable Tape, Zipper Lock, Peel & Seal, Button & String, Snap Seal End User: Third-Party Logistics Providers, Courier Services, Online Retailers, Pharmaceutical Distributors, Print Media Houses, Small Businesses |
| Companies Covered | Sealed Air Corporation, Pregis LLC, Intertape Polymer Group Inc., PAC Worldwide Corporation, ProAmpac LLC, PolyPak Industries, Uline, Avery Dennison Corporation, International Plastics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polybag Mailers Market Strategic Shifts
Material science advances and regulatory compliance frameworks are converging to reshape competitive positioning in protective packaging. Three distinct vectors are redefining product specifications and procurement criteria.
Mono-material polyethylene structures with integrated barrier coatings are supplanting multi-layer laminates in pharmaceutical and consumer goods applications. Third-party logistics providers in Germany and the Netherlands are specifying these formats for automated sortation compatibility. The shift compresses converter R&D timelines while eliminating separation steps in mechanical recycling streams.
REACH restrictions on per- and polyfluoroalkyl substances are accelerating fluorochemical-free barrier development for moisture-sensitive shipments. Industrial consequence includes reformulation of opaque mailer films previously dependent on PFAS-based grease resistance. Pharmaceutical distributors in the EU are now requiring supplier certifications documenting fluorine-free composition.
Brand-direct procurement teams are consolidating supplier relationships around vertically integrated film extruders with in-house PCR content certification. This pattern displaces fragmented spot purchasing through distribution intermediaries. Apparel and cosmetics verticals in North America exhibit the most visible concentration, with specified recycled content thresholds written into multi-year supply agreements.
Polybag Mailers Market Segmentation
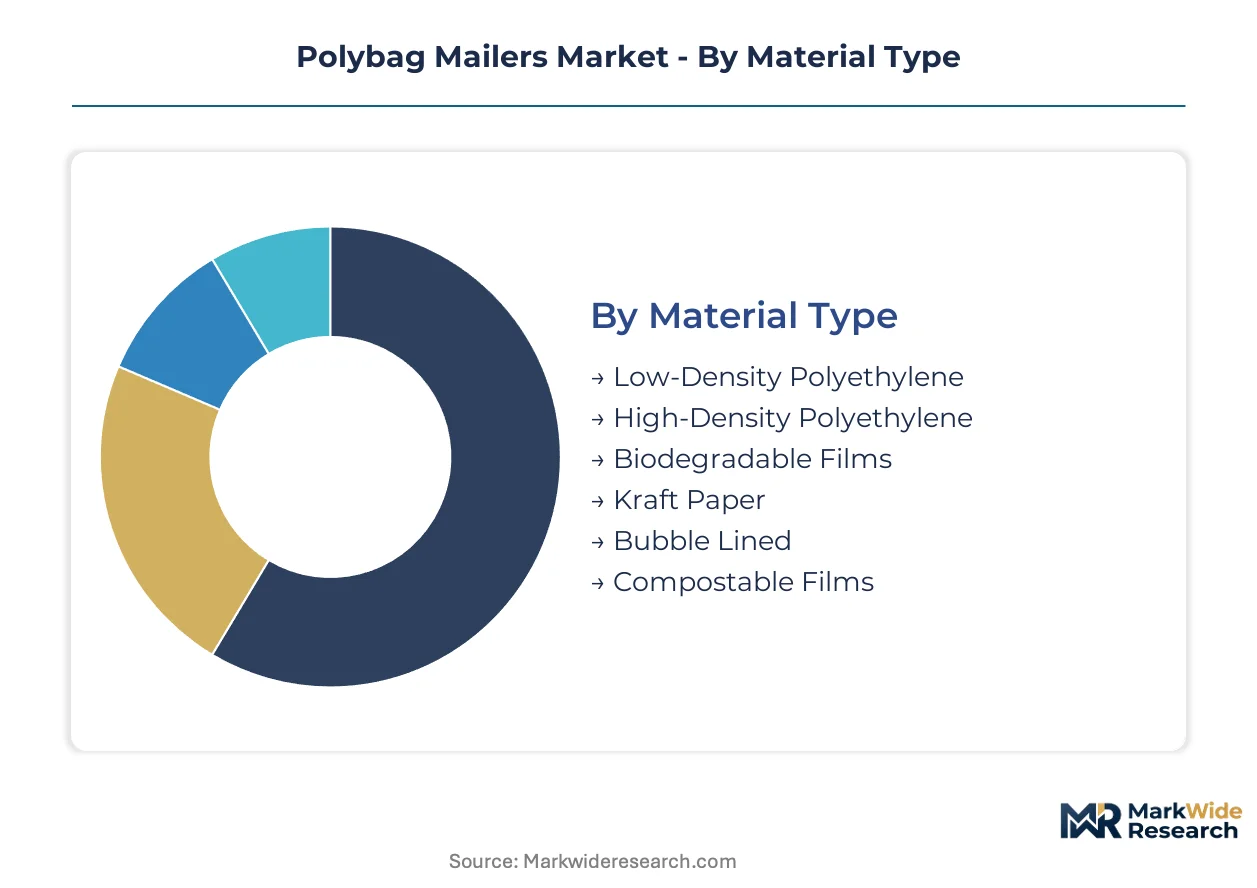
Segmentation in the polybag mailers market reveals how material specifications and closure technologies align with distinct regulatory thresholds across e-commerce and pharmaceutical supply chains. Procurement teams segment specifications by automated handling compatibility and post-consumer recyclability mandates rather than cost alone.
Material Type:
REACH and FDA compliance timelines differentiate material selection, with mono-material structures gaining preference for simplified certification pathways.
- Low-Density Polyethylene:Thermoplastic polymer with high branching density delivers tear resistance and flexibility for automated sortation systems. E-commerce fulfillment centers in Germany's Düsseldorf-Frankfurt corridor specify LDPE for dimensional weight pricing advantages and high-speed conveyor compatibility.
- Biodegradable Films:Starch-based or aliphatic polyester compositions degrade under industrial composting conditions per EN 13432 standards. EU Green Deal packaging waste targets are pulling demand toward these films in France and the Netherlands where industrial composting infrastructure is municipally supported.
- High-Density Polyethylene:Linear polymer structure with higher crystallinity offers stiffness for document-heavy shipments requiring edge protection.
- Kraft Paper:Unbleached wood pulp construction satisfies brand-direct unboxing requirements and paper-stream recyclability in North American municipal systems.
- Bubble Lined:Co-extruded polyethylene air retention layers laminated to outer film skins for fragile goods protection.
- Compostable Films:Certified home-compostable variants meeting TÜV OK Compost HOME specifications for direct-to-consumer cosmetics verticals.
Established volume favors Low-Density Polyethylene; emerging adoption favors Biodegradable Films.
Application:
End-use concentration determines barrier specification intensity, with pharmaceutical cold chain requirements imposing the strictest material validation protocols.
- E-commerce:Standardized formats with printed barcodes and tear strips for automated returns processing. Third-party logistics providers in the Netherlands specify tamper-evident closures and dimensional stability for cross-border parcel networks handling high SKU velocity.
- Pharmaceutical Packaging:Multi-layer laminates or coated mono-materials with moisture vapor transmission rate specifications for biologics distribution. FDA 21 CFR compliance and EMA cold chain guidelines force extended development cycles for recycled content integration in this segment.
- Logistics:Bulk shipment protection for inter-facility transfers with minimal branding requirements.
- Subscription Boxes:Premium print surfaces and resealable closures for recurring unboxing experiences in beauty and apparel verticals.
- Apparel Shipment:Lightweight constructions optimized for soft goods with minimal corner protection needs.
- Document Delivery:Rigid formats with edge reinforcement for legal and financial document integrity.
Procurement scale concentrates in E-commerce; technical complexity peaks in Pharmaceutical Packaging.
Closure Style:
Automation compatibility and recyclability certification separate closure technologies, with adhesive systems facing the strictest reformulation pressures under PFAS restrictions.
- Self-Seal:Pressure-sensitive adhesive strips with release liners enabling single-motion closure. Logistics corridors in Germany specify these for high-speed packing stations where operator time per unit directly influences fulfillment cost structures.
- Recyclable Tape:Water-based acrylic adhesives compatible with PE film recycling streams without delamination. California's extended producer responsibility frameworks are accelerating specification of these closures by brand-direct procurement teams.
- Zipper Lock:Interlocking plastic profiles for reusable return pathways in rental apparel and reusable packaging schemes.
- Peel & Seal:Extended adhesive coverage for heavy contents requiring reinforced closure integrity.
- Button & String:Mechanical closure for document and certificate presentation requiring ceremonial unboxing.
- Snap Seal:Rigid interlocking tabs for temperature-stable pharmaceutical shipments.
Operational speed favors Self-Seal; regulatory compliance favors Recyclable Tape.
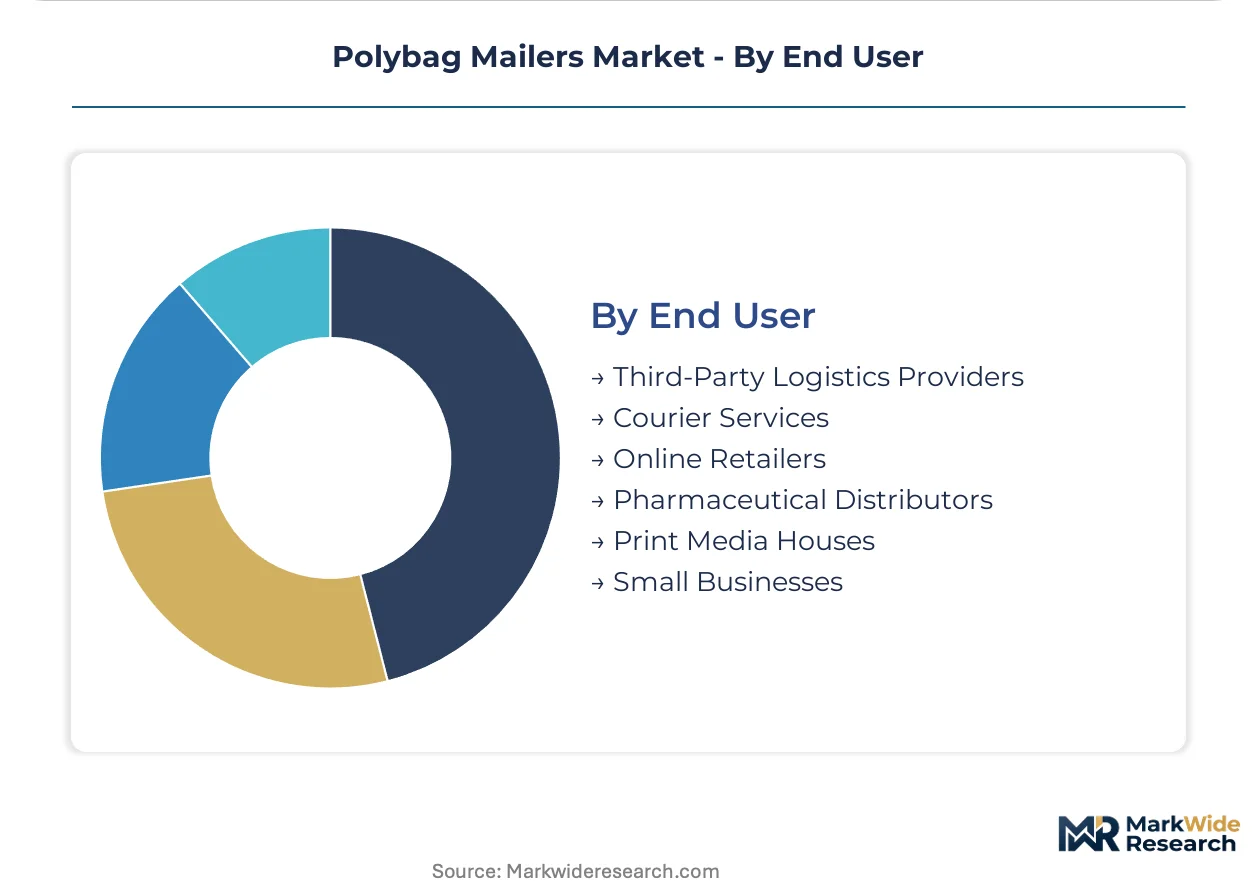
End User:
Procurement sophistication varies sharply, with pharmaceutical distributors imposing certificate-of-analysis requirements absent in small business spot purchasing.
- Third-Party Logistics Providers:Centralized procurement of standardized formats across multi-tenant fulfillment networks. These operators in Germany's logistics corridor consolidate volumes to extract dimensional pricing advantages from film converters.
- Online Retailers:Brand-customized print specifications with unboxing experience requirements driving premium mailer segments. North American apparel verticals specify post-consumer recycled content thresholds in multi-year supply agreements.
- Courier Services:High-velocity procurement of undifferentiated formats for last-mile delivery density.
- Pharmaceutical Distributors:Temperature qualification protocols and FDA food-contact material standards for secondary packaging.
- Print Media Houses:Rigid mailer specifications for catalog and magazine distribution with address window integration.
- Small Businesses:Spot purchasing through distribution intermediaries with minimal technical specification.
Contract discipline concentrates with Third-Party Logistics Providers; customization intensity peaks with Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main corridor's high-speed freight rail network underwrites Germany's dominance in European fulfillment infrastructure, while the Port of Rotterdam's automated container handling anchors Netherlands logistics. Cross-border parcel volumes concentrate where these assets intersect with regulatory pressure for sustainable packaging reform.
Germany
The Düsseldorf-Frankfurt logistics corridor concentrates third-party fulfillment demand from e-commerce platforms. EU Packaging and Packaging Waste Regulation mandates are accelerating mono-material mailer specifications among film converters in Hesse. Regional procurement teams at DHL and Hermes hubs now require post-consumer recycled content thresholds in multi-year supply contracts.
United States
EPA recycled content guidelines and California's extended producer responsibility frameworks are reshaping procurement patterns across West Coast fulfillment networks. The Inland Empire warehouse cluster east of Los Angeles anchors domestic e-commerce packaging demand. Amazon and Walmart distribution centers in the region specify recyclable tape closures and dimensional stability for automated sortation.
Netherlands
Port of Rotterdam's automated handling systems standardize mailer formats for cross-border parcel networks serving Northern Europe. REACH restrictions on PFAS chemicals are forcing fluorochemical-free barrier development among film converters in South Holland. Third-party logistics providers in Venlo's free trade zone consolidate volumes to extract pricing advantages from regional extruders.
France
Industrial composting infrastructure in Île-de-France and Provence-Alpes-Côte d'Azur supports biodegradable film adoption for cosmetics and apparel verticals. ANSM pharmaceutical packaging guidelines impose certificate-of-analysis requirements on mailers entering cold chain distribution. Paris-based fulfillment networks specify EN 13432-certified compostable structures for direct-to-consumer brands.
China
Dual carbon goals and MIIT packaging waste reduction targets are pulling investment into post-consumer recycled film infrastructure across the Yangtze River Delta. Shanghai's automated parcel sorting hubs standardize LDPE mailer specifications for dimensional weight pricing. Cross-border e-commerce platforms in Hangzhou specify tamper-evident closures for international shipment compliance.
Polybag Mailers Market Competitive Environment
Concentration sits with integrated film extruders possessing captive PCR certification capabilities. The supplier base stratifies between multinational converters with global manufacturing footprints and regional specialists serving single logistics corridors. Two archetypes dominate: vertically integrated resin-to-mailer producers and technology-focused barrier coating developers. Competitive moves center on backward integration into film reprocessing and geographic expansion through distribution partnerships in high-growth fulfillment markets.
Among North American fabricators, Sealed Air Corporation and Pregis LLC exemplify the scale-driven archetype with integrated operations across multiple logistics corridors. Intertape Polymer Group Inc. occupies a position within the regional supply anchor tier, serving automated sortation networks through captive film extrusion. These three entities represent distinct competitive postures: global network coverage, specialized cushioning technology, and upstream control over resin conversion.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis LLC |
| Intertape Polymer Group Inc. |
| PAC Worldwide Corporation |
| ProAmpac LLC |
| PolyPak Industries |
| Uline |
| Avery Dennison Corporation |
| International Plastics, Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between German third-party logistics providers and film converters lock in LDPE resin access while stabilizing unit cost visibility across volatile feedstock cycles. These arrangements concentrate procurement power among Düsseldorf-Frankfurt corridor operators, compressing spot-market participation for smaller fulfillment networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade certified mailers from e-commerce bulk formats. Price differentiation hinges on post-consumer recycled content thresholds and FDA food-contact certification status. Cost compression in standard tiers is intensifying because LDPE resin volatility transfers directly to converter margins. Small business spot purchasers exhibit highest price sensitivity; pharmaceutical distributors accept premium positioning for validated cold chain performance.
Supply Chain Analysis
Inventory buffers at Rotterdam port facilities extend lead times for North American buyers sourcing European film extrusion. Supply concentrates in Germany, the Netherlands, and China, with resin conversion clustered near automated parcel hubs. Raw material dependencies center on virgin and recycled LDPE pellets, adhesive formulations, and barrier coating chemicals. Single-source vulnerability runs through Yangtze River Delta reprocessing infrastructure. Distribution runs through vertically integrated converters with captive PCR certification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as EU Green Deal packaging mandates force accelerated adoption of mono-material structures across fulfillment networks. Penetration tailwinds from pharmaceutical cold chain expansion and direct-to-consumer brand verticals remain underdeveloped relative to e-commerce baseline demand.
For Market Incumbents: Secure captive film reprocessing capacity in Germany's logistics corridor to defend against emerging regional specialists. Deepen backward integration into PCR certification infrastructure before California EPR frameworks tighten compliance windows. Prioritize fluorochemical-free barrier R&D to preempt REACH restriction enforcement.
For New Entrants and Emerging Players: Lead with temperature-stable mailer laminates for biologics distribution, the most penetrable white-space segment given extended FDA approval timelines for incumbent reformulations. Target pharmaceutical distributors in France and the Netherlands with certificate-of-analysis documentation capabilities absent in generalist converters.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated resin-to-mailer producers with multi-year supply contracts to third-party logistics providers. Five-to-ten year viability favors converters with in-house PCR content certification rather than spot-market resin purchasers. Monitor California EPR implementation velocity as inflection indicator for compliant mono-material pricing premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Reprocessing | Captive PCR supply secures EU Packaging and Packaging Waste Regulation compliance ahead of competitor reformulation cycles. |
| Fluorochemical-Free Barrier Development | REACH restriction anticipation positions converters for pharmaceutical distributor qualification requirements. |
| Long-Term Supply Agreements with 3PLs | Düsseldorf-Frankfurt corridor volume consolidation extracts dimensional pricing advantages from regional extruders. |
| Temperature-Stable Mailer Certification | FDA 21 CFR pathway completion opens biologics distribution segment with extended development cycle barriers. |
| Geographic Expansion through Distribution Partnerships | Rotterdam port access enables standardized format penetration of Northern European cross-border parcel networks. |
Study Parameters
Desk research of customs trade databases, SEC filings from packaging converters, and EU regulatory submission records preceded structured interviews with film extrusion plant managers, third-party logistics procurement leads, pharmaceutical distributor packaging engineers, and brand-direct supply chain directors. Primary fieldwork combined with secondary validation across REACH restriction timelines and FDA food-contact material guidance documents. Bottom-up volume estimates from converter capacity utilization triangulated against top-down e-commerce parcel flow projections.
Variance decomposition separates growth contributions from material substitution, regulatory compliance-driven specification upgrades, and fulfillment network expansion across the analysis window. Segmentation dimensions modeled include material type, application end-use, closure technology, and geographic logistics corridor concentration. CAGRs were derived from weighted average of historical resin price elasticity and projected automation adoption curves. Forecast inputs incorporate LDPE resin futures volatility bands and municipal recycling infrastructure investment pipelines.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce volume growth or accelerated EU regulatory enforcement would require recalibration. Forecasts reflect documented assumptions regarding PCR content availability and mechanical recycling yield rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Foamed Polypropylene Films Market
Poly film
North America Plastic Film Packaging Market
Poly film
Mexico Plastic Packaging Films Market
Poly film
Polyurethane (PU) Film Market
Poly film
Light Reflective Film Market
Poly film
Printed Plastic Films Market
Poly film
Global BOPP Films Market
Poly film
Canada Plastic Packaging Films Market
Poly film
Global Polycarbonate Sheets and Films Market
Poly film
Vinyl Films Market
Poly film
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market
Poly film
Americas Polypropylene (PP) Films Market
Poly film
Laminated Packaging Films Market
Poly film
Thermoforming Films Market
Poly film
Bundling Film Market
Poly film
Global Specialty Films Polymer Market