
 Foam Edge Protectors Market | 2026-2036
Foam Edge Protectors Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Edge Protectors Market Foresight
Closed-cell foam molding technology is reconfiguring how edge protectors achieve density gradients and impact resistance without material waste. Sealed Air Corporation leverages its proprietary foam extrusion systems to sustain manufacturing scale across North American and European plants. Storopack Hans Reichenecker GmbH anchors its competitive position through deep specialization in customized protective packaging geometries for industrial machinery. Pregis LLC differentiates by controlling direct-to-manufacturer distribution channels that bypass traditional wholesale markup structures.
Foam edge protectors are engineered cushioning devices fabricated from expanded polymer matrices, typically featuring densities between 1.5 and 6.0 pounds per cubic foot, designed to absorb and distribute impact forces at product corners and edges during handling and transit. Polyethylene formulations dominate volume production due to their closed-cell structure, moisture resistance, and suitability for repeated-use logistics cycles, while polyurethane segments command premium positioning in applications requiring conformability to irregular surface contours. Electronics assemblers represent the fastest-growing end user industry as semiconductor and display panel shipments require increasingly precise corner protection against micro-fracture risks.
The EPA regulates foam manufacturing emissions under Clean Air Act standards, while REACH compliance in Europe restricts certain chemical blowing agents used in polystyrene expansion processes. These frameworks elevate R&D spending toward bio-based and recycled-content formulations that satisfy both jurisdictions without reformulation for export markets. Stakeholders must monitor evolving extended producer responsibility schemes that will shift disposal cost liability upstream to foam converter operations.
Market Dynamics
Closed-cell foam molding technology is collapsing the trade-off between density gradients and material waste, forcing converters to retool extrusion lines or cede share to specialized molders. Electronics assemblers now specify corner-protection tolerances that legacy die-cutting cannot meet.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability mandates for protective materials accelerate converter investment in mono-material polyethylene formulations that simplify end-of-life sorting.
- Semiconductor logistics:Micro-fracture risks in display panel and chip shipments drive specification of conformable polyurethane edge protectors with Shore A hardness below 30.
- German automotive export packaging:Precision-machined foam geometries for powertrain components sustain specialized closed-cell consumption despite broader volume pressures.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and propylene price swings compress foam converter margins, particularly for small-batch custom molders without indexed supply contracts.
- REACH chemical restrictions:Banned blowing agents in polystyrene expansion force reformulation costs that disproportionately burden mid-tier European producers.
- Paper-based substitutes:Molded pulp edge protectors gain traction in cost-sensitive e-commerce fulfillment, displacing foam in non-fragile consumer goods lanes.
Strategic Opportunities
- Extended producer responsibility schemes:Upcoming EU disposal cost liability shifts create first-mover advantage for converters offering take-back programs and closed-loop recycling infrastructure.
- India electronics manufacturing:PLI scheme incentives for semiconductor and display fabrication build domestic demand for precision protective packaging currently met by imports.
- Bio-based foam convergence:Integration of mycelium and algae-derived feedstocks with conventional extrusion equipment opens premium positioning for carbon-conscious brand owners.
Industry Challenges
- Tooling capex intensity:Closed-cell density gradient molding requires multi-cavity aluminum dies costing $150,000-$400,000 per configuration, straining converter balance sheets.
- REACH compliance timelines:Chemical substance notification deadlines compress R&D cycles, forcing parallel formulation tracks for EU and non-EU export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Edge Protectors Market |
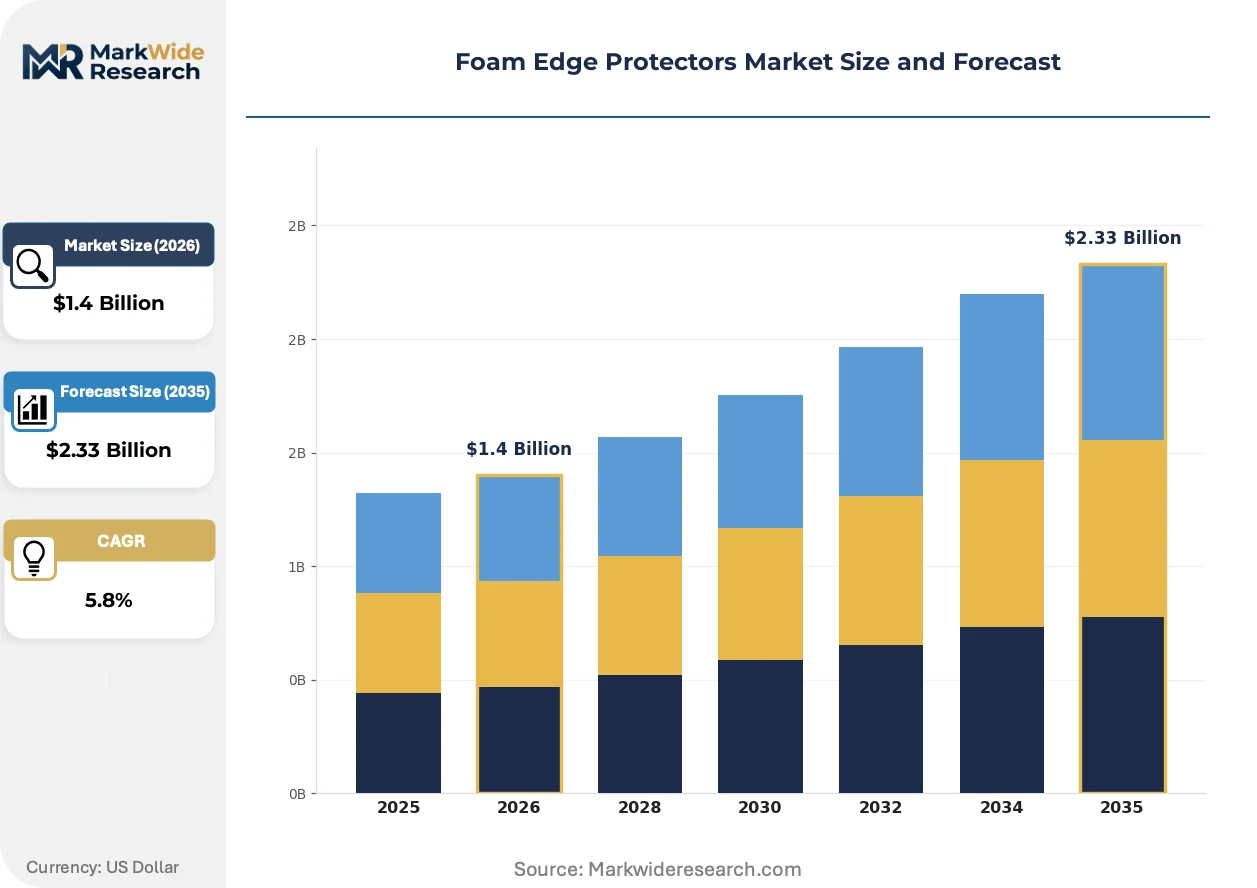
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polyurethane, Polystyrene, EVA Foam, Neoprene End User Industry: Furniture Manufacturers, Electronics Assemblers, Packaging Companies, Construction Firms, Logistics Providers Application: Package Cushioning, Corner Protection, Surface Guarding, Pallet Stabilization, Impact Absorption Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesale Suppliers, Specialized Dealers |
| Companies Covered | Sealed Air Corporation, Storopack Hans Reichenecker GmbH, Pregis LLC, Polartech, Springpack, Nomaco, Nefab Group, FP International, GMA Systems Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Edge Protectors Market Shifts & Advancements
Material science advances and regulatory stringency are compressing product development cycles while elevating performance specifications. Three forces currently reshape competitive positioning.
Multi-layer co-extrusion is collapsing the cost-performance frontier for moisture-resistant edge protectors. Automotive tier suppliers in Germany and Mexico are adopting five-layer polyethylene structures that eliminate separate lamination steps. This technology is collapsing the premium that closed-cell formulations previously commanded over open-cell alternatives in humid logistics corridors.
REACH restrictions on persistent organic pollutants in blowing agents are redirecting R&D spending toward water-blown and supercritical CO2 expansion systems. Foam converters in the Netherlands and Belgium face 2026 compliance deadlines that require full process retooling. Electronics packaging segments respond fastest, as brand owners demand certification-ready supply chains ahead of regulatory enforcement.
Direct-to-manufacturer distribution is displacing wholesale intermediaries in North American industrial packaging procurement. Large automotive and aerospace OEMs now specify foam edge protectors through integrated supplier portals that bypass traditional packaging distributors. This pattern concentrates most visibly in Michigan and Ohio manufacturing clusters, where tier-one suppliers consolidate protective packaging sourcing under single-vendor agreements.
Foam Edge Protectors Market Segmentation
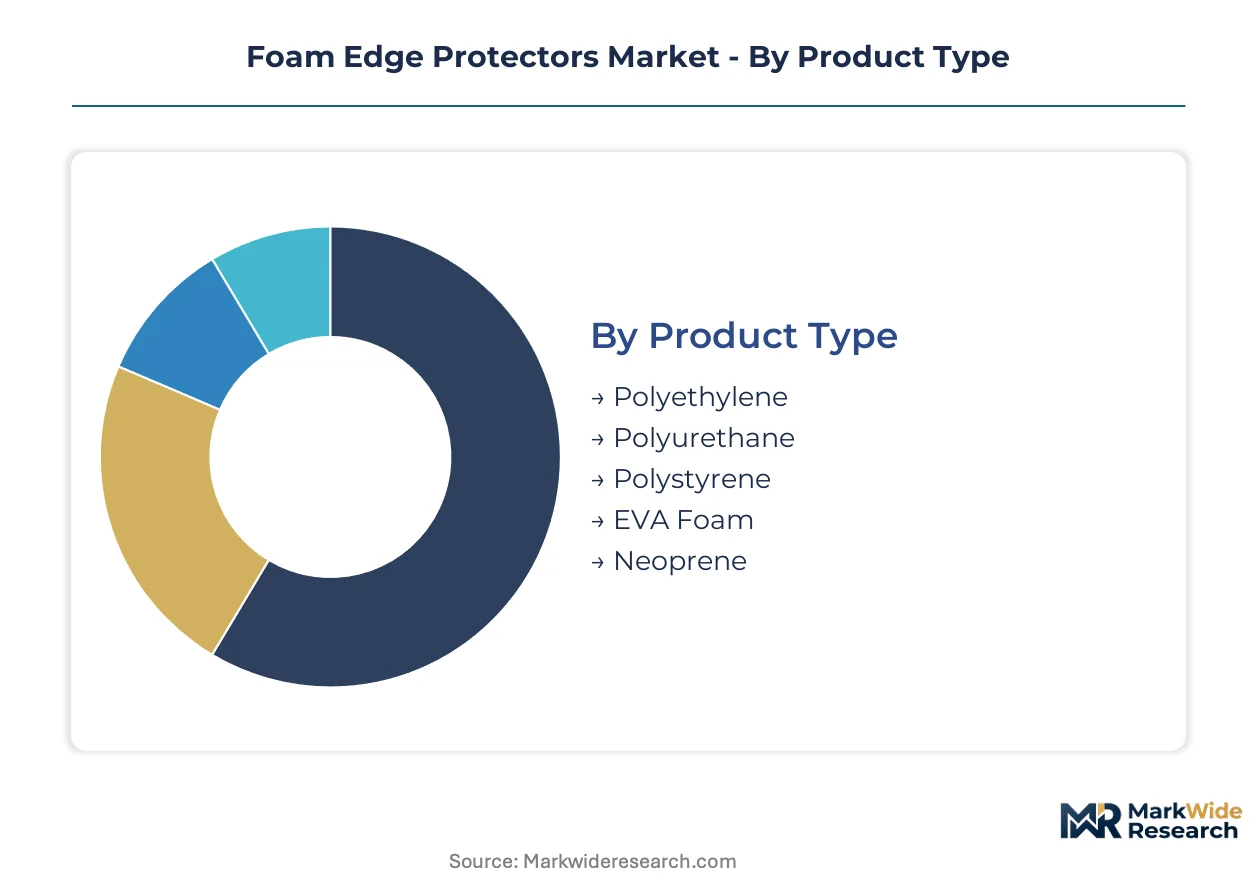
Segmentation in foam edge protectors reveals how material chemistry, end-use precision requirements, and channel economics create distinct competitive arenas. Each dimension carries divergent margin structures and technical barriers that reshape converter investment priorities.
Product Type:
Material composition determines moisture resistance, conformability, and recyclability profiles that lock converters into specific customer relationships.
- Polyethylene:Closed-cell extrusions with densities between 1.5 and 6.0 pounds per cubic foot dominate volume production through moisture resistance and suitability for repeated-use logistics cycles. German automotive parts exporters specify this grade for powertrain component packaging despite broader volume pressures from paper substitutes.
- Polyurethane:Open-cell formulations with Shore A hardness below 30 command premium positioning through conformability to irregular surface contours. Electronics assemblers in semiconductor and display panel shipments drive specification for micro-fracture protection against corner impact.
- Polystyrene:Expanded bead structures face REACH restrictions on chemical blowing agents that force reformulation costs disproportionately burdening mid-tier European producers.
- EVA Foam:Ethylene-vinyl acetate copolymers balance cushioning recovery with UV stability for outdoor construction applications.
- Neoprene:Chloroprene-based closed-cell grades serve chemical-resistant industrial machinery guarding with higher temperature tolerance.
Polyethylene commands the established base. The steepest expansion runs through polyurethane.
End User Industry:
Customer type segmentation exposes how precision tolerance requirements and procurement scale separate commodity from specialty foam conversion.
- Electronics Assemblers:Semiconductor and display panel manufacturers specify corner-protection tolerances that legacy die-cutting cannot meet, with conformable polyurethane edge protectors gaining fastest traction against micro-fracture risks in chip shipments.
- Logistics Providers:Third-party fulfillment operators prioritize polyethylene closed-cell grades for pallet stabilization across repeated handling cycles, with cost sensitivity driving consolidation toward direct-manufacturer procurement channels that bypass wholesale markup.
- Furniture Manufacturers:Upholstery and case goods producers specify medium-density polyethylene for package cushioning of finished goods with moderate fragility.
- Packaging Companies:Converter intermediaries stock standardized edge protector inventories for resale to smaller fulfillment operations without volume for direct mill relationships.
- Construction Firms:Building material distributors absorb surface guarding applications for glass, metal trim, and prefabricated components with lower specification intensity.
Electronics assemblers are climbing the fastest. Logistics providers anchor volume throughput.
Application:
Functional use case segmentation maps directly to impact energy absorption requirements and geometric complexity in foam fabrication.
- Corner Protection:L-profile and U-profile extrusions with precise angle tolerances protect high-value goods at highest fracture risk points. Electronics packaging segments in the Netherlands and Belgium respond fastest to REACH compliance deadlines for blowing agent restrictions.
- Package Cushioning:Flat sheet and custom-cut inserts absorb distributed impact forces across product surfaces. E-commerce fulfillment channels in cost-sensitive consumer goods lanes see displacement pressure from molded pulp substitutes.
- Surface Guarding:Adhesive-backed foam strips prevent abrasion during stacked storage and transit.
- Pallet Stabilization:Edge rails and corner posts secure unitized loads against strap cutting and fork impact.
- Impact Absorption:Thicker profile sections engineered for drop-test certification in heavy machinery logistics.
Corner protection captures premium positioning. Package cushioning faces the steepest substitution threat.
Distribution Channel:
Channel structure segmentation reveals how procurement consolidation among large OEMs is collapsing traditional intermediary economics.
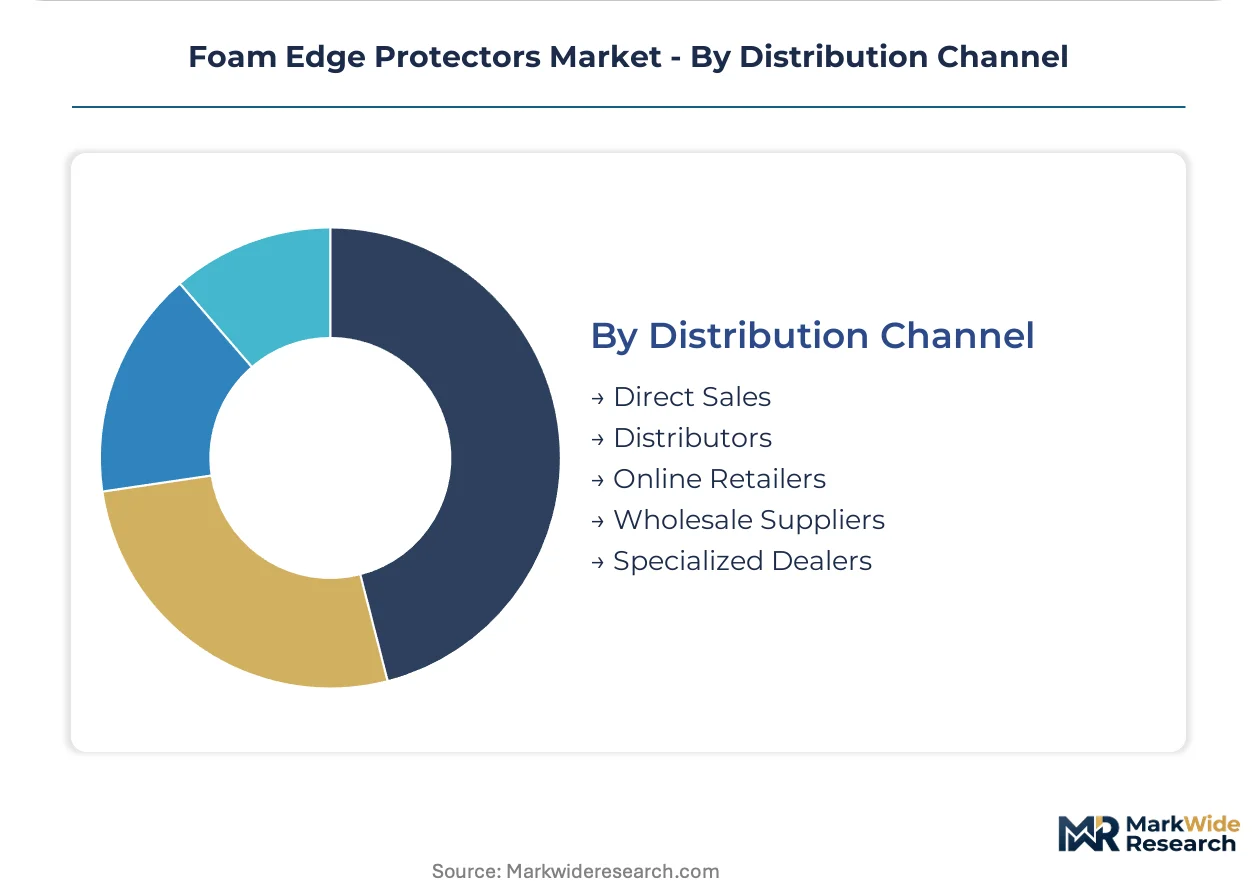
- Direct Sales:Converter-to-manufacturer relationships bypass wholesale markups through integrated supplier portals. Michigan and Ohio automotive manufacturing clusters concentrate this pattern most visibly under single-vendor protective packaging agreements.
- Distributors:Regional packaging supply houses maintain inventory breadth for mid-tier customers lacking volume for direct mill contracts.
- Online Retailers:Digital procurement platforms serve small-batch custom molders without indexed supply contracts.
- Wholesale Suppliers:Traditional intermediaries face margin compression as large automotive and aerospace OEMs consolidate sourcing.
- Specialized Dealers:Niche providers focus on certified protective packaging for aerospace and medical device segments.
Direct sales is gaining share fastest. Distributors retain relevance in fragmented customer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing clusters drive foam edge protector demand unevenly across major economies. Germany's automotive parts shipments and China's electronics exports anchor volume consumption, while regulatory divergence between REACH-compliant Europe and EPA-governed North America fragments formulation strategies.
Germany
Powertrain component exports to global automotive networks sustain specialized closed-cell polyethylene consumption. The EU Packaging and Packaging Waste Regulation tightens recyclability mandates for protective materials, forcing converters toward mono-material formulations. Stuttgart and Wolfsburg manufacturing corridors concentrate precision-machined foam geometries for tier-one supplier packaging.
United States
EPA Clean Air Act standards regulate foam manufacturing emissions, elevating compliance costs for domestic extrusion operations. Michigan and Ohio automotive clusters consolidate protective packaging sourcing through direct-manufacturer procurement portals that bypass traditional distributors. Semiconductor logistics in Arizona and Texas drive specification of conformable polyurethane grades for chip shipment protection.
China
Electronics export manufacturing in the Yangtze and Pearl River Delta regions absorbs high volumes of corner-protection foam for display panel and consumer device shipments. MIIT industrial standards for packaging materials increasingly reference recyclability benchmarks that align with EU export requirements. Shenzhen and Suzhou logistics hubs specialize in repeated-use closed-cell cycles for cross-border e-commerce fulfillment.
India
PLI scheme incentives for semiconductor and display fabrication build domestic demand for precision protective packaging currently met by imports. BIS certification requirements for industrial packaging materials create compliance barriers for non-domestic converters. Karnataka and Tamil Nadu electronics manufacturing clusters attract foam edge protector suppliers establishing local extrusion capacity.
Netherlands
Rotterdam port logistics and Amsterdam distribution corridors position the country as a protective packaging trade gateway for northwest European manufacturing. ECHA REACH compliance deadlines for 2026 force foam converters toward water-blown expansion systems ahead of chemical blowing agent restrictions. Eindhoven's high-tech systems sector drives specification of ultra-conformable polyurethane edge protectors for precision equipment transit.
Foam Edge Protectors Market Competitive Landscape
On the supply side, the industry is moderately consolidated around integrated material converters and specialized protective packaging fabricators. Large-scale foam extrusion operations compete against mid-tier custom molders on tooling flexibility and batch economics. Two strategic archetypes dominate: multinational chemical-material conglomerates with captive foam divisions, and independent packaging specialists with deep geometry customization capabilities. Capacity expansion and direct-to-manufacturer distribution channel development represent the dominant competitive moves.
Within the multinational-material tier, Sealed Air Corporation anchors North American and European manufacturing scale through proprietary extrusion infrastructure. Storopack Hans Reichenecker GmbH exemplifies the European specialist archetype, occupying a position in customized protective geometries for industrial machinery applications. Pregis LLC represents the distribution-innovation vector, controlling direct-to-manufacturer channels that compress wholesale intermediaries from procurement flows.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Storopack Hans Reichenecker GmbH |
| Pregis LLC |
| Polartech |
| Springpack |
| Nomaco |
| Nefab Group |
| FP International |
| GMA Systems Ltd |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese extrusion plants is compressing export pricing for standard-density polyethylene grades while forcing European converters toward specialized polyurethane formulations. This utilization asymmetry rewards suppliers with indexed petrochemical contracts and punishes small-batch custom molders exposed to spot ethylene markets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that secure volume commitments against volatile feedstock indices. Price differentiation hinges on Shore A hardness certification tiers and geographic delivery cost differentials between Rotterdam port logistics and inland European manufacturing clusters. Cost compression in commodity polyethylene runs through paper-based substitute availability in e-commerce fulfillment channels. Third-party logistics providers exhibit highest price sensitivity due to thin margin structures, while semiconductor assemblers accept premium positioning for micro-fracture protection compliance.
Supply Chain Analysis
Extended payment terms from German automotive tier suppliers are straining converter working capital and accelerating consolidation toward integrated material conglomerates. Feedstock supply concentrates in Saudi Arabia, South Korea, and the US Gulf Coast, with ethylene and propylene derivatives feeding extrusion operations across three continents. Raw material sourcing draws from naphtha cracking, shale gas liquids, and bio-based algae feedstocks. Single-source vulnerability in closed-cell molding die fabrication elevates risk exposure. Distribution runs through direct-to-manufacturer procurement portals that displace traditional wholesale intermediaries in Michigan and Ohio manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The foam edge protector market is exiting a cyclical trough as semiconductor capital expenditure recovery and automotive export packaging restocking converge. Electronics manufacturing reshoring under India PLI scheme incentives provides the cyclical justification.
For Market Incumbents: Entrench position through backward integration into captive polyethylene resin production and multi-cavity aluminum die ownership. REACH chemical blowing agent restrictions threaten mid-tier European competitors lacking reformulation capacity. Certification investment in water-blown expansion systems secures first-mover positioning ahead of 2026 compliance deadlines.
For New Entrants and Emerging Players: Karnataka and Tamil Nadu electronics manufacturing clusters represent the most penetrable entry point given import-dependent domestic supply and BIS certification barriers for non-resident converters. Bio-based foam convergence using mycelium-derived feedstocks opens premium positioning with carbon-conscious brand owners. Direct sales channel development through integrated supplier portals bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across closed-cell density gradient molding as multi-cavity aluminum die costs reach $400,000 per configuration. Long-term viability over a 5-10 year window favors converters with scalable extrusion infrastructure and established direct-manufacturer relationships. Acquisition target archetype: regional specialists with proprietary geometry customization capabilities and REACH-compliant formulation libraries. Monitor extended producer responsibility scheme implementation timelines as inflection indicator for disposal cost liability shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive ethylene supply insulates margin compression from petrochemical volatility in European markets. |
| Water-Blown Expansion System Deployment | REACH compliance ahead of 2026 deadlines secures electronics packaging certification requirements. |
| Direct-to-Manufacturer Channel Development | Integrated supplier portals in Michigan and Ohio bypass wholesale markups and lock automotive OEM relationships. |
| Bio-Based Feedstock Integration | Mycelium and algae-derived formulations open premium positioning with carbon-conscious brand owners. |
| Multi-Cavity Aluminum Die Investment | Closed-cell density gradient molding capability captures precision tolerance specifications from semiconductor assemblers. |
Research Methodology
The analysis maps polyethylene extrusion, polyurethane molding, polystyrene expansion, and bio-based foam convergence sub-sectors, each validated through foam converter operations managers, automotive tier supplier procurement leads, electronics assembler packaging engineers, and petrochemical feedstock traders. Primary interview findings triangulate against customs trade data, EPA Clean Air Act enforcement records, ECHA REACH substance notifications, and SEC filings from integrated material conglomerates. Bottom-up volume estimates from named manufacturing clusters reconcile with top-down demand projections across end-use industries.
Forecast assumptions hold fixed the current regulatory trajectory for EU Packaging and Packaging Waste Regulation recyclability mandates and EPA emission standards, while varying semiconductor capital expenditure cycles and automotive export volume scenarios across the projection horizon. Segmentation dimensions modeled include material chemistry grade, Shore A hardness tier, end-use precision requirement, and distribution channel structure. CAGRs derive from fitted growth curves applied to normalized baseline consumption, with inputs from ethylene price index movements and electronics manufacturing location shifts.
Practitioners should monitor REACH substance notification deadlines and extended producer responsibility scheme implementation for early signals of formulation cost inflection. Forecasts reflect assumptions of continued petrochemical feedstock volatility and paper-based substitute displacement pressure in non-fragile consumer goods lanes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Tamper Proof Packaging Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Global Packaging Inserts and Cushions Market
Protective Packaging
Corrugated Bubble Wrap Market
Protective Packaging
Insulated Shipping Boxes Market
Protective Packaging
Padded Dividers Market
Protective Packaging
Static Shielding Bags Market
Protective Packaging
Middle East and Africa Protective Packaging Market
Protective Packaging
Adhesive Bubble Wrap Market
Protective Packaging
Insulated Packaging Market
Protective Packaging
Packaging and Protective Packaging Market
Protective Packaging
Insulated Shippers Market
Protective Packaging
Grease Resistant Packaging Market
Protective Packaging
Fiber Cushioning Market
Protective Packaging
Void Fill Pillows Market
Protective Packaging
Secondary Containment Trays Market