
 Sweet Biscuits Market | 2026-2036
Sweet Biscuits Market Size, Share, and Industry Trends Forecast 2026-2036
Sweet Biscuits Market Intelligence
The European Union's regulation on acrylamide mitigation measures is repositioning the cost-of-entry calculus for biscuit manufacturers. This environment favors large-scale producers like Mondelez International, which leverages its extensive R&D to reformulate products across global brands. In contrast, Britannia Industries sustains its leadership in the Indian market through localized product innovation and deep distribution networks. PepsiCo competes by integrating its sweet biscuit offerings within a broader snack portfolio.
Sweet biscuits are flour-based baked products characterized by high sugar and fat content, with a moisture level below 5% ensuring shelf stability. Their primary commercial purpose is serving as a convenient, ready-to-eat snack. Chocolate chip varieties lead the product type segment, while oatmeal raisin gains traction due to health perceptions. Although retail consumers are the primary customer type, the food service channel shows significant growth, particularly for products in wrapper packaging.
Regulatory oversight from bodies like the US FDA, the European Food Safety Authority (EFSA), and the FSSAI in India dictates permissible ingredients and nutritional labeling. These standards directly influence formulation strategies and marketing claims, particularly concerning sugar content and allergens. Stakeholder success will depend on effectively balancing consumer demand for indulgent flavors with evolving health and wellness considerations.
Market Dynamics
The central tension shaping the sweet biscuits market is the collision between stringent government-led health initiatives aimed at reducing sugar and fat consumption and the persistent consumer demand for indulgent, convenient snack products, a conflict that defines all innovation.
Growth Catalysts
- Indian Urbanization:Rapid urbanization and rising disposable incomes in India are altering traditional eating patterns, creating substantial demand for convenient, packaged snacks like biscuits as meal replacements or on-the-go options.
- Food Service Channel Expansion:The hotel, restaurant, and catering (HoReCa) sector's preference for portion-controlled, individually wrapped biscuits for coffee service, amenities, and catering is creating a significant B2B growth vector.
- Health-Perception Ingredients:The incorporation of ingredients like oats, whole grains, and seeds creates a "health halo" effect, allowing brands to appeal to wellness-conscious consumers without fundamentally altering the indulgent nature of the product.
Market Restraints
- Commodity Price Volatility:Manufacturer margins are continuously exposed to price fluctuations in essential raw materials, including sugar, wheat flour, and cocoa, making cost management and pricing strategies exceptionally challenging.
- Acrylamide Regulation Compliance:Mandates from bodies like the European Food Safety Authority (EFSA) on mitigating acrylamide in baked goods impose significant R&D and process adjustment costs, creating a barrier for smaller producers.
- Healthier Snack Substitution:The category faces intense competition from alternative snacks perceived as healthier, such as fruit bars, yogurt, protein snacks, and nuts, which are eroding biscuit consumption occasions among health-focused demographics.
Strategic Opportunities
- Reformulation for Nutritional Labeling:Upcoming front-of-pack labeling regulations, particularly in the European Union, present an opportunity for proactive brands to reformulate products to achieve better nutritional scores, turning compliance into a competitive advantage.
- Direct-to-Consumer (DTC) Channels:E-commerce platforms and brand-owned websites offer a direct route to market for niche, premium, and artisanal biscuit makers, bypassing the competitive constraints of traditional retail shelf space.
- Plant-Based and Free-From Segments:There is a clear market opening for biscuits formulated with plant-based ingredients or tailored to "free-from" dietary needs, such as gluten-free or allergen-free, to serve a growing consumer base with specific health requirements.
Industry Challenges
- Sensory Profile Preservation:A primary operational challenge is reformulating recipes to reduce sugar, salt, and fat content in line with health guidelines without negatively impacting the taste, texture, and mouthfeel that define consumer preference.
- Navigating Global Regulatory Patchwork:Manufacturers face significant operational complexity and cost in ensuring products comply with the diverse and evolving ingredient, labeling, and food safety standards set by authorities like the US FDA, EFSA, and FSSAI.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweet Biscuits Market |
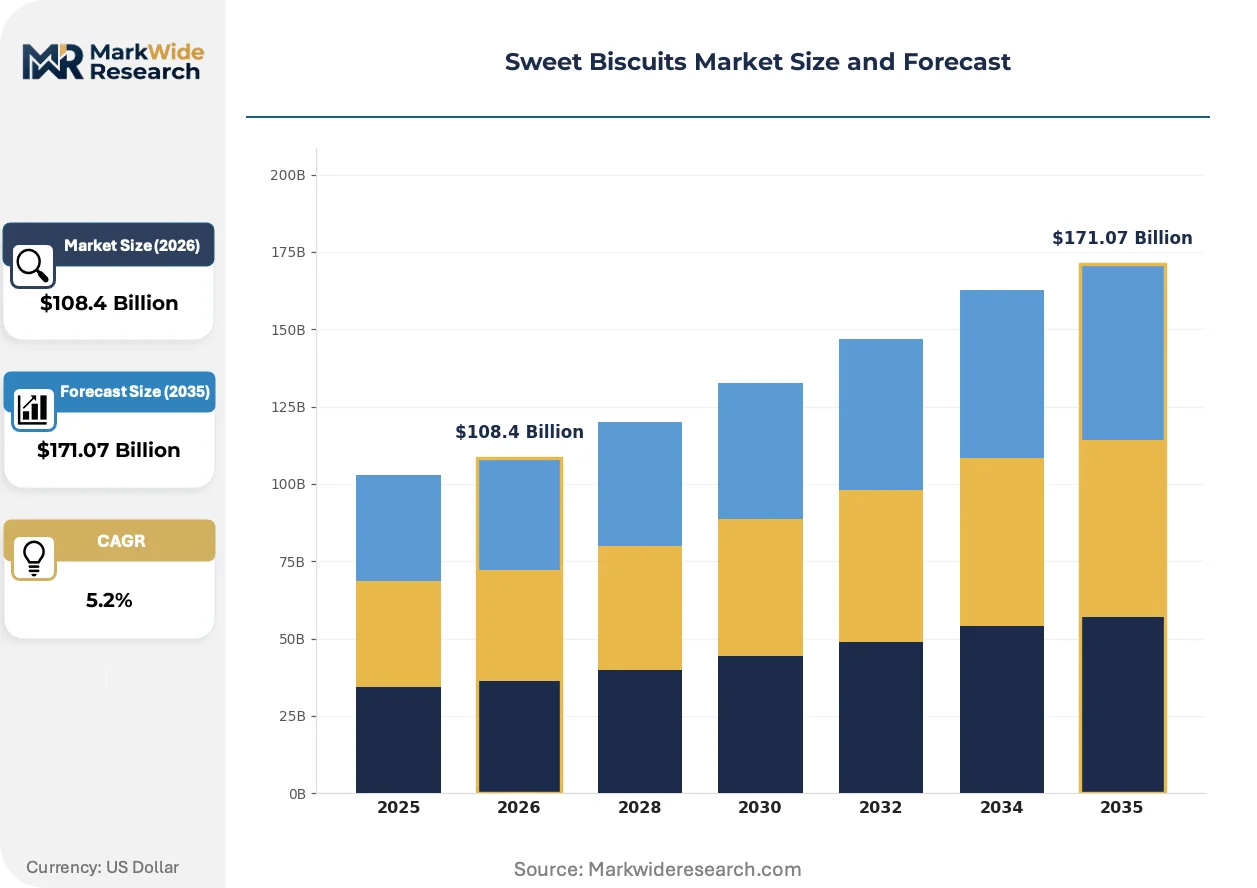
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $171.07 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Chip, Oatmeal Raisin, Peanut Butter, Shortbread Packaging Type: Box, Bag, Tin, Wrapper Customer Type: Retail Consumers, Food Service, Bakeries, Wholesalers Price Tier: Premium, Mid-Range, Economy, Value |
| Companies Covered | Mondelez International, Nestlé, Ferrero Group, PepsiCo, Britannia Industries, ITC Limited, Lotus Bakeries, Kellogg Company, Campbell Soup Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweet Biscuits Market Strategic Shifts & Innovations
Product development is increasingly defined by a dual focus on health-conscious reformulation and sensory indulgence. This balance is being achieved through advancements in ingredient science and processing technology, driven by both regulatory pressure and evolving consumer expectations for healthier snacks.
Advanced food processing technology, including AI-powered recipe modeling and precision baking systems, provides manufacturers with tools to manage complex formulations. Major producers are rapidly adopting these systems to accelerate R&D cycles for reduced-sugar and reduced-fat products. This processing capability is converging with ingredient science, enabling the creation of biscuits that meet new health standards without sacrificing traditional taste and texture.
The European Commission’s push for mandatory front-of-pack (FOP) nutritional labeling, such as the Nutri-Score system, is a significant regulatory driver. This policy forces a public-facing nutritional evaluation, compelling manufacturers to improve their products' health profiles to avoid poor ratings. Product categories with high sugar and fat content, like chocolate-coated and cream-filled biscuits, are the most exposed and are undergoing urgent reformulation.
A notable behavioral change is the rise of "snackification," where consumers substitute traditional meals with multiple smaller snacks. This trend disrupts sales of family-sized packs in supermarkets, favoring single-serve and portion-controlled formats available in convenience stores, cafes, and vending machines. This consumption pattern is most pronounced among urban consumers in North America and Western Europe, reshaping packaging and distribution strategies.
Sweet Biscuits Market Segmentation
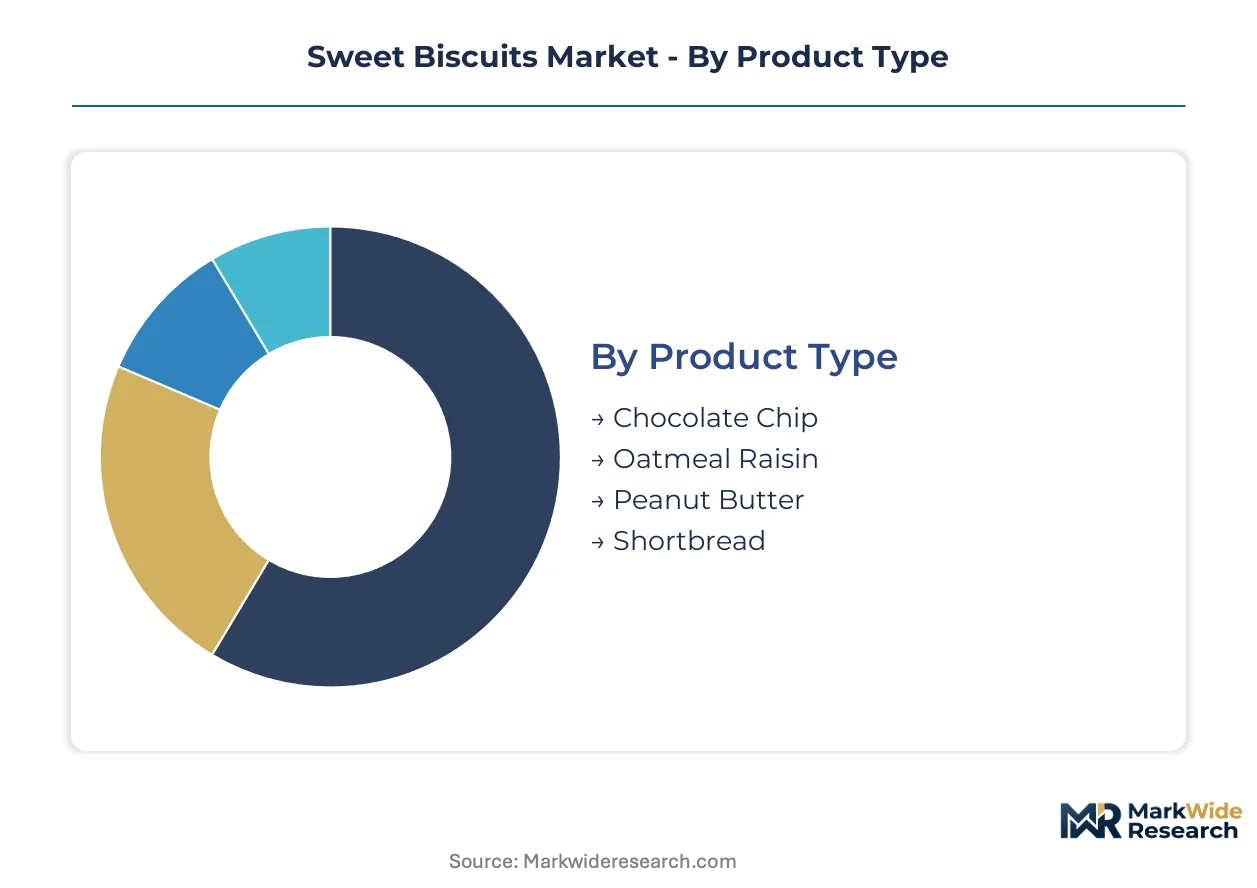
The sweet biscuits market segmentations provide a granular view of product evolution and consumer preferences, enabling manufacturers to tailor offerings for specific niches. Understanding these distinct categories helps stakeholders identify high-growth areas and optimize product development, packaging, and distribution strategies for maximum market penetration.
Product Type:
Product formulation defines the core offering, with variations in ingredients and processing driving distinct consumer appeal across the sweet biscuits market.
- Chocolate Chip:These biscuits feature a flour-based dough embedded with chocolate pieces, often characterized by a chewy or crisp texture depending on the recipe. Demand for chocolate chip varieties remains robust in North America and Western Europe, driven by their classic indulgent appeal and versatility as a snack.
- Oatmeal Raisin:Comprising oats, flour, and raisins, these biscuits often contain spices like cinnamon, offering a chewier texture and a perception of healthier indulgence. This segment gains traction in markets like Germany and the UK as consumers increasingly seek snacks with added fiber and natural fruit content.
- Peanut Butter:These biscuits incorporate peanut butter into the dough, providing a distinct nutty flavor and often a softer, crumbly texture.
- Shortbread:A traditional butter-rich biscuit with a high fat content, delivering a crumbly, melt-in-the-mouth texture and a simple, sweet flavor profile.
Mature deployment sits with Chocolate Chip varieties. Newer deployment is concentrated in Oatmeal Raisin, reflecting evolving health perceptions.
Packaging Type:
Packaging innovation in sweet biscuits focuses on convenience, shelf-life extension, and consumer appeal, directly influencing purchase decisions and consumption occasions.
- Wrapper:Individual or small-pack flexible packaging, often made from plastic films or metallized foils, designed for single servings and on-the-go consumption. The wrapper segment is experiencing the steepest expansion trajectory, particularly within the food service channel and vending machine sales across urban centers in India and China.
- Box:Rigid or semi-rigid cardboard packaging, frequently used for multi-pack or family-size assortments, providing product protection and branding space. Box packaging dominates retail shelf space for household consumption, especially in established markets like the United States and France.
- Bag:Flexible packaging, typically made from plastic or foil, often used for larger quantities of biscuits or irregular shapes, offering cost-effectiveness.
- Tin:Durable metal containers, often decorative, used for premium or gift-oriented biscuit assortments, providing extended shelf life and reusability.
The wrapper segment is expanding most quickly in commercial applications. Box packaging maintains the largest volume share in household purchases.
Customer Type:
The sweet biscuits market serves a diverse range of customers, each with unique purchasing patterns, volume requirements, and product format preferences.
- Retail Consumers:Individual shoppers purchasing biscuits for household consumption through supermarkets, convenience stores, and online platforms. Retail consumers constitute the primary revenue source for sweet biscuits globally, with purchasing decisions influenced by brand recognition and promotional activities in markets like Japan and Brazil.
- Food Service:Businesses in the hotel, restaurant, and catering (HoReCa) sector, purchasing biscuits for inclusion in meals, coffee service, or amenities. The food service channel demonstrates significant growth, driven by demand for individually wrapped, portion-controlled items for cafes and quick-service restaurants in the United Kingdom and Australia.
- Bakeries:Commercial bakeries that may use sweet biscuits as ingredients in other desserts or sell them as part of their prepared offerings.
- Wholesalers:Intermediary businesses that purchase biscuits in bulk from manufacturers for distribution to smaller retailers or institutions.
Retail Consumers hold the largest market influence. Food Service accounts for a rapidly growing share of commercial sales.
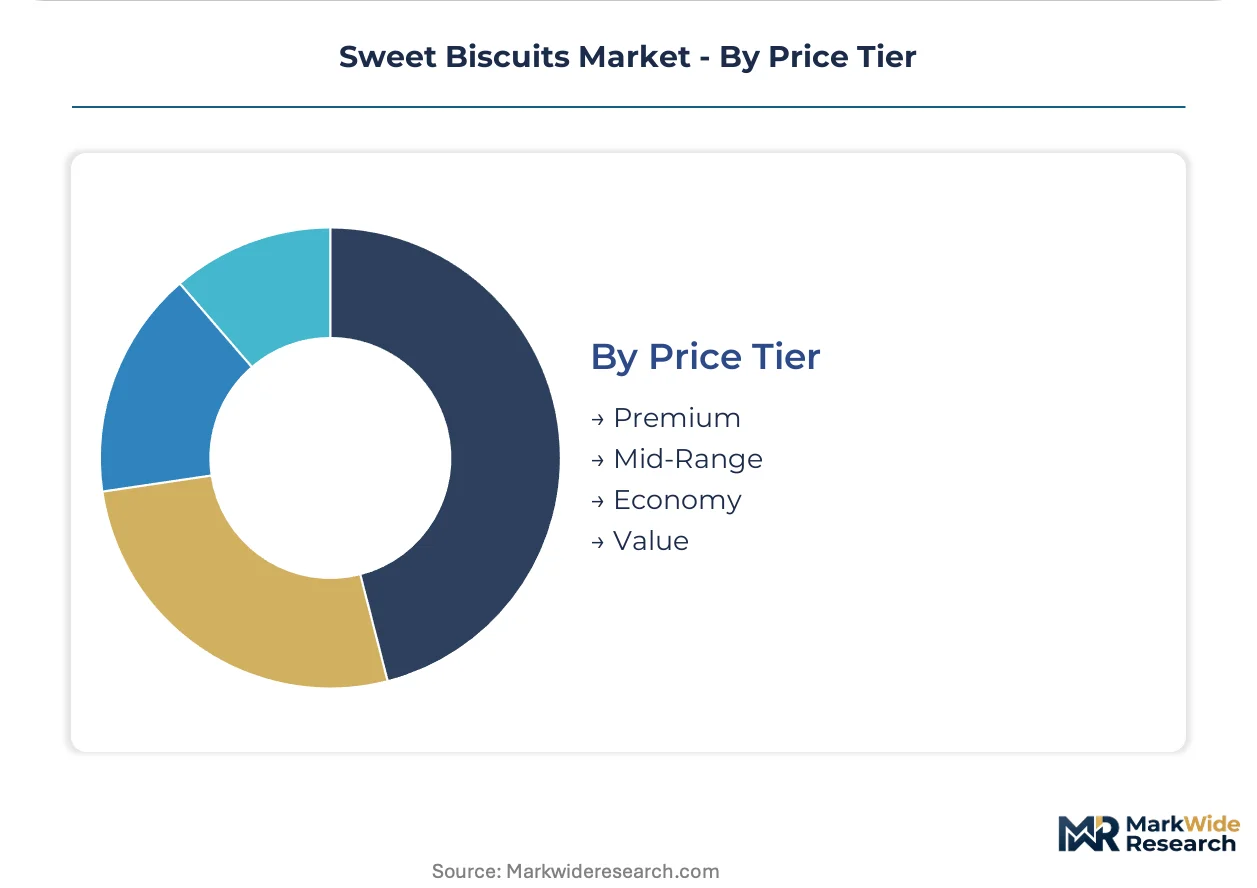
Price Tier:
The pricing strategy for sweet biscuits reflects ingredient quality, brand positioning, and target consumer demographics, influencing market accessibility and perceived value.
- Premium:Biscuits characterized by high-quality ingredients, artisanal production methods, unique flavors, and sophisticated packaging, commanding higher prices. The premium segment appeals to discerning consumers in markets like Switzerland and Canada, seeking unique taste experiences and often niche dietary attributes.
- Economy:Mass-market biscuits focused on affordability and broad accessibility, often sold in larger packs with simpler formulations and less elaborate packaging. The economy segment underpins volume sales in price-sensitive markets such as Indonesia and Egypt, catering to everyday consumption needs for a large consumer base.
- Mid-Range:Biscuits that balance quality and affordability, offering a good value proposition for a wide consumer base.
- Value:A sub-segment of economy, often private label or store brands, emphasizing the lowest possible price point.
Premium biscuits differentiate through ingredient quality. Economy biscuits compete primarily on price and accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's regulatory landscape, particularly regarding acrylamide mitigation and front-of-pack nutritional labeling, acts as a significant zone of influence, compelling manufacturers to concentrate reformulation efforts. This concentrated regulatory pressure impacts product development across the bloc. Meanwhile, rapid urbanization in India creates a distinct zone of concentrated demand for convenient snack formats.
India
Rapid urbanization and rising disposable incomes in India drive substantial demand for convenient, packaged snacks, altering traditional eating patterns. The FSSAI dictates permissible ingredients and nutritional labeling, influencing local formulation strategies. Mumbai's growing middle class demonstrates a strong preference for on-the-go biscuit formats.
Germany
Consumers in Germany increasingly seek snacks with added fiber and natural fruit content, leading to traction for healthier perceived varieties like oatmeal raisin. The European Food Safety Authority (EFSA) mandates acrylamide mitigation, imposing R&D costs on manufacturers. Berlin's food tech sector actively develops advanced baking systems for reduced-sugar biscuit formulations.
United States
The United States market sustains robust demand for classic indulgent chocolate chip varieties, alongside household consumption of biscuits in box packaging. The US FDA dictates permissible ingredients and nutritional labeling, directly influencing product claims. Chicago's snack food manufacturers continuously adapt formulations to meet evolving consumer preferences for both indulgence and perceived health.
China
China's urban centers and expanding food service channel drive significant growth for individually wrapped biscuits, particularly for vending machine sales. National food safety standards influence ingredient sourcing and product quality across the industry. Shanghai's rapidly expanding HoReCa sector drives demand for portion-controlled biscuit options for hotels and cafes.
Sweet Biscuits Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a tiered market structure within the sweet biscuits sector. Large-scale producers leverage extensive R&D capabilities, while smaller, niche players target specific dietary needs. Dominant competitive moves include strategic product reformulation and the development of robust distribution networks.
Mondelez International, a major global producer, exemplifies the archetype of a large-scale manufacturer leveraging extensive R&D to reformulate products across global brands. Britannia Industries, based in India, occupies a position as a localized leader, driving market penetration through targeted product innovation and deep distribution networks. PepsiCo represents another strategic approach, integrating its sweet biscuit offerings within a broader, diversified snack portfolio.
| Leading Market Players |
|---|
| Mondelez International |
| Nestlé |
| Ferrero Group |
| PepsiCo |
| Britannia Industries |
| ITC Limited |
| Lotus Bakeries |
| Kellogg Company |
| Campbell Soup Company |
| Others |
Cost & Logistics Intelligence
Advanced food processing technology, specifically AI-powered recipe modeling, reshapes cost economics by enabling complex reformulations. This shift simultaneously concentrates supply power among large manufacturers capable of such R&D investments.
Pricing Analysis
Immediate commodity price fluctuations, influenced by short procurement lead times, drive pricing volatility across the sweet biscuits market. This market exhibits a three-tier pricing structure across premium, mid-range, and economy levels. Ingredient quality and brand recognition differentiate premium offerings. Pricing softness stems from intense competition among mass-market brands and raw material cost volatility. Economy segment consumers are highly price-sensitive, while premium segment consumers prioritize unique taste experiences.
Supply Chain Analysis
Logistics and freight costs significantly influence the sweet biscuits supply chain, particularly for bulk raw materials. Production is concentrated in regions with high consumption, such as the United States and the European Union, alongside emerging hubs like India. The industry relies heavily on global supplies of sugar, wheat flour, and cocoa. Commodity price volatility represents a continuous structural risk for manufacturers. Distribution runs through traditional retail channels for household consumption and a rapidly expanding food service channel for commercial sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sweet biscuits market operates as a supply-constrained story, primarily due to the complex reformulation requirements driven by nutritional labeling. This R&D capacity bottleneck for reduced-sugar and reduced-fat products props up pricing for compliant, yet indulgent, offerings.
For Market Incumbents: To counter the threat of stringent acrylamide regulation compliance and competition from healthier snack alternatives, large-scale producers must leverage extensive R&D capabilities. They should prioritize continuous product reformulation to meet evolving nutritional standards without compromising sensory profiles. Strengthening deep distribution networks, particularly in high-growth markets like India, also ensures sustained market penetration and channel control. For New Entrants and Emerging Players: E-commerce platforms offer a direct route to market for niche, premium, and artisanal biscuit makers. New entrants should target the plant-based and "free-from" segments, which represent significant white-space opportunities. Focusing on specific dietary requirements, such as gluten-free or allergen-free formulations, provides a clear go-to-market angle to serve wellness-conscious consumers. For Investors and Strategic Acquirers: Exit pathways concentrate in large diversified conglomerates seeking to expand their health-aligned snack portfolios. The sweet biscuits market presents long-term viability over a 5-10 year window, driven by persistent snackification trends. Acquisition targets should be niche specialists demonstrating success in plant-based or free-from segments, or those with strong localized distribution networks. Widespread consumer acceptance of reduced-sugar products maintaining sensory appeal serves as a critical inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation for Nutritional Labeling | Enables brands to achieve better Nutri-Score ratings, turning compliance into a competitive advantage in the European Union. |
| Direct-to-Consumer (DTC) Channel Expansion | Bypasses traditional retail constraints, offering niche and premium brands direct access to consumers in North America. |
| Plant-Based Product Line Development | Caters to growing consumer demand for specific dietary needs, expanding market reach beyond traditional offerings. |
| Advanced Baking Systems Adoption | Accelerates R&D cycles for reduced-sugar products, allowing major producers to meet health standards without sacrificing taste. |
| Localized Distribution Network Strengthening | Enhances market penetration and responsiveness to regional consumer preferences, particularly for Britannia Industries in India. |
Research Approach
US FDA guidelines, European Food Safety Authority (EFSA) reports, and FSSAI regulations formed the secondary backbone for this analysis. The study combined primary interviews with R&D directors, procurement leads, brand managers, and food service channel managers across multiple geographies. This approach allowed for bottom-up market sizing and top-down validation of quantitative data.
A bottom-up approach to market sizing was complemented by top-down validation across the analysis window. Product type, packaging type, customer type, and price tier were key segmentation dimensions modeled. Compound Annual Growth Rates were derived from historical trends and projected demand drivers. Urbanization rates in emerging markets and evolving front-of-pack labeling mandates served as critical forecast inputs.
Caveats apply where unforeseen shifts in commodity prices or new health regulations could materially shift the outlook. Forecasts reflect documented assumptions regarding market dynamics and competitive responses. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
South America Ice Cream Market
Bakery Products
Bakery Flavors Market
Bakery Products
Pastry Premixes Market
Bakery Products
Southeast Asia Bakery Products Market
Bakery Products
Ezekiel Bread Market
Bakery Products
Packaged Bread Market
Bakery Products
Low-Gluten Emmer and Einkorn Flour Blends Market
Bakery Products
Europe Sourdough Market
Bakery Products
Instant Cake Emulsifier Market
Bakery Products
Specula Market
Bakery Products
Baked Foods Market
Bakery Products
Dough Conveyor Market
Bakery Products
Oman Frozen Bakery Products Market
Bakery Products
Malted Rye Flour Market
Bakery Products
Pie Shells Market
Bakery Products
Asia-Pacific Baked Food and Cereals Market