
 Packaged Bread Market | 2026-2036
Packaged Bread Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Bread Market Outlook
North American industrial bakeries is expanding output to serve sustained demand for extended-shelf-life packaged loaves. Grupo Bimbo leverages its vertically integrated flour-to-retail network across Mexico and the United States to control cost positions. Flowers Foods sustains regional dominance in the southeastern United States through dense direct-store-delivery infrastructure. Associated British Foods plc anchors European supply through specialized frozen and ambient bread platforms.
Packaged bread denotes industrially manufactured, pre-sliced or whole-loaf bread products sealed in protective packaging, typically containing preservatives, emulsifiers, and humectants to achieve shelf lives of five to fourteen days under ambient conditions; the category serves retail consumers and foodservice operators requiring consistent quality, portion control, and minimal preparation time. White bread retains volume leadership in emerging markets where price sensitivity dominates purchasing decisions, yet whole wheat and multigrain bread segments capture expanding margin pools as health-positioned formulations command shelf-space premiums. Gluten-free bread occupies a narrow but defensible niche where specialized ingredient sourcing and dedicated production lines create barriers to commoditization.
The FDA governs ingredient labeling and nutritional claims for packaged bread sold in the United States, while the EPA oversees emissions standards at large-scale baking facilities; in Europe, EFSA evaluates health claims and the EU Green Deal pressures producers toward lower-carbon production methods. India's FSSAI mandates iron and folic acid fortification in mass-market bread, redirecting R&D spending toward compliant premix integration. Stakeholders must monitor evolving fortification rules and carbon-accounting requirements as these frameworks increasingly determine market access and product positioning.
Market Dynamics
India's FSSAI fortification mandates are compressing product development cycles across the packaged bread sector, forcing reformulation investments and redirecting R&D budgets toward compliant premix integration before competitors can capture shelf-space premiums.
Growth Catalysts
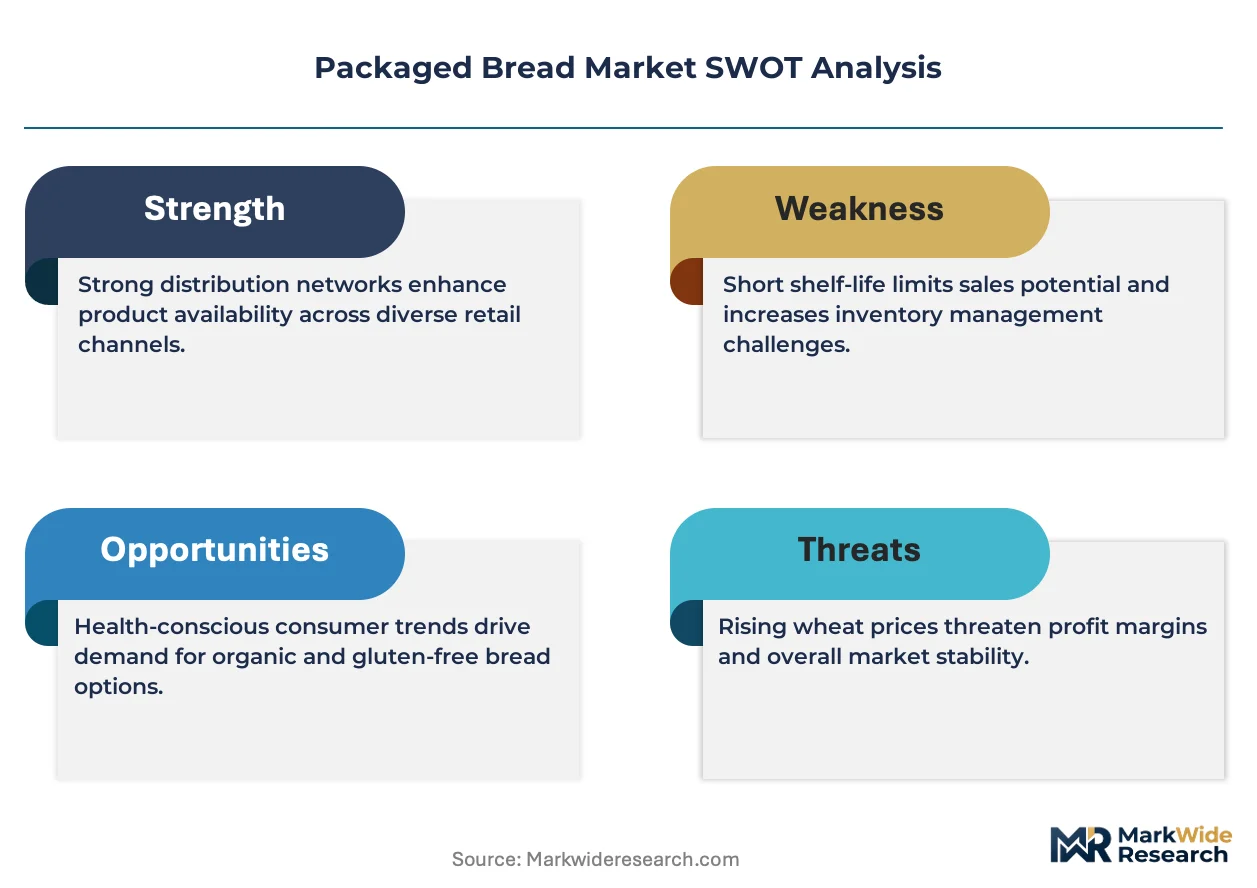
- Urban Convenience Demand:Households in India's metropolitan corridors and tier-two cities drive adoption of sliced and pre-packaged formats as modern retail penetration deepens fastest in these corridors.
- FSSAI Fortification Mandates:India's regulatory requirement for iron and folic acid fortification in mass-market bread creates compliant product differentiation and redirects competitor R&D spending.
- Whole Wheat Formulation Advances:Milling technology improvements enable multigrain and whole wheat variants to capture expanding margin pools through health-positioned formulations commanding shelf-space premiums.
Market Restraints
- Wheat Price Volatility:Input cost fluctuations in global grain markets compress margin structures for producers lacking captive flour milling capacity or long-term supply contracts.
- Extended Shelf-Life Chemistry Limits:Technical constraints around clean-label preservation create tension between consumer preference for minimal ingredients and retail requirements for seven-to-fourteen-day ambient stability.
- Gluten-Free Substitution Threat:Specialized alternative grain breads capture niche but defensible demand pools where dedicated production lines and ingredient sourcing create barriers to commoditization.
Strategic Opportunities
- Tier-Two City Distribution Expansion:Underpenetrated urban corridors in India outside the four major metros present white-space growth as modern retail formats expand into these catchments.
- EU Green Deal Carbon Positioning:Lower-carbon production methods pressured by European regulatory frameworks create export positioning advantages for producers investing in energy-efficient baking infrastructure.
- Foodservice Channel Direct Supply:Bypassing traditional retail distribution to serve institutional buyers requiring consistent quality and portion control opens volume contracts with predictable offtake.
Industry Challenges
- Premix Integration Technical Gap:Fortification compliance requires specialized formulation expertise that strains existing product development teams and extends certification timelines.
- Legacy Equipment Retrofit Costs:Capex intensity for clean-label production line upgrades pressures mid-scale bakeries unable to amortize investments across sufficient volume bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Bread Market |
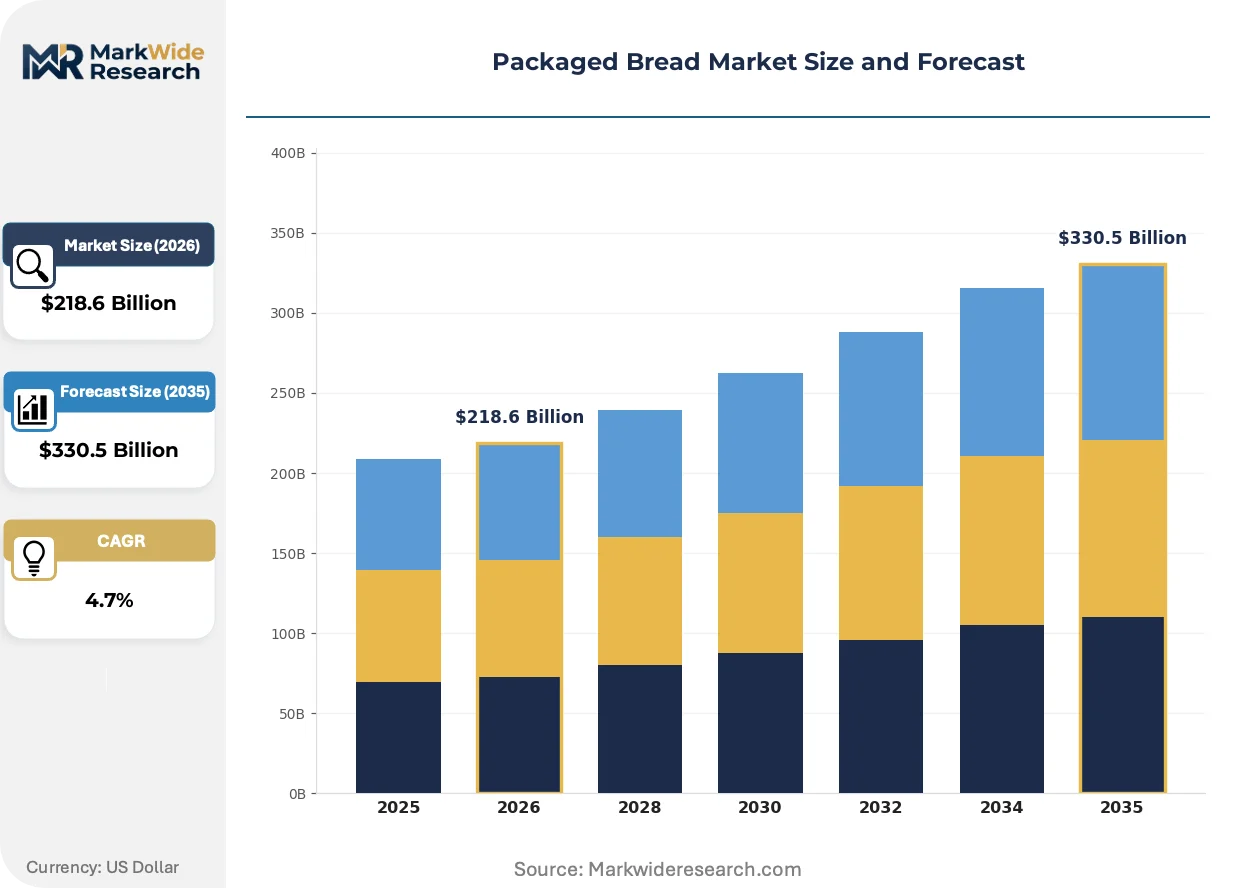
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $330.5 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Bread, Whole Wheat Bread, Multigrain Bread, Gluten-Free Bread Packaging Type: Bags, Loaves, Buns, Slices Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores End User: Households, Cafes, Restaurants, Bakeries |
| Companies Covered | Mondelez International, Inc., General Mills, Inc., Grupo Bimbo, The Kraft Heinz Company, Aryzta AG, Flowers Foods, Inc., Yamazaki Baking Co., Ltd., Warburtons Ltd., Associated British Foods plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Bread Market Strategic Shifts
Active reformulation across the packaged bread sector centers on three vectors: processing technology enabling cleaner labels, regulatory pressure accelerating fortification compliance, and urban consumption patterns favoring convenience formats over traditional loose bread.
High-pressure processing and modified-atmosphere packaging is electrifying shelf-life extension without synthetic preservatives. Urban Indian households adopting these formats shift purchasing from loose bread vendors to modern retail. This technology is compressing the competitive window for traditional bakeries unable to invest in barrier packaging infrastructure.
The EU Green Deal pressures producers toward lower-carbon production methods across European baking facilities. Industrial heat recovery systems and renewable energy integration now determine market access for export-oriented producers. Whole wheat and multigrain segments respond fastest, leveraging health positioning to justify carbon-accounting transparency investments.
Direct-store-delivery networks are displacing traditional wholesale distribution in dense urban catchments. Southeastern United States retail patterns demonstrate this shift, with frequent replenishment cycles replacing bulk warehouse deliveries. Foodservice operators in metropolitan India mirror this behavior, demanding just-in-time supply agreements that minimize inventory holding.
Packaged Bread Market Segmentation
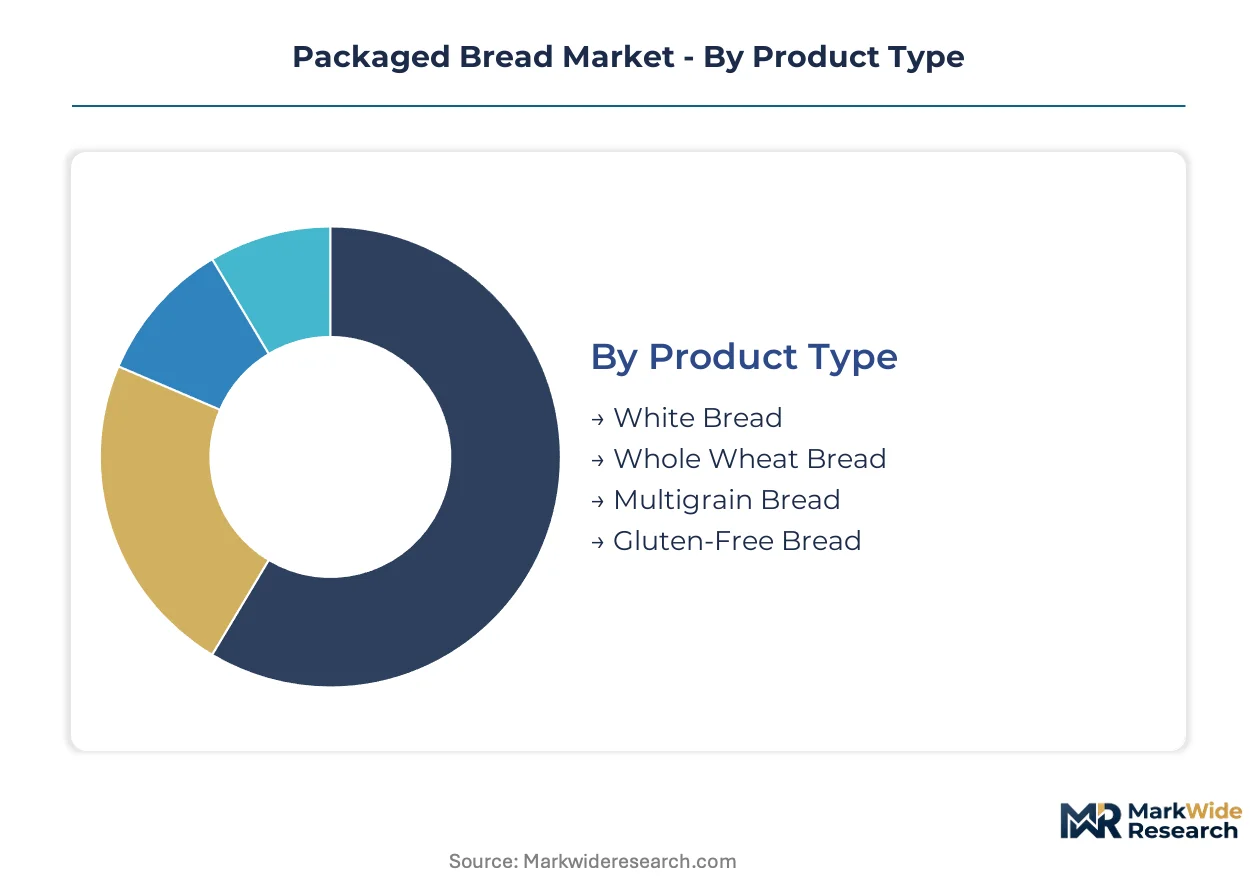
Segmentation in packaged bread reveals how formulation choices, packaging formats, and channel strategies align with distinct consumption occasions. Manufacturers optimize production lines and inventory deployment around these divides.
Product Type:
Reformulation cycles accelerate as fortification mandates and clean-label preferences force portfolio upgrades across all bread categories.
- White Bread:Standard refined-flour formulations with minimal bran content dominate volume in price-sensitive emerging markets. Indian metropolitan households in Mumbai and Delhi sustain demand through modern retail penetration, though margin compression from wheat price volatility limits producer flexibility.
- Whole Wheat Bread:Stone-ground or roller-milled whole grain formulations retain fiber and micronutrients for health-positioned consumers. Demand concentrates in European urban corridors where EU Green Deal carbon-accounting transparency investments align with wellness marketing; shelf-space premiums justify reformulation R&D spending.
- Multigrain Bread:Composite formulations incorporating oats, flax, and seeds target premium positioning through visible ingredient differentiation.
- Gluten-Free Bread:Alternative grain bases using rice, tapioca, or sorghum serve celiac and lifestyle-avoidance segments through dedicated production lines.
Volume placements concentrate in White Bread; the faster expansion belongs to Whole Wheat Bread.
Packaging Type:
Packaging innovation determines shelf-life extension capabilities and retail display economics across ambient distribution networks.
- Bags:Flexible polyethylene or polypropylene barrier films with modified-atmosphere sealing protect sliced loaves for seven-to-fourteen-day retail cycles. Adoption concentrates in Indian tier-two cities where modern format expansion outpaces loose bread vendor displacement.
- Loaves:Unsliced whole-loaf formats in flow-wrap or clip-closure packaging serve foodservice portion-control requirements and artisan-positioned retail segments. European bakery chains in Germany and France deploy these for in-store bakery adjacencies.
- Buns:Individual or twin-pack formats target convenience occasions and foodservice bun specifications.
- Slices:Pre-portioned single-serve packs for institutional catering and airline meal programs.
Foodservice procurement favors Loaves; Bags gain share fastest through retail format conversion.
Distribution Channel:
Channel selection shapes replenishment frequency, promotional intensity, and private-label exposure for branded manufacturers.
- Supermarkets:Full-assortment retail formats with dedicated bakery aisles and promotional end-cap positioning drive branded volume. Direct-store-delivery networks in the southeastern United States demonstrate how frequent replenishment cycles displace wholesale distribution.
- Convenience Stores:Limited-SKU formats prioritizing extended-shelf-life and grab-and-go pack sizes serve immediate consumption occasions. Urban Indian corridors in Bangalore and Hyderabad show fastest modern format penetration here.
- Online Retail:Subscription and on-demand delivery platforms with temperature-controlled logistics.
- Specialty Stores:Health-food and organic-focused retailers with curated gluten-free and clean-label assortments.
Supermarkets anchor volume throughput; Online Retail climbs the fastest as delivery infrastructure matures.
End User:
End-use segmentation separates predictable institutional offtake from fragmented household purchasing patterns.
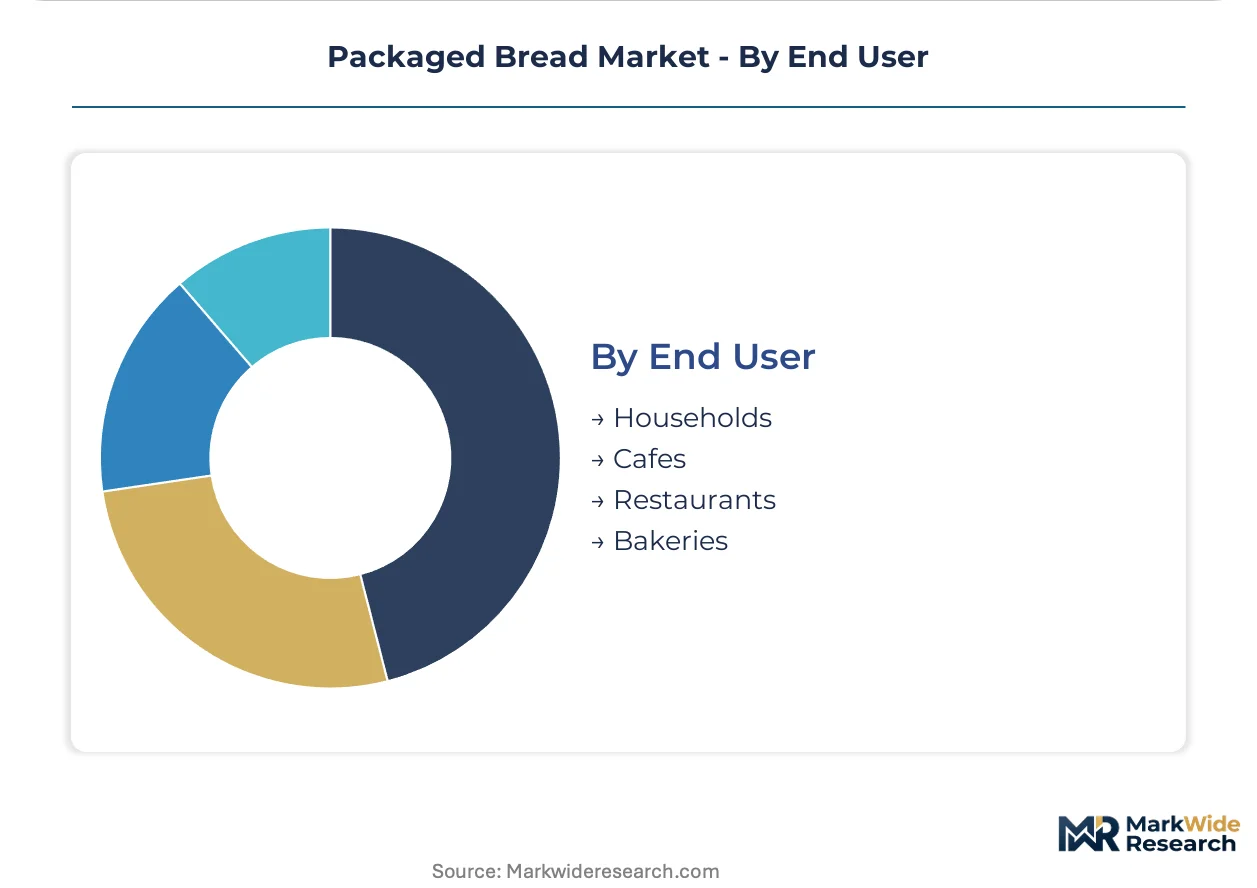
- Households:Retail consumers purchasing for home consumption through weekly or biweekly stock-up trips. Indian metropolitan and tier-two urban households drive sliced format adoption as nuclear family structures reduce traditional loose bread purchasing.
- Cafes:Coffee-shop chains and independent operators requiring consistent portion control for sandwich preparation. Just-in-time supply agreements in Mumbai and Delhi minimize inventory holding for this segment.
- Restaurants:Full-service and quick-service operators with bread-basket and sandwich applications.
- Bakeries:Artisan and retail bakery chains sourcing par-baked or fully baked products for finishing and resale.
Households generate baseline volume; Cafes offer the steepest expansion trajectory through chain outlet growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wheat-growing regions anchor packaged bread production geography. The United States, India, Germany, Mexico, and Japan concentrate milling capacity and industrial baking infrastructure.
United States
Extended-shelf-life demand from retail chains and foodservice operators sustains output volumes. The FDA governs ingredient labeling and nutritional claims for packaged bread sold across state lines. Southeastern industrial corridors demonstrate how direct-store-delivery networks displace wholesale distribution through frequent replenishment cycles.
India
Urban households in Mumbai, Delhi, and Bangalore drive sliced format adoption as nuclear family structures reduce traditional loose bread purchasing. The FSSAI mandates iron and folic acid fortification in mass-market bread, redirecting R&D spending toward compliant premix integration. Tier-two cities in Gujarat and Maharashtra present white-space growth as modern retail formats expand beyond the four major metros.
Germany
Whole wheat and multigrain variants capture expanding margin pools through health-positioned formulations commanding shelf-space premiums. The EU Green Deal pressures producers toward lower-carbon production methods across baking facilities. Industrial clusters in Bavaria and North Rhine-Westphalia deploy heat recovery systems and renewable energy integration to maintain export market access.
Mexico
Convenience-seeking households in Mexico City and Guadalajara metropolitan areas adopt pre-packaged formats as modern retail penetration deepens. Grupo Bimbo leverages vertically integrated flour-to-retail networks to control cost positions against wheat price volatility. Northern border states concentrate production capacity serving cross-border retail and foodservice demand.
Japan
Single-serve and portion-controlled formats target aging demographics and smaller household sizes in Tokyo and Osaka corridors. METI standards influence packaging material specifications and shelf-life labeling requirements. Yamazaki Baking and domestic competitors anchor supply through specialized frozen and ambient bread platforms serving convenience store networks.
Packaged Bread Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue clean-label and gluten-free specialization. The market structure consolidates around multinational baking conglomerates with captive flour milling and regional direct-store-delivery networks. Three archetypes dominate: vertically integrated conglomerates controlling upstream grain supply, regional specialists with dense distribution infrastructure, and niche formulators targeting health-positioned segments. Competitive moves center on portfolio diversification into whole wheat and multigrain variants, plus geographic expansion into underpenetrated tier-two urban corridors.
Within the multinational conglomerate tier, Grupo Bimbo, Flowers Foods, and Associated British Foods plc exemplify scale-driven positioning. Grupo Bimbo anchors Americas supply through integrated Mexican and United States operations. Flowers Foods occupies southeastern United States regional dominance. Associated British Foods plc represents European supply chain specialization through frozen and ambient bread platforms. These entities demonstrate how captive milling capacity and distribution density create defensive positioning against input cost volatility.
| Leading Market Players |
|---|
| Mondelez International, Inc. |
| General Mills, Inc. |
| Grupo Bimbo |
| The Kraft Heinz Company |
| Aryzta AG |
| Flowers Foods, Inc. |
| Yamazaki Baking Co., Ltd. |
| Warburtons Ltd. |
| Associated British Foods plc |
| Others |
Value Chain & Pricing Dynamics
Captive flour milling anchors supply positions and pricing power for industrial bakeries, compressing input cost exposure while enabling margin defense against wheat price volatility in global grain markets.
Pricing Analysis
Extended-shelf-life warranties bundle modified-atmosphere packaging chemistry with seven-to-fourteen-day retail guarantees, differentiating premium tiers from economy positions through clean-label ingredient transparency and FSSAI fortification compliance. Price differentiation hinges on certification grade and volume scale, with institutional foodservice contracts commanding lowest unit costs. Cost compression in the standard tier intensifies as private-label penetration deepens in Indian supermarkets. Household retail consumers exhibit highest price sensitivity; foodservice operators prioritize supply consistency over per-unit savings.
Supply Chain Analysis
Wheat supply rests on cultivation concentration across the United States, India, and Russia, with milling capacity clustering near major metropolitan demand corridors in each geography. Key inputs include high-protein wheat varieties, industrial yeast strains, and barrier film packaging materials. Single-source vulnerability concentrates in specialty premix suppliers serving fortification mandates. Distribution runs through direct-store-delivery networks displacing traditional wholesale channels in dense urban catchments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial bakeries face a vertical-integration race, with captive flour milling and distribution density emerging as the decisive levers for cost control and shelf-space capture.
For Market Incumbents: Acquire regional milling assets to secure wheat supply positions against commodity volatility and compress input costs. Defend market share by accelerating clean-label reformulation ahead of regulatory tightening on synthetic preservatives. Channel control through direct-store-delivery infrastructure in southeastern United States corridors and Indian tier-two cities locks out wholesale-dependent competitors. For New Entrants and Emerging Players: Launch via foodservice direct-supply agreements bypassing retail slotting fee barriers, targeting cafe chains in Mumbai and Delhi with just-in-time delivery commitments. White-space concentration sits in gluten-free and ancient-grain formulations where dedicated production lines create defensible niches. Clean-label positioning with carbon-accounting transparency captures EU Green Deal-aligned export demand. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale regional specialists with captive milling and underutilized distribution density ripe for consolidation. Long-term viability favors producers with backward-integrated grain supply and modern retail channel penetration scaling fastest. Watch FSSAI fortification enforcement timelines as inflection indicator for compliance-capable asset premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flour Milling | Captive wheat processing insulates Grupo Bimbo and Flowers Foods from commodity price spikes. |
| Clean-Label Reformulation Investment | High-pressure processing adoption enables shelf-life extension without synthetic preservatives for premium positioning. |
| Tier-Two City Distribution Expansion | Modern retail penetration in Gujarat and Maharashtra corridors captures nuclear household format conversion. |
| Foodservice Direct Supply Agreements | Just-in-time contracts with Mumbai cafe chains minimize inventory holding and displace loose bread vendors. |
| Carbon-Accounting Transparency Program | EU Green Deal compliance investments unlock export market access for German and Mexican producers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with industrial bakery plant managers, retail category buyers, foodservice procurement leads, and FSSAI compliance officers. Secondary sources included FDA ingredient labeling databases, EFSA health claim evaluations, EU Green Deal implementation trackers, and Indian modern retail expansion reports. Bottom-up volume modeling triangulated against top-down market sizing across producer revenue disclosures.
Production volume, shipment data, and pricing observations reconciled across the analysis window to generate consistent value estimates. Segmentation dimensions spanned product formulation, packaging technology, distribution channel, and end-use occasion. CAGRs derived from trend extrapolation adjusted for regulatory inflection points and technology adoption curves. Wheat price volatility indices and fortification compliance cost curves fed scenario-weighted projections.
The model assumes a particular technology adoption path; alternative pathways for clean-label preservation chemistry would alter the outlook. Forecasts embed assumptions around FSSAI enforcement intensity, EU carbon border adjustment timing, and modern retail penetration rates in Indian tier-two cities. A small set of named triggers—wheat export restriction events, fortification mandate expansion, and barrier packaging material cost shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bake Stable Pastry Fillings Market
Bakery Products
Cream Cheese Frosting Market
Bakery Products
Low Fat Bread Market
Bakery Products
Healthy Biscuits Market
Bakery Products
Lentil Bread Market
Bakery Products
Doughnuts Market
Bakery Products
Low Fat Bran Muffins Market
Bakery Products
Fondant Market
Bakery Products
Low Calorie Rice Cake Market
Bakery Products
Asia-Pacific Baked Food and Cereals Market
Bakery Products
South America Bakery Products Market
Bakery Products
Biscuit Mixes Market
Bakery Products
Europe Bakery Products Market
Bakery Products
Bread Improver Market
Bakery Products
Baked Foods Market
Bakery Products
Pizza Crust Market