
 Malted Rye Flour Market | 2026-2036
Malted Rye Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Malted Rye Flour Market Foresight
Premium organic specification tiers is unwinding commodity pricing conventions across the malted rye flour supply base. Muntons plc leverages its integrated malting infrastructure to secure consistent enzyme activity profiles for brewing clients. Shipton Mill Ltd anchors heritage milling expertise to sustain long-term contracts with UK artisan bakeries. The Soufflet Group extends its grain origination network across northern European growing regions to control input quality.
Malted rye flour consists of rye grain that undergoes controlled germination followed by kiln-drying and milling, producing a diastatic or non-diastatic powder with standardized alpha-amylase levels between 50 and 150 degrees Lintner depending on intended application. Brewers prize this material for its contribution to fermentable sugars, color development, and distinctive spicy flavor compounds absent in barley malt. Organic malted rye commands structural premium positioning as clean-label formulations displace conventional alternatives in European retail channels. Brewing end use attracts the fastest capacity expansion among millers, while snack foods applications remain nascent with concentrated trials in Nordic markets.
EFSA organic labeling standards, EU Green Deal farm-to-fork traceability mandates, and REACH chemical safety protocols collectively elevate compliance costs for non-integrated suppliers while rewarding vertically controlled operations. Germany's KBA-equivalent food safety inspections and France's ANSM-aligned quality controls further fragment market access requirements across member states. Stakeholders must evaluate whether backward integration into malting or forward partnerships with certified organic growers offers more durable margin protection as regulatory stringency intensifies.
Market Dynamics
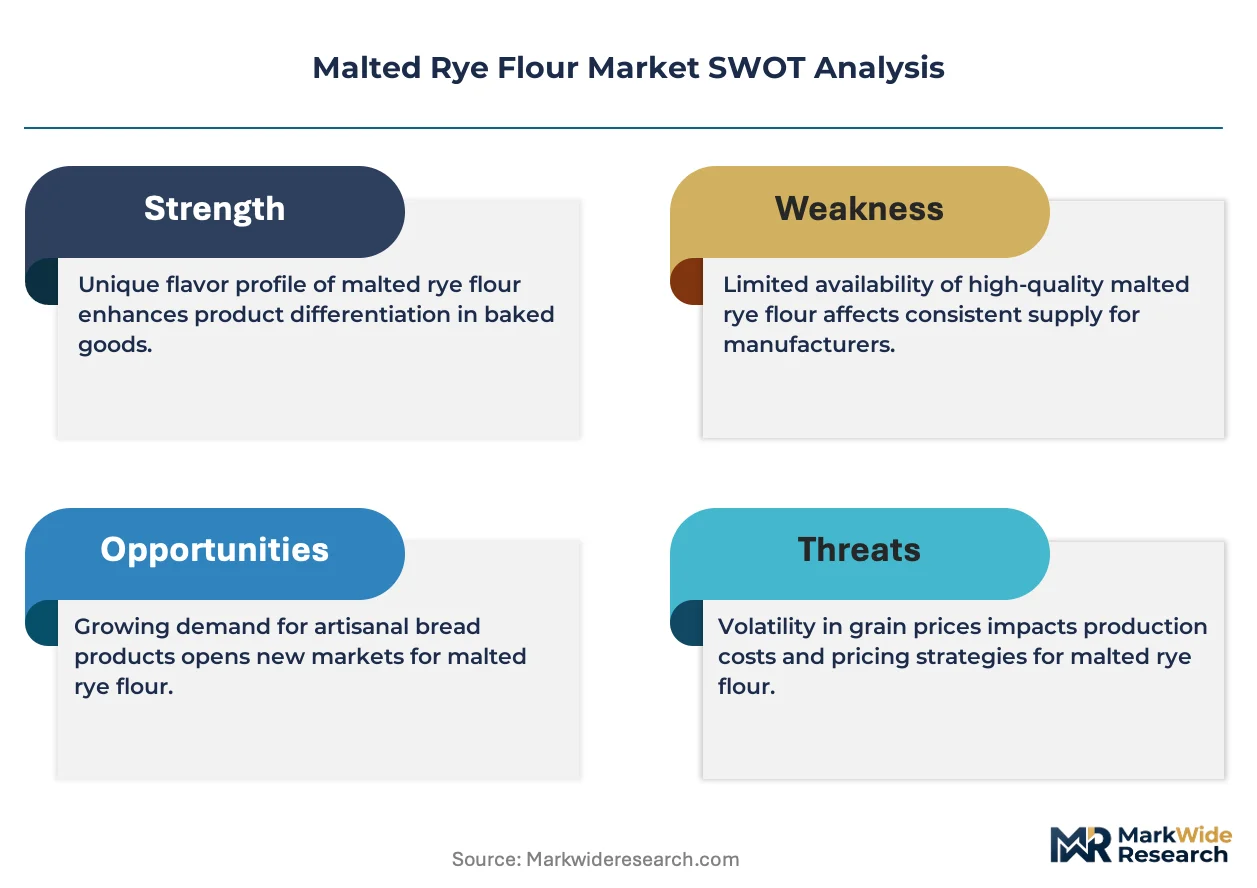
EU Green Deal farm-to-fork traceability mandates are forcing malted rye flour suppliers to restructure procurement networks around certified organic grain streams, compressing margins for non-integrated millers while rewarding captive malting operations.
Growth Catalysts
- EFSA Organic Certification:Tightened supply chain documentation requirements under EU organic labeling standards are locking in premium pricing tiers for compliant malted rye flour across German and Scandinavian retail channels.
- Craft Brewing Revival:Baltic Sea port cities from Gdansk to Copenhagen are witnessing expanded capacity investments in specialty malting infrastructure to serve small-batch distillers and artisan brewers seeking distinctive spicy flavor profiles.
- Sourdough Applications:Heritage baking techniques are driving artisan bakery procurement of diastatic malted rye flour with standardized alpha-amylase levels for controlled fermentation performance.
Market Restraints
- Input Cost Volatility:Rye grain prices fluctuate with Black Sea export disruptions and Baltic harvest variability, compressing malting margins when contract structures lack pass-through mechanisms.
- Supply Concentration Risk:Northern European malting infrastructure clusters in Germany and Poland, creating geographic vulnerability to regional weather shocks and logistics bottlenecks.
- Substitution Threat:Barley malt dominates brewing formulations due to established enzyme performance benchmarks, limiting malted rye flour penetration in volume brewing segments.
Strategic Opportunities
- Snack Foods White Space:Nordic markets are piloting malted rye flour in savory cracker and crisp formulations, opening incremental demand beyond traditional baking and brewing verticals.
- Clean-Label Tailwinds:REACH chemical safety protocols and EU Green Deal sustainability disclosures are accelerating displacement of conventional malted grains in European retail formulations.
- Direct-to-Bakery Channels:Specialty millers are bypassing traditional ingredient distributors to secure long-term supply contracts with UK and German artisan bakeries seeking provenance documentation.
Industry Challenges
- Malting Technician Scarcity:Controlled germination and kiln-drying expertise is concentrated among aging specialists in traditional European malting regions, constraining capacity expansion timelines.
- Certification Timeline Compression:EU organic conversion periods and EFSA documentation requirements extend supplier onboarding cycles, delaying revenue recognition for new grain partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malted Rye Flour Market |
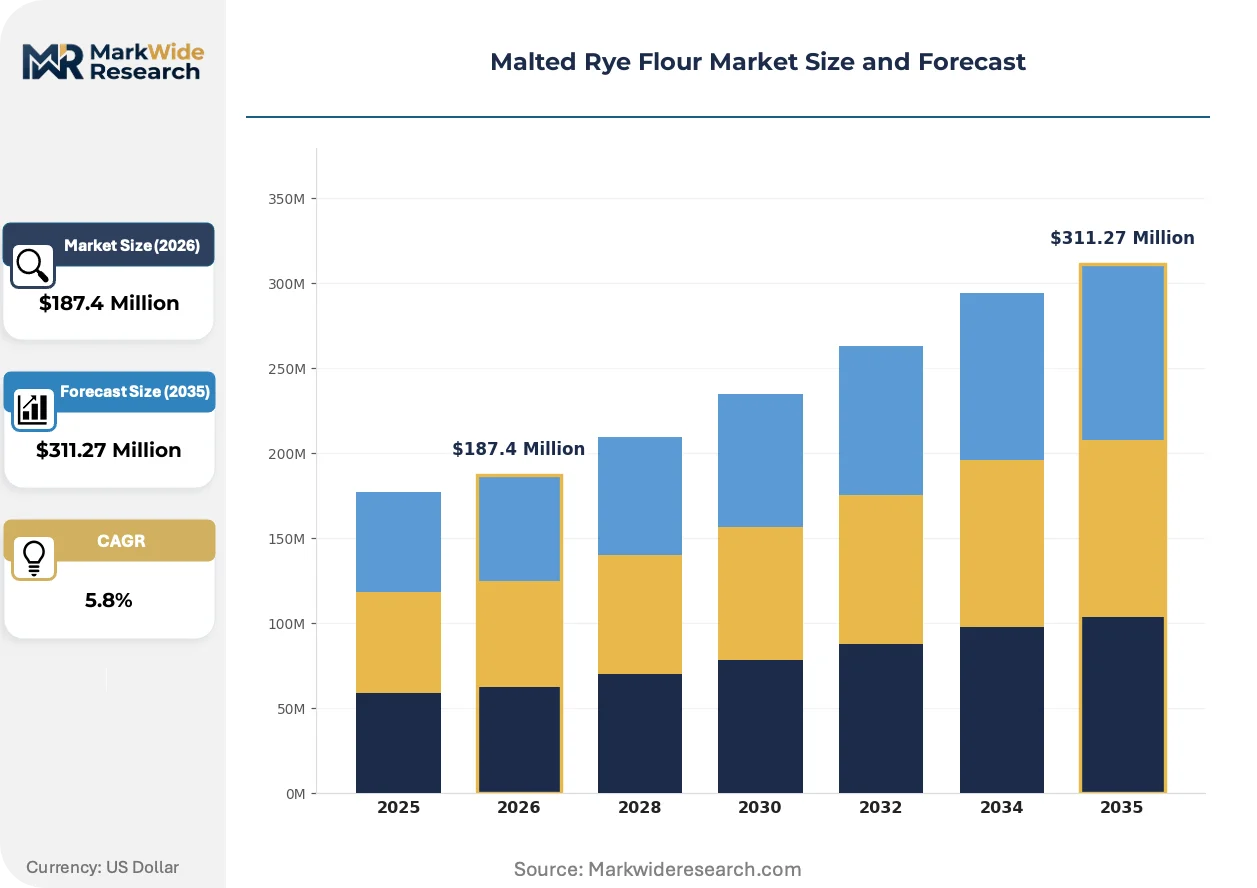
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Malted Rye, Conventional Malted Rye, Whole Grain Malted Rye, Specialty Malted Rye End Use: Baking, Brewing, Snack Foods, Cereals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service Packaging Type: Bulk Packaging, Retail Bags, Pouches, Cans |
| Companies Covered | FWP Matthews Ltd, Shipton Mill Ltd, Janie's Mill, Central Milling Company, Lindley Mills, Malterie Frontenac, Farinart, Muntons plc, The Soufflet Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malted Rye Flour Market Shifts & Advancements
Precision malting technologies and digital supply chain verification tools are restructuring how enzyme activity consistency and organic provenance guarantees are delivered to European craft brewers and artisan bakers.
Automated kiln control systems with real-time moisture sensing and temperature modulation are fragmenting traditional malting expertise dependencies. Mid-size millers in Poland and the Czech Republic are adopting these systems to achieve batch-to-batch alpha-amylase consistency previously reserved for large integrated malting groups. This capability diffusion is compressing quality-based price premiums and enabling new market entrants to compete on specification reliability.
EU Green Deal digital product passport requirements are mandating blockchain-anchored traceability from field to flour bag. EFSA-aligned documentation systems now require geotagged harvest records, malting facility audit logs, and chain-of-custody verification for organic claims. German and French regulators are enforcing these standards most aggressively, pushing non-compliant suppliers toward costly system overhauls or market exit.
Bakery procurement teams are consolidating supplier relationships around integrated malting-milling operations that can deliver both diastatic performance guarantees and single-origin organic certification. This concentration pattern favors vertically structured suppliers with captive grain origination networks across northern European growing regions. Danish and Swedish craft brewers are extending this consolidation logic, negotiating multi-year supply agreements that bundle technical support with volume commitments.
Malted Rye Flour Market Segmentation
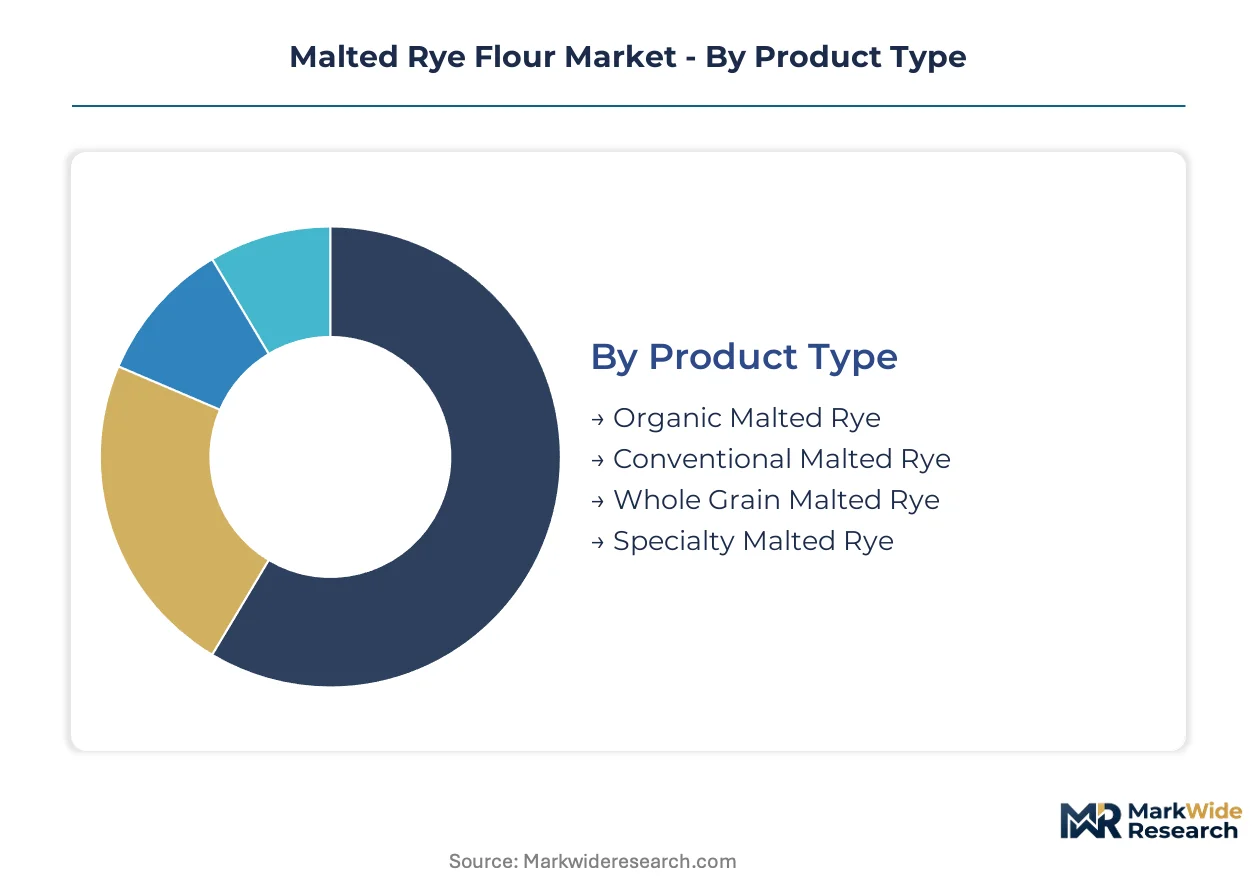
Malted rye flour segmentation reflects divergent technical specifications and certification requirements that reshape procurement priorities across European supply chains. Distinct product tiers, end-use applications, and channel strategies fragment competitive positioning in ways that reward specialized operational capabilities.
Product Type:
Barley malt substitution pressure concentrates most intensely on conventional specifications, while organic and specialty variants command defensive positioning through certification barriers and technical differentiation.
- Organic Malted Rye:Grain undergoes controlled germination and kiln-drying under EFSA-certified organic protocols, producing standardized enzyme profiles with full farm-to-fork traceability documentation. German and Scandinavian artisan bakeries anchor procurement volumes for sourdough applications, driven by EU Green Deal sustainability disclosure mandates and clean-label retail formulation requirements.
- Conventional Malted Rye:Standard malting process without organic certification delivers cost-competitive enzyme activity for volume brewing operations. Polish and Czech millers face margin compression from barley malt substitution in mainstream beer production, limiting expansion beyond price-sensitive contract manufacturing.
- Whole Grain Malted Rye:Retains bran and germ layers through milling, delivering elevated fiber content and denser nutritional profiles for health-positioned bakery formulations.
- Specialty Malted Rye:Custom kiln profiles and germination protocols produce distinctive flavor compounds for craft distillers and premium chocolate makers seeking differentiated ingredient provenance.
Conventional malted rye anchors the volume base while organic malted rye gains share at the steepest rate.
End Use:
Application-based cost tiers separate commodity-volume brewing from premium-positioned artisan baking, with snack foods emerging as an experimental margin layer.
- Brewing:Diastatic malted rye contributes fermentable sugars, color development, and spicy phenolic compounds to small-batch beer and spirits production. Baltic Sea port cities from Gdansk to Copenhagen concentrate capacity investments, supported by craft brewing revival demand for flavor differentiation beyond barley-dominant formulations.
- Baking:Standardized alpha-amylase levels between 50 and 150 degrees Lintner enable controlled fermentation performance in sourdough and heritage bread applications. UK and German artisan bakeries sustain long-term supply contracts with specialty millers seeking provenance documentation and technical support bundled with volume commitments.
- Snack Foods:Nordic markets pilot savory cracker and crisp formulations, opening incremental demand beyond traditional verticals with concentrated trials in Denmark and Sweden.
- Cereals:Breakfast and granola applications remain nascent, with limited penetration outside Scandinavian health-food retail channels.
Brewing commands the dominant revenue share while snack foods applications climb the fastest.
Distribution Channel:
Customer-type concentration patterns favor direct procurement relationships over fragmented retail intermediation, particularly for technical specification-dependent buyers.
- Specialty Stores:Dedicated ingredient suppliers and bakery-focused retailers serve artisan producers requiring technical consultation and batch-specific enzyme documentation. German and French markets sustain the densest specialty store networks, aligned with heritage malting traditions and craft baking density.
- Food Service:Direct-to-bakery and direct-to-brewery channels bypass traditional distributors, securing multi-year supply agreements with integrated malting-milling operations. UK artisan bakeries consolidate procurement around vertically structured suppliers with captive grain origination networks.
- Online Retail:E-commerce platforms serve small-scale producers and home baking enthusiasts with packaged retail formats, though technical support limitations constrain penetration among professional users.
- Supermarkets:Mass retail channels carry limited SKU depth, focusing on conventional specifications for consumer baking applications with minimal technical differentiation.
Food service channels anchor the volume base while specialty stores expand most quickly.
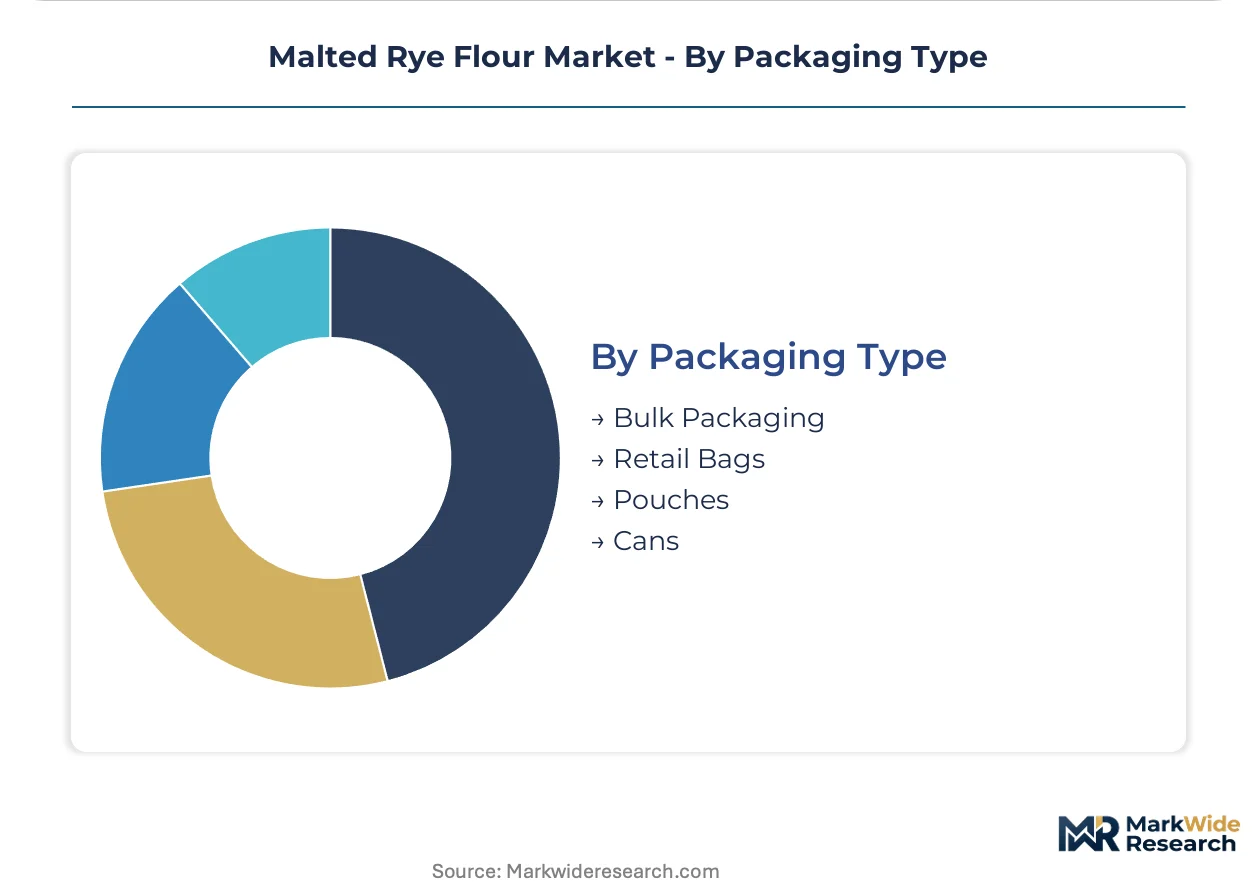
Packaging Type:
Supply concentration in northern European malting clusters shapes packaging configuration around logistics efficiency and shelf-life preservation requirements.
- Bulk Packaging:Industrial totes and silo deliveries serve high-volume brewing and commercial baking operations with continuous production schedules. German and Polish malting infrastructure clusters optimize bulk logistics through Baltic Sea port access and rail-linked distribution networks.
- Retail Bags:Paper and multi-layer laminate bags target artisan bakeries and small-batch producers with intermediate volume requirements and storage flexibility needs.
- Pouches:Flexible packaging formats serve online retail and specialty store channels with portion-controlled offerings for trial and premium positioning.
- Cans:Airtight metal packaging preserves enzyme activity and flavor stability for export markets and extended shelf-life applications, though cost premiums limit adoption.
Bulk packaging anchors the volume base while pouches gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish malted rye flour shipments flow westward to German artisan bakeries and northward to Scandinavian craft brewers, anchoring Baltic Sea trade corridors that concentrate value-added processing capacity in northern European port cities.
Germany
Artisan sourdough bakeries in Berlin and Munich sustain procurement volumes for organic malted rye with standardized enzyme documentation. KBA-equivalent food safety inspections enforce strict malting facility audit protocols. Hamburg anchors the densest specialty malting infrastructure, where integrated operations serve both domestic brewing clients and export markets.
Poland
Grain origination networks across Pomeranian and Warmian-Masurian growing regions supply captive malting operations with organic rye streams. EU Green Deal farm-to-fork traceability mandates compress certification timelines for new supplier onboarding. Gdansk port facilities enable bulk export logistics to Scandinavian craft brewing clusters.
United Kingdom
Heritage milling expertise in the Cotswolds and West Country sustains long-term supply contracts with artisan bakeries seeking provenance documentation. EFSA-aligned organic labeling requirements lock in premium pricing tiers for compliant suppliers. Shipton Mill anchors specialty procurement relationships through direct-to-bakery channel structures.
Denmark
Craft brewing revival demand concentrates in Copenhagen for distinctive spicy flavor profiles beyond barley-dominant formulations. REACH chemical safety protocols accelerate displacement of conventional malted grains in retail formulations. Baltic Sea port access enables just-in-time delivery relationships with Polish malting suppliers.
France
ANSM-aligned quality controls fragment market access requirements across regional baking clusters in Normandy and Brittany. EU organic conversion periods extend supplier onboarding cycles for grain partnerships. Lille and Calais serve as distribution nodes for cross-channel supply to UK artisan producers.
Malted Rye Flour Market Competitive Landscape
Listed leaders compete with private specialists across certification and channel dimensions, producing a tiered structure where integrated malting groups capture premium organic volumes while regional millers defend commodity positions. Three archetypes dominate: vertically structured grain-to-flour operators, heritage specialty millers with provenance anchoring, and contract malting service providers. Capacity expansion and direct-to-bakery channel development represent the dominant competitive moves as distributors lose share to relationship-based supply agreements.
Within the integrated malting tier, Muntons plc and The Soufflet Group exemplify archetypes of scale-driven operations with captive grain origination networks. Shipton Mill Ltd occupies a position among heritage specialists leveraging geographic anchoring and technical consultation bundling. These three entities represent distinct strategic postures without implying specific market shares or financial performance.
| Leading Market Players |
|---|
| FWP Matthews Ltd |
| Shipton Mill Ltd |
| Janie's Mill |
| Central Milling Company |
| Lindley Mills |
| Malterie Frontenac |
| Farinart |
| Muntons plc |
| The Soufflet Group |
| Others |
Supply & Pricing Matrix
Integrated malting capacity utilization above 85 percent in northern Germany and Poland compresses unit costs for captive grain-to-flour operators while elevating price floors for non-integrated millers dependent on spot grain markets. This scale asymmetry concentrates pricing power among vertically structured suppliers serving EFSA-certified organic channels.
Pricing Analysis
Next-generation precision malting equipment with automated kiln control commands 15-25 percent premiums over conventional malting infrastructure, while legacy diastatic specifications face commodity price erosion. Three-tier pricing structure across premium organic, standard conventional, and economy bulk tiers separates EFSA-certified provenance from uncertified alternatives. Pricing pressure stems from barley malt substitution in volume brewing segments, compressing conventional malted rye margins. Artisan bakeries in Germany and Scandinavia exhibit lowest price sensitivity due to clean-label formulation mandates, while Polish contract brewers anchor the most price-elastic demand tier.
Supply Chain Analysis
Germany and Poland anchor European malting infrastructure, with Gdansk and Hamburg port clusters concentrating value-added processing capacity for Baltic Sea trade corridors. Rye grain supply draws from Pomeranian and Warmian-Masurian growing regions, while enzyme activity consistency rests on controlled germination expertise concentrated among aging malting technicians. Single-source vulnerability to Black Sea export disruptions and Baltic harvest variability elevates input cost volatility. Distribution runs through direct-to-bakery and direct-to-brewery channels bypassing traditional ingredient distributors, with bulk silo deliveries dominating high-volume brewing procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated artisan bakery procurement teams in Germany and the United Kingdom, fragmenting distributor intermediation and rewarding direct supply relationships with integrated malting-milling operations.
For Market Incumbents: Consolidate grain origination networks across northern European organic growing regions to secure EFSA certification pipeline capacity. Deepen backward integration into captive malting infrastructure to defend margin position against barley malt substitution pressure in mainstream brewing. Prioritize malting technician apprenticeship programs to address capability scarcity constraining capacity expansion timelines. For New Entrants and Emerging Players: Technical consultation gaps in enzyme activity documentation and sourdough fermentation support present white-space openings for specialized service bundling. Nordic snack foods trials in savory cracker formulations offer the most penetrable application expansion beyond traditional brewing and baking verticals. Pursue direct-to-bakery channel development with provenance documentation and batch-specific alpha-amylase guarantees as primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated malting groups with captive organic grain origination and digital traceability infrastructure deployed. Long-term viability across the projection horizon rests on EU Green Deal compliance scalability rather than commodity volume exposure. Acquisition target archetype: mid-size Polish or Czech millers with precision malting technology adoption and EFSA certification pathway progress. Signal to watch: Baltic Sea port capacity expansion announcements indicating craft brewing demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Grain Origination | Secures EFSA-certified supply pipeline against EU Green Deal traceability mandates. |
| Precision Malting Technology Deployment | Enables batch-to-batch enzyme consistency previously reserved for large integrated groups. |
| Direct-to-Bakery Channel Development | Bypasses distributor intermediation to capture consolidated artisan procurement relationships. |
| Malting Technician Apprenticeship Programs | Addresses capability scarcity constraining capacity expansion in traditional European regions. |
| Blockchain-Anchored Traceability Implementation | Satisfies EU digital product passport requirements for organic provenance verification. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with artisan bakery procurement managers, craft brewing technical directors, malting facility operations leads, and specialty ingredient distributors. Secondary validation drew from EFSA organic certification registries, EU customs trade data, REACH chemical safety filings, and malting industry association capacity reports. Bottom-up volume estimates from individual facility outputs were triangulated against top-down demand projections from end-use application consumption patterns.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation across product type tiers, end-use application verticals, distribution channel structures, and regional production clusters. CAGRs were derived from trend extrapolation of historical procurement patterns adjusted for regulatory inflection points and technology adoption curves. Key inputs included organic conversion timeline assumptions, craft brewing capacity expansion announcements, and EFSA documentation requirement implementation schedules.
Underlying assumptions cover sustained EU Green Deal enforcement intensity and Baltic Sea logistics corridor stability, with deviation risk concentrated in Black Sea grain export disruption scenarios and malting technician retirement acceleration. Forecasts reflect these baseline conditions with sensitivity bands for regulatory timeline compression and organic certification backlog scenarios. Recalibration cycles align with material shifts in EFSA audit protocol changes and EU digital product passport mandate rollouts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bread Mix Market
Bakery Products
Low Fat Chocolate Cake Market
Bakery Products
Personalized Bakery Products Market
Bakery Products
Instant Cake Gel Market
Bakery Products
Middle East and Africa Sweet Biscuits Market
Bakery Products
Low-Calorie Pie Market
Bakery Products
North America Bakery Products Market
Bakery Products
North America Sweet Biscuits Market
Bakery Products
Specialty Bakery Market
Bakery Products
Europe Bakery Products Market
Bakery Products
Low Calorie Bread Market
Bakery Products
Gluten-Free Baking Mixes Market
Bakery Products
Bakery Flavors Market
Bakery Products
Bakery Mixes Market
Bakery Products
Organic Frozen Bakery Market
Bakery Products
Fondant Market