
 Asia-Pacific Baked Food and Cereals Market | 2026-2036
Asia-Pacific Baked Food and Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Baked Food and Cereals Market Outlook
Urban food-service buyers is redrawing procurement patterns across the Asia-Pacific baked food and cereals landscape. Britannia Industries Ltd leverages its coastal manufacturing footprint to dominate South Indian distribution corridors. Nestle SA sustains R&D intensity in whole-grain breakfast cereals tailored to Japanese and Australian palates. General Mills competes through brand strength in the premium cookie segment across ASEAN duty-free and travel-retail channels.
Asia-Pacific baked food and cereals encompass wheat-based, yeast-leavened, and chemically aerated products with moisture contents typically below 14 percent for shelf-stable classification, serving commercial nourishment and convenience consumption across household and institutional channels. The breads category anchors volume throughput in the product-type dimension, though gluten-free ingredient formulations generate disproportionate margin capture in urban Australian and South Korean markets. Supermarkets control the distribution-channel hierarchy in China and India, while online-retail velocity accelerates fastest in Japan's aging-consumer segments where home-delivery subscription models reduce store-visit frequency.
FSSAI fortification rules in India, China's GB standards for food-contact packaging, and Japan's JIS quality benchmarks collectively elevate compliance costs for cross-border suppliers while creating product-differentiation opportunities for certified domestic producers. Australia's FSANZ labeling requirements and South Korea's MFDS sodium-reduction campaigns further fragment the regulatory terrain that manufacturers must navigate. Stakeholders should monitor how ASEAN harmonization negotiations reshape mutual-recognition agreements for processed-grain safety standards before committing to single-country production strategies.
Market Dynamics
Urbanization across Southeast Asian megacities is compressing traditional breakfast preparation time, forcing a structural pivot toward shelf-stable packaged solutions that trade freshness for convenience. This demand compression is reshaping manufacturing footprints and distribution network investments across the region.
Growth Catalysts
- FSSAI fortification mandates:India's mandatory micronutrient enrichment of wheat flour creates standardized formulation demand that domestic millers must meet, expanding fortified premix supply chains.
- Cold-chain bakery penetration:China's tier-two city logistics networks now support temperature-controlled distribution of cream-filled and dairy-based products previously limited to coastal megacities.
- Whole-grain breakfast cereals:Japanese and Australian consumers are migrating toward high-fiber morning options, pulling R&D investment into bran stabilization and texture modification technologies.
Market Restraints
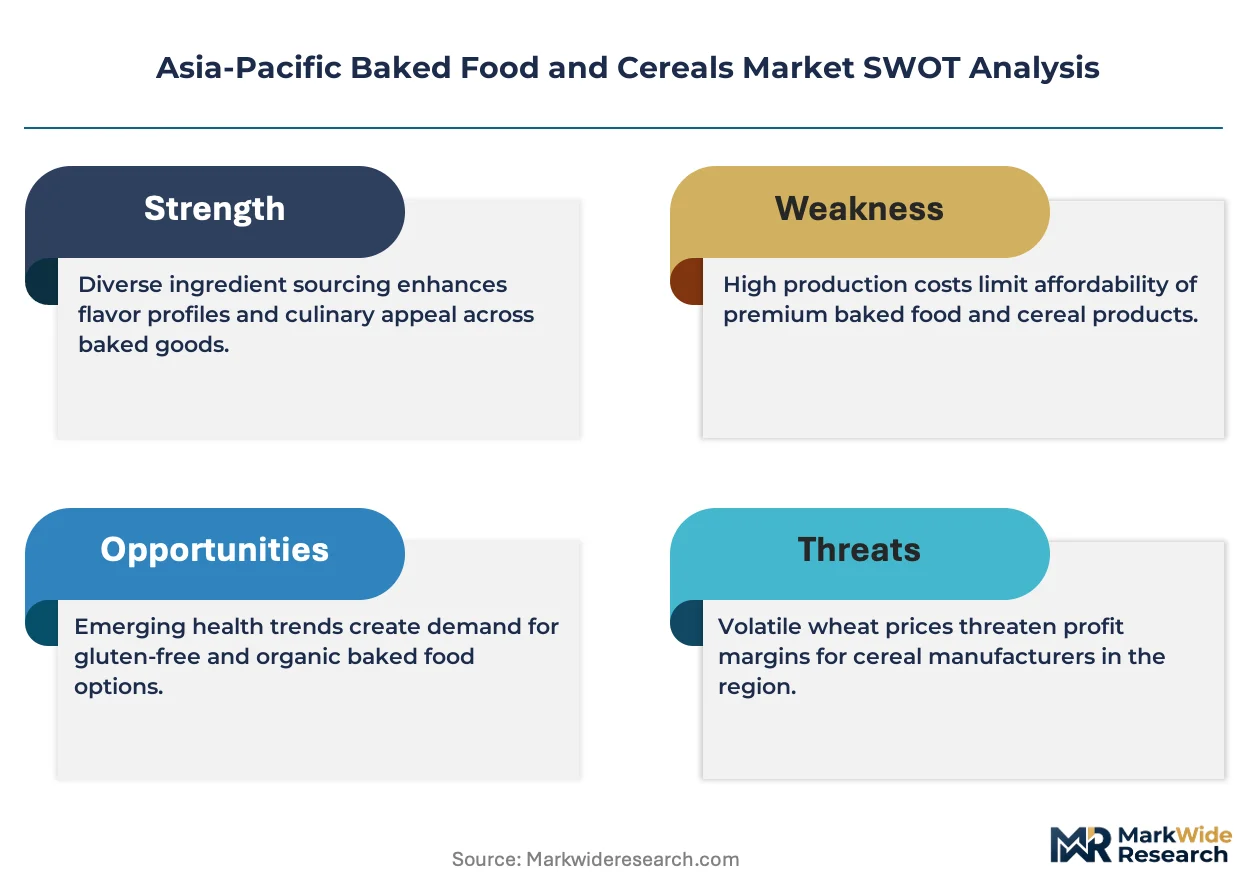
- Wheat import dependency:Southeast Asian markets rely on Black Sea and Australian grain supplies, exposing margins to currency volatility and shipping route disruptions.
- GB standards compliance costs:China's food-contact packaging regulations require migration testing for plastic films and coatings, adding certification overhead for cross-border ingredient suppliers.
- Fresh bakery substitution:Traditional wet markets and neighborhood bakeries in Vietnam and Indonesia retain price-sensitive consumers through daily production cycles that packaged goods cannot replicate.
Strategic Opportunities
- Home-delivery subscription models:Japan's aging demographic is accelerating direct-to-consumer cereal replenishment services that bypass conventional retail shelf competition.
- Gluten-free ingredient systems:South Korean and Australian urban centers show willingness to pay premium prices for rice-based and alternative-grain formulations certified by national allergen standards.
- ASEAN harmonization negotiations:Mutual-recognition agreements for processed-grain safety standards could reduce redundant testing for manufacturers operating across multiple member states.
Industry Challenges
- Artisan skill scarcity:Industrial-scale production of laminated dough and long-fermentation breads requires trained bakers that vocational programs in India and Indonesia are not yet producing at sufficient scale.
- Legacy equipment integration:Brownfield facilities across China's eastern seaboard struggle to retrofit automated packaging lines without disrupting continuous production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Baked Food and Cereals Market |
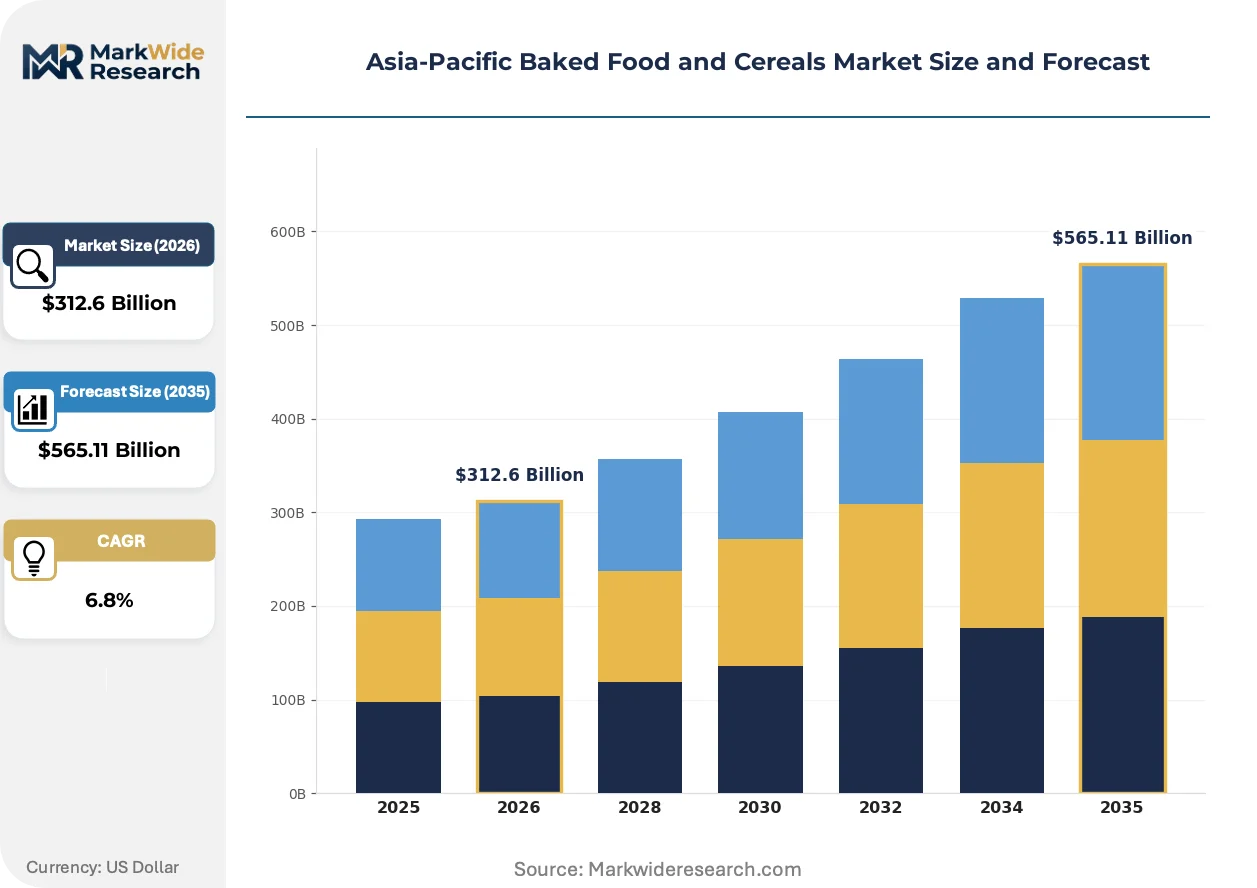
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Pastries, Cookies, Crackers Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores Ingredient Type: Whole Grain, Gluten-Free, Organic, Artificial Additives End User: Households, Food Service, Retail Outlets, Bakeries |
| Companies Covered | Grupo Bimbo, Kellogg's, Nestle SA, General Mills, Mondelez, The Garden Company Limited, Campbells Soup Company, Barilla Group, Britannia Industries Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Baked Food and Cereals Market Strategic Shifts
Active fermentation control technologies and precision moisture management systems are compressing production cycle times while extending shelf stability. These process innovations are redrawing capital allocation priorities across the region's manufacturing base.
Sourdough starter propagation and controlled atmosphere packaging is miniaturizing the equipment footprint required for traditional flavor development, enabling artisan-style production in compact urban facilities. South Korean bakery chains are adopting these systems to localize output without suburban plant investments. The technology is compressing the minimum efficient scale for differentiated product categories.
Japan's JIS quality benchmarks for rice-based processed foods are tightening contaminant thresholds and labeling precision requirements. Domestic manufacturers are reformulating seasoning blends and restructuring supply documentation to maintain certification. The premium snack and ready-meal segments are absorbing compliance costs through ingredient specification upgrades.
Subscription-based replenishment for breakfast cereals is displacing supermarket bulk purchasing among time-constrained professionals in Tokyo and Osaka. Home-delivery operators are capturing recurring revenue streams that traditional retail cannot match. This channel rotation is most visible in single-person households and elderly consumers reducing store-visit frequency.
Asia-Pacific Baked Food and Cereals Market Segmentation
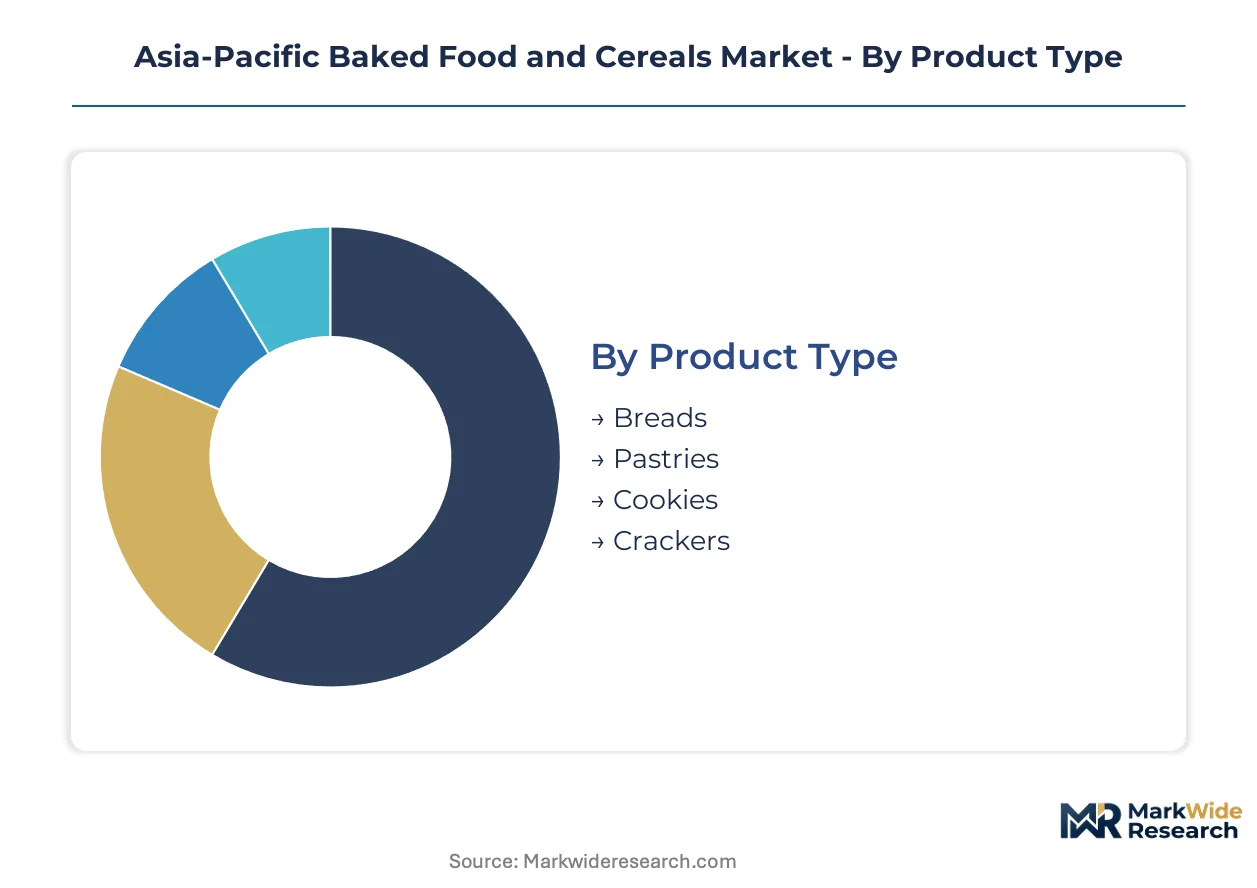
Segmentation in the Asia-Pacific baked food and cereals market reveals how channel power, ingredient premiums, and end-user concentration create divergent margin structures. Manufacturers must align formulation and packaging investments to the specific throughput economics of each segment cluster.
Product Type:
Channel flow varies sharply across product categories, with ambient-stable formats dominating supermarket shelf space while temperature-sensitive items concentrate in cold-chain-dependent channels.
- Breads:Yeast-leavened and chemically aerated loaves with moisture content below 14 percent for shelf-stable classification. Volume concentrates in China's eastern seaboard provinces where cold-chain bakery networks now penetrate tier-two cities, pulling demand away from traditional wet markets.
- Pastries:Laminated dough products including croissants and Danish varieties requiring controlled fermentation and temperature-managed distribution. South Korean bakery chains are adopting compact active fermentation systems to localize output without suburban plant investments.
- Cookies:Low-moiture baked goods with extended ambient shelf life, flowing heavily through ASEAN duty-free and travel-retail channels where premium positioning captures tourist expenditure.
- Crackers:Savory flat-baked products serving both snacking and meal-accompaniment functions, with whole-grain variants gaining traction in Australian and Japanese convenience retail.
Breads dominate installed base. Pastries are where expansion concentrates.
Distribution Channel:
Cost tier stratification separates premium-positioned channels from high-volume, low-margin routes, with direct-to-consumer models capturing recurring revenue streams.
- Supermarkets:Control the distribution hierarchy in China and India, commanding slotting fees and promotional participation that squeeze supplier margins while delivering mass-market penetration.
- Online Retail:Velocity accelerates fastest in Japan's aging-consumer segments where home-delivery subscription models reduce store-visit frequency and capture recurring cereal replenishment.
- Convenience Stores:High-turnout, limited-SKU environments favoring single-serve and immediate-consumption formats across Southeast Asian megacities.
- Specialty Stores:Premium bakeries and health-food retailers in South Korean and Australian urban centers commanding price premiums for certified gluten-free and organic formulations.
Supermarkets dominate installed base. Online retail is climbing the fastest.
Ingredient Type:
Application-specific requirements drive formulation divergence, with regulatory mandates in some segments creating standardized demand while premium segments reward differentiation.
- Whole Grain:High-fiber formulations incorporating bran and germ components, with Japanese and Australian consumers migrating toward these options and pulling R&D investment into bran stabilization technologies.
- Gluten-Free:Rice-based and alternative-grain systems certified by national allergen standards, generating disproportionate margin capture in urban Australian and South Korean markets willing to pay premium prices.
- Organic:Cultivation and processing standards excluding synthetic inputs, concentrated in specialty retail channels with documented supply chain transparency.
- Artificial Additives:Preservative and coloring systems facing tightening JIS quality benchmarks and South Korean MFDS sodium-reduction campaigns that elevate compliance costs.
Whole grain dominates installed base. Gluten-free is gaining share fastest.
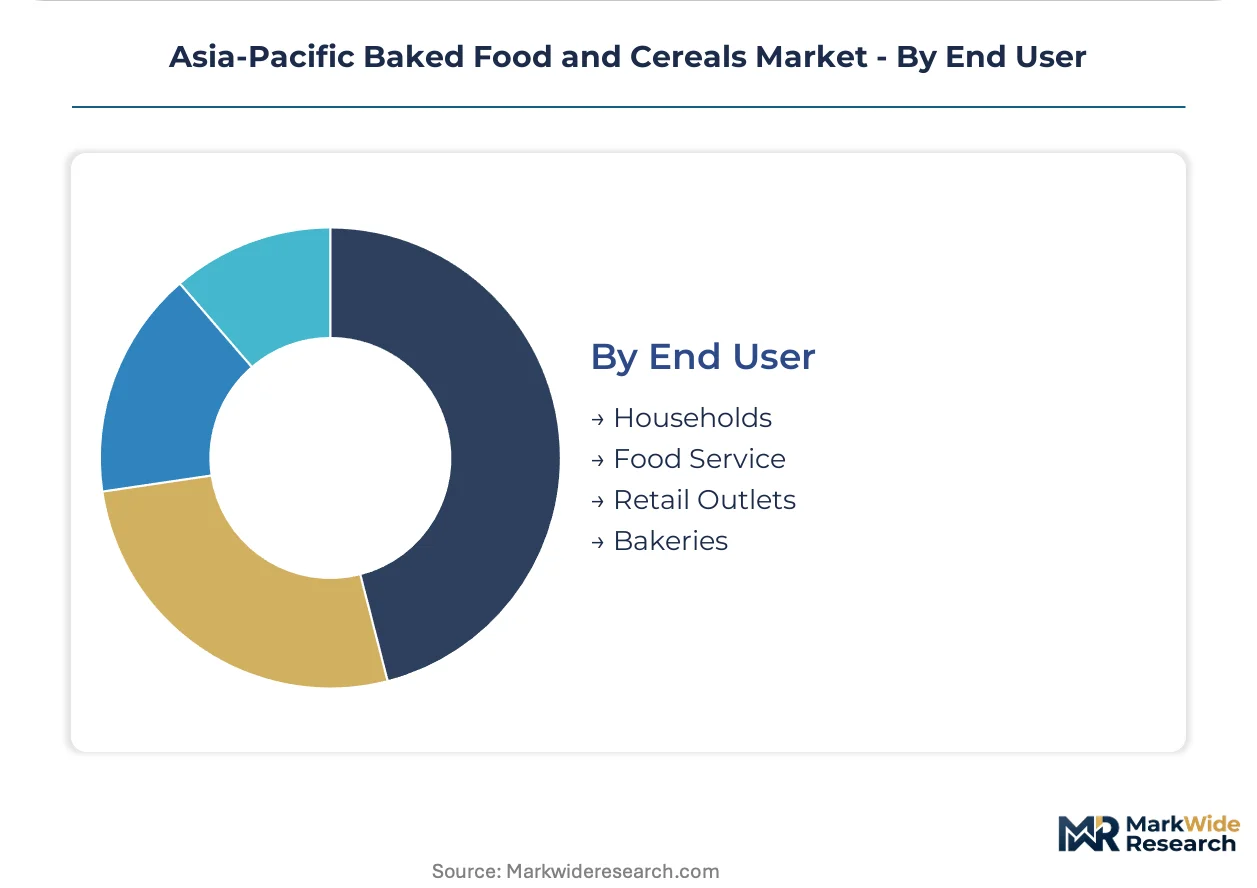
End User:
Customer type determines order frequency, batch size, and specification stringency, with institutional buyers rewriting procurement patterns through consolidated purchasing power.
- Households:Individual and family consumption units driving breakfast routine shifts toward packaged convenience across Southeast Asian megacities.
- Food Service:Hotels, restaurants, and institutional catering operations requiring consistent supply and customized portion formats, with urban food-service buyers redrawing procurement patterns across the region.
- Retail Outlets:Independent grocers and neighborhood stores in Vietnam and Indonesia retaining price-sensitive consumers through daily production cycles.
- Bakeries:Artisan and industrial producers requiring ingredient supply and premix solutions, facing scarcity of trained bakers for laminated dough and long-fermentation production in India and Indonesia.
Households dominate installed base. Food service is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in ingredient import logistics, while Singapore's transshipment hub status connects Australian grain suppliers to Southeast Asian millers. Cold-chain infrastructure investments across the region are redrawing distribution radii for temperature-sensitive bakery products.
China
Urban households in Jiangsu and Zhejiang provinces are accelerating breakfast cereal adoption as cold-chain networks penetrate tier-two cities like Ningbo and Wuxi. GB standards for food-contact packaging mandate migration testing that elevates compliance costs for cross-border ingredient suppliers. The Yangtze River Delta manufacturing corridor is consolidating milling capacity to serve eastern seaboard demand clusters.
India
FSSAI fortification mandates for wheat flour are reshaping product formulation standards across Maharashtra and Gujarat processing hubs. The national food regulator's micronutrient enrichment rules create standardized demand that domestic millers in the Delhi-NCR corridor must meet. Britannia Industries leverages its coastal manufacturing footprint to dominate South Indian distribution corridors through Karnataka and Tamil Nadu.
Japan
Subscription-based cereal replenishment is displacing supermarket bulk purchasing among time-constrained professionals in Tokyo and Osaka. METI-aligned JIS quality benchmarks for rice-based processed foods tighten contaminant thresholds that domestic manufacturers must absorb. The Kanto region's aging-consumer segments are accelerating home-delivery models that reduce store-visit frequency.
Australia
Whole-grain breakfast cereal demand is pulling R&D investment into bran stabilization technologies for export-oriented processors in New South Wales and Victoria. FSANZ labeling requirements fragment the regulatory terrain that manufacturers must navigate for domestic and Asian export markets. Sydney and Melbourne specialty retailers command price premiums for certified gluten-free formulations targeting health-conscious urban consumers.
South Korea
MFDS sodium-reduction campaigns are forcing reformulation of savory baked products across Seoul Capital Area manufacturing facilities. Compact active fermentation systems enable bakery chains to localize artisan-style output without suburban plant investments. Busan-Ulsan logistics hubs support rice-based alternative grain supply chains certified by national allergen standards.
Asia-Pacific Baked Food and Cereals Market Competitive Environment
Listed leaders compete with private specialists across distribution channel control, creating a tiered structure where scale advantages clash with regional agility. The market consolidates around multinational packaged-food conglomerates with R&D intensity in whole-grain and fortified formulations, while domestic specialists defend share through coastal manufacturing proximity and regulatory certification speed. Three archetypes dominate: global brand licensors leveraging duty-free and travel-retail channels, national champions with fortified premix supply chain integration, and regional bakery chains adopting compact production systems. Competitive moves concentrate on cold-chain network expansion and subscription-based direct-to-consumer platform development.
Within the multinational conglomerate tier, Nestle SA and General Mills occupy positions anchored by brand strength in breakfast cereals and premium cookies respectively. Britannia Industries Ltd exemplifies the national champion archetype through its coastal manufacturing footprint and FSSAI compliance integration. These three entities represent divergent strategic postures: technology licensing and portfolio diversification for the globals, versus distribution corridor dominance and regulatory-first formulation for the domestic leader.
| Leading Market Players |
|---|
| Grupo Bimbo |
| Kellogg's |
| Nestle SA |
| General Mills |
| Mondelez |
| The Garden Company Limited |
| Campbells Soup Company |
| Barilla Group |
| Britannia Industries Ltd |
| Others |
Value Chain & Pricing Dynamics
FSSAI fortification mandates and JIS quality benchmarks simultaneously gate supplier qualification and enable price stratification across the Asia-Pacific baked food and cereals landscape. Certification compliance creates tiered entry barriers where domestic millers command premium positioning over uncertified imports.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts between multinational manufacturers and institutional food-service buyers across Southeast Asian megacities. Three-tier pricing separates certified organic formulations from standard fortified products from economy private-label alternatives. Price differentiation hinges on FSSAI compliance status and cold-chain delivery capability. Pricing pressure stems from wheat import dependency exposing margins to currency volatility. Retail outlets in Vietnam and Indonesia exhibit highest price sensitivity; Japanese subscription-based direct-to-consumer channels show lowest sensitivity.
Supply Chain Analysis
Australia and the Black Sea region anchor wheat grain supply for Southeast Asian millers, while China and India dominate regional flour processing capacity. Raw material flows draw from Australian bulk grain terminals, Ukrainian port logistics, and domestic Indian procurement pools. Single-source vulnerability concentrates in Black Sea shipping route disruptions. Distribution runs through Shanghai's container terminals for ingredient imports and Singapore's transshipment hub for intra-regional flour redistribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics dynamics are reshaping competitive positioning as subscription-based replenishment and direct-to-consumer channels displace traditional retail shelf competition. Interoperability between cold-chain logistics networks and home-delivery platforms creates new ecosystem control points.
For Market Incumbents: Secure fortified premix supply chain integration to defend against emerging domestic millers capturing FSSAI-mandated demand. Lock in coastal manufacturing footprint advantages through capacity modernization in Karnataka and Tamil Nadu corridors. Certification speed remains the critical lever against regional bakery chains adopting compact production systems.
For New Entrants and Emerging Players: FSSAI fast-track certification creates immediate access to India's standardized formulation demand. Target gluten-free ingredient systems in South Korean and Australian urban centers where allergen-certified products command disproportionate margins. Leverage direct-to-consumer platform partnerships to bypass supermarket slotting fee barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across compact active fermentation technology deployments. Long-term viability favors acquisition targets with coastal manufacturing proximity and regulatory certification integration. Monitor ASEAN harmonization negotiation progress as inflection indicator for cross-border supply chain consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Network Expansion | Temperature-controlled distribution unlocks tier-two city penetration in China's eastern seaboard provinces. |
| Subscription Platform Development | Direct-to-consumer replenishment captures recurring revenue from Japan's aging demographic segments. |
| Fortification Compliance Integration | FSSAI-certified premix supply chains secure standardized demand across Indian processing hubs. |
| Compact Production System Adoption | Active fermentation miniaturization enables urban facility localization without suburban plant investments. |
| Gluten-Free Certification Investment | National allergen standards unlock premium positioning in South Korean and Australian specialty retail. |
Study Parameters
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. The research team conducted structured discussions with bakery operations managers, flour mill procurement leads, supermarket category buyers, cold-chain logistics coordinators, and FSSAI compliance officers. Secondary validation drew from customs trade databases, FSSAI fortification guidelines, GB standards documentation, JIS quality benchmark publications, and Nielsen retail audit data. Bottom-up segment sizing triangulated against top-down macroeconomic consumption trends.
Sensitivity analysis frameworks tested volume and value projections across the modeling period under varying wheat price and currency volatility assumptions. Segmentation dimensions include product type, distribution channel, ingredient certification tier, and end-user concentration. CAGRs were derived from trend extrapolation calibrated to historical consumption patterns and regulatory implementation timelines. Forecast inputs incorporated cold-chain infrastructure buildout schedules and urbanization velocity across Southeast Asian megacities.
Underlying assumptions cover sustained FSSAI enforcement continuity and ASEAN harmonization negotiation progress, with deviation risk concentrated in Black Sea supply disruptions and GB standards migration testing requirement changes. Recalibration cycles align with material shifts in fortification mandate scope and cold-chain network penetration milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bakery Premixes Market
Bakery Products
Baking Mixes Market
Bakery Products
Wedding Cakes Market
Bakery Products
Ready-To-Finish Bakery Products Market
Bakery Products
Banana Bread Market
Bakery Products
Soft Biscuit Market
Bakery Products
Global Cake Mix Market
Bakery Products
Bakery Contract Manufacturing Market
Bakery Products
Toasted Flour Market
Bakery Products
Sourdough Market
Bakery Products
Dough Whitener Market
Bakery Products
Low Fat Bran Muffins Market
Bakery Products
Muffins Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
Low Calorie Rice Cake Market
Bakery Products
Diabetic Bakery Products Market