
 Middle East and Africa Free-From Food Market | 2026-2036
Middle East and Africa Free-From Food Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Free-From Food Market Foresight
Market Context
South African specialty milling capacity is pivoting toward dedicated gluten-free grain processing to serve rising household demand. Danone S.A. leverages its dairy-free fermentation expertise to anchor shelf presence across Gulf retail networks. Dr. Schär AG / SPA specializes in certified gluten-free baked goods and controls distribution through pharmacy-linked specialty channels in the region.
Technical Definition and Segments
Free-from food comprises formulated products excluding specific allergens or ingredients, manufactured under segregated production lines with validated cleaning protocols and ppm-level contaminant thresholds. Gluten-free formulations rely on alternative starch matrices from sorghum, teff, or rice to replicate viscoelastic dough properties. Dairy-free milk alternatives lead product type momentum due to lactose intolerance prevalence across Middle Eastern and African populations. Sugar-free segments occupy niche pharmacy and diabetic-care channels with premium positioning. Supermarkets dominate distribution channel volume, though online retail registers the fastest route expansion as fulfillment infrastructure matures.
Regulatory Outlook
South Africa's Department of Health mandates comprehensive allergen labeling under foodstuffs regulations, while Gulf Cooperation Council standardization bodies enforce ingredient disclosure for cross-border trade. Saudi Arabia's SFDA and the UAE's MOHAP both administer import registration and halal-certification overlays that shape product reformulation requirements. Stakeholders must monitor evolving GCC technical regulations and national allergen threshold harmonization to secure sustained market access.
Market Dynamics
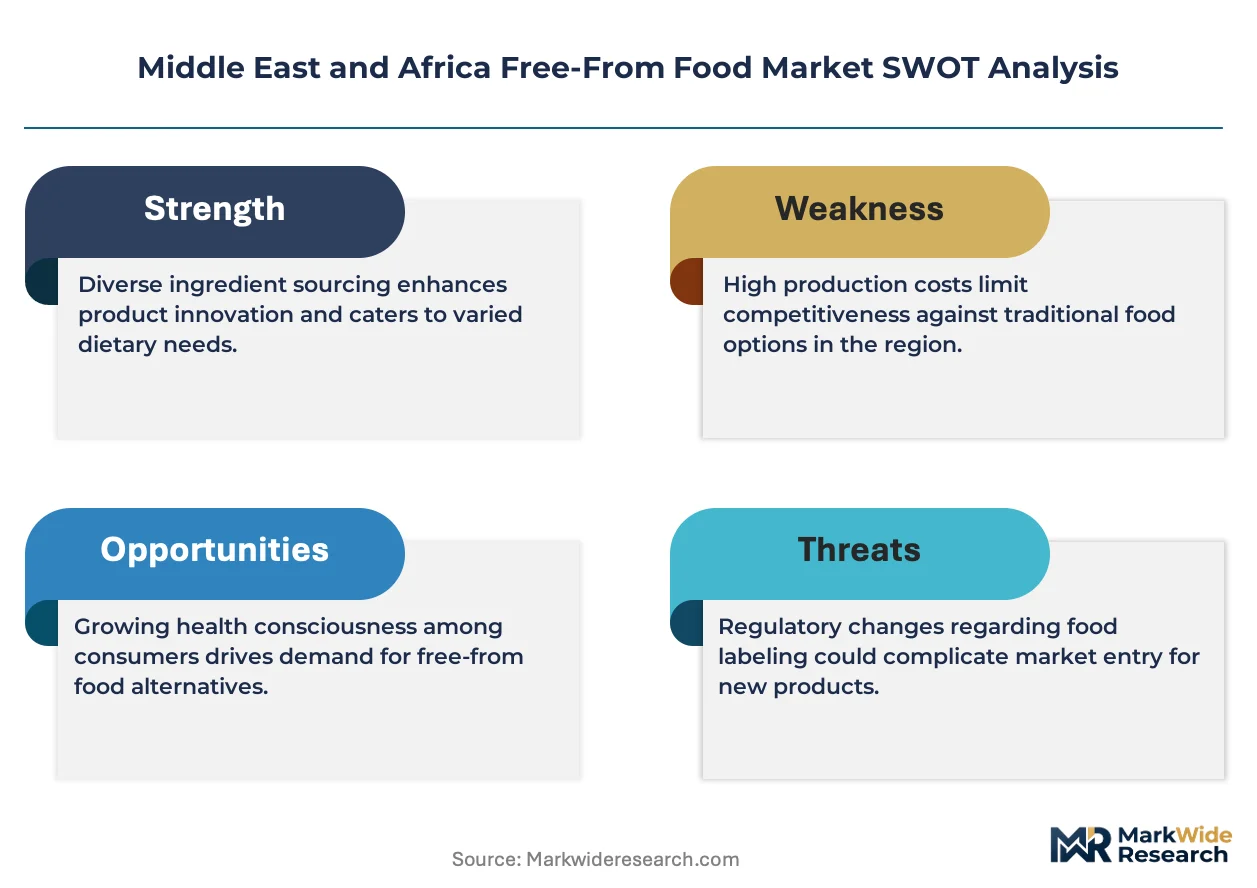
Specialty milling capacity across South Africa is pivoting toward dedicated gluten-free grain processing, creating supply-side bottlenecks as household demand outpaces certified production infrastructure.
Growth Catalysts
- South Africa's allergen labeling mandate:The Department of Health enforces comprehensive disclosure standards that build consumer trust and accelerate retail shelf expansion for verified free-from products.
- Teff and sorghum processing innovation:Alternative starch matrices now replicate viscoelastic dough properties, enabling bakery segment penetration previously blocked by texture limitations.
- UAE expatriate concentration:Dubai and Abu Dhabi host dense populations seeking specialized nutrition, concentrating demand pull for dairy-free and gluten-free alternatives.
Market Restraints
- Segregated production line capex:Validated cleaning protocols and ppm-level contaminant thresholds require dedicated facility investment that smaller regional millers cannot absorb.
- GCC import registration friction:Saudi Arabia's SFDA and UAE's MOHAP administer overlapping halal-certification and allergen disclosure requirements that delay product launches.
- Sugar alcohol substitution ceiling:Maltitol and erythritol face digestive tolerance limits among Middle Eastern diabetic consumers, capping sugar-free segment expansion.
Strategic Opportunities
- Nigeria's underpenetrated urban corridors:Lagos and Kano present white space for pharmacy-linked specialty channels serving lactose-intolerant populations without established local competition.
- Online retail fulfillment maturation:Last-mile infrastructure investments across Gulf Cooperation Council states enable direct-to-consumer models bypassing traditional supermarket gatekeepers.
- Dual halal-allergen certification convergence:Products achieving both GCC standardization body approval and national allergen thresholds command premium positioning in cross-border trade.
Industry Challenges
- Food safety auditor scarcity:Validated cleaning protocol certification requires specialized third-party verification that regional inspection bodies struggle to staff at required throughput.
- Legacy ERP integration with traceability systems:Segregated production line documentation demands real-time ingredient tracking that existing mill software cannot accommodate without costly middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Free-From Food Market |
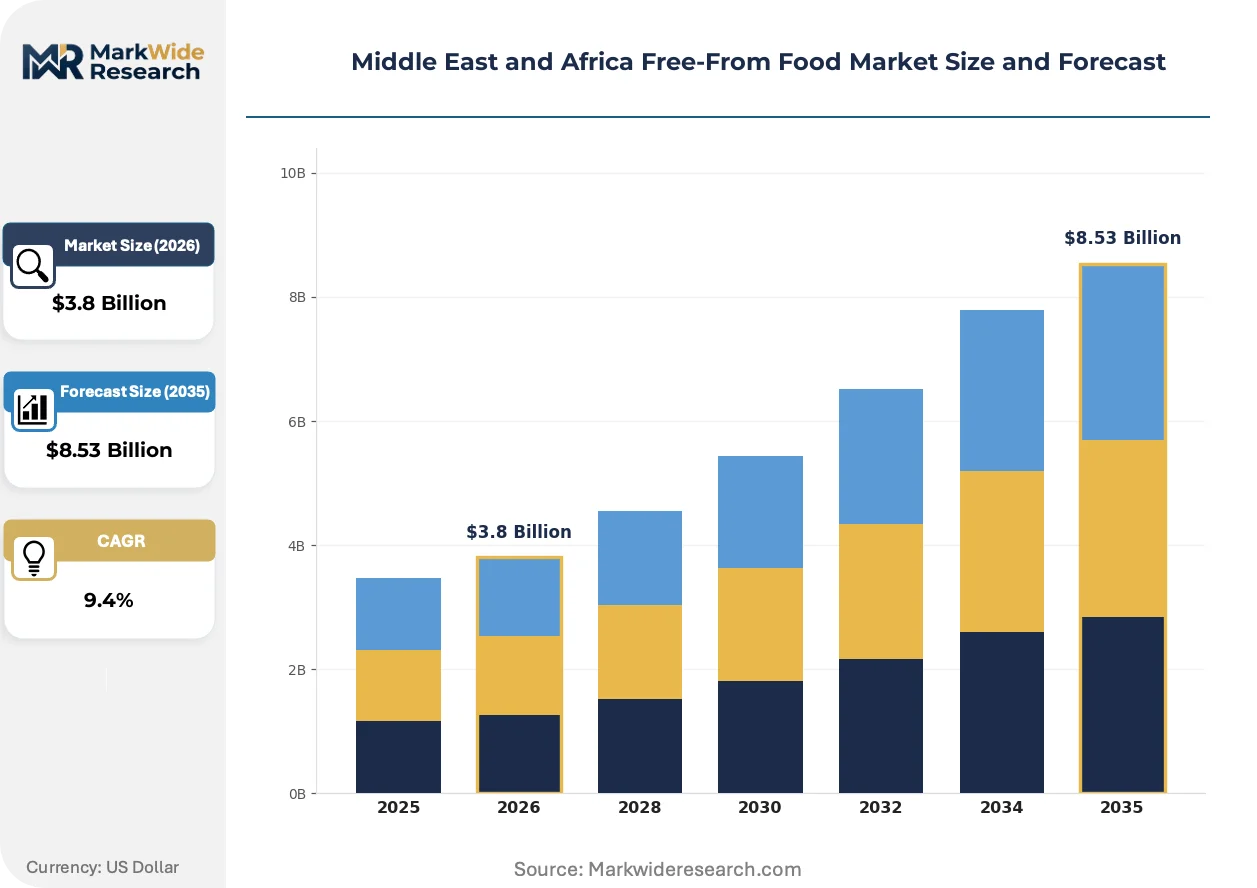
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free, Dairy-Free, Nut-Free, Sugar-Free End User: Households, Restaurants, Food Chains, Healthcare Facilities Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Direct Sales Price Tier: Premium, Mid-Range, Economy, Discount |
| Companies Covered | Danone S.A., The Hain Celestial Group, Inc., General Mills, Inc., Dr. Schär AG / SPA, Nestlé S.A., Unilever PLC, Alpro UK Ltd., Conagra Brands Inc., Archer Daniels Midland Co., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Free-From Food Market Shifts & Advancements
Formulation science and regulatory convergence are compressing product development cycles while reshaping how free-from foods reach Middle Eastern and African consumers.
Fermentation-derived dairy alternatives are expanding into traditional yogurt and cheese applications previously dominated by animal milk. Gulf retail networks now stock extended shelf-stable SKUs targeting expatriate households. This technology is expanding into ambient distribution channels that bypass cold-chain limitations across African markets.
South Africa's Department of Health continues tightening allergen threshold harmonization with Codex Alimentarius frameworks. Manufacturers must reformulate existing products to meet stricter ppm limits or face delisting from major supermarket chains. Bakery and infant nutrition segments bear the heaviest compliance burden as they operate closest to current detection limits.
Pharmacy channel preference is displacing supermarket dominance for sugar-free diabetic-care products. Saudi Arabian and Emirati consumers now associate free-from claims with clinical credibility when products appear in healthcare retail settings. This behavioral shift concentrates margin capture among brands securing MOHAP or SFDA pharmacy distribution licenses.
Middle East and Africa Free-From Food Market Segmentation
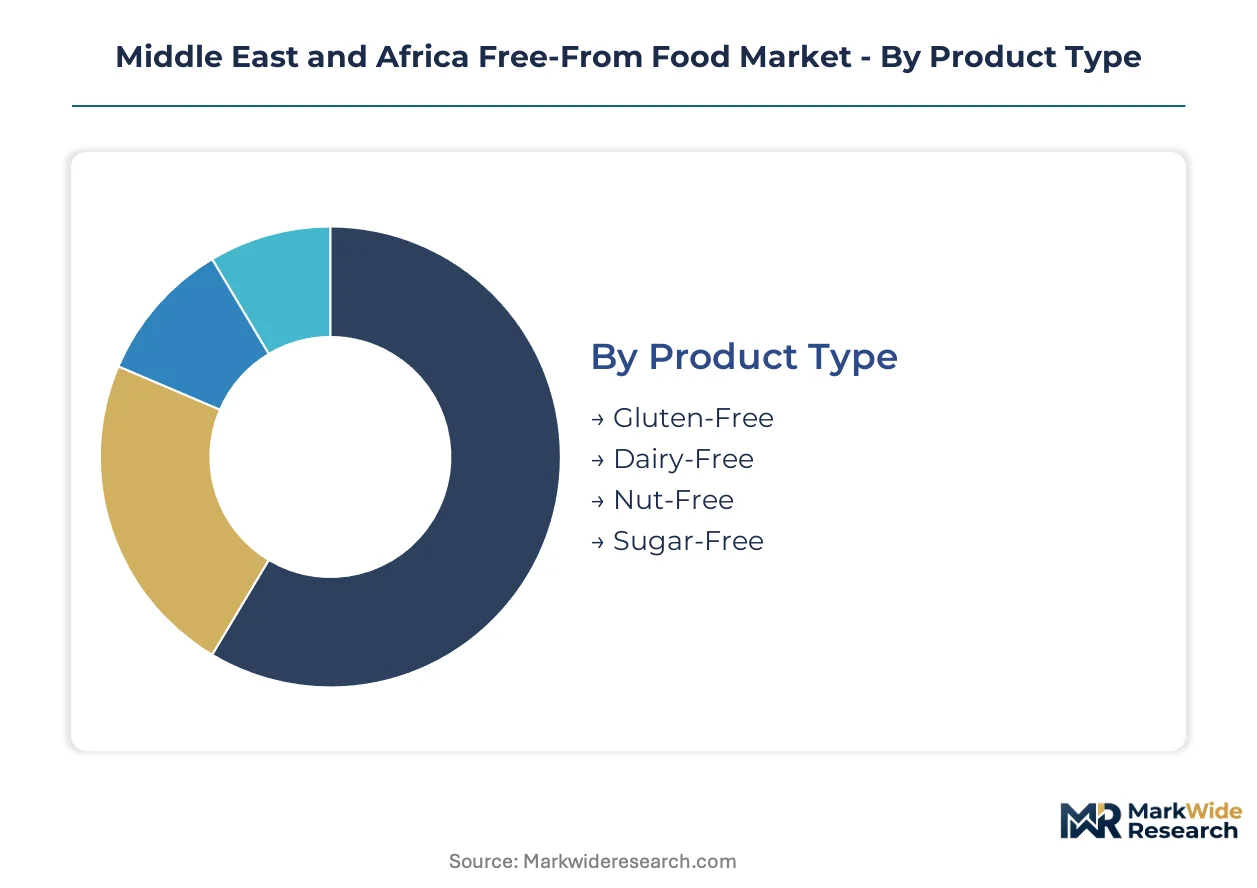
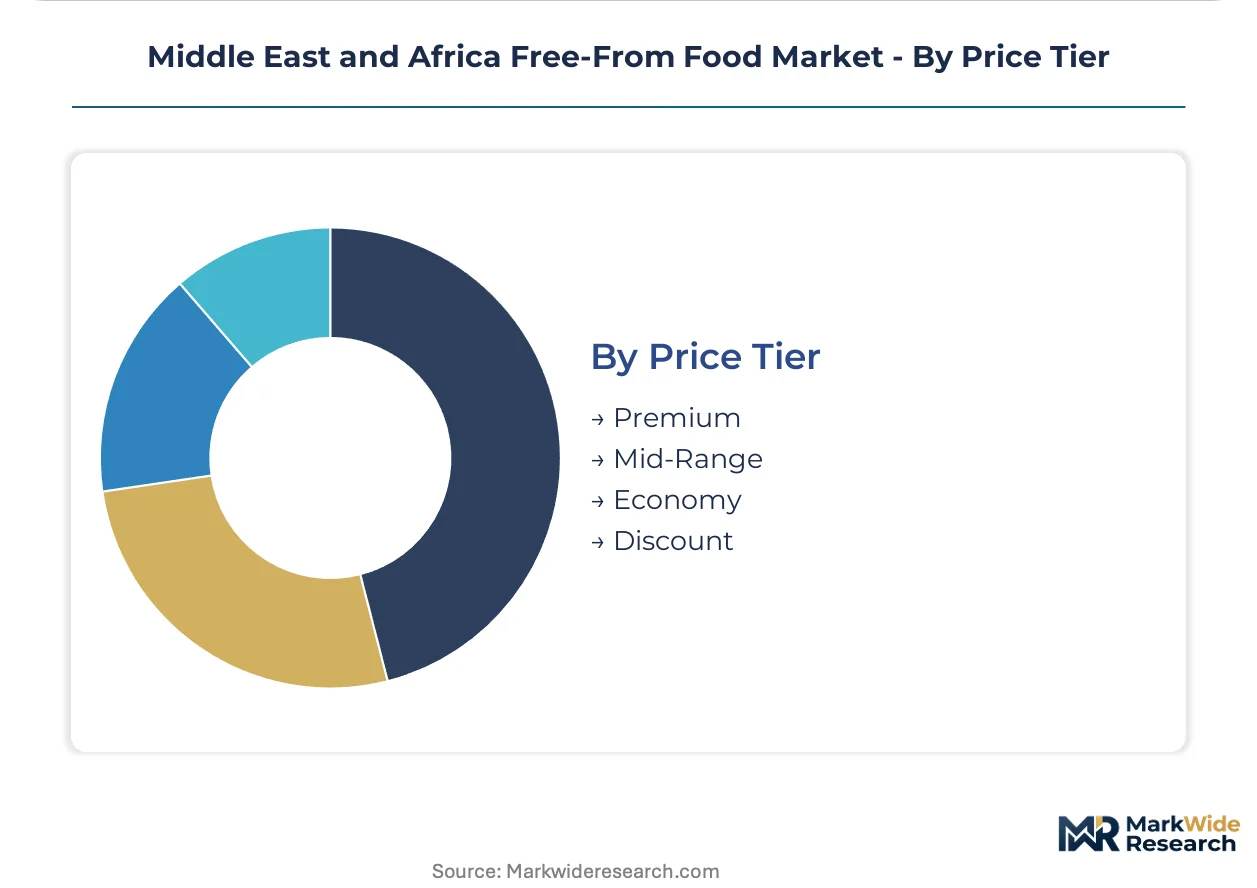
Free-from food manufacturers across the Middle East and Africa must align production capacity with four distinct demand profiles. Each segmentation axis reveals where margin pools concentrate versus where volume scales fastest.
Product Type:
Dairy-free formulations command volume leadership while gluten-free products extract premium pricing through certified production complexity.
- Dairy-Free:Fermentation-derived alternatives using oat, almond, and soy bases now replicate traditional yogurt and cheese functionality. UAE expatriate households and Saudi lactose-intolerant populations drive concentrated demand in Gulf retail networks.
- Gluten-Free:Sorghum, teff, and rice starch matrices replace wheat viscoelasticity in baked goods. South African households seeking celiac-safe options absorb specialty milling capacity as the Department of Health tightens ppm thresholds.
- Nut-Free:Segregated production protocols exclude cross-contamination risks for anaphylactic consumers. School and healthcare procurement channels in the UAE specify nut-free certification for institutional contracts.
- Sugar-Free:Maltitol and erythritol formulations target diabetic-care segments. Saudi Arabian and Emirati pharmacy channels now displace supermarkets for clinical-credibility positioning.
Today's leader: Dairy-Free. Tomorrow's challenger: Gluten-Free.
End User:
Household purchasing patterns diverge sharply from institutional procurement cycles across the region.
- Households:South African families and UAE expatriate residents drive repeat purchases of certified gluten-free and dairy-free staples. Retail shelf expansion depends on allergen labeling compliance verified by national health departments.
- Restaurants:Menu reformulation for allergen-sensitive diners requires supplier traceability systems. Lagos and Dubai hospitality sectors source verified ingredients to mitigate liability exposure.
- Food Chains:Standardized procurement across Gulf Cooperation Council outlets demands dual halal-allergen certification. Central kitchen operations impose batch-level documentation requirements on ingredient vendors.
- Healthcare Facilities:Diabetic and renal diet protocols specify sugar-free and controlled-protein formulations. MOHAP-licensed pharmacy distribution now anchors clinical credibility for therapeutic nutrition products.
Households anchor current volume. Healthcare facilities are climbing the fastest as pharmacy channel preference hardens.
Distribution Channel:
Fulfillment infrastructure maturity determines which channels can handle temperature-sensitive and short-dated free-from inventory.
- Supermarkets:Gulf retail networks and South African chains dominate current volume through dedicated free-from aisle positioning. Shelf space allocation hinges on third-party allergen certification and halal compliance documentation.
- Online Retail:Last-mile investments across UAE and Saudi Arabia enable direct-to-consumer models. Cold-chain limitations in African markets restrict ambient-stable SKU expansion.
- Specialty Stores:Pharmacy-linked channels in Saudi Arabia and the UAE concentrate diabetic-care and infant nutrition sales. SFDA and MOHAP distribution licenses gate entry to this margin-rich segment.
- Direct Sales:Institutional contracts with healthcare and education facilities bypass retail markups. Traceability system integration remains a prerequisite for vendor qualification.
Supermarkets retain volume leadership. Online retail shows the steepest expansion trajectory as Gulf logistics networks mature.
Price Tier:
Certification grade and production scale separate premium positioning from economy penetration.
- Premium:Certified gluten-free and dual halal-allergen products command shelf price multiples. UAE and Saudi consumers absorb these premiums for clinical credibility and cross-border brand assurance.
- Mid-Range:Mainstream dairy-free alternatives from regional fermentation facilities occupy this band. South African retailers use mid-range positioning to bridge certified and conventional product aisles.
- Economy:Local grain milling without third-party certification serves price-sensitive Nigerian and Kenyan urban corridors. Informal distribution networks bypass formal retail gatekeepers.
- Discount:Near-date inventory and bulk formats target institutional procurement. Healthcare facilities in underpenetrated markets source discount tiers for cost-contained therapeutic feeding programs.
Premium tier captures margin. Economy tier gains share fastest as Nigerian and Kenyan urban demand scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's specialty milling infrastructure outpaces Nigeria's nascent gluten-free processing capacity by a significant margin, yet both markets face parallel constraints around certified production line investment and third-party allergen verification.
United Arab Emirates
Expatriate households in Dubai and Abu Dhabi generate concentrated demand for dairy-free and gluten-free staples. The Ministry of Health and Prevention (MOHAP) administers import registration and pharmacy distribution licensing that gates premium market access. Jebel Ali industrial zones host cold-chain logistics clusters serving Gulf retail networks with temperature-controlled free-from inventory.
Saudi Arabia
Lactose-intolerant populations and diabetic-care segments drive pharmacy channel preference for sugar-free formulations. The Saudi Food and Drug Authority (SFDA) enforces halal-certification overlays alongside allergen disclosure requirements. Riyadh and Jeddah retail corridors anchor supermarket shelf expansion for verified free-from products.
South Africa
Household adoption of certified gluten-free grains absorbs regional specialty milling capacity. The Department of Health mandates comprehensive allergen labeling under foodstuffs regulations that accelerates retail shelf expansion. Cape Town and Johannesburg industrial zones pivot toward dedicated gluten-free grain processing with validated cleaning protocols.
Nigeria
Urban corridors in Lagos and Kano present underpenetrated demand for lactose-free alternatives without established local competition. The country's national food safety regulator applies evolving import standards that shape product qualification timelines. Local grain milling without third-party certification currently serves price-sensitive segments through informal distribution networks.
Egypt
Diabetic-care and therapeutic nutrition segments concentrate demand for sugar-free formulations in Cairo and Alexandria healthcare retail. The country's national pharmaceutical regulator oversees pharmacy-linked distribution channels. Nile Delta processing clusters face cold-chain limitations that restrict ambient-stable SKU expansion.
Middle East and Africa Free-From Food Market Competitive Landscape
European producers anchor the premium certified tier; Gulf-based specialists hold pharmacy distribution licenses. The vendor base splits between multinational fermentation facilities with dairy-free expertise and dedicated gluten-free millers with segregated production infrastructure. Three archetypes dominate: scale-driven multinationals with Gulf retail network access, certified specialists controlling pharmacy channels, and regional millers serving economy segments. Competitive moves concentrate on dual halal-allergen certification convergence and online retail fulfillment partnerships.
Within the scale-driven tier, Danone S.A. and Nestlé S.A. exemplify multinational fermentation capabilities, while Dr. Schär AG / SPA occupies a distinct position as a certified gluten-free specialist with pharmacy-linked distribution expertise.
| Leading Market Players |
|---|
| Danone S.A. |
| The Hain Celestial Group, Inc. |
| General Mills, Inc. |
| Dr. Schär AG / SPA |
| Nestlé S.A. |
| Unilever PLC |
| Alpro UK Ltd. |
| Conagra Brands Inc. |
| Archer Daniels Midland Co. |
| Others |
Supply & Pricing Matrix
Specialized food safety auditors in South Africa and the Gulf Cooperation Council states command wage premiums that compress mid-range pricing spreads between certified gluten-free products and informal economy alternatives. Labor-cost differentials between these certified production zones and unverified Nigerian milling corridors create tiered pricing architectures that segment buyers by risk tolerance and clinical need.
Pricing Analysis
Capacity additions in South Africa's Western Cape are reshaping price floors for certified gluten-free grains as dedicated facility investment accelerates. Three-tier pricing structure across premium, standard, and economy levels separates dual halal-allergen certified imports from regional fermentation-based dairy alternatives and unverified local grain milling. Price differentiation stems from certification grade and volume scale, with South African Department of Health ppm compliance commanding shelf price multiples. Cost compression in the economy tier is intensifying because Nigerian informal distribution networks bypass third-party verification overhead. Healthcare facilities and MOHAP-licensed pharmacy channels show least price sensitivity; household segments in Kenyan urban corridors absorb highest relative cost burden.
Supply Chain Analysis
Alternative starch matrices for gluten-free formulations rest on Ethiopian teff cultivation, South African sorghum processing, and Thai rice starch refining. Raw material dependencies include certified gluten-free grain stocks, fermentation-derived dairy bases from oat and almond sources, and sugar alcohol substitutes facing digestive tolerance constraints. Single-source vulnerability concentrates in Ethiopian teff export channels subject to regional harvest volatility. Distribution runs through Jebel Ali cold-chain clusters serving Gulf retail networks, with ambient-stable SKU expansion bypassing African cold-chain limitations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Free-From Food Market compounds steadily as regulatory convergence around allergen thresholds locks in certified production demand. Household clinical need and pharmacy channel preference create durable revenue visibility across economic cycles.
For Market Incumbents: Cement dual halal-allergen certification convergence to defend Gulf retail shelf positioning against emerging regional fermentation specialists. Prioritize backward integration into South African specialty milling capacity to secure teff and sorghum supply amid Ethiopian export volatility. Channel control through MOHAP and SFDA pharmacy distribution licenses anchors margin capture as supermarket price competition intensifies. For New Entrants and Emerging Players: Pharmacy-linked specialty channels in Lagos and Kano present underpenetrated white space for lactose-free alternatives without established local competition. Direct-to-consumer online retail models leveraging UAE and Saudi last-mile infrastructure bypass traditional supermarket gatekeepers. Target Nigerian urban household segments through ambient-stable dairy-free SKUs that circumvent African cold-chain gaps. For Investors and Strategic Acquirers: Gulf-based dairy-free fermentation specialists with MOHAP distribution licenses are the most active acquirer category in this space. Five-to-ten year viability rests on regulatory harmonization momentum and certified production capacity scarcity. Acquisition target archetype: regional millers with validated cleaning protocols and existing SFDA registration. Watch Ethiopian teff harvest yields and South African Department of Health threshold tightening as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Halal-Allergen Certification Investment | SFDA and MOHAP approval unlocks premium pharmacy channel positioning across Gulf markets. |
| Backward Integration into Teff Sourcing | Ethiopian cultivation partnerships reduce single-source exposure for gluten-free starch matrices. |
| Pharmacy Distribution License Acquisition | MOHAP-licensed channels displace supermarkets for diabetic-care and infant nutrition margin capture. |
| Ambient-Stable SKU Development | Shelf-stable fermentation technology bypasses cold-chain limitations across Nigerian and Kenyan corridors. |
| Online Retail Fulfillment Partnership | UAE and Saudi last-mile investments enable direct-to-consumer models with higher net revenue retention. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct segment-level demand estimates. Primary engagement with food safety auditors at South African certification bodies, procurement leads at UAE supermarket chains, regulatory affairs officers at Gulf health ministries, and pharmacy distribution managers at Saudi healthcare facilities supplied operational ground truth. Secondary validation drew from customs and trade data, Department of Health foodstuffs regulation filings, SFDA and MOHAP registration databases, and Nielsen retail audit coverage of Gulf Cooperation Council markets. Bottom-up production capacity assessments and top-down household expenditure surveys were reconciled through iterative triangulation.
Segment-weighting across product type, end user, distribution channel, and price tier dimensions anchored volume and value outputs throughout the forecast period. Modeled dimensions included gluten-free versus dairy-free formulation splits, household versus healthcare facility procurement patterns, supermarket versus online retail channel shares, and premium versus economy tier penetration rates. CAGRs were derived from fitted growth curves applied to certified production capacity expansion timelines and regulatory threshold implementation schedules. Industry-specific inputs encompassed South African specialty milling investment pipelines and Ethiopian teff export volume trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GCC regulatory harmonization pace and Ethiopian agricultural export policy shifts. Forecasts reflect documented assumptions around certification body staffing capacity and cold-chain infrastructure investment cadence across African markets. A small set of named triggers warrants ongoing watch: South African Department of Health ppm threshold revisions, Ethiopian teff harvest disruption events, and SFDA halal-certification processing backlogs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Low Calorie Desserts Market
Specialty Foods
Global Honey Market
Specialty Foods
Liquid Mushroom Market
Specialty Foods
Fruit Dessert Market
Specialty Foods
Moringa Products Market
Specialty Foods
Asia-Pacific Tofu Market
Specialty Foods
Military Forces Ready to Eat Meals Market
Specialty Foods
Therapeutic Dog Food Market
Specialty Foods
United States Tofu Market
Specialty Foods
Medicinal Herbs Market
Specialty Foods
Global Guilt-Free Desserts Market
Specialty Foods
Mediterranean Kimchi-Style Vegetable Culture Starters Market
Specialty Foods
Cat and Dog Food Toppers Market
Specialty Foods
Fermented Black Beans Market
Specialty Foods
Foie Gras Market
Specialty Foods
Yeast-Based Spreads Market