
 Baked Foods Market | 2026-2036
Baked Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Baked Foods Market Analysis
Subscription-based fresh bread delivery is shifting how urban consumers access daily baked goods. Grupo Bimbo leverages its route-to-market density across Latin America to sustain last-mile freshness. Mondelez International anchors its competitive position through R&D intensity in shelf-stable snacking formats. Associated British Foods differentiates via vertical integration from milling to retail bakery.
Baked foods comprise cereal-based products subjected to dry-heat processing, typically at 150–230°C, where starch gelatinization and Maillard browning develop texture, flavor, and shelf stability for human consumption. Bread and pastries occupy mature volume positions with margin compression in commodity segments, while gluten-free and whole-grain ingredient categories capture premium pricing from health-conscious consumer segments. Online distribution channels are expanding fastest among digital-native shoppers, though supermarkets retain dominant throughput for mass-market cookies and cakes.
FDA sodium-reduction targets and EU Green Deal farm-to-fork standards are reshaping formulation requirements and wheat sourcing protocols for multinational baked-goods producers. BIS fortification mandates in India and EFSA additive reviews in Europe create divergent compliance matrices that fragment product portfolios. Stakeholders must monitor how clean-label ingredient costs interact with energy-intensive oven operations to preserve margin structures.
Market Dynamics
Clean-label reformulation pressure from EFSA and FDA sodium-reduction guidance is forcing industrial bakeries to re-engineer formulations while maintaining shelf stability and taste profiles.
Growth Catalysts
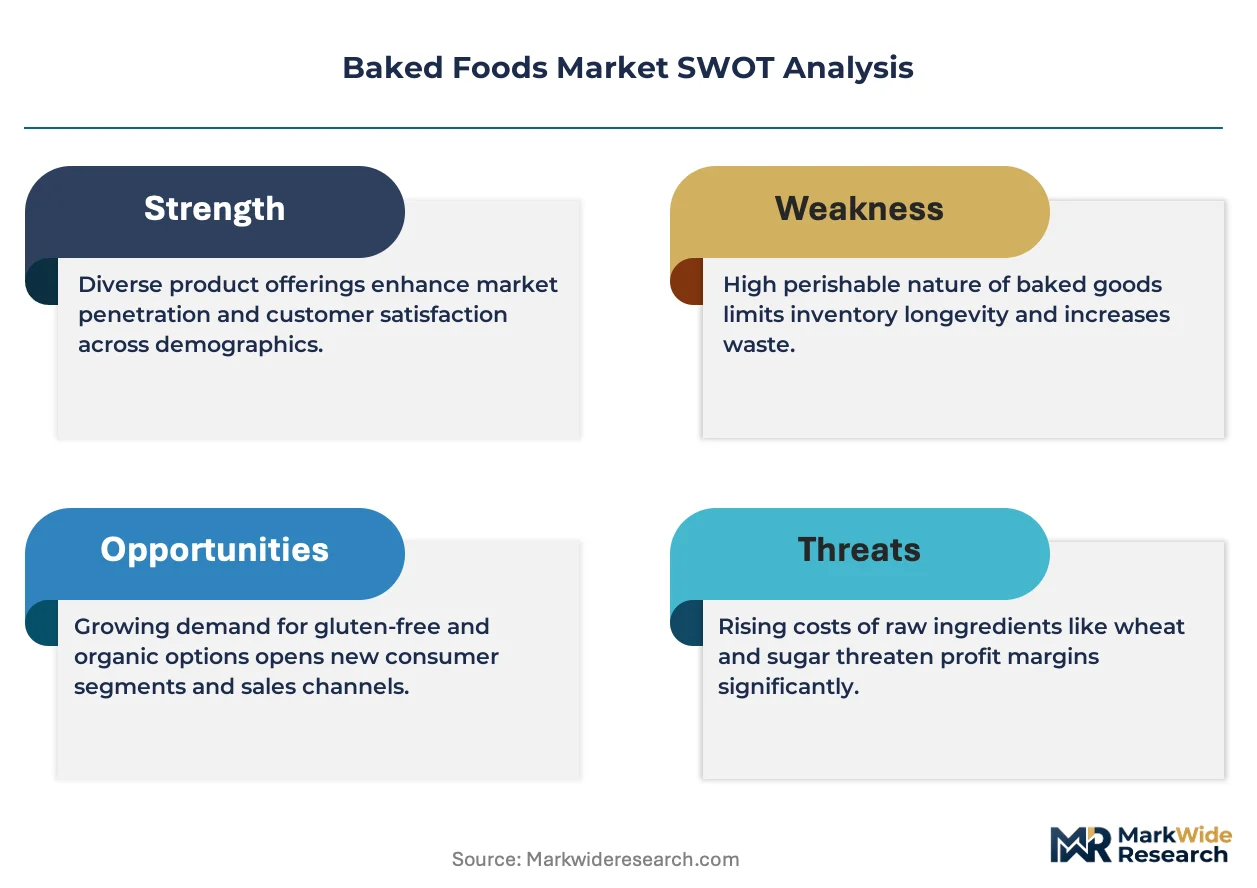
- EU Green Deal farm-to-fork standards:Wheat sourcing protocols are tightening across European supply chains, creating competitive differentiation for compliant producers.
- Artisanal bread traditions in Germany:Consumer preference for heritage baking methods is sustaining premium pricing power in mature Western European markets.
- Sourdough fermentation:Extended fermentation processes are displacing chemical preservatives in clean-label product lines across retail and foodservice channels.
Market Restraints
- Energy-intensive oven operations:Natural gas and electricity cost volatility compresses margins for continuous-process industrial bakeries operating at scale.
- Wheat supply concentration:Black Sea region export disruptions expose European millers to input price spikes and sourcing instability.
- EFSA additive reviews:Pending restrictions on emulsifiers and preservatives force costly reformulation cycles before regulatory certainty emerges.
Strategic Opportunities
- Subscription fresh bread delivery:Direct-to-consumer channels are capturing urban household recurring revenue outside traditional retail.
- Gluten-free ingredient systems:Rice, tapioca, and pulse flour blends command premium positioning in health-conscious consumer segments.
- BIS fortification mandates:India's mandatory micronutrient requirements create volume opportunities for premix suppliers and compliant manufacturers.
Industry Challenges
- Clean-label ingredient cost premiums:Natural preservatives and specialty flours inflate COGS while price elasticity limits pass-through to mass-market consumers.
- Maillard reaction control:Acrylamide mitigation requirements demand precise oven temperature management and process revalidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baked Foods Market |
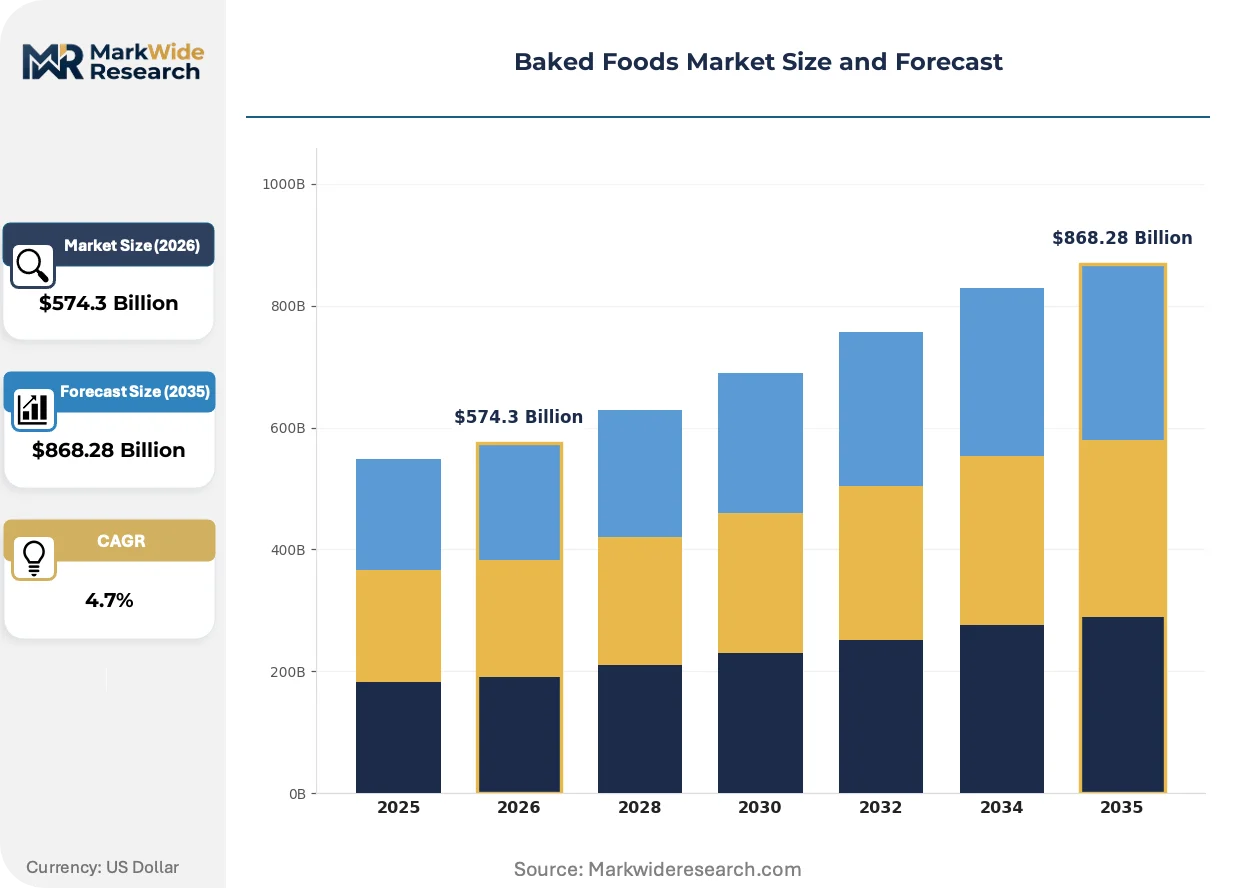
| Market Size in 2026 | $574.3 Billion |
| Market Size in 2035 | $868.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread, Pastries, Cookies, Cakes Ingredient: Wheat, Rye, Gluten-Free, Whole Grain Consumer Segment: Health-Conscious, Children, Adults, Seniors Distribution Channel: Supermarkets, Bakeries, Online, Convenience Stores |
| Companies Covered | Mondelez International, Grupo Bimbo, Associated British Foods, Kellogg Company, Flowers Foods, General Mills, Barilla Group, Britannia Industries, Arnott's Biscuits Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baked Foods Market Emerging Trajectories
Digital-native distribution models and precision fermentation ingredients are rewriting competitive boundaries between artisanal craft and industrial scale in baked goods.
Enzymatic shelf-life extension is expanding into industrial bread production as amylase and lipase systems replace calcium propionate in clean-label formulations. Mid-tier regional bakeries are adopting these enzyme platforms fastest, seeking positioning between commodity private-label and premium artisanal. The technology is expanding into frozen dough applications, enabling longer distribution radii without chemical preservatives.
EFSA's systematic re-evaluation of food additives is tightening the approved substance list for bread improvers and cake emulsifiers. Industrial formulators face compressed timelines to validate alternative ingredient systems before sunset dates remove legacy options. Western European packaged bread segments are responding with accelerated R&D partnerships between bakeries and enzyme suppliers.
Urban consumers are consolidating daily bread purchases through subscription platforms offering scheduled delivery and customizable product rotation. Traditional bakery retail in dense metropolitan areas faces volume erosion as convenience-oriented households shift to app-based ordering. This behavioral shift concentrates most visibly in German and UK cities where logistics infrastructure supports same-day freshness guarantees.
Baked Foods Market Segmentation
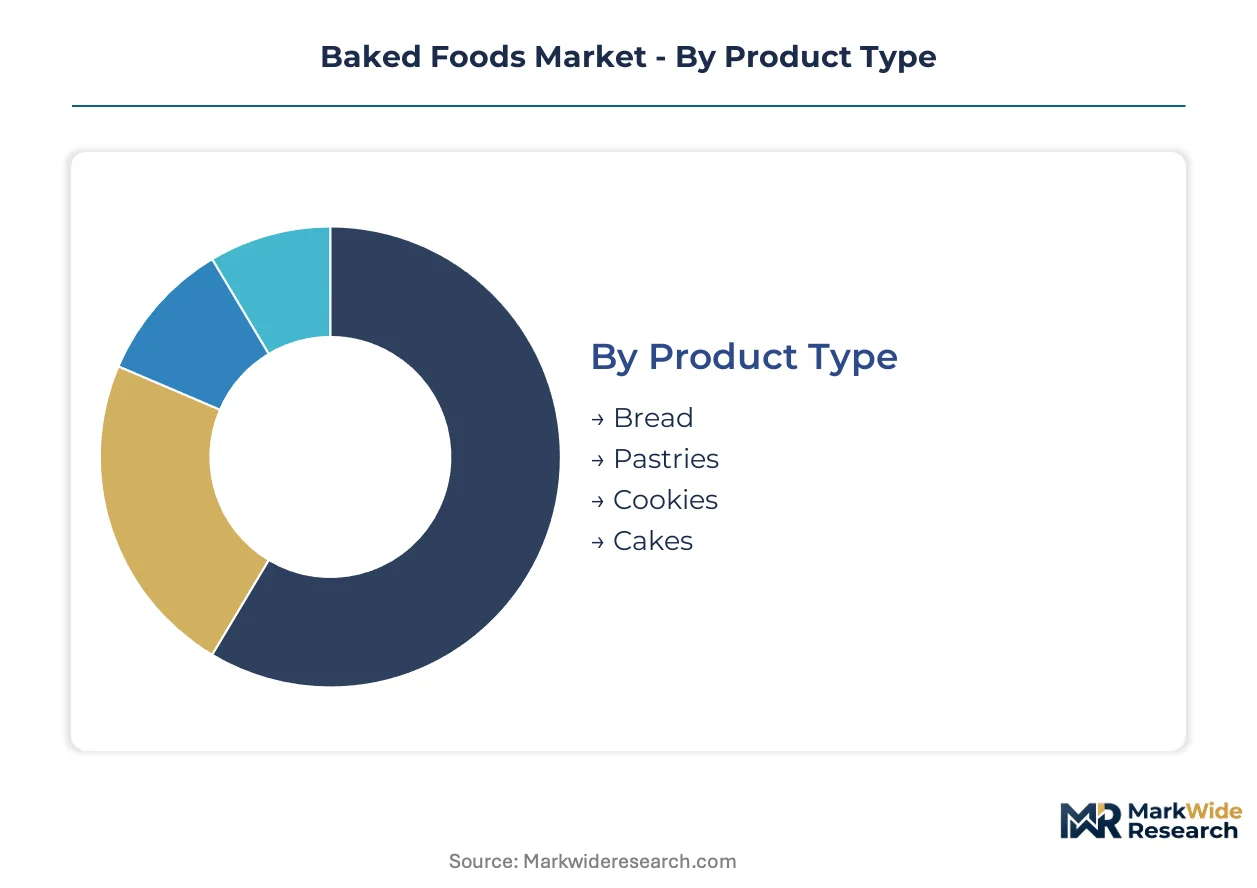
Baked foods segmentation reveals how formulation choices, ingredient sourcing, and channel access fragment commercial opportunity across distinct consumer occasions and price tiers. Product type and ingredient categories drive the deepest margin differentiation, while distribution channel selection determines geographic reach and freshness guarantees.
Product Type:
Standalone daily staples dominate volume procurement cycles, while embedded snacking formats integrate into broader foodservice and retail meal solutions.
- Bread:Daily consumption staple produced through continuous-process industrial baking or artisanal batch methods, with sourdough and clean-label variants commanding shelf price premiums in German and UK urban markets. German foodservice operators are expanding artisanal bread procurement as EFSA sodium-reduction guidance forces reformulation of traditional recipes.
- Pastries:Laminated dough products including croissants and Danish requiring controlled fermentation and butter layering, where extended production cycles limit industrial scale and preserve regional craft differentiation. Demand concentrates in French and Belgian breakfast channels where heritage preparation methods sustain premium positioning against commoditized alternatives.
- Cookies:Shelf-stable snacking formats with extended distribution radii and lower perishability constraints, enabling centralized production and private-label penetration.
- Cakes:Occasion-driven purchases with higher margin per unit but concentrated demand around celebrations and seasonal peaks, limiting inventory turnover velocity.
Bread leads volumes today; pastries are gaining share fastest in premium urban channels.
Ingredient:
Cost tier stratification separates commodity grain inputs from specialty and restricted-diet formulations that capture health-motivated spending.
- Wheat:Standard bread wheat and high-protein hard varieties constitute the baseline input for mass-market production, with Black Sea supply disruptions exposing European millers to price volatility and sourcing instability.
- Rye:Dense, low-gluten grain traditional to Northern and Eastern European baking, requiring adapted fermentation protocols and delivering distinctive flavor profiles that resist commodity substitution.
- Gluten-Free:Rice, tapioca, and pulse flour blends formulated for celiac and health-conscious consumers, commanding significant price premiums despite higher ingredient costs and processing complexity.
- Whole Grain:Bran and germ-inclusive flours responding to FDA dietary guidance and EU nutrition claims regulation, with fiber content positioning against refined alternatives in health-focused retail sets.
Wheat dominates tonnage throughput; gluten-free blends are expanding most quickly in North American and Western European premium aisles.
Consumer Segment:
Application context determines whether purchases serve household replenishment, child-targeted snacking, or age-specific nutritional requirements.
- Health-Conscious:Consumers prioritizing clean-label ingredient decks, reduced sodium, and functional nutritional claims, driving reformulation investment across branded and private-label portfolios.
- Children:Portion-controlled formats with fortified micronutrient profiles, shaped products, and lower sugar variants responding to parental purchasing criteria and school nutritional standards.
- Adults:Core household bread buyers balancing convenience, price sensitivity, and emerging interest in artisanal quality in daily staple categories.
- Seniors:Soft-texture and nutrient-dense formulations addressing chewing difficulty and elevated protein requirements in aging populations.
Adult household purchasers anchor volume today; health-conscious segments are climbing the fastest as clean-label penetration deepens.
Distribution Channel:
Supply concentration and freshness requirements shape which channels control mass throughput versus premium positioning.
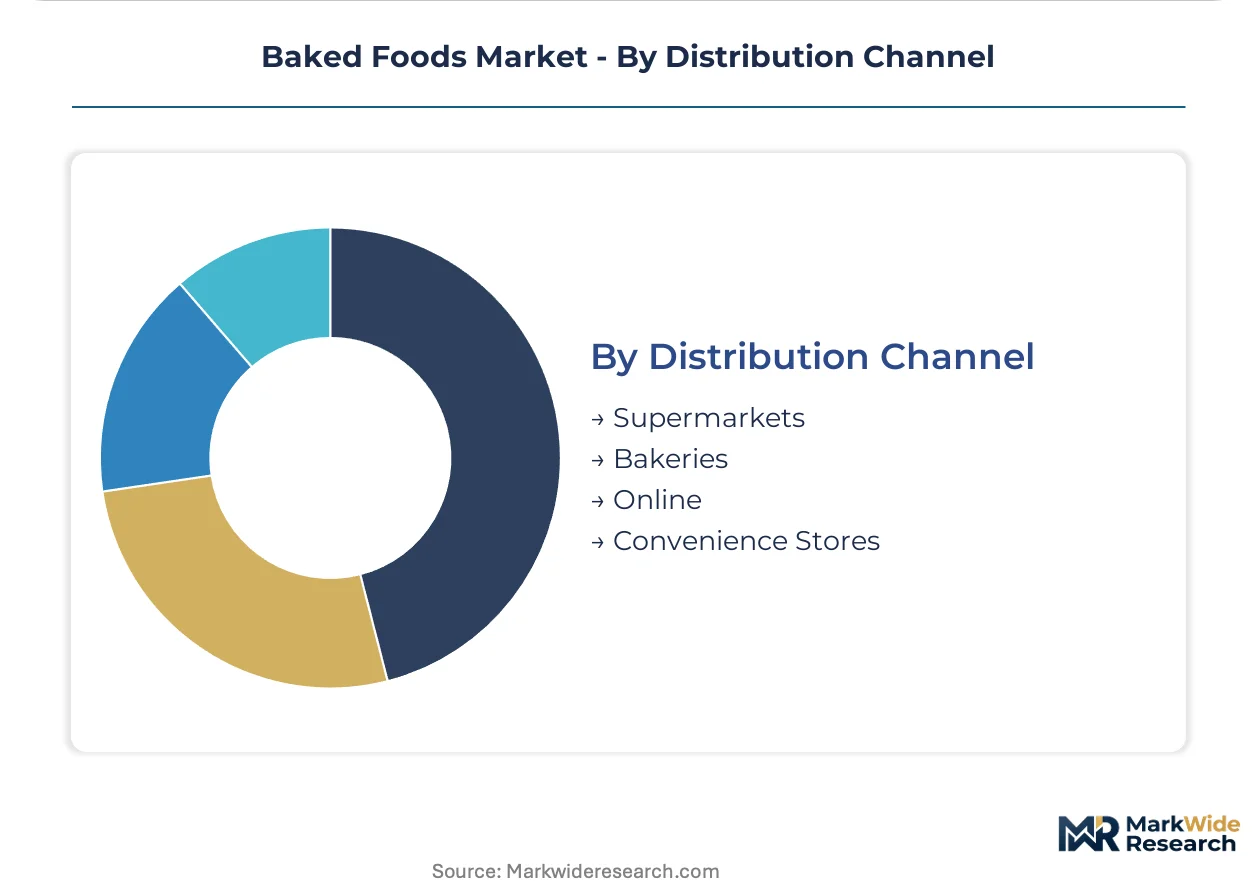
- Supermarkets:Mass-market cookies and cakes retain dominant throughput here, with centralized bakery operations and extended shelf-life packaging enabling scale efficiency.
- Bakeries:Fresh-daily production with limited distribution radius, preserving texture and aroma advantages that command price premiums in dense metropolitan areas.
- Online:Subscription-based fresh bread delivery is capturing urban household recurring revenue outside traditional retail, with logistics infrastructure determining same-day freshness feasibility.
- Convenience Stores:Impulse and immediate-consumption occasions with limited assortment depth, prioritizing wrapped, extended-shelf-life formats over fresh bakery.
Supermarkets retain the largest volume position; online channels are gaining share fastest among digital-native urban consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between EFSA additive reviews and FDA sodium-reduction timelines is creating cost-of-compliance arbitrage that favors production relocation toward jurisdictions with stable formulation rules. Industrial bakeries are reassessing footprint strategies as EU Green Deal sourcing mandates tighten wheat traceability requirements.
Germany
Artisanal bread traditions sustain premium pricing in Munich and Berlin metropolitan corridors. EFSA's systematic re-evaluation of bread improvers forces accelerated reformulation partnerships between regional bakeries and enzyme suppliers. The Baden-Württemberg industrial cluster hosts specialized fermentation technology providers serving clean-label transition demands.
United States
FDA dietary guidance on sodium reduction drives reformulation investment across branded and private-label bread portfolios. The agency's acrylamide mitigation recommendations demand precise oven temperature management in continuous-process facilities. Chicago and Minneapolis-St. Paul anchor Midwest grain milling and industrial baking concentration.
India
BIS fortification mandates create volume opportunities for premix suppliers and compliant manufacturers in packaged bread segments. FSSAI enforcement of micronutrient requirements expands addressable market for fortified bakery products. Maharashtra and Gujarat host the densest concentration of industrial biscuit and bread production capacity.
Brazil
ANVISA food additive regulations shape formulation choices for multinational producers operating in Mercosur trade zones. Wheat import dependency exposes millers to currency volatility and Black Sea supply disruptions. São Paulo state concentrates industrial baking capacity serving Southeast urban demand corridors.
United Kingdom
Subscription-based fresh bread delivery platforms capture recurring revenue from London and Manchester urban households. FSA acrylamide guidance aligns with EFSA timelines, creating formulation certainty for exporters. The Midlands baking cluster supplies national retail chains with centralized production efficiency.
Baked Foods Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational packaged goods conglomerates dominating shelf-stable cookies and cakes while regional artisan bakeries control fresh-daily metropolitan throughput. Market structure concentrates in three tiers: global scale players with R&D-intensive portfolios, mid-cap national champions leveraging route-to-market density, and fragmented local craft producers. Strategic archetypes include vertical integrators controlling milling-to-retail value chains, enzyme technology licensors enabling clean-label transitions, and subscription logistics platforms capturing direct-to-consumer recurring revenue. Dominant competitive moves encompass backward integration into specialty grain sourcing and partnerships with precision fermentation ingredient suppliers.
Within the global scale tier, Mondelez International and Grupo Bimbo exemplify divergent geographic anchoring strategies. Mondelez International occupies a position emphasizing shelf-stable snacking formats with extended distribution radii. Grupo Bimbo represents route-to-market density advantages across Latin American urban corridors. Associated British Foods sits within the vertical integration archetype, with milling-to-retail control visible in its corporate structure.
| Leading Market Players |
|---|
| Mondelez International |
| Grupo Bimbo |
| Associated British Foods |
| Kellogg Company |
| Flowers Foods |
| General Mills |
| Barilla Group |
| Britannia Industries |
| Arnott's Biscuits Holdings |
| Others |
Supply Flow & Price Mechanics
EFSA sodium-reduction mandates are forcing industrial bakeries toward enzyme-based reformulations that inflate ingredient costs while supermarket buyers resist pass-through pricing. This tension compresses margins across mid-tier producers caught between clean-label compliance demands and mass-market price ceilings.
Pricing Analysis
Retailer markup layers dominate final shelf pricing, with supermarkets capturing 25-35 percent gross margin on packaged bread versus 15-20 percent on private-label alternatives. Three-tier pricing structure across premium artisanal, standard packaged, and economy private-label segments reflects ingredient grade and freshness guarantee differentiation. Cost compression in the standard tier is intensifying as wheat futures volatility and natural gas oven costs outpace branded pricing power. Mass-market household purchasers exhibit highest price elasticity, while health-conscious urban subscribers accept premium positioning for same-day delivery freshness.
Supply Chain Analysis
Wheat supply rests on Black Sea region exports, Canadian prairie hard varieties, and Australian premium milling grades as the foundational input triad. Specialty inputs including industrial enzyme systems, pulse flour blends for gluten-free lines, and natural preservative alternatives draw from concentrated European and North American suppliers. Single-source vulnerability in Black Sea export corridors exposes millers to input price spikes when geopolitical disruptions constrain Ukrainian and Russian grain flows. Distribution runs through centralized industrial baking clusters serving supermarket networks, with direct-to-consumer subscription platforms building parallel cold-chain logistics for urban last-mile freshness.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The baked foods market functions as a stable compounder anchored by non-discretionary daily consumption patterns that sustain volume through economic cycles.
For Market Incumbents: Deploy enzymatic shelf-life extension platforms to displace chemical preservatives ahead of EFSA sunset dates. Consolidate regional milling assets to secure wheat supply certainty against Black Sea volatility. Capacity addition in Germany's Baden-Württemberg fermentation technology cluster strengthens clean-label positioning against private-label encroachment. For New Entrants and Emerging Players: Urban health-conscious subscribers represent the most penetrable buyer archetype for subscription fresh bread platforms. India's BIS-compliant fortified bread segment offers white-space volume under enforcement expansion. A direct-to-consumer app-based ordering model with customizable product rotation captures recurring revenue outside supermarket channel control. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap regional bakeries possessing route-to-market density in underserved metropolitan corridors. Five-to-ten year viability favors producers with backward integration into specialty grain sourcing and enzyme technology licensing partnerships. Watch EFSA additive review timelines as inflection triggers for accelerated M&A in compliant formulation capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme Platform Licensing | Clean-label transition partnerships with regional bakeries accelerate EFSA compliance ahead of preservative sunset dates. |
| Specialty Grain Backward Integration | Captive supply of heritage wheat varieties secures premium artisanal positioning against commodity substitution. |
| Subscription Logistics Buildout | Same-day freshness guarantees in German and UK urban corridors capture recurring revenue outside retail concentration. |
| Fortification Premix Partnership | BIS-compliant micronutrient systems unlock volume in India's mandated packaged bread expansion. |
| Energy Efficiency Retrofit | Oven heat recovery and renewable thermal systems defend margin structure against natural gas price volatility. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with industrial bakery operations directors, supermarket category buyers, enzyme supplier technical sales leads, and foodservice procurement managers with secondary validation. Regulatory filings from EFSA, FDA, and BIS anchored compliance timeline assumptions. Trade data from Eurostat and customs records informed wheat sourcing pattern analysis. SEC 10-K disclosures from publicly traded baked goods producers provided margin structure benchmarks. Bottom-up volume modeling and top-down category spend estimates were triangulated for convergence.
Segment-weighting approaches distributed value across product type, ingredient category, consumer segment, and distribution channel dimensions. CAGRs were derived from trend-line extrapolation of historical volume and value trajectories, adjusted for regulatory phase-in effects and channel shift velocities. Wheat price forecasting inputs incorporated futures curve analysis and Black Sea supply risk scenarios. Enzyme adoption curves were modeled against EFSA additive review publication schedules.
Inputs from regulatory databases and trade statistics were available through the study window; gaps in real-time foodservice operator procurement data introduce uncertainty bands around out-of-home consumption estimates. Forecasts reflect documented assumptions about reformulation cost pass-through elasticity and subscription platform penetration rates. Supply disruption scenarios and regulatory timeline delays constitute specific revision triggers. A small set of EFSA additive review outcomes, Black Sea export corridor stability, and BIS enforcement intensity metrics warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Oman Frozen Bakery Products Market
Bakery Products
Fortified Bakery Market
Bakery Products
Middle East and Africa Sweet Biscuits Market
Bakery Products
North America Bakery Products Market
Bakery Products
Baking Mix, Base and Concentrate Market
Bakery Products
Pancake Mixes Market
Bakery Products
Europe Zwieback Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
Biscuit Mixes Market
Bakery Products
Low-Calorie Breakfast Muffins Market
Bakery Products
Pizza Crust Market
Bakery Products
Bread Improver Market
Bakery Products
Laminated Dough Market
Bakery Products
Sourdough Market
Bakery Products
Instant Cake Emulsifier Market