
 Europe Sourdough Market | 2026-2036
Europe Sourdough Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sourdough Market Foresight
Artisan bakery demand is consolidating across Europe as consumer preference shifts toward slow-fermented, additive-free bread. Puratos leverages its sourdough library and fermentation expertise to anchor supply relationships with mid-sized European bakeries. Lesaffre competes through its controlled fermentation technology and geographic reach across Western and Eastern Europe. IREKS GmbH specializes in region-specific starter cultures that differentiate its portfolio in German and Scandinavian markets.
Sourdough is a naturally leavened bread produced through the fermentation of dough using wild yeasts and lactic acid bacteria, typically requiring 12 to 24 hours of bulk fermentation to develop its characteristic acidity and crumb structure. The process relies on a living starter culture maintained through regular feeding cycles, with commercial producers now standardizing pH targets between 3.8 and 4.2 for consistent flavor profiles. Artisan and specialty product types command premium positioning in retail channels where provenance labeling and organic certification drive margin pools. Traditional formats dominate volume in German and Austrian markets, while commercial sourdough concentrates in food service and supermarket private-label programs.
EU Green Deal frameworks and EFSA labeling requirements shape ingredient transparency mandates across the European sourdough supply chain. REACH compliance affects starter culture substrates and processing aids used in industrial fermentation. Bakers must monitor how CSRD reporting obligations extend to agricultural suppliers and how EMA-adjacent food contact regulations evolve for packaging materials in direct bread contact.
Market Dynamics
EU Green Deal sustainable food system targets are forcing commercial bakers across Europe to restructure ingredient sourcing and fermentation processes, compressing margins for conventional producers while rewarding certified organic and regenerative supply chains.
Growth Catalysts
- EU Green Deal mandates:Binding targets for sustainable food systems accelerate baker adoption of certified organic flours and regenerative grain sourcing across Germany, France, and Italy.
- Artisan bakery expansion:Mid-sized craft bakeries in Scandinavia and the Netherlands scale production capacity to meet retail demand for slow-fermented, additive-free bread formats.
- Consumer preference rotation:German and Austrian households sustain above-average per-capita sourdough consumption, anchoring volume demand for traditional rye-wheat hybrid starters.
Market Restraints
- Input cost volatility:Organic wheat and specialty rye prices fluctuate with weather-driven harvest variability across Eastern European grain belts.
- Supply concentration risk:Starter culture production clusters in Southern Germany and Northern France, creating single-source dependency for industrial bakers.
- Technical limitation:Maintaining live starter consistency across temperature-variable commercial kitchens requires specialized climate control infrastructure.
Strategic Opportunities
- Underpenetrated geographies:Poland and Romania exhibit low sourdough penetration relative to Western Europe, offering first-mover positioning for regional starter culture suppliers.
- Regulatory tailwind:EFSA clean-label guidance and CSRD supply-chain disclosure rules favor transparent, short-ingredient-list products in supermarket private-label programs.
- Distribution innovation:Direct-to-bakery starter subscription services bypass traditional ingredient distributors, capturing margin from small urban craft producers in Barcelona and Copenhagen.
Industry Challenges
- Skill gap in fermentation science:Commercial bakeries struggle to recruit trained sourdough specialists capable of managing multi-day bulk fermentation schedules.
- Certification timeline compression:Organic and PDO regional certification processes delay product launches by 12-18 months, freezing working capital in pipeline inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sourdough Market |
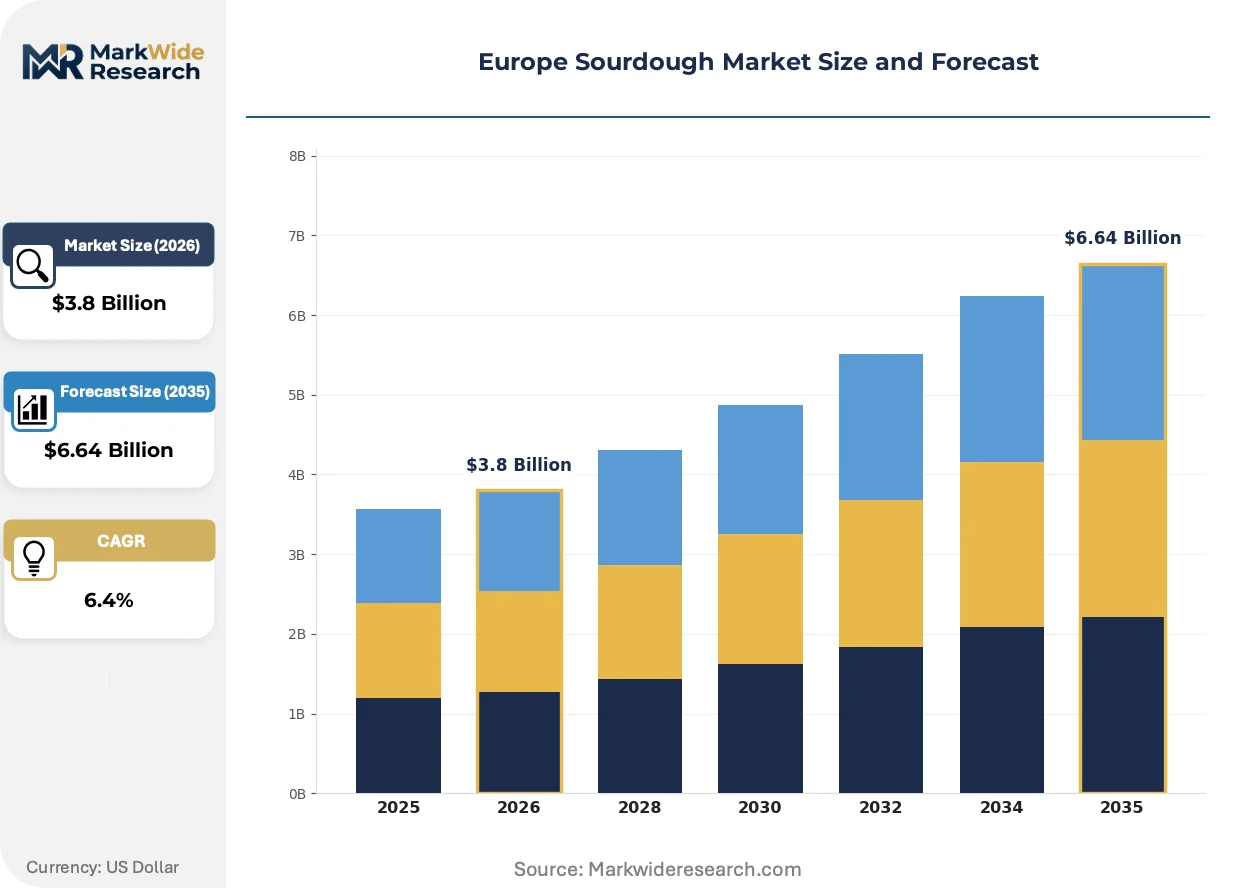
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Artisan, Commercial, Specialty Distribution Channel: Retail, Online, Food Service, Wholesalers End User: Bakeries, Restaurants, Supermarkets, Households Packaging Type: Loaves, Rolls, Baguettes, Slices |
| Companies Covered | Puratos, Lesaffre, IREKS GmbH, Ernst Böcker GmbH & Co. KG, Lallemand, GoodMills Group, Aryzta, Philibert Savours, Dr. Otto Suwelack Nachf. GmbH & Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sourdough Market Shifts & Advancements
Controlled fermentation technology and digital monitoring systems are reshaping how European bakeries standardize sourdough production, replacing intuition-based methods with pH and temperature telemetry that ensures batch consistency.
Dried and stabilized liquid starter cultures is overtaking traditional fresh starter maintenance in mid-scale commercial bakeries. German and Austrian industrial bakeries adopt these shelf-stable formats to reduce labor costs and eliminate daily feeding cycles. The shift is compressing demand for on-site fermentation expertise while expanding private-label sourdough availability in discount retail channels.
REACH compliance requirements for processing aids and starter substrates are tightening disclosure obligations across the European supply chain. ECHA substance evaluation processes now extend to enzymatic fermentation accelerators used in accelerated sourdough programs. French and Italian ingredient suppliers are reformulating product lines to eliminate contested additives ahead of 2025 registration deadlines.
Retail procurement patterns are rotating toward provenance-verified and organic-certified sourdough lines. Supermarket buyers in Germany and the Netherlands now require blockchain-traceable grain sourcing and third-party organic certification as baseline listing criteria. This preference shift is marginalizing conventional sourdough concentrates in favor of transparent supply-chain products with regional terroir labeling.
Europe Sourdough Market Segmentation
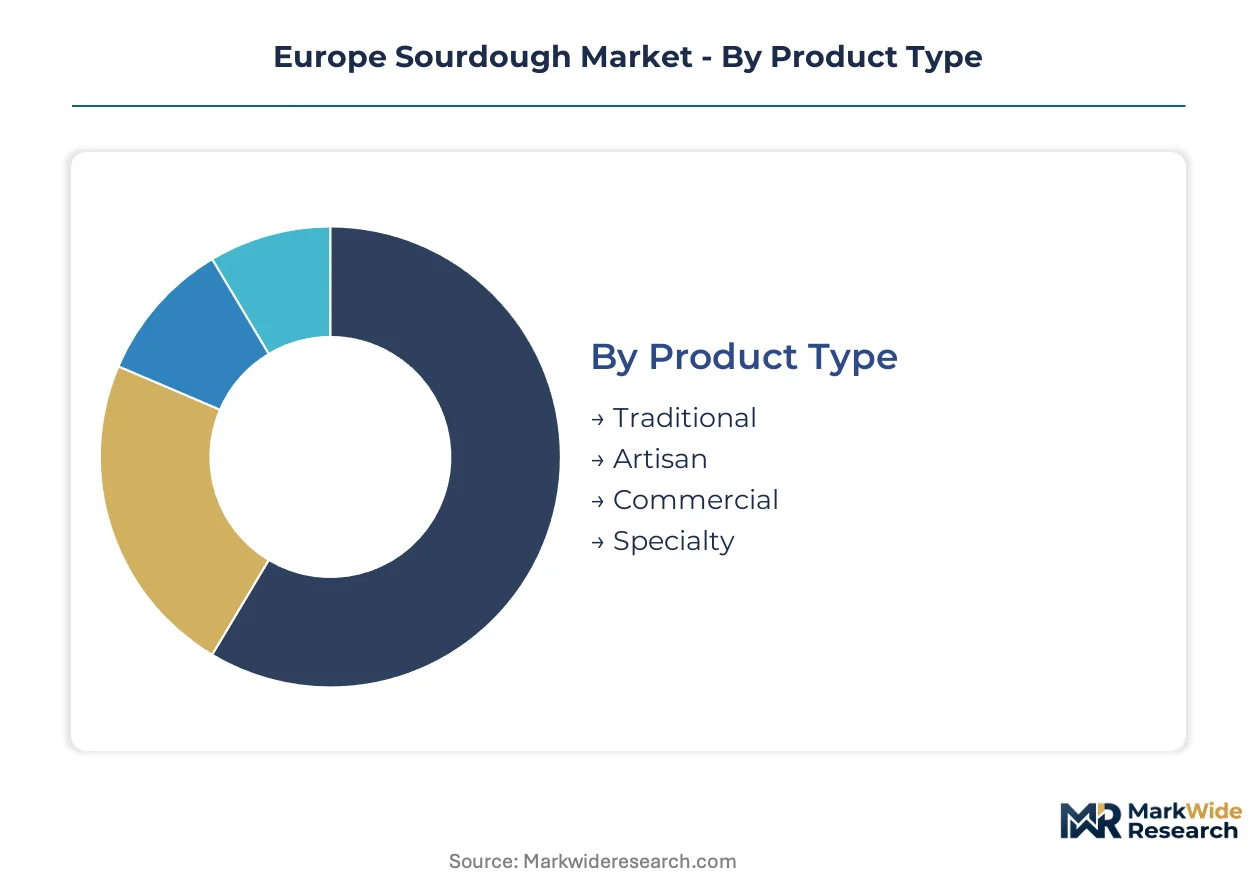
Sourdough market segmentation reveals how production methods, channel economics, and consumption occasions create distinct margin pools across Europe. Understanding these divides helps suppliers align starter culture formulations and packaging formats with buyer priorities.
Product Type:
Price sensitivity and production scale determine which formats bakeries prioritize when sourcing fermentation inputs.
- Traditional:Long-fermented loaves using rye-wheat hybrid starters dominate German and Austrian household consumption. Regional PDO certifications in Bavaria and Vorarlberg protect provenance labeling that commands retail premiums.
- Artisan:Small-batch production with wild-caught starters concentrates in urban craft bakeries across Copenhagen, Barcelona, and Amsterdam. These buyers prioritize living starter subscriptions over dried concentrates despite higher labor costs.
- Commercial:Standardized pH-controlled fermentation supplies supermarket private-label programs and food-service distributors with consistent acidity profiles.
- Specialty:Organic-certified and gluten-reduced variants target health-positioned retail channels in France and the Netherlands.
Traditional leads on scale; Artisan leads on momentum.
Distribution Channel:
Channel selection shapes cold-chain requirements, shelf-life specifications, and margin capture for sourdough suppliers.
- Retail:Supermarket bakery counters and packaged bread aisles in Germany and France account for the largest volume flows. Buyers demand 5-7 day shelf-life extensions through modified atmosphere packaging.
- Online:Direct-to-consumer starter culture subscriptions and frozen sourdough delivery services expand fastest in Scandinavian urban markets. Copenhagen-based craft producers bypass distributors through this channel.
- Food Service:Restaurant and hotel bread programs in Italy and Spain require par-baked formats with rapid finish-bake protocols.
- Wholesalers:Broadline distributors aggregate demand from independent bakeries across Poland and Romania, though starter culture technical support remains limited in these markets.
Retail dominates absolute volume; Online climbs the fastest.
End User:
Technical sophistication and batch size determine whether buyers maintain live starters or outsource fermentation entirely.
- Bakeries:Mid-sized craft producers across Belgium and the Netherlands represent the core demand base for stabilized liquid starter cultures. These buyers seek to reduce daily feeding labor without sacrificing flavor complexity.
- Restaurants:Fine-dining bread programs in Paris and Milan emphasize house-fermented starters for menu differentiation, though few maintain consistent production volumes.
- Supermarkets:Central bakery operations in German chains like REWE and Edeka drive bulk concentrate procurement with strict organic certification requirements.
- Households:Home bakers purchasing dried starter cultures and fermentation kits concentrate in UK and Nordic markets with strong DIY baking cultures.
Bakeries anchor supplier relationships; Supermarkets drive procurement standardization.
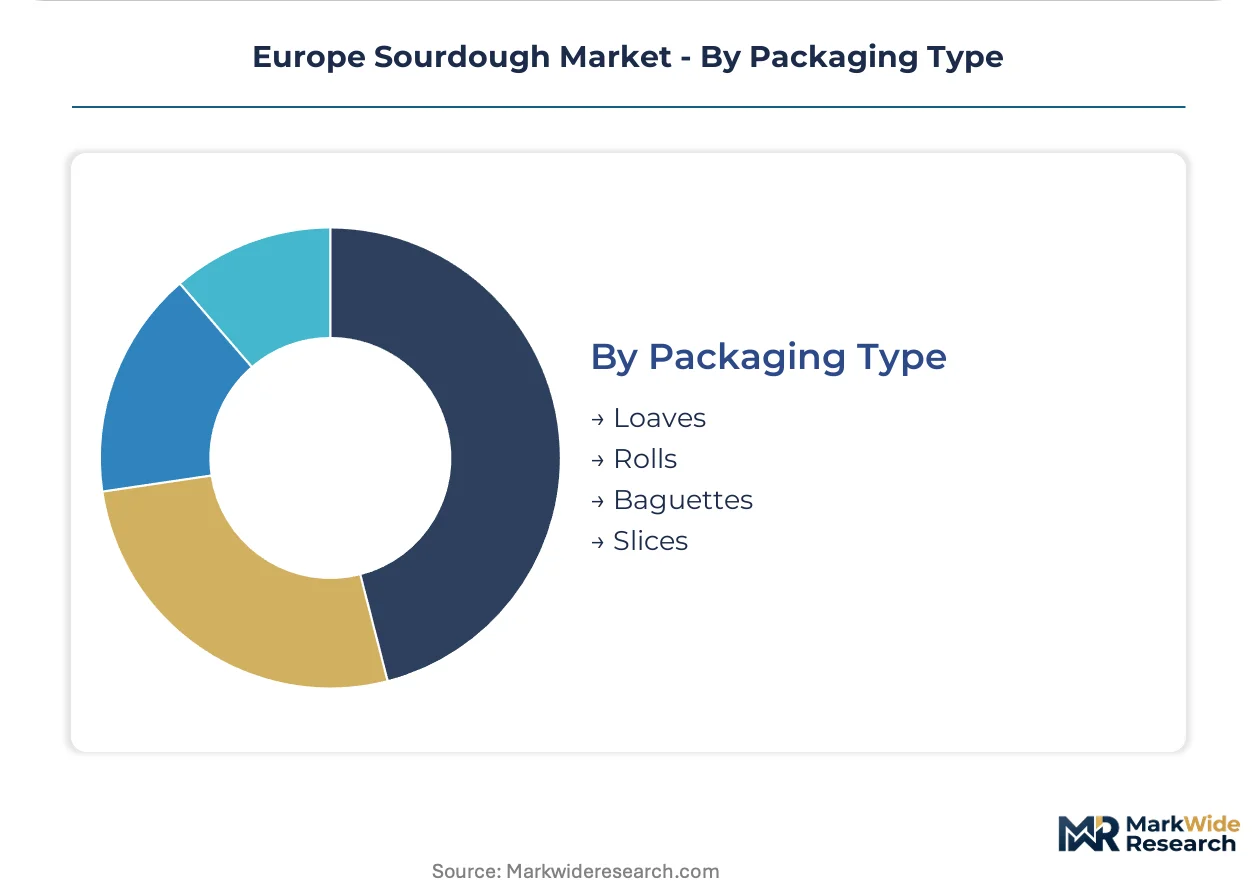
Packaging Type:
Format selection reflects consumption occasion patterns and retail display requirements across European markets.
- Loaves:Standard 500-750g round and oval formats dominate German household purchase patterns and account for the largest production volumes.
- Rolls:Individual portion sizes concentrate in food-service breakfast programs and pre-packaged retail assortments in France.
- Baguettes:Elongated formats with extended crust surface area prevail in French and Belgian retail, though authentic sourdough baguette production remains technically demanding.
- Slices:Pre-sliced sandwich formats target UK and Irish convenience-oriented consumers through supermarket private-label programs.
Loaves capture the largest production base; Rolls gain share fastest in food-service channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's dense bakery network anchors European sourdough production, with regional starter culture clusters concentrated in Bavaria and Baden-Württemberg. The EU Green Deal's sustainable food system targets are reshaping ingredient sourcing requirements across the continent's fermentation supply chains.
Germany
Traditional rye-wheat hybrid starters drive household consumption volumes in Bavaria and North Rhine-Westphalia. The EU Green Deal mandates accelerate baker adoption of certified organic flours from regenerative grain programs. Munich and Stuttgart host concentrated starter culture production facilities serving industrial and craft bakery segments.
France
Artisan baguette traditions sustain demand for elongated sourdough formats in Paris and Lyon metropolitan bakeries. EFSA clean-label guidance tightens disclosure requirements for enzymatic processing aids in accelerated fermentation programs. The Auvergne-Rhône-Alpes cluster specializes in region-specific starter cultures for protected designation of origin bread lines.
Italy
Fine-dining bread programs in Milan and Rome emphasize house-fermented starters for menu differentiation. REACH compliance deadlines pressure ingredient suppliers to reformulate enzymatic fermentation accelerators ahead of 2025 registration reviews. Emilia-Romagna maintains traditional production methods for heritage grain sourdough varieties.
Netherlands
Mid-sized craft bakeries in Amsterdam and Rotterdam scale capacity for retail slow-fermented bread formats. CSRD supply-chain disclosure rules favor transparent, short-ingredient-list products in supermarket private-label procurement. The Randstad corridor concentrates stabilized liquid starter culture demand from urban commercial producers.
Poland
Low sourdough penetration relative to Western Europe creates first-mover positioning for regional starter culture suppliers. ECHA substance evaluation processes extend to processing aids used in industrial fermentation expansion. Warsaw and Krakow industrial zones attract distributor investment for broadline bakery ingredient aggregation.
Europe Sourdough Market Competitive Landscape
Portfolio diversification dominates the current landscape as suppliers expand beyond starter cultures into complete fermentation solutions. The vendor base organizes around three tiers: multinational ingredient conglomerates with controlled fermentation technology, mid-sized specialists in region-specific starter libraries, and niche suppliers of organic-certified concentrates. Strategic archetypes include technology licensors, geographic expansionists, and certification-focused premium positioning players. M&A activity and capacity expansion in stabilized liquid formats represent the dominant competitive vectors.
Within the multinational technology tier, Puratos and Lesaffre exemplify scale-driven fermentation expertise across Western and Eastern European markets. IREKS GmbH anchors specialist positioning in German and Scandinavian regional starter varieties. These three entities represent distinct archetypes: Puratos occupies the sourdough library and technical service position, Lesaffre exemplifies controlled fermentation platform reach, and IREKS GmbH embodies geographic specialization within heritage bread cultures.
| Leading Market Players |
|---|
| Puratos |
| Lesaffre |
| IREKS GmbH |
| Ernst Böcker GmbH & Co. KG |
| Lallemand |
| GoodMills Group |
| Aryzta |
| Philibert Savours |
| Dr. Otto Suwelack Nachf. GmbH & Co. |
| Others |
Supply & Pricing Matrix
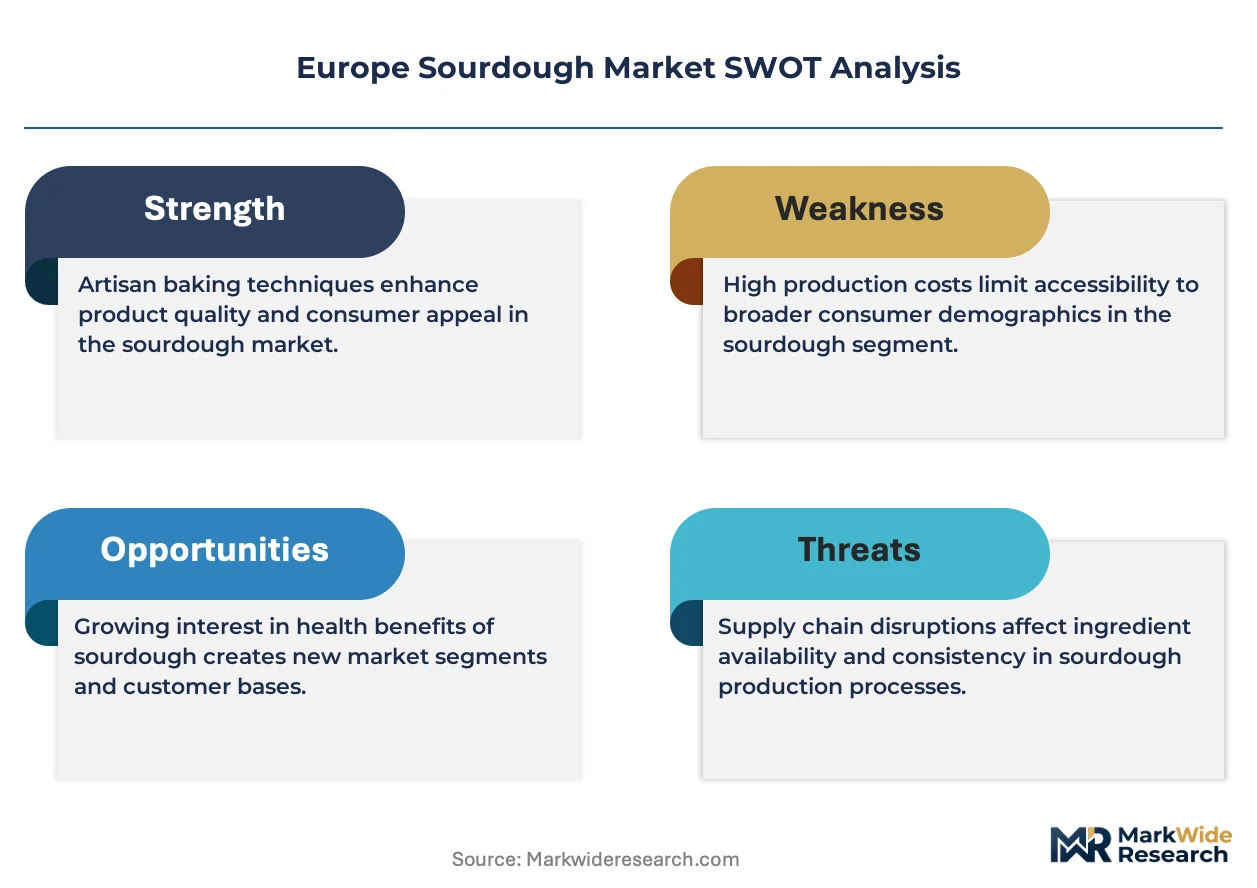
Captive sourcing of organic grain from regenerative programs anchors both supply security and premium-tier pricing power for German and French bakery ingredient suppliers. EU Green Deal compliance costs feed directly into concentrate pricing, compressing margins for conventional producers while rewarding certified organic supply chains with defendable premium positioning.
Pricing Analysis
Input-cost pass-through from organic wheat and specialty rye harvest variability runs directly into concentrate pricing for industrial bakers. Three-tier pricing structure across premium organic-certified, standard conventional, and economy dried-starter levels reflects certification grade and volume scale differentiation. Pricing pressure stems from weather-driven grain price spikes across Eastern European belts, with supermarket private-label buyers exhibiting highest price sensitivity and artisan craft bakeries showing lowest.
Supply Chain Analysis
Certification gating through EU organic standards and PDO regional designations restricts starter culture supply to qualified producers in Southern Germany, Northern France, and the Auvergne-Rhône-Alpes cluster. Raw material dependencies center on heritage rye varieties, wheat substrates, and lactic acid bacteria strains. Single-source vulnerability concentrates in Bavarian starter culture facilities serving industrial bakeries across the continent. Distribution runs through broadline ingredient distributors and direct-to-bakery subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European sourdough rests on stabilized liquid starter adoption reducing labor costs for mid-scale craft producers, coupled with organic certification premiums widening spread between input and output pricing.
For Market Incumbents: Lock in supply relationships with regenerative grain programs ahead of EU Green Deal enforcement tightening. Expand controlled fermentation technology licensing to Polish and Romanian distributors before regional starter culture competitors establish footholds. Certification investment in PDO-protected regional varieties defends against private-label price erosion. For New Entrants and Emerging Players: Capture whitespace in Warsaw and Krakow industrial zones where broadline distributor technical support remains limited. Target subscription-based starter delivery to urban craft bakeries in Barcelona and Copenhagen bypassing traditional ingredient channels. Lead with organic-certified positioning to exploit EFSA clean-label procurement preferences. For Investors and Strategic Acquirers: Roll-up economics work for regional starter culture specialists with heritage grain libraries because EU organic certification timelines create acquisition barriers for new entrants. Mid-cap producers with captive regenerative sourcing and existing PDO registrations represent priority targets. Watch ECHA substance evaluation outcomes for enzymatic processing aids as margin inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regenerative Grain | Secures organic-certified supply streams ahead of EU Green Deal sourcing mandates. |
| Stabilized Liquid Starter Scale-Up | Reduces craft bakery labor costs while expanding private-label availability in discount retail. |
| PDO Regional Certification Investment | Protects provenance labeling premiums in Bavaria and Vorarlberg heritage bread markets. |
| Direct-to-Bakery Subscription Launch | Bypasses traditional distributors to capture margin from Copenhagen and Barcelona urban producers. |
| Controlled Fermentation Technology Licensing | Extends pH-standardization platforms to underpenetrated Polish and Romanian bakery markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with bakery operations directors, ingredient procurement managers, fermentation R&D leads, and distributor category heads with secondary validation against customs trade data, EU organic certification registries, EFSA guidance documents, and bakery industry association reports. Bottom-up volume builds from starter culture shipments triangulated against top-down bakery production capacity estimates.
Comparable-period anchoring used historical fermentation input demand across conventional, organic, and artisan production tiers to project forward over the analysis window. Segmentation modeling incorporated product type, distribution channel, end-user technical sophistication, and packaging format dimensions. CAGRs derived from curve-fitting normalized growth rates against grain price volatility indices and certified organic acreage expansion trajectories.
Underlying measurement precision varies by segment; commercial concentrate volumes carry tighter precision than artisan wild-caught starter estimates. Forecasts reflect assumptions on EU Green Deal implementation pace and ECHA substance evaluation timelines. A model refresh is warranted upon material change in organic grain harvest variability or regulatory acceleration of clean-label disclosure requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Dough Conveyor Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Aerating Cake Emulsifier Market
Bakery Products
Muffins Market
Bakery Products
Bakery Premixes Market
Bakery Products
Ice Cream Cones Market
Bakery Products
Frosting, Toppings, and Decorations Market
Bakery Products
North America Bakery Products Market
Bakery Products
Global Cake Mix Market
Bakery Products
Gluten-Free Bakery Premixes Market
Bakery Products
Bread and Baked Food Market
Bakery Products
Sourdough Market
Bakery Products
Personalized Bakery Products Market
Bakery Products
Low Fat Oatmeal Cookies Market
Bakery Products
Low Calorie Rice Cake Market
Bakery Products
Asia-Pacific Bakery Products Market