
 Faba Bean Protein Market | 2026-2036
Faba Bean Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Faba Bean Protein Market Insights
Specialty ingredient distribution is rewriting procurement geography for European plant protein buyers. Roquette Frères leverages its decades of extrusion expertise to anchor supply relationships with meat-alternative brands across France and Belgium. Prairie Fava dominates Canadian origin supply through backward integration into Saskatchewan acreage contracts. AGT Food and Ingredients competes on pulse processing scale, extending its port-advantaged footprint through Thunder Bay and Vancouver.
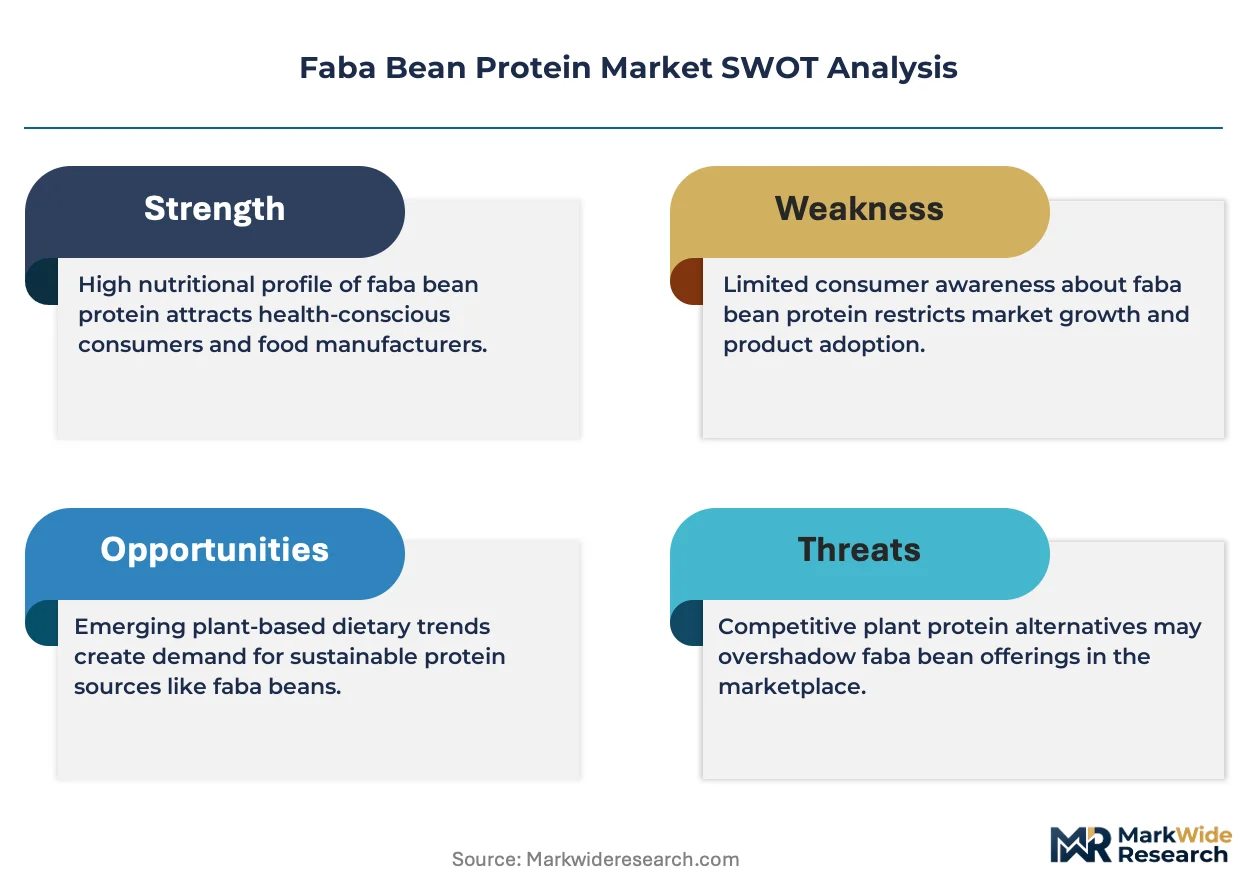
Faba bean protein is a legume-derived protein extract containing approximately 60-85% protein by dry weight, obtained through dry or wet fractionation of dehulled seeds, and functions as an emulsifying and gelling agent in formulated foods. Isolate commands premium positioning due to superior solubility and neutral flavor required by beverage applications, while textured protein sustains the fastest growth trajectory as whole-muscle analog production scales. Food manufacturers represent the deepest end-user margin pool, though feed producers occupy growing volume as aquaculture diets seek alternatives to fishmeal.
EU REACH compliance and the F-Gas Regulation shape extraction technology investment, while EFSA novel food approvals govern isolate introduction timelines. Health Canada and FDA parallel-track evaluations for protein content claims influence North American market access speed. Stakeholders must monitor carbon border adjustment mechanism developments to anticipate origin-switching incentives before facility location decisions crystallize.
Market Dynamics
The EU Green Deal's carbon border adjustment mechanism is forcing plant-based meat formulators to abandon imported soy in favor of traceable European-origin faba bean isolate, compressing procurement timelines and rewiring supplier qualification criteria across Northern European extrusion clusters.
Growth Catalysts
- EU Green Deal carbon accounting:Tightened emissions reporting for imported feedstocks accelerates substitution toward domestically grown pulse proteins with verifiable supply chain footprints.
- Aquaculture feed diversification:Fishmeal replacement mandates in Norwegian and Scottish salmon farming drive isolate-grade procurement for high-protein diet formulations.
- Rotterdam port infrastructure:Concentrated extrusion technology providers and ingredient traders create procurement efficiency for Benelux meat-alternative manufacturers.
Market Restraints
- Input cost volatility:Saskatchewan acreage contract pricing fluctuates with prairie drought cycles, squeezing margin predictability for processors dependent on Canadian origin supply.
- Supply concentration risk:Prairie Fava's backward integration into Saskatchewan farming locks competitors out of premium origin material during peak demand windows.
- Regulatory friction:EFSA novel food approval timelines for isolate introductions extend market access delays by 18-24 months versus textured protein pathways.
Strategic Opportunities
- Underpenetrated German beverage sector:Neutral-flavor isolate applications in sports nutrition and dairy alternatives remain underserved relative to meat-analog adoption rates.
- Technology convergence:Precision fermentation partners are exploring hybrid formulations combining faba isolate with microbial proteins for enhanced amino acid profiles.
- Direct-to-manufacturer platforms:Digital procurement channels bypass traditional ingredient traders, capturing margin for mid-scale extrusion operators in France and Belgium.
Industry Challenges
- Specialized extrusion engineering talent:Shortage of technicians proficient in high-moisture extrusion for whole-muscle analog production constrains capacity expansion at European processing facilities.
- EFSA certification timeline compression:Novel food dossier preparation demands toxicology and clinical study investment that mid-cap processors struggle to fund without partnership structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Faba Bean Protein Market |
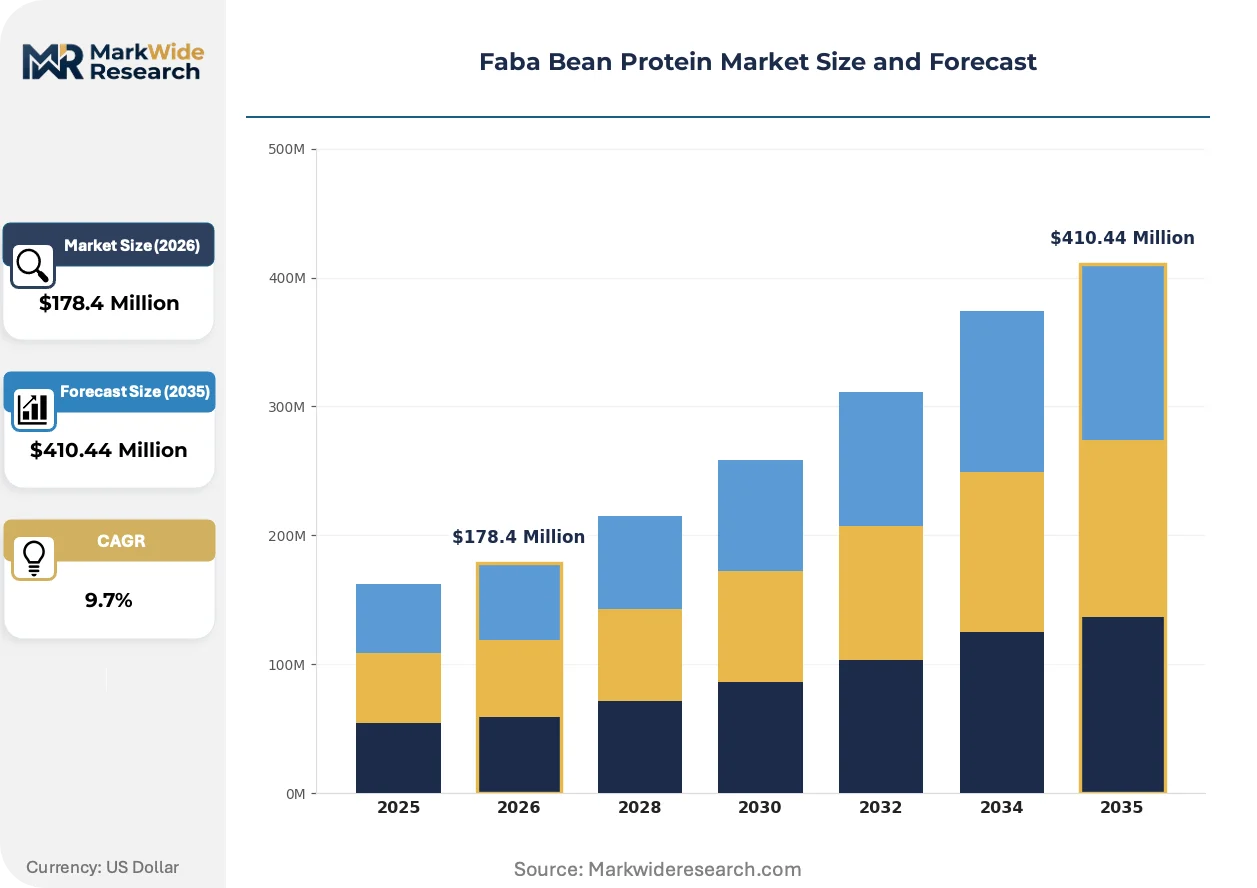
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $410.44 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Flour, Concentrate, Textured Protein Application: Food & Beverages, Nutraceuticals, Animal Feed, Personal Care End User: Food Manufacturers, Health Supplements, Bakeries, Feed Producers Packaging Type: Bulk Bags, Sachets, Jars, Pouches |
| Companies Covered | Cargill, Prairie Fava, Roquette Frères, Ingredion, GrainCorp, Puris Proteins, BI Nutraceuticals, BENEO, AGT Food and Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Faba Bean Protein Market Trends and Innovations
Extraction technology advances and regulatory carbon accounting are converging to reshape competitive positioning in European plant protein supply chains, with wet fractionation methods gaining traction over conventional dry processing.
Wet fractionation using aqueous extraction is collapsing the solubility gap between commodity-grade concentrates and premium isolates. Beverage manufacturers in Germany and the Netherlands are adopting this technology at pilot scale. The process compression enables mid-tier processors to enter isolate markets without legacy capital investment in alcohol-wash infrastructure.
REACH compliance requirements and the F-Gas Regulation are mandating solvent recovery systems and low-carbon thermal processing in EU extraction facilities. Industrial consequence includes accelerated capex cycles for equipment replacement. French and Belgian processors are responding by consolidating production at Roquette Frères' established sites rather than greenfield development.
Buyer concentration among plant-based meat brands is compressing supplier negotiation cycles from annual to quarterly frameworks. Traditional ingredient distributors in the Netherlands are losing share to direct mill relationships. This pattern is most visible in Rotterdam-adjacent extrusion clusters serving Benelux meat-alternative manufacturers.
Faba Bean Protein Market Segmentation
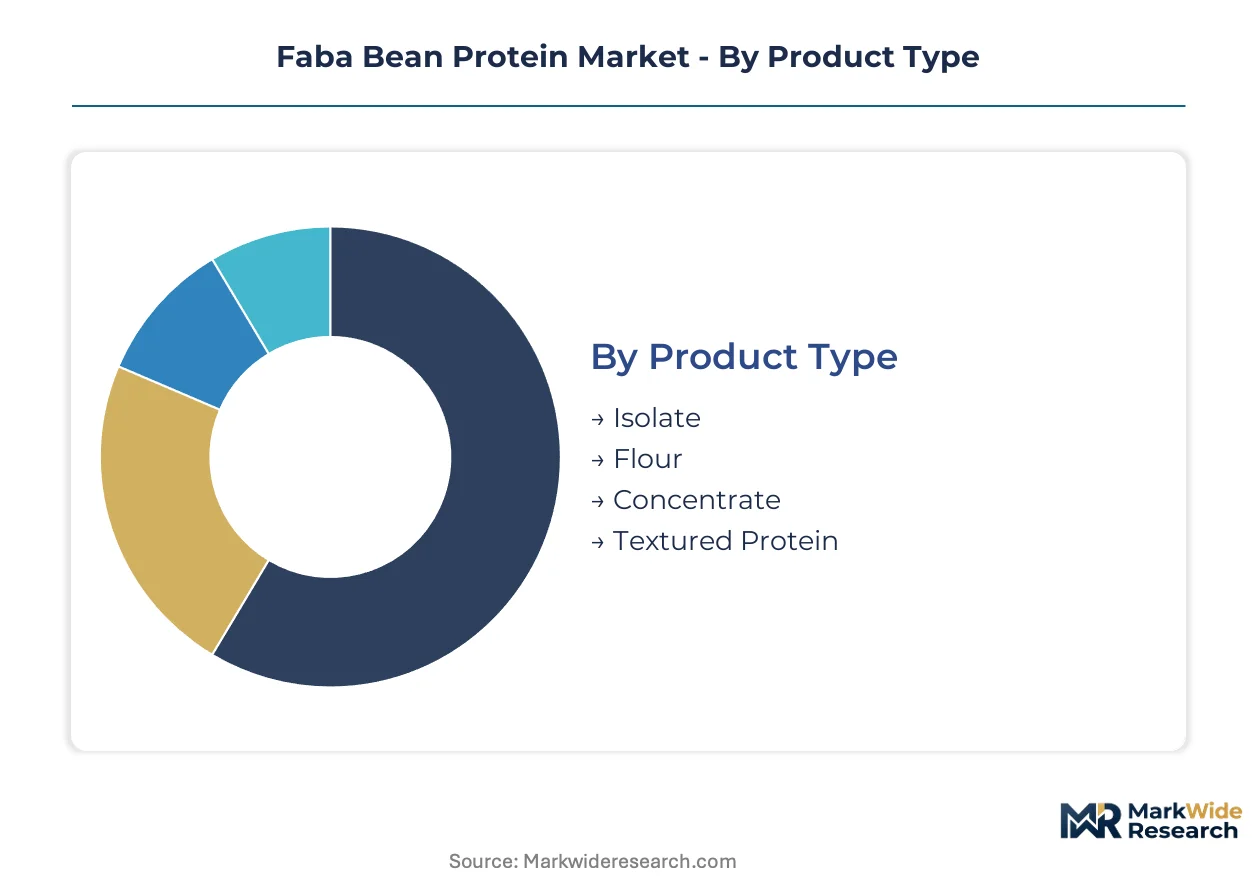
Product form determines functional performance and price positioning in faba bean protein procurement. Application end-use dictates regulatory pathway complexity and margin capture potential. Understanding segment intersections reveals where processors can defend margin against commodity pressure.
Product Type:
Cost tier stratification separates premium isolate grades from commodity flour and concentrate positions.
- Isolate:Protein content reaches 85% through wet fractionation with alcohol wash or aqueous extraction. German beverage formulators in sports nutrition and dairy alternatives concentrate procurement here, paying premium multiples for neutral flavor and solubility specifications that EFSA novel food approvals govern.
- Textured Protein:High-moisture extrusion creates fibrous structures mimicking whole-muscle meat analogs. Benelux meat-alternative manufacturers around Rotterdam drive fastest volume expansion as quarterly procurement cycles replace annual frameworks.
- Flour:Whole-seed milling retains fiber and starch fractions for bakery and traditional food applications.
- Concentrate:Dry fractionation yields 60-70% protein for cost-sensitive formulated foods where solubility requirements moderate.
Isolate holds installed capacity. Textured protein is rotating up the share rankings.
Application:
End-use maturity determines which segments absorb regulatory friction versus technology investment.
- Food & Beverages:Plant-based meat analogs and dairy alternatives command formulation investment from Roquette Frères and Rotterdam-cluster extrusion operators. EU Green Deal carbon accounting accelerates substitution away from imported soy toward traceable European-origin isolates.
- Animal Feed:Norwegian and Scottish salmon farming operations source isolate-grade material for fishmeal replacement mandates in high-protein aquaculture diets.
- Nutraceuticals:Protein content claims require Health Canada and FDA parallel-track evaluations that extend North American market access timelines.
- Personal Care:Emulsifying properties drive cosmetic formulation adoption at smaller volume scale.
Food and beverages anchors revenue concentration. Animal feed is climbing the fastest as diet formulation science advances.
End User:
Customer type shapes contract structure and technical service intensity in supplier relationships.
- Food Manufacturers:Meat-alternative brands and dairy substitute producers represent the deepest margin pool through direct mill relationships that bypass traditional Dutch ingredient distributors.
- Feed Producers:Aquaculture diet compounders in Norway and Scotland scale isolate procurement for fishmeal substitution mandates.
- Health Supplements:Sports nutrition brands in Germany seek neutral-flavor isolates for beverage applications that remain underpenetrated relative to meat-analog adoption.
- Bakeries:Regional European operators source flour and concentrate grades for protein fortification at price-sensitive volume.
Food manufacturers command negotiation leverage. Feed producers are gaining share fastest through diet mandate compliance.
Packaging Type:
Volume scale and handling requirements differentiate procurement logistics across customer tiers.
- Bulk Bags:Ton-scale flexible intermediate bulk containers serve Rotterdam-port extrusion clusters and compound feed operations with pneumatic handling infrastructure.
- Sachets:Single-serve retail formats target sports nutrition and health supplement channels in German and Dutch consumer markets.
- Jars:Rigid packaging for premium isolate positioning in specialty health food retail.
- Pouches:Flexible retail formats for flour and concentrate grades in bakery supply chains.
Bulk bags dominate processor intake. Sachets are expanding most quickly as direct-to-consumer channels mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food approval timelines anchor European market access, while Health Canada and FDA parallel-track evaluations govern North American expansion speed. Procurement clusters concentrate around Rotterdam port infrastructure and Saskatchewan prairie acreage contracts.
Germany
Plant-based meat formulators in Germany accelerate isolate-grade procurement as the EU Green Deal tightens carbon accounting for imported soy. EFSA REACH compliance governs extraction technology investment timelines. Berlin-Brandenburg extrusion clusters serve domestic meat-alternative brands with quarterly procurement frameworks replacing annual contracts.
Netherlands
Ingredient traders and extrusion technology providers cluster around Rotterdam port infrastructure, creating procurement efficiency for Benelux manufacturers. EU F-Gas Regulation mandates solvent recovery systems in extraction facilities. Rotterdam-adjacent processing sites consolidate wet fractionation capacity as traditional distributors lose share to direct mill relationships.
Canada
Saskatchewan acreage contracts dominate Canadian origin supply through backward integration into prairie farming operations. Health Canada protein content claims influence beverage application market access speed. Thunder Bay and Vancouver port-advantaged footprints extend pulse processing scale across North American distribution networks.
France
Roquette Frères leverages decades of extrusion expertise to anchor supply relationships with meat-alternative brands across France and Belgium. EU REACH compliance and F-Gas Regulation accelerate capex cycles for equipment replacement. French processors consolidate production at established sites rather than pursue greenfield development.
Norway
Norwegian salmon farming operations source isolate-grade material for fishmeal replacement mandates in high-protein aquaculture diets. EFSA novel food approvals extend market access delays relative to textured protein pathways. Coastal feed compounders scale procurement as diet formulation science advances.
Faba Bean Protein Market Competitive Landscape
Multinational agribusiness conglomerates and regionally anchored pulse specialists split the market into distinct capability tiers. Roquette Frères and Cargill represent integrated processing scale, while Prairie Fava and AGT Food and Ingredients occupy origin-controlled supply positions. Competitive moves concentrate on backward integration into Saskatchewan farming and wet fractionation technology licensing to collapse the solubility gap between concentrates and isolates.
Within the origin-integrated tier, Prairie Fava exemplifies backward integration through Saskatchewan acreage contracts that lock competitors out of premium material during peak demand windows. AGT Food and Ingredients anchors port-advantaged scale across Thunder Bay and Vancouver. Roquette Frères occupies the extrusion technology leadership position serving Benelux and French meat-alternative manufacturers.
| Leading Market Players |
|---|
| Cargill |
| Prairie Fava |
| Roquette Frères |
| Ingredion |
| GrainCorp |
| Puris Proteins |
| BI Nutraceuticals |
| BENEO |
| AGT Food and Ingredients |
| Others |
Pricing and Supply Chain Analysis
Saskatchewan acreage concentration under Prairie Fava's backward integration funnels margin downstream to Rotterdam-port extrusion operators and German beverage formulators who command quarterly procurement leverage. This upstream lock on premium origin material forces mid-tier processors to absorb cost volatility or consolidate at Roquette Frères' established sites.
Pricing Analysis
Geographic spreads widen between Canadian-origin isolate and European-processed grades as Rotterdam-port operators capture carbon-accounting premiums under EU Green Deal compliance. Three-tier pricing structure across premium isolate, standard concentrate, and economy flour segments reflects protein content and EFSA certification status. Pricing pressure stems from Saskatchewan drought-cycle volatility compressing processor margins. Feed compounders in Norwegian aquaculture show highest price sensitivity, while German sports nutrition brands absorb premiums for neutral-flavor specifications.
Supply Chain Analysis
Extended payment terms from Rotterdam-cluster extrusion operators to Saskatchewan growers are compressing working capital cycles for mid-cap processors. Supply concentrates in Canada, the Netherlands, and France, with raw material flows drawing from prairie acreage contracts, port-advantaged pulse processing, and Roquette Frères' established extraction infrastructure. Single-source vulnerability sits with Prairie Fava's locked Saskatchewan premium material during peak demand windows. Distribution runs through direct mill relationships that bypass traditional Dutch ingredient traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around Rotterdam-port extrusion clusters and German meat-alternative brands, fragmenting traditional ingredient distributor margins as quarterly procurement frameworks displace annual contracts.
For Market Incumbents: Pre-empt margin erosion by securing captive Saskatchewan acreage through long-term farming contracts before Prairie Fava extends its lock on premium origin supply. Accelerate wet fractionation technology licensing to collapse the solubility gap between concentrate and isolate tiers, defending position against aqueous extraction newcomers. EFSA novel food approval timelines represent the critical regulatory lever to extend competitive moats.
For New Entrants and Emerging Players: German beverage sector underpenetration offers white-space access for neutral-flavor isolate applications in sports nutrition and dairy alternatives. Precision fermentation hybrid formulations present a technology convergence entry path without legacy alcohol-wash infrastructure investment. Direct-to-manufacturer digital procurement platforms bypass Dutch trader intermediaries.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed extrusion technology providers clustered around Rotterdam port infrastructure. Long-term viability hinges on carbon border adjustment mechanism enforcement deepening European-origin preference. Monitor EFSA novel food approval acceleration as the inflection signal for isolate-grade market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Saskatchewan Acreage | Secures premium origin supply locked by Prairie Fava's farming contracts. |
| Wet Fractionation Technology Licensing | Enables mid-tier processors to enter isolate markets without legacy capital investment. |
| Direct-to-Manufacturer Digital Platform Launch | Bypasses traditional Dutch ingredient traders to capture margin in Benelux clusters. |
| EFSA Novel Food Dossier Investment | Accelerates market access timelines for isolate-grade beverage applications. |
| Precision Fermentation Hybrid Partnership | Combines faba isolate with microbial proteins for enhanced amino acid profiles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA novel food registrations, EU REACH compliance filings, and Health Canada protein content claim evaluations. Primary interviews engaged extrusion technology providers, procurement leads at Rotterdam-port meat-alternative manufacturers, Saskatchewan acreage contract managers, and aquaculture feed compounders in Norway. Secondary sources included customs trade data, EU Green Deal carbon accounting disclosures, and SEC filings from listed pulse processors. Bottom-up volume modeling triangulated against top-down market sizing across product type and application segments.
Forecast inputs span protein content tier, extraction technology method, end-use regulatory pathway, and regional procurement cluster concentration. Segmentation dimensions modeled include isolate versus textured protein versus concentrate grades, food and beverage versus animal feed versus nutraceutical applications, and direct mill versus distributor channel structures. CAGRs were derived from trajectory analysis of procurement volume shifts and capacity expansion announcements. Industry-specific inputs incorporated EFSA approval timeline distributions and Saskatchewan prairie yield variance patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation startups or carbon border adjustment mechanism accelerators would shift outcomes. Macroeconomic drought cycles, regulatory approval compression, or aqueous extraction technology breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
Burdock Root Extract Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Plant Based Breads Market
Plant Based Food
Global Chaga Mushroom-Based Products Market
Plant Based Food
Asia-Pacific Rice Protein Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
Oat Protein Market
Plant Based Food
Targeting Pod Market
Plant Based Food
Fava Bean Protein Market
Plant Based Food
Vegan Asian Food Market
Plant Based Food
Asia-Pacific Plant-Based Seafood Market
Plant Based Food
Vegan Flour Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Flax-Based Protein Market
Plant Based Food
Veggie Meals Market