
 Take Out Coffee Market | 2026-2036
Take Out Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Take Out Coffee Market Analytics
Barista workforce availability is rotating toward automation-compatible skill profiles as chains expand drive-through and mobile-order throughput. Starbucks sustains unmatched real estate density in U.S. metropolitan zones. Luckin Coffee dominates app-based ordering infrastructure in Chinese cities. Dutch Bros specializes in high-velocity lane formats that minimize labor per transaction.
Take out coffee denotes brewed or extracted coffee beverages prepared for immediate consumption outside fixed dining premises, typically served in temperature-retentive disposable vessels with aseptic sealing requirements. Espresso-based formats anchor premium pricing tiers due to equipment intensity and bean grading standards. Latte and cappuccino variants capture the largest volume share among product types. Professionals represent the most concentrated customer segment by weekday frequency, while food trucks and convenience stores expand fastest as distribution channels by capital efficiency.
FDA food-contact material rules and EU Green Deal packaging waste frameworks govern cup composition and recyclability claims across major markets. Municipal bans on polystyrene and perfluorinated compounds in the United States, plus China's GB standards for food packaging, create compliance thresholds that favor larger operators with reformulation resources. Stakeholders must monitor evolving extended producer responsibility schemes and material substitution timelines to align capital deployment with regulatory trajectories.
Market Dynamics
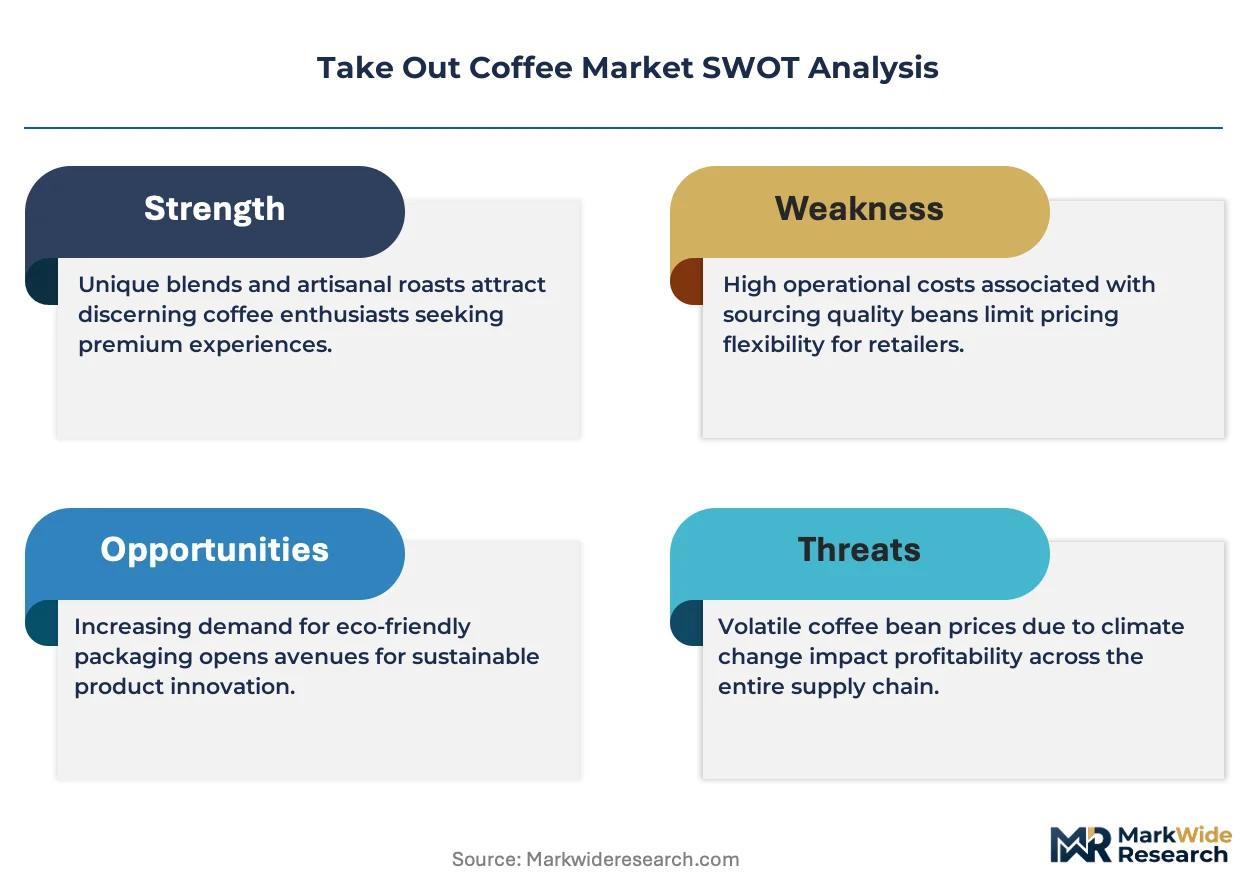
Single-use packaging directives from the EU Green Deal and municipal ordinances across the United States are forcing rapid material substitution in cup and lid manufacturing, compressing margins for operators lacking reformulation scale while creating compliance premiums for early movers.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility schemes in Europe accelerate demand for fiber-based alternatives and deposit-return infrastructure, expanding addressable market for certified compostable suppliers.
- Mobile-ordering platform penetration:App-based throughput optimization in Chinese and Brazilian urban corridors reduces labor per transaction and extends peak-hour capacity without proportional real estate expansion.
- Drive-through format velocity:High-lane-count formats in U.S. metropolitan zones capture commuter demand across morning and afternoon dayparts through throughput engineering that minimizes dwell time.
Market Restraints
- Arabica price volatility:Weather-driven supply shocks in Brazilian and Colombian growing regions transmit directly to input cost structures, compressing margin predictability for roasters without forward-contract coverage.
- Polystyrene ban diffusion:Municipal ordinances in U.S. coastal cities and China's GB standards for food-contact materials force simultaneous multi-jurisdiction compliance, favoring capital-rich operators with dedicated regulatory teams.
- Barista labor scarcity:Automation-compatible skill profiles remain concentrated in urban markets, constraining expansion velocity in secondary cities where training infrastructure lags equipment deployment.
Strategic Opportunities
- India urban corridor penetration:Underdeveloped drive-through infrastructure in Mumbai and Bangalore metro regions offers first-mover positioning before real estate density saturates comparable to U.S. or Chinese benchmarks.
- FSSAI packaging compliance alignment:India's food safety regulator is tightening food-contact material rules, creating certification-premium positioning for operators with pre-positioned biodegradable supply chains.
- Convenience store channel integration:Capital-light kiosk formats within petroleum retail networks in Brazil and Mexico extend distribution reach without standalone development costs or zoning friction.
Industry Challenges
- Equipment-technician shortage:Automated espresso and brewing systems require specialized maintenance capabilities that outpace vocational training program output in most markets.
- Multi-jurisdiction certification lag:Simultaneous FDA, EU Green Deal, and GB standards compliance creates timeline compression for new material introductions, delaying product launches by 8-14 months.
- Legacy POS integration friction:Mobile-ordering platforms must interface with fragmented point-of-sale architectures across franchisee bases, complicating unified customer data capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Take Out Coffee Market |
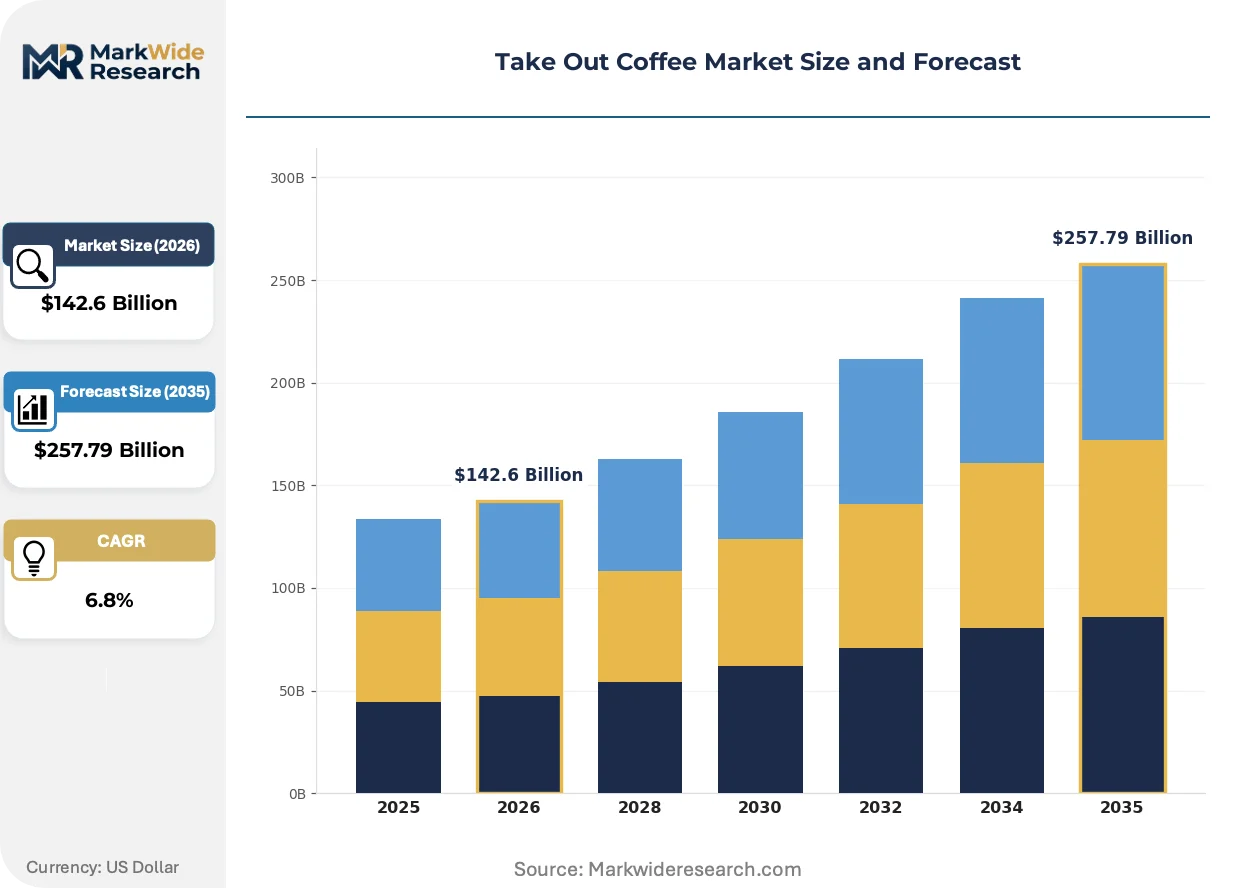
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $257.79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Espresso, Americano, Cappuccino, Latte Customer Type: Students, Professionals, Tourists, Families Distribution Channel: Cafés, Food Trucks, Convenience Stores, Vending Machines Flavor Profile: Classic, Mocha, Vanilla, Caramel |
| Companies Covered | Scooter's Coffee, Luckin Coffee, Starbucks, Aroma Joe's, Paris Baguette, Dunkin', 7 Brew, Black Rock Coffee Bar, Dutch Bros, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Take Out Coffee Market Evolving Landscape
Material science advances and regulatory pressure are converging to transform vessel composition, brewing automation, and customer interface protocols across the value chain.
Plant-fiber molded pulp technology with integrated barrier coatings is displacing conventional polyethylene-lined paper cups in premium urban markets. Chains with sustainability-forward positioning in Seattle, Amsterdam, and Sydney are piloting these vessels at 15-20% price premiums. The technology is displacing incumbent cup suppliers that lack thermoforming adaptation capacity, consolidating procurement toward integrated packaging converters.
REACH substance restrictions and EU Green Deal packaging waste frameworks are tightening perfluorinated compound prohibitions across European markets. Manufacturers must reformulate barrier coatings or exit the compliance zone entirely. Roasters with direct European distribution are accelerating supplier audits and dual-sourcing arrangements to avoid stockout risk during transition windows.
Subscription-based office coffee programs are capturing weekday professional consumption previously served by individual café visits. Corporate facilities managers in London, Toronto, and Singapore are consolidating vendor relationships around single-source equipment-plus-bean contracts. This procurement consolidation is most visible in finance and technology verticals where headcount density justifies dedicated on-premise brewing infrastructure.
Take Out Coffee Market Segmentation
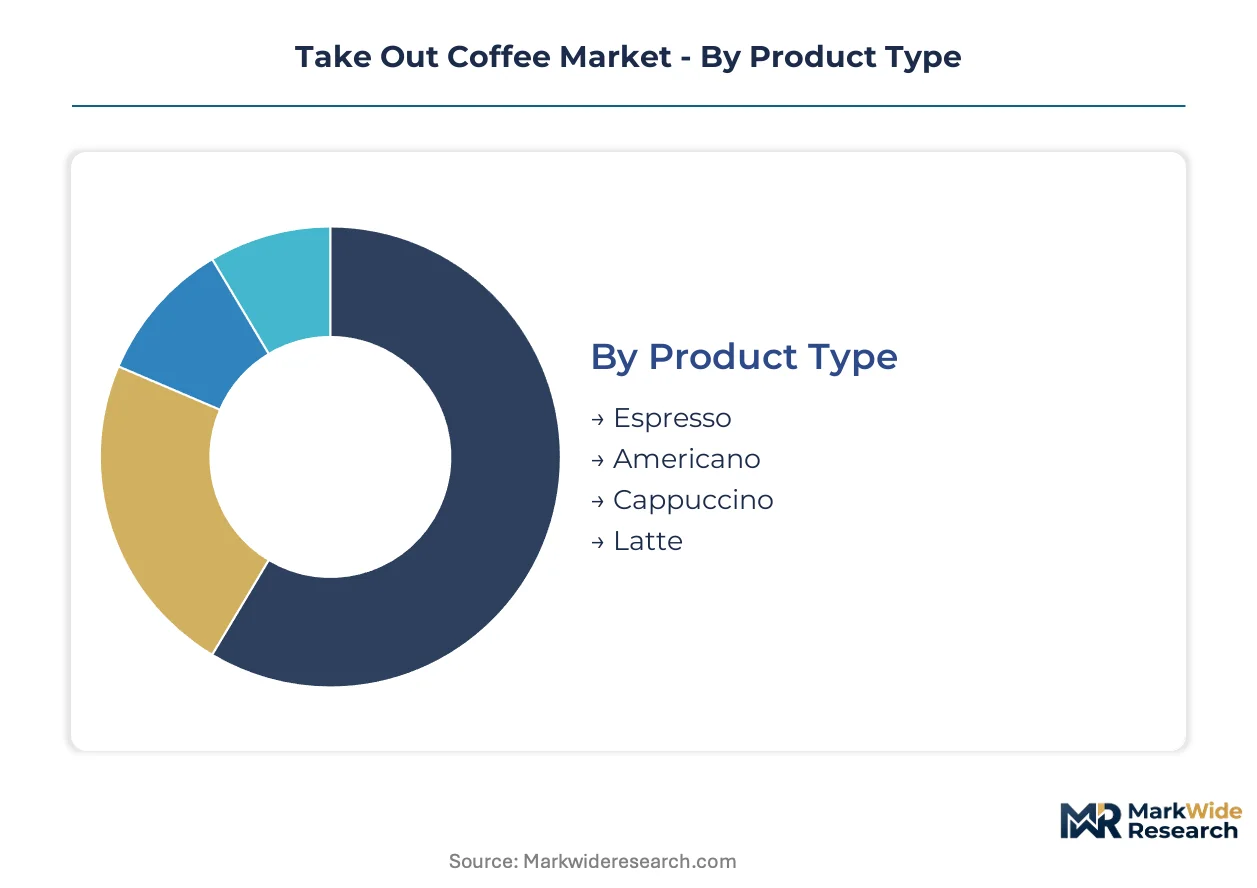
Take out coffee segmentation reveals distinct margin profiles and substitution vulnerabilities across product formats and channel economics. Equipment intensity, labor requirements, and packaging compliance costs vary sharply by segment, directing capital deployment toward formats with scalable throughput and regulatory insulation.
Product Type:
Substitution pressure from at-home espresso systems and workplace brewing equipment weighs most heavily on standardized black coffee formats, while milk-integrated preparations retain differentiation through texture engineering that consumer equipment cannot replicate.
- Latte:Espresso combined with steamed milk creates the highest per-unit revenue format through dairy input costs and preparation labor. Demand concentrates in U.S. and Chinese urban corridors where drive-through throughput engineering maximizes morning commuter capture. Barista training requirements and milk refrigeration infrastructure create format-specific barriers to rapid scaling.
- Cappuccino:Foamed milk texture demands precise steam wand technique and equipment calibration that automated systems struggle to replicate at volume. European markets maintain the strongest preference density, though afternoon consumption patterns in São Paulo and Melbourne are expanding addressable dayparts.
- Espresso:Concentrated extraction served without milk integration faces direct substitution from capsule systems and workplace super-automatic machines. Premium positioning depends on bean provenance transparency and roast-date freshness signaling.
- Americano:Diluted espresso format carries the lowest equipment barrier to entry and faces intense price competition from filter coffee alternatives in convenience store channels.
Latte retains volume leadership; Cappuccino holds the steepest expansion curve.
Customer Type:
Cost tier stratification separates weekday routine consumption from discretionary weekend and travel occasions, with professionals commanding the highest per-capita spend and frequency metrics.
- Professionals:Weekday commuter patterns in dense metropolitan employment zones generate predictable morning and afternoon peak demand. Corporate subscription programs in London and Singapore are capturing this segment through on-premise brewing contracts that displace individual café visits.
- Students:Price sensitivity and campus proximity requirements concentrate demand near university districts in Boston, Berlin, and Beijing. Mobile-ordering platforms with loyalty point accumulation retain this cohort despite lower per-transaction values.
- Tourists:Seasonal and location-dependent demand concentrates in historic city centers and transportation hubs where queue tolerance exceeds local norms. Disposable income elevation during travel occasions supports premium pricing acceptance.
- Families:Multi-beverage orders and food attachment opportunities drive higher basket values, though frequency trails individual consumption patterns. Drive-through lane design accommodating vehicle occupancy shapes format suitability.
Professionals anchor revenue density; Students are gaining share fastest through app-based platform penetration.
Distribution Channel:
Capital efficiency and zoning friction determine expansion velocity, with formats requiring minimal real estate footprint and regulatory approval outpacing traditional storefront development.
- Convenience Stores:Petroleum retail network integration in Brazil and Mexico extends distribution without standalone construction timelines or municipal permitting delays. Equipment-plus-bean supplier contracts consolidate procurement for facility operators seeking single-vendor relationships.
- Food Trucks:Mobility permits rapid demand testing and relocation toward event-based or construction-site concentrations. Regulatory fragmentation across municipal food safety jurisdictions complicates multi-city scaling.
- Cafés:Traditional storefront formats face rising real estate costs in prime urban corridors and increasing labor intensity relative to automated alternatives. Third-place positioning retains relevance in markets with strong sidewalk culture.
- Vending Machines:Bean-to-cup automation reduces labor to zero but requires specialized maintenance capabilities and frequent restocking logistics that constrain placement density.
Cafés retain volume leadership; Convenience Stores hold the steepest expansion curve.
Flavor Profile:
Maturity gradients separate established unflavored preparations from syrup-integrated variants where innovation cycles and seasonal limited releases drive traffic and social media engagement.
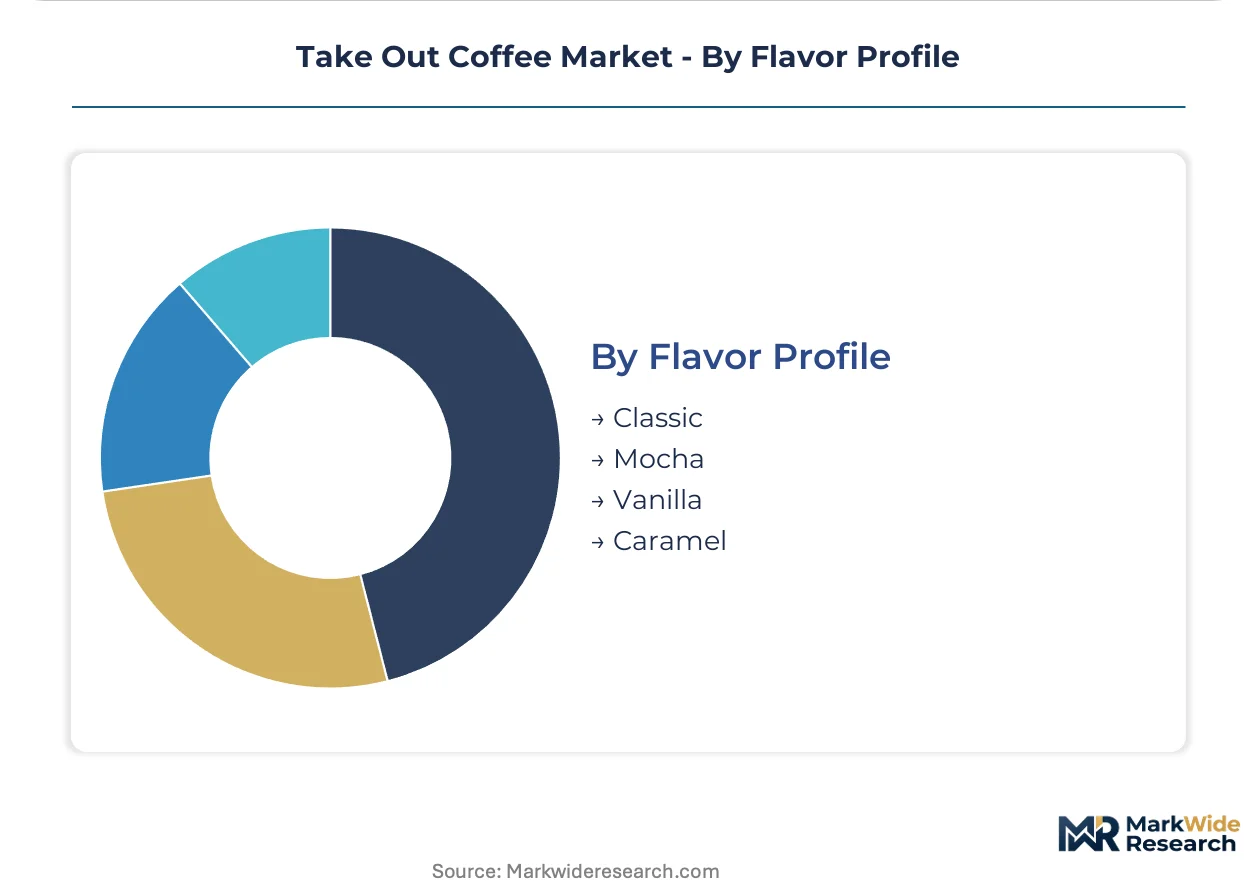
- Classic:Unflavored coffee preparation commands the broadest demographic acceptance and lowest input cost structure. Purist positioning in Italian and Australian markets resists syrup integration despite mainstream adoption elsewhere.
- Vanilla:Syrup integration creates the highest attachment rate among younger demographics and afternoon consumption occasions. Supply chain concentration in flavor house procurement creates formulation dependency risks.
- Caramel:Seasonal menu rotation and holiday-themed limited releases generate periodic demand spikes that strain production scheduling and inventory management systems.
- Mocha:Chocolate integration doubles ingredient complexity and allergen disclosure requirements while commanding premium pricing through perceived indulgence positioning.
Classic retains volume leadership; Vanilla holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States commuters favor drive-through velocity with afternoon daypart expansion, while Chinese urbanites prioritize app-based ordering infrastructure and Brazilian consumers integrate petroleum retail networks into daily coffee rituals.
United States
Morning and afternoon workplace commuter patterns sustain volume density across metropolitan corridors. FDA food-contact material rules and municipal polystyrene bans in coastal cities compress margins for non-compliant operators. Real estate density in Seattle and Los Angeles anchors Starbucks' unmatched storefront positioning.
China
App-based ordering penetration in Beijing and Shanghai reduces labor per transaction while extending peak-hour capacity. GB standards for food-contact materials and packaging waste frameworks govern cup composition and recyclability claims. Luckin Coffee dominates mobile-ordering infrastructure in tier-one urban clusters.
Brazil
Petroleum retail network integration drives capital-light expansion through convenience store channels. ANVISA food safety protocols and municipal waste ordinances shape packaging compliance thresholds. São Paulo's afternoon consumption patterns expand addressable dayparts beyond traditional morning peaks.
Germany
EU Green Deal packaging mandates and REACH substance restrictions accelerate fiber-based cup adoption. Extended producer responsibility schemes expand addressable market for certified compostable suppliers. Berlin and Hamburg pilot plant-fiber molded pulp vessels at sustainability premiums.
India
Underdeveloped drive-through infrastructure in Mumbai and Bangalore metro regions offers first-mover positioning. FSSAI food-contact material rules tighten compliance requirements for biodegradable supply chains. Corporate subscription programs in Delhi-NCR capture weekday professional consumption.
Take Out Coffee Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with format-specific velocity engineers and regional convenience operators occupying distinct competitive positions. The market structures around three archetypes: real estate-dense metropolitan incumbents, app-native digital-first platforms, and high-throughput drive-through specialists. Dominant competitive moves include automation-compatible workforce restructuring and multi-jurisdiction packaging compliance pre-positioning.
Within the integrated leader tier, Starbucks and Luckin Coffee exemplify divergent geographic dominance strategies, with the former anchoring U.S. metropolitan real estate density and the latter occupying Chinese digital infrastructure. Dutch Bros represents the high-velocity drive-through archetype, minimizing labor per transaction through lane-format engineering. Scooter's Coffee, 7 Brew, and Black Rock Coffee Bar sit within the regional specialist tier, expanding through capital-efficient formats in secondary U.S. markets.
| Leading Market Players |
|---|
| Scooter's Coffee |
| Luckin Coffee |
| Starbucks |
| Aroma Joe's |
| Paris Baguette |
| Dunkin' |
| 7 Brew |
| Black Rock Coffee Bar |
| Dutch Bros |
| Others |
Value Network & Pricing Analysis
Eighty-day inventory cycles for green Arabica beans concentrate margin pressure on roasters lacking forward-contract coverage, amplifying pricing power asymmetry between vertically integrated chains and independent operators dependent on spot markets. This lead-time exposure shapes how procurement scale translates into cost insulation across tier-one and tier-two market positions.
Pricing Analysis
Long-term offtake agreements with Brazilian and Colombian cooperatives anchor input cost predictability for integrated roasters, while spot-market exposure dominates procurement for mid-tier independents. Three-tier pricing structure across premium single-origin, standard espresso blends, and economy filter tiers separates Starbucks and Luckin Coffee from convenience store competitors. Pricing pressure stems from Arabica futures volatility transmitting through to menu boards, with students and campus-adjacent locations exhibiting highest price sensitivity and corporate subscription clients showing lowest elasticity.
Supply Chain Analysis
Panama Canal transit constraints and Santos port congestion in Brazil periodically choke bean flow to U.S. and European roasting facilities, amplifying working capital requirements during harvest windows. Supply concentrates in Brazil, Colombia, and Vietnam for green coffee sourcing, with Germany and Italy anchoring European roasting infrastructure. Input dependencies span temperature-retentive cup manufacturing in China, dairy supply networks in regional production zones, and flavor syrup formulation from concentrated flavor houses. Single-source vulnerability in compostable barrier coating technology creates stockout risk during EU Green Deal transition periods. Distribution runs through direct-store-delivery for café chains, petroleum retail networks for convenience store channels, and third-party logistics for mobile-order fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face intensifying substitution pressure from workplace super-automatic brewing systems and at-home espresso equipment that erodes weekday commuter traffic. Defense requires preemptive positioning before corporate facilities managers consolidate around on-premise vendor contracts.
For Market Incumbents: Consolidate procurement scale through backward integration into roasting infrastructure and exclusive supplier contracts with certified compostable packaging converters. Lock in multi-year green coffee offtake before futures volatility intensifies. Preempt corporate subscription displacement by embedding equipment-plus-bean contracts directly with facilities managers in London and Singapore finance verticals.
For New Entrants and Emerging Players: Differentiate on fiber-based vessel compliance pre-positioning before FSSAI rules tighten in Indian metro corridors. Target underdeveloped drive-through infrastructure in Mumbai and Bangalore where real estate density remains below U.S. or Chinese benchmarks. Pursue capital-light kiosk integration within Brazil's petroleum retail networks to bypass standalone zoning friction.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because packaging compliance pre-positioning creates acquisition premiums as EU Green Deal and municipal polystyrene bans compress margins for non-compliant operators. Target regional drive-through specialists with automation-compatible workforce structures and established mobile-order platforms. Watch for inflection when extended producer responsibility schemes trigger forced consolidation among packaging-dependent independents.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Packaging Pre-Positioning | FSSAI and EU Green Deal alignment creates certification-premium positioning before compliance deadlines compress competitor margins. |
| Drive-Through Format Expansion | High-lane-count throughput engineering in U.S. and Indian metros captures commuter demand across extended morning and afternoon dayparts. |
| Mobile-Ordering Infrastructure Investment | App-based labor optimization in Chinese and Brazilian urban corridors extends peak-hour capacity without proportional real estate expansion. |
| Corporate Subscription Program Development | Single-source equipment-plus-bean contracts with London and Singapore facilities managers displace individual café visit frequency. |
| Green Coffee Forward Contracting | Long-term offtake agreements with Brazilian cooperatives insulate roasting margins from weather-driven Arabica futures volatility. |
Research Methodology
Operator-level perspectives from café chain procurement directors, packaging converter technical leads, and petroleum retail network category managers anchored the qualitative base for this analysis. Primary fieldwork combined with secondary validation from FDA food-contact material filings, EU Green Deal implementation timelines, and Brazilian customs export data. Bottom-up triangulation across metropolitan store-count expansion and top-down reconciliation against national coffee consumption surveys shaped volume estimates.
Sensitivity analysis around Arabica price volatility bands and regulatory compliance timeline scenarios framed the forecast envelope across the projection horizon. Segmentation modeling spanned product type, customer archetype, distribution channel, and flavor profile dimensions, with additional granularity on automation penetration by format. CAGRs derived from trend-line extrapolation adjusted for mobile-ordering platform saturation curves and drive-through lane-count expansion trajectories in priority metro corridors.
Material uncertainties — Brazilian harvest yield shocks, EU perfluorinated compound prohibition acceleration, and municipal polystyrene ban diffusion — sit outside the modeled envelope and could compress or extend growth trajectories. Forecasts reflect documented assumptions on consumer mobility patterns and workplace return-to-office density. Practitioners should keep alternative scenarios live as extended producer responsibility scheme implementation dates and FSSAI packaging rule finalization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Drip Coffee Machine Market
Coffee
Cafix Market
Coffee
Global Coffee Market
Coffee
India Ready-To-Drink (RTD) Coffee Market
Coffee
China Ready-To-Drink (RTD) Coffee Market
Coffee
South America Coffee Market
Coffee
Coffee Pods Market
Coffee
Out-Of-Home Coffee Market
Coffee
North America Instant Coffee Market
Coffee
Ground Coffee Market
Coffee
Coffea Arabica (Coffee) Seed Oil Market
Coffee
Raw Coffee Beans Market
Coffee
Stove Top Moka Coffee Pot Market
Coffee
Global Cafe Market
Coffee
Encapsulated Caffeine Market
Coffee
Coffee Syrup Market