
 Ezekiel Bread Market | 2026-2036
Ezekiel Bread Market Size, Share, and Industry Trends Forecast 2026-2036
Ezekiel Bread Market Foresight
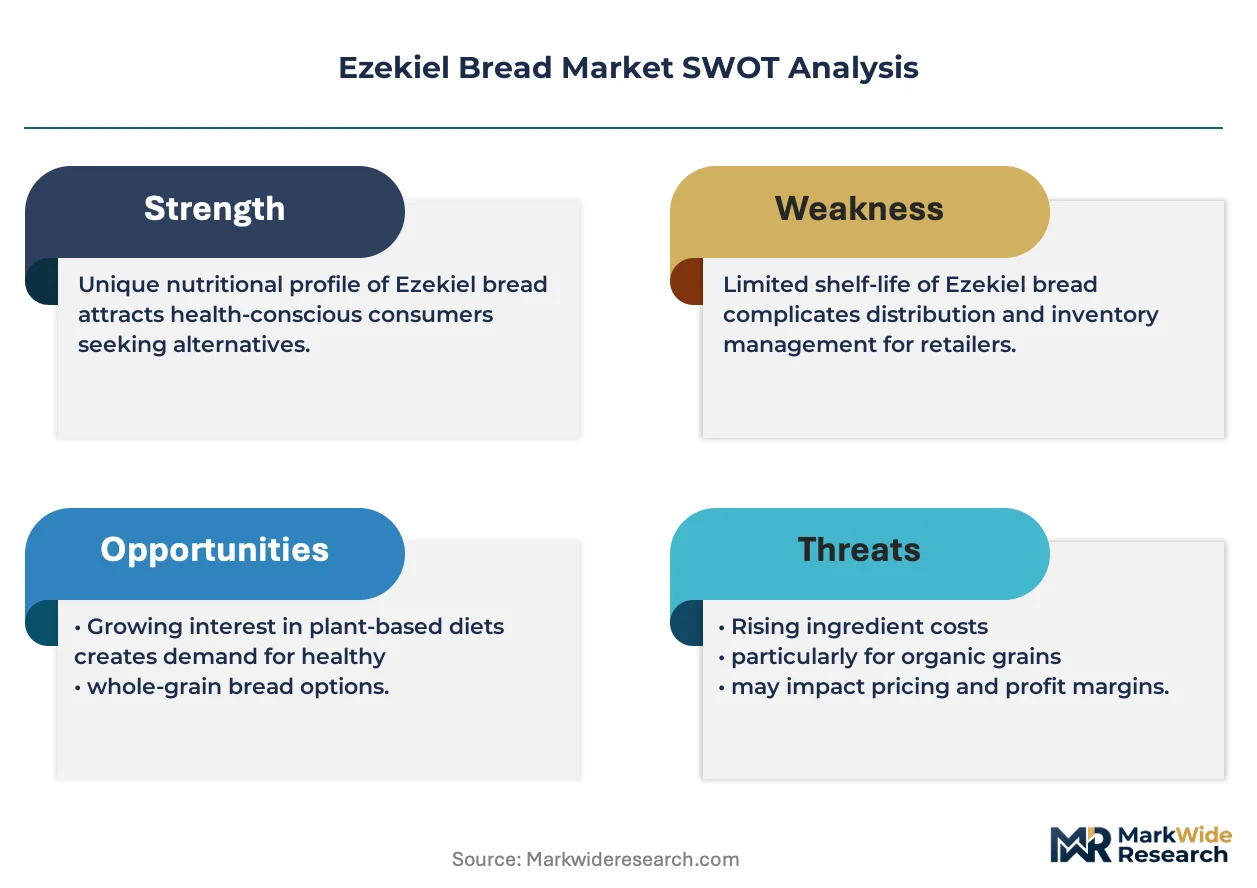
Sprouted grain processing technology is narrowing the efficiency gap between artisan-scale and commercial-batch Ezekiel bread production. Food for Life leverages proprietary sprouting protocols to anchor its position in certified organic channels. Alvarado Street Bakery sustains worker-cooperative ownership while competing on West Coast retail shelf space. Silver Hills Bakery specializes in non-GMO sprouted grain lines that dominate Canadian natural-food distribution and extend into US border markets.
Ezekiel bread refers to a dense, flourless loaf produced from sprouted wheat, barley, millet, spelt, lentils, and soybeans, with hydration levels typically below forty percent to preserve structural integrity during baking. Its primary commercial purpose centers on delivering complete-protein nutrition to consumers avoiding refined carbohydrates or seeking low-glycemic index alternatives. Loaf formats occupy the dominant share of shelf-stable revenue, while gluten-free variants command premium positioning despite smaller volume bases. Health enthusiasts represent the most concentrated consumer type, though diabetic-specific labeling is emerging as a faster-growing addressable niche.
The USDA National Organic Program and FDA food-labeling standards govern ingredient disclosure and health claim permissibility for Ezekiel bread sold in the United States. The Non-GMO Project verification framework shapes procurement contracts for sprouted grain suppliers seeking retail differentiation. State-level cottage food laws in Texas and California create fragmented pathways for small-batch producers entering direct-to-consumer channels. Stakeholders must monitor evolving sprouted grain safety guidelines while calibrating scale investments against regional certification requirements.
Market Dynamics
Sprouted grain processing automation is compressing production cycle times and eroding the artisan premium that historically justified higher shelf prices for Ezekiel bread. Commercial-scale germination chambers now replicate small-batch enzymatic activation with precision that threatens regional craft bakeries.
Growth Catalysts
- USDA Organic Program certification:Federal labeling standards create procurement pull chains that favor verified sprouted grain suppliers, locking conventional competitors out of premium retail slots.
- Low-glycemic index positioning:Diabetic consumer segments and metabolic health protocols drive repeat purchase velocity in pharmacy and clinical nutrition channels.
- Pacific Northwest cluster density:Washington and Oregon host concentrated clean-label bakery infrastructure that reduces inbound logistics costs for sprouted grain inputs.
Market Restraints
- Organic wheat input volatility:Certified grain premiums fluctuate with drought cycles in the Great Plains, compressing margin stability for fixed-price retail contracts.
- Sprouting facility concentration:North American commercial germination capacity clusters in California and Ontario, creating single-source vulnerability for East Coast distributors.
- Gluten-free substitution threat:Almond flour and cassava-based alternatives capture price-insensitive consumers seeking grain elimination rather than grain modification.
Strategic Opportunities
- Texas cottage food law expansion:Direct-to-consumer exemption thresholds for home-based bakeries enable micro-producers to test regional flavor variants without commercial lease overhead.
- Clinical nutrition channel penetration:Hospital outpatient retail and diabetes education centers represent unserved institutional volume for glycemic-labeled formats.
- Frozen dough technology convergence:Blast freezing combined with modified-atmosphere packaging extends distribution radius for fresh-baked texture upon thaw.
Industry Challenges
- Sprouted grain safety protocol gaps:FDA hazard analysis requirements for time-temperature controlled germination lack standardized validation methods, slowing new facility approvals.
- Skilled fermentation technician scarcity:Commercial enzyme management and mold prevention expertise concentrates among legacy artisan producers, constraining workforce scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ezekiel Bread Market |
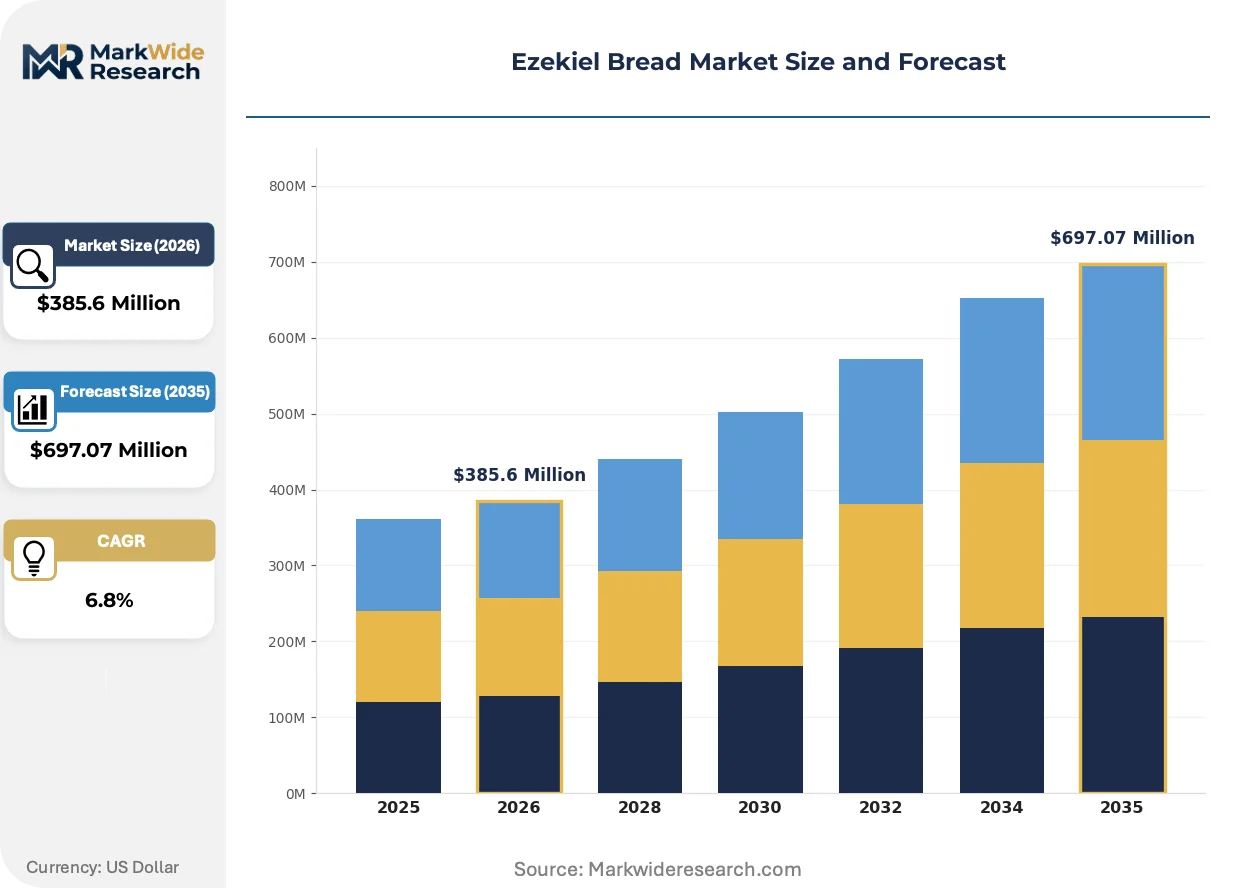
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loaf, Wraps, Buns, Croutons Ingredient Source: Organic Grains, Sprouted Grains, Whole Wheat, Gluten-Free Consumer Type: Health Enthusiasts, Vegetarians, Vegans, Diabetics Packaging Type: Plastic Bags, Paper Bags, Cardboard Boxes, Reusable Containers |
| Companies Covered | Allied Bakeries, ShaSha Bread Co., Food for Life, Berlin Natural Bakery, Bake House, Alvarado Street Bakery, Dave's Killer Bread, Rainbows Health Food, Silver Hills Bakery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ezekiel Bread Market Shifts & Advancements
Digital monitoring systems are penetrating sprouted grain production, replacing manual germination judgment with sensor-driven consistency. These platforms compress the expertise gap between craft and commercial operations while generating compliance documentation for organic auditors.
Hyperspectral imaging is virtualizing quality control in sprouted grain intake. Large-scale bakeries deploy inline spectroscopy to assess enzymatic activity without destructive sampling. California-based cooperatives adopt these systems fastest, using real-time data to adjust soak schedules. The technology is virtualizing the artisan intuition that previously commanded premium pricing.
EU Green Deal agricultural sustainability criteria are reshaping import sourcing for North American sprouted grain processors. Carbon footprint disclosure requirements for organic wheat now influence supplier selection in Rotterdam and Hamburg transshipment hubs. Canadian exporters respond by certifying prairie farm operations under parallel climate protocols to maintain European market access.
Subscription direct-to-consumer models are fragmenting traditional grocery channel concentration for Ezekiel bread. Health enthusiasts in Colorado and Vermont bypass retail markup through automated replenishment platforms. This behavior concentrates highest among diabetic-label buyers seeking predictable inventory without store visitation.
Ezekiel Bread Market Segmentation
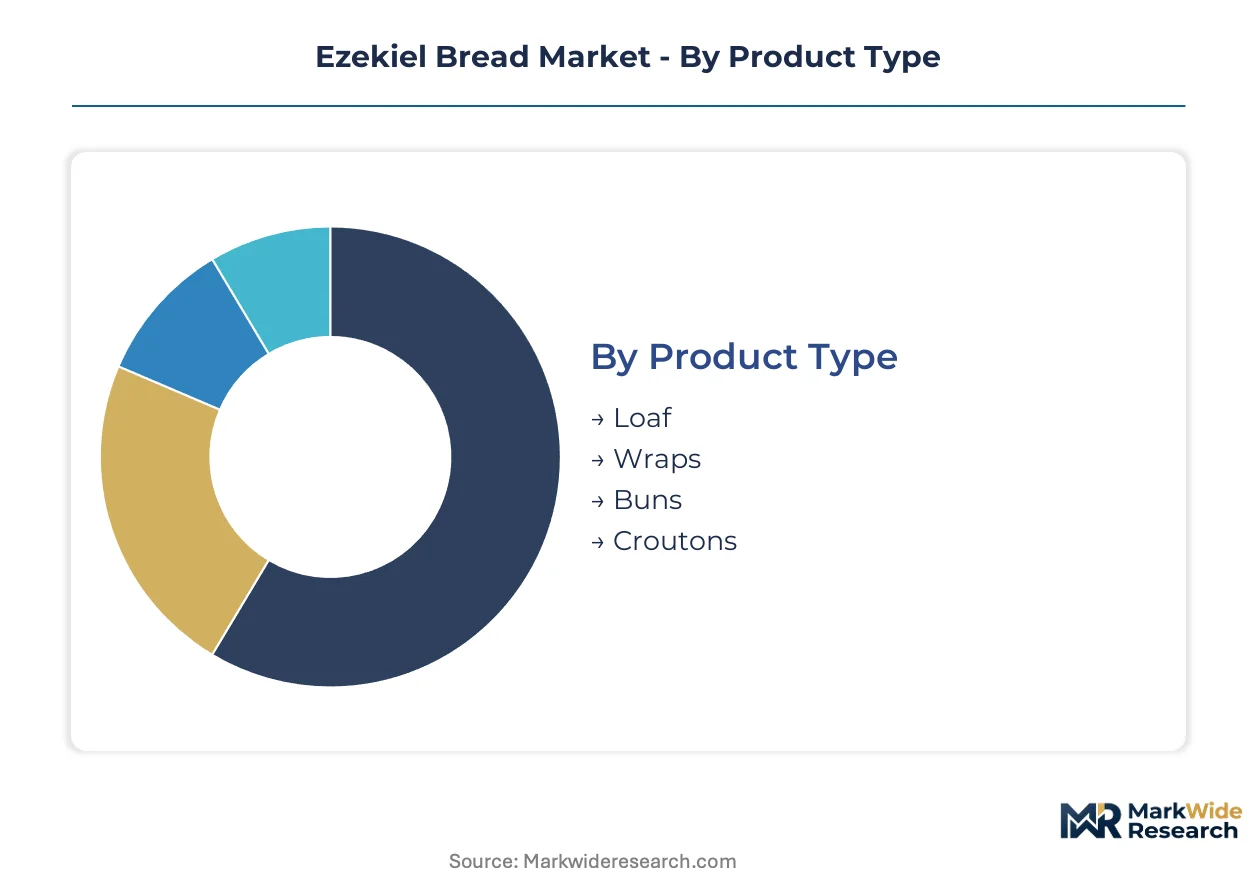
Ezekiel bread producers calibrate formulation density and shelf-stability against distinct consumption occasions. Product architecture, ingredient provenance, and packaging format each create separable addressable markets with divergent margin profiles and channel access requirements.
Product Type:
Volume concentration across formats tracks directly to consumption occasion frequency and storage practicality in household kitchens.
- Loaf:Dense rectangular formats dominate retail shelf space with hydration levels below forty percent to preserve structural integrity during extended baking cycles. Health enthusiasts in California and Pacific Northwest metropolitan areas drive repeat purchase velocity through specialty retail channels seeking complete-protein nutrition alternatives.
- Wraps:Thin-pressed circular sheets enable sandwich preparation without structural collapse, commanding premium positioning in foodservice and meal-kit channels. Demand concentrates among vegetarian and vegan consumer segments seeking portable protein delivery in workplace and travel contexts.
- Buns:Individual-portion rounds serve burger and sandwich applications with modified crumb density for structural load-bearing.
- Croutons:Cubed and toasted remnants target salad topping and soup accompaniment occasions with extended shelf-life through dehydration.
Loaf holds installed capacity. Wraps is rotating up the share rankings.
Ingredient Source:
Certification tier determines procurement cost structure and retail slot access through verified supply chain documentation.
- Organic Grains:USDA National Organic Program certification mandates input traceability from field to finished product, locking conventional competitors out of premium retail placement. Pacific Northwest cluster density reduces inbound logistics costs for certified wheat and barley suppliers.
- Sprouted Grains:Enzymatic activation during controlled germination increases bioavailable nutrient density and reduces antinutrient content. Commercial-scale germination chambers in California and Ontario now replicate artisan-batch precision, compressing production cycle times.
- Whole Wheat:Unsprouted intact bran and germ inclusion delivers fiber-forward positioning at lower price points.
- Gluten-Free:Almond flour and cassava-based alternatives capture consumers seeking grain elimination rather than grain modification.
Organic Grains commands margin premiums. Sprouted Grains is climbing the fastest.
Consumer Type:
Health condition specificity and dietary protocol adherence create distinct purchasing patterns and label literacy requirements.
- Health Enthusiasts:Fitness-oriented consumers prioritize complete amino acid profiles and low-glycemic index credentials in routine meal planning. Colorado and Vermont demonstrate highest subscription direct-to-consumer penetration through automated replenishment platforms.
- Diabetics:Glycemic-labeled formats drive pharmacy and clinical nutrition channel expansion with predictable inventory management needs. Hospital outpatient retail represents unserved institutional volume for certified low-glycemic positioning.
- Vegetarians:Plant-forward consumers seek protein density without animal ingredient inclusion.
- Vegans:Strict plant-based protocol adherence demands verification of honey and dairy absence in processing environments.
Health Enthusiasts holds established volume. Diabetics is gaining share fastest.
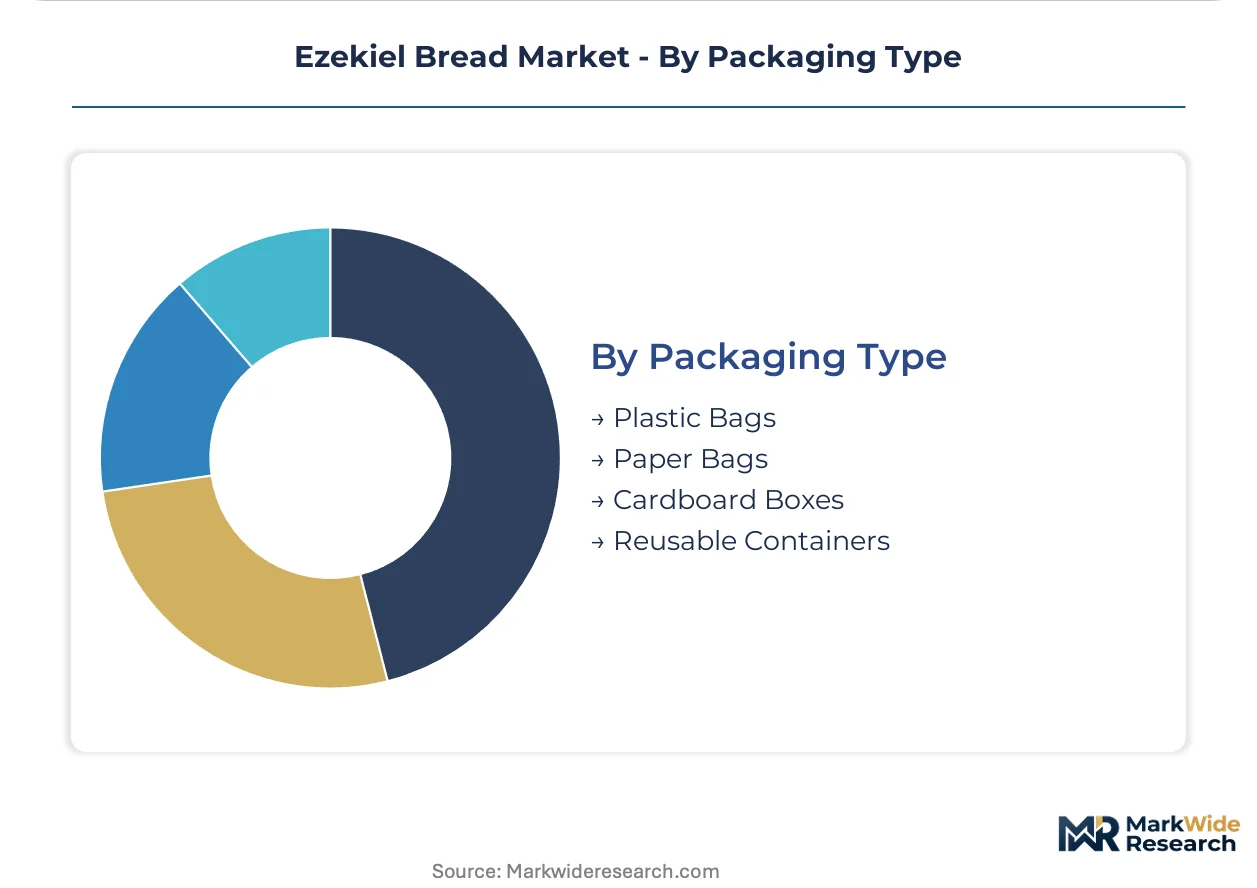
Packaging Type:
Material selection balances shelf-life extension, sustainability signaling, and cost per unit in channel-specific distribution.
- Plastic Bags:Modified-atmosphere polyethylene extends mold-free duration through oxygen barrier properties. Frozen dough technology convergence enables blast freezing combined with gas-flushed packaging for extended distribution radius.
- Reusable Containers:Deposit-return systems in Vermont and Colorado test direct-to-consumer circularity models with higher per-unit acquisition cost offset by loyalty program integration.
- Paper Bags:Kraft-based breathable enclosures signal artisan authenticity in farmers market and bakery-direct channels.
- Cardboard Boxes:Rigid secondary protection enables e-commerce shipment without compression damage.
Plastic Bags holds infrastructure scale. Reusable Containers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian sprouted grain processors export frozen dough formats into the US Northeast and Midwest, leveraging proximity to dense clean-label retail networks. This cross-border trade flow anchors North American supply while European and Asian markets develop parallel certification frameworks.
United States
California and Pacific Northwest metropolitan areas concentrate health enthusiast demand through specialty retail channels. The USDA National Organic Program governs ingredient disclosure and certification requirements for domestic producers. Los Angeles and Seattle host dense clean-label bakery clusters that reduce inbound logistics costs for certified wheat suppliers.
Canada
Prairie provinces supply organic wheat and barley to North American germination facilities with expanding US border market penetration. Health Canada and the PMRA regulate pesticide residue thresholds in grain imports. Ontario hosts commercial-scale germination capacity that serves East Coast distributors with compressed delivery cycles.
Germany
EU Green Deal agricultural sustainability criteria reshape import sourcing for sprouted grain processors serving Rotterdam and Hamburg transshipment hubs. EFSA governs novel food approvals and health claim permissibility. Bavaria and Baden-Württemberg host artisan bakeries that compete with North American frozen dough imports.
United Kingdom
London and Southeast England demonstrate subscription direct-to-consumer penetration among diabetic-label buyers seeking predictable inventory. The Food Standards Agency regulates sprouted grain safety protocols with parallel organic certification frameworks. Midlands-based distributors test deposit-return reusable container models.
Australia
New South Wales and Victoria host growing clean-label bakery infrastructure with export orientation toward Southeast Asian markets. The TGA governs clinical nutrition channel health claims for glycemic-labeled formats. Sydney-based cooperatives adopt hyperspectral imaging for enzymatic activity assessment.
Ezekiel Bread Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented shelf-space allocations in natural-food retail. The vendor base clusters around three strategic archetypes: certified organic specialists leveraging proprietary sprouting protocols, worker-cooperative structures competing on ownership transparency, and non-GMO focused lines dominating border markets. Dominant competitive moves include geographic expansion into clinical nutrition channels and portfolio diversification toward frozen dough technology.
Within the certified organic tier, Food for Life and Alvarado Street Bakery exemplify divergent structural approaches to West Coast retail penetration. Silver Hills Bakery anchors the non-GMO sprouted grain archetype with Canadian base operations extending into US border markets. These three entities represent the primary competitive anchors shaping procurement contract terms and certification requirements across North American distribution networks.
| Leading Market Players |
|---|
| Allied Bakeries |
| ShaSha Bread Co. |
| Food for Life |
| Berlin Natural Bakery |
| Bake House |
| Alvarado Street Bakery |
| Dave's Killer Bread |
| Rainbows Health Food |
| Silver Hills Bakery |
| Others |
Supply & Pricing Matrix
Ontario's commercial germination capacity anchors North American sprouted grain supply, with California's Central Valley forming a secondary hub whose capacity dynamics translate directly into pricing power for organic-certified Ezekiel bread. These dual concentration points create tiered margin structures where proximity to germination infrastructure determines wholesale cost baselines for downstream distributors.
Pricing Analysis
Manual germination versus automated chamber technology drives the dominant pricing gap in Ezekiel bread production. Three-tier pricing structure across certified organic, non-GMO verified, and conventional sprouted tiers separates retail shelf positioning, with USDA Organic certification commanding the widest premium. Pricing pressure stems from gluten-free almond flour substitutes capturing price-insensitive consumers seeking grain elimination. Diabetic-label buyers demonstrate lowest price sensitivity due to clinical protocol adherence, while standard health enthusiasts exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between Canada and the United States dominates supply chain risk for frozen dough cross-border shipments. Ontario, California, and Manitoba concentrate commercial germination infrastructure, with organic wheat inputs drawing from Great Plains prairie provinces and upper Midwest states. Single-source vulnerability concentrates in California's drought-exposed Central Valley for sprouted soybean supply. Distribution runs through natural-food retail cooperatives and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ezekiel bread functions as a service-attach opportunity where subscription replenishment platforms and clinical nutrition channel partnerships expand recurring revenue faster than unit sales growth in traditional grocery. Automated delivery scheduling and glycemic management coaching represent attach layers accelerating faster than loaf-format production.
For Market Incumbents: Insulate market position by deepening captive supply of certified organic grain through backward integration into Great Plains farm partnerships. Lock in FDA-compliant germination documentation protocols ahead of standardized safety validation requirements. Channel control through exclusive clinical nutrition distribution agreements defends against frozen dough imports from Canadian processors. For New Entrants and Emerging Players: Build out micro-production capacity under Texas cottage food law thresholds to test regional flavor variants without commercial lease overhead. Texas and Southeast US direct-to-consumer channels represent the most penetrable white space. Hospital outpatient retail partnerships offer a specific go-to-market angle for glycemic-labeled formats. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-platform-enabled brands with diabetic-label positioning. Long-term viability across the five-to-ten year window favors acquisition targets with proprietary sprouting protocols and USDA Organic certification locked in. Watch for FDA publication of standardized sprouted grain safety guidelines as the inflection signal for facility approval velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Nutrition Channel Partnership | Hospital outpatient retail integration expands institutional volume for glycemic-labeled Ezekiel bread formats. |
| Backward Integration into Organic Grain Supply | Captive sourcing from Great Plains prairie farms stabilizes input costs against drought-driven premium volatility. |
| Frozen Dough Technology Investment | Blast freezing combined with modified-atmosphere packaging extends distribution radius for fresh-baked texture. |
| Subscription Platform Launch | Automated replenishment in Colorado and Vermont concentrates highest among diabetic-label buyer segments. |
| Hyperspectral Imaging Quality Control | Inline spectroscopy adoption virtualizes artisan intuition while generating compliance documentation for USDA organic auditors. |
Research Methodology
Desk research of FDA food-labeling standards, USDA National Organic Program documentation, and Health Canada regulatory filings preceded structured interviews with sprouted grain facility managers, natural-food retail category buyers, clinical nutrition procurement leads, and organic certification auditors. Primary fieldwork with California and Ontario germination chamber operators combined with secondary validation through trade customs data and cooperative bakery financial disclosures. Bottom-up production capacity estimates triangulated against top-down retail scan data across the analysis window.
Assumptions regarding USDA Organic certification retention rates and FDA sprouted grain safety protocol timelines were held fixed, while organic wheat input cost volatility and gluten-free substitution rates were varied across sensitivity scenarios. Segmentation dimensions modeled include product format, certification tier, consumer health condition, and packaging type alongside regional cluster density. CAGRs were derived from installed capacity expansion trajectories and channel penetration curves, with sprouted grain processing automation adoption and direct-to-consumer subscription growth as primary industry-specific forecast inputs.
Stress conditions across Great Plains drought cycles, FDA regulatory approval delays, and EU Green Deal carbon disclosure requirements were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledgment that sprouted grain safety validation standardization or trade policy shifts could revise trajectory materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Low-Calorie Toast Market
Bakery Products
US Frozen Bakery Market
Bakery Products
Frosting, Toppings, and Decorations Market
Bakery Products
Global Baked Food and Cereals Market
Bakery Products
Bakery Conditioner Market
Bakery Products
Bakers Yeast Market
Bakery Products
North America Par Baked Bread Market
Bakery Products
Instant Cake Gel Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
Bread Mix Market
Bakery Products
Aerating Cake Emulsifier Market
Bakery Products
Frozen Bakery Additives Market
Bakery Products
Pastry Dough Market
Bakery Products
Vegan Baking Mix Market
Bakery Products
Low Fat Chocolate Cake Market
Bakery Products
Premixed Bread Flour Market