
 Dough Conveyor Market | 2026-2036
Dough Conveyor Market Size, Share, and Industry Trends Forecast 2026-2036
Dough Conveyor Market Analytics
Multi-source equipment procurement is pivoting toward integrated system partnerships as bakeries seek single-vendor accountability for throughput reliability. Daifuku leverages its automotive automation heritage to compete in food-grade material handling with washdown-compatible designs. Dematic anchors its position through modular conveyor architectures that accommodate variable dough consistencies across bakery SKUs. SSI Schäfer differentiates via vertical integration into control software and warehouse execution systems that synchronize conveyor lines with downstream packaging.
A dough conveyor is a mechanized transport system engineered from food-grade stainless steel with belt surfaces rated for temperatures between minus twenty and plus one hundred ten degrees Celsius, designed to move fermented or unfermented dough masses between mixing, proofing, shaping, and baking stations without structural deformation or contamination. Spiral conveyors occupy the premium tier in product type segmentation due to their compact footprint and continuous elevation change capability in multi-level bakeries. Smart conveyor technology within the technology dimension is capturing accelerated capital allocation as IoT-enabled belt tension monitoring and predictive vibration analytics reduce unplanned downtime in three-shift operations. Horizontal conveyors remain the volume base across pizzerias and mid-scale bakeries where straight-line transfer between adjacent workstations satisfies layout constraints without complexity premiums.
FDA food contact substance regulations and EU Machinery Directive safety standards govern belt material composition and emergency stop architecture, compelling manufacturers to certify components for direct food contact and operator protection. BIS hygiene benchmarks in India and GB standards in China add parallel compliance layers for exporters targeting Asia-Pacific bakery automation projects. Stakeholders must monitor how ESG disclosure requirements from the EU Corporate Sustainability Reporting Directive reshape supplier qualification criteria for energy-efficient motor and drive systems in conveyor installations.
Market Dynamics
Commercial bakeries are consolidating automated handling lines around single-vendor accountability, compressing multi-source procurement cycles into integrated system partnerships that tie conveyor reliability to throughput guarantees.
Growth Catalysts
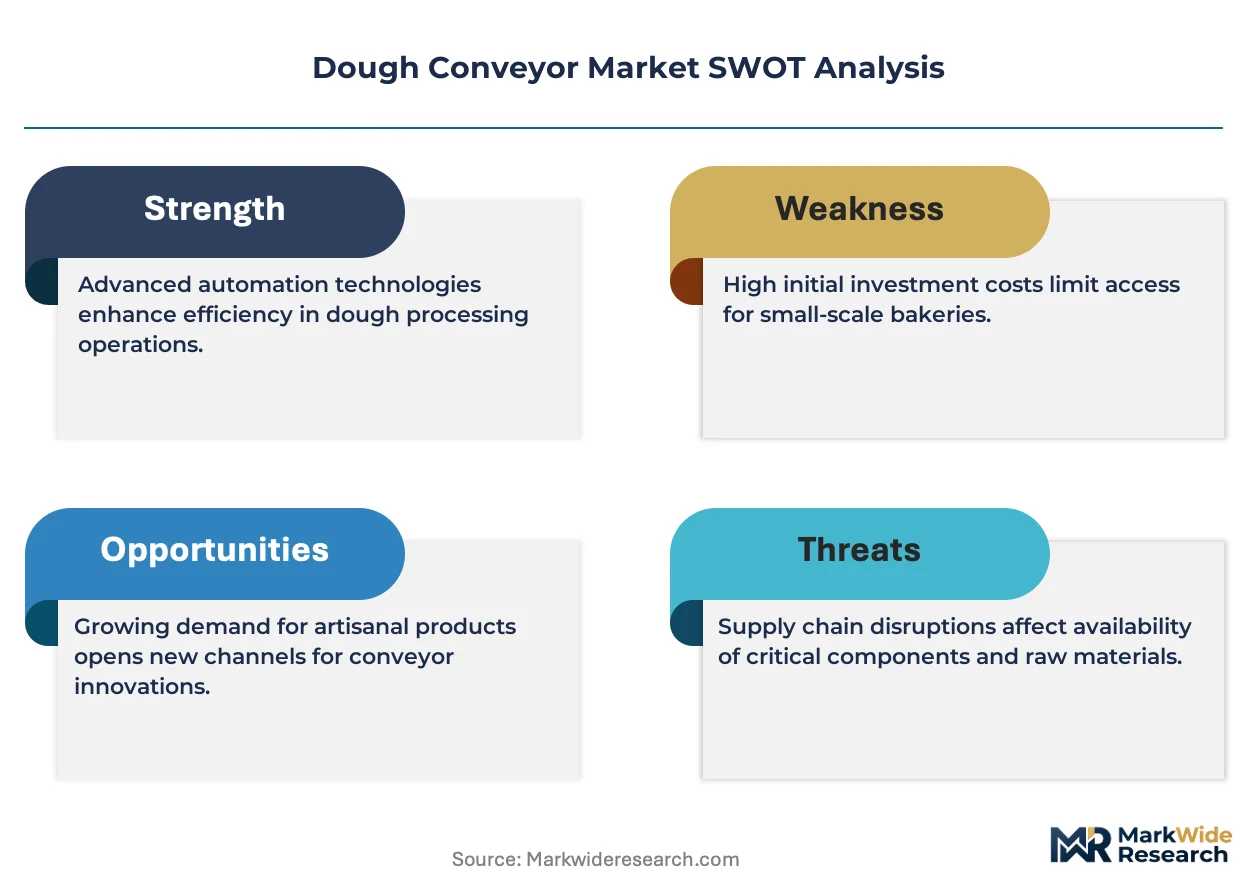
- EU Machinery Directive safety mandates:Emergency stop architecture and belt material certification requirements are forcing equipment upgrades across industrial baking clusters, accelerating replacement cycles for legacy installations.
- Stainless steel hygiene standards:FDA food contact substance regulations and EU food safety frameworks are disqualifying non-compliant components, redirecting capital toward washdown-compatible conveyor systems.
- Three-shift bakery operations:Predictive vibration analytics and IoT-enabled belt tension monitoring are reducing unplanned downtime in continuous production environments.
Market Restraints
- Food-grade stainless steel input volatility:Nickel and chromium price swings compress margin visibility for conveyor manufacturers locked into fixed-price maintenance contracts.
- Specialized drive motor supply concentration:IP65-rated washdown motors for bakery environments concentrate among a limited supplier base in Germany and Japan, creating procurement bottlenecks.
- Legacy PLC integration friction:Smart conveyor retrofits face protocol incompatibility with existing bakery control systems, extending commissioning timelines.
Strategic Opportunities
- India PLI scheme for food processing equipment:Domestic manufacturing incentives are lowering landed costs for European and Japanese conveyor vendors establishing local assembly operations.
- Spiral conveyor compact footprint demand:Multi-level urban bakeries in Tokyo and Singapore are specifying continuous elevation change systems to maximize production density.
- EU Corporate Sustainability Reporting Directive:ESG disclosure requirements for energy-efficient motor and drive systems are reshaping supplier qualification criteria toward regenerative drive architectures.
Industry Challenges
- Washdown electrical certification timelines:IP69K motor validation for high-pressure sanitation cycles extends product development cycles by eight to fourteen months.
- Retrofit integration complexity:Variable dough consistency algorithms from new smart conveyors clash with legacy proofing and shaping station control logic.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dough Conveyor Market |
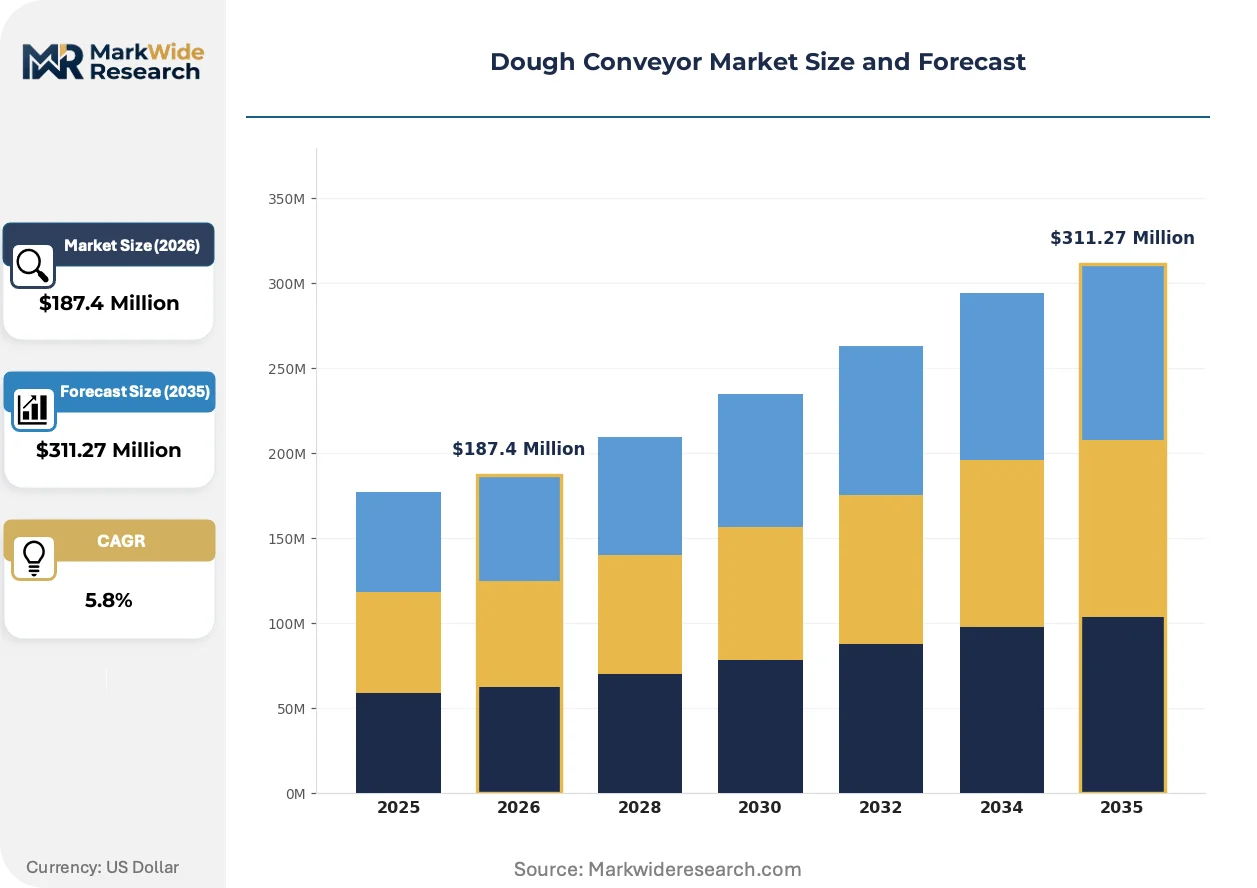
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
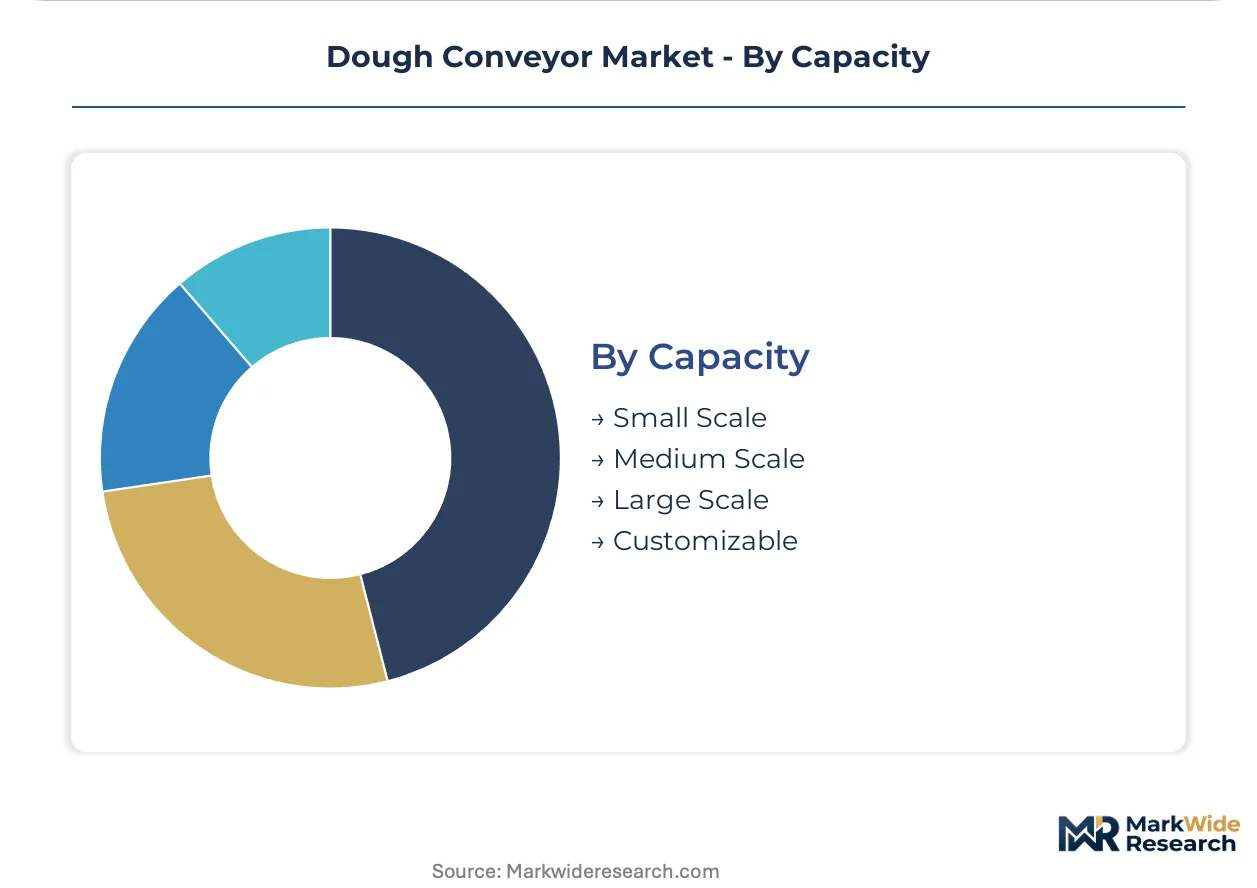
| Segmentation | Product Type: Horizontal Conveyor, Vertical Conveyor, Modular Conveyor, Spiral Conveyor End User: Bakeries, Pizzerias, Food Processing Plants, Restaurants Technology: Automated Systems, Manual Systems, Hybrid Systems, Smart Conveyor Capacity: Small Scale, Medium Scale, Large Scale, Customizable |
| Companies Covered | Daifuku, Dematic, SSI Schäfer, BEUMER Group, Interroll, Fives Intralogistics, Vanderlande, TGW Logistics, Honeywell Intelligrated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dough Conveyor Market Evolving Landscape
Smart conveyor architectures are compressing the gap between mechanical transport and digital process control, embedding predictive capabilities directly into belt drive systems.
IoT-enabled belt tension monitoring is expanding into mid-scale bakery operations previously priced out of predictive maintenance. Regional equipment lessors in Germany and Italy are bundling sensor subscriptions with conveyor rentals, lowering adoption barriers for pizzeria chains and artisan bakeries. This sensor-as-a-service model is expanding into secondary markets where capital constraints previously blocked automation investment.
REACH substance restrictions on perfluorinated compounds are eliminating legacy non-stick belt coatings from EU-sourced equipment. Conveyor manufacturers are qualifying ceramic-impregnated and plasma-treated stainless steel surfaces as direct food contact alternatives. Industrial baking clusters in the Netherlands and Belgium are accelerating validation timelines for these replacement materials to maintain export compliance.
Integrated system partnerships are displacing component-level procurement as bakeries seek single-vendor accountability for throughput reliability. Equipment finance houses in Chicago and Frankfurt are structuring performance-based lease arrangements where conveyor uptime guarantees determine payment schedules. This contractual shift concentrates procurement authority among vendors with captive control software and service networks.
Dough Conveyor Market Segmentation
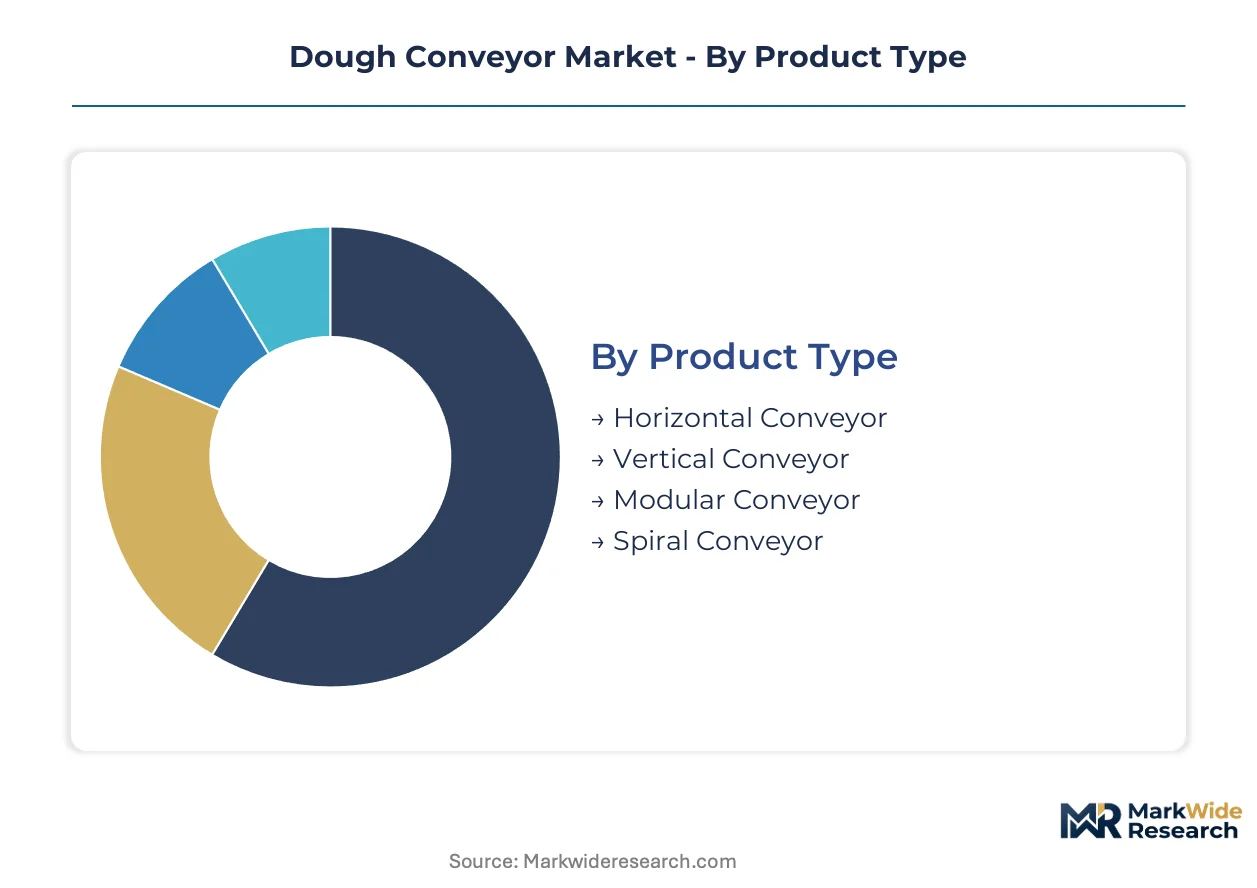
Dough conveyor segmentation reveals stark trade-offs between throughput volume and layout flexibility. Equipment specification diverges sharply between artisan-scale pizzerias prioritizing footprint economy and industrial bakeries demanding continuous elevation change capability.
Product Type:
Horizontal conveyors anchor volume shipments while spiral systems command premium positioning for vertical space optimization.
- Spiral Conveyor:Continuous elevation change mechanisms enable multi-level bakery layouts without floor space expansion. Demand concentrates in Tokyo and Singapore urban clusters where production density premiums justify capital outlay for compact footprint systems.
- Horizontal Conveyor:Straight-line belt configurations serve pizzerias and mid-scale bakeries with adjacent workstation layouts. Germany's industrial baking belt favors these systems for high-throughput mixing-to-proofing transfers where elevation change is unnecessary.
- Vertical Conveyor:Z-pattern lift mechanisms handle dough mass elevation between split-level production floors.
- Modular Conveyor:Reconfigurable segment architectures accommodate seasonal SKU variation and line rebalancing.
Today's leader: Horizontal Conveyor. Tomorrow's challenger: Spiral Conveyor.
End User:
Commercial bakeries drive specification complexity while food processing plants prioritize washdown durability.
- Bakeries:Industrial baking clusters specify stainless steel hygiene ratings and three-shift reliability guarantees. EU Machinery Directive compliance mandates dominate procurement criteria for automated handling line upgrades.
- Food Processing Plants:High-pressure sanitation cycles require IP69K motor validation and ceramic-impregnated belt surfaces replacing legacy non-stick coatings under REACH restrictions.
- Pizzerias:Mid-scale operators favor rental-subscription models with bundled sensor monitoring to bypass capital constraints.
- Restaurants:Limited throughput demands favor manual loading interfaces over full automation.
Food Processing Plants set the durability benchmark. Bakeries define the technology frontier.
Technology:
Smart systems are climbing the fastest while manual configurations retain cost-sensitive niches.
- Smart Conveyor:IoT-enabled belt tension monitoring and predictive vibration analytics embed directly into drive systems. Three-shift operations in Netherlands industrial clusters are accelerating adoption to compress unplanned downtime.
- Automated Systems:PLC-controlled synchronization with upstream mixing and downstream packaging stations dominates greenfield installations.
- Hybrid Systems:Manual loading with automated discharge accommodates variable batch sizes in artisan production.
- Manual Systems:Hand-crank or gravity-fed mechanisms persist in developing markets with unreliable power infrastructure.
Automated Systems hold current share. Smart Conveyor commands tomorrow's capital allocation.
Capacity:
Large scale installations concentrate procurement authority while customizable configurations address SKU proliferation.
- Large Scale:Continuous throughput designs with regenerative drive architectures meet EU Corporate Sustainability Reporting Directive energy disclosure requirements.
- Customizable:Variable speed and belt width adjustment accommodate seasonal product mix shifts without line replacement.
- Medium Scale:Fixed-parameter systems serve stable production schedules with predictable dough consistency.
- Small Scale:Compact tabletop units target independent bakeries with space constraints and intermittent operation.
Large Scale defines supplier relationships. Customizable capacity captures flexibility premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redirecting conveyor procurement toward jurisdictions with streamlined food-equipment certification pathways, compressing lead times for bakeries facing EU Machinery Directive compliance deadlines. Capital is migrating to markets where stainless steel fabrication costs and washdown motor availability create favorable total-cost-of-ownership profiles.
Germany
Industrial baking clusters in Lower Saxony and Bavaria anchor European capital investment in automated handling lines. EU Machinery Directive safety mandates and REACH substance restrictions on belt coatings are accelerating replacement cycles for legacy installations. The Munich-Stuttgart corridor concentrates specification authority for spiral conveyor systems serving multi-level urban bakeries.
United States
Commercial bakeries in Chicago and the Midwest industrial belt are consolidating procurement around integrated system partnerships with uptime guarantees. FDA food contact substance regulations govern belt material composition for direct dough contact surfaces. Equipment finance houses in Chicago are structuring performance-based lease arrangements where conveyor reliability determines payment schedules.
Japan
Tokyo's high-density urban bakeries specify compact spiral conveyor architectures to maximize production per square meter. METI industrial automation incentives support IoT-enabled belt tension monitoring adoption in three-shift operations. IP65-rated washdown motor supply concentrates among specialized drive manufacturers in the Nagoya industrial zone.
India
The PLI scheme for food processing equipment is lowering landed costs for conveyor vendors establishing local assembly operations in Maharashtra and Gujarat. BIS hygiene benchmarks add parallel compliance layers for equipment targeting domestic bakery automation projects. Industrial baking clusters in Pune and Ahmedabad are driving specification for customizable capacity systems accommodating seasonal SKU variation.
China
GB standards and dual carbon goals are reshaping supplier qualification criteria toward energy-efficient motor and drive systems in conveyor installations. Yangtze River Delta baking equipment manufacturers are qualifying ceramic-impregnated belt surfaces as REACH-compliant alternatives for export markets. Shanghai and Jiangsu province concentrate domestic demand for horizontal conveyor systems in mid-scale pizzeria chains.
Dough Conveyor Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue washdown-compatible automation heritage from adjacent material handling sectors. The vendor base stratifies across three tiers: automotive automation heritage players, modular conveyor architecture specialists, and warehouse execution system integrators. Strategic differentiation concentrates on captive control software, service network density, and regenerative drive architectures. Competitive moves center on integrated system partnerships replacing component-level procurement, and performance-based lease arrangements tying payment to uptime guarantees.
Among Japanese and German automation conglomerates, Daifuku and Dematic exemplify archetypes leveraging adjacent-sector expertise for food-grade applications. Daifuku represents the automotive-to-food automation migration pattern, while Dematic anchors modular architecture specialization. SSI Schäfer occupies a position within the warehouse execution system tier, where backward integration into control software creates differentiation. These three entities illustrate how competitive positioning depends on whether vendors control software layers, service networks, or drive system technologies.
| Leading Market Players |
|---|
| Daifuku |
| Dematic |
| SSI Schäfer |
| BEUMER Group |
| Interroll |
| Fives Intralogistics |
| Vanderlande |
| TGW Logistics |
| Honeywell Intelligrated |
| Others |
Value Network & Pricing Analysis
Stainless steel fabrication specialists in Lower Saxony and Bavaria anchor European production, and labor-cost differentials between German engineering clusters and emerging assembly operations in Maharashtra widen pricing-tier spreads across premium washdown-certified systems and mid-scale horizontal configurations.
Pricing Analysis
Distributor margins on spiral conveyor systems compress channel economics, with premium-tier pricing commanding certification premiums for FDA food contact substance compliance and EU Machinery Directive safety validation. Three-tier pricing structure across premium, standard, and economy levels separates regenerative drive architectures from fixed-speed alternatives from gravity-fed manual units. Price erosion runs through economy-tier horizontal conveyors as Chinese and Indian manufacturers expand stainless steel fabrication capacity. Food processing plants exhibit lowest price sensitivity due to IP69K washdown requirements, while pizzeria chains and artisan bakeries gravitate toward rental-subscription models to bypass capital constraints.
Supply Chain Analysis
Certification and qualification gating for IP65-rated washdown motors concentrates supply among specialized drive manufacturers in Germany and Japan, with BIS hygiene benchmarks in India and GB standards in China adding parallel compliance layers for exporters. Raw material dependencies center on food-grade stainless steel with nickel and chromium alloying, ceramic-impregnated belt surfaces replacing REACH-restricted non-stick coatings, and precision bearings rated for continuous operation. Single-source vulnerability in specialized motor supply creates procurement bottlenecks when demand spikes from three-shift bakery expansions. Distribution runs through equipment finance houses in Chicago and Frankfurt structuring performance-based lease arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU Machinery Directive compliance costs in Germany and the Netherlands run substantially higher than BIS-qualification pathways in Maharashtra and Gujarat, creating landed-cost advantages for vendors establishing local assembly.
For Market Incumbents: Deepen captive control software integration to defend against automotive automation heritage players migrating into food-grade material handling. Anchor service network density in industrial baking clusters to offset margin pressure from fixed-price maintenance contracts. Prioritize regenerative drive architecture R&D to meet EU Corporate Sustainability Reporting Directive energy disclosure requirements before qualification criteria harden. For New Entrants and Emerging Players: Capture pizzeria chain and artisan bakery segments through sensor-as-a-service rental models that bypass capital constraints blocking automation investment. Target India's PLI scheme beneficiaries in Pune and Ahmedabad with customizable capacity systems accommodating seasonal SKU variation. Pursue go-to-market partnerships with regional equipment lessors in Germany and Italy bundling IoT-enabled monitoring subscriptions. For Investors and Strategic Acquirers: Warehouse execution system integrators are the most active acquirer in this space, seeking backward integration into conveyor hardware to complement control software portfolios. Viability over the medium-term horizon hinges on single-vendor accountability contracts displacing component-level procurement. Monitor smart conveyor commissioning timelines as inflection indicator: protocol compatibility friction with legacy PLC systems signals integration complexity risk.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated System Partnership | Single-vendor accountability contracts tie conveyor reliability to throughput guarantees in three-shift operations. |
| Sensor-as-a-Service Launch | Regional lessors in Germany and Italy bundle IoT-enabled belt tension monitoring with equipment rentals. |
| Regenerative Drive Investment | Energy-efficient motor architectures satisfy EU Corporate Sustainability Reporting Directive supplier qualification criteria. |
| Ceramic-Impregnated Surface Validation | Replacement materials for REACH-restricted non-stick coatings maintain export compliance for EU-sourced equipment. |
| Local Assembly Expansion | India PLI scheme operations in Maharashtra and Gujarat lower landed costs for European and Japanese vendors. |
Research Methodology
Multiple input streams — plant engineer interviews, OEM procurement team discussions, aftermarket service head consultations, and equipment finance house structuring conversations — were reconciled against secondary validation from EU Machinery Directive filing databases, FDA food contact substance registrations, BIS hygiene benchmark documentation, and customs trade data on stainless steel equipment imports. Bottom-up shipment tallies by conveyor type and capacity tier were cross-checked against top-down capital expenditure patterns in industrial baking clusters.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation modeling spanning product architecture, end-use environment, automation technology tier, and capacity scale. CAGRs were derived from trend extrapolation of replacement cycle acceleration driven by regulatory compliance mandates. Forecast inputs incorporated stainless steel price volatility indices and washdown motor supplier lead time dynamics.
Underlying measurement precision varies by segment; smart conveyor and spiral system categories carry tighter precision than manual configurations due to concentrated vendor disclosure. Forecasts reflect assumptions on regulatory enforcement intensity and raw material price stabilization. A model refresh is warranted upon material change in EU REACH substance restriction scope or India PLI scheme extension timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bakery Fats Market
Bakery Products
Europe Sweet Biscuits Market
Bakery Products
Low-Gluten Emmer and Einkorn Flour Blends Market
Bakery Products
Low Fat Muffin Market
Bakery Products
Cake Base Discs Market
Bakery Products
North America Fortified Bakery Products Market
Bakery Products
Ice Cream Market
Bakery Products
Wedding Cakes Market
Bakery Products
United States Bread Market
Bakery Products
Qatar Bakery Product Market
Bakery Products
Waffle Market
Bakery Products
Sourdough Market
Bakery Products
Vegan Certified Cake Mixes Market
Bakery Products
Cakes, Pastries, and Sweet Pies Market
Bakery Products
Bread Dough Improver Market
Bakery Products
Flour Mixes Market