
 Biscuits Market | 2026-2036
Biscuits Market Size, Share, and Industry Trends Forecast 2026-2036
Biscuits Market Intelligence
The premium-commodity split in biscuits is rebalancing around ingredient provenance and price-per-kilogram expectations. Mondelēz International leverages its chocolate-biscuit fusion portfolio to command higher margins in developed markets. Britannia Industries anchors its position through deep distribution into India's tier-two and tier-three cities. ITC Limited differentiates via in-house flour milling and bakery ingredient sourcing.
Biscuits are baked cereal-based products, typically composed of wheat flour, sugar, fat, and leavening agents, formed through rotary molding, wire cutting, or laminating processes before oven drying to moisture levels below five percent. Cream biscuits and digestive segments dominate volume, while butter cookies capture disproportionate margin due to gift-packaging occasions and premium positioning. Wafer biscuits compete on manufacturing scale, with automated layering lines enabling cost leadership.
The FDA governs nutritional labeling and allergen declarations for biscuits sold in the United States, while the FSSAI enforces fortification standards and limits on artificial additives in India. The EU's F-Gas Regulation indirectly shapes packaging costs through refrigerant rules affecting cold-chain logistics for cream-filled variants. Stakeholders must monitor evolving sugar-tax proposals and front-of-pack labeling mandates that threaten reformulation timelines.
Market Dynamics
The biscuits market is restructuring around clean-label ingredient sourcing and front-of-pack labeling mandates, with FSSAI fortification requirements and EU F-Gas refrigerant rules forcing reformulation and cold-chain investment decisions across cream-filled and chocolate-coated segments.
Growth Catalysts
- Urban corridor demand concentration:Indonesia's Jakarta-Surabaya corridor drives volume expansion as convenience stores extend shelf space for packaged snacks. Modern trade penetration in Vietnamese cities accelerates premium biscuit adoption.
- FSSAI trans-fat mandates:Stricter labeling requirements for processed foods push manufacturers toward palm oil alternatives and reformulated fat blends. Compliance investments create barrier advantages for organized players with R&D infrastructure.
- Chocolate-biscuit fusion formats:Enrobing and co-extrusion technologies enable margin expansion through premium positioning. Gift-packaging occasions for butter cookies sustain price-per-kilogram premiums in developed markets.
Market Restraints
- Wheat flour input volatility:Global grain price fluctuations compress margins for standard biscuit categories lacking pricing power. In-house milling capabilities at ITC Limited and Britannia Industries partially insulate against commodity swings.
- Supply concentration in Southeast Asian palm oil:Dependency on Indonesian and Malaysian oleochemical suppliers exposes producers to export duty volatility and sustainability certification costs.
- Refrigerated logistics limitations:EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants raise cold-chain costs for cream-filled variants, constraining distribution reach in emerging markets with underdeveloped chilled infrastructure.
Strategic Opportunities
- India tier-two and tier-three city penetration:Deep distribution networks into secondary urban centers capture rising disposable incomes. Britannia Industries' rural stockist model demonstrates scalable last-mile architecture.
- Digestive and functional biscuit segments:Fortification with fiber, protein, and micronutrients aligns with FSSAI fortification standards. Health-positioned variants command shelf space in pharmacy and wellness retail channels.
- Automated wafer layering lines:Capital-intensive manufacturing scale enables cost leadership in volume-driven wafer categories. Technology convergence between extrusion and enrobing equipment reduces changeover downtime.
Industry Challenges
- Reformulation timeline compression:Front-of-pack labeling mandates and sugar-tax proposals in multiple jurisdictions force accelerated recipe redevelopment. Sensory equivalence maintenance during fat and sugar reduction demands extended pilot testing.
- Allergen management complexity:FDA nutritional labeling requirements and FSSAI allergen declarations necessitate segregated production lines and enhanced traceability systems. Cross-contamination risk audits consume operational bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biscuits Market |
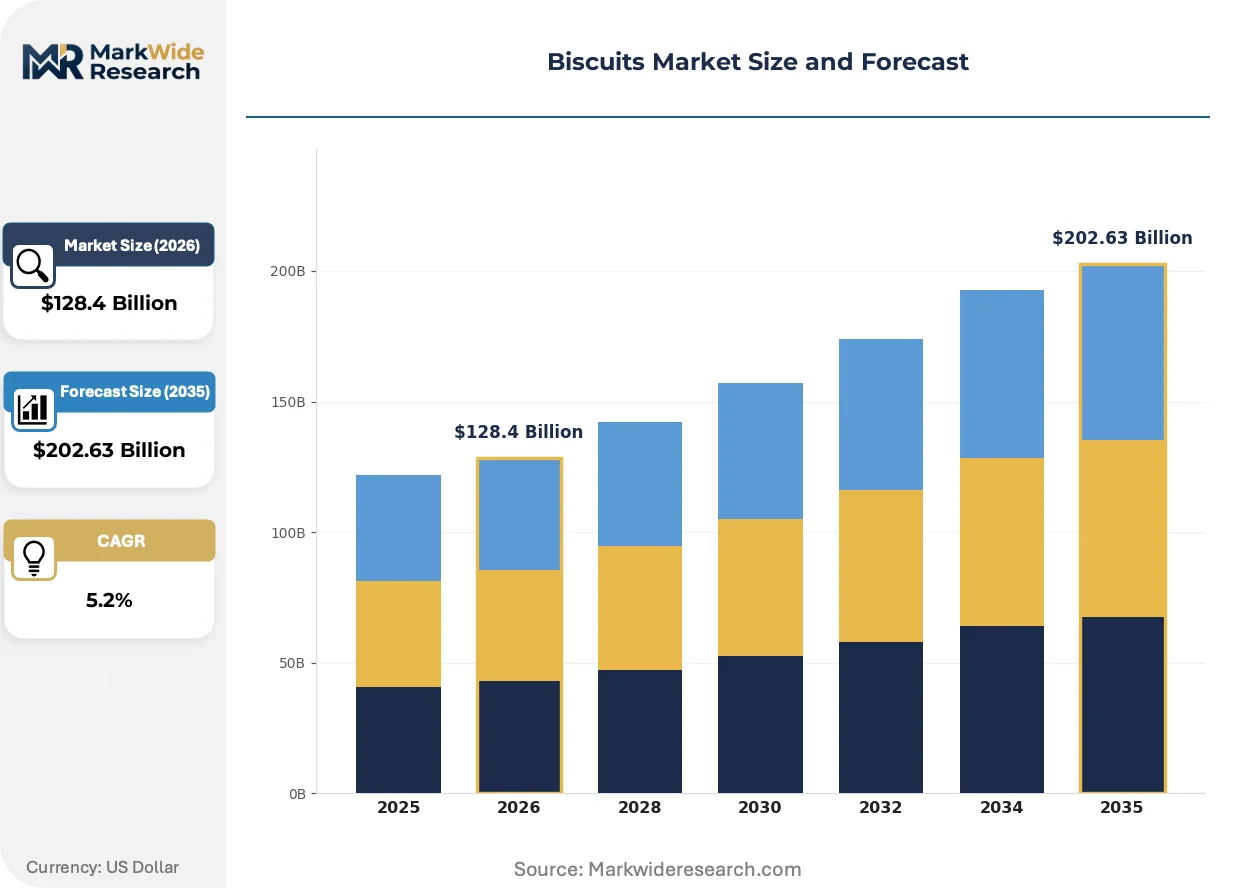
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $202.63 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream Biscuits, Marie, Digestive, Butter Cookies, Wafer Biscuits Packaging Type: Stand-up Pouches, Tin Boxes, Plastic Trays, Flow Wrap, Carton Boxes Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Wholesale Suppliers, Specialty Stores Consumer Age Group: Children, Teenagers, Adults, Seniors |
| Companies Covered | ITC Limited, Lotus Bakeries Corporate, Yıldız Holding, Nestlé, Campbell Soup Company, Mondelēz International, Britannia Industries, The Kraft Heinz Company, Kellogg Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biscuits Market Strategic Shifts & Innovations
Clean-label ingredient provenance and manufacturing automation are compressing traditional competitive advantages, while regulatory pressure on packaging and nutritional composition forces capital reallocation toward compliance infrastructure.
Modular extrusion systems for biscuit forming are modularizing production flexibility across rotary molding, wire cutting, and laminating processes. Mid-size manufacturers in Thailand and Vietnam adopt these configurable lines to reduce changeover times between cream biscuits and butter cookie formats. The technology is modularizing asset utilization rates, enabling smaller batch runs for regional flavor variants without dedicated production lines.
REACH chemical registration requirements and EU F-Gas refrigerant phase-down rules are elevating packaging and cold-chain costs for cream-filled biscuit exports. Manufacturers serving European markets invest in natural refrigerant systems and modified-atmosphere packaging to maintain shelf stability. The wafer and cream sandwich segment bears disproportionate compliance burden relative to ambient-stable hard biscuits.
Convenience store channel expansion in Southeast Asia is compressing traditional wholesale distribution hierarchies. Modern trade buyers in Indonesia and the Philippines negotiate direct supply relationships, disintermediating regional distributors. Urban corridor concentration in Ho Chi Minh City and Manila accelerates this shift, with shelf-space fees and promotional fund requirements favoring manufacturers with centralized category management capabilities.
Biscuits Market Segmentation
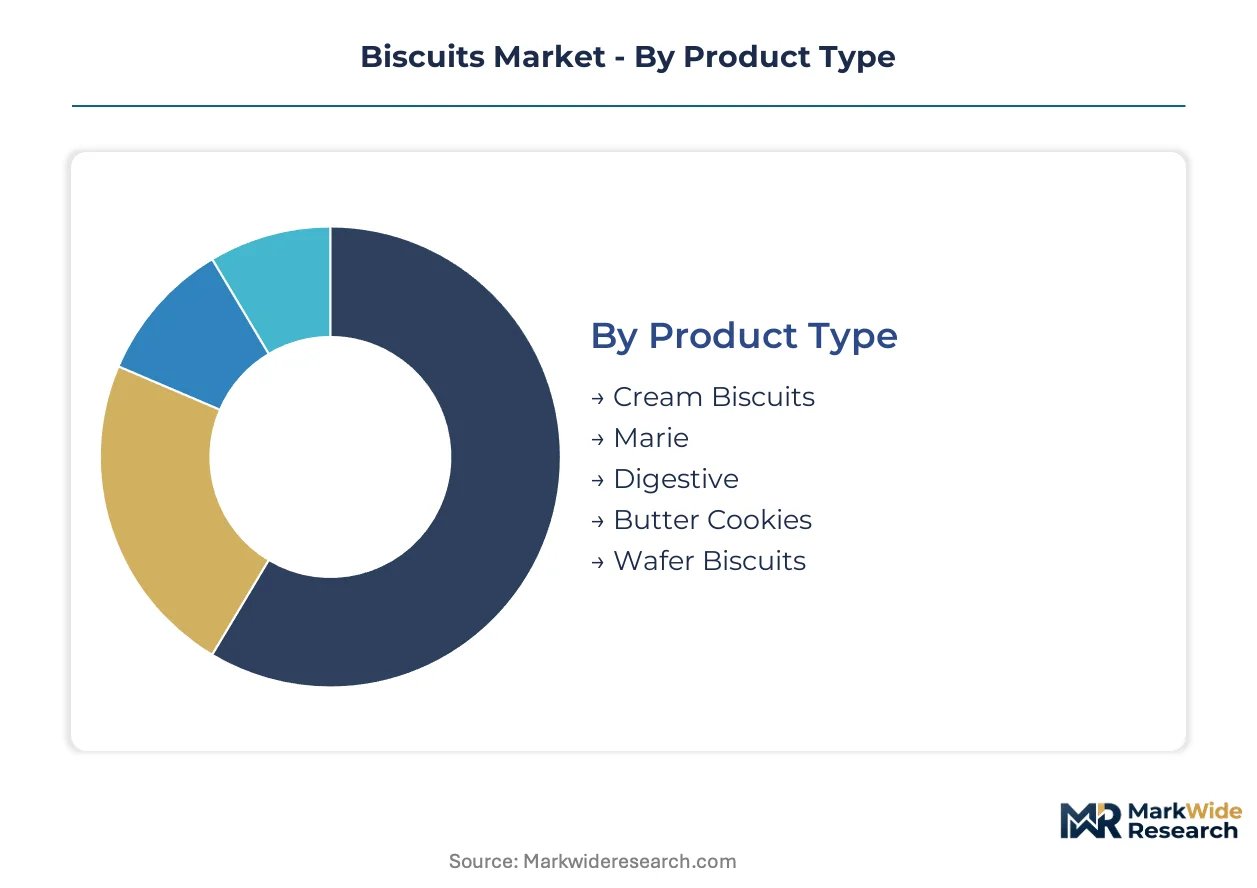
Biscuit manufacturers calibrate product architecture across four intersecting dimensions: formulation chemistry determines margin structure, packaging engineering shapes shelf-life economics, channel configuration dictates working capital intensity, and demographic targeting drives flavor portfolio breadth. Misalignment between any two dimensions compresses profitability.
Product Type:
Formulation technology separates commodity volume plays from premium margin capture, with fat content, moisture management, and layering complexity defining production asset requirements.
- Cream Biscuits:Sandwich construction with fat-based filling requires precision extrusion and enrobing lines. Demand clusters in Indonesia's Jakarta-Surabaya corridor where convenience store expansion supports single-serve packaging formats, though EU F-Gas refrigerant rules elevate cold-chain costs for cream stability.
- Digestive:Whole wheat fiber content and reduced sugar positioning align with FSSAI fortification mandates. Pharmacy and wellness retail channels in India allocate expanded shelf space to health-positioned variants, creating distribution advantages for compliant manufacturers.
- Marie:Low-fat, low-sugar tea biscuit format with extended ambient shelf stability. Standard rotary molding production enables cost leadership in price-sensitive South Asian markets.
- Butter Cookies:High butterfat content and gift-packaging occasions sustain premium price-per-kilogram positioning. Seasonal demand spikes in developed markets drive disproportionate margin contribution.
- Wafer Biscuits:Automated layering lines enable manufacturing scale economies. Volume-driven categories compete on production throughput rather than formulation differentiation.
Mature deployment sits with Marie and digestive formats in South Asian markets. Newer deployment is concentrated in cream biscuit fusion products with chocolate enrobing.
Packaging Type:
Barrier properties and shelf-life extension requirements segment packaging investment, with modified-atmosphere technologies commanding premium positioning in export-oriented production.
- Stand-up Pouches:Flexible film structures with resealable zippers extend consumption occasions. Modern trade buyers in Vietnam and Philippines negotiate direct supply relationships favoring pouch formats with high shelf impact.
- Tin Boxes:Metal substrate provides premium gift-positioning and extended shelf protection. Butter cookie assortments in developed markets sustain tin packaging despite material cost premiums.
- Plastic Trays:Thermoformed PET structures protect cream-filled sandwich integrity. REACH chemical registration requirements elevate compliance costs for European market exports.
- Flow Wrap:High-speed horizontal wrapping maximizes throughput for single-serve portions. Convenience store channel expansion in Southeast Asia accelerates flow wrap adoption for impulse purchase formats.
- Carton Boxes:Paperboard secondary packaging for multi-unit retail configurations. Sustainability positioning drives fiber-based substrate substitution in EU-facing production.
Volume concentration favors flow wrap and stand-up pouch formats. Premium positioning remains anchored in tin box and modified-atmosphere configurations.
Distribution Channel:
Working capital intensity and promotional fund requirements separate organized channel strategies, with modern trade consolidation in Southeast Asia compressing traditional wholesale hierarchies.
- Supermarkets:Category management capabilities and centralized buyer negotiations dominate developed market volume. Shelf-space fees and promotional calendars demand manufacturer scale.
- Convenience Stores:Extended operating hours and urban corridor density drive impulse purchase frequency. Indonesia and Vietnam modern trade penetration accelerates direct supply relationships.
- Online Retailers:Fulfillment infrastructure requirements and return logistics complexity constrain participation. Premium and gift formats show highest e-commerce conversion.
- Wholesale Suppliers:Traditional distribution hierarchy remains relevant in India's tier-two and tier-three cities. Britannia Industries' rural stockist model demonstrates scalable last-mile architecture.
- Specialty Stores:Health food and pharmacy channels capture fortification-positioned digestive variants. FSSAI compliance creates barrier advantages for organized players.
Channel expansion is climbing the fastest in convenience store formats. Wholesale consolidation pressures traditional distributor margins.
Consumer Age Group:
Palate development stage and snacking occasion frequency determine flavor intensity, portion size, and nutritional positioning requirements across the lifecycle.
- Children:Chocolate-coated and character-licensed formats drive pester-power purchase influence. Sugar reduction mandates complicate formulation in regulated markets.
- Teenagers:Portable single-serve formats align with school and transit consumption occasions. Social media packaging aesthetics influence trial conversion.
- Adults:Functional fortification and clean-label positioning capture wellness-oriented consumption. Fiber and protein enrichment aligns with FSSAI standards.
- Seniors:Reduced hardness and enhanced digestibility specifications address dental and gastric constraints. Pharmacy channel placement supports discovery.
Functional innovation concentrates in adult and senior segments. Volume scale remains anchored in children and teenager targeting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta anchors Southeast Asian biscuit demand concentration through its Surabaya corridor expansion, where convenience store shelf-space allocation for packaged snacks accelerates volume throughput across Indonesia's urban centers.
India
Tier-two and tier-three city penetration drives volume expansion as disposable incomes rise in secondary urban centers. FSSAI mandates stricter trans-fat labeling and fortification standards for processed foods. Britannia Industries leverages its rural stockist model to capture distribution advantages across Maharashtra and Gujarat manufacturing clusters.
Indonesia
Modern trade penetration in Jakarta-Surabaya urban corridors accelerates premium biscuit adoption through convenience store channel expansion. The country's national food safety regulator enforces processed food labeling requirements that push reformulation toward palm oil alternatives. Surabaya's manufacturing zones concentrate automated wafer layering production for regional export.
United States
Gift-packaging occasions for butter cookies sustain premium price-per-kilogram positioning in developed market consumption. FDA nutritional labeling and allergen declaration requirements govern biscuit composition and packaging disclosures. Chicago-area food manufacturing corridors concentrate chocolate-biscuit fusion production for domestic and export markets.
Vietnam
Ho Chi Minh City modern trade buyers negotiate direct supply relationships that disintermediate traditional wholesale distribution hierarchies. The country's national food safety authority aligns fortification standards with regional compliance frameworks. Urban corridor shelf-space fees favor manufacturers with centralized category management capabilities in the Mekong Delta processing zones.
Germany
EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants elevate cold-chain costs for cream-filled biscuit exports to European markets. REACH chemical registration requirements govern packaging material compliance for food-contact applications. Bavaria's precision engineering clusters supply modular extrusion systems to Southeast Asian biscuit manufacturers.
Biscuits Market Key Industry Players
Premium-margin players sit above commodity-margin players across ingredient provenance and price-per-kilogram expectations, with chocolate-biscuit fusion formats commanding disproportionate returns against standard rotary-molded categories. The vendor base stratifies between multinational packaged food conglomerates with centralized R&D infrastructure and regional specialists leveraging deep distribution into secondary urban markets. Three archetypes dominate: scale-driven wafer manufacturers competing on automated throughput, premium-positioned butter cookie specialists capturing gift occasions, and fortified digestive producers aligning with pharmacy channel placement. Competitive moves concentrate on portfolio diversification toward clean-label formulations and backward integration into in-house flour milling.
Among Asia-Pacific-based manufacturers, ITC Limited and Britannia Industries exemplify the distribution-architecture archetype, while Mondelēz International occupies a position representing the premium-fusion format specialist tier. These anchors demonstrate how regulatory compliance capabilities and channel-specific penetration models separate organized players from fragmented regional competition.
| Leading Market Players |
|---|
| ITC Limited |
| Lotus Bakeries Corporate |
| Yıldız Holding |
| Nestlé |
| Campbell Soup Company |
| Mondelēz International |
| Britannia Industries |
| The Kraft Heinz Company |
| Kellogg Co. |
| Others |
Cost & Logistics Intelligence
Precision extrusion technicians in Bavaria's engineering clusters command wage premiums that compress margin spreads between premium butter cookie tiers and economy Marie biscuit lines. Labor-cost differentials between automated wafer production hubs and hand-finished gift assortments translate into three-tier pricing structures across premium, standard, and economy levels.
Pricing Analysis
Throughput-based pricing anchors wafer biscuit contracts, with automated layering line utilization rates determining per-kilogram contract terms. Price differentiation separates chocolate-enrobed fusion formats from standard rotary-molded categories through ingredient provenance certification and gift-packaging occasion bundling. Pricing pressure stems from wheat flour input volatility compressing margins for commodity segments lacking brand pricing power. Modern trade buyers in Jakarta-Surabaya corridors exhibit lowest price sensitivity for premium-positioned assortments, while wholesale distributors in India's tier-three cities face intense cost competition.
Supply Chain Analysis
FSSAI fortification mandates and domestic-content preferences in India's processed food sector are reshaping sourcing patterns toward local flour milling and regional palm oil refining. Supply concentration draws from Indonesia, Malaysia, and India for oleochemical inputs, with wheat sourcing anchored in Black Sea and North American grain corridors. Raw material dependencies rest on palm oil derivatives, wheat flour grades, and chocolate liquor supplies. Single-source vulnerability runs through Indonesian oleochemical export duty volatility. Distribution runs through modern trade direct supply relationships disintermediating traditional wholesale hierarchies in Southeast Asian urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FSSAI trans-fat labeling mandates and fortification standards erect barrier-to-entry moats favoring organized players with captive R&D infrastructure.
For Market Incumbents: Deploy backward integration into in-house flour milling to insulate margin structures from wheat price volatility threatening standard biscuit categories. Britannia Industries' rural stockist model demonstrates scalable channel control defending against modern trade consolidation pressures. Capture barrier advantages by accelerating clean-label reformulation ahead of front-of-pack labeling mandate timelines compressing competitor response windows. For New Entrants and Emerging Players: Begin with digestive and functional biscuit segments where FSSAI fortification compliance requirements disadvantage fragmented regional competition lacking laboratory infrastructure. India's tier-two city pharmacy channels represent the most penetrable white-space target, with wellness-positioned fiber-enriched variants commanding shelf space. Pursue contract manufacturing partnerships with established distributors to bypass upfront cold-chain investment for cream-filled formats. For Investors and Strategic Acquirers: Re-rating potential sits with automated wafer manufacturers given capital intensity advantages and regional export scalability through Surabaya production zones. Long-term viability favors scale-driven players with centralized category management capabilities serving modern trade consolidation. Monitor EU F-Gas refrigerant rule enforcement as inflection signal for cream-filled segment profitability compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flour Milling | ITC Limited's captive wheat sourcing insulates margin structures from commodity volatility. |
| Clean-Label Reformulation Investment | FSSAI trans-fat mandates force palm oil alternative R&D creating compliance moats. |
| Modern Trade Direct Supply Relationships | Ho Chi Minh City buyer consolidation disintermediates traditional wholesale hierarchies. |
| Automated Wafer Layering Scale-Up | Surabaya manufacturing zones concentrate regional export production for cost leadership. |
| Pharmacy Channel Placement Expansion | FSSAI-compliant digestive variants capture wellness retail shelf space in India. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this biscuits market analysis. Primary interviews with brand managers, category buyers at Indonesian convenience chains, supply planners at regional distributors, and R&D directors at fortified biscuit manufacturers were cross-referenced against FSSAI compliance databases, EU REACH chemical registrations, and Nielsen retail audit data. Bottom-up production capacity assessments and top-down consumption surveys were reconciled through triangulation.
Data-stream reconciliation across volume shipments, retail velocity, and ingredient input costs informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product formulation chemistry, packaging barrier technology, distribution channel configuration, and consumer age-group targeting. CAGRs were derived from trend extrapolation of urban corridor demand concentration and regulatory compliance investment cycles, with wheat price volatility and palm oil duty regimes serving as key forecast sensitivity inputs.
Underlying measurement precision varies by segment; cream biscuit and wafer categories carry tighter precision than fragmented regional butter cookie specialists. Forecasts reflect documented assumptions regarding FSSAI enforcement timelines and EU F-Gas refrigerant phase-down schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Pizza Crust Mix Market
Bakery Products
North America Bakery Products Market
Bakery Products
Ezekiel Bread Market
Bakery Products
Dough Whitener Market
Bakery Products
Vegan Baking Mix Market
Bakery Products
Baking Mixes Market
Bakery Products
Ice Cream Market
Bakery Products
Pie Shells Market
Bakery Products
Batter and Breader Premixes Market
Bakery Products
Specula Market
Bakery Products
Bread Premix Market
Bakery Products
Bakery Fats Market
Bakery Products
Instant Cake Gel Market
Bakery Products
Pastry Premixes Market
Bakery Products
Gluten-Free Bakery Market
Bakery Products
Healthy Biscuits Market