
 Oman Frozen Bakery Products Market | 2026-2036
Oman Frozen Bakery Products Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Frozen Bakery Products Market Analytics
Asset-light leasing arrangements for commercial freezer capacity are reconfiguring competitive entry barriers for smaller bakery operators in Oman. Americana Group Inc leverages its integrated supply chain to dominate quick-service and retail channels across the Gulf. Atyab Food Industries anchors its position through localized production that reduces import dependency and shortens delivery cycles.
Frozen bakery products comprise doughs, batters, and fully baked items preserved at sub-zero temperatures to halt staling and microbial activity, with shelf-life extension achieved through blast freezing at minus thirty-five degrees Celsius and controlled-atmosphere packaging. The primary commercial purpose centers on enabling food-service operators and retailers to deliver consistent quality without on-site baking infrastructure. Bread and pastries capture the bulk of current volume given their role in daily consumption patterns across Omani households and hospitality outlets. Gluten-free and organic ingredient categories are expanding fastest as health-conscious retail consumers and premium hotel food-service buyers seek differentiated offerings.
Oman’s Ministry of Regional Municipalities and Water Resources administers halal certification mandates that govern both domestic production and imported frozen bakery goods, while the Gulf Standards Organization harmonizes labeling and safety requirements across GCC trade corridors. Compliance with these frameworks determines market access and shapes formulation decisions for multinational suppliers. Stakeholders must monitor evolving municipal enforcement patterns and halal audit stringency as local production capacity expands.
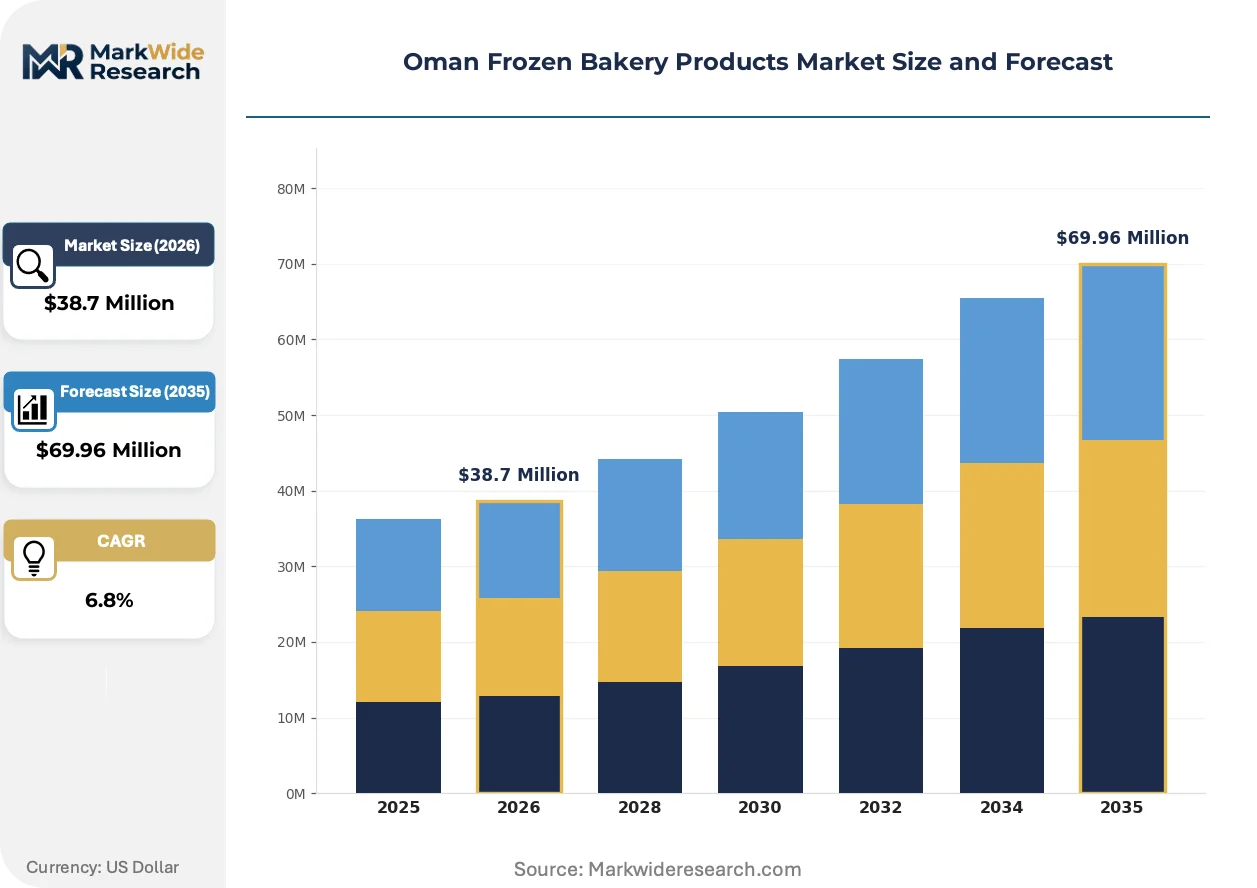
Market Dynamics
Asset-light commercial freezer leasing is collapsing traditional capital barriers for smaller Omani bakery operators, while the Ministry of Regional Municipalities and Water Resources tightens halal audit stringency on both domestic production and imports.
Growth Catalysts
- Quick-service restaurant expansion:Chains across Muscat and Dhofar are standardizing procurement through frozen bakery SKUs to reduce labor costs and outlet-level baking infrastructure. This pulls volume through centralized distribution hubs.
- Gulf Standards Organization harmonization:Cross-border labeling and safety alignment is reducing friction for UAE and Saudi suppliers entering Omani retail and food-service channels.
- Blast freezing at minus thirty-five degrees Celsius:This process technology is extending shelf-life windows for dough and pastry products, enabling longer supply chains from regional production centers into Omani interior governorates.
Market Restraints
- Wheat and butter input volatility:Global commodity swings compress margin predictability for frozen bakery manufacturers serving price-sensitive Omani retail channels.
- Import concentration from UAE and Saudi Arabia:Over-reliance on cross-border supply corridors creates vulnerability to customs delays and GCC trade policy shifts.
- Halal certification timeline friction:The Ministry of Regional Municipalities and Water Resources audit backlog extends product launch cycles for new entrants.
Strategic Opportunities
- Al Batinah South and Al Dakhiliyah governorates:Retail infrastructure gaps in these interior regions present first-mover potential for cold-chain-equipped distributors.
- Organic and gluten-free ingredient convergence:Premium hotel food-service buyers are creating tiered SKU demand that local producers can capture with reformulated product lines.
- Hotel chain direct procurement platforms:Bypassing traditional wholesale layers lets suppliers capture margin and build contractual volume commitments.
Industry Challenges
- Cold-chain technician scarcity:Qualified personnel for blast freezer maintenance and temperature-controlled logistics are concentrated in Muscat, raising operational costs for interior distribution.
- Legacy ERP integration with halal traceability systems:Food-service operators struggle to merge existing inventory platforms with certification documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Frozen Bakery Products Market |
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $69.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread, Pastries, Cakes, Cookies Ingredient Type: Wheat, Gluten-Free, Organic, Additives End User: Retail, Food Service, Catering, Households Packaging Type: Box, Bag, Tray, Vacuum Pack |
| Companies Covered | Americana Group Inc, Atyab Food Industries, Dr. August Oetker KG, Switz Group, Agthia Group, B&G Foods, IL Fornaio del Casale SpA, Tiseo's Foods, Lantmannen Unibake, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Frozen Bakery Products Market Evolving Landscape
Controlled-atmosphere packaging and reformulation around clean-label ingredients are redefining product differentiation in Omani frozen bakery, while regulatory audit digitization compresses compliance timelines.
Blast freezing technology is migrating from standard mechanical systems to cryogenic nitrogen tunnel configurations. Premium hotel and airline catering buyers in Muscat are adopting these systems for superior moisture retention in croissant and puff pastry applications. This migration from conventional freezing is enabling smaller batch production with extended distribution radius.
The Ministry of Regional Municipalities and Water Resources is piloting blockchain-linked halal certification verification. This policy shift creates immutable audit trails from ingredient sourcing through retail shelf placement. Import-heavy frozen bakery categories face the steepest compliance adaptation costs as the framework rolls out.
Food-service procurement is consolidating through centralized purchasing cooperatives. Quick-service restaurant groups in Oman are displacing fragmented supplier relationships with contracted volume agreements covering multiple outlet locations. This behavioral shift is most visible among emerging regional chains expanding beyond Muscat into Sohar and Salalah.
Oman Frozen Bakery Products Market Segmentation
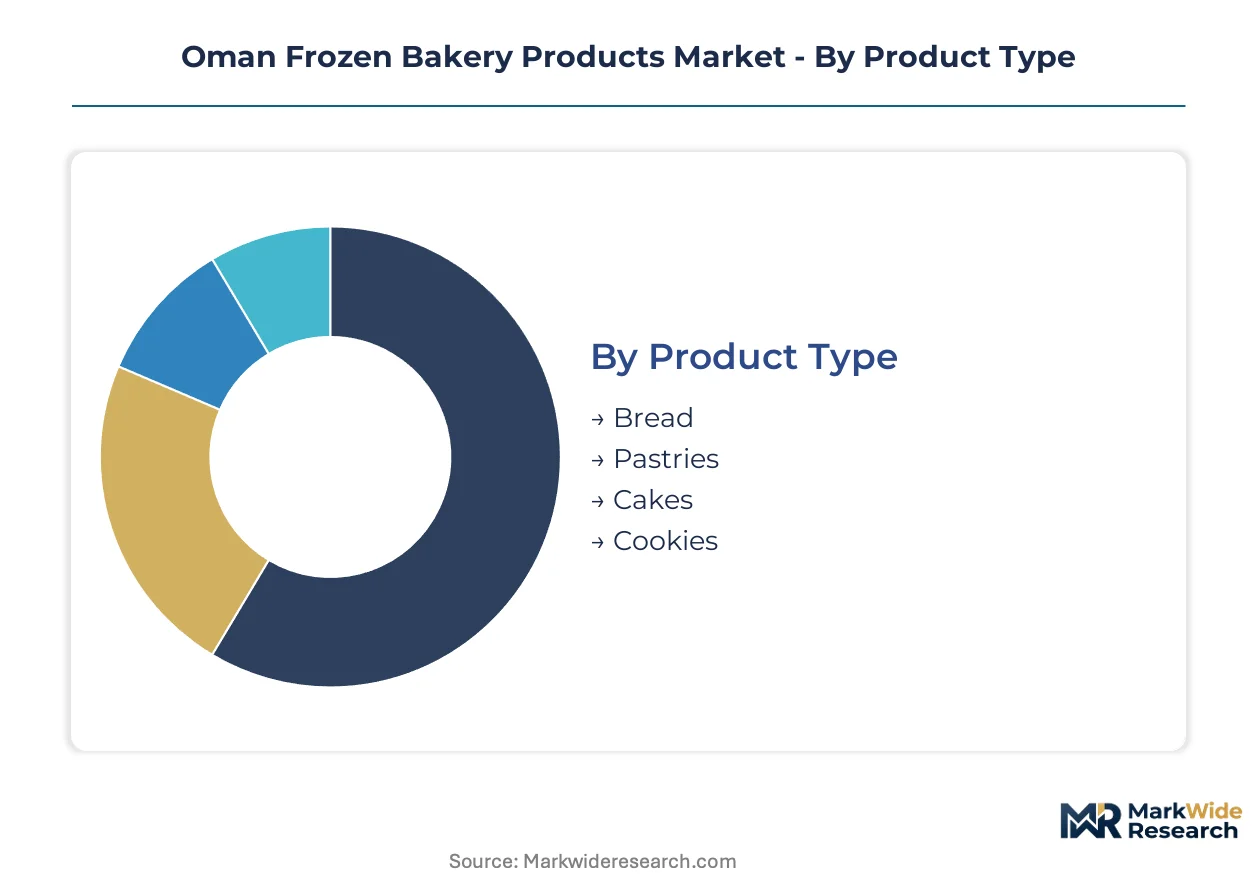
Segmentation in the Oman frozen bakery market reveals how procurement patterns diverge across customer types, product formats, and distribution channels. These distinctions shape everything from halal certification workflows to cold-chain infrastructure investment priorities.
Product Type:
Application context drives product selection, with daily consumption frequency and preparation complexity creating distinct demand profiles across Omani food-service and retail channels.
- Bread:Standardized loaves and flatbreads dominate quick-service restaurant procurement in Muscat and Sohar, where labor cost reduction through pre-proofed frozen dough pulls volume. The Ministry of Regional Municipalities and Water Resources mandates halal certification for all wheat-based imports, extending approval timelines for new suppliers.
- Pastries:Croissants, Danish, and puff pastry applications require blast freezing at minus thirty-five degrees Celsius to preserve lamination structure. Premium hotel chains in Salalah and Muscat are consolidating procurement through centralized purchasing cooperatives for these higher-margin items.
- Cakes:Celebration and portion-controlled formats serve catering operations and retail freezer aisles.
- Cookies:Pre-portioned frozen dough targets in-store bakery programs and hotel breakfast buffets.
Bread commands the established base. The steepest expansion runs through pastries as premium hospitality investment accelerates.
Ingredient Type:
Margin structure and certification burden vary sharply across ingredient sourcing strategies, with reformulation costs creating tiered competitive entry barriers.
- Wheat:Conventional flour formulations anchor mass-market retail and quick-service channels. Global commodity price volatility compresses manufacturer margins, particularly for price-sensitive distribution through Al Batinah South governorate supermarkets.
- Gluten-Free:Rice, tapioca, and alternative starch blends address celiac and health-conscious segments. Premium hotel food-service buyers in Muscat are creating dedicated SKU demand that local producers can capture with certified production lines.
- Organic:Certified ingredient supply chains shorten shelf-life windows and raise cold-chain requirements.
- Additives:Emulsifiers and preservatives extend distribution radius for interior governorate penetration.
Wheat maintains volume leadership. Gluten-free applications are gaining share fastest among premium hospitality buyers.
End User:
Customer type determines order frequency, batch size, and certification documentation intensity, with food-service operators demanding tighter halal traceability than retail channels.
- Food Service:Quick-service restaurants and hotel chains standardize procurement through frozen bakery SKUs to eliminate outlet-level baking infrastructure. Centralized distribution hubs in Muscat and Sohar pull volume through contracted volume agreements covering multiple outlet locations.
- Retail:Supermarket freezer aisles and convenience stores concentrate in Muscat governorate and surrounding urban corridors. Shelf-space competition intensifies as UAE and Saudi suppliers leverage Gulf Standards Organization harmonization for cross-border entry.
- Catering:Event and institutional buyers require flexible batch sizing for variable demand.
- Households:Direct consumer purchase remains limited by cold-chain penetration outside major urban centers.
Food service anchors current volume. Retail channels are climbing the fastest as supermarket freezer capacity expands in secondary cities.
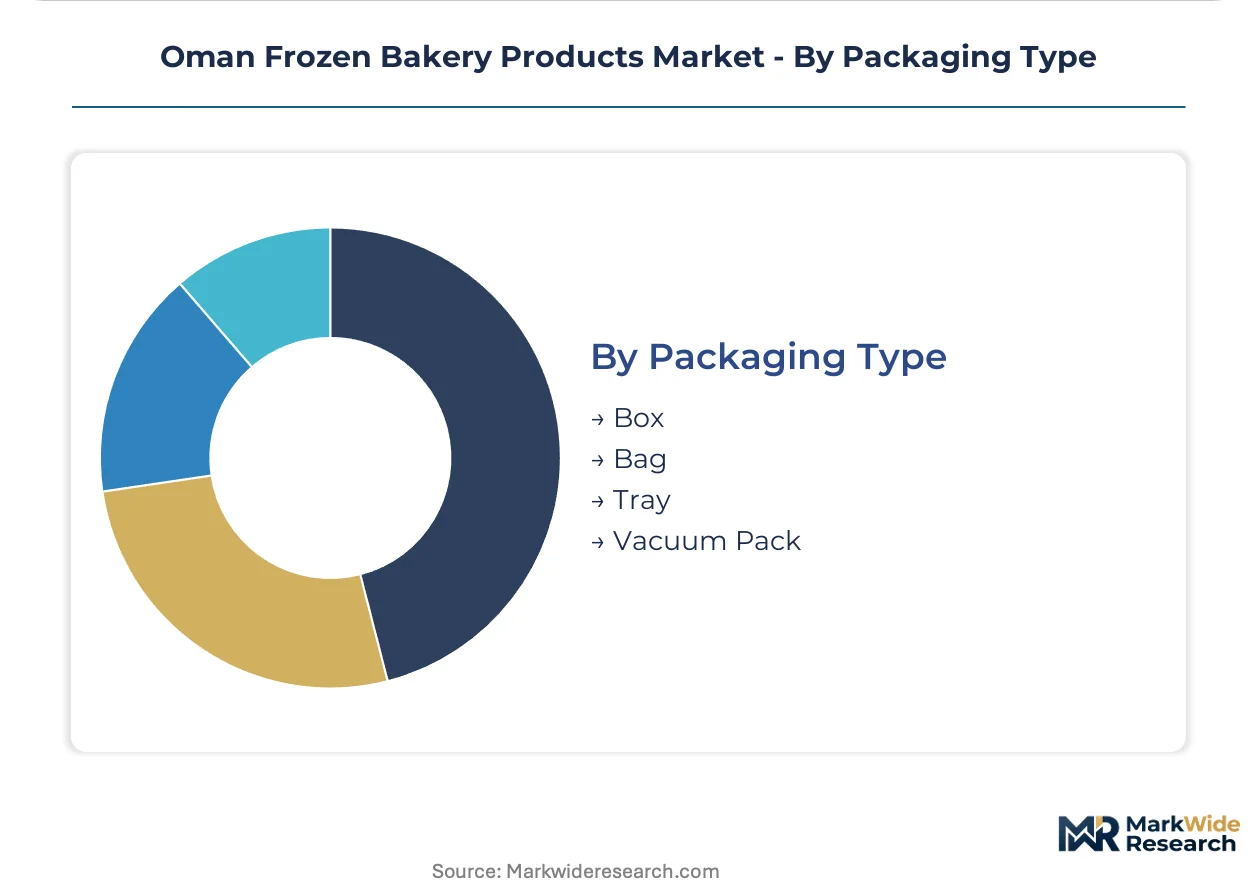
Packaging Type:
Packaging configuration directly shapes shelf-life extension, logistics efficiency, and retail presentation requirements across Omani distribution networks.
- Vacuum Pack:Controlled-atmosphere sealing eliminates oxygen exposure, extending distribution radius for Al Dakhiliyah and Al Batinah South governorates. Blast-frozen croissants and puff pastries retain moisture integrity through this format, satisfying premium hotel specifications.
- Box:Rigid corrugated protection suits palletized distribution to quick-service restaurant chains and hotel central kitchens. Standardized cube efficiency reduces freight cost per unit in high-volume Muscat corridors.
- Bag:Flexible polyethylene suits bread and cookie formats for retail impulse purchase.
- Tray:Thermoformed bases present pastries for deli and in-store bakery display.
Box packaging dominates food-service logistics. Vacuum pack formats are expanding most quickly as premium segment requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oman runs a structural trade deficit in frozen bakery goods, with cross-border flows from UAE and Saudi Arabia supplying the bulk of current consumption. Import dependency concentrates risk around customs corridor efficiency and GCC tariff harmonization.
Muscat Governorate
Quick-service restaurant chains and five-star hotel properties drive frozen dough procurement volumes in the capital corridor. The Ministry of Regional Municipalities and Water Resources maintains its halal certification headquarters here, processing import approvals and domestic facility audits. Cold-chain infrastructure clusters around Muscat International Airport and the Sultan Qaboos Port free zone.
Al Batinah South
Retail freezer capacity is expanding through supermarket chain penetration into Sohar and Rustaq urban centers. Gulf Standards Organization labeling harmonization accelerates UAE supplier entry into this coastal corridor. Americana Group Inc leverages its integrated distribution network to supply quick-service outlets along the Batinah highway corridor.
Dhofar Governorate
Salalah's port free zone and monsoon tourism seasonality create distinct demand pulses for frozen pastry and bread products. The Ministry of Regional Municipalities and Water Resources operates a regional halal certification satellite office to reduce audit backlog for southern producers. Hotel construction along the Salalah beachfront is pulling premium frozen croissant and Danish volumes through specialized distributors.
Al Dakhiliyah Governorate
Interior retail infrastructure gaps present first-mover opportunities for cold-chain-equipped distributors reaching Nizwa and Bahla markets. Blast freezing technology adoption remains limited by technician scarcity outside Muscat. Atyab Food Industries has localized production capacity that shortens delivery cycles to this underserved interior region.
Oman Frozen Bakery Products Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation and freezing technology. The Oman market exhibits tiered concentration, with Gulf-based conglomerates controlling quick-service and retail channels while European specialists serve premium hospitality segments. Three archetypes dominate: integrated Gulf food conglomerates with captive distribution, European branded goods exporters, and local production facilities reducing import dependency. Competitive moves center on strategic partnerships with hotel purchasing cooperatives and backward integration into wheat sourcing.
Within the integrated conglomerate tier, Americana Group Inc and Agthia Group exemplify platform players with cross-Gulf distribution networks. Among European exporters, Dr. August Oetker KG and Lantmannen Unibake occupy positions serving premium hotel and retail channels through specialized frozen pastry and dough lines. These named entities represent the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Americana Group Inc |
| Atyab Food Industries |
| Dr. August Oetker KG |
| Switz Group |
| Agthia Group |
| B&G Foods |
| IL Fornaio del Casale SpA |
| Tiseo's Foods |
| Lantmannen Unibake |
| Others |
Value Network & Pricing Analysis
Wheat and butter import concentration from UAE and Saudi Arabia concentrates upstream margin capture with Gulf-based trading houses, pushing Omani frozen bakery manufacturers to defend position through volume contracting with quick-service restaurant chains and hotel purchasing cooperatives where procurement consolidation creates captive demand pools.
Pricing Analysis
Quick-service restaurant chains anchor contract-based long-term offtake pricing across the Omani market, with three-tier pricing structure across premium, standard, and economy levels differentiating by halal certification grade and blast freezing technology tier. Cost compression in standard wheat-based bread categories is intensifying because global commodity volatility feeds directly into manufacturer margins, while premium hotel food-service buyers show least price sensitivity for cryogenic nitrogen tunnel frozen pastries with extended shelf-life specifications.
Supply Chain Analysis
Upstream wheat sourcing draws from Australia, Ukraine, and Black Sea corridor suppliers, with butter and dairy inputs resting on New Zealand and European Union export flows. Single-source vulnerability concentrates around UAE-Saudi cross-border distribution corridors where customs delays propagate downstream. Distribution runs through Muscat-based cold-chain hubs serving quick-service restaurant central kitchens and hotel procurement platforms, with interior governorate penetration requiring specialized blast freezer technician deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-linked halal certification verification piloted by the Ministry of Regional Municipalities and Water Resources is accelerating compliance digitization, compressing audit timelines and reshaping competitive entry barriers for frozen bakery suppliers across Oman.
For Market Incumbents: Harden halal traceability infrastructure through backward integration into certified wheat sourcing and captive blast freezing capacity additions in Muscat and Sohar corridors. Defend against emerging UAE supplier entry by locking multi-year volume agreements with expanding hotel purchasing cooperatives before Gulf Standards Organization harmonization fully matures. For New Entrants and Emerging Players: Establish a beachhead in Al Dakhiliyah and Al Batinah South governorates where retail freezer infrastructure gaps and technician scarcity have slowed incumbent penetration. Target premium organic and gluten-free pastry segments for Salalah hotel construction pipelines, leveraging direct procurement platform relationships to bypass wholesale margin layers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with Gulf-based food conglomerates seeking portfolio rationalization outside core quick-service restaurant supply chains. Five-to-ten year viability hinges on cold-chain infrastructure density and regulatory compliance digitization maturity. Watch for Ministry audit backlog clearance rates as inflection indicator for new entrant timing.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Digitization | Blockchain-linked audit trails reduce Ministry approval timelines for new product launches. |
| Cryogenic Freezing Technology Migration | Nitrogen tunnel configurations capture premium hotel and airline catering specifications in Muscat. |
| Interior Governorate Distribution Expansion | Cold-chain-equipped distributors capture first-mover advantage in Al Dakhiliyah retail corridors. |
| Direct Hotel Procurement Platform Integration | Bypassing wholesale layers secures margin and contractual volume commitments with premium buyers. |
| Organic and Gluten-Free Product Line Extension | Certified reformulation addresses tiered SKU demand from health-conscious retail and hospitality segments. |
Research Methodology
Operator-level perspectives from quick-service restaurant procurement directors, hotel food-service executives, cold-chain logistics managers, and Ministry of Regional Municipalities certification auditors anchored the qualitative base. Secondary validation drew from Gulf Standards Organization regulatory filings, Oman customs trade databases, and SEC disclosures from listed food conglomerates. Bottom-up demand modeling triangulated against top-down macroeconomic consumption projections.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling across product type, ingredient category, end-user channel, and packaging format dimensions. CAGRs derived from historical consumption trajectories adjusted for quick-service restaurant expansion rates and hotel construction pipelines. Forecast inputs incorporated blast freezing technology adoption curves and halal certification audit processing capacity constraints.
Sensitivities concentrate around wheat commodity price volatility corridors and Ministry audit backlog fluctuations. Cross-checking against GCC customs trade flow databases and regional cold-chain infrastructure investment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Doughnuts Market
Bakery Products
Bakery Flavors Market
Bakery Products
Lentil Bread Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
Teaseed Cake Market
Bakery Products
Low Calorie Cake Market
Bakery Products
Pancakes Market
Bakery Products
Shelf-Stable Dough Market
Bakery Products
Dough Conveyor Market
Bakery Products
Aerating Cake Emulsifier Market
Bakery Products
Instant Cake Emulsifier Market
Bakery Products
United States Bread Market
Bakery Products
Dough Whitener Market
Bakery Products
Ezekiel Bread Market
Bakery Products
Global Cakes Market
Bakery Products
Layer Cake Mixes Market