
 Bakery Flavors Market | 2026-2036
Bakery Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Bakery Flavors Market Analysis
China is narrowing its import dependency for high-intensity bakery flavor concentrates through domestic fermentation capacity expansion. Firmenich leverages captive biotechnology assets to secure vanillin supply chains. Kerry Group anchors industrial-scale emulsion capabilities across Asia-Pacific manufacturing zones. Givaudan specializes in heat-stable flavor systems for laminated dough applications.
Bakery flavors comprise volatile aromatic compounds, essential oils, and synthetic or natural flavor substances formulated to withstand thermal processing in flour-based products. These compositions typically retain organoleptic integrity at temperatures exceeding 180°C during oven cycles, ensuring consistent taste delivery in finished goods. Liquid flavor formulations dominate industrial throughput due to metering precision in automated dosing systems, while powder formats sustain extended shelf stability for dry-mix distribution channels. Pastry applications command premium formulation complexity, whereas bread segments prioritize cost-optimized yeast-compatible profiles.
The FDA maintains GRAS self-affirmation pathways for natural flavor substances, while EFSA enforces stricter purity thresholds under Regulation EC 1333/2008, bifurcating compliance costs across Atlantic supply chains. China's SAMR implements GB standards for food flavor usage levels, creating localized testing requirements for imported concentrates. Stakeholders must reconcile divergent natural-claim definitions between jurisdictions while monitoring fermentation-derived ingredient classifications that challenge traditional extraction economics.
Market Dynamics
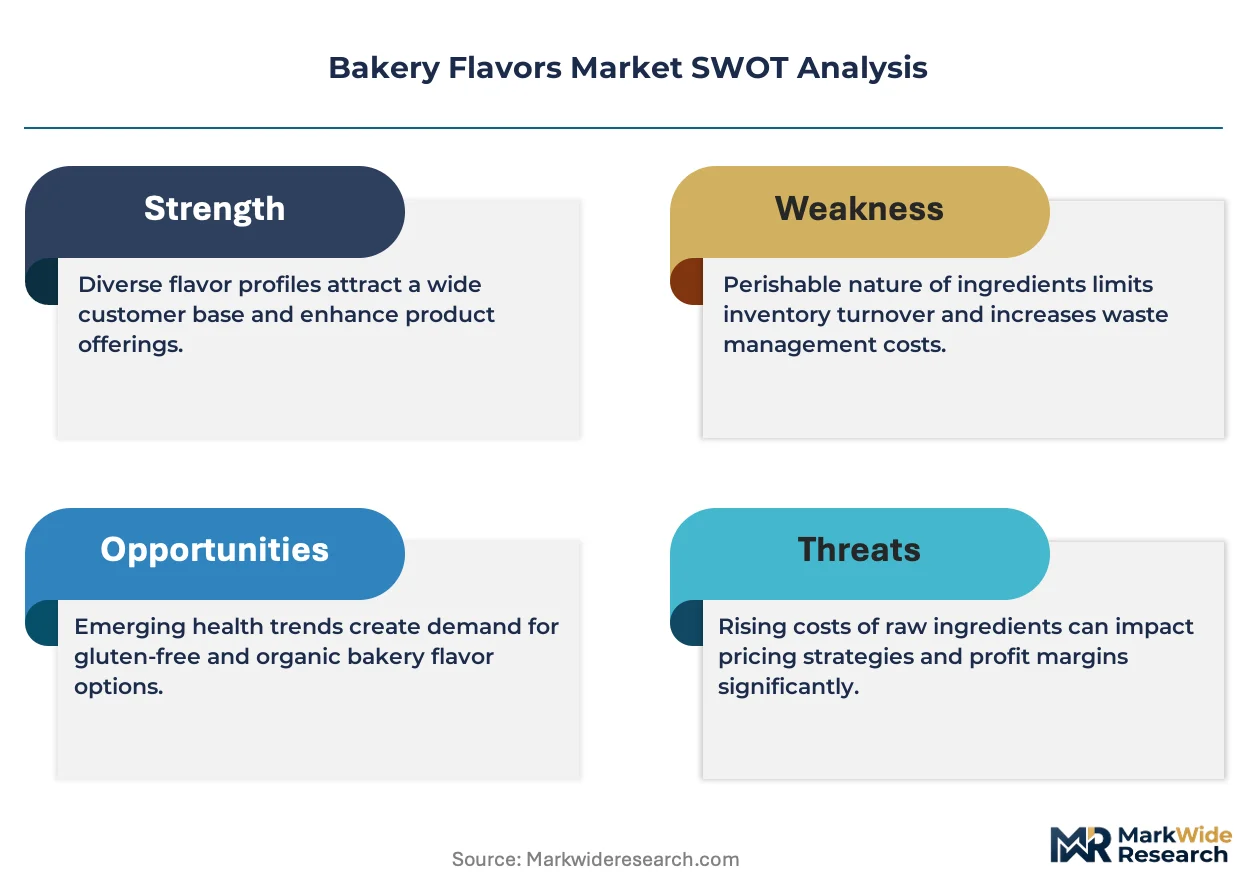
Clean-label reformulation pressure under EU Regulation 1333/2008 is forcing natural extract substitution at scale, compressing synthetic flavor margins while elevating biotechnology-derived alternatives across European retail channels.
Growth Catalysts
- EU Additive Restrictions:EFSA enforcement of purity thresholds under Regulation EC 1333/2008 accelerates natural flavor adoption in French patisserie and German industrial bakery operations.
- Fermentation Biotechnology:Domestic vanillin production through microbial fermentation is displacing petrochemical-derived supply in China's bakery concentrate sector.
- Artisan Bread Premiumization:European retail channels are scaling flavor complexity as traditional patisserie culture intersects with industrial modernization across France and Italy.
Market Restraints
- Natural Extract Cost Volatility:Weather-dependent vanilla and citrus harvests create input price instability for clean-label formulations.
- Biotechnology Supply Concentration:Captive fermentation assets remain concentrated among Swiss and Dutch specialty chemical producers.
- Heat Stability Limitations:Natural flavor compounds degrade faster than synthetic alternatives above 180°C in laminated dough applications.
Strategic Opportunities
- India Bakery Modernization:FSSAI regulatory harmonization and organized retail expansion create entry points for heat-stable emulsion technologies.
- Precision Fermentation Convergence:Integration of synthetic biology with AI-driven strain optimization unlocks novel aromatic compound pathways.
- E-Commerce Ingredient Channels:Direct-to-bakery distribution platforms bypass traditional foodservice intermediaries in Southeast Asian markets.
Industry Challenges
- Flavor Chemist Talent Scarcity:Cross-disciplinary expertise spanning biotechnology and classical flavor science remains concentrated in Basel and Paris clusters.
- Clean-Label Certification Timelines:EFSA natural-claim verification processes extend product development cycles by 12-18 months.
- Legacy Dosing System Retrofit:Automated liquid metering infrastructure requires capital outlay incompatible with small-batch artisan producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakery Flavors Market |
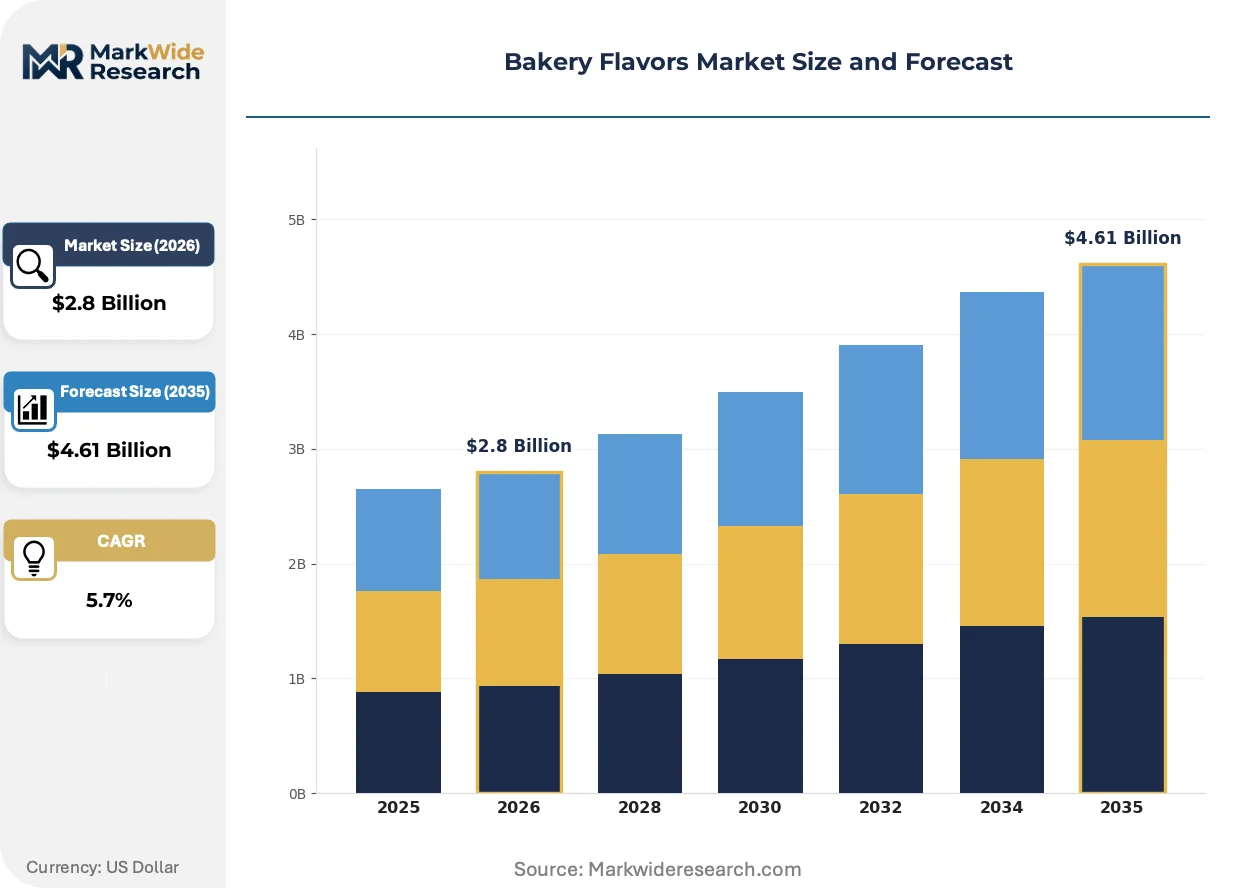
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Type: Chocolate, Vanilla, Strawberry, Butterscotch Application: Pastries, Breads, Cakes, Cookies Form: Liquid, Powder, Paste, Concentrate End User: Retail Bakeries, Industrial Bakers, Home Bakers, Foodservice Operators |
| Companies Covered | Firmenich, Kerry Group, Givaudan, Prinova, McCormick & Company, International Flavors & Fragrances, Symrise, Puratos, Sensient Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakery Flavors Market Emerging Trajectories
Digital sensing technologies and biotechnology convergence are compressing flavor development timelines while regulatory fragmentation across Atlantic supply chains forces dual-track compliance architectures.
Precision fermentation platforms are digitizing aromatic compound production by replacing solvent extraction with microbial cell factories. Industrial bakery groups in the Netherlands and Denmark are adopting these bioreactor systems at pilot scale. This technology is digitizing supply chain traceability from strain to finished flavor, compressing traditional agricultural procurement cycles.
EFSA's 2023 updated guidance on novel food classifications is reclassifying fermentation-derived ingredients as distinct from traditional extracts. This creates separate approval pathways for vanillin and benzaldehyde substitutes. Heat-stable flavor systems for laminated dough applications face the steepest compliance cost escalation.
Bakery procurement teams are consolidating supplier relationships around integrated flavor houses offering formulation plus regulatory dossier services. This disintermediates standalone extract traders and concentrates volume with biotechnology-enabled partners. France and Germany exhibit the fastest consolidation pace as patisserie chains centralize R&D functions.
Bakery Flavors Market Segmentation
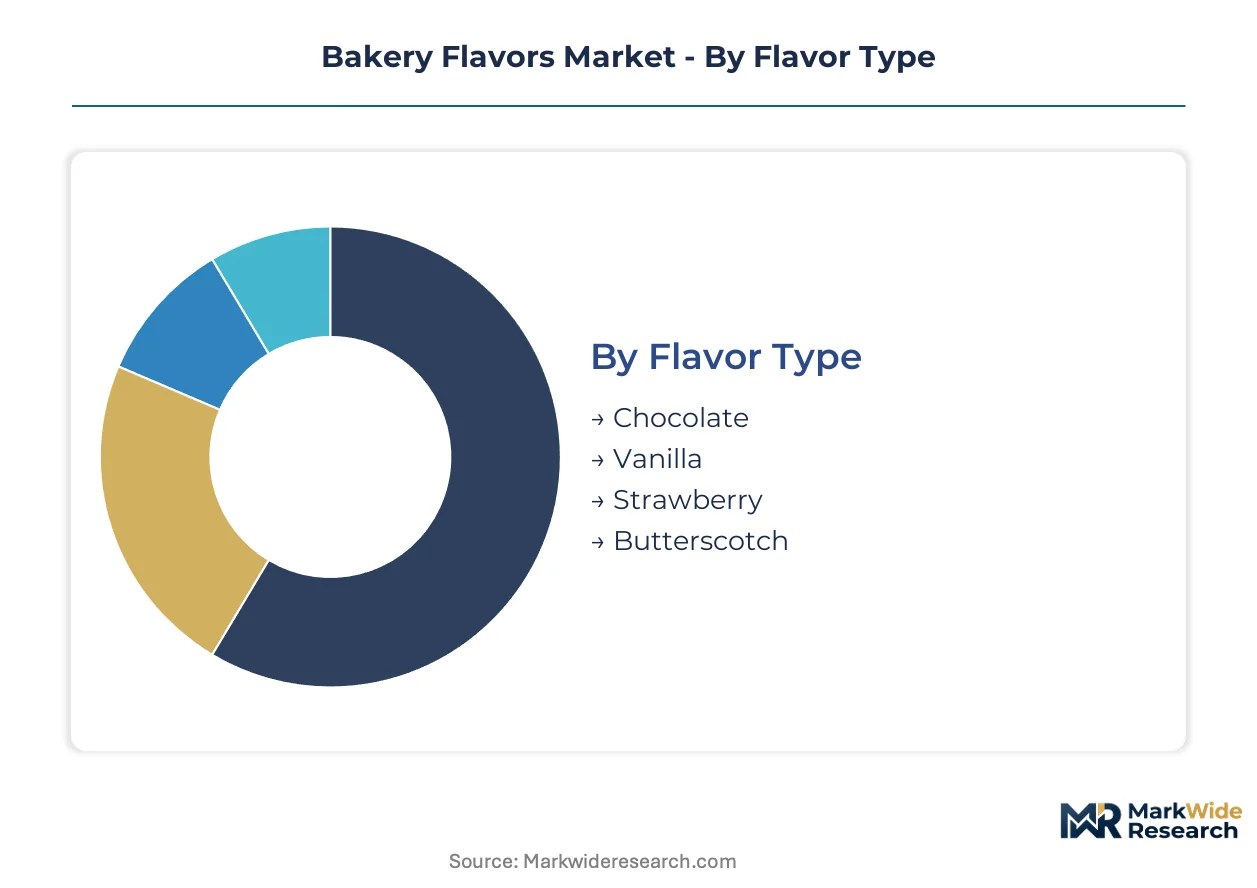
Bakery flavor procurement splits across four structural dimensions: sensory profile, thermal application, physical state, and operational scale. Each axis carries distinct formulation requirements and margin profiles that determine supplier selection and technology deployment.
Flavor Type:
Cost tier stratification within aromatic ingredients determines margin capture and clean-label positioning across European and Asian supply chains.
- Chocolate:Cocoa-derived alkaloids and synthetic methyl pyrazines dominate industrial formulations. French patisserie chains and German industrial bakeries drive demand concentration as EFSA Regulation 1333/2008 restricts artificial colorant pairings.
- Vanilla:Natural vanillin extracted from cured vanilla pods or fermentation-derived alternatives command premium positioning. China's domestic bioreactor capacity expansion is displacing petrochemical-derived supply in concentrate manufacturing.
- Strawberry:Ester-based aromatic compounds formulated for heat stability in oven applications. Retail bakery segments in Italy and Spain favor this profile for seasonal product rotations.
- Butterscotch:Diacetyl and furaneol-based caramelized sugar notes optimized for laminated dough systems. Industrial cookie producers prioritize cost-engineered synthetic variants.
Vanilla commands the established base. The steepest expansion runs through chocolate as clean-label cocoa extract adoption accelerates.
Application:
Heat exposure severity and fat content dictate flavor system architecture across flour-based finished goods.
- Pastries:Laminated dough applications require heat-stable encapsulated flavor systems surviving thermal cycling above 180°C. French and Italian artisan producers specify premium natural extract complexes despite cost premiums.
- Breads:Yeast-compatible profiles with minimal fermentation inhibition define formulation constraints. Industrial-scale German and Dutch bakeries prioritize cost-optimized liquid emulsions for automated dosing lines.
- Cakes:High-sugar matrices demand alcohol-soluble aromatic compounds resistant to Maillard reaction masking. British retail channels concentrate volume for celebration cake segments.
- Cookies:Extended bake times and low moisture finished states favor powder format stability. Southeast Asian export-oriented manufacturing clusters standardize on concentrated paste systems.
Bread applications anchor volume throughput. Pastry segments generate the fastest margin expansion through premiumization.
Form:
Physical state determines dosing precision, shelf stability, and capital equipment compatibility across production scales.
- Liquid:Metering accuracy in automated continuous lines defines industrial preference. Flowable emulsions dominate high-throughput German and French manufacturing facilities with integrated dosing infrastructure.
- Powder:Extended ambient stability suits dry-mix distribution and small-batch artisan operations. Microencapsulation technologies protect volatile compounds during storage.
- Paste:High-viscosity formats concentrate flavor load for reduced transportation costs. Southeast Asian foodservice distributors favor this form for manual scaling flexibility.
- Concentrate:Dilution-ratio standardization enables precise cost control in large-scale industrial baking. China's expanding domestic fermentation capacity targets this segment for import substitution.
Liquid formats hold the installed base. Concentrate systems are climbing the fastest as biotechnology-derived supply scales.
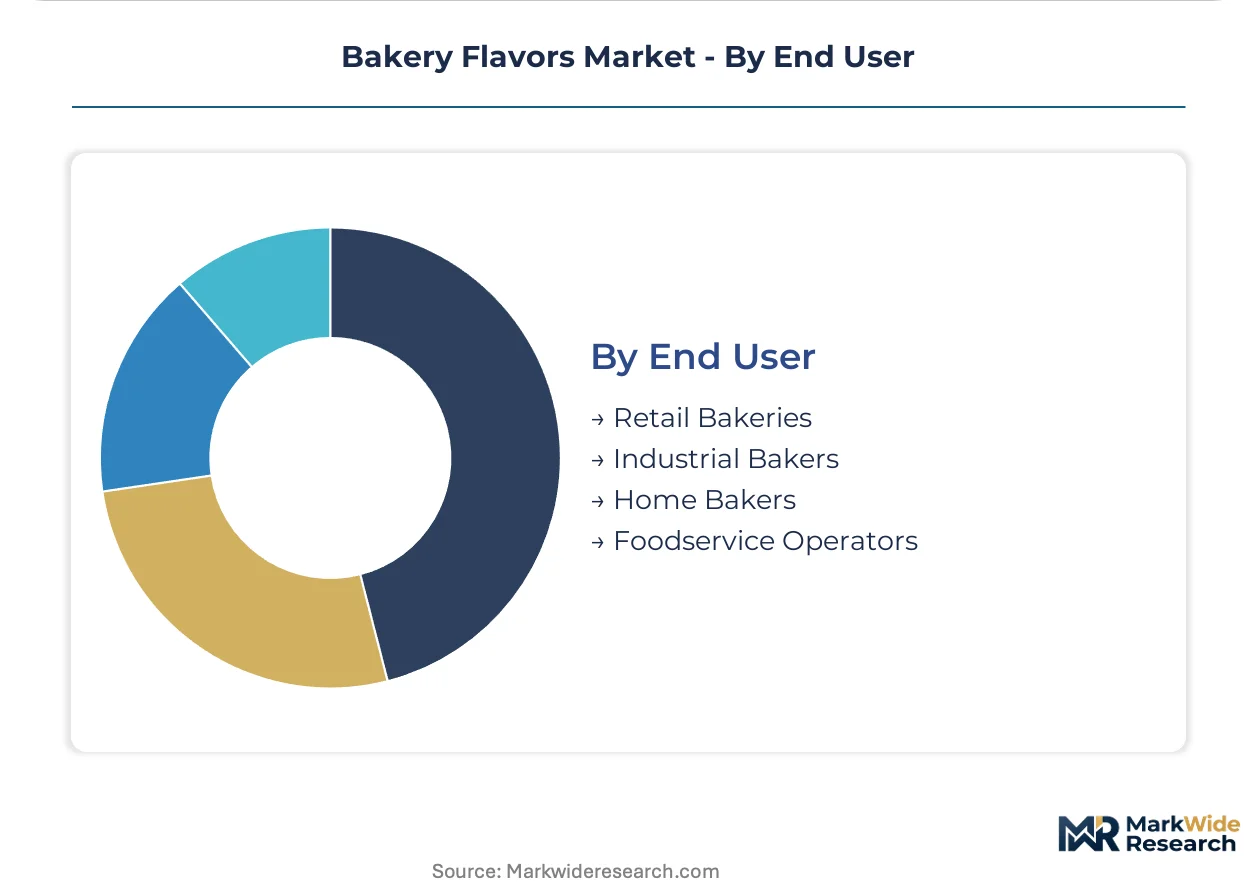
End User:
Operational scale and technical capability create divergent procurement patterns across bakery value chain participants.
- Industrial Bakers:Automated production lines demand bulk liquid supply with integrated regulatory dossier services. Consolidated supplier relationships dominate procurement in Netherlands and Denmark manufacturing zones.
- Retail Bakeries:Mid-scale batch operations balance formulation flexibility with cost control. French patisserie chains centralize R&D functions driving flavor complexity scaling.
- Foodservice Operators:Menu consistency requirements favor standardized concentrate formats with simple dilution protocols. Southeast Asian hospitality sectors concentrate demand growth.
- Home Bakers:Small-format retail packaging prioritizes extended shelf stability and intuitive usage instructions. E-commerce direct-to-consumer channels bypass traditional distribution intermediaries.
Industrial bakers represent the volume anchor. Foodservice operators are gaining share fastest as organized hospitality expands across Asia-Pacific markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France consumes bakery flavors through artisan patisserie channels demanding premium natural extracts, while China deploys fermentation-derived concentrates for industrial-scale bread manufacturing at cost-optimized price points.
France
Traditional patisserie culture drives demand for heat-stable encapsulated flavor systems in laminated dough applications. EFSA enforces purity thresholds under Regulation EC 1333/2008, accelerating natural extract substitution. Paris and Lyon industrial clusters concentrate formulation R&D for retail bakery chains.
Germany
Industrial bakery automation prioritizes liquid emulsion formats with integrated dosing precision. The country's national food regulator maintains strict additive approval timelines under EU harmonized standards. North Rhine-Westphalia manufacturing zones anchor high-throughput bread production lines.
China
Domestic fermentation capacity expansion narrows import dependency for high-intensity concentrates. SAMR implements GB standards for food flavor usage levels, creating localized testing requirements. Yangtze River Delta bioreactor facilities scale vanillin production through microbial cell factories.
United States
GRAS self-affirmation pathways for natural flavor substances enable faster product development cycles than European counterparts. FDA maintains distinct natural-claim definitions from EFSA, bifurcating compliance costs. Midwest industrial baking corridors concentrate automated production infrastructure.
India
Organized retail expansion creates entry points for heat-stable emulsion technologies in emerging bakery segments. FSSAI regulatory harmonization accelerates clean-label adoption timelines. Maharashtra and Karnataka food processing clusters attract multinational flavor house technical partnerships.
Bakery Flavors Market Vendor Landscape
Capability concentration sits with biotechnology-enabled specialists; scale advantage sits with diversified ingredient conglomerates. The vendor base separates into three tiers: Swiss-Dutch fermentation specialists, Irish-American integrated nutrition platforms, and regional emulsion technology providers. Consolidation pressure favors players offering combined formulation plus regulatory dossier services. Dominant competitive moves include captive biotechnology asset acquisition and automated dosing system integration partnerships.
Among Swiss-Dutch specialty chemical producers, Firmenich and Givaudan occupy positions anchoring precision fermentation capabilities for natural aromatic compounds. Kerry Group exemplifies the integrated nutrition platform archetype spanning industrial-scale emulsion manufacturing. These three entities represent the convergence of biotechnology assets with regulatory compliance infrastructure that procurement teams increasingly require.
| Leading Market Players |
|---|
| Firmenich |
| Kerry Group |
| Givaudan |
| Prinova |
| McCormick & Company |
| International Flavors & Fragrances |
| Symrise |
| Puratos |
| Sensient Technologies |
| Others |
Supply Flow & Price Mechanics
Madagascar and Indonesian vanilla bean harvests concentrate upstream supply for natural extract formulations, positioning Swiss fermentation specialists to capture margin pools from petrochemical-derived alternatives through biotechnology-derived aromatic compounds.
Pricing Analysis
Long-term offtake agreements dominate procurement between industrial bakery groups and integrated flavor houses, insulating volume buyers from spot volatility in agricultural extracts. Three-tier pricing structure across premium natural extracts, standard fermentation-derived compounds, and economy synthetic grades reflects certification complexity under EFSA Regulation 1333/2008. Cost compression in synthetic vanillin intensifies as Chinese bioreactor capacity scales, while French patisserie chains exhibit lowest price sensitivity due to heritage positioning requirements.
Supply Chain Analysis
Extended payment terms from European retail bakery chains strain working capital for Southeast Asian extract traders, accelerating consolidation around integrated suppliers with supply-chain finance facilities. Raw material sourcing centers on Madagascar and Indonesia for vanilla, China for citrus terpenes, and India for spice oleoresins. Single-source vulnerability in Madagascar vanilla harvests creates catastrophic disruption risk. Distribution runs through bulk liquid tanker networks for industrial accounts and specialty foodservice distributors for mid-scale operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation platforms are disrupting traditional agricultural extraction economics, with EFSA's 2023 novel food reclassification creating regulatory arbitrage opportunities for biotechnology-enabled suppliers.
For Market Incumbents: Entrench formulation-plus-dossier service bundles to disintermediate standalone extract traders. Acquire captive fermentation assets in Yangtze River Delta manufacturing zones to secure vanillin supply chains against Chinese domestic substitution. Prioritize heat-stable encapsulated systems R&D as natural compound thermal degradation threatens laminated dough applications.
For New Entrants and Emerging Players: India's Maharashtra and Karnataka food processing clusters offer underpenetrated entry points where FSSAI harmonization accelerates clean-label adoption timelines. Target foodservice concentrate formats in Southeast Asian hospitality sectors bypassing legacy distributor relationships. Deploy direct-to-bakery e-commerce platforms with simple dilution protocols to circumvent entrenched intermediaries.
For Investors and Strategic Acquirers: Capital is best deployed toward precision fermentation specialists with strain optimization IP and existing EFSA novel food dossiers. Long-term viability hinges on biotechnology-derived ingredient classifications achieving regulatory equivalence with traditional extracts. Monitor EFSA enforcement consistency on natural-claim verification timelines as inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fermentation Asset Acquisition | Secures vanillin supply chains against Chinese domestic bioreactor expansion displacing imports. |
| Heat-Stable Encapsulation R&D Investment | Addresses natural compound degradation above 180°C in French laminated dough applications. |
| Regulatory Dossier Service Expansion | Captures procurement consolidation as bakery chains centralize EFSA 1333/2008 compliance functions. |
| Direct-to-Bakery E-Commerce Launch | Bypasses traditional foodservice intermediaries in Southeast Asian organized hospitality expansion. |
| Precision Fermentation Strain Optimization | Unlocks novel aromatic pathways through AI-driven synthetic biology convergence at pilot scale. |
Methodological Framework
Desk research of EFSA guidance documents, SAMR GB standards filings, and customs trade data preceded structured interviews with flavor chemists, industrial bakery procurement directors, and fermentation platform engineers. Primary fieldwork with retail bakery chain R&D heads and specialty chemical distribution partners validated secondary findings. Bottom-up volume modeling triangulated against top-down ingredient consumption estimates from national bakery association statistics.
The analytical framework held regulatory enforcement intensity and biotechnology adoption curves constant across the projection horizon, varying flavor type segmentation by thermal application severity and physical state compatibility. CAGRs derived from segment-level volume build-ups incorporating end-user automation penetration rates and clean-label reformulation timelines. Heat stability performance thresholds and fermentation yield improvements served as key industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed bioreactor operators would shift outcomes substantially. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
South America Bakery Products Market
Bakery Products
Pastry Premixes Market
Bakery Products
Par-Baked Bread Market
Bakery Products
Packaged Bread Market
Bakery Products
Shelf-Stable Dough Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Gluten-Free Pizza Crust Market
Bakery Products
Pastry Dough Market
Bakery Products
Bread Mix Market
Bakery Products
Sweet Biscuits Market
Bakery Products
Ezekiel Bread Market
Bakery Products
South America Ice Cream Market
Bakery Products
Low Fat Oatmeal Cookies Market
Bakery Products
Aerating Cake Emulsifier Market
Bakery Products
Southeast Asia Bakery Products Market
Bakery Products
Bread and Baked Food Market