
 Pie Shells Market | 2026-2036
Pie Shells Market Size, Share, and Industry Trends Forecast 2026-2036
Pie Shells Market Analytics
A capital-intensity divergence between in-house milling capabilities and outsourced flour sourcing is unwinding competitive parity across the pie shells landscape. Pillsbury Pie Crusts leverages parent-company grain procurement infrastructure to sustain cost advantages in refrigerated dough production. Harlan Bakeries anchors its position through dedicated frozen shell lines serving co-manufacturing contracts for private-label retail programs. Wicks Pies Inc. differentiates via regional brand strength in the Midwest, where it controls distribution through direct-store-delivery networks.
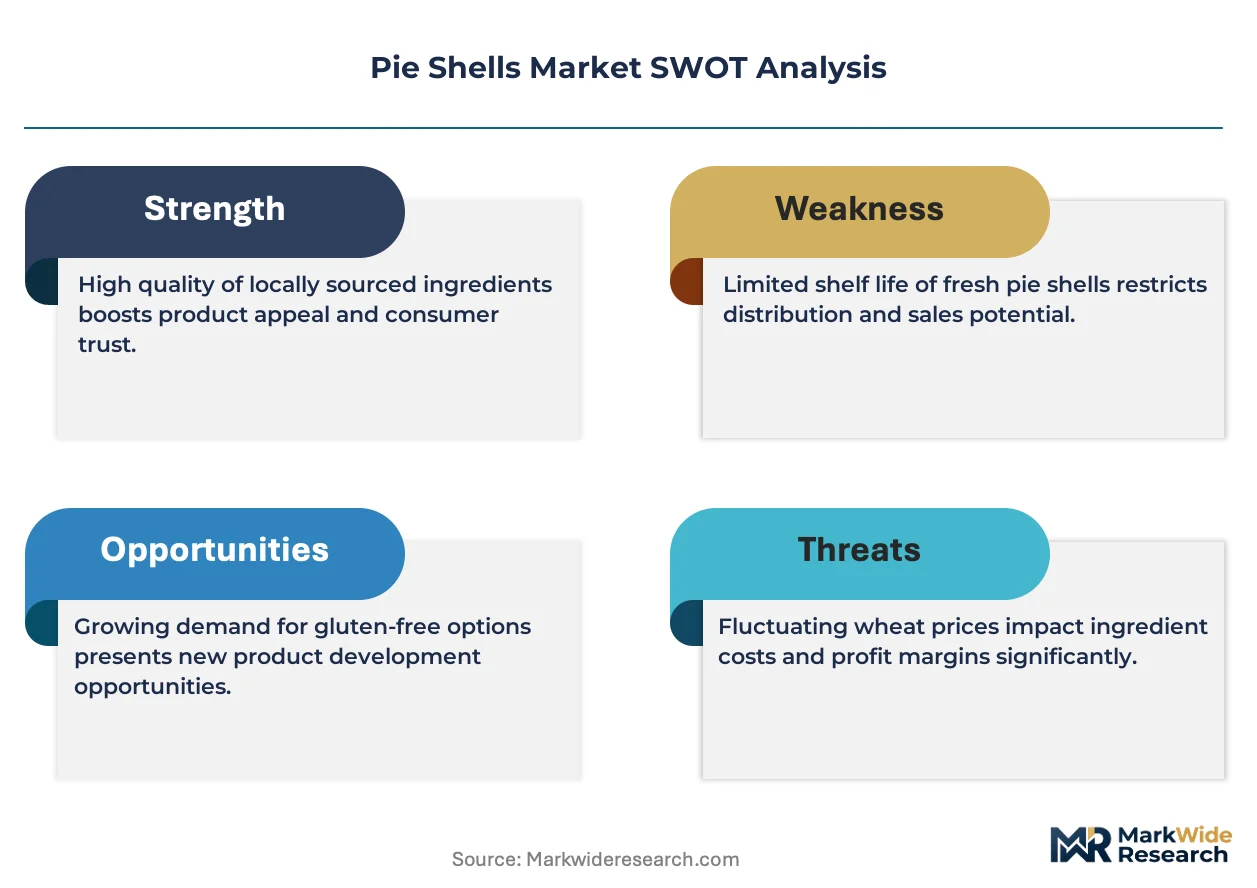
Pie shells are pre-formed, ready-to-fill crust structures manufactured from laminated or pressed dough, typically composed of wheat flour, shortening, and water, with thickness calibrated between 2.5 and 4.0 millimeters to withstand filling weights without structural failure. Their primary commercial purpose is to eliminate scratch preparation time in food manufacturing and foodservice operations while delivering consistent bake performance and flakiness. Frozen pie shells capture the dominant volume share due to extended shelf life and supply chain flexibility, though gluten-free formulations represent the fastest-expanding margin pool as allergen-free certification commands price premiums. Shelf-stable formats occupy a mature niche constrained by texture degradation under ambient storage, while refrigerated segments concentrate margin in premium private-label channels.
The FDA's Food Safety Modernization Act preventive controls and USDA facility inspection requirements shape manufacturing investments, particularly for ambient-stable products requiring validated kill-step documentation. The EPA's Clean Air Act permitting affects oven emissions in large-scale commercial bakeries, nudging capacity expansion toward states with streamlined environmental compliance pathways. Stakeholders must monitor evolving front-of-package labeling proposals and state-level extended producer responsibility legislation for plastic tray packaging, as these frameworks will determine which material and packaging segments absorb compliance costs versus competitive advantage.
Market Dynamics
Food service operators now source more pre-formed shells to reduce labor hours in commercial kitchens. The FDA's updated Food Safety Modernization Act rules on preventive controls for human food directly shape manufacturing protocols for ready-to-fill crusts.
Growth Catalysts
- FSMA Preventive Controls:The FDA's updated rules mandate validated kill-step documentation for ambient-stable products, forcing manufacturers to upgrade thermal processing capabilities and creating compliance-driven demand for certified shell suppliers.
- Quick-Service Restaurant Expansion:Institutional cafeterias and QSR chains in the United States drive bulk procurement of frozen formats, converting scratch kitchens to pre-formed solutions to compress labor costs and standardize output.
- Gluten-Free Formulation Advances:Alternative flour technologies using rice, almond, and tapioca bases now achieve structural integrity comparable to wheat, opening allergen-free certification channels that command price premiums in retail and foodservice.
Market Restraints
- Wheat Flour Price Volatility:Input cost swings tied to commodity grain markets compress margins for manufacturers without parent-company grain procurement infrastructure or long-term supply contracts.
- Extended Shelf-Life Trade-offs:Ambient-stable formats require moisture-barrier packaging and modified atmosphere systems that degrade texture quality, limiting penetration in premium channels where flakiness is non-negotiable.
- Plastic Packaging Liability:State-level extended producer responsibility legislation in California and New York threatens to impose end-of-life costs on manufacturers using traditional PET trays, squeezing economics for frozen shell distributors.
Strategic Opportunities
- Co-Manufacturing Partnerships:Private-label retail programs seek dedicated frozen shell lines, creating white-space for mid-cap bakeries to capture volume through contract production without brand-building overhead.
- Direct-Store-Delivery Networks:Regional distributors in the Midwest control refrigerated segments through captive route density, offering template for geographic expansion into underserved Southeast and Southwest markets.
- Clean Air Act Compliance Arbitrage:EPA oven emissions permitting drives capacity expansion toward states with streamlined environmental pathways, rewarding early movers in Texas and Florida with faster commissioning timelines.
Industry Challenges
- Preventive Controls Qualified Individual Shortage:FSMA mandates PCQI certification for food safety plan oversight, yet training pipeline bottlenecks delay facility approvals and constrain output ramp rates.
- Laminated Dough Process Capital Intensity:Automated sheeting and layering equipment for flakiness calibration demands seven-figure capital deployment, favoring scaled players over artisan entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pie Shells Market |
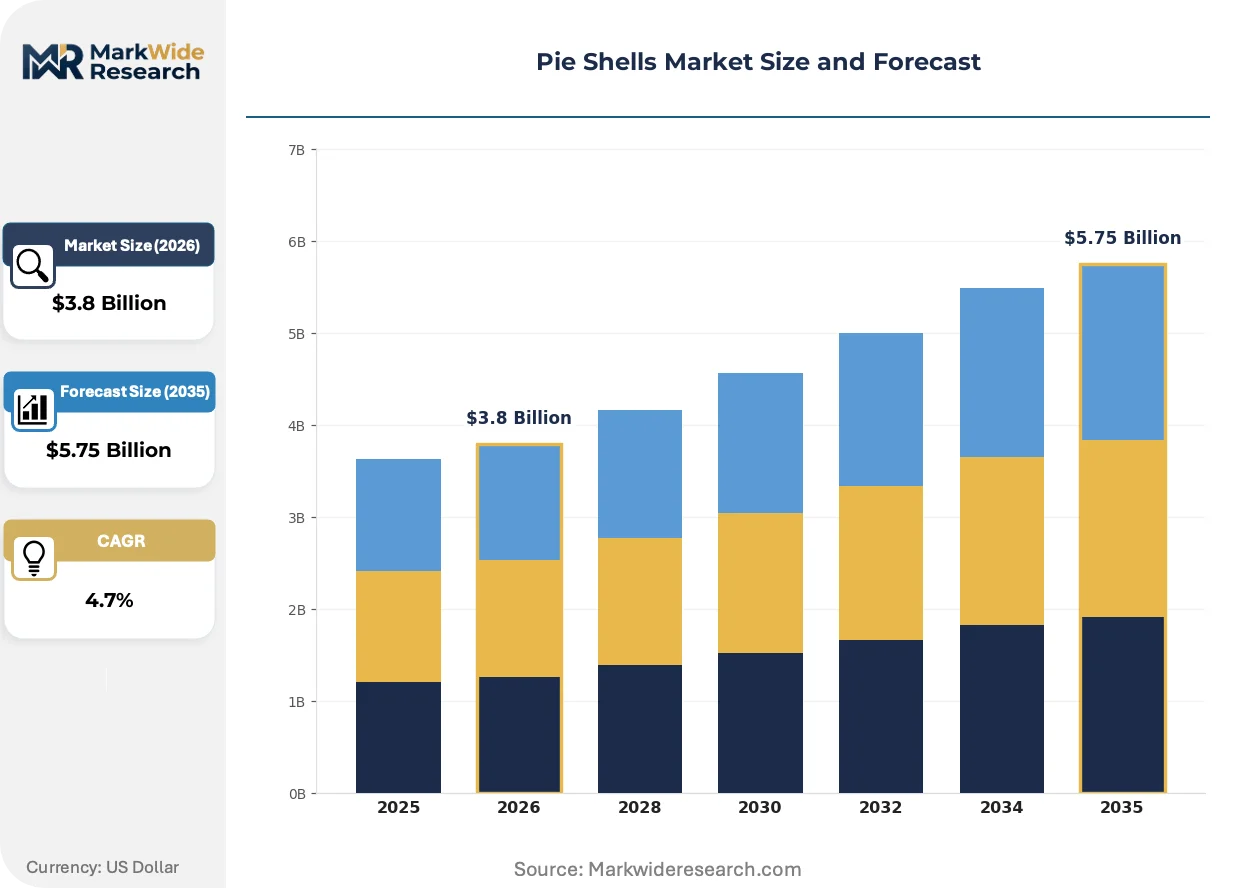
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen, Refrigerated, Shelf-Stable, Gluten-Free Material: Wheat, Almond Flour, Coconut, Rice Flour End User: Households, Bakeries, Restaurants, Food Service Packaging Type: Boxes, Plastic Wrap, Pouches, Trays |
| Companies Covered | Wholly Wholesome, Ready Bake Pty Ltd, Chalmers Bakery, DIY Scotch Pie Company, Pillsbury Pie Crusts, Harlan Bakeries, Wicks Pies Inc., Gilster-Mary Lee Corporation, Pied Piper Pastries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pie Shells Market Evolving Landscape
Active thermal processing and packaging technologies are compressing spoilage windows and enabling format diversification. Regulatory pressure on emissions and labeling is accelerating equipment turnover and material substitution across the value chain.
High-pressure processing technology for refrigerated dough is miniaturizing. Mid-scale regional bakeries now adopt compact HPP units previously limited to multinational facilities, enabling extended shelf-life claims without freezing. This capability compression erodes the volume advantage of centralized frozen production and supports distributed manufacturing models.
REACH restrictions on per- and polyfluoroalkyl substances in food-contact materials are forcing fluoropolymer coating replacements in baking trays. European manufacturers pilot ceramic-silicone hybrid surfaces that eliminate PFAS migration risk while maintaining release properties. Frozen shell exporters to the EU face reformulation deadlines that favor early adopters with validated alternative coatings.
Consolidated buying by group purchasing organizations now dominates institutional procurement. Independent distributors lose share to GPO-negotiated contracts that bundle pie shells with broader bakery portfolios, compressing margins for standalone shell specialists. This concentration is most visible in K-12 and healthcare foodservice verticals across the United States.
Pie Shells Market Segmentation
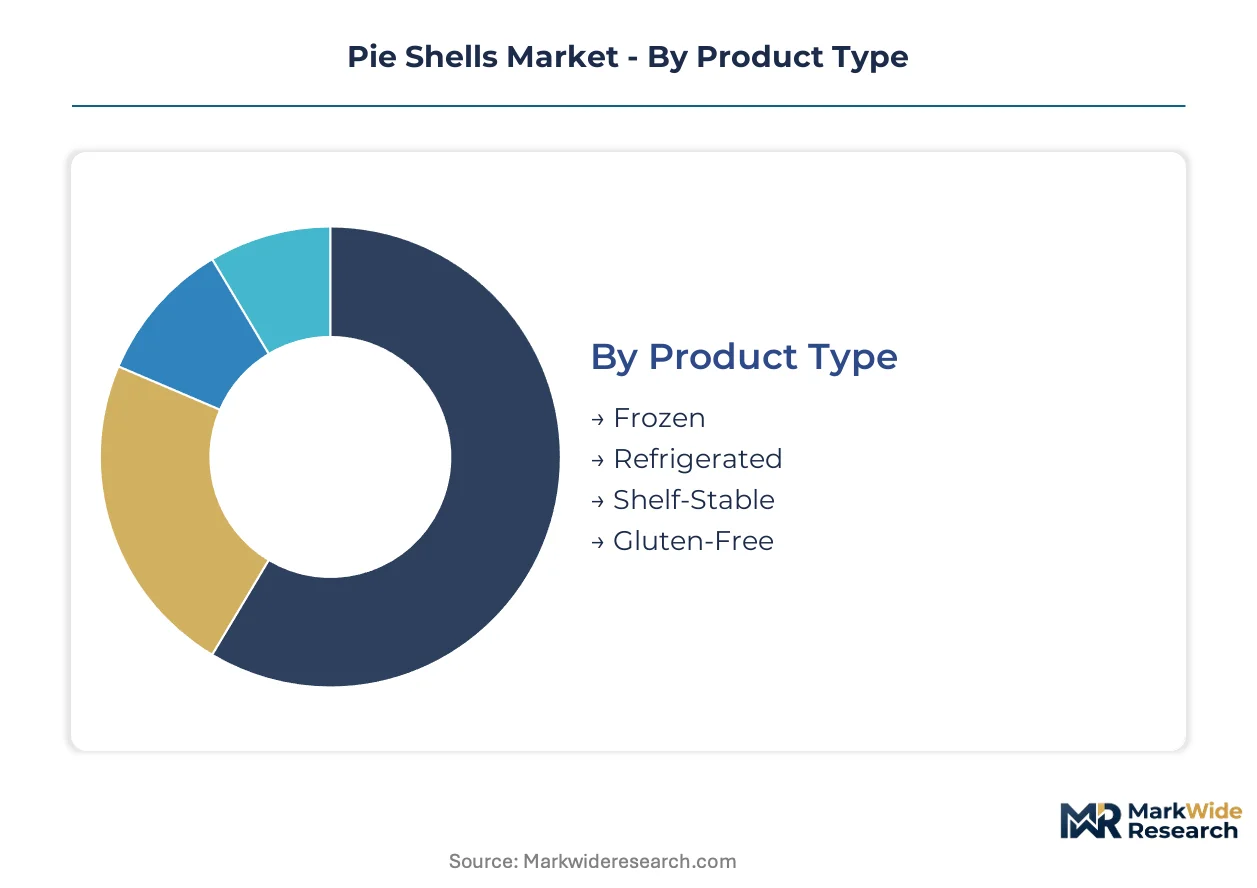
Pie shells manufacturers calibrate production lines to distinct shelf-life and handling requirements across formats. Segment-specific compliance obligations, particularly thermal processing documentation for ambient-stable variants, determine facility investments and geographic sourcing patterns.
Product Type:
Domestic procurement dominates frozen and refrigerated segments, while shelf-stable formats drive export volume to markets with limited cold-chain infrastructure.
- Frozen:Extended shelf-life through blast freezing at minus 18 degrees Celsius enables nationwide distribution without spoilage risk. Quick-service restaurants and institutional cafeterias in the United States consolidate procurement through frozen formats to standardize portion control and reduce kitchen labor.
- Gluten-Free:Alternative flour formulations using rice, almond, and tapioca bases achieve structural parity with wheat crusts. Allergen-free certification commands price premiums in retail channels across the United States, where celiac awareness drives substitution demand.
- Refrigerated:Premium positioning in private-label retail with shorter shelf windows requiring continuous cold-chain integrity.
- Shelf-Stable:Moisture-barrier packaging and validated kill-step documentation per FDA preventive controls; texture trade-offs limit premium channel penetration.
Frozen commands the established base. The steepest expansion runs through gluten-free.
Material:
Cost tier stratification separates commodity wheat from specialty alternative flours with divergent margin profiles and supply concentration.
- Wheat:Standard hard red winter and spring wheat varieties deliver consistent gluten development for laminated dough structures. Parent-company grain procurement infrastructure, as seen with Pillsbury's captive supply, sustains cost advantages against contract-dependent competitors.
- Almond Flour:California-sourced blanched almond meal provides fat content that mimics shortening functionality in gluten-free formulations. Price volatility tied to drought cycles and pollination costs compresses margins for manufacturers without multi-year nut supply contracts.
- Rice Flour:White and brown rice milling byproducts from Arkansas and Louisiana processors offer domestic sourcing security with neutral flavor profiles.
- Coconut:Southeast Asian and Philippine supply chains introduce currency and shipping cost variables for desiccated flour variants.
Wheat anchors volume scale. Almond flour climbs the fastest on allergen-free demand.
End User:
Customer type determines order frequency, specification stringency, and route-to-market economics across the value chain.
- Food Service:Group purchasing organizations bundle pie shells with broader bakery portfolios, compressing margins for standalone specialists. K-12 and healthcare verticals concentrate procurement through GPO-negotiated contracts with frozen format dominance.
- Restaurants:Quick-service chains convert scratch kitchens to pre-formed solutions, driving bulk procurement with standardized thickness tolerances between 2.5 and 4.0 millimeters.
- Bakeries:Co-manufacturing demand from private-label retail programs rewards dedicated frozen shell lines without brand-building overhead.
- Households:Supermarket retail with seasonal demand spikes concentrated around holiday baking periods.
Food service locks in contract volume. Restaurant channel gains share fastest on QSR expansion.
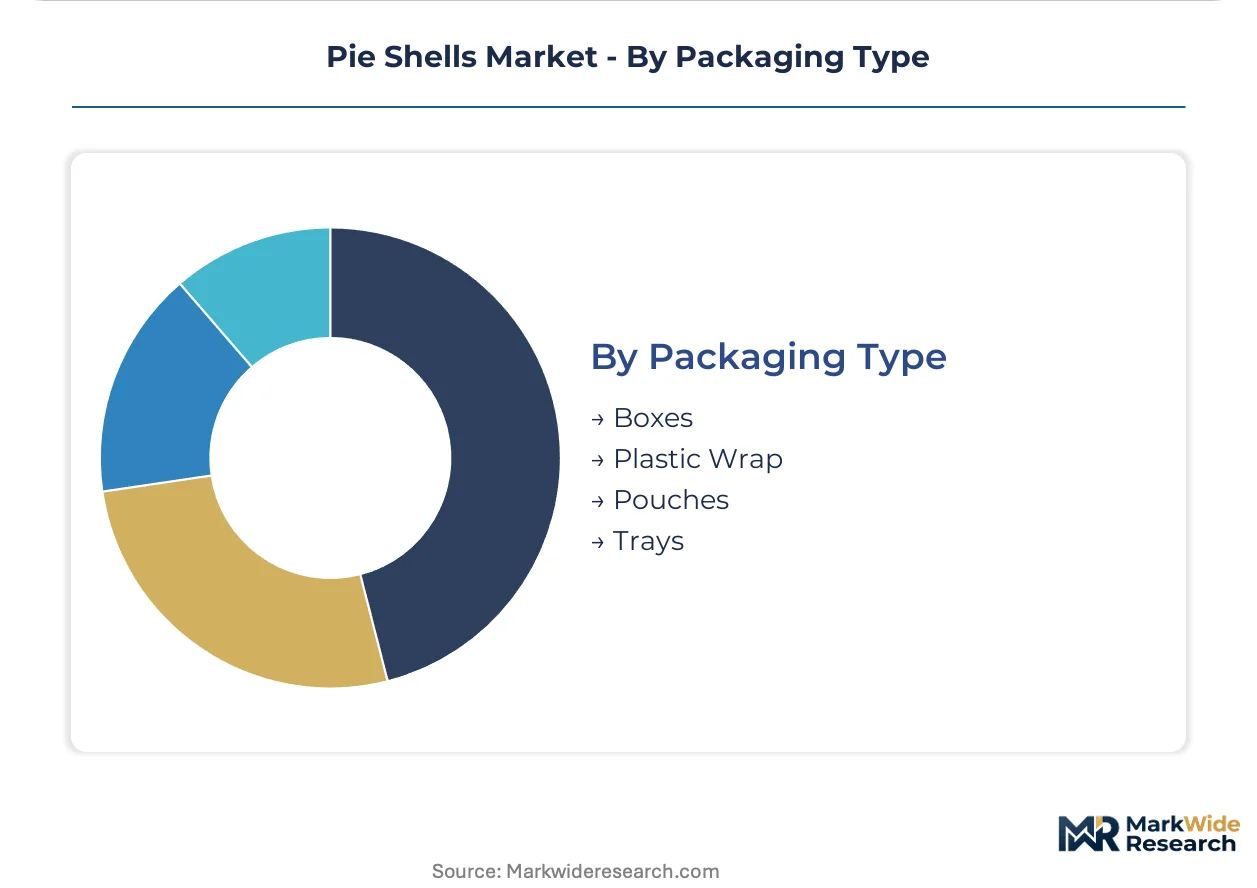
Packaging Type:
Material substitution accelerates under extended producer responsibility legislation with divergent compliance cost allocation.
- Trays:PET and PP thermoformed containers dominate frozen shell presentation with structural protection during distribution. California and New York state-level EPR laws threaten end-of-life cost imposition, favoring early movers into fiber-based alternatives.
- Boxes:Corrugated secondary packaging for multi-unit retail configurations with established recycling infrastructure.
- Plastic Wrap:PVC and PE films for refrigerated dough logs with oxygen barrier properties.
- Pouches:Flexible laminates for ambient-stable formats requiring moisture and light exclusion.
Trays maintain format dominance. Pouch configurations expand most quickly on shelf-stable export demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European markets absorb compliance premiums. The Midwest corridor anchors frozen shell production capacity. Asian markets remain import-dependent for gluten-free formulations.
United States
Quick-service restaurants and institutional cafeterias drive bulk frozen format procurement through group purchasing organizations. The FDA's Food Safety Modernization Act preventive controls mandate validated kill-step documentation for ambient-stable production. Chicago and Indianapolis host dedicated frozen shell lines serving private-label retail programs.
Germany
REACH restrictions on per- and polyfluoroalkyl substances force fluoropolymer coating replacements in baking trays. ECHA compliance deadlines favor early adopters with validated ceramic-silicone hybrid surfaces. Bavaria-based industrial bakeries pilot PFAS-free release coatings for frozen shell exports.
United Kingdom
Co-manufacturing demand from supermarket private-label programs rewards dedicated production lines without brand-building overhead. The Food Standards Agency enforces allergen labeling protocols that compress time-to-market for gluten-free launches. Greater Manchester clusters refrigerated dough capacity for premium retail channels.
Canada
Health Canada and PMRA regulate food-contact materials and pesticide residues in wheat sourcing. Cross-border frozen shell trade flows through Ontario distribution hubs serving QSR chains. Toronto-area facilities specialize in extended shelf-life refrigerated formats for foodservice.
Australia
TGA-aligned state food regulators enforce strict import inspection for frozen bakery products. Domestic almond flour milling from South Australian orchards supports gluten-free formulation security. Sydney and Melbourne bakeries concentrate pouch-format ambient-stable production for Pacific export.
Pie Shells Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the pie shells landscape. Parent-company grain procurement infrastructure sustains cost advantages for scaled refrigerated dough producers. Three archetypes dominate: vertically integrated grain-to-crust operators, dedicated frozen shell co-manufacturers, and regional direct-store-delivery specialists. Competitive moves concentrate on co-manufacturing contract capture and geographic expansion into underserved Southeast and Southwest markets.
Among North American operators, Pillsbury Pie Crusts exemplifies the grain-procurement-integrated archetype, while Harlan Bakeries occupies a position within the dedicated frozen production tier. Wicks Pies Inc. represents the regional direct-store-delivery model with captive route density in the Midwest. These three anchors illustrate how capital intensity, supply chain configuration, and distribution control separate sustainable positions from commodity pressure.
| Leading Market Players |
|---|
| Wholly Wholesome |
| Ready Bake Pty Ltd |
| Chalmers Bakery |
| DIY Scotch Pie Company |
| Pillsbury Pie Crusts |
| Harlan Bakeries |
| Wicks Pies Inc. |
| Gilster-Mary Lee Corporation |
| Pied Piper Pastries |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between frozen shell manufacturers and quick-service restaurant chains lock in multi-year supply access while insulating buyers from wheat flour price volatility. These arrangements concentrate procurement power among institutional buyers with volume scale, compressing spot-market liquidity and amplifying cost advantages for parent-company grain procurement infrastructure.
Pricing Analysis
Customization-premium spreads separate configured-to-order gluten-free formulations from standard wheat-based shells. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with FSMA-compliant ambient-stable formats commanding top-tier positioning. Pricing pressure stems from almond flour input volatility tied to California drought cycles, squeezing margins for allergen-free specialists without multi-year nut supply contracts. Quick-service restaurants exhibit highest price sensitivity due to GPO-negotiated bundled procurement, while premium private-label retail channels absorb certification premiums with minimal elasticity.
Supply Chain Analysis
Inbound logistics costs from Southeast Asian coconut flour supply chains face currency fluctuation and container availability constraints on Pacific trade lanes. Production gravity centers on the United States, Canada, and Germany, with wheat sourcing anchored in domestic hard red winter varieties and almond flour drawn from California orchards. Single-source vulnerability concentrates in Philippine desiccated coconut supply for specialty formulations. Distribution runs through frozen cold-chain networks serving institutional cafeterias and direct-store-delivery routes for refrigerated premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable barriers. FSMA preventive controls certification and PCQI staffing requirements impose switching costs that protect incumbent positions.
For Market Incumbents: Secure co-manufacturing contract capture through dedicated frozen shell line investments in Texas and Florida, exploiting Clean Air Act compliance arbitrage for faster commissioning timelines. Deepen backward integration into almond flour milling to offset California drought-driven input volatility. Reinforce route density in underserved Southeast markets before regional distributors replicate Midwest direct-store-delivery templates. For New Entrants and Emerging Players: Lead with gluten-free formulation specialization targeting retail channels where allergen-free certification commands price premiums absent from commoditized wheat segments. Geographic white space concentrates in Southwest institutional cafeterias where GPO bundling has displaced standalone shell specialists. Co-manufacturing partnerships with private-label programs offer volume ramp without brand-building overhead. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among frozen shell co-manufacturers with multi-year QSR contracts and validated kill-step documentation. Five-to-ten-year viability favors operators with parent-company grain procurement infrastructure or captive regional distribution networks. Watch for EPR legislation acceleration in additional states as inflection indicator for packaging material substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Manufacturing Contract Capture | Harlan Bakeries validates dedicated frozen shell lines serving private-label retail programs without brand overhead. |
| Clean Air Act Compliance Arbitrage | Capacity expansion toward Texas and Florida rewards early movers with streamlined EPA oven emissions permitting. |
| Gluten-Free Formulation Investment | Rice and tapioca flour alternatives achieve structural parity with wheat crusts for allergen-free certification premiums. |
| Direct-Store-Delivery Network Expansion | Wicks Pies Inc. demonstrates Midwest route density control that templates Southeast and Southwest geographic penetration. |
| PFAS-Free Coating Transition | German ceramic-silicone hybrid surfaces eliminate REACH restriction exposure for frozen shell EU export compliance. |
Research Methodology
Operator-level perspectives from plant managers at commercial bakeries, procurement leads at quick-service restaurant chains, and regulatory affairs specialists anchored the qualitative base for this analysis. Primary interviews with frozen dough production supervisors and group purchasing organization contract managers combined with secondary validation from FDA FSMA guidance documents, USDA facility inspection records, and EPA Clean Air Act permitting databases. Trade data from customs records and commercial bakery industry associations supported bottom-up and top-down triangulation across the projection horizon.
Sensitivity analysis tested volume and value outputs against wheat flour commodity price bands and almond supply shock scenarios. The analytical framework modeled segmentation dimensions including product format, material composition, end-user channel, and packaging type across the analysis window. CAGRs derived from installed capacity utilization trends and QSR expansion pipeline data, with gluten-free penetration rates and EPR legislation adoption timelines as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA preventive controls and EPA emissions regimes; material policy shifts would require re-modeling. Wheat price volatility, PFAS restriction acceleration, or cold-chain infrastructure disruptions represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Pastry Premixes Market
Bakery Products
Wedding Cakes Market
Bakery Products
Matcha Cookie Market
Bakery Products
Baking Molds and Trays Market
Bakery Products
Biscuit Mixes Market
Bakery Products
Fondant Market
Bakery Products
Low Calorie Bread Market
Bakery Products
Sweet Biscuits Market
Bakery Products
Batter and Breader Premixes Market
Bakery Products
Low Fat Bran Muffins Market
Bakery Products
Asia-Pacific Bakery Products Market
Bakery Products
Bahrain Bakery Product Market
Bakery Products
Ice Cream Cones Market
Bakery Products
Bread Market
Bakery Products
Gluten-Free Bakery Premixes Market
Bakery Products
Ready-To-Finish Bakery Products Market