
 Wine Filling Machine Market | 2026-2036
Wine Filling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Filling Machine Market Analytics
Contract packers are redrawing equipment procurement patterns as boutique wineries outsource bottling to manage seasonal volume swings. Krones AG anchors European supply with integrated filling lines that span rinsing to capping. Sidel Group differentiates through aseptic technology leadership for premium still and sparkling formats. Jiangsu Zenith Packaging competes on manufacturing scale for mid-capacity Asian installations.
A wine filling machine meters precise liquid volumes into bottles, carafes, or alternative vessels while controlling oxidation, foam, and fill-level accuracy to within ±1 milliliter. Gravity fillers dominate still wine applications where low-viscosity flow permits simple, sanitation-friendly architecture; vacuum fillers lead sparkling and high-alcohol segments where CO₂ retention demands pressure-balanced systems. Automatic technology captures the majority of new capital expenditure as labor costs and throughput requirements climb, while robotic integration remains nascent outside top-tier Champagne houses.
EU CE marking and the EU Green Deal shape machine design through energy-efficiency mandates and recyclable material compatibility requirements. FDA oversight of imported wine contact surfaces affects cross-Atlantic equipment trade. Stakeholders must weigh automation depth against winery scale and regulatory jurisdiction before committing capital.
Market Dynamics
EU MDR and CE marking frameworks are compressing equipment replacement cycles as boutique wineries face mandatory hygiene upgrades, while contract packers absorb seasonal volume volatility that individual producers cannot shoulder alone.
Growth Catalysts
- EU Green Deal energy mandates:Equipment manufacturers redesign filling lines to meet recyclable material compatibility and energy-efficiency thresholds, forcing wineries to modernize.
- Prosecco and Barolo cluster expansion:Veneto and Piedmont production zones drive capacity investment as protected designation of origin volumes climb.
- Semi-automatic technology:Mid-scale wineries abandon manual bottling to satisfy tightening MDR documentation and traceability requirements.
Market Restraints
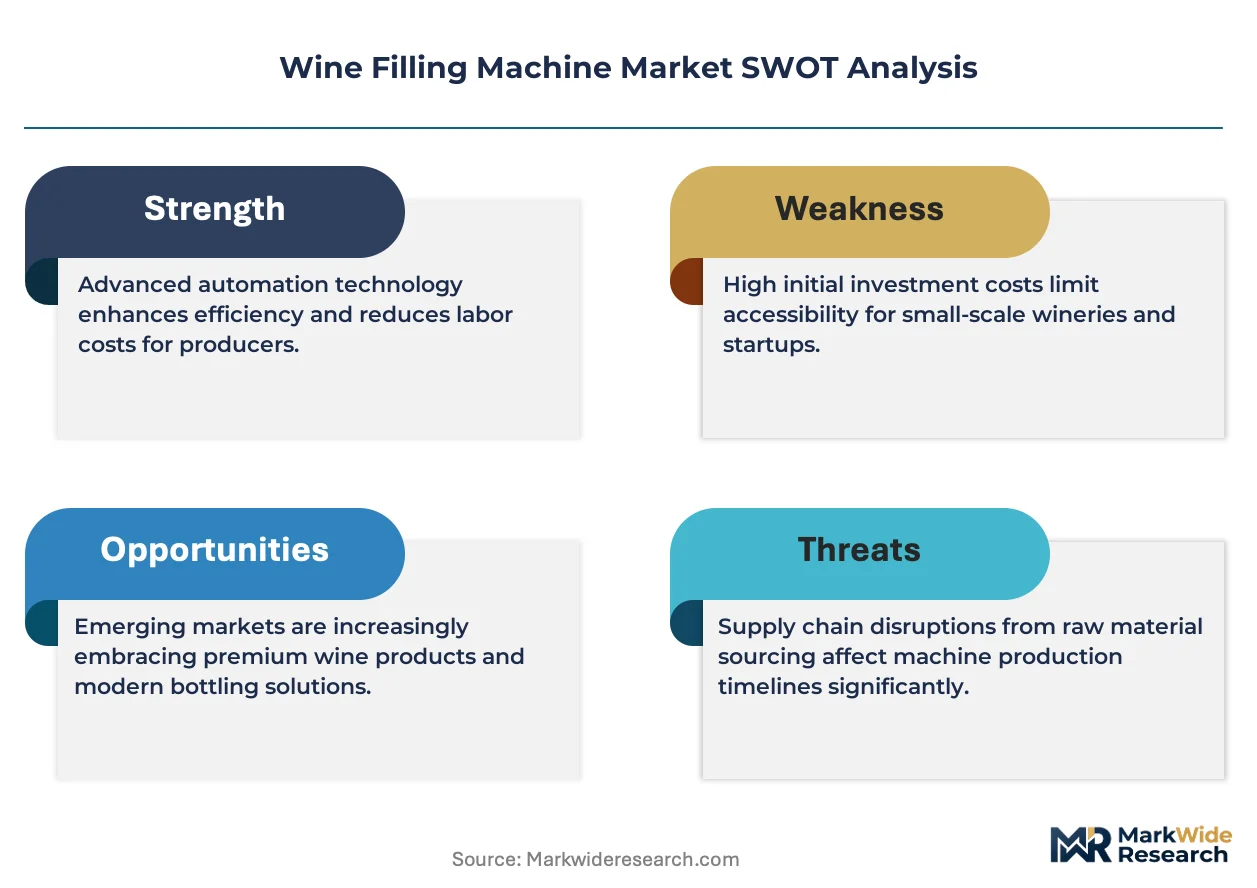
- Stainless steel and servo motor cost volatility:Input price swings compress margin visibility for equipment fabricators and extend quoting cycles.
- European component supply concentration:Precision valve and pump sourcing clusters in Germany and northern Italy, creating single-source vulnerability.
- CO₂ retention technical ceiling:Vacuum filler architecture hits pressure-balancing limits at ultra-high sparkling wine throughput, capping line speed.
Strategic Opportunities
- Indian wine sector formalization:Nascent domestic production and imported bulk bottling create first-mover positioning for mid-capacity gravity filler suppliers.
- Robotic integration convergence:Vision-guided depalletizing and capping robotics merge with traditional filling lines in Champagne houses, establishing upgrade templates.
- Aseptic technology licensing:Premium still and sparkling formats demand sterile filling environments, opening technology transfer partnerships outside Europe.
Industry Challenges
- Mechatronics technician scarcity:Servo-driven filling line maintenance demands cross-trained automation specialists that regional labor pools lack.
- CE-MDR dual certification timelines:Parallel conformity assessment processes delay equipment commissioning by quarters, freezing capital deployment.
- Legacy gravity filler integration:Older rinsing and capping stations resist communication protocol harmonization with new PLC architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Filling Machine Market |
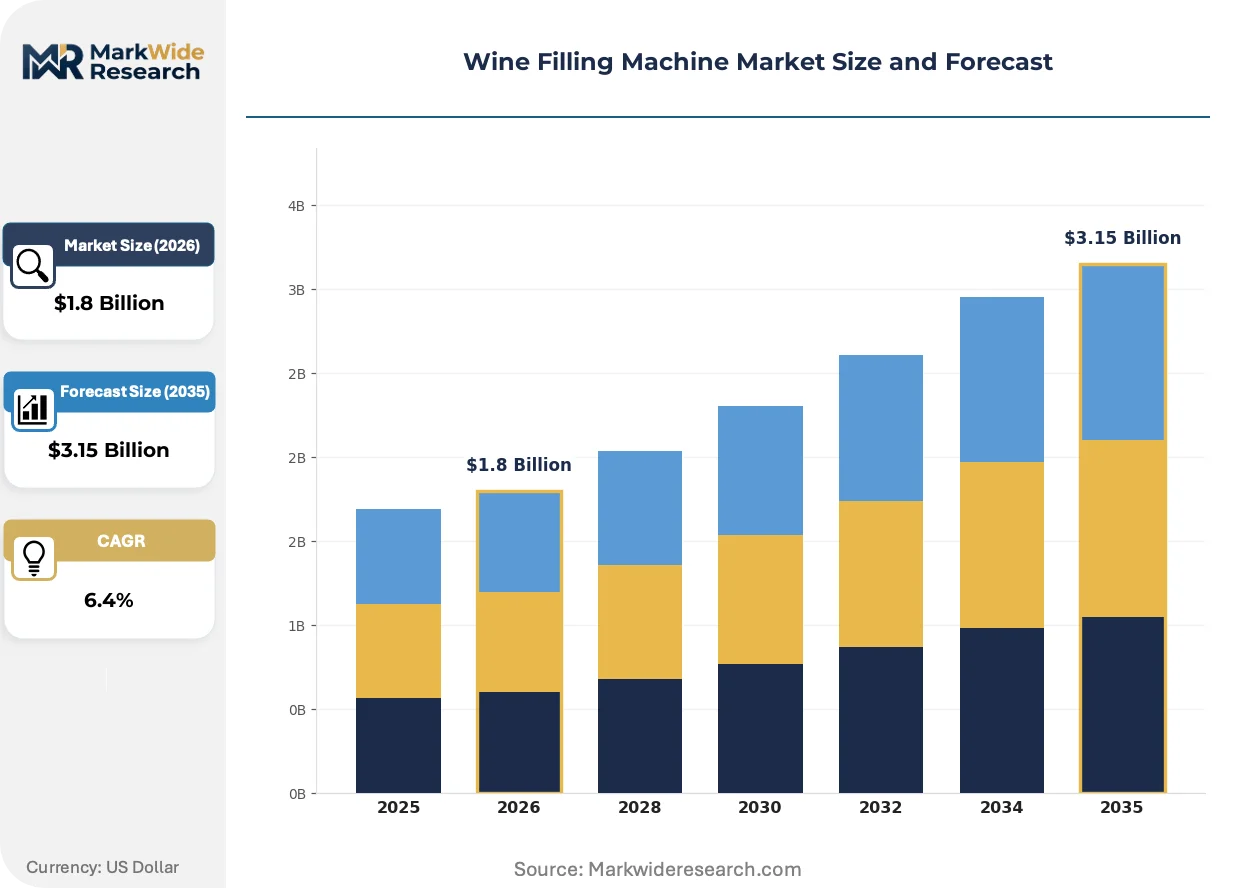
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
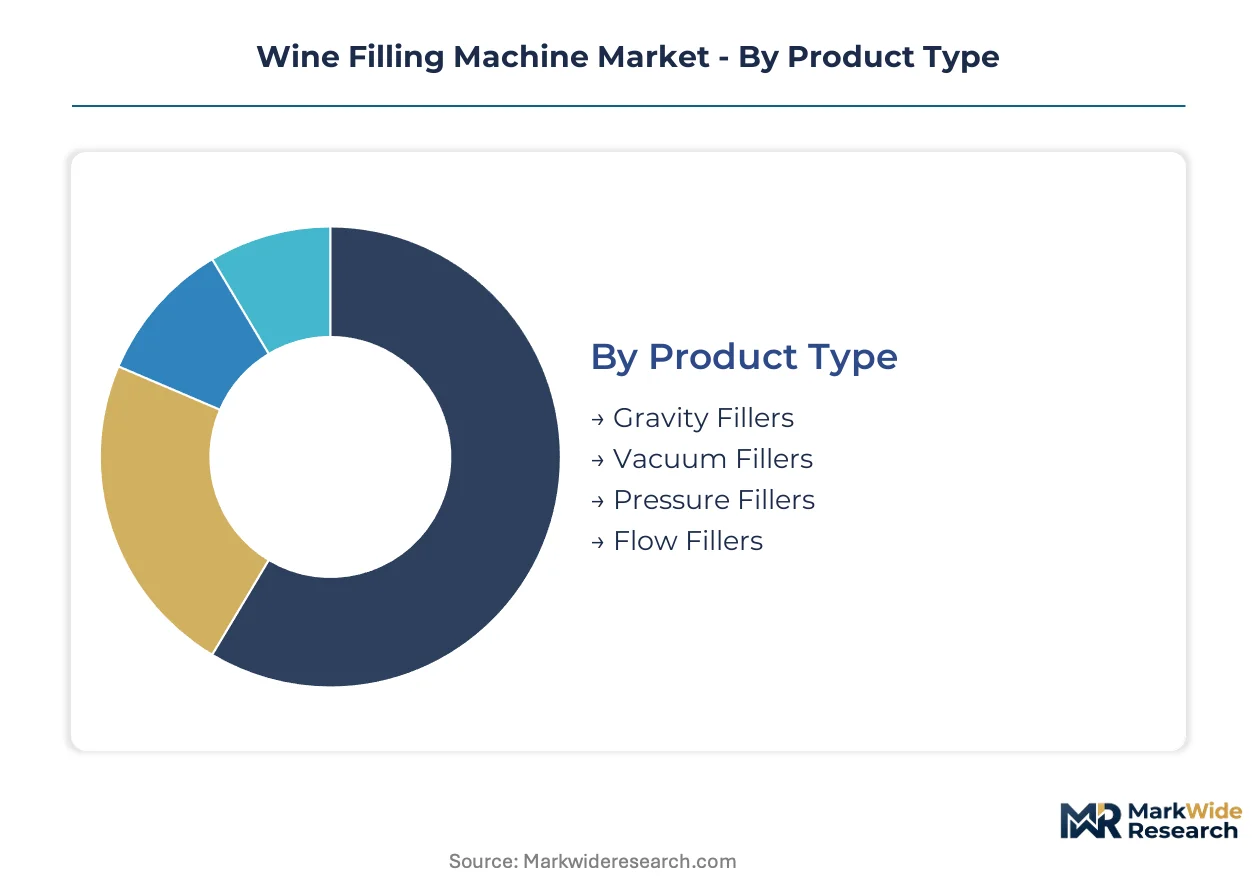
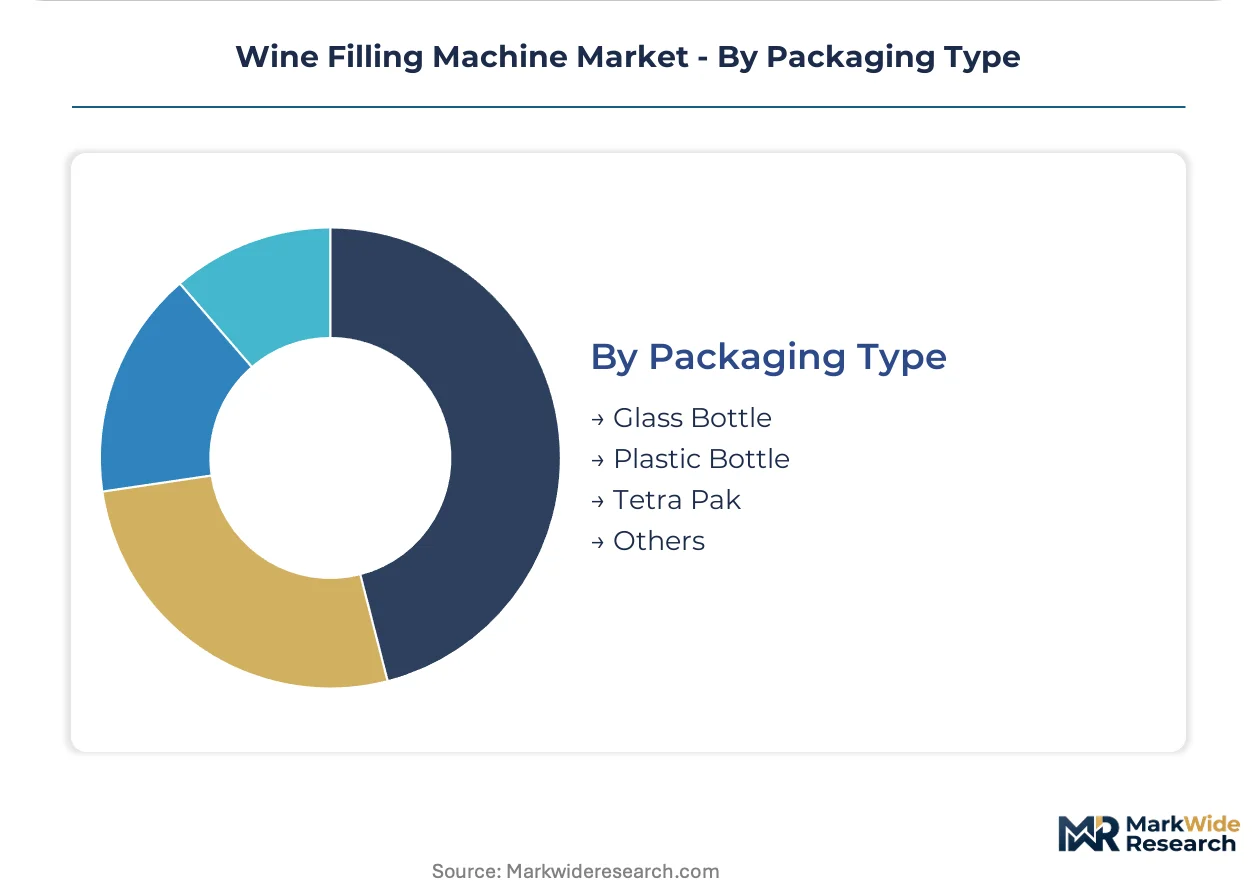
| Segmentation | Product Type: Gravity Fillers, Vacuum Fillers, Pressure Fillers, Flow Fillers End User: Winery, Beverage Manufacturer, Contract Packer, Research Institution Technology: Automatic, Semi-Automatic, Manual, Robotic Packaging Type: Glass Bottle, Plastic Bottle, Tetra Pak, Others |
| Companies Covered | GAIotto srl, Fogg Filler, Krones AG, Biner Ellison, JBT Corporation, Sidel Group, KHS GmbH, Jiangsu Zenith Packaging, Sacmi Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Filling Machine Market Evolving Landscape
Digital twin simulation and closed-loop fill-level sensing are compressing commissioning errors and oxidation losses, reshaping how wineries justify automation capital.
Electromagnetic flow metering is fragmenting traditional volumetric filler architectures by enabling real-time density compensation without mechanical contact. Champagne houses and premium still wine producers adopt these systems fastest, drawn by ±0.5 milliliter accuracy claims. The technology is fragmenting supplier hierarchies as sensor-software specialists enter a market once dominated by mechanical engineering incumbents.
EU F-Gas Regulation phase-down mandates are accelerating hydrocarbon and CO₂ refrigerant adoption in bottle-cooling tunnels that precondition vessels before filling. Equipment fabricators redesign heat exchangers and compressor loops to accommodate lower-GWP alternatives. Sparkling wine producers in France and Italy face the steepest retrofit obligations given their reliance on precise temperature control for CO₂ saturation stability.
Boutique wineries are consolidating bottling runs through mobile contract packing services rather than owning dedicated lines. Third-party packers in Australia's Yarra Valley and California's Central Coast aggregate fragmented vintage schedules into efficient block bookings. This behavior concentrates equipment procurement decisions among fewer, larger contract operators who favor flexible, quick-changeover formats over dedicated single-SKU lines.
Wine Filling Machine Market Segmentation
Wine filling machine procurement channels diverge sharply by segment. Boutique wineries purchase through regional distributors, while contract packers negotiate direct with European fabricators for integrated lines.
Product Type:
Gravity fillers flow through high-volume distributor networks serving still wine producers, while vacuum and pressure systems move via specialized technical sales channels targeting sparkling houses.
- Gravity Fillers:These machines rely on hydrostatic head to meter low-viscosity still wines without mechanical pumps, minimizing oxidation through gentle laminar flow. Demand clusters in Italy's Veneto region where prosecco bottling lines prioritize sanitation-friendly architecture and simple CIP protocols. Producers value the format's compatibility with EU Green Deal energy mandates.
- Vacuum Fillers:Negative pressure systems draw wine into bottles while maintaining CO₂ equilibrium, essential for sparkling wine and high-alcohol fortified categories. Champagne houses in France's Marne department specify these for pressure-balanced filling at sub-zero temperatures. The segment faces throughput ceilings as line speeds approach vacuum pump capacity limits.
- Pressure Fillers:Counter-pressure designs handle carbonated wines and alternative formats requiring precise gas retention control.
- Flow Fillers:Electromagnetic and Coriolis-based metering systems enable real-time density compensation for premium still wines.
Gravity fillers dominate installed base. Vacuum fillers are where expansion concentrates.
End User:
Winery scale determines automation depth, with capital tiers separating estate producers from outsourced bottling operations.
- Winery:Estate-owned installations span manual single-head units to fully automatic rotary systems. Piedmont's Barolo producers favor semi-automatic gravity lines that balance MDR compliance with limited vintage volumes. These operators prioritize traceability documentation and CE-marked hygiene standards over maximum throughput.
- Contract Packer:Third-party bottling services aggregate fragmented demand across multiple small producers, requiring quick-changeover flexibility. Australia's Yarra Valley packers specify modular lines that switch between still and sparkling formats within single shifts. Their procurement concentrates capital among fewer, larger equipment decisions than individual wineries.
- Beverage Manufacturer:Multi-category drinks groups deploy standardized filling platforms across wine and adjacent segments.
- Research Institution:University enology programs and experimental wineries pilot novel filling technologies at pilot scale.
Wineries retain the largest installed base. Contract packers are climbing the fastest.
Technology:
Labor cost trajectories and regulatory documentation burdens push automation decisions, with robotic integration remaining nascent outside elite Champagne houses.
- Automatic:PLC-controlled rotary fillers with servo-driven bottle handling capture majority capital expenditure as throughput requirements climb. These systems integrate closed-loop fill-level sensing and automatic changeover protocols demanded by EU MDR traceability frameworks. Italian and German fabricators lead supply.
- Semi-Automatic:Operator-assisted machines bridge manual bottling and full automation for mid-scale producers. Boutique wineries across Spain's Rioja and Portugal's Douro upgrade to this tier to satisfy tightening hygiene documentation without champagne-house capital commitments.
- Manual:Hand-operated single or double-head fillers persist in micro-wineries and experimental production.
- Robotic:Vision-guided depalletizing and capping systems remain confined to top-tier installations.
Automatic technology dominates installed base. Semi-automatic is where expansion concentrates.
Packaging Type:
Material compatibility requirements and recycling mandates reshape filler architecture across container categories.
- Glass Bottle:Traditional wine packaging demands gentle handling to prevent breakage and precise neck-centering for accurate fill levels. European producers face EU Green Deal pressure to reduce bottle weight while maintaining structural integrity for high-speed filling. Sparkling formats require thicker glass for pressure containment.
- Plastic Bottle:PET and alternative polymers gain share in entry-level and outdoor consumption segments. Filler designs must accommodate thermal expansion and reduced rigidity compared to glass, with modified gripper geometries and reduced clamping forces.
- Tetra Pak:Aseptic carton formats require sterile filling environments and specialized sealing systems.
- Others:Bag-in-box, aluminum cans, and alternative formats occupy niche applications.
Glass bottles dominate installed base. Plastic formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in wine filling machinery supply chains, connecting component fabricators in southern Germany to bottling clusters along the Danube basin.
Italy
Veneto's prosecco boom and Piedmont's Barolo expansion drive gravity filler demand as protected designation volumes climb. CE marking and MDR frameworks compress replacement cycles for boutique producers upgrading from manual equipment. Verona and Alba anchor machinery procurement decisions, with regional packers aggregating fragmented winery demand.
Germany
Precision valve and servo motor supply concentrates in Bavaria and Baden-Württemberg, creating component sourcing gravity for European fabricators. EU Green Deal energy mandates force redesign of filling line heat exchangers and compressor loops. Stuttgart's automation engineering base feeds mechatronics integration into next-generation rotary systems.
France
Champagne houses in Marne demand vacuum fillers capable of sub-zero pressure-balanced filling for CO₂ retention. F-Gas Regulation phase-down accelerates hydrocarbon refrigerant adoption in bottle-cooling tunnels. Reims and Épernay clusters pioneer robotic depalletizing convergence with traditional filling architectures.
United States
California's Central Coast contract packers aggregate seasonal bottling demand from Napa and Sonoma wineries, favoring quick-changeover modular lines. FDA oversight of wine contact surfaces shapes cross-Atlantic equipment trade compliance. Sacramento Valley bulk wine terminals drive mid-capacity gravity filler installations for imported product finishing.
China
Yantai and Changli wine production zones in Shandong and Hebei provinces expand domestic bottling capacity as consumption formalizes. NMPA-equivalent hygiene documentation requirements emerge for imported equipment. Yangtze River Delta fabricators compete on manufacturing scale for Asian mid-market installations.
Wine Filling Machine Market Competitive Landscape
Concentration sits with integrated European engineering groups that span rinsing to capping architectures. The vendor base separates into three tiers: full-line system integrators commanding premium positioning, regional specialists dominating gravity filler segments, and Asian fabricants competing on manufacturing scale for emerging market volume. M&A activity clusters around automation technology tuck-ins, while strategic partnerships target aseptic licensing outside Europe.
Among Germany-based engineering groups, Krones AG and KHS GmbH exemplify full-line integration archetypes. Sidel Group represents French aseptic technology leadership for premium sparkling formats. Jiangsu Zenith Packaging occupies the scale-driven tier for Asian mid-capacity installations. These anchors illustrate how geographic origin and corporate structure map to competitive positioning without prescribing specific strategic actions or market shares.
| Leading Market Players |
|---|
| GAIotto srl |
| Fogg Filler |
| Krones AG |
| Biner Ellison |
| JBT Corporation |
| Sidel Group |
| KHS GmbH |
| Jiangsu Zenith Packaging |
| Sacmi Packaging |
| Others |
Value Network & Pricing Analysis
CE marking and MDR dual certification requirements gate supplier qualification while simultaneously stratifying price tiers across the European wine filling machine landscape, compressing procurement timelines for buyers and margin visibility for fabricators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, with premium tiers commanding substantial markups for integrated rinsing-to-capping architectures and CE-MDR bundled documentation. Price differentiation hinges on automation depth and after-sales service bundling, where full-line system integrators extract premiums against regional gravity filler specialists. Cost compression in mid-capacity segments is intensifying because stainless steel and servo motor input volatility extends quoting cycles. Boutique wineries exhibit highest price sensitivity, while contract packers prioritize quick-changeover flexibility over unit economics.
Supply Chain Analysis
Germany and Italy anchor precision component fabrication for wine filling machinery, with Bavaria and Baden-Württemberg housing servo motor and precision valve production while northern Italy clusters pump and control system manufacturing. Raw material dependencies center on food-grade stainless steel, specialized fluoropolymer seals, and high-torque servo drives. Single-source vulnerability concentrates in German precision valve suppliers, creating procurement risk for European fabricators. Distribution runs through regional distributor networks serving boutique wineries, with direct manufacturer relationships dominating contract packer procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-trained mechatronics technician scarcity constrains maintenance capacity expansion, limiting how quickly automated filling lines can scale across mid-tier winery installations and contract packing operations.
For Market Incumbents: Compound defensive positioning through captive supply of precision valve components and accelerated CE-MDR certification pipelines, insulating against emerging Asian fabricants competing on manufacturing scale. Prioritize backward integration into servo motor assembly to offset input cost volatility. For New Entrants and Emerging Players: Aftermarket service coverage gaps in India's nascent wine formalization present white-space entry points, with mid-capacity gravity filler supply underserved by established European brands. Target domestic Indian bottling operations through localized technical support partnerships rather than equipment-only sales. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down reshapes the acquisition landscape toward heat exchanger and compressor loop specialists capable of hydrocarbon refrigerant retrofit engineering. Long-term viability favors targets with established aseptic technology licensing frameworks. Monitor NMPA-equivalent documentation requirements in China as inflection signal for Asian market access premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Technology Licensing | Technology transfer partnerships unlock premium still and sparkling format access outside European supply concentration. |
| Backward Integration into Precision Valves | Captive component supply insulates German fabricators against single-source vulnerability and margin compression. |
| Robotic Depalletizing Convergence | Vision-guided systems integration establishes upgrade templates for Champagne house automation roadmaps. |
| Mobile Contract Packing Service Expansion | Third-party aggregation models concentrate procurement decisions among fewer, larger equipment buyers. |
| Hydrocarbon Refrigerant Retrofit Engineering | F-Gas compliance capabilities differentiate suppliers serving French and Italian sparkling wine cooling tunnel obligations. |
Research Methodology
Operator-level perspectives from maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads anchored the qualitative base, cross-referenced with customs and trade data, SEC filings from publicly traded packaging machinery groups, EU MDR conformity assessment databases, and industry association technical publications. Bottom-up equipment shipment tallies triangulated against top-down winery capacity expansion announcements.
Sensitivity analysis tested forecast outputs against alternative scenarios for stainless steel price trajectories and EU Green Deal implementation pacing. Segmentation modeling spanned filler architecture type, automation technology tier, end-user scale category, and regional regulatory cluster. CAGRs derived from installed base replacement cycle analysis and net capacity addition tracking across prosecco and Barolo production zones.
Underlying assumptions cover CE-MDR parallel certification timeline stability and servo motor supply continuity, with deviation risk concentrated in European component supply concentration and Indian wine sector formalization pace. Recalibration cycles align with material shifts in F-Gas Regulation enforcement and NMPA-equivalent documentation finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Japan Alcohol E-Commerce Market
Alcoholic Beverages
Germany Alcohol E-Commerce Market
Alcoholic Beverages
Asia-Pacific Craft Beer Market
Alcoholic Beverages
Cooking Wine Market
Alcoholic Beverages
Premium Wine Cooler Market
Alcoholic Beverages
North America Mezcal Market
Alcoholic Beverages
Wine Enzymes Market
Alcoholic Beverages
Wine Chocolate Market
Alcoholic Beverages
Stemware Market
Alcoholic Beverages
Japan Beer Market
Alcoholic Beverages
Ethanol Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
RTD Canned Cocktail Market
Alcoholic Beverages
Brewers Spent Grain Market
Alcoholic Beverages
Alcoholic Flavors Market
Alcoholic Beverages
North America Craft Beer Market