
 Southeast Asia Bakery Products Market | 2026-2036
Southeast Asia Bakery Products Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Bakery Products Market Analytics
Multi-source flour procurement is recalibrating cost structures for Southeast Asian bakery manufacturers. Mondelēz International leverages its regional milling partnerships to secure consistent wheat supply across Indonesian and Thai plants. PT Nippon Indosari Corpindo anchors its competitiveness through dense distribution networks spanning thousands of Indonesian convenience outlets. Yamazaki Baking differentiates via Japanese-standard quality protocols adapted for tropical climate production.
Southeast Asia bakery products comprise leavened and unleavened goods manufactured from wheat, rice, or alternative flours, with formulations adjusted for humidity tolerance and shelf stability in tropical conditions; these products serve retail, food service, and institutional channels requiring standardized portion control and consistent sensory profiles. Bread dominates volume as a daily staple across Philippine and Indonesian households, while pastries capture expanding margin pools in Vietnamese and Thai urban centers where premium positioning commands price premiums. The food service segment channels growing demand as hotel chains and quick-service operators centralize bakery procurement through contracted suppliers rather than artisanal sources.
Indonesia's BPOM, Thailand's FDA, and Vietnam's VFA enforce divergent additive and labeling standards that fragment compliance costs for multi-country operators. ASEAN harmonization efforts on food safety standards remain incomplete, forcing manufacturers to maintain country-specific formulation variants. Stakeholders must monitor regulatory convergence timelines and pre-position flexible production lines capable of rapid reformulation shifts.
Market Dynamics
Food service procurement centralization is restructuring Southeast Asian bakery demand as hotel chains and quick-service restaurants abandon fragmented artisanal sourcing for contracted supply agreements with industrial-scale manufacturers.
Growth Catalysts
- Urban retail modernization:Greater Jakarta and Surabaya witness accelerated modern trade penetration, expanding branded bakery shelf space and cold-chain distribution reach into convenience networks.
- ASEAN food service expansion:Thailand's tourism recovery and Vietnam's hospitality investment surge drive centralized bakery procurement from standardized suppliers rather than traditional bakeries.
- Tropical formulation adaptation:Enzyme-based shelf-life extension technologies enable ambient distribution without refrigeration, unlocking rural penetration previously blocked by climate constraints.
Market Restraints
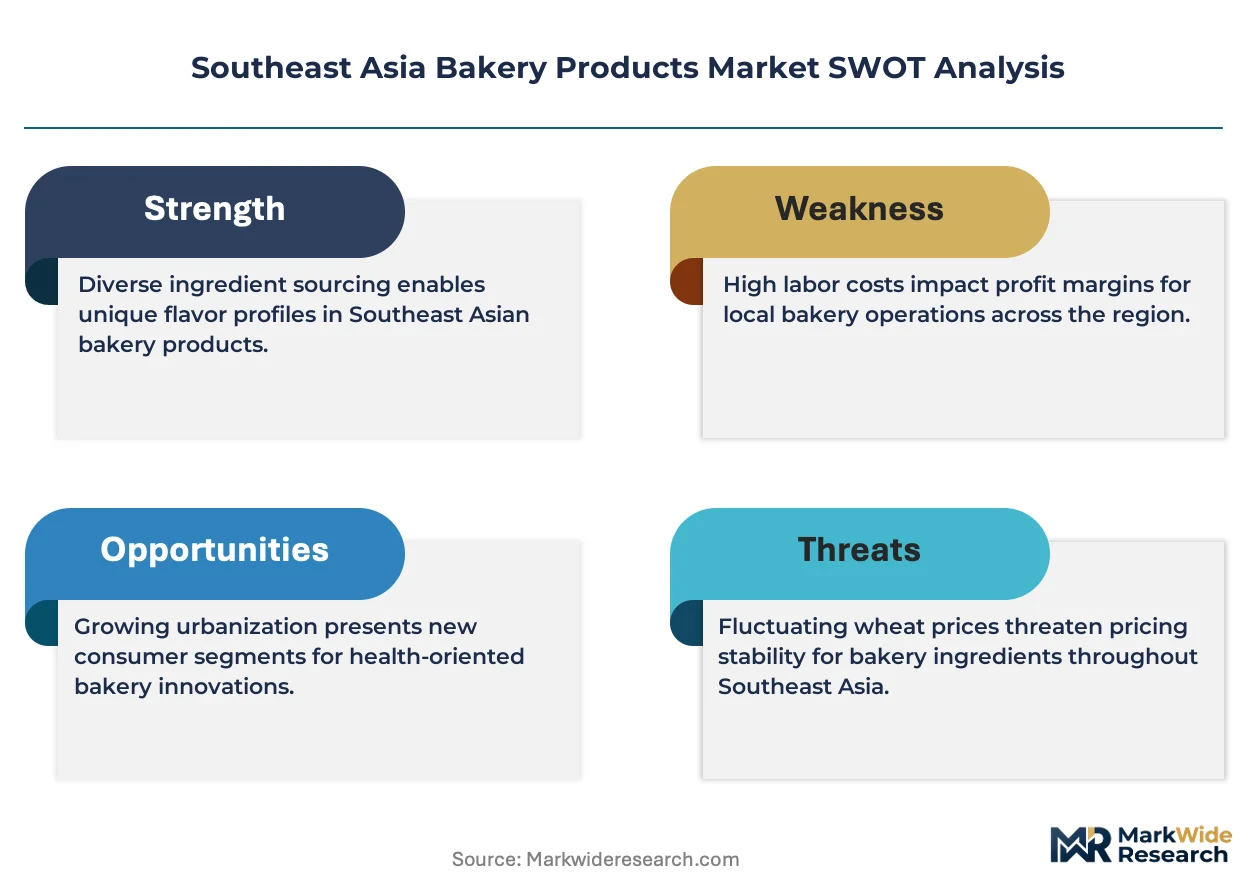
- Wheat import dependency:Indonesia and the Philippines rely on Australian and Black Sea wheat, exposing margins to currency volatility and maritime freight cost spikes.
- Regulatory fragmentation:Divergent additive approval lists between BPOM, Thailand FDA, and Vietnam VFA force manufacturers to maintain parallel formulation inventories.
- Artisanal substitution resilience:Traditional neighborhood bakeries retain price-sensitive consumers through zero-overhead home-based production and unbranded freshness claims.
Strategic Opportunities
- Central Vietnamese corridor:Da Nang and Hue present underpenetrated modern retail landscapes where first-mover branded distribution can preempt local artisanal loyalty.
- Plant-based ingredient convergence:Egg replacement systems combined with oat protein fortification address emerging flexitarian demand in Bangkok and Singapore expatriate segments.
- Halal certification arbitrage:MUI and JAKIM dual certification opens simultaneous access to Indonesian domestic and Malaysian export channels with minimal incremental compliance cost.
Industry Challenges
- Climate-controlled logistics capex:Maintaining product integrity across archipelagic supply chains requires substantial investment in refrigerated fleet expansion and humidity-monitoring infrastructure.
- Food safety auditor scarcity:BPOM-registered inspectors face capacity constraints, extending facility certification timelines and delaying new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Bakery Products Market |
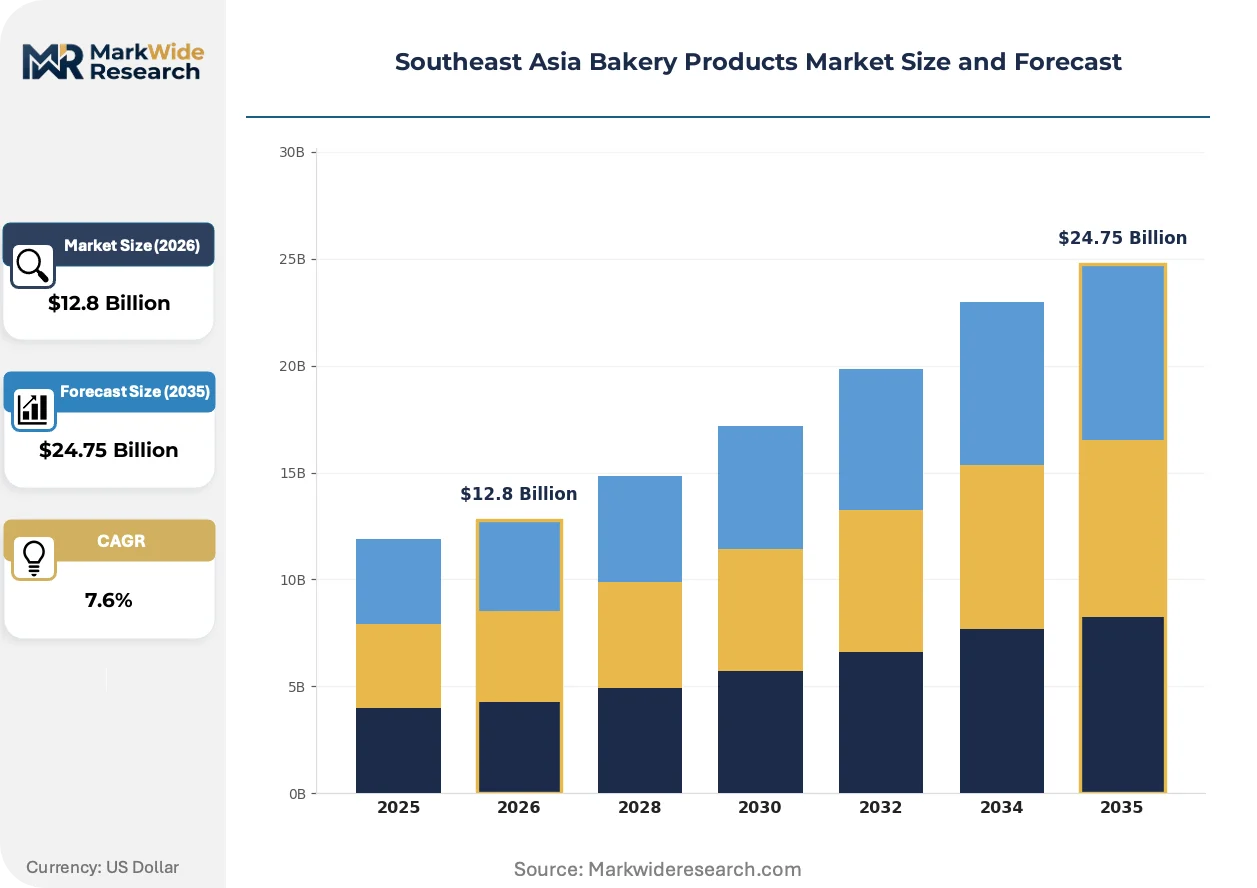
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $24.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread, Pastries, Cakes, Cookies Consumer Type: Retail Customers, Food Service, Wholesalers, Bakeries Packaging Type: Boxes, Bags, Trays, Wrap Sales Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores |
| Companies Covered | Mondelēz International, SPC Group, PT Nippon Indosari Corpindo, Yamazaki Baking, Universal Robina Corporation, QAF Limited, Mayora Indah, Mighty Bakery, President Bakery Public Company Limited, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Bakery Products Market Evolving Landscape
Automation and clean-label reformulation are converging to redefine production economics and consumer positioning across Southeast Asian bakery manufacturing, compressing legacy cost structures while opening premium price tiers.
Retort-stable laminated dough technology is overtaking frozen distribution in Philippine and Indonesian food service channels. Hotel procurement departments adopt ambient-storage pastries to eliminate freezer capex and simplify inventory rotation. This compression of cold-chain dependency is overtaking traditional frozen supply contracts and enabling direct-to-kitchen delivery models previously uneconomical at tropical ambient temperatures.
Thailand FDA's revised nutrition labeling mandate now requires front-of-pack sugar disclosure for bakery products exceeding specified thresholds. Manufacturers reformulate using stevia and monk fruit blends to avoid visual warning labels that depress impulse purchases. Premium-positioned brands in Bangkok and Chiang Mai accelerate clean-label launches ahead of enforcement deadlines to capture health-conscious urban consumers.
Quick-service restaurant chains consolidate supplier relationships from multi-vendor artisanal sourcing to single-source national contracts. Centralized procurement teams at Philippine and Indonesian burger and coffee chains now specify sensory consistency metrics and quarterly audit requirements. This concentration is most visible in Metro Manila, where three national bakery suppliers now capture majority share of chain restaurant bread and pastry procurement previously fragmented across hundreds of local bakeries.
Southeast Asia Bakery Products Market Segmentation
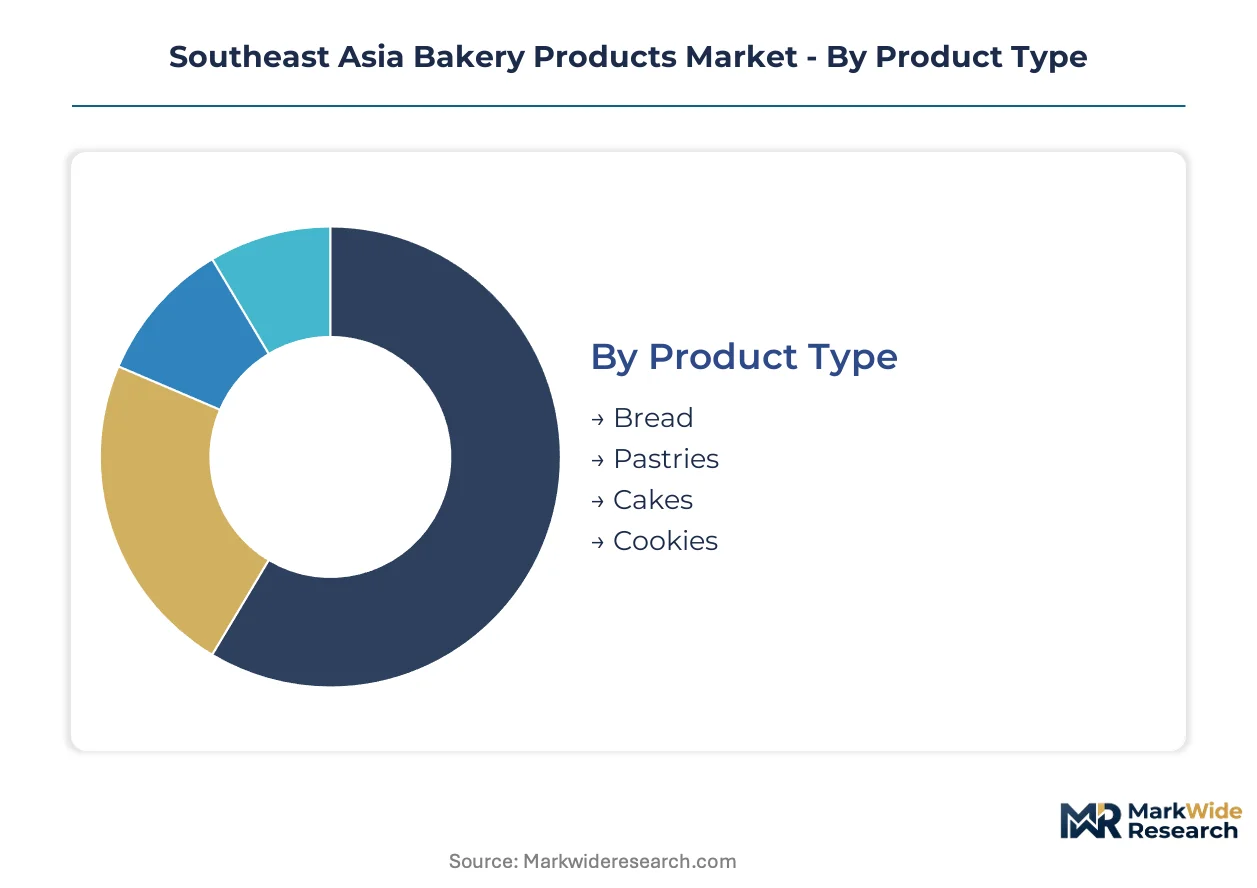
Southeast Asian bakery manufacturers calibrate production lines and distribution investments against four distinct segmentation axes. Product type dictates flour procurement and shelf-life engineering, while consumer type determines packaging format and delivery cadence. Packaging and channel choices further fragment as modern retail penetration diverges across Indonesian, Thai, and Vietnamese urban corridors.
Product Type:
Bread anchors volume throughput across Indonesian and Philippine plants, while pastries command premium positioning in Thai and Vietnamese urban centers where hotel procurement concentrates.
- Bread:Leavened wheat and rice-flour formulations dominate daily household consumption across Greater Jakarta and Metro Manila. Industrial-scale manufacturers supply standardized loaves to quick-service restaurant chains through national distribution contracts.
- Pastries:Laminated dough products with tropical-stabilized fat systems capture expanding food service procurement from Bangkok and Ho Chi Minh City hotel operators. Retort-stable variants eliminate cold-chain dependency for archipelagic logistics.
- Cakes:Celebration and portion-controlled formats serve institutional and retail channels with moisture-retention formulations adapted for ambient humidity.
- Cookies:Crisp-texture products with extended shelf stability penetrate rural convenience networks through low-unit-price packaging configurations.
Today's leader: Bread. Tomorrow's challenger: Pastries.
Consumer Type:
Food service procurement centralization is displacing fragmented artisanal sourcing, while retail customers drive branded product uptake through modern trade expansion.
- Retail Customers:Urban households in Surabaya and Da Nang purchase branded packaged bakery through supermarket and convenience store networks. Clean-label and reduced-sugar variants attract health-conscious segments ahead of Thailand FDA nutrition labeling enforcement.
- Food Service:Hotel chains and quick-service restaurants in Metro Manila and Bangkok consolidate supplier relationships toward single-source national contracts with sensory consistency requirements and quarterly audit protocols.
- Wholesalers:Regional distributors aggregate volume for secondary city penetration across the Philippine archipelago and Indonesian outer islands.
- Bakeries:Independent operators retain price-sensitive consumers through zero-overhead production and unbranded freshness positioning in neighborhood trade areas.
Food service contracts are concentrating fastest; artisanal bakeries defend share through cost position.
Packaging Type:
Format selection balances shelf-life extension against material cost and retail display requirements across humid tropical distribution.
- Boxes:Rigid paperboard formats protect premium pastries and cakes for gift and hotel channel presentation.
- Bags:Flexible polymer and paper laminates dominate bread and cookie distribution through high-velocity convenience retail.
- Trays:Thermoformed and pressed-pulp containers organize multi-unit bakery assortments for supermarket shelf display.
- Wrap:Film and wax-paper enclosures provide cost-minimized single-serve portioning for price-sensitive rural penetration.
Bags capture the highest unit volume; boxes secure the premium margin tier.
Sales Channel:
Channel strategy diverges between cold-chain-dependent fresh formats and ambient-stable products engineered for archipelagic reach.
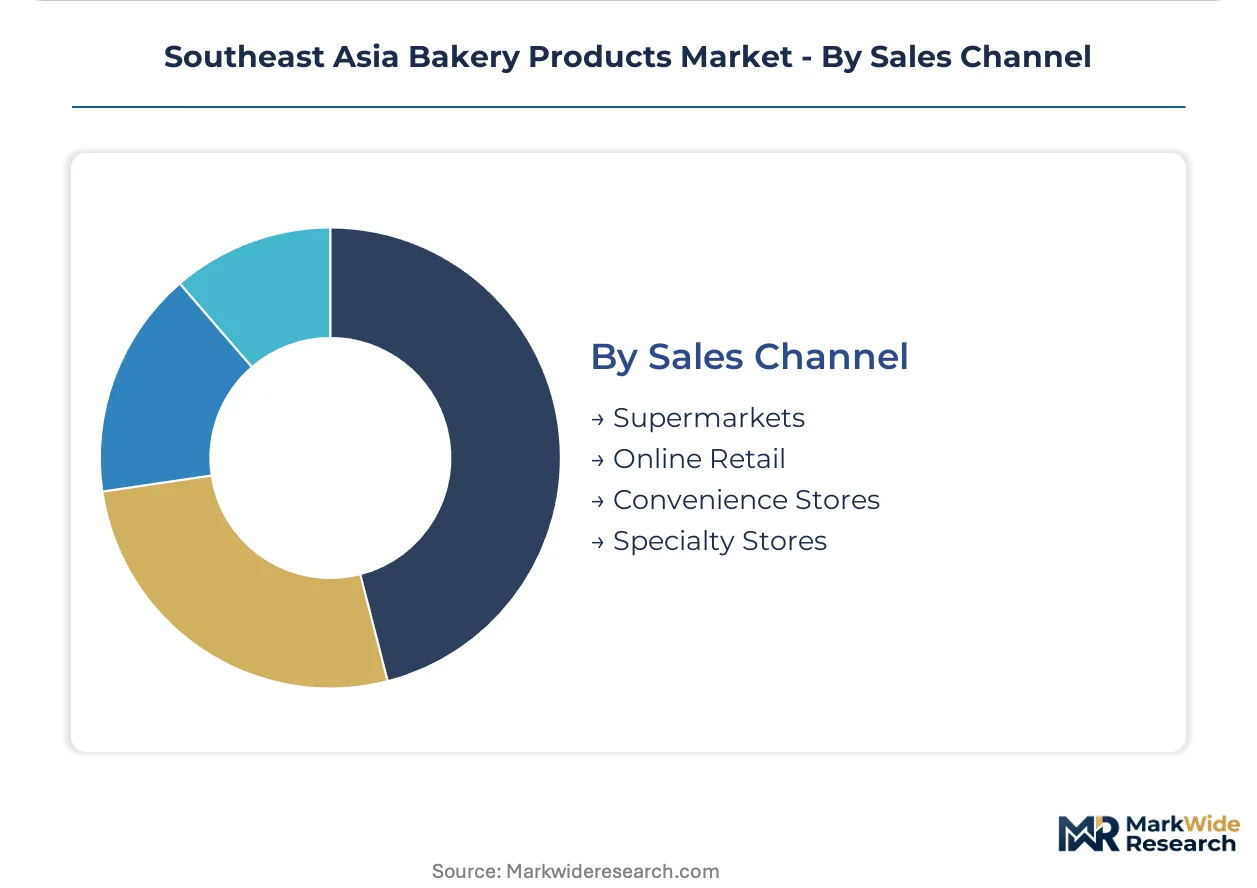
- Supermarkets:Modern trade outlets in Greater Jakarta and Bangkok allocate expanding shelf space to branded bakery with promotional calendar coordination.
- Online Retail:E-commerce platforms aggregate subscription and bulk purchases in Singapore and Kuala Lumpur expatriate segments with delivery-scheduling flexibility.
- Convenience Stores:Dense outlet networks across Indonesian urban corridors and Philippine barangay-level trade stock single-serve bread and pastry for immediate consumption.
- Specialty Stores:Premium bakery boutiques in Ho Chi Minh City and Chiang Mai emphasize artisanal positioning and customized celebration cake services.
Convenience stores drive volume density; specialty stores extract margin through experience differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Jakarta anchors bakery demand concentration across Southeast Asia, with Surabaya and Bangkok forming secondary production clusters. Modern retail penetration and food service procurement centralization drive divergent growth trajectories across national markets.
Indonesia
Urban corridor expansion in Greater Jakarta and Surabaya accelerates branded bakery uptake through convenience store densification. BPOM enforces additive traceability mandates that elevate compliance costs for multi-plant operators. Bandung's manufacturing belt hosts industrial-scale facilities supplying national quick-service restaurant contracts.
Thailand
Tourism recovery and hospitality investment surge drive centralized bakery procurement from standardized suppliers. Thailand FDA's revised nutrition labeling mandate requires front-of-pack sugar disclosure, forcing reformulation with stevia and monk fruit blends. Bangkok's industrial estates concentrate production capacity serving hotel chains and retail networks.
Vietnam
Ho Chi Minh City and Da Nang present underpenetrated modern retail landscapes where first-mover distribution can preempt artisanal loyalty. Vietnam VFA maintains divergent additive approval lists that fragment compliance costs for regional operators. The Central Vietnamese corridor around Hue shows emerging food service procurement concentration.
Philippines
Metro Manila's quick-service restaurant chains consolidate supplier relationships toward single-source national contracts with sensory consistency requirements. Wheat import dependency from Australian and Black Sea sources exposes margins to currency volatility. Cebu and Davao secondary cities drive volume through wholesale distributor networks.
Singapore
Expatriate segments and premium retail channels sustain demand for plant-based ingredient convergence and clean-label positioning. The city-state's regulatory alignment with international standards enables regional headquarters functions for multi-country operators. Jurong's logistics infrastructure supports ambient-stable distribution across archipelagic supply chains.
Southeast Asia Bakery Products Market Competitive Landscape
Global majors compete with regional champions across distribution density and tropical formulation expertise. The market structure shows moderate consolidation with tiered competition between multinational CPG conglomerates and domestic specialists. Three archetypes dominate: global scale players leveraging regional milling partnerships, dense distribution network operators anchoring convenience retail penetration, and Japanese-standard quality protocol specialists. Competitive moves concentrate on M&A for route-to-market expansion and strategic partnerships for wheat supply security.
Within the global scale tier, Mondelēz International occupies a position exemplifying regional milling integration, while PT Nippon Indosari Corpindo anchors the dense distribution archetype across Indonesian convenience networks. Yamazaki Baking represents the quality protocol specialist segment with tropical-adapted production standards. These three entities collectively illustrate the competitive vectors shaping procurement consolidation and shelf-space allocation across Southeast Asian markets.
| Leading Market Players |
|---|
| Mondelēz International |
| SPC Group |
| PT Nippon Indosari Corpindo |
| Yamazaki Baking |
| Universal Robina Corporation |
| QAF Limited |
| Mayora Indah |
| Mighty Bakery |
| President Bakery Public Company Limited |
| Others |
Value Network & Pricing Analysis
Food service procurement consolidation across Metro Manila and Bangkok is compressing supplier margins and forcing industrial-scale manufacturers to absorb wheat cost volatility or lose national contract eligibility. This buyer-side concentration is reshaping how supply chains source flour and distribute finished goods across archipelagic markets.
Pricing Analysis
Wheat import cost pass-through dominates pricing structures across Indonesian and Philippine manufacturing. Three-tier pricing structure across premium, standard, and economy levels separates hotel procurement contracts from convenience retail and traditional bakery channels. Price differentiation hinges on halal certification tier and volume scale commitments. Cost compression in the economy tier is intensifying because artisanal competitors operate with zero facility overhead. Quick-service restaurant chains show least price sensitivity due to standardized national sourcing mandates.
Supply Chain Analysis
Single-source vulnerability sits with Australian and Black Sea wheat suppliers that feed Indonesian and Philippine milling operations. Raw material dependencies center on imported wheat, tropical-stabilized fat systems, and enzyme-based shelf-life extenders. Supply chain risk manifests as currency volatility exposure on wheat purchases denominated in USD. Distribution runs through refrigerated fleet networks and humidity-monitoring infrastructure serving convenience store densification in Greater Jakarta and Surabaya.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in reformulation cost-down and premium pastry tier capture as food service procurement consolidates. Tropical formulation adaptation and clean-label positioning enable simultaneous cost reduction and price premium extraction.
For Market Incumbents: Acquire refrigerated logistics assets to lock in archipelagic distribution coverage before regional competitors scale. Secure backward integration into regional milling partnerships to hedge wheat import volatility threatening contract bakery margins. Defend against artisanal substitution by deploying ambient-stable retort technology that eliminates cold-chain dependency for rural penetration. For New Entrants and Emerging Players: Thailand FDA's revised nutrition labeling mandate opens a window for stevia-monk fruit reformulation specialists to capture health-conscious urban segments ahead of enforcement deadlines. Target the Central Vietnamese corridor around Da Nang and Hue where modern retail underpenetration allows first-mover branded distribution to preempt artisanal loyalty. Pursue direct-to-kitchen delivery models bypassing traditional wholesale layers. For Investors and Strategic Acquirers: Asymmetric upside sits with dense distribution network operators anchoring Indonesian convenience retail penetration. Five-to-ten year viability favors manufacturers with dual MUI-JAKIM halal certification enabling simultaneous Indonesian domestic and Malaysian export channel access. Monitor ASEAN food safety harmonization timelines as the inflection signal for multi-country formulation standardization plays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regional Milling | Captive wheat supply secures margin stability against Australian and Black Sea price volatility. |
| Halal Certification Dual-Stacking | MUI and JAKIM dual certification unlocks Indonesian-Malaysian cross-border revenue with minimal compliance increment. |
| Ambient-Stable Product Line Expansion | Retort-stable laminated dough eliminates refrigerated fleet capex for archipelagic reach. |
| Clean-Label Reformulation Investment | Stevia-monk fruit blends preempt Thailand FDA sugar disclosure mandates depressing impulse purchases. |
| Food Service National Contract Consolidation | Single-source agreements with Philippine and Indonesian quick-service chains displace fragmented artisanal sourcing. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured plant managers at Indonesian and Thai industrial bakery facilities, procurement leads at Metro Manila quick-service restaurant chains, and category buyers at Jakarta modern retail networks. Secondary validation drew from BPOM additive approval registers, Thailand FDA nutrition labeling directives, Vietnam VFA regulatory filings, and ASEAN trade customs records. Bottom-up volume builds across product type and channel segments were cross-checked against top-down market sizing.
Comparable-period anchoring established baseline consumption patterns before projecting trajectory shifts across the analysis window. Segmentation modeling incorporated product type, consumer channel, packaging format, and regional regulatory cluster dimensions. CAGRs were derived from growth rate convergence analysis applied to wheat import volume trends, modern retail penetration curves, and food service procurement centralization rates. Tropical climate adaptation technology diffusion and halal certification uptake curves informed scenario weighting.
Revisions become necessary when ASEAN regulatory harmonization accelerates, wheat sourcing patterns shift from Australian to alternative origins, or artisanal bakery consolidation unexpectedly alters competitive dynamics. Forecasts reflect documented assumptions about convenience store densification rates and tourism recovery trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Specialty Frozen Bakery Market
Bakery Products
Organic Frozen Bakery Market
Bakery Products
Bakers Yeast Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Toasted Flour Market
Bakery Products
Low Calorie Bread Market
Bakery Products
Cookies Market
Bakery Products
Low Calorie Cake Market
Bakery Products
Low Calorie Rice Cake Market
Bakery Products
Fortified Bakery Market
Bakery Products
Pie Shells Market
Bakery Products
Oman Frozen Bakery Products Market
Bakery Products
Specula Market
Bakery Products
Bakery Flavors Market
Bakery Products
Bakery Fillings Market
Bakery Products
Tunnel Bakery Oven Market