
 Train Catering Service Market | 2026-2036
Train Catering Service Market Size, Share, and Industry Trends Forecast 2026-2036
Train Catering Service Market Insights
Modular meal bundling is recalibrating passenger choice architecture across premium and economy rail classes. Deutsche Bahn AG leverages its ICE onboard kitchens to sustain hot-meal differentiation on cross-border routes. IRCTC Limited anchors India's vast network through centralized commissary production and digital pre-ordering infrastructure. Compass Group competes via multi-rail contracts that span station retail, lounge catering, and onboard service under unified procurement.
Train catering services encompass the preparation, packaging, and delivery of food and beverages consumed during rail journeys, typically involving chilled-chain logistics, microwave-regeneration protocols, and tray-set configurations designed for seat-back or table service. The primary commercial purpose is to convert dwell time into ancillary revenue while meeting passenger nutritional needs across variable journey durations. In-train dining commands the highest margin pool where full kitchen galley equipment permits à la carte preparation, while meal pre-packaging dominates volume throughput on high-frequency commuter and intercity corridors. Vegan options within food type segmentation are expanding fastest as rail operators respond to dietary diversity mandates and sustainability procurement criteria.
The EU F-Gas Regulation and REACH compliance standards govern refrigerant use and food-contact materials in European rail catering supply chains, directly affecting equipment replacement cycles and packaging specifications. India's FSSAI licensing requirements and China's SAMR food safety protocols impose parallel compliance burdens on commissary operators serving cross-border routes. Stakeholders must monitor how divergent national food safety audits and emerging carbon-labeling obligations will reshape supplier qualification criteria and cross-border kitchen certification costs.
Market Dynamics
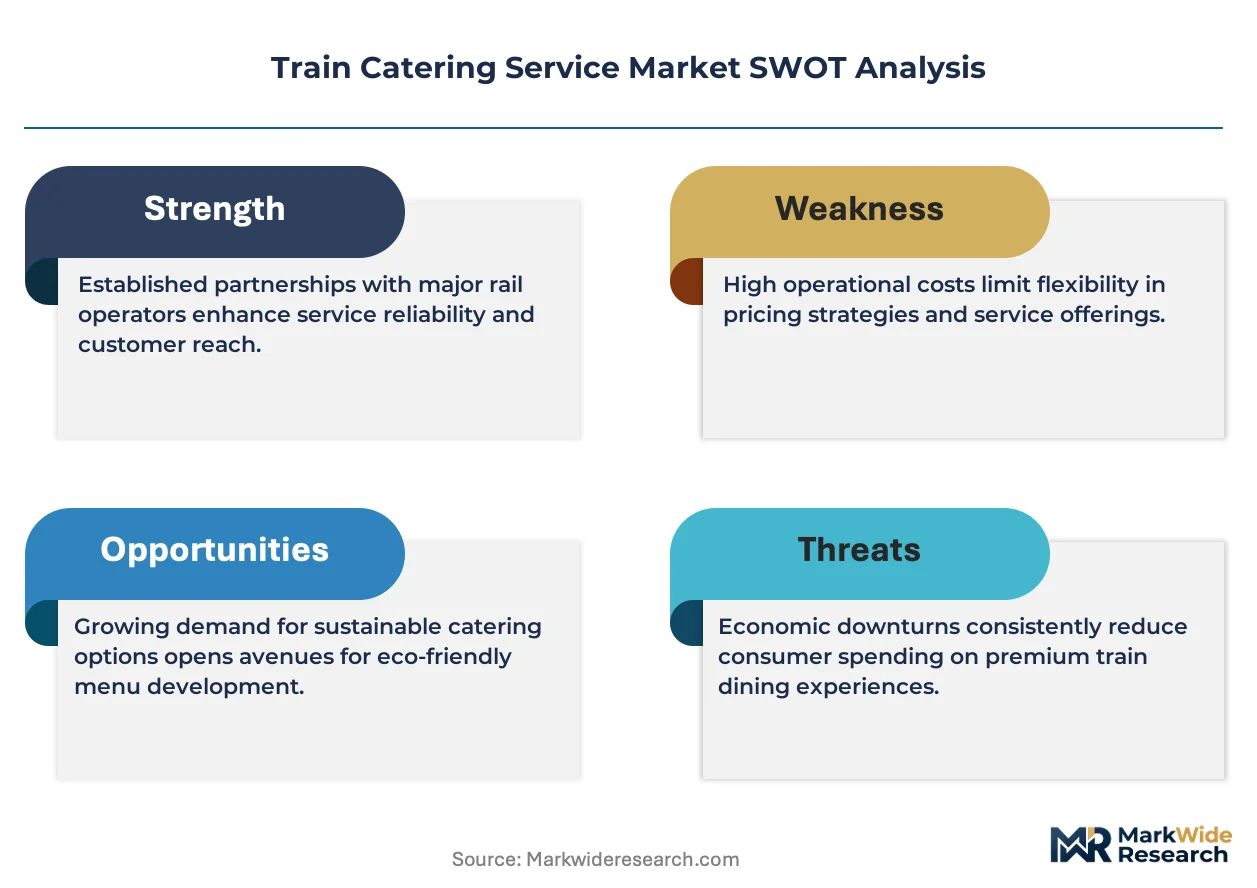
Digital pre-ordering infrastructure is restructuring how rail operators convert passenger dwell time into ancillary revenue, compressing traditional onboard inventory models while expanding commissary production scale. This shift concentrates procurement decisions into centralized platforms that bypass legacy galley-based service hierarchies.
Growth Catalysts
- IRCTC e-catering platform:India's centralized digital ordering system aggregates restaurant supply into rail stations, expanding meal accessibility beyond traditional pantry car limitations.
- EU Single European Railway Area:Technical standardization across member states enables cross-border catering contracts and unified kitchen certification protocols.
- High-speed rail corridor density:China's Beijing-Shanghai route generates concentrated passenger volumes that justify dedicated commissary investments and premium meal program economics.
Market Restraints
- EU F-Gas Regulation:Refrigerant phase-down mandates accelerate equipment replacement cycles in European rail kitchens, elevating capital intensity for cross-border operators.
- Commissary supply concentration:Chilled-chain logistics depend on limited regional cold storage infrastructure, creating vulnerability in secondary rail corridors.
- Microwave-regeneration protocols:Hot-meal quality ceiling in economy segments constrains price elasticity and margin expansion on high-frequency routes.
Strategic Opportunities
- Vegan meal expansion:Dietary diversity mandates in European procurement criteria open supplier slots for plant-based commissary operators.
- Carbon-labeling integration:Emerging sustainability disclosure requirements create first-mover advantage for operators with verified supply chain emissions data.
- Station-lounge convergence:Unified catering contracts spanning platform retail and onboard service consolidate procurement under single vendor relationships.
Industry Challenges
- FSSAI-SAMR audit divergence:India's food safety licensing and China's market regulator protocols impose conflicting documentation burdens on cross-border kitchen operators.
- Galley equipment standardization:Legacy train configurations lack compatibility with modern regeneration systems, forcing route-specific equipment procurement.
- REACH compliance timeline:Food-contact material certification delays in European supply chains extend supplier qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Train Catering Service Market |
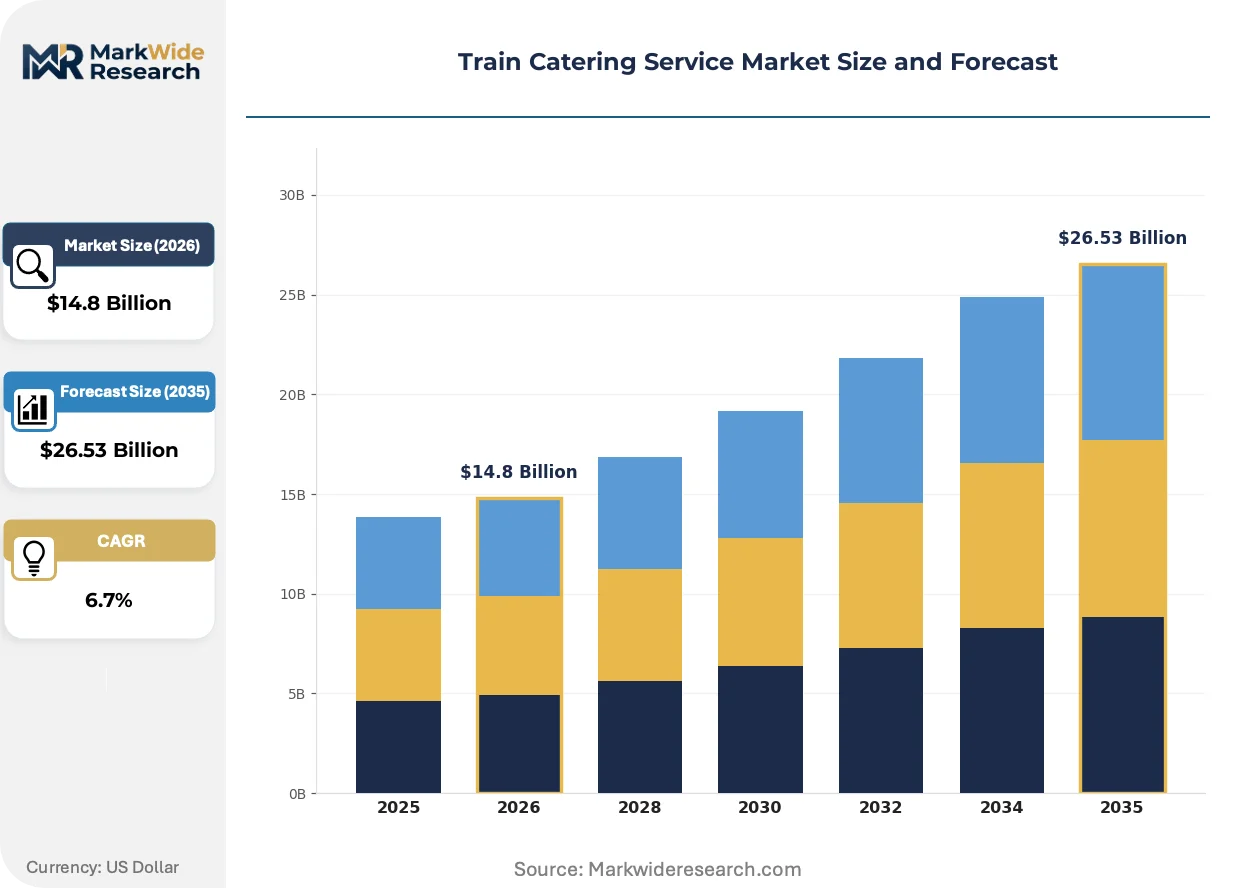
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: In-Train Dining, Refreshment Cart, Meal Pre-packaging, Beverage Services End User: Passengers, Rail Operators, Event Organizers, Travel Agencies Food Type: Vegan Options, Gourmet Meals, Snacks, Traditional Cuisine Delivery Mode: On-Board Service, Pre-Ordered Delivery, Self-Service, Direct Purchase |
| Companies Covered | LSG Sky Chefs, Deutsche Bahn AG, Compass Group, Trenitalia, Eurostar, IRCTC Limited, Elior Group, Gate Gourmet, Newrest Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Train Catering Service Market Trends and Innovations
Chilled-chain logistics is converging with digital inventory management to reshape how rail operators balance meal freshness against waste minimization. This convergence compresses the traditional trade-off between pre-packaged volume and à la carte quality.
Blockchain-enabled traceability is converging with supplier certification databases. Deutsche Bahn and JR East now pilot immutable ledger systems for allergen tracking. This technology convergence is compressing liability exposure while accelerating audit response times for cross-border routes.
REACH and the EU F-Gas Regulation are tightening material and equipment specifications simultaneously. Food-contact substance restrictions now overlap with refrigerant phase-down mandates, forcing coordinated kitchen retrofit programs. European operators face the steepest compliance burden, with commissary suppliers consolidating to spread certification costs across larger contract volumes.
Rail passengers increasingly pre-order meals through operator apps rather than purchasing spontaneously onboard. This behavioral shift concentrates demand forecasting accuracy requirements into digital platform operators, displacing traditional galley inventory risk onto centralized commissaries. Japan and India exhibit the most advanced adoption, where mobile penetration and long-distance ridership overlap.
Train Catering Service Market Segmentation
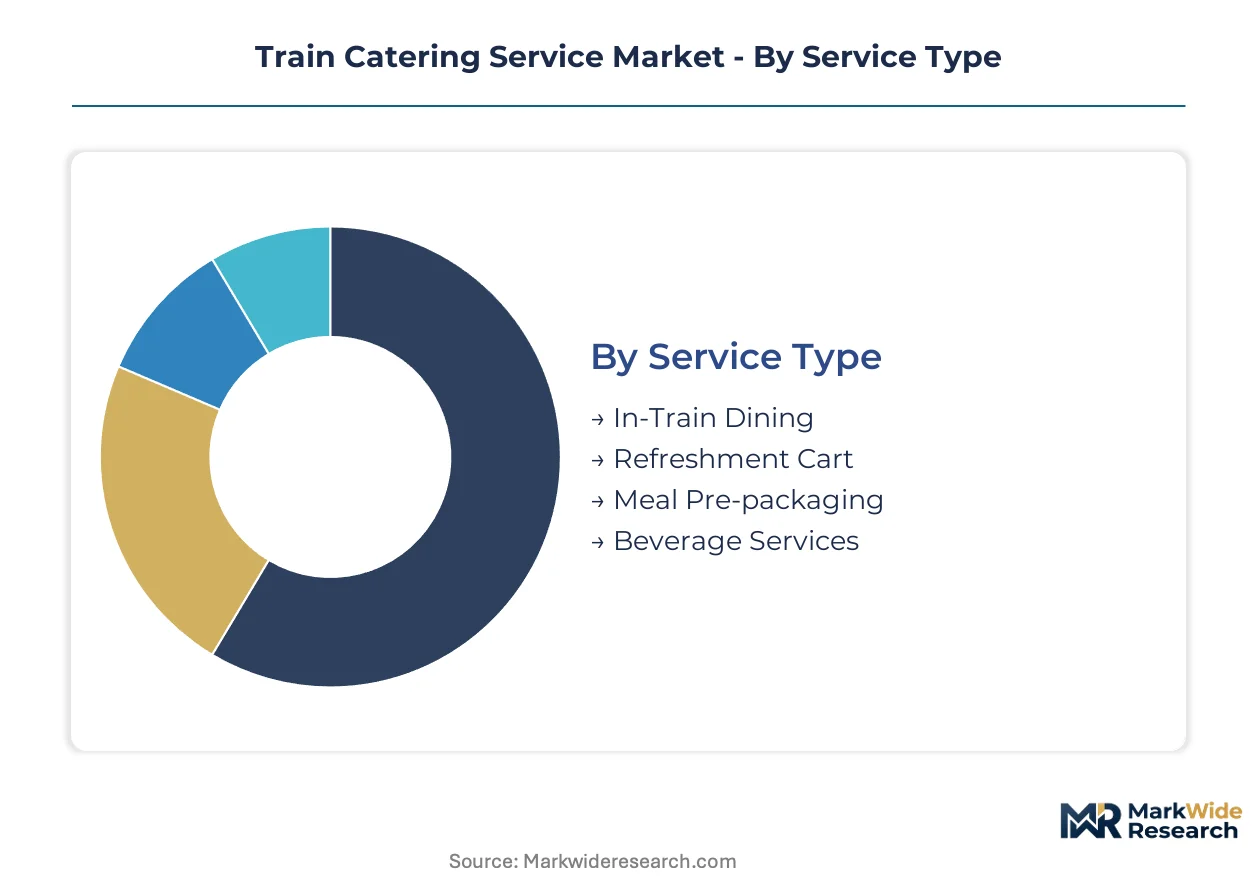
Segmentation in train catering services determines equipment procurement, commissary licensing requirements, and margin structures across rail networks. Each category carries distinct regulatory burdens and operational constraints that shape supplier qualification and contract economics.
Service Type:
REACH compliance for food-contact materials and F-Gas Regulation mandates for refrigeration equipment apply differentially across service formats, with full kitchen operations facing the steepest certification requirements.
- In-Train Dining:Full galley kitchens with à la carte preparation capability command premium pricing on long-distance routes. Deutsche Bahn AG deploys ICE onboard kitchens to sustain hot-meal differentiation across cross-border corridors where ECHA material standards and refrigerant phase-down rules concentrate compliance costs.
- Meal Pre-packaging:Centralized commissary production with chilled-chain logistics dominates high-frequency corridors. China's Beijing-Shanghai high-speed rail corridor generates concentrated volumes that justify dedicated cold storage infrastructure and SAMR-compliant packaging protocols.
- Refreshment Cart:Mobile trolley service with limited heating capability serves regional and commuter segments. India's IRCTC platform aggregates mobile cart operations alongside digital ordering to extend service reach beyond pantry car constraints.
- Beverage Services:Hot and cold drink distribution through dedicated dispensers or cart service. EU F-Gas Regulation governs cooling equipment specifications for chilled beverage systems across member state networks.
Meal Pre-packaging sits at the top of the volume ranking, with In-Train Dining climbing the fastest as premium rail experiences expand.
End User:
Cost tier differentiation separates procurement approaches, with direct rail operator contracts commanding scale economies that individual passenger transactions cannot match.
- Rail Operators:Long-term catering contracts spanning multiple routes and service classes. Compass Group secures multi-rail agreements covering station retail, lounge catering, and onboard service under unified procurement frameworks with centralized vendor management.
- Passengers:Individual meal purchases through onboard service or digital pre-ordering platforms. JR East and Indian Railways lead mobile penetration where app-based ordering concentrates demand forecasting into platform operators.
- Event Organizers:Charter train and special service catering with customized menu requirements. Seasonal demand peaks around cultural festivals and sporting events create temporary capacity pressures on regional commissaries.
- Travel Agencies:Packaged tour operations with pre-arranged meal inclusions. Cross-border European tour operators leverage EU Single European Railway Area technical standards to streamline multi-country catering arrangements.
Rail Operators anchor procurement volume, with Travel Agencies expanding most quickly as packaged rail tourism recovers.
Food Type:
Application context drives preparation protocols, with dietary diversity mandates reshaping procurement criteria across European and Asian networks.
- Vegan Options:Plant-based menus requiring segregated preparation lines and allergen controls. European procurement criteria increasingly mandate vegan availability, opening supplier slots for specialized commissary operators with verified sustainability credentials.
- Gourmet Meals:Chef-designed menus with premium ingredients and presentation standards. Japan's Shinkansen dining programs and European sleeper train services sustain margin pools through culinary differentiation on extended journeys.
- Snacks:Pre-packaged items with extended shelf life for impulse purchase. High-frequency commuter routes depend on snack throughput to maximize revenue per passenger kilometer without galley infrastructure.
- Traditional Cuisine:Region-specific menus reflecting local culinary heritage. India's IRCTC platform aggregates restaurant partners to deliver regional specialties at station stops, bypassing onboard kitchen limitations.
Traditional Cuisine holds volume leadership, with Vegan Options gaining share fastest as sustainability procurement criteria tighten.
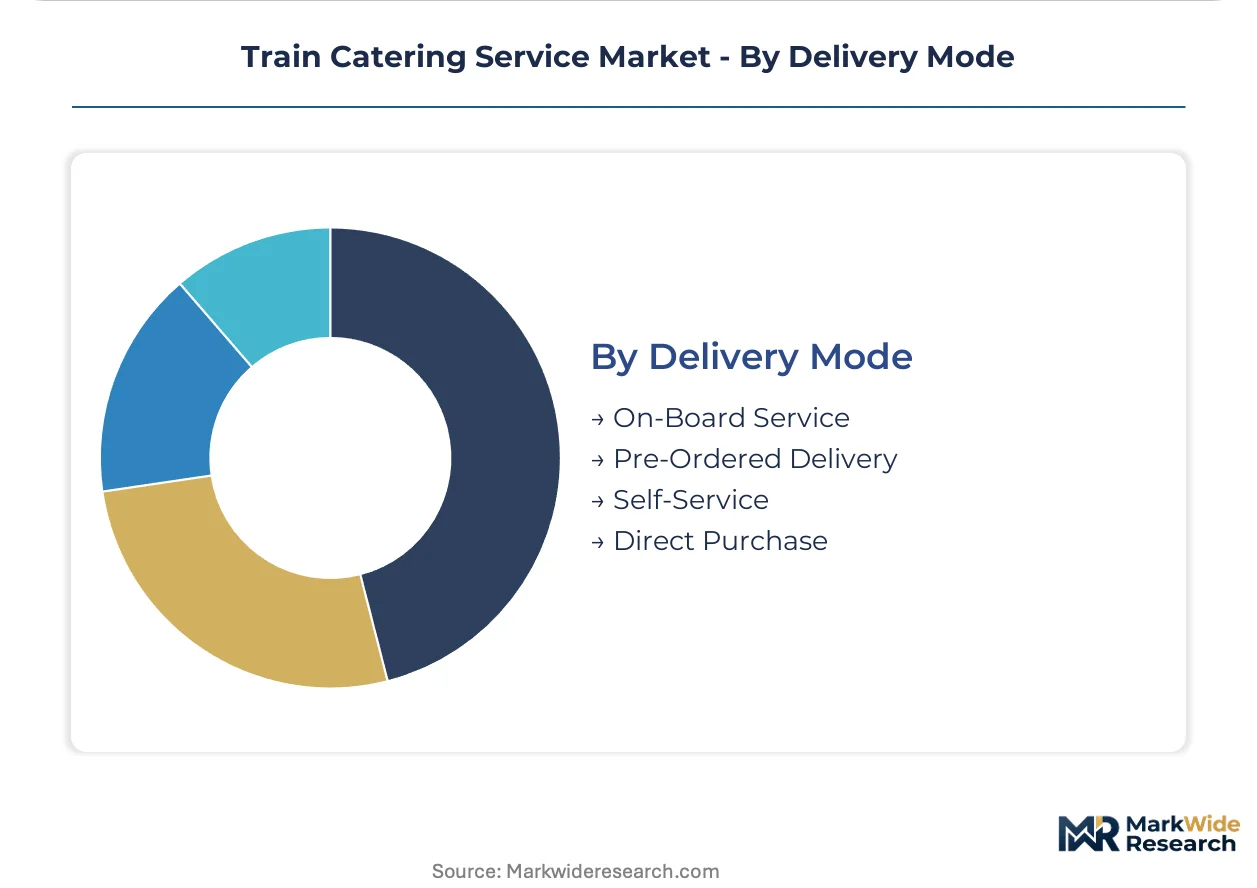
Delivery Mode:
Customer interaction models determine inventory risk placement, with digital platforms displacing spontaneous onboard purchasing.
- Pre-Ordered Delivery:Digital platform orders fulfilled at seat or station pickup. India's e-catering infrastructure and Japan's mobile penetration demonstrate the most advanced adoption, compressing traditional galley inventory models.
- On-Board Service:Attendant-served meals from galley or cart. Full-service dining retains premium positioning on long-distance routes where dwell time conversion justifies labor-intensive service models.
- Self-Service:Passenger collection from designated points within train or station. Grab-and-go formats reduce service labor while maintaining chilled-chain integrity through controlled access points.
- Direct Purchase:Unplanned transactions at station retail or onboard carts. Spontaneous purchasing declines as pre-ordering platforms capture demand upstream of the journey.
On-Board Service maintains volume dominance, with Pre-Ordered Delivery showing the steepest expansion trajectory as rail operators invest in digital infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Train catering services originated in nineteenth-century Europe and North America, where railway dining cars established the operational template for mobile food service. The industry scaled through colonial rail networks and post-war nationalization programs before fragmenting into regional procurement models.
Germany
Deutsche Bahn AG operates ICE onboard kitchens across cross-border corridors into France, Switzerland, and Austria. The EU F-Gas Regulation and REACH compliance standards govern refrigerant use and food-contact materials, elevating equipment replacement costs. Berlin and Munich anchor commissary production clusters serving high-frequency domestic and international routes.
India
IRCTC Limited manages centralized digital ordering infrastructure aggregating restaurant supply into rail stations nationwide. FSSAI licensing requirements impose documentation burdens on kitchen operators serving interstate routes. The Delhi-Mumbai and Delhi-Kolkata corridors concentrate commissary investments where passenger volumes justify dedicated cold storage facilities.
Japan
JR East and JR Central deploy mobile pre-ordering platforms with advanced penetration rates on Shinkansen routes. METI guidelines and JIS standards shape equipment procurement and food safety protocols. The Tokyo-Osaka corridor generates concentrated premium meal program economics through bento box and ekiben traditions.
China
SAMR food safety protocols and dual carbon goals govern commissary operations on high-speed rail networks. The Beijing-Shanghai corridor commands disproportionate revenue per passenger kilometer, justifying dedicated kitchen infrastructure. Shanghai and Beijing anchor supplier qualification programs for cross-border routes into neighboring jurisdictions.
United Kingdom
Eurostar and domestic operators balance onboard service with station retail convergence under post-Brexit procurement frameworks. ECHA material standards apply to cross-Channel operations, while domestic routes follow Food Standards Agency protocols. London anchors multi-rail catering contracts spanning terminal lounges and onboard dining.
Train Catering Service Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service differentiation, with full galley kitchens commanding pricing power on long-distance routes while pre-packaged meal operators compete on volume throughput. The vendor base concentrates around three strategic archetypes: integrated rail operators with captive catering divisions, multi-service contractors spanning station and onboard environments, and specialized commissary suppliers focused on chilled-chain production. M&A activity targets digital platform capabilities and cross-border kitchen certifications, while capacity expansion concentrates in high-speed rail corridors with proven passenger density.
Among integrated rail operators, Deutsche Bahn AG and Trenitalia exemplify the captive-service archetype, controlling end-to-end catering operations within their network footprints. IRCTC Limited occupies a distinctive position as a state-affiliated platform operator managing centralized procurement for one of the world's largest passenger rail networks. Compass Group represents the multi-service contractor model, with unified agreements spanning station retail, lounge catering, and onboard delivery under consolidated vendor relationships.
| Leading Market Players |
|---|
| LSG Sky Chefs |
| Deutsche Bahn AG |
| Compass Group |
| Trenitalia |
| Eurostar |
| IRCTC Limited |
| Elior Group |
| Gate Gourmet |
| Newrest Group |
| Others |
Pricing and Supply Chain Analysis
Commissary kitchen workforce concentration in India's Delhi-Mumbai corridor widens pricing-tier spreads between premium full-galley service and economy pre-packaged meals. Labor-cost differentials between certified commissary operators and informal station vendors compress margins at the economy tier while sustaining premium pricing power on long-distance routes.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments passengers by journey duration and service class. Certification grade under EU F-Gas Regulation and FSSAI licensing separates compliant operators from informal competitors, while volume scale on China's Beijing-Shanghai corridor enables cost absorption. Cost compression in economy segments intensifies because microwave-regeneration protocols cap quality perception. Charter tour operators exhibit least price sensitivity; commuter passengers show highest elasticity.
Supply Chain Analysis
Domestic-content mandates in India's IRCTC procurement framework and China's SAMR localization requirements are reshaping sourcing toward regional commissary networks. Supply concentrates in India, China, and Germany, with chilled-chain infrastructure drawing from specialized cold storage equipment, food-contact packaging materials, and galley regeneration systems. Single-source vulnerability runs through limited EU F-Gas compliant refrigeration suppliers. Distribution runs through centralized commissary hubs feeding station-based fulfillment and onboard inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The train catering service market functions as a stable compounder, with digital pre-ordering infrastructure driving steady ancillary revenue conversion across recovering ridership bases.
For Market Incumbents: Deploy digital platform consolidation to capture pre-ordering demand upstream of traditional galley service. Incumbents should deepen backward integration into commissary production to defend against emerging cloud-kitchen entrants, while accelerating REACH and F-Gas certification investments to raise rival qualification barriers across European cross-border routes. For New Entrants and Emerging Players: Station-based cloud kitchen operators represent the most penetrable channel partner type for bypassing captive rail operator relationships. New entrants should target India's secondary corridor e-catering aggregation, where IRCTC's platform openness creates supplier slots, and leverage carbon-labeling verification as a differentiated go-to-market angle for European procurement tenders. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized commissary operators with multi-rail certifications but limited brand recognition. Long-term viability hinges on digital platform control rather than physical kitchen assets; the signal to watch is pre-ordering platform market share consolidation as a predictor of commissary contract renewal concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Integration | IRCTC and JR East demonstrate how pre-ordering infrastructure displaces spontaneous onboard purchasing. |
| Commissary Certification Investment | REACH and EU F-Gas compliance raises supplier qualification barriers across European cross-border networks. |
| Carbon-Labeling Program Launch | Verified supply chain emissions data opens procurement slots under tightening European sustainability criteria. |
| Station-Lounge Convergence Contract | Compass Group's unified agreements spanning retail, lounge, and onboard service consolidate vendor relationships. |
| Vegan Menu Line Expansion | Segregated preparation infrastructure captures dietary diversity mandates reshaping European rail procurement. |
Research Methodology
Coverage spans Germany, India, Japan, China, and the United Kingdom, with primary inputs from each market's rail operators and commissary suppliers. The analytical approach combines primary interviews with catering procurement managers, commissary operations directors, digital platform engineers, and food safety compliance officers alongside secondary validation through FSSAI licensing databases, EU F-Gas Regulation implementation reports, and SAMR food safety protocols. Bottom-up route-level revenue modeling and top-down market sizing triangulate volume estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include service type, end user, food type, and delivery mode, with additional modeling of regulatory compliance tier and digital platform penetration. CAGRs derive from ridership recovery trajectories, commissary capacity expansion plans, and pre-ordering adoption curves specific to each corridor's passenger demographics and journey duration distribution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cross-border regulatory divergence, refrigerant phase-down acceleration, and shifts in passenger pre-ordering behavior. Forecasts reflect documented assumptions regarding ridership recovery, certification timeline adherence, and platform adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
UK Smokeless Indoor Grills Market
Food Service
GCC Biodegradable Food Service Disposables Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
Smokeless Grill Market
Food Service
Contract Catering Market
Food Service
Healthy Takeout Market
Food Service
Galley Equipment Market
Food Service
Nigeria Food Service Market
Food Service
Workplace Service Market
Food Service
North America Online Grocery Delivery Market
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
US Restaurant Point of Sale Solution Market
Food Service
Russia Foodservice Market
Food Service
Saudi Arabia Out of Home (OOH) Delivery Market
Food Service
Electric Tiffin Market
Food Service
Instant Grocery Market