
 Specula Market | 2026-2036
Specula Market Size, Share, and Industry Trends Forecast 2026-2036
Specula Market Intelligence
Single-use sterility assurance is bifurcating the Specula Market into premium disposable and value reusable tiers. Integra LifeSciences leverages its surgical instrumentation heritage to dominate the reusable stainless steel segment in North American hospital systems. CooperSurgical anchors the disposable plastic category through deep gynecology channel relationships with outpatient clinics. BD differentiates via vertical integration into polymer molding, securing cost advantages at high production volumes.
Specula are hinged or fixed-blade instruments, typically manufactured from medical-grade stainless steel or polymer composites, designed to dilate body cavities for visual examination or procedural access. Their primary purpose spans gynecological examination, dental retraction, and veterinary inspection where aseptic field maintenance is critical. The disposable plastic product type captures the fastest volume expansion as clinics prioritize cross-contamination elimination over per-unit economics. Gynecological application generates the deepest margin pools due to higher instrument turnover and specialized sizing requirements. Hospitals as an end-user segment sustain the largest absolute spend, though private practices are shifting procurement toward online retail channels for smaller lot sizes.
FDA 510(k) clearance requirements govern speculum safety and biocompatibility in the United States, while EU MDR and CE marking enforce post-market surveillance and clinical evidence standards across European member states. Japan's PMDA maintains distinct mechanical testing protocols that create incremental compliance costs for imported devices. Stakeholders must monitor evolving single-use mandates from WHO infection control guidelines and assess regional sterilization infrastructure gaps before committing capacity to reusable or disposable platforms.
Market Dynamics
FDA single-use device guidelines and EU MDR sterilization standards are compressing reusable instrument lifecycles while accelerating polymer speculum procurement in ambulatory settings. Hospital supply committees now weigh cross-contamination liability against per-procedure cost differentials.
Growth Catalysts
- WHO infection control mandates:The organization's aseptic field protocols are mandating disposable instruments in outbreak-prone regions, expanding polymer speculum procurement in sub-Saharan African clinics.
- Ambulatory surgical center densification:United States outpatient facility networks are prioritizing single-use sterility assurance over sterilization infrastructure investment.
- Polymer composite molding advances:Medical-grade plastics with integrated LED illumination channels are enabling functional differentiation without stainless steel machining costs.
Market Restraints
- Petrochemical input volatility:Polypropylene and polystyrene resin prices fluctuate with crude oil markets, compressing disposable speculum margins for manufacturers without backward integration into polymer supply.
- Stainless steel supply concentration:Medical-grade 316L sourcing clusters in German and Japanese foundries, exposing reusable instrument producers to alloy price shocks and export licensing delays.
- Autoclave infrastructure lock-in:Hospital systems with captive sterilization departments face sunk-cost resistance when evaluating disposable platform conversions.
Strategic Opportunities
- Veterinary diagnostic expansion:Companion animal practice networks in Australia and Canada are adopting human-grade disposable specula for reproductive health screening.
- E-commerce direct procurement:Small-lot online channels are capturing private gynecology practices seeking inventory flexibility outside hospital group purchasing organizations.
- EU MDR clinical evidence requirements:The regulation's post-market surveillance mandates are advantaging manufacturers with established biocompatibility documentation over new market entrants.
Industry Challenges
- Polymer biocompatibility certification timelines:ISO 10993 cytotoxicity and sensitization testing protocols extend product development cycles by 12-18 months for novel material formulations.
- Sterilization validation complexity:Gamma irradiation dose mapping for disposable speculum packaging requires specialized contract laboratory capacity with limited geographic availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specula Market |
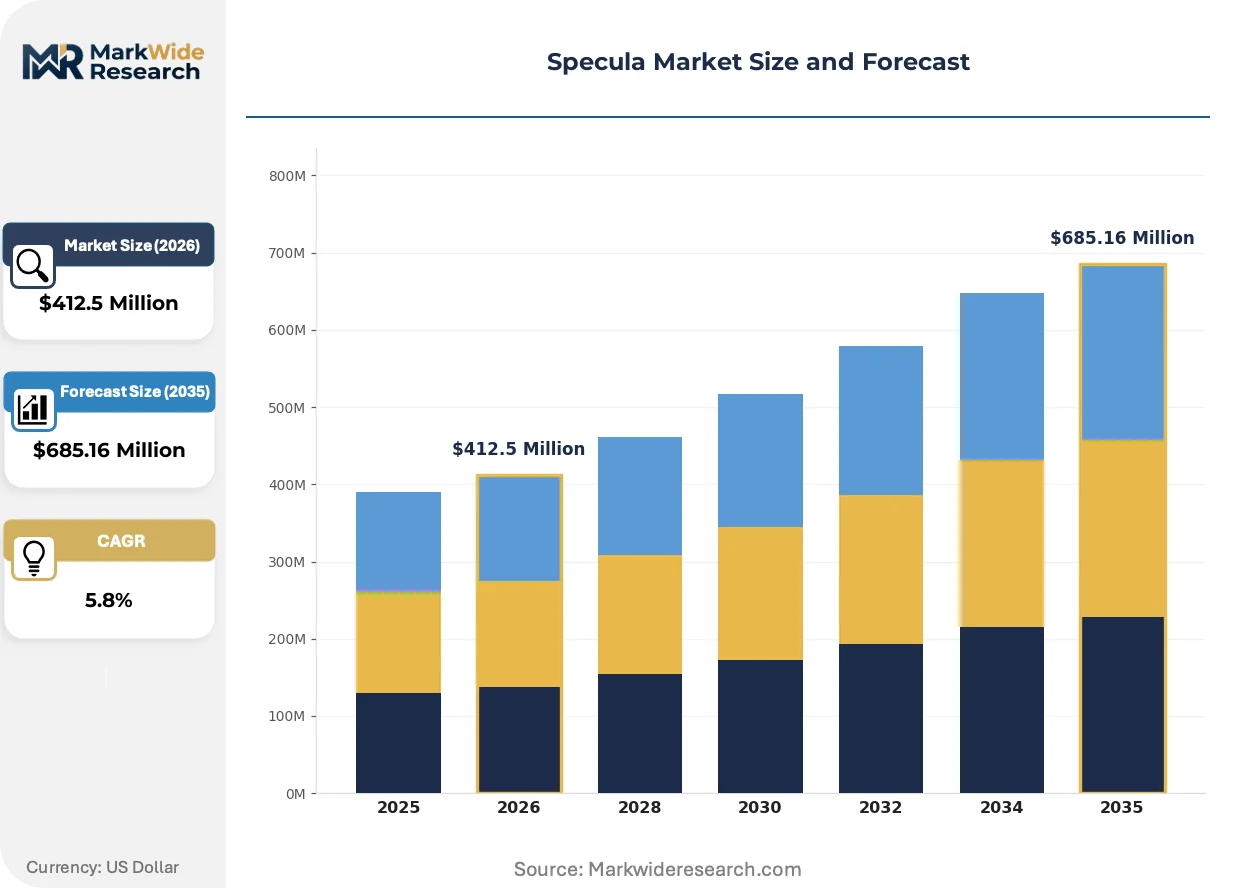
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Plastic, Disposable, Reusable Application: Dental, Gynecological, Surgical, Veterinary End User: Hospitals, Clinics, Laboratories, Private Practices Distribution Channel: Online Retail, Medical Supply Stores, Direct Sales, Wholesalers |
| Companies Covered | Integra LifeSciences, CooperSurgical, BD, Medline Industries, B. Braun Melsungen AG, STERIS Corporation, MedGyn Products, Welch Allyn, Teleflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specula Market Strategic Shifts & Innovations
Illuminated polymer specula with integrated LED channels are displacing separate light-source configurations in examination rooms. Regulatory harmonization pressures and procurement centralization are simultaneously reshaping competitive positioning across disposable and reusable platform categories.
LED-integrated polymer speculum designs are displacing detachable light-source systems in gynecological examination protocols. Outpatient clinics in the United States and Germany are adopting these instruments to eliminate cable sterilization and reduce room turnover time. The convergence is compressing demand for standalone vaginal wall illuminators and reshaping accessory revenue pools for distributors.
EU MDR Article 10 clinical evidence requirements are extending regulatory clearance timelines for new speculum geometries and surface coatings. Manufacturers must now submit post-market surveillance plans and periodic safety update reports that exceed previous CE marking documentation burdens. The French ANSM and German BfArM are enforcing these standards most stringently, delaying market entry for polymer speculum variants lacking established biocompatibility histories.
Consolidated procurement through hospital group purchasing organizations is concentrating volume among speculum suppliers with national distribution contracts. Independent gynecology practices are responding through specialty medical distributors and direct manufacturer portals for smaller lot sizes. This bifurcation is most pronounced in Japan, where metropolitan hospital networks centralize purchasing while rural clinics maintain fragmented supplier relationships.
Specula Market Segmentation
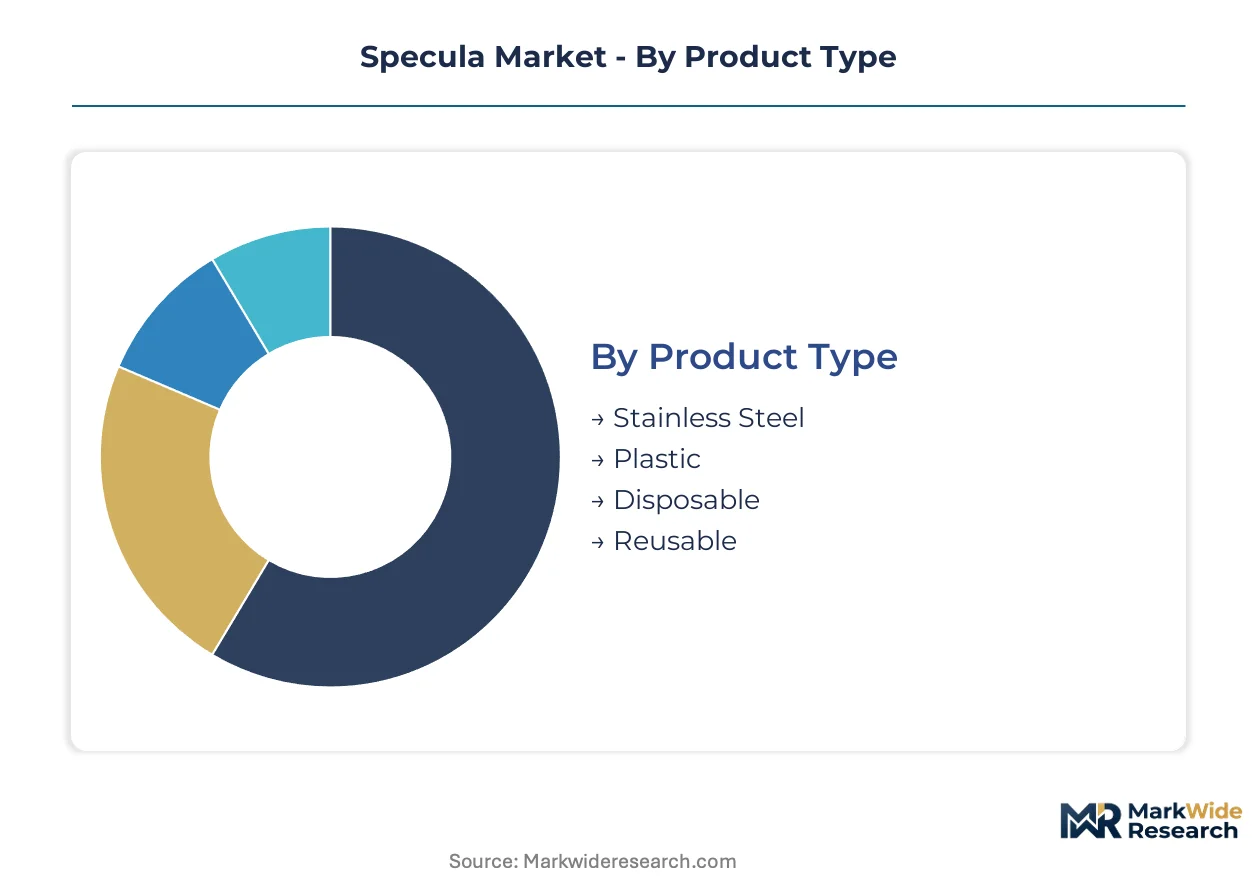
Specula procurement patterns diverge sharply across clinical settings, with sterilization infrastructure and procedure volume dicting whether facilities favor capital-intensive reusable platforms or operational-expense disposable models. Channel selection further stratifies the market, as hospital group purchasing organizations concentrate volume through direct sales while fragmented private practices gravitate toward online retail for inventory flexibility.
Product Type:
Channel-mix dynamics split sharply between reusable and disposable platforms, with stainless steel instruments flowing through surgical distributor networks and polymer disposables penetrating outpatient clinics via direct manufacturer portals.
- Stainless Steel:Medical-grade 316L alloy construction delivers instrument longevity exceeding 1,000 autoclave cycles. Demand concentrates in United States metropolitan hospital systems with captive sterilization departments, where per-procedure amortization outweighs disposable premium. German university hospitals anchor European procurement for reusable platforms.
- Plastic:Polypropylene and polystyrene formulations enable integrated LED illumination channels without machining costs. Outpatient surgical centers in Japan and ambulatory clinics across Australia are displacing separate light-source configurations to reduce room turnover time.
- Disposable:Single-use sterility assurance eliminates cross-contamination liability in high-throughput settings. WHO infection control protocols are mandating polymer specula in outbreak-prone sub-Saharan African clinics.
- Reusable:Long instrument lifecycles require validated sterilization infrastructure and trained biomedical engineering staff. Procurement concentrates where autoclave capacity is already sunk.
Stainless steel dominates installed base. Disposable is where expansion concentrates.
Application:
Margin structures vary dramatically by clinical discipline, with gynecological procedures generating premium instrument turnover due to specialized sizing requirements and higher examination frequency.
- Gynecological:Cervical visualization and biopsy access demand specula with adjustable blade angles and integrated suction ports. United States ambulatory surgical center networks prioritize single-use polymer platforms to eliminate sterilization bottlenecks between procedures.
- Dental:Cheek and tongue retraction applications favor smaller apertures with smooth polymer surfaces to prevent mucosal trauma. Canadian and Australian companion animal practice networks are adopting human-grade disposable specula for veterinary dental screening.
- Surgical:Operating room specula require rigid construction for tissue retraction under tension. Reusable stainless steel retains preference where procedure duration exceeds one hour.
- Veterinary:Reproductive health screening in large animal practices drives demand for extended-length instruments. Direct manufacturer portals are capturing volume from rural veterinary clinics outside consolidated distributor networks.
Gynecological applications command premium pricing tiers. Veterinary represents the steepest expansion trajectory as companion animal spending climbs.
End User:
Procurement centralization versus fragmentation determines contract structure, with hospitals leveraging group purchasing organization scale against the inventory flexibility sought by independent practitioners.
- Hospitals:Supply committees evaluate total cost of ownership across sterilization labor, equipment depreciation, and liability exposure. Metropolitan networks in Japan centralize purchasing through national distribution contracts.
- Clinics:Lower procedure volumes favor disposable platforms that eliminate capital investment in autoclave infrastructure. EU MDR compliance costs are accelerating consolidation toward suppliers with established biocompatibility documentation.
- Laboratories:Specimen collection protocols prioritize sterility assurance over instrument longevity. Procurement flows through specialty medical distributors with cold-chain logistics capabilities.
- Private Practices:Small-lot requirements and irregular ordering patterns drive adoption of e-commerce direct procurement channels outside hospital group purchasing organization structures.
Hospitals anchor absolute spend volume. Private practices are where channel disruption concentrates.
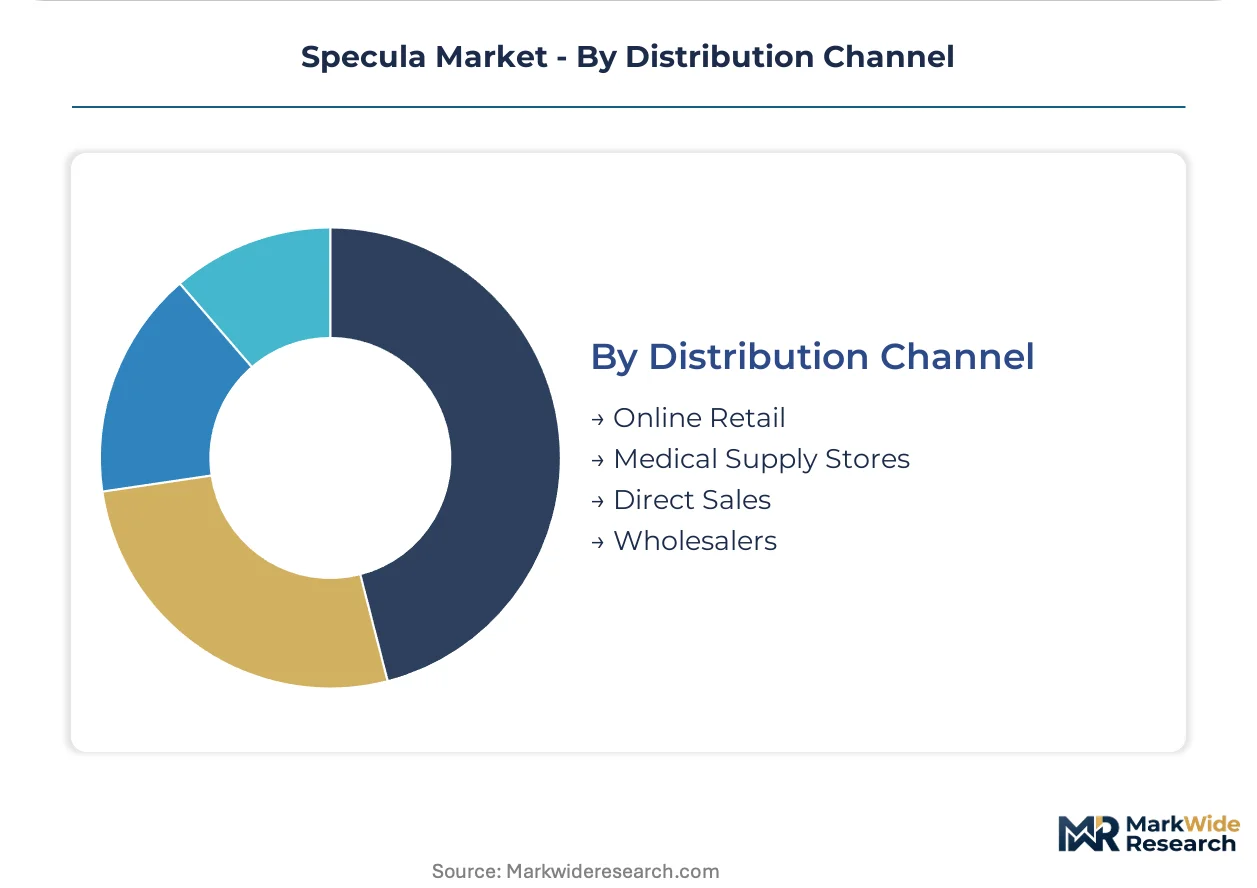
Distribution Channel:
Supply chain configuration reflects customer scale and regulatory complexity, with national contracts requiring validated quality management systems that exclude smaller regional wholesalers.
- Direct Sales:Manufacturer field forces manage hospital group purchasing organization negotiations and clinical training support. FDA 510(k) documentation and EU MDR technical files become competitive differentiators in contract tenders.
- Online Retail:E-commerce platforms capture private gynecology practices seeking lot-size flexibility and rapid replenishment. Inventory visibility and automated reordering algorithms reduce stockout risk for low-volume purchasers.
- Medical Supply Stores:Local distributors maintain relationships with rural clinics and independent veterinarians requiring immediate availability. Geographic coverage gaps in sub-Saharan Africa limit penetration outside urban corridors.
- Wholesalers:Regional distributors aggregate fragmented demand for manufacturers lacking direct sales infrastructure. Margin compression from tiered pricing structures favors high-volume disposable speculum categories.
Direct sales dominate contract value. Online retail is where customer acquisition concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specula trade flows reflect divergent sterilization infrastructure investments across major healthcare markets. Import dependence concentrates in regions lacking domestic polymer molding capacity, while established surgical instrument exporters maintain reusable platform advantages.
United States
Ambulatory surgical center densification drives disposable polymer procurement in Texas and Florida outpatient networks. FDA 510(k) clearance requirements govern biocompatibility standards for imported devices. Minneapolis and Boston medical device clusters anchor domestic manufacturing of illuminated plastic specula.
Germany
University hospital systems in Bavaria and North Rhine-Westphalia sustain demand for medical-grade 316L stainless steel instruments with extended autoclave cycles. EU MDR post-market surveillance mandates enforce clinical evidence standards for polymer variants. Tuttlingen's surgical instrument cluster supplies reusable platforms across European member states.
Japan
Metropolitan hospital networks in Tokyo and Osaka centralize procurement through national distribution contracts favoring single-use sterility assurance. PMDA mechanical testing protocols create incremental compliance costs for European and North American exporters. Nagoya's polymer processing hub enables domestic LED-integrated speculum assembly.
Australia
Companion animal practice networks in New South Wales and Victoria adopt human-grade disposable specula for veterinary reproductive screening. TGA registration requirements align with ISO 13485 quality management standards. Sydney's specialty medical distributors capture volume from fragmented rural clinics outside hospital purchasing organizations.
India
Government hospital procurement in Maharashtra and Karnataka prioritizes cost-optimized reusable platforms where autoclave infrastructure exists. CDSCO import licensing governs polymer biocompatibility certification for disposable variants. Ahmedabad's medical plastics molding sector supplies domestic private clinic demand.
Specula Market Key Industry Players
Concentration sits with diversified surgical instrument conglomerates commanding hospital group purchasing organization contracts. Mid-tier specialists occupy the veterinary and dental retraction segments where volume thresholds favor niche positioning. Two strategic archetypes dominate: integrated manufacturers with captive polymer supply, and instrument pure-plays leveraging surgical distributor relationships. Competitive moves center on EU MDR compliance documentation investments and e-commerce channel buildouts for private practice direct procurement.
Within the diversified surgical conglomerate tier, Integra LifeSciences and CooperSurgical exemplify contrasting platform strategies—one anchored in reusable stainless steel heritage, the other in gynecology channel depth for disposable polymer penetration. BD occupies a position reflecting backward integration into medical-grade polymer molding. These three entities represent the spectrum from instrument specialization to materials control, with each archetype responding differently to FDA single-use guidance and WHO infection control protocol expansion.
| Leading Market Players |
|---|
| Integra LifeSciences |
| CooperSurgical |
| BD |
| Medline Industries |
| B. Braun Melsungen AG |
| STERIS Corporation |
| MedGyn Products |
| Welch Allyn |
| Teleflex |
| Others |
Cost & Logistics Intelligence
High-volume polymer molding capacity in Germany and Japan anchors cost floors for disposable specula while compressing margins for mid-tier competitors lacking comparable scale. Hospital group purchasing organizations leverage this concentration to extract volume discounts, forcing smaller manufacturers toward specialty distributor channels where price premiums reflect lot-size flexibility rather than manufacturing efficiency.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels, with FDA 510(k) clearance tier and LED integration grade driving differentiation. Cost compression in economy polymer specula is intensifying because polypropylene resin volatility transfers directly to per-unit margins. Private gynecology practices exhibit highest price sensitivity, while metropolitan hospital networks with captive sterilization departments accept premium stainless steel pricing for extended instrument lifecycles.
Supply Chain Analysis
Medical-grade 316L stainless steel sourcing from Tuttlingen and Nagoya foundries underwrites reusable instrument supply security for European and Japanese hospital systems. Polypropylene resin feeds from petrochemical complexes in Germany and the US Gulf Coast, with polystyrene additives drawing from East Asian polymer processors. Single-source vulnerability concentrates in gamma irradiation contract laboratories with limited geographic availability. Distribution runs through surgical instrument distributors for reusable platforms and direct manufacturer portals for disposable polymer variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The specula market exhibits durable defensive moats rooted in regulatory entrenchment, where FDA 510(k) clearance timelines and EU MDR clinical evidence requirements create multi-year barriers against new platform entrants.
For Market Incumbents: Compound regulatory documentation advantages by deepening biocompatibility testing archives ahead of EU MDR periodic safety update report deadlines. Expand gamma irradiation contract laboratory relationships to preempt sterilization validation bottlenecks that constrain disposable platform competitors. Threat of polymer speculum commoditization from Asian molders demands certification investment as the primary defensive lever. For New Entrants and Emerging Players: Anchor in veterinary diagnostic expansion across Australian and Canadian companion animal practice networks, where human-grade disposable specula adoption outpaces regulatory scrutiny intensity. Target rural Japanese clinics outside metropolitan hospital purchasing organization consolidation through specialty medical distributor partnerships. E-commerce direct procurement channels offer the most penetrable go-to-market angle for inventory-flexible private practices. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors polymer speculum manufacturers with established LED integration capabilities and backward polymer supply control. Long-term viability hinges on sterilization infrastructure transition economics across ambulatory surgical center densification. Acquisition target archetype: mid-tier disposable speculum specialists with EU MDR technical files already submitted. Watch WHO infection control protocol expansion into sub-Saharan African procurement as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Completion | Establishes post-market surveillance capability ahead of ANSM and BfArM enforcement deadlines. |
| LED-Integrated Polymer Platform Launch | Eliminates separate light-source configurations and reduces examination room turnover time. |
| Gamma Irradiation Partnership Expansion | Secures sterilization validation capacity with limited geographic contract laboratory availability. |
| Veterinary Diagnostic Channel Entry | Captures companion animal practice volume adopting human-grade disposable instruments. |
| E-Commerce Direct Procurement Buildout | Targets private gynecology practices seeking lot-size flexibility outside GPO structures. |
Research Approach
Operator-level perspectives from hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and veterinary practice owners anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) filings, EU MDR technical file databases, hospital procurement contract registries, and polymer trade flow data. Bottom-up instrument volume modeling triangulated against top-down healthcare expenditure allocation estimates.
Sensitivity analysis tested forecast robustness across polypropylene resin price scenarios, sterilization infrastructure investment trajectories, and regulatory timeline variations throughout the projection horizon. Segmentation dimensions modeled include product type, application discipline, end-user facility scale, and distribution channel structure. CAGRs derived from procedure volume elasticity analysis against instrument replacement rates, with LED integration adoption curves and WHO protocol expansion timelines as key industry-specific inputs.
Material uncertainties — petrochemical input volatility, autoclave infrastructure lock-in persistence, and EU MDR enforcement intensity variation — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding ambulatory surgical center densification pace and infection control protocol geographic expansion. Practitioners should keep alternative scenarios live as polymer biocompatibility certification timelines and gamma irradiation capacity constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Fortified Bakery Market
Bakery Products
Baking Mats Market
Bakery Products
Matcha Cookie Market
Bakery Products
Frosting, Toppings, and Decorations Market
Bakery Products
Bakery Premixes Market
Bakery Products
Cake Base Discs Market
Bakery Products
South America Bakery Products Market
Bakery Products
Laminated Dough Market
Bakery Products
Marzipan Market
Bakery Products
Pizza Dough Balls Market
Bakery Products
Diabetic Bakery Products Market
Bakery Products
India Cake Market
Bakery Products
Pastries Market
Bakery Products
Pancake Mixes Market
Bakery Products
Pastry Margarine Market
Bakery Products
On-The-Go Breakfast Products Market