
 Low-Gluten Emmer and Einkorn Flour Blends Market | 2026-2036
Low-Gluten Emmer and Einkorn Flour Blends Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Gluten Emmer and Einkorn Flour Blends Market Insights
The capital-intensity divergence between stone-milled heritage operations and industrial roller-milling infrastructure is bifurcating competitive dynamics across the Low-Gluten Emmer and Einkorn Flour Blends landscape. Jovial Foods leverages its integrated Italian supply chain to sustain premium positioning in organic emmer sourcing. Hayden Flour Mills anchors Southwestern US distribution through direct relationships with regional artisan bakeries. Bob's Red Mill competes at scale with broad retail penetration across conventional grocery channels.
Low-gluten emmer and einkorn flour blends combine ancient wheat varieties with gluten content typically below ten percent, milled through stone or roller processes that preserve bran integrity and mineral density for digestibility-focused baking and pasta applications. Emmer flour blends dominate current volume through established Mediterranean supply chains, while specialty flour mixes capture expanding margin pools as health food manufacturers formulate targeted gluten-reduced products. Artisan bakeries represent the fastest-growing end-user channel, though retail brands still occupy the largest absolute revenue position through supermarket distribution networks.
EFSA gluten threshold standards and USDA organic certification requirements shape product formulation and cross-border market access for heritage grain suppliers. The EU Green Deal's pesticide reduction targets and FDA food-labeling rules for gluten content collectively pressure mills toward certified supply chain documentation. Stakeholders must monitor evolving allergen classification debates and heritage variety seed registry protections that could reshape raw material availability.
Market Dynamics
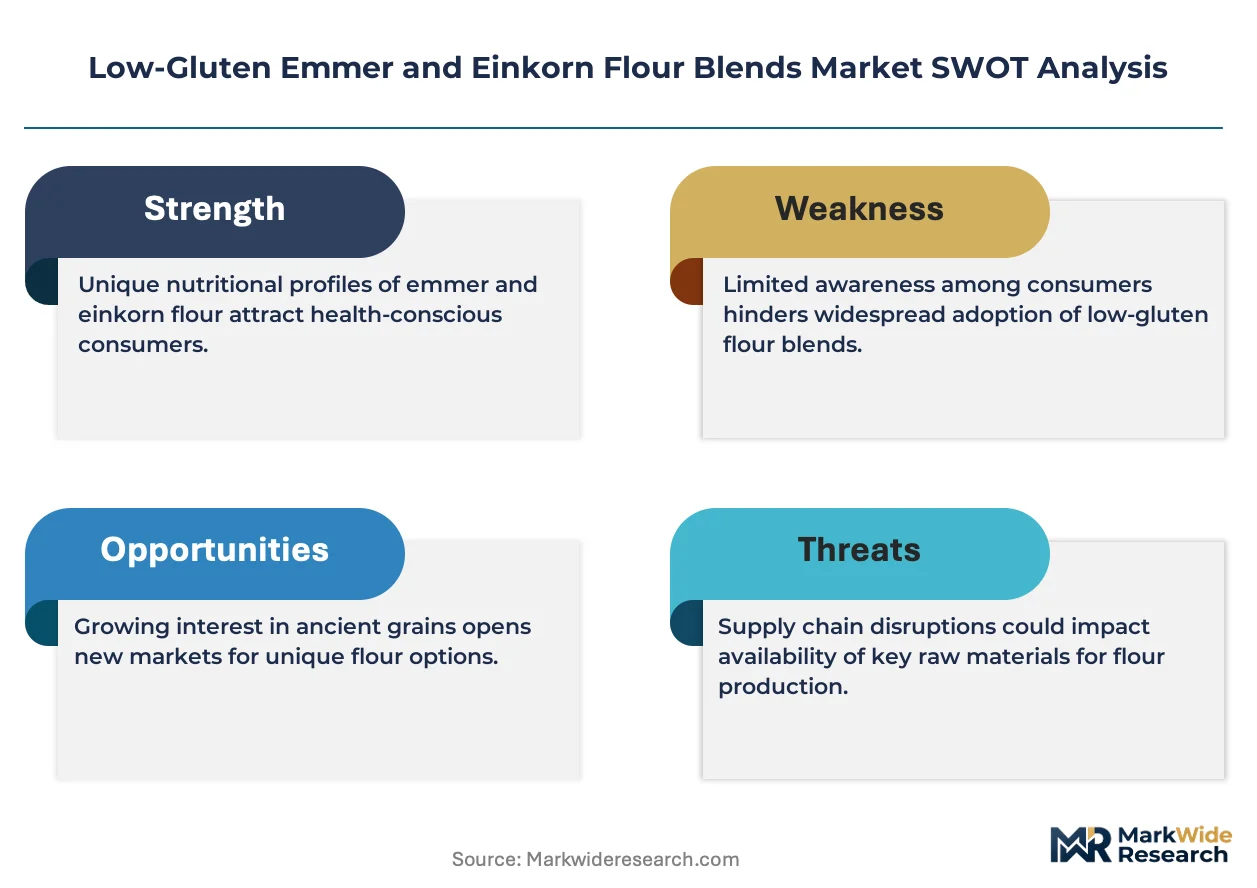
Heritage wheat supply chains face intensifying pressure from EFSA gluten threshold enforcement and the EU Green Deal's pesticide reduction mandates, forcing mills to document certified organic provenance while scaling stone-milled capacity to serve artisan bakery demand.
Growth Catalysts
- EU Farm to Fork Strategy:Cleaner-label grain processing requirements under EFSA standards are pulling heritage varieties into mainstream retail distribution as conventional wheat faces chemical residue scrutiny.
- Artisan bakery channel expansion:Mediterranean craft bakers in Germany and Italy are formulating emmer-einkorn blends for digestibility-focused consumers, creating pull-through demand for certified organic supply.
- Stone-milling technology:Preservation of bran integrity and mineral density through traditional milling methods is differentiating premium positioning against industrial roller-milled alternatives.
Market Restraints
- Input cost volatility:Heritage wheat seed scarcity and limited acreage under organic cultivation in Italy and the United States create raw material price instability for millers.
- Supply concentration risk:Mediterranean emmer sourcing clusters in specific Italian growing regions, exposing buyers to climate-driven harvest variability and single-origin dependency.
- Technical limitation:Gluten content below ten percent restricts dough elasticity for industrial-scale bread production, constraining volume applications outside artisan and specialty segments.
Strategic Opportunities
- Pacific Northwest penetration:Underdeveloped distribution in Oregon and Washington state offers whitespace for heritage flour brands targeting regional craft bakeries and farmers market channels.
- Pasta application expansion:Einkorn's al dente texture properties are opening formulation opportunities for premium dried pasta manufacturers seeking ancient wheat differentiation.
- USDA organic certification tailwind:Federal procurement preferences and retail slotting fee reductions for certified organic products are accelerating shelf placement in conventional grocery.
Industry Challenges
- Heritage grain agronomy expertise gap:Limited agronomists trained in ancient wheat cultivation practices constrain yield optimization and disease management for expanding organic acreage.
- EFSA compliance documentation burden:Cross-border gluten threshold verification and supply chain traceability requirements extend certification timelines and inflate administrative overhead for small-scale millers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Gluten Emmer and Einkorn Flour Blends Market |
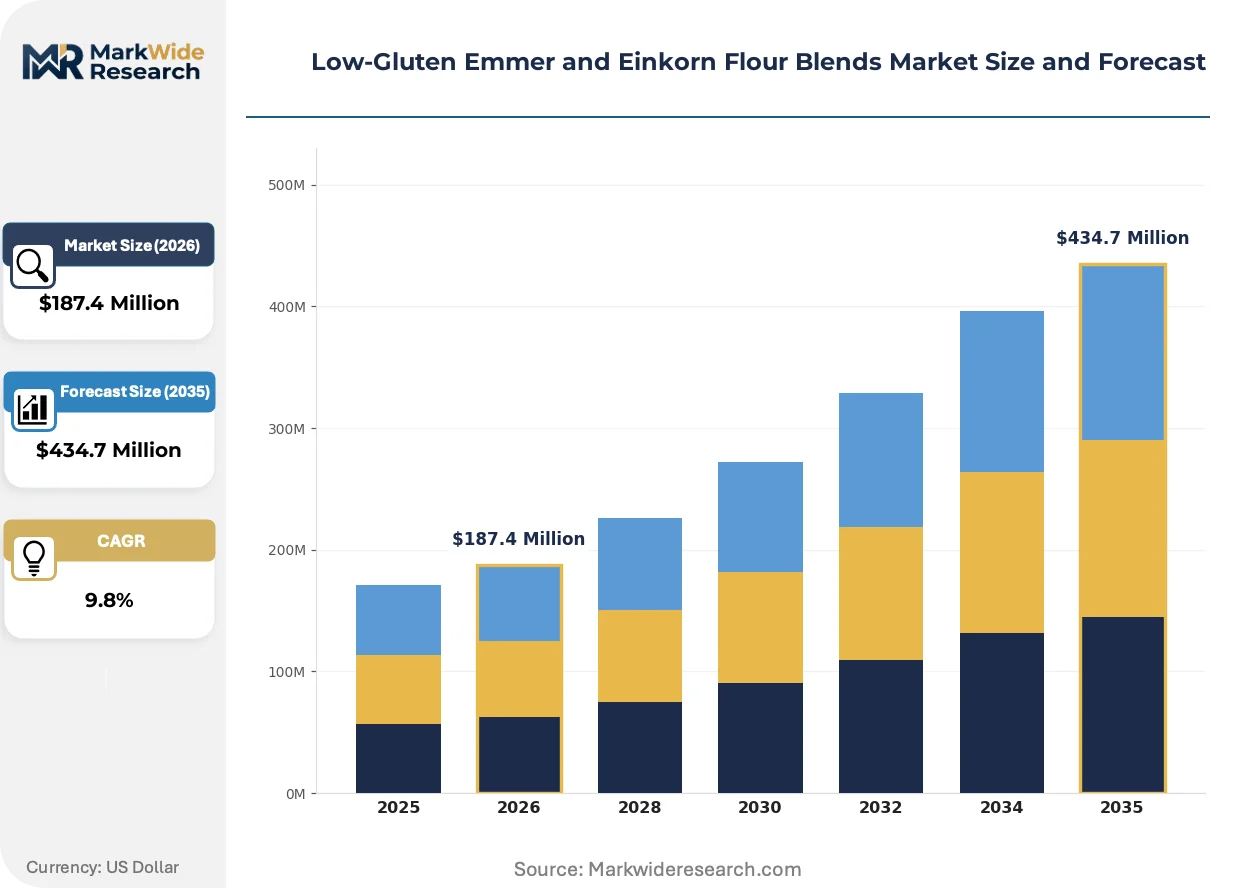
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emmer Flour Blends, Einkorn Flour Blends, Mixed Grain Blends, Specialty Flour Mixes Application: Baking, Pasta Production, Snack Foods, Breakfast Cereals, Gluten-Reduced Products End User: Artisan Bakeries, Health Food Manufacturers, Foodservice Providers, Retail Brands Packaging Type: Bulk Bags, Consumer Packs, Vacuum Sealed Packs, Paper Bags, Resealable Pouches |
| Companies Covered | Jovial Foods, Bluebird Grain Farms, Hayden Flour Mills, Grand Teton Ancient Grains, Barton Springs Mill, Central Milling, SchapfenMühle, Bob's Red Mill, Breadtopia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Gluten Emmer and Einkorn Flour Blends Market Trends and Innovations
Heritage grain processing is undergoing rapid transformation as regulatory compliance, milling technology, and buyer procurement patterns simultaneously reshape competitive requirements for emmer and einkorn suppliers.
Optical sorting and near-infrared spectroscopy for gluten content verification is decomposing traditional batch-testing protocols that delayed mill output. Artisan bakeries and co-manufacturers are adopting inline quality control to reduce hold times and reject rates. Real-time compositional analysis is compressing the gap between harvest variability and consistent blend formulation, enabling smaller mills to compete on specification reliability.
EFSA's evolving gluten threshold standards and the EU Green Deal's pesticide reduction targets are tightening documentation requirements for heritage grain imports into European markets. Mills must now maintain chain-of-custody records from seed registry to final package, with non-compliant shipments facing border rejection. Italian and German suppliers are responding by consolidating backward integration into certified organic farming cooperatives to control provenance verification.
Direct procurement relationships between artisan bakeries and heritage grain mills are displacing traditional distributor intermediaries in the premium flour segment. Pacific Northwest and Mediterranean craft bakers are sourcing through vertical supply agreements that guarantee varietal purity and harvest-specific gluten profiles. This channel compression is most visible in urban clusters like Portland, Seattle, and Berlin where bakery-dedicated mill operations are establishing satellite stone-milling facilities.
Low-Gluten Emmer and Einkorn Flour Blends Market Segmentation

Segmentation in the Low-Gluten Emmer and Einkorn Flour Blends Market reveals distinct procurement patterns between domestic artisan channels and export-oriented industrial buyers. Heritage grain sourcing clusters and milling scale create divergent margin structures across product categories.
Product Type:
Emmer flour blends anchor Mediterranean export flows to Germany and the United States, while einkorn varieties serve more concentrated domestic Italian and Pacific Northwest markets.
- Emmer Flour Blends:Stone-milled emmer with gluten content typically below ten percent preserves bran integrity for digestibility-focused baking. German artisan bakeries in Berlin and Munich drive import demand through established Mediterranean supply chains, though Italian domestic consumption remains substantial.
- Einkorn Flour Blends:Higher protein density and distinct al dente texture properties differentiate einkorn for premium pasta applications. Pacific Northwest craft bakeries in Portland and Seattle source directly from regional mills, creating localized pull-through demand outside traditional distribution networks.
- Mixed Grain Blends:Formulations combining emmer, einkorn, and secondary heritage wheats target health food manufacturers seeking diversified nutritional profiles.
- Specialty Flour Mixes:Pre-formulated blends with added functional ingredients serve retail brands targeting home bakers with simplified preparation requirements.
Emmer flour blends command the established base. The steepest expansion runs through specialty flour mixes as health food manufacturers accelerate gluten-reduced product launches.
Application:
Cost tier stratification separates premium artisan baking from volume-driven snack food manufacturing, with pasta production occupying a mid-tier positioning based on ingredient specification requirements.
- Baking:Artisan bakeries formulate emmer-einkorn blends for digestibility-focused bread and pastry applications requiring specific dough elasticity management. Mediterranean craft bakers in Italy and Germany create pull-through demand for certified organic supply with harvest-specific gluten profiles.
- Pasta Production:Einkorn's al dente texture properties open formulation opportunities for premium dried pasta manufacturers. Italian heritage grain mills supply regional pasta producers through backward integration into certified organic farming cooperatives.
- Snack Foods:Cracker and flatbread manufacturers utilize low-gluten blends for differentiated positioning in health-conscious retail channels.
- Breakfast Cereals:Heritage grain inclusion supports clean-label claims for premium cereal brands targeting organic certification requirements.
- Gluten-Reduced Products:Formulations meeting EFSA threshold standards serve consumers with non-celiac gluten sensitivity through controlled gluten content verification protocols.
Baking anchors volume concentration. Pasta production is gaining share fastest as premium dried pasta manufacturers seek ancient wheat differentiation.
End User:
Customer type determines procurement scale and relationship structure, with direct mill relationships displacing distributor intermediaries in premium channels while retail brands maintain conventional grocery network dependencies.
- Artisan Bakeries:Mediterranean and Pacific Northwest craft bakers source through vertical supply agreements guaranteeing varietal purity. Urban clusters in Berlin, Portland, and Seattle drive satellite stone-milling facility expansion.
- Health Food Manufacturers:Formulation of targeted gluten-reduced products creates expanding margin pools for heritage grain suppliers with certified organic documentation.
- Foodservice Providers:Restaurant and institutional buyers prioritize specification reliability and consistent supply for menu integration.
- Retail Brands:Supermarket distribution networks still occupy the largest absolute revenue position despite slower growth rates compared to direct channels.
Retail brands command the established base. Artisan bakeries are climbing the fastest as channel compression accelerates direct procurement relationships.
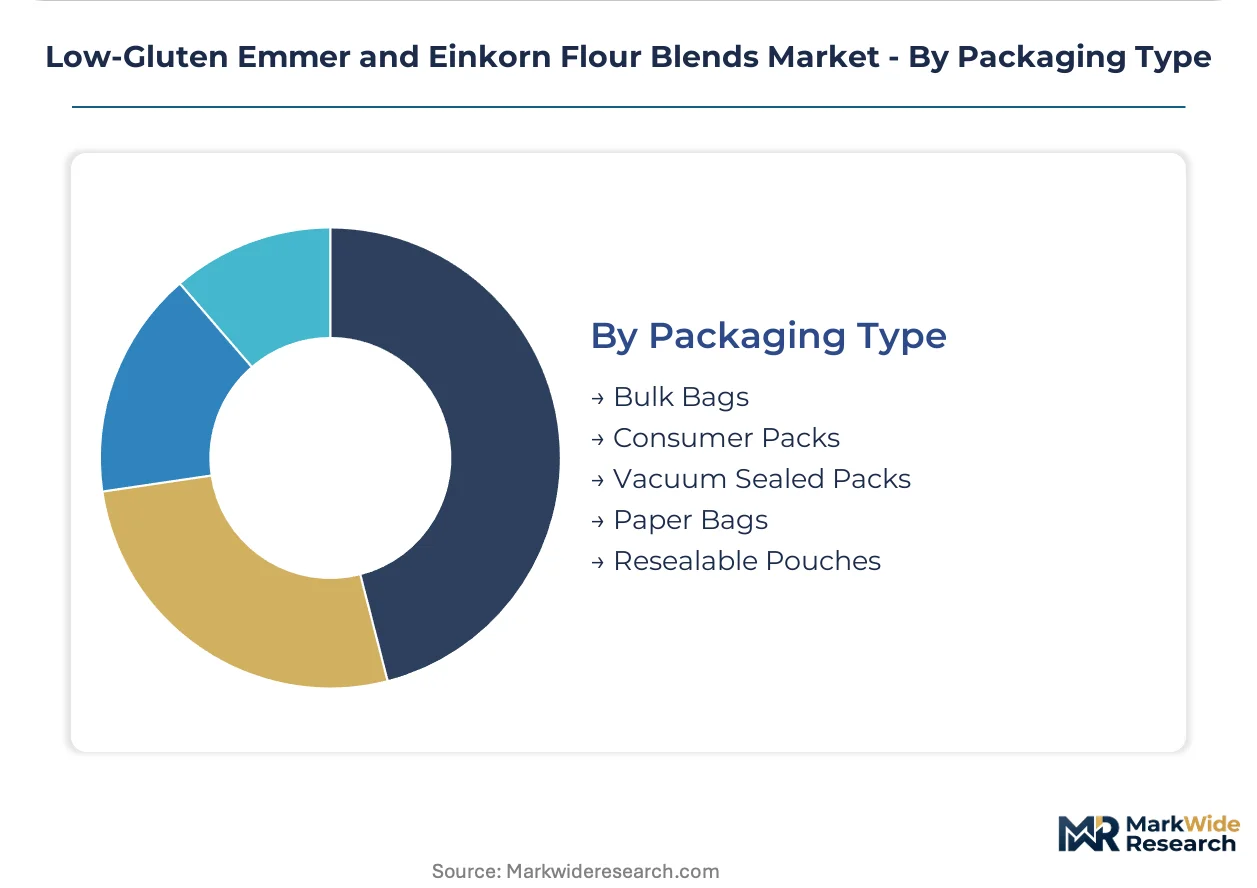
Packaging Type:
Volume scale and shelf-life requirements differentiate bulk industrial formats from consumer-facing retail packaging with premium positioning implications.
- Bulk Bags:Foodservice providers and industrial manufacturers procure multi-ton quantities through established distribution networks with specification contracts.
- Consumer Packs:Standard retail packaging serves conventional grocery channels with USDA organic certification driving shelf placement preferences.
- Vacuum Sealed Packs:Extended shelf-life preservation targets premium health food retail and export markets requiring prolonged distribution timelines.
- Paper Bags:Sustainability-focused packaging aligns with EU Green Deal environmental positioning for Mediterranean market penetration.
- Resealable Pouches:Convenience-oriented formats support home baker usage patterns and repeat purchase loyalty in specialty retail.
Consumer packs command the established base. Vacuum sealed packs are expanding most quickly as export distribution and premium retail channels extend shelf-life requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between Mediterranean markets, where heritage wheat varieties anchor traditional food culture, and Pacific Northwest clusters, where artisan bakeries drive adoption through digestibility positioning rather than culinary tradition.
United States
Pacific Northwest craft bakeries in Portland and Seattle source directly from regional stone-milling operations, bypassing conventional distribution networks. FDA gluten content labeling rules and USDA organic certification requirements shape procurement documentation for cross-state sales. Artisan bakery clusters in Oregon and Washington are establishing satellite milling facilities to secure harvest-specific varietal purity.
Germany
Berlin and Munich bakeries import Mediterranean emmer blends through established supply chains serving digestibility-focused consumers. EFSA gluten threshold enforcement and EU Green Deal pesticide reduction mandates force mills to document certified organic provenance from seed registry to final package. Urban craft bakery expansion in German metropolitan areas is compressing channel intermediaries.
Italy
Domestic consumption of einkorn varieties concentrates in Tuscany and Emilia-Romagna pasta production corridors. EFSA standards and heritage variety seed registry protections shape raw material availability for millers. Italian organic farming cooperatives are consolidating backward integration to control provenance verification for export markets.
Canada
Prairie Provinces heritage grain acreage remains limited, constraining domestic supply for Ontario and Quebec artisan bakery demand. Health Canada food labeling requirements align with FDA gluten disclosure standards for cross-border product flows. Toronto and Montreal specialty food retailers are expanding shelf placement for certified organic imported blends.
Australia
Victoria and New South Wales specialty grain growers are trialing Mediterranean emmer varieties for domestic artisan milling. TGA food standards and import quarantine protocols regulate heritage wheat seed introduction. Melbourne craft bakery clusters are sourcing through direct mill relationships to secure consistent gluten specification profiles.
Low-Gluten Emmer and Einkorn Flour Blends Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence between stone-milled heritage operations and industrial roller-milling infrastructure bifurcating competitive dynamics. Scale-driven players compete through retail shelf placement and broad distribution networks, while regional specialists anchor premium positioning through direct artisan bakery relationships. Strategic archetypes include integrated Italian supply chain operators, Southwestern US heritage grain mills, and Pacific Northwest craft-focused suppliers. Dominant competitive moves encompass backward integration into certified organic farming cooperatives and geographic expansion through satellite stone-milling facilities.
Within the integrated supply chain tier, Jovial Foods exemplifies Mediterranean-origin vertical coordination, while Hayden Flour Mills anchors Southwestern US regional distribution. Bob's Red Mill occupies a position bridging premium heritage positioning with conventional grocery scale. Bluebird Grain Farms and Grand Teton Ancient Grains represent Pacific Northwest craft-specialist archetypes, with Barton Springs Mill and Central Milling exemplifying regional stone-milling specialists serving localized artisan bakery clusters. SchapfenMühle and Breadtopia sit within European and direct-to-consumer specialist segments respectively.
| Leading Market Players |
|---|
| Jovial Foods |
| Bluebird Grain Farms |
| Hayden Flour Mills |
| Grand Teton Ancient Grains |
| Barton Springs Mill |
| Central Milling |
| SchapfenMühle |
| Bob's Red Mill |
| Breadtopia |
| Others |
Pricing and Supply Chain Analysis
Ninety-day harvest-to-mill lead times for Mediterranean emmer create inventory pressure that concentrates pricing power among Italian cooperatives with certified organic acreage, while Pacific Northwest mills absorb premium freight costs to secure varietal purity for artisan bakery contracts.
Pricing Analysis
Long-term offtake agreements dominate heritage grain procurement, with Italian organic cooperatives locking annual volume commitments from German and United States buyers before planting season. Pricing stratifies across premium stone-milled certified organic, standard roller-milled organic, and economy conventional heritage tiers. Cost compression in the economy tier intensifies as roller-milled volume producers compete for retail shelf placement. Artisan bakeries demonstrate the lowest price sensitivity, prioritizing harvest-specific gluten profiles and provenance documentation over per-unit cost.
Supply Chain Analysis
Just-in-time milling preferences among Pacific Northwest craft bakeries contrast with strategic stockpiling by Italian cooperatives facing EFSA compliance documentation delays. Raw material supply draws from Italy, the United States, and Germany, with heritage wheat seed, organic fertilizer inputs, and stone-milling equipment creating interdependent sourcing clusters. Single-source vulnerability concentrates in Tuscan emmer seed registries protected under EU heritage variety laws. Distribution runs through direct mill-bakery vertical agreements displacing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as artisan bakery channel compression dismantles conventional distribution hierarchies, enabling regional specialists to capture margin pools previously absorbed by intermediaries.
For Market Incumbents: Fortify certified organic acreage through cooperative equity stakes in Italian and Pacific Northwest farming operations, insulating against EFSA gluten threshold enforcement and seed registry access restrictions. Expand satellite stone-milling capacity in Berlin and Seattle urban clusters to defend against regional craft mill entrants capturing direct bakery relationships. For New Entrants and Emerging Players: Anchor in Oregon and Washington state farmers market channels where heritage flour penetration remains underdeveloped relative to established Mediterranean supply corridors. Target vacuum-sealed export formats for Australian and Canadian specialty retailers seeking extended shelf-life organic certification, leveraging USDA organic procurement preferences for initial shelf placement. For Investors and Strategic Acquirers: Long-term, this sits as a premiumization play because artisan bakery demand for provenance-verified supply chains outpaces industrial roller-milled capacity expansion. Acquisition targets include Pacific Northwest stone-milling specialists with established gluten specification protocols and backward integration into organic farming cooperatives. The signal to watch is EFSA heritage variety seed registry expansion decisions affecting raw material access concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Farming Cooperatives | Secures certified acreage for EFSA gluten threshold compliance and provenance documentation. |
| Satellite Stone-Milling Facility Expansion | Positions regional mills within Portland and Berlin artisan bakery clusters for direct supply relationships. |
| Optical Sorting Technology Deployment | Enables real-time gluten content verification reducing batch rejection rates for small-scale mills. |
| Vacuum-Sealed Export Format Development | Extends distribution reach to Australian and Canadian premium retail channels requiring shelf-life preservation. |
| Heritage Variety Seed Registry Protection | Locks exclusive access to protected emmer and einkorn germplasm under EU genetic resource regulations. |
Research Methodology
The analysis maps emmer flour blends, einkorn varieties, mixed grain formulations, and specialty flour mixes, each validated through primary interviews with stone-mill operators, organic cooperative agronomists, artisan bakery procurement heads, and heritage grain distributors. Secondary validation draws from USDA organic certification databases, EFSA food safety filings, EU Farm to Fork Strategy implementation reports, and regional customs trade flows. Bottom-up volume triangulation across milling capacity and top-down value reconciliation against retail channel revenue estimates ensures cross-verification.
Consistency checks validated projections against external benchmarks including organic grain trade associations, regional bakery industry surveys, and certified acreage expansion filings across the analysis window. Segmentation dimensions encompass product type, application category, end-user archetype, and packaging format, with gluten content thresholds and organic certification status as industry-specific forecast inputs. CAGRs derive from modeled volume expansion in artisan bakery channels and premium pasta manufacturing applications.
Underlying assumptions cover sustained EFSA gluten threshold enforcement, stable organic certification cost structures, and continued artisan bakery channel compression, with deviation risk concentrated in climate-driven harvest variability and heritage seed registry policy shifts. Revision becomes warranted when certified organic acreage expansion rates or regulatory classification of heritage varieties cross material thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Cake Concentrate Market
Bakery Products
Fortified Bakery Market
Bakery Products
Baking Mixes Market
Bakery Products
Flatbread Market
Bakery Products
Low Calorie Muffins Market
Bakery Products
Bakery Contract Manufacturing Market
Bakery Products
US Frozen Bakery Market
Bakery Products
Biscuits Market
Bakery Products
Batter and Breader Premixes Market
Bakery Products
GCC Frozen Bakery Products Market
Bakery Products
Middle East and Africa Sweet Biscuits Market
Bakery Products
Bread and Baked Food Market
Bakery Products
Cookies Market
Bakery Products
Asia-Pacific Frozen Bakery Market
Bakery Products
Vegan Donuts Market
Bakery Products
Global Cake Mix Market