
 Sustained Release Excipients Market | 2026-2036
Sustained Release Excipients Market Size, Share, and Industry Trends Forecast 2026-2036
Sustained Release Excipients Market Intelligence
Polymer engineering advances in biodegradable matrices is rewriting formulation development timelines across the sustained release landscape. Evonik Industries AG leverages its Resomer platform to dominate parenteral depot formulations with precise degradation kinetics. BASF SE anchors oral solid dosage supply through its Kollicoat SR portfolio, while Colorcon Inc specializes in functional film coatings that modulate drug release profiles.
Sustained release excipients comprise pharmacologically inactive substances engineered to modulate drug dissolution kinetics through controlled diffusion, erosion, or osmotic mechanisms, typically formulated as hydroxypropyl methylcellulose matrices with viscosity grades spanning 4,000 to 100,000 mPa·s or as polylactic-co-glycolic acid copolymers with lactide:glycolide ratios tuned to achieve release windows from days to months. Polymer-based excipients occupy the largest value share due to tunable mechanical properties and established regulatory pathways, while lipid-based alternatives represent the fastest-expanding category as hot-melt extrusion and self-emulsifying systems gain traction in bioavailability enhancement. Injectable delivery commands premium positioning within the delivery mode taxonomy, though oral delivery sustains the highest absolute volume given its centrality in chronic disease management.
The FDA enforces Current Good Manufacturing Practice standards through ICH Q7 and Q11 guidelines that mandate excipient quality attribute documentation, while the EMA's MDR and REACH frameworks impose substance safety and traceability obligations across European supply chains. The US Pharmacopeia and European Pharmacopoeia monographs on controlled-release functionality create compliance benchmarks that filter supplier eligibility. Stakeholders must monitor how pharmacopeial harmonization efforts and emerging continuous manufacturing guidances reshape qualification requirements for novel excipient technologies.
Market Dynamics
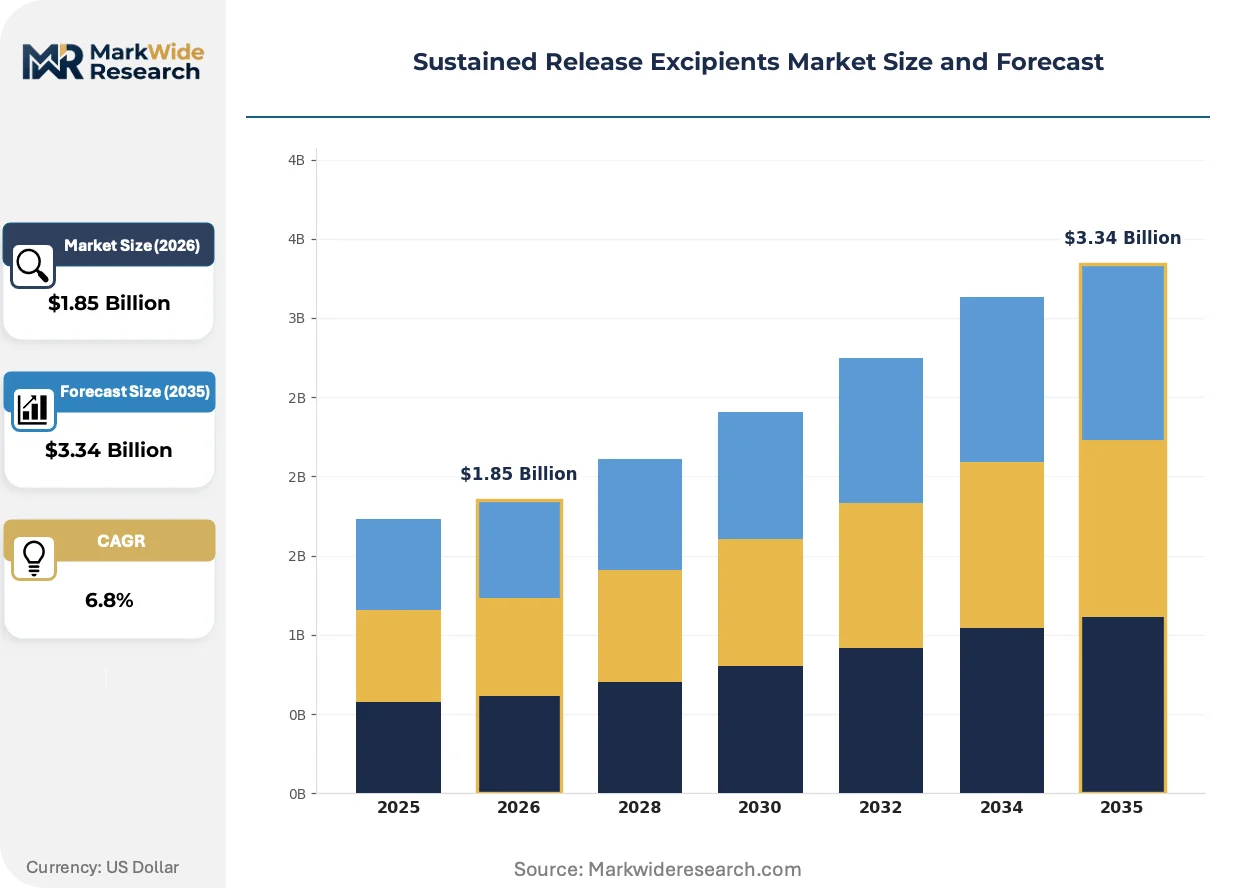
FDA's Quality by Design initiative and evolving ICH Q13 guidelines on continuous manufacturing are compressing supplier qualification timelines while elevating documentation burdens for sustained release excipient manufacturers.
Growth Catalysts
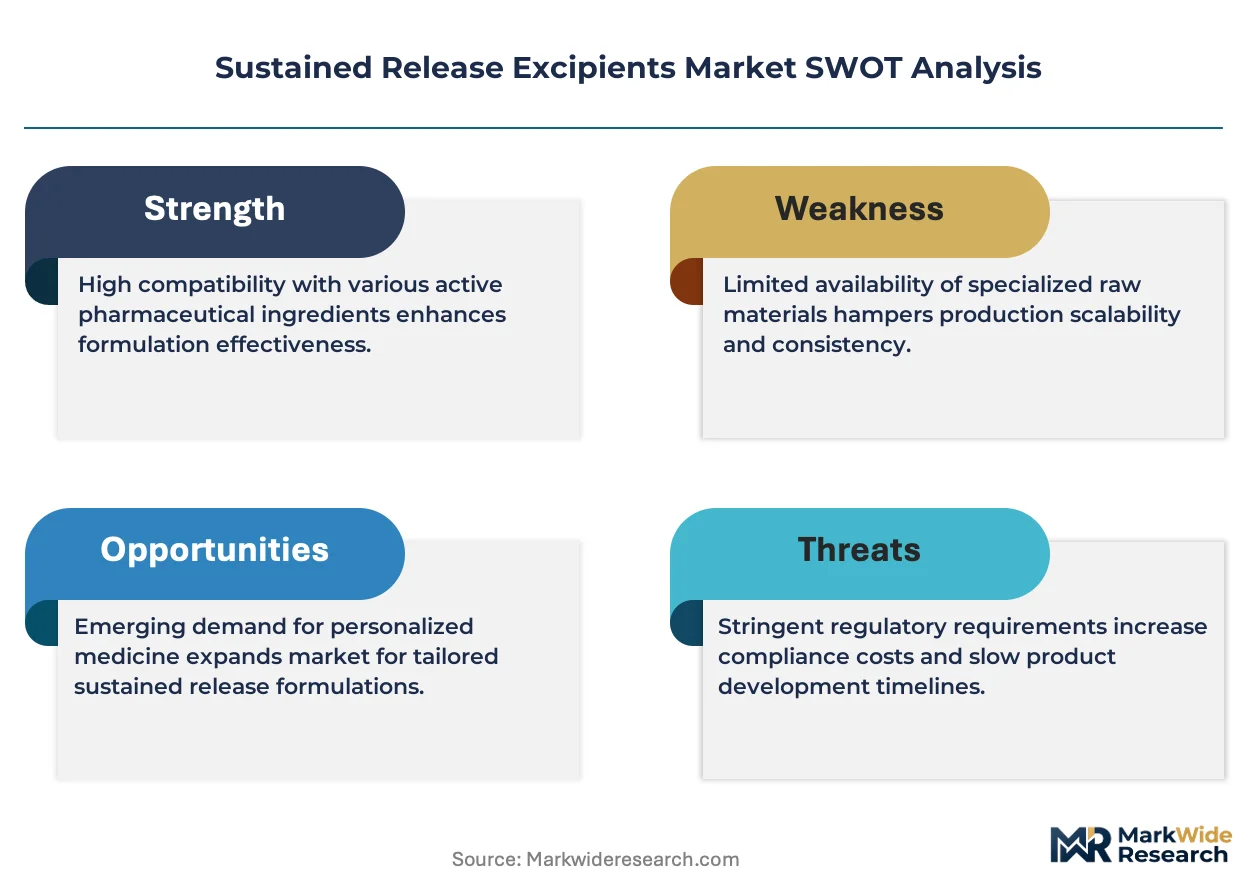
- Oncology formulation demand:Controlled-release parenteral depots improve patient compliance in chronic cancer regimens. Drug developers prioritize biodegradable matrices for multi-week dosing windows.
- REACH substance traceability:ECHA's expanded safety data requirements filter out non-compliant suppliers. European pharmaceutical procurement now mandates documented excipient quality attributes.
- Hot-melt extrusion adoption:Lipid-based systems enable bioavailability enhancement for poorly soluble APIs. Contract manufacturers invest in twin-screw processing capacity.
Market Restraints
- PLGA raw material concentration:Lactide and glycolide monomer supply concentrates among three chemical producers. Polymer manufacturers face input cost volatility from corn-based feedstock competition.
- Injectable certification timelines:USP <661.1> and <1788> compliance documentation extends supplier onboarding to 18-24 months. Generic developers delay complex product launches.
- Cellulose ether substitution pressure:Synthetic polymer alternatives offer tighter degradation control. Hydroxypropyl methylcellulose faces displacement in precision parenteral applications.
Strategic Opportunities
- Continuous manufacturing regulatory tailwind:ICH Q13 guideline implementation rewards real-time release testing adoption. Excipient suppliers embedding process analytical technology capture preferred vendor status.
- Self-emulsifying drug delivery systems:Lipid excipient blends address bioavailability challenges in oncology and CNS pipelines. Formulation houses expand hot-melt extrusion service offerings.
- India CDMO integration:Domestic pharmaceutical manufacturing under PLI schemes creates captive excipient demand. Local polymer engineering capabilities mature for oral solid dosage supply.
Industry Challenges
- Polymer rheology expertise scarcity:Formulation scientists with PLGA degradation kinetics specialization command premium compensation. Academic programs lag industrial demand for controlled-release competency.
- Multinational pharmacopeial divergence:USP, EP, and JP monograph inconsistencies force redundant stability studies. Harmonization delays extend product registration timelines.
- Legacy batch record integration:Continuous manufacturing transitions require MES overlay with existing ERP infrastructure. SME excipient producers defer digitalization investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustained Release Excipients Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-Based Excipients, Lipid-Based Excipients, Natural Excipients, Inorganic Excipients Delivery Mode: Oral Delivery, Injectable Delivery, Transdermal Delivery, Intranasal Delivery End User: Pharmaceutical Companies, Biotech Firms, Contract Manufacturers, Research Institutions Application: Cardiovascular, Oncology, Diabetes Management, CNS Disorders |
| Companies Covered | Roquette Freres, Colorcon Inc, BASF SE, Merck KGaA, Croda International Plc, Evonik Industries AG, Lubrizol Corporation, Shin Etsu Chemical Co Ltd, Ashland Global Holdings Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustained Release Excipients Market Strategic Shifts & Innovations
Digital twin technology and real-time release testing are compressing development cycles while regulatory convergence around ICH standards creates new competitive filters for excipient qualification.
Computational polymer design platforms are virtualizing traditional empirical formulation development. Large pharmaceutical developers deploy molecular dynamics simulations to predict PLGA degradation profiles before bench work. This capability collapses 12-18 month prototype cycles into 8-12 week iterations.
ICH Q13 continuous manufacturing guidelines are reshaping facility investment patterns. Real-time release testing mandates drive spectroscopic PAT sensor deployment across granulation and coating operations. Oral solid dosage manufacturers in Germany and Switzerland lead adoption, integrating excipient variability data directly into process control loops.
Integrated service contracts are displacing transactional excipient procurement. Biopharma customers demand formulation development partnerships extending from preclinical characterization through commercial scale-up. CDMOs in the United States and Ireland capture volume by bundling polymer supply with hot-melt extrusion processing capabilities.
Sustained Release Excipients Market Segmentation
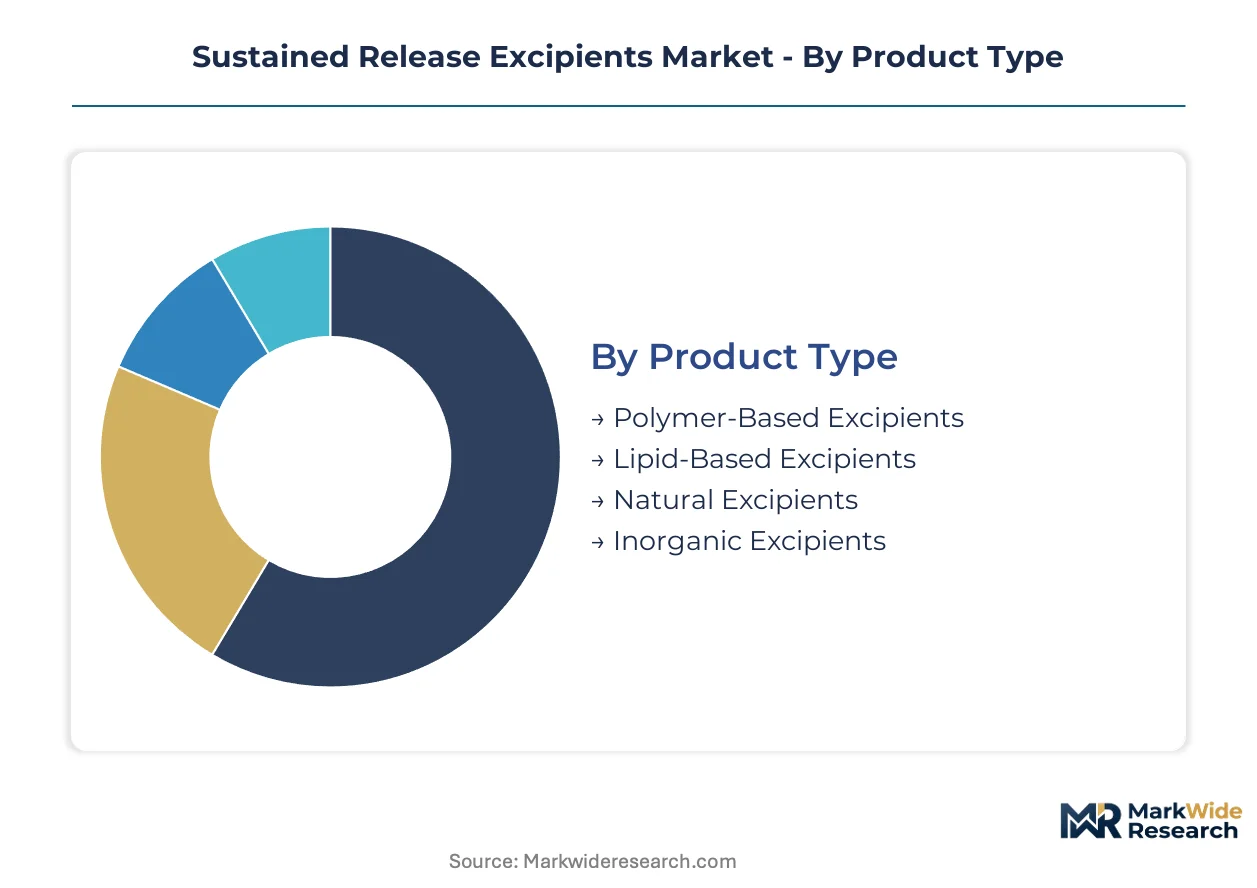
Excipient selection cascades through formulation economics, regulatory burden, and manufacturing compatibility. Segment boundaries in this market reflect technical trade-offs between release precision, scalability, and route-specific qualification requirements.
Product Type:
Polymer engineering cycles stretch across years for novel biodegradable matrices, while lipid formulation iterations compress into months for established hot-melt platforms.
- Polymer-Based Excipients:Hydroxypropyl methylcellulose and polylactic-co-glycolic acid copolymers dominate oral and parenteral depot formulations respectively. FDA's ICH Q11 quality attribute documentation requirements concentrate procurement among suppliers with established USP monograph compliance, particularly for oncology parenteral depots requiring multi-week release windows.
- Lipid-Based Excipients:Glycerides and fatty acid esters enable self-emulsifying drug delivery systems for bioavailability enhancement. Hot-melt extrusion adoption in Germany and Switzerland drives demand for lipid matrices that accommodate poorly soluble APIs in continuous manufacturing lines.
- Natural Excipients:Cellulose derivatives and chitosan offer renewable-source alternatives with established safety profiles.
- Inorganic Excipients:Calcium phosphates and silicates provide erosion-controlled release for niche oral applications.
Polymer-based excipients anchor the volume base while lipid-based alternatives gain share at the steepest rate.
Delivery Mode:
Qualification intensity separates premium-positioned injectable routes from high-throughput oral platforms, with transdermal and intranasal occupying intermediate investment tiers.
- Oral Delivery:Matrix tablets and osmotic pump systems sustain the highest absolute excipient consumption through chronic disease applications. USP <661.1> compliance documentation requirements filter supplier pools for solid dosage manufacturers serving cardiovascular and diabetes management segments.
- Injectable Delivery:Parenteral depots command premium excipient positioning through biodegradable polymer requirements. PLGA degradation kinetics specialization concentrates among polymer engineers serving oncology developers in the United States and Ireland.
- Transdermal Delivery:Pressure-sensitive adhesives and rate-controlling membranes serve hormone replacement and pain management patches.
- Intranasal Delivery:Mucoadhesive polymers and absorption enhancers address CNS drug delivery through the olfactory pathway.
Oral delivery sustains the largest installed base while injectable delivery commands the highest value per kilogram.
End User:
Internal formulation capabilities versus externalized manufacturing determine excipient procurement sophistication and partnership depth.
- Pharmaceutical Companies:Integrated R&D-to-commercial organizations drive excipient co-development partnerships. Large developers in the United States embed polymer suppliers into Quality by Design workflows for oncology and CNS pipelines.
- Biotech Firms:Asset-focused developers prioritize speed-to-IND over excipient customization, favoring catalog offerings with established DMFs.
- Contract Manufacturers:CDMOs in India and Ireland bundle excipient supply with formulation services to capture integrated contracts.
- Research Institutions:Academic and government labs drive early-stage polymer innovation with limited commercial procurement volume.
Pharmaceutical companies dominate premium formulation development while contract manufacturers expand fastest through outsourcing trends.
Application:
Therapeutic area-specific release requirements create divergent excipient performance specifications and regulatory scrutiny levels.
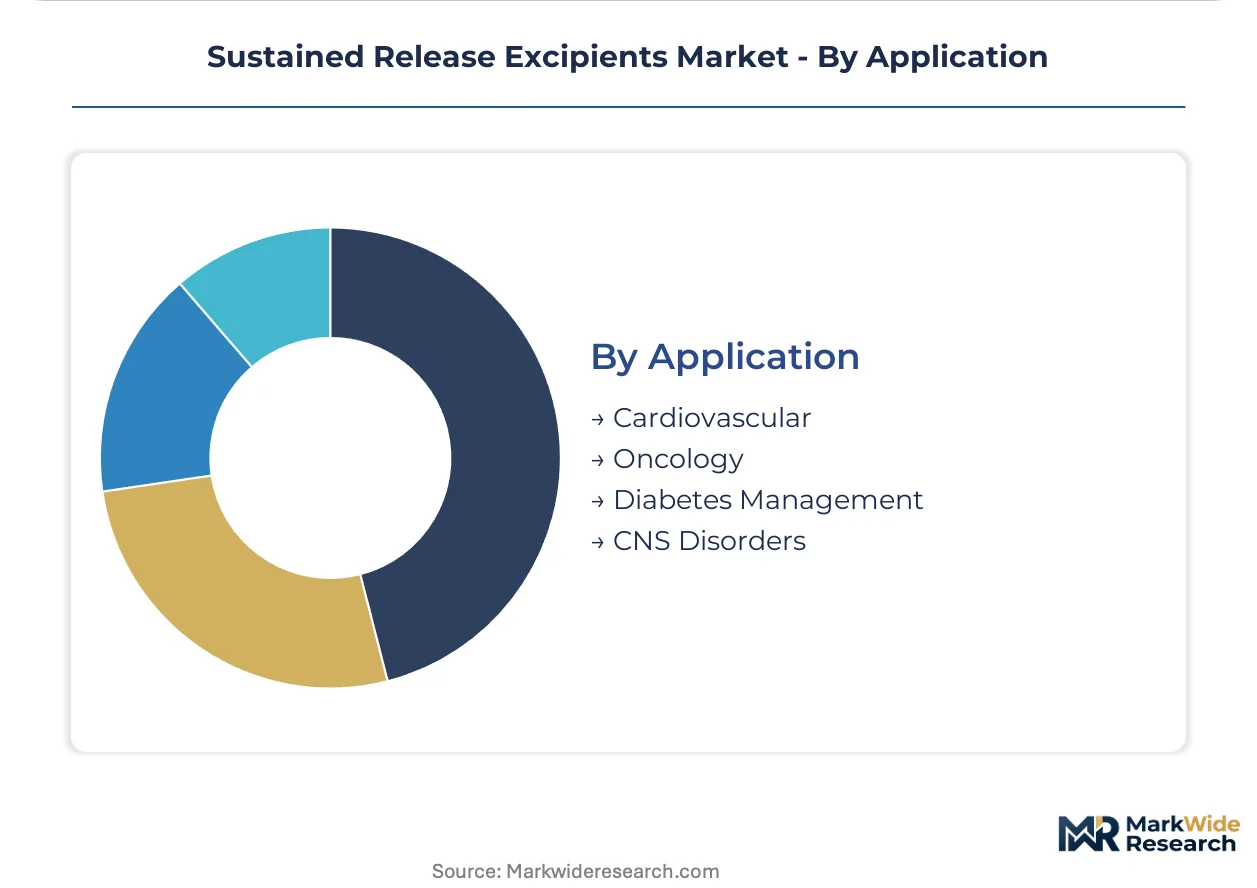
- Oncology:Controlled-release parenteral depots require biodegradable matrices with precisely tuned degradation kinetics. FDA's emphasis on patient compliance in chronic cancer regimens drives multi-week dosing formulation investment.
- Cardiovascular:Oral sustained-release platforms for antihypertensives and antiarrhythmics sustain mature excipient demand with established HPMC matrix specifications.
- Diabetes Management:GLP-1 agonist depot formulations and oral insulin delivery systems create emerging excipient requirements.
- CNS Disorders:Blood-brain barrier penetration challenges drive lipid-based and intranasal excipient innovation for neurodegenerative and psychiatric indications.
Cardiovascular applications provide the stable demand foundation while oncology applications expand most quickly through parenteral depot adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports sustained release excipients to pharmaceutical manufacturers across Ireland and Switzerland, while the United States supplies parenteral depot formulations to oncology developers in the United Kingdom.
United States
Specialty pharmaceutical investment and complex generic development drive excipient procurement in chronic disease management. FDA's Quality by Design initiative compresses supplier qualification timelines while elevating documentation burdens. The Greater Boston biotech cluster anchors parenteral depot formulation partnerships with polymer engineering specialists.
Germany
Hot-melt extrusion adoption and continuous manufacturing leadership create demand for lipid-based excipient systems. ECHA's REACH substance traceability requirements filter non-compliant suppliers from European procurement pools. The Rhine-Ruhr industrial corridor concentrates oral solid dosage manufacturing with integrated PAT sensor deployment.
India
Domestic pharmaceutical manufacturing under PLI schemes generates captive excipient demand for oral solid dosage supply. CDSCO's evolving quality standards align with ICH guidelines for excipient documentation. The Hyderabad-Visakhapatnam corridor matures local polymer engineering capabilities for contract manufacturing exports.
Switzerland
Precision parenteral applications and oncology formulation partnerships command premium excipient positioning. Swissmedic's regulatory convergence with EMA standards streamlines multi-market registrations. The Basel-Zurich biopharma cluster integrates excipient suppliers into early-stage formulation development workflows.
Ireland
CDMO expansion and integrated service contracts drive excipient procurement for biopharma customers. EMA's MDR framework imposes substance safety obligations across formulation supply chains. The Dublin-Cork pharmaceutical belt bundles polymer supply with commercial scale-up capabilities for North American clients.
Sustained Release Excipients Market Key Industry Players
On the supply side, the industry is consolidating around three to five integrated chemical conglomerates with polymer engineering depth, while specialty coating and lipid formulation houses occupy differentiated niches. Strategic archetypes span diversified chemical majors with pharmaceutical divisions, pure-play excipient specialists with film-coating expertise, and Japanese chemical conglomerates with cellulose ether portfolios. Competitive moves concentrate on backward integration into lactide and glycolide monomer supply, plus capacity expansion for continuous manufacturing-compatible excipient grades.
Within the diversified chemical major tier, BASF SE and Evonik Industries AG exemplify integrated supply positions spanning polymer synthesis through formulation partnerships. Colorcon Inc occupies the functional film-coating specialist archetype. These three anchors represent distinct competitive vectors: European chemical conglomerates with pharmaceutical-grade polymer platforms, and US-based coating technology specialists with modulated release expertise.
| Leading Market Players |
|---|
| Roquette Freres |
| Colorcon Inc |
| BASF SE |
| Merck KGaA |
| Croda International Plc |
| Evonik Industries AG |
| Lubrizol Corporation |
| Shin Etsu Chemical Co Ltd |
| Ashland Global Holdings Inc |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Chinese lactide monomer supply determines both pricing tier spreads and supply chain shape across the sustained release excipients landscape. Corn-based feedstock competition for PLGA precursors compresses margins at the polymer synthesis tier while elevating premiums for qualified parenteral-grade suppliers.
Pricing Analysis
Current-generation HPMC matrices trade at substantial discounts to next-generation PLGA copolymers with precision-tuned degradation kinetics. Pricing stratifies across parenteral-grade certification, oral solid dosage standard, and economy-tier cellulose ether tiers, with USP <661.1> compliance and DMF documentation driving 40-60% spreads between adjacent tiers. Cost compression in oral solid dosage grades is intensifying as Indian CDMOs expand captive polymer engineering capabilities. Generic developers exhibit highest price sensitivity, while oncology-focused biotech firms prioritize release precision over unit economics.
Supply Chain Analysis
Contract manufacturing concentration at Catalent, Lonza, and Thermo Fisher Scientific's Patheon division anchors downstream formulation capacity. Lactide and glycolide monomer production concentrates in China, Germany, and the United States, while polymer synthesis capabilities cluster in the United States, Ireland, and Switzerland. Raw material sourcing draws from corn-derived feedstocks, petroleum-based glycolide precursors, and cellulose pulp supply. Single-source vulnerability at the monomer tier exposes polymer manufacturers to input cost volatility. Distribution runs through qualified supplier programs directly to pharmaceutical R&D and manufacturing sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic polymer alternatives threaten displacement of established cellulose ether matrices, forcing incumbents to defend formulation partnerships through performance differentiation.
For Market Incumbents: Build regulatory documentation moats by embedding USP and EP monograph compliance into customer Quality by Design workflows. Deepen captive supply of lactide and glycolide monomers through backward integration or long-term offtake agreements with Chinese chemical producers. Expand hot-melt extrusion service capabilities to capture integrated formulation contracts from biotech developers. For New Entrants and Emerging Players: Establish a beachhead in lipid-based excipient supply for self-emulsifying drug delivery systems, where formulation expertise barriers remain lower than polymer engineering. Target Indian CDMO integration under PLI schemes, where domestic pharmaceutical manufacturing generates captive demand for oral solid dosage excipients. Lead with continuous manufacturing-compatible excipient grades and embedded PAT sensor compatibility. For Investors and Strategic Acquirers: ICH Q13 continuous manufacturing guideline implementation reshapes the acquisition landscape by rewarding excipient suppliers with real-time release testing capabilities. Five-to-ten-year viability favors polymer engineering specialists with established parenteral depot partnerships over commodity cellulose ether producers. Target acquisition archetype: mid-cap excipient houses with PLGA degradation kinetics expertise and oncology customer concentration. Monitor FDA draft guidances on continuous manufacturing as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive lactide and glycolide sourcing insulates polymer manufacturers from corn feedstock price volatility. |
| Continuous Manufacturing Grade Development | ICH Q13-compliant excipient specifications capture preferred vendor status at oral solid dosage manufacturers. |
| Integrated Formulation Service Expansion | Hot-melt extrusion bundling with polymer supply deepens CDMO customer lock-in. |
| DMF Documentation Investment | FDA master file establishment accelerates generic developer supplier qualification timelines. |
| PAT Sensor Compatibility Embedding | Spectroscopic process analytical technology integration enables real-time release testing adoption. |
Research Approach
The analysis maps polymer-based, lipid-based, natural, and inorganic excipient sub-sectors, each validated through formulation scientists, regulatory affairs directors, CDMO procurement managers, and polymer engineering specialists. Primary interviews with excipient manufacturers and pharmaceutical developers combined with secondary validation from FDA filings, EMA submissions, USP monograph databases, and ICH guideline documentation. Bottom-up excipient consumption modeling triangulated against top-down pharmaceutical formulation spend estimates.
Assumption sets held regulatory convergence and continuous manufacturing adoption rates fixed while varying oncology pipeline expansion and generic complex product launch timelines across the projection horizon. Segmentation dimensions modeled include excipient chemistry class, delivery mode, therapeutic application, end-user organizational type, and regional regulatory cluster. CAGRs derived from regression analysis of historical pharmaceutical excipient procurement patterns against formulation development pipeline indicators, with PLGA degradation kinetics specialization and lipid-based bioavailability enhancement serving as industry-specific demand drivers.
Sensitivities concentrate around FDA continuous manufacturing guidance finalization, REACH substance traceability enforcement intensity, and PLGA monomer supply disruption scenarios. Forecasts reflect assumptions regarding ICH Q13 implementation pace and oncology parenteral depot formulation success rates. Quarterly review of CDER guidance releases, ECHA substance restriction proposals, and Indian PLI scheme excipient localization metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
China Food Acidulants Market
Food Additives and Ingredients
India Food Colorants Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
Carrageenan Market
Food Additives and Ingredients
Egypt Feed Additives Market
Food Additives and Ingredients
Europe Food Additives Market
Food Additives and Ingredients
South America Brewing Enzymes Market
Food Additives and Ingredients
Russia Feed Additives Market
Food Additives and Ingredients
Food Emulsifiers Market
Food Additives and Ingredients
Nanoencapsulated Food Additives Market
Food Additives and Ingredients
Bakery Enzymes Market
Food Additives and Ingredients
Food Preservatives Market
Food Additives and Ingredients
North America Microencapsulation Market
Food Additives and Ingredients
Sunset Yellow FCF Market
Food Additives and Ingredients
Wine Fining Agent Market