
 Carrageenan Market | 2026-2036
Carrageenan Market Size, Share, and Industry Trends Forecast 2026-2036
Carrageenan Market Analysis
The capital-intensity divergence between integrated seaweed cultivators and standalone extractors is unwinding competitive stability in the carrageenan supply base. Cargill leverages its backward integration into Philippine seaweed farming to secure raw material throughput. CP Kelco anchors its position through specialized R&D in refined kappa and iota carrageenan grades for dairy applications. MCPI Corporation dominates regional supply chains across Southeast Asian processing corridors.
Carrageenan comprises sulfated linear polysaccharides extracted primarily from red algae of the Rhodophyceae class, with kappa, iota, and lambda variants distinguished by their sulfate ester content and calcium sensitivity. Food Grade carrageenan sustains the largest value pool through its functional role as a gelling and stabilizing agent in processed dairy and meat systems. Pharmaceutical Grade material registers the fastest structural expansion as oral-dosage and controlled-release applications multiply. Powdered form occupies the dominant share of commercial transactions due to handling efficiency and dissolution control in industrial batching.
The FDA maintains food-additive safety standards under 21 CFR 172.620 while the EU EFSA evaluates carrageenan through its food-additive reauthorization process, with both frameworks shaping permissible applications and purity thresholds. ISO 9001 and HACCP certification requirements from Philippine and Indonesian export authorities govern market access for seaweed-derived hydrocolloids. Stakeholders must monitor evolving clean-label sentiment and regional substitution threats from locust bean gum and gellan gum to calibrate portfolio positioning.
Market Dynamics
The EU F-Gas Regulation and EU Green Deal are tightening environmental compliance requirements for seaweed processing operations, forcing extraction facilities to retrofit energy-intensive alkali treatment systems and wastewater management infrastructure.
Growth Catalysts
- Plant-based dairy alternatives:Food manufacturers are reformulating oat, almond, and coconut milk systems with kappa carrageenan to replicate mouthfeel and suspension stability previously delivered by dairy proteins.
- EU EFSA food-additive reauthorization:The ongoing safety review process is consolidating permissible applications and purity thresholds, directing investment toward pharmaceutical-grade refinement capabilities.
- Philippine seaweed farming clusters:Tropical cultivation infrastructure in the Sulu Sea and Tawi-Tawi provinces is expanding raw material throughput for integrated processors.
Market Restraints
- Potassium chloride and calcium hydroxide input volatility:Alkali reagent costs fluctuate with chlor-alkali plant capacity utilization and regional energy pricing, compressing margin stability for standalone extractors.
- Seaweed supply concentration:Raw material procurement depends on Philippine and Indonesian coastal farming cooperatives, exposing processors to climate-driven harvest variability and logistics bottlenecks.
- Locust bean gum substitution:Clean-label formulators are displacing carrageenan in premium dairy applications where "seaweed-derived" positioning carries negative perception baggage.
Strategic Opportunities
- Controlled-release pharmaceutical applications:Oral-dosage tablet binders and sustained-release matrices are opening specification windows for ultra-pure iota carrageenan with defined sulfate ester profiles.
- EU Green Deal retrofit incentives:Seaweed processors can access transition financing for closed-loop water recovery and biomass cogeneration systems that reduce Scope 2 emissions intensity.
- Direct-to-manufacturer distribution platforms:Specialty hydrocolloid marketplaces are compressing traditional distributor markups and enabling smaller food tech startups to access technical-grade materials at pilot scale.
Industry Challenges
- ISO 9001 and HACCP certification timelines:Philippine and Indonesian export authorities require extensive documentation for seaweed-derived hydrocolloid market access, delaying facility commissioning by 8-14 months.
- Refined-grade process engineering expertise:The talent pool for alkali modification and selective precipitation optimization is concentrated among legacy European and Japanese extraction specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carrageenan Market |
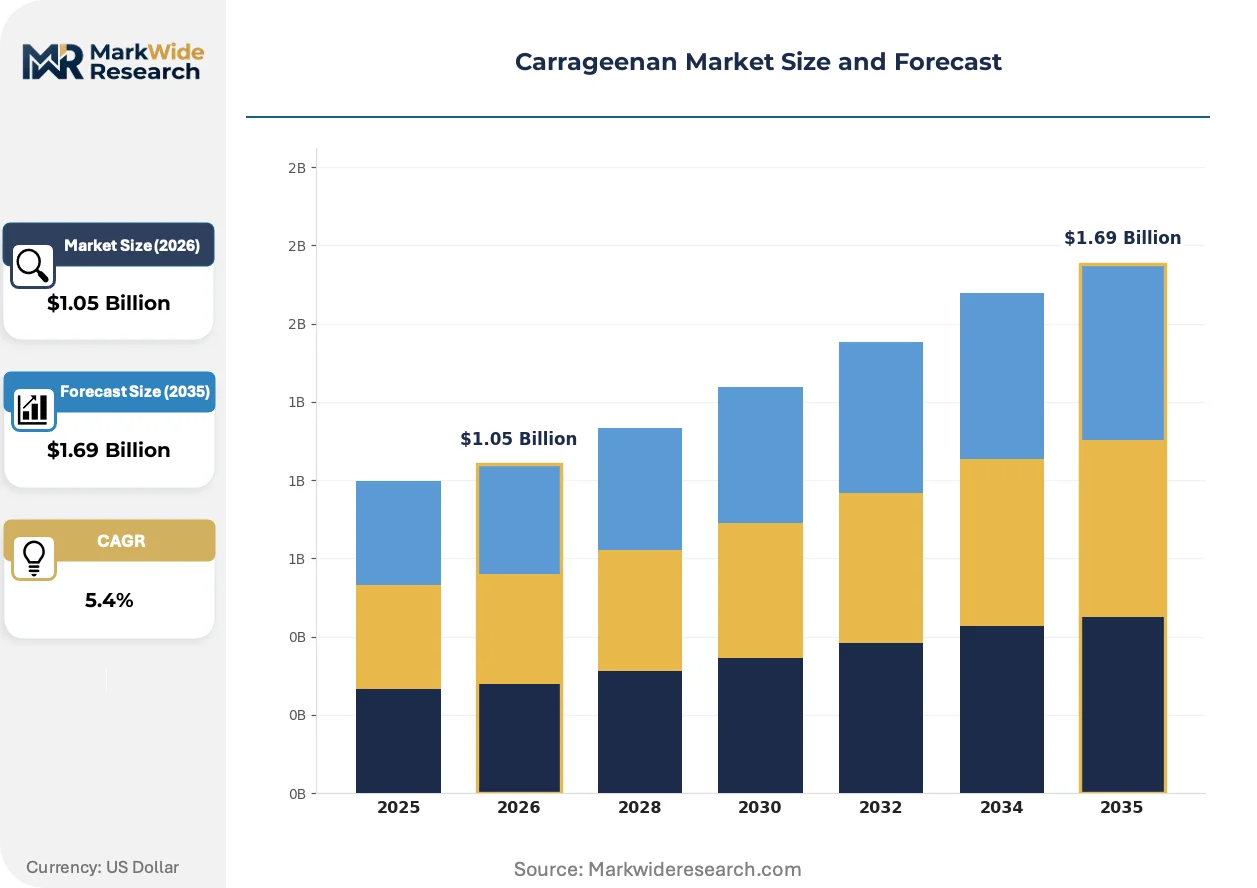
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.69 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Nutraceutical Grade Application: Dairy Products, Meat Products, Beverages, Personal Care End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Beverage Producers Form: Powdered, Flaked, Granular, Gelled |
| Companies Covered | Cargill, MCPI Corporation, CP Kelco, TBK Manufacturing Corporation, Gelymar S.A., DuPont, Ashland, CEAMSA, Ingredion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carrageenan Market Emerging Trajectories
Clean-label reformulation pressures and pharmaceutical-grade specification expansion are redirecting R&D investment toward precision sulfation control and solvent-free extraction pathways.
Enzymatic extraction protocols are miniaturizing. Biocatalytic cell-wall disruption using engineered hydrolases reduces alkali consumption and thermal energy inputs compared to conventional hot-water extraction. Specialty chemical suppliers are licensing these processes to mid-scale Philippine processors seeking EU EFSA compliance without capital-intensive infrastructure rebuilds. The technology is compressing the capital barrier between food-grade and pharmaceutical-grade production tiers.
REACH and F-Gas Regulation alignment is reshaping solvent recovery mandates. European extraction facilities must demonstrate closed-loop methanol and isopropanol recovery rates above 98.5% to maintain operating permits. German and Dutch processors are investing in membrane separation and adsorption regeneration systems. Pharmaceutical-grade material manufactured under these constraints commands specification premiums in oral-dosage applications.
Formulation laboratories are unbundling technical service from material supply. Food manufacturers previously relied on carrageenan suppliers for application development support; now they retain independent hydrocolloid consultants and purchase commoditized powders through digital procurement platforms. This pattern is most visible in North American plant-based dairy startups where speed-to-market priorities override traditional supplier relationships.
Carrageenan Market Segmentation
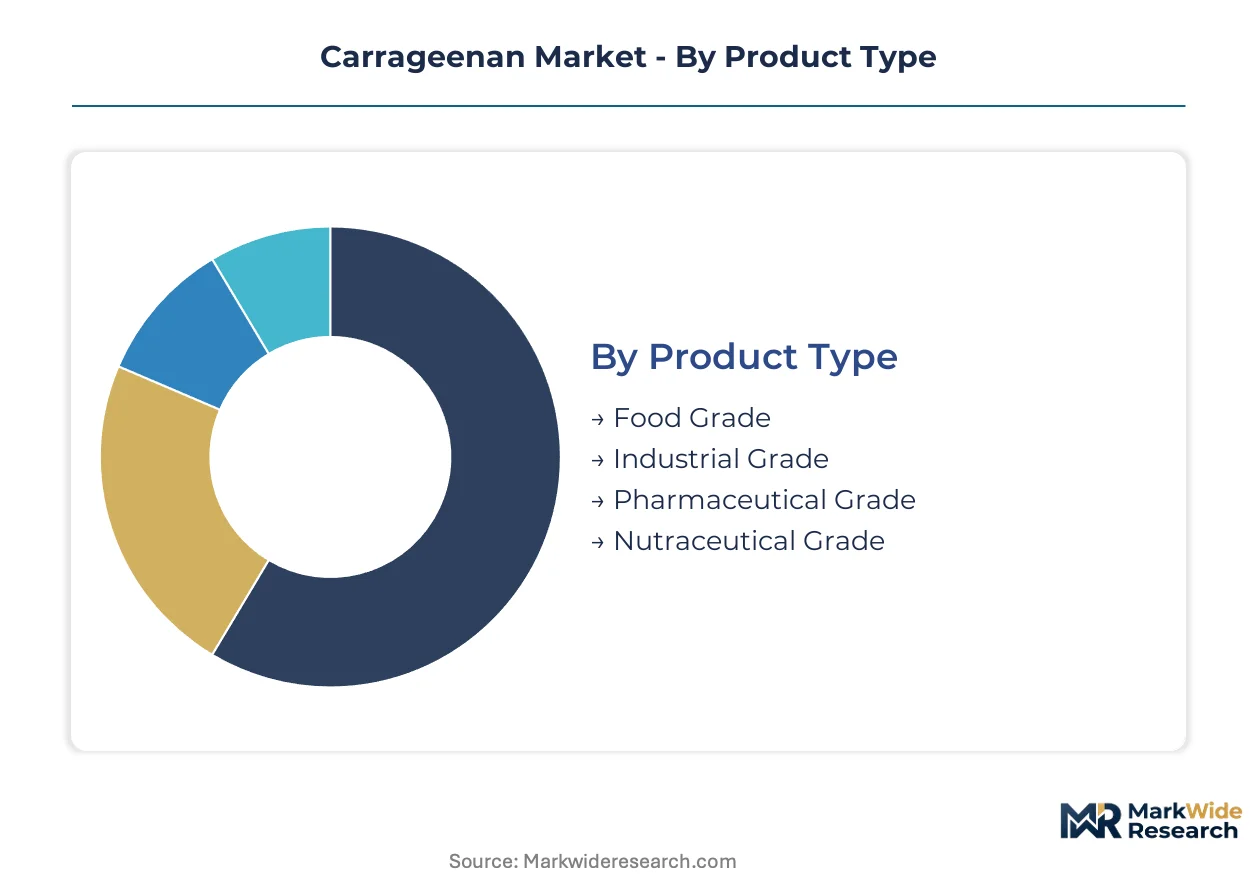
Carrageenan procurement patterns diverge sharply between commodity food systems and specification-driven pharmaceutical applications. Understanding these segment boundaries clarifies where margin pools concentrate and where substitution threats loom largest.
Product Type:
Food Grade dominates domestic consumption across North American and European dairy corridors, while Pharmaceutical Grade exports concentrate toward German and Japanese formulation facilities.
- Food Grade:Standardized sulfated polysaccharide extracts meeting FDA 21 CFR 172.620 and EFSA purity thresholds for processed dairy and meat suspension systems. Demand clusters in US Midwest dairy processing belts and French cheese manufacturing regions, with procurement volume tied to plant-based milk reformulation cycles.
- Pharmaceutical Grade:Ultra-pure kappa and iota variants with defined sulfate ester profiles below 0.1% residual protein. Japanese PMDA and German BfArM certification requirements are concentrating production investment in Dutch and Irish extraction facilities with closed-loop solvent recovery.
- Industrial Grade:Lower-purity material for textile sizing and printing paste applications, sourced primarily from Indonesian coastal processors.
- Nutraceutical Grade:Semi-refined extracts for dietary supplement gelling, positioned between food and pharmaceutical specification tiers.
Food Grade holds the largest share; momentum sits with Pharmaceutical Grade.
Application:
Cost tier segmentation separates high-volume dairy stabilizers from premium personal care emulsifiers where formulation flexibility commands price premiums.
- Dairy Products:Kappa carrageenan forms thermoreversible gels with potassium ions, delivering mouthfeel replication in oat and almond milk systems. US plant-based dairy startups in California and New York metro areas are expanding specification orders for organic-certified variants.
- Meat Products:Water-binding and sliceability retention in processed poultry and surimi applications, with volume demand anchored in Brazilian and Thai export-oriented processing plants.
- Beverages:Suspension stability for cocoa and pulp particulates, concentrated in Mexican and Nigerian ready-to-drink manufacturing corridors.
- Personal Care:Lambda carrageenan serves as a non-ionic thickener in toothpaste and lotion emulsions, with formulation development concentrated in French and South Korean cosmetic laboratories.
Dairy Products commands the dominant revenue pool; Beverages is expanding most quickly as pulp suspension applications multiply in tropical markets.
End User:
Customer type determines contract structure, with multinational food manufacturers locking in annual volume agreements while pharmaceutical firms purchase on specification-certified spot markets.
- Food Manufacturers:Integrated dairy and meat processors procuring standardized powders through distributor networks, with technical service expectations declining as independent hydrocolloid consultants displace supplier-led formulation support.
- Cosmetic Companies:Specialty chemical divisions of L'Oréal and Kao Group sourcing lambda grades for emulsion stability, prioritizing REACH-compliant documentation and batch-to-batch viscosity consistency.
- Pharmaceutical Firms:Oral-dosage and controlled-release specialists requiring EMA and PMDA Drug Master File submissions, with procurement concentrated among German, Swiss, and Japanese generics manufacturers.
- Beverage Producers:Carbonated soft drink and ready-to-drink coffee formulators purchasing flaked carrageenan for rapid-hydration batching systems.
Food Manufacturers represent the largest contract volume; Pharmaceutical Firms show the steepest specification premium expansion.
Form:
Handling efficiency and dissolution kinetics separate industrial batching preferences from pharmaceutical precision requirements.
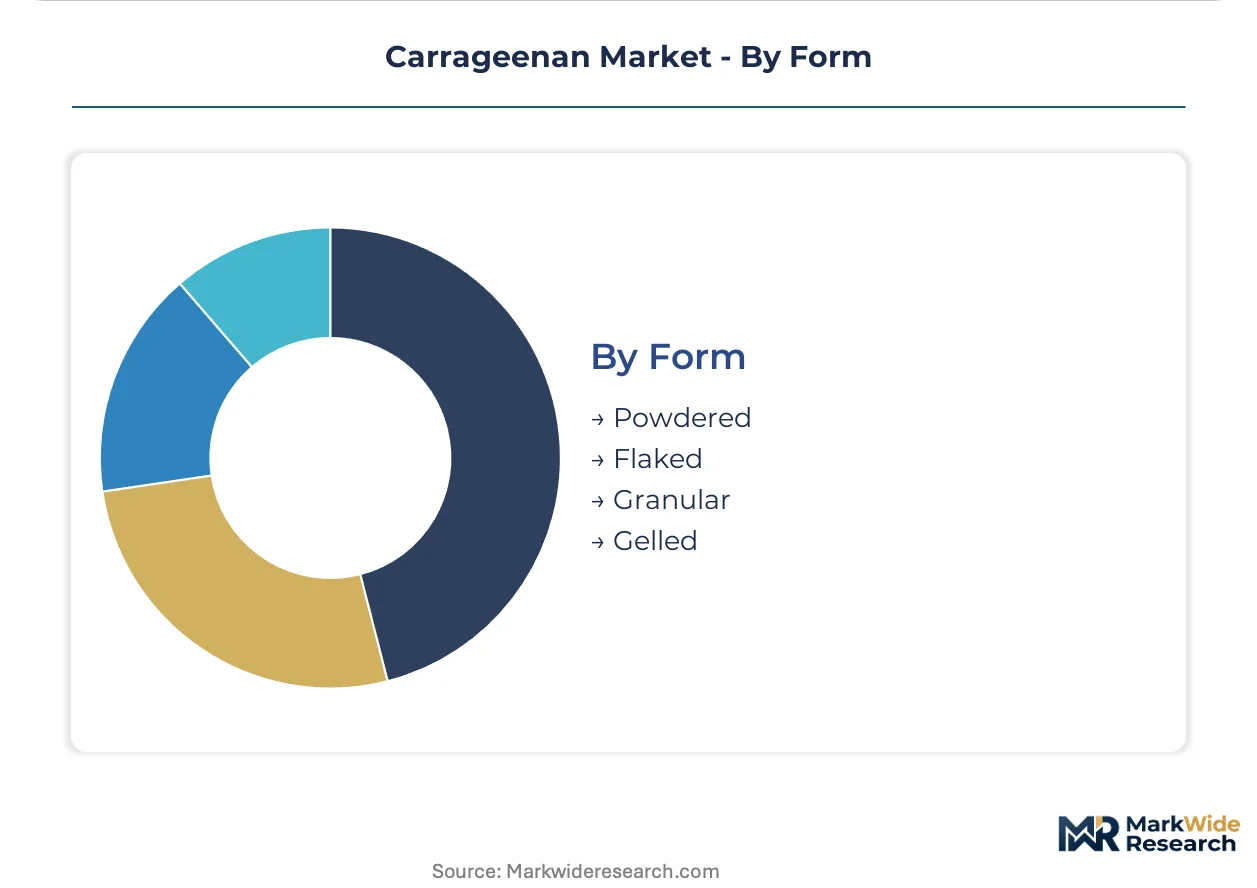
- Powdered:Spray-dried material with controlled particle size distribution for dust-free conveying and predictable hydration rates. Dominates commercial transactions across US and European dairy processing infrastructure.
- Flaked:Drum-dried sheets for rapid dissolution in high-shear beverage batching, preferred by Mexican and Southeast Asian juice processors.
- Granular:Agglomerated particles reducing airborne dust during pneumatic conveying, adopted by mid-scale Philippine processors seeking EU export compliance.
- Gelled:Pre-hydrated blocks for direct incorporation into meat emulsion systems, concentrated in Brazilian poultry processing plants.
Powdered form holds the largest share; granular agglomeration technology is gaining share fastest as dust-control regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are redirecting carrageenan trade flows, with Philippine raw material dominance contrasting against European pharmaceutical-grade processing demand and North American plant-based dairy formulation requirements.
Philippines
Tropical seaweed farming in the Sulu Sea and Tawi-Tawi provinces supplies the majority of global raw material throughput. Bureau of Fisheries and Aquatic Resources licensing governs coastal cultivation cooperatives. Davao del Sur processing corridors are expanding alkali treatment capacity to serve integrated extractors.
Germany
Pharmaceutical-grade refinement demand from BfArM-certified generics manufacturers drives specification premiums. REACH compliance mandates closed-loop solvent recovery rates above 98.5% for operating permits. Hamburg and Dutch border extraction facilities are investing in membrane separation systems.
United States
Plant-based dairy startups in California and New York metro areas are expanding organic-certified kappa carrageenan procurement. FDA 21 CFR 172.620 governs food-additive safety standards for processed dairy applications. Midwest dairy processing belts maintain standardized powder demand through distributor networks.
Indonesia
Coastal farming cooperatives in Sulawesi and Nusa Tenggara provide semi-refined material for regional processors. Indonesian export authorities require ISO 9001 and HACCP certification documentation, delaying facility commissioning timelines. Surabaya processing clusters serve textile sizing and industrial grade markets.
Japan
PMDA certification requirements for oral-dosage applications concentrate pharmaceutical-grade import demand. Japanese cosmetics laboratories source lambda grades for toothpaste and lotion emulsion stability. Osaka formulation facilities prioritize batch-to-batch viscosity consistency from REACH-compliant European suppliers.
Carrageenan Market Vendor Landscape
Concentration sits with integrated seaweed cultivators and specialized hydrocolloid refiners. The supply base exhibits tiered structure, with backward-integrated Philippine processors commanding raw material security against standalone extractors facing margin compression. Three archetypes dominate: tropical farming-integrated processors, European pharmaceutical-grade specialists, and diversified food-ingredient conglomerates. Competitive moves center on alkali treatment capacity expansion and enzymatic extraction technology licensing.
Within the integrated cultivation tier, Cargill exemplifies backward integration into Philippine seaweed farming. CP Kelco occupies a position as a specialized refiner of kappa and iota grades. MCPI Corporation anchors regional supply chain coordination across Southeast Asian processing corridors.
| Leading Market Players |
|---|
| Cargill |
| MCPI Corporation |
| CP Kelco |
| TBK Manufacturing Corporation |
| Gelymar S.A. |
| DuPont |
| Ashland |
| CEAMSA |
| Ingredion |
| Others |
Supply Flow & Price Mechanics
ISO 9001 and HACCP certification requirements from Philippine and Indonesian export authorities simultaneously gate facility commissioning timelines and stratify price premiums between qualified and non-qualified supply tiers. Pharmaceutical-grade material commands specification premiums that food-grade processors cannot access without alkali treatment retrofits and closed-loop solvent recovery investments.
Pricing Analysis
Configured-to-order pricing for pharmaceutical-grade iota carrageenan with defined sulfate ester profiles spreads 40-60% above standard food-grade powder quotations. Three-tier pricing structure across pharmaceutical, food, and industrial grades anchors differentiation on certification level and residual protein thresholds. Pricing pressure stems from locust bean gum substitution in premium dairy applications where clean-label positioning overrides functional performance. Food manufacturers exhibit highest price sensitivity, while pharmaceutical firms purchasing on specification-certified spot markets absorb premium spreads for EMA and PMDA Drug Master File compliance.
Supply Chain Analysis
Inventory cycles stretch 8-14 months for Philippine and Indonesian processors awaiting export authority documentation, compressing working capital efficiency for standalone extractors. Raw material procurement draws from Sulu Sea and Tawi-Tawi farming cooperatives, with alkali reagent supply tethered to chlor-alkali plant capacity in Northeast Asia. Single-source vulnerability concentrates in tropical seaweed harvests exposed to climate-driven variability. Distribution runs through specialty hydrocolloid marketplaces that compress traditional distributor markups and enable direct-to-manufacturer procurement for food tech startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives against locust bean gum displacement in clean-label dairy formulations, requiring portfolio repositioning that separates functional performance claims from negative perception baggage.
For Market Incumbents: Shield food-grade margin pools by accelerating enzymatic extraction licensing to mid-scale Philippine processors seeking EU EFSA compliance without capital-intensive infrastructure rebuilds. Backward integration into seaweed farming secures raw material throughput against climate-driven harvest volatility. Defensive patent filings around precision sulfation control protect specification windows for oral-dosage applications where Japanese PMDA and German BfArM certification requirements concentrate demand.
For New Entrants and Emerging Players: Lead with pharmaceutical-grade refinement capabilities targeting German and Swiss generics manufacturers requiring closed-loop solvent recovery documentation. White-space concentration sits with controlled-release matrix applications for oral-dosage tablet binders where ultra-pure iota carrageenan with defined sulfate ester profiles commands specification premiums. Direct-to-manufacturer distribution platforms offer go-to-market compression for technical-grade materials at pilot scale.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Philippine processors holding Bureau of Fisheries and Aquatic Resources licenses but lacking alkali modification expertise. Long-term viability across the analysis window hinges on EU Green Deal retrofit completion and REACH alignment for methanol recovery rates above 98.5%. The signal to watch is enzymatic extraction technology adoption velocity among mid-scale processors seeking tier migration without infrastructure rebuilds.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Farming | Cargill's Philippine cultivation control secures raw material throughput against climate-driven harvest variability. |
| Enzymatic Extraction Technology Licensing | Biocatalytic cell-wall disruption reduces alkali consumption for mid-scale processors seeking EU EFSA compliance. |
| Pharmaceutical-Grade Refinement Capacity Expansion | Dutch and Irish facilities with closed-loop solvent recovery capture Japanese PMDA certification premiums. |
| Direct-to-Manufacturer Distribution Platform | Specialty hydrocolloid marketplaces compress distributor markups for North American plant-based dairy startups. |
| EU Green Deal Retrofit Investment | Closed-loop water recovery and biomass cogeneration systems reduce Scope 2 emissions intensity for operating permit maintenance. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across extraction facility engineering, seaweed farming cooperative management, food manufacturer procurement, and pharmaceutical formulation development. Primary interviews with alkali treatment specialists, hydrocolloid application consultants, and EU regulatory affairs leads combined with secondary validation from FDA 21 CFR filings, EFSA food-additive reauthorization documentation, Philippine Bureau of Fisheries licensing records, and customs trade data for seaweed-derived hydrocolloids. Bottom-up volume builds across grade tiers, applications, and end-user segments triangulated against top-down macroeconomic drivers and regulatory framework shifts.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product grade tier, end-use application, customer type contract structure, and regional production hub configuration. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and substitution threat velocity. Forecast inputs incorporated EU F-Gas Regulation compliance timelines, enzymatic extraction technology adoption curves, and plant-based dairy reformulation cycle intensity.
Underlying assumptions cover sustained Philippine and Indonesian raw material dominance, alkali reagent cost stability, and clean-label sentiment trajectory, with deviation risk concentrated in climate-driven harvest variability and locust bean gum substitution acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Tara Gum Market
Food Additives and Ingredients
Titanium-Free Food Color Alternatives Market
Food Additives and Ingredients
Food and Beverage Additives Market
Food Additives and Ingredients
Natural Ferulic Acid Market
Food Additives and Ingredients
Italy Food Additives Market
Food Additives and Ingredients
Global Organic Food Preservatives Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
Food Glazing Agents Market
Food Additives and Ingredients
Global Cereal Ingredients Market
Food Additives and Ingredients
Global Food Anti Caking Agents Market
Food Additives and Ingredients
Meat Tenderizing Agents Market
Food Additives and Ingredients
Mexico Food Preservatives Market
Food Additives and Ingredients
Dairy Starter Culture Market
Food Additives and Ingredients
Monostarch Phosphate Market
Food Additives and Ingredients
Natural Solubilizers Market
Food Additives and Ingredients
Fat Replacers Salt Reducers and Replacers Market