
 Egypt Feed Additives Market | 2026-2036
Egypt Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Feed Additives Market Foresight
Market Context with Strategic Players
Egypt's updated feed safety regulations are decoupling market access from traditional import dependency, forcing new compliance investments across the value chain. Cargill, Incorporated leverages its Alexandria port terminal and local blending capacity to sustain a dominant position in imported vitamin premixes. DSM-Firmenich anchors its Egyptian presence through technical service partnerships with large poultry integrators, while Adisseo France SAS competes aggressively on methionine pricing to extend its share among independent feed mills. Evonik Industries AG differentiates through its amino acid portfolio and localized quality certification programs.
Technical Definition and Structural Segments
Feed additives are biologically active or chemically functional substances incorporated into animal diets at inclusion rates typically below one percent to enhance nutrient utilization, preserve feed integrity, or support physiological performance. These formulations range from organic acidifiers with defined pH-lowering capacity to multi-enzyme complexes targeting specific anti-nutritional factors in soybean and sorghum-based rations common across Egyptian livestock systems. Enzymes command the fastest expansion trajectory among product types, driven by persistent local shortages of high-quality protein meals that force formulators to unlock energy from lower-grade feedstuffs. Poultry applications absorb the dominant volume share, though aquaculture segments are gaining structural importance as Egypt's tilapia and mullet production scales in the Northern Lakes region. Powder delivery modes retain margin advantages in bulk compound feed manufacturing, while liquid systems grow in integrated operations with automated dosing infrastructure.
Regulatory Frame and Forward-Looking Close
Egypt's Ministry of Agriculture and Land Reclamation, the Central Administration of Veterinary Services, and the Egyptian Organization for Standardization and Quality collectively govern feed additive registration, import licensing, and finished feed specifications. These bodies enforce mandatory labeling, residue monitoring, and Good Manufacturing Practice compliance that determine which suppliers qualify for government-subsidized feed programs. Stakeholders must monitor pending revisions to maximum permitted levels of synthetic antioxidants and the potential introduction of enzymatic activity disclosure requirements that would reshape competitive positioning among international and domestic suppliers.
Market Dynamics
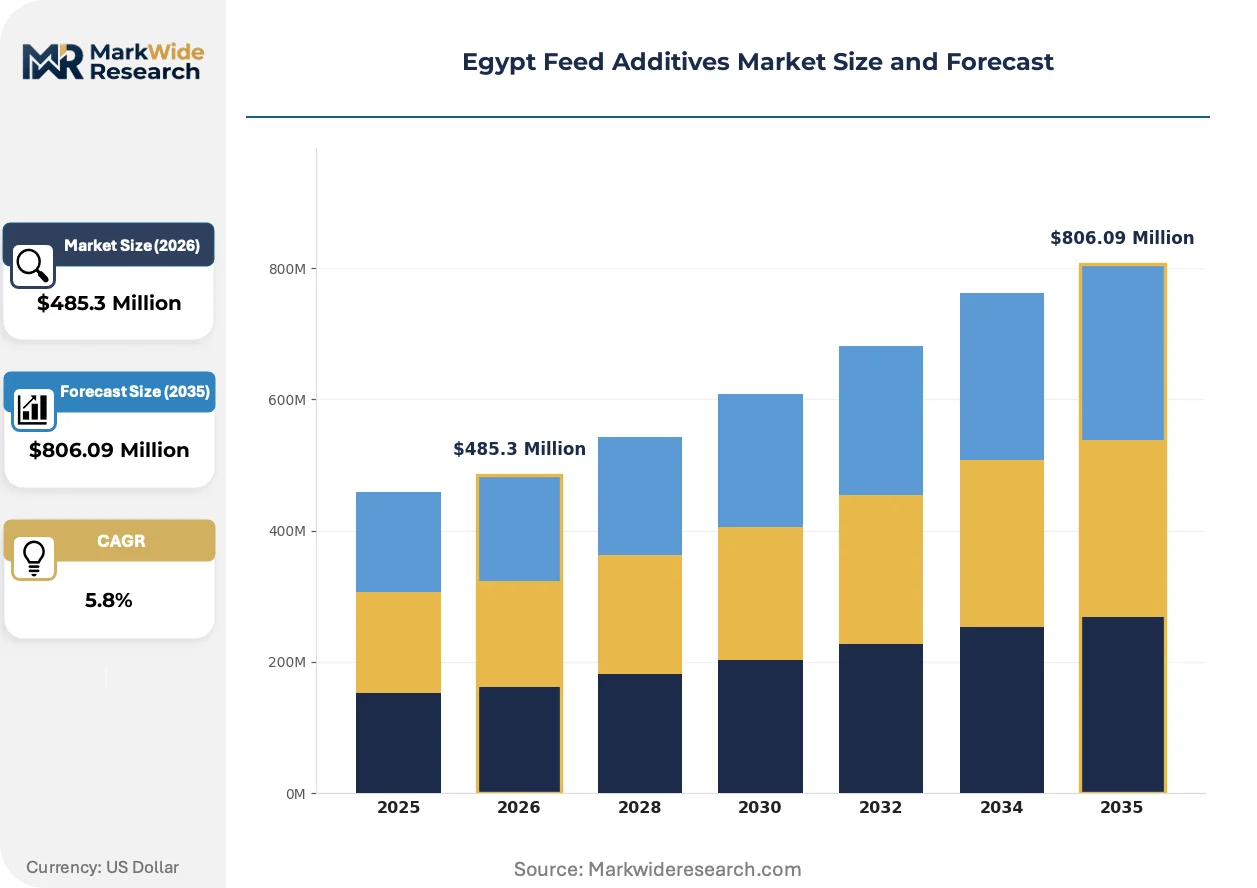
Egypt's feed additive sector is restructuring around the Ministry of Agriculture and Land Reclamation's tightened import protocols for veterinary premixes, which are forcing domestic compound feed mills to rebuild supply relationships around local blending capacity and certified domestic sourcing.
Growth Catalysts
- Regulatory Localization Mandates:The Ministry of Agriculture and Land Reclamation's import protocol revisions are compelling feed mills to source vitamin premixes through registered domestic blenders, expanding local manufacturing capacity.
- Enzyme Technology Diffusion:Multi-enzyme complexes targeting anti-nutritional factors in sorghum-based rations are spreading across Sharqia and Dakahlia governorates as protein meal shortages persist.
- Aquaculture Infrastructure Buildout:Tilapia and mullet production scaling in Egypt's Northern Lakes region is creating dedicated demand for species-specific amino acid formulations.
Market Restraints
- Feed-Grade Input Volatility:Global sorghum and soybean meal price swings transmit directly into Egyptian formulator margins, compressing willingness to experiment with novel additive categories.
- Import Concentration Risk:Alexandria port terminal bottlenecks and foreign exchange rationing create single-point vulnerability for vitamin premix supply security.
- Technical Efficacy Thresholds:Enzyme activity stability under Egyptian heat and humidity conditions limits performance guarantees, slowing adoption among risk-averse independent mills.
Strategic Opportunities
- Upper Egypt Penetration Gap:Sohag and Qena governorates remain underserved by technical service networks, creating first-mover advantage for localized quality certification programs.
- Liquid Dosing Infrastructure:Automated dosing systems in integrated poultry operations enable premium pricing for liquid enzyme and acidifier formulations versus powder alternatives.
- Subsidy Program Alignment:Qualification for government-subsidized feed programs under Egyptian Organization for Standardization and Quality specifications opens volume contracts with state-affiliated cooperatives.
Industry Challenges
- Formulation Chemistry Expertise Scarcity:Egyptian universities produce insufficient graduates with combined feed science and enzymology training, forcing mills to rely on foreign technical service partnerships.
- Dual Certification Burden:Separate registration requirements with the Central Administration of Veterinary Services and Egyptian Organization for Standardization and Quality extend product launch timelines by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Feed Additives Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $806.09 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acidifiers, Antioxidants, Enzymes, Vitamins Application: Poultry, Swine, Ruminants, Aquaculture Delivery Mode: Liquid, Powder, Granules, Tablets End User: Farmers, Livestock Producers, Feed Manufacturers, Distributors |
| Companies Covered | DSM-Firmenich, Novozymes A/S, Cargill, Incorporated, Archer Daniels Midland Co., Danisco A/S, Nutreco NV, Evonik Industries AG, Adisseo France SAS, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Feed Additives Market Shifts & Advancements
Formulation science in Egyptian feed systems is pivoting from static premix recipes toward dynamic, substrate-matched enzyme cocktails that unlock energy from lower-grade local feedstuffs. This shift is compressing traditional supplier margins while rewarding technical service depth.
Multi-enzyme complexes combining xylanase, β-glucanase, and protease activity are modularizing feed formulation workflows across Nile Delta compound feed facilities. Large poultry integrators in Sharqia governorate are adopting these platforms fastest, replacing fixed-ratio vitamin-mineral premixes with adjustable enzyme loading protocols. The technology is modularizing supplier relationships, allowing mills to unbundle vitamin sourcing from enzyme technical service.
Egypt's Ministry of Agriculture and Land Reclamation is advancing mandatory enzymatic activity disclosure requirements for imported feed additives. This policy shift will force international suppliers to reveal performance specifications previously treated as proprietary, leveling competitive positioning for domestic blenders. Powder enzyme suppliers face the steepest compliance burden, as liquid formulation houses already maintain detailed activity certification.
Procurement patterns among independent feed mills are fragmenting from single-source annual contracts toward quarterly multi-vendor sourcing. This behavioral shift is disintermediating traditional distributor networks in favor of direct mill-to-manufacturer relationships. The transformation is most visible in Dakahlia governorate, where mid-sized compound feed facilities are building in-house quality testing capacity to validate incoming enzyme activity claims.
Egypt Feed Additives Market Segmentation
Feed additive procurement in Egypt fragments sharply between commodity vitamin premixes and performance-tier enzyme formulations, with channel economics and technical service requirements determining supplier-miller matching across each segment boundary.
Product Type:
Volume concentration sits with legacy vitamin and antioxidant categories, while premium pricing and technical differentiation cluster around enzymatic platforms.
- Enzymes:Multi-enzyme complexes combining xylanase, β-glucanase, and protease activity target anti-nutritional factors in sorghum and soybean-based rations prevalent across Nile Delta poultry operations. Demand concentrates in Sharqia and Dakahlia governorates where integrated poultry companies operate the largest compound feed facilities, driven by persistent local shortages of high-quality protein meals that force formulators to unlock energy from lower-grade feedstuffs.
- Vitamins:Vitamin premixes—comprising fat-soluble and water-soluble micronutrient blends—constitute the procurement baseline for Egyptian compound feed mills, with Cargill's Alexandria port terminal anchoring import supply security. Tightened Ministry of Agriculture and Land Reclamation import protocols are pushing mills toward registered domestic blenders, expanding local manufacturing capacity for standard premix formulations.
- Acidifiers:Organic acid formulations with defined pH-lowering capacity preserve feed integrity in Egypt's heat-stressed storage conditions, finding application among independent mills lacking climate-controlled infrastructure.
- Antioxidants:Synthetic and natural antioxidant compounds protect lipid fractions in locally sourced feedstuffs, with pending regulatory revisions to maximum permitted levels creating compliance uncertainty for formulators.
Mature deployment sits with vitamin premixes across government-subsidized feed programs. Newer deployment is concentrated in enzyme platforms among technically sophisticated integrated operations.
Application:
Customer scale and species-specific formulation complexity separate high-volume contract supply from specialized technical service relationships.
- Poultry:Broiler and layer operations across the Nile Delta absorb the dominant volume share of Egyptian feed additive demand, with enzyme-based formulations improving feed conversion ratios in Sharqia governorate facilities. Large integrators are adopting adjustable enzyme loading protocols that modularize supplier relationships and unbundle vitamin sourcing from technical service.
- Aquaculture:Tilapia and mullet production scaling in Egypt's Northern Lakes region is creating dedicated demand for species-specific amino acid formulations, with Evonik Industries AG and DSM-Firmenich competing on localized quality certification programs for this emerging segment.
- Swine:Limited swine production due to religious dietary restrictions constrains segment scale, with additives targeting small-scale commercial operations in peri-urban Cairo and Alexandria.
- Ruminants:Dairy and beef cattle operations in the Nile Valley utilize ionophores and rumen modifiers, though segment growth lags poultry and aquaculture expansion trajectories.
Procurement sophistication peaks in poultry, where automated dosing infrastructure enables premium liquid enzyme pricing. Aquaculture represents the steepest expansion trajectory as Egyptian fish production scales toward export markets.
Delivery Mode:
Physical form selection tracks manufacturing automation levels and climate exposure risk across Egyptian feed mill infrastructure.
- Powder:Powder delivery modes retain margin advantages in bulk compound feed manufacturing across mid-sized independent mills, though enzyme activity stability under Egyptian heat and humidity conditions limits performance guarantees and slows adoption among risk-averse operators.
- Liquid:Liquid systems are gaining structural importance in integrated poultry operations with automated dosing infrastructure, enabling precise enzyme and acidifier loading protocols that justify premium pricing over powder alternatives.
- Granules:Granular formulations reduce dust exposure and improve handling characteristics for manual mixing operations prevalent among smaller livestock producers in Upper Egypt.
- Tablets:Tablet forms serve niche applications in on-farm supplementation and veterinary-directed therapeutic feeding, with limited scale in commercial compound feed manufacturing.
Liquid dosing penetration correlates with operational scale, clustering in Dakahlia governorate facilities. Powder dominance persists among price-sensitive independents lacking capital for infrastructure upgrades.
End User:
Purchasing power and technical capability stratify the Egyptian feed additive demand base from multinational-integrated operations to fragmented smallholder channels.
- Feed Manufacturers:Compound feed mills represent the primary volume channel, with procurement patterns fragmenting from single-source annual contracts toward quarterly multi-vendor sourcing as mills build in-house quality testing capacity to validate incoming enzyme activity claims.
- Livestock Producers:Large integrated poultry companies in Sharqia and Dakahlia governorates command technical service partnerships with international suppliers, while independent producers rely on distributor networks for standard premix access.
- Farmers:Smallholder livestock operations in Sohag and Qena governorates remain underserved by technical service networks, creating first-mover advantage for localized quality certification programs targeting this penetration gap.
- Distributors:Traditional distributor networks face disintermediation pressure as direct mill-to-manufacturer relationships proliferate, particularly visible in Dakahlia governorate where procurement centralization is compressing intermediary margins.
Feed manufacturers concentrate volume and negotiate supplier terms. Farmers represent the most dispersed and technically underserved tier, with subsidy program alignment determining access to government-subsidized feed specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed additive procurement concentrates along the Nile Delta corridor, where integrated poultry operations in Sharqia and Dakahlia governorates absorb the dominant volume share. Upper Egypt remains structurally underserved by technical service networks, creating geographic asymmetry in supplier penetration.
Nile Delta Region
Broiler and layer operations across Sharqia and Dakahlia governorates drive enzyme formulation demand, with multi-enzyme complexes targeting anti-nutritional factors in sorghum-based rations. Egypt's Ministry of Agriculture and Land Reclamation enforces tightened import protocols for veterinary premixes through the Central Administration of Veterinary Services. Alexandria port terminal serves as the primary entry point for vitamin premix imports, with Cargill leveraging local blending capacity to sustain supply security.
Northern Lakes Region
Tilapia and mullet production scaling creates dedicated demand for species-specific amino acid formulations among aquaculture feed mills. The Egyptian Organization for Standardization and Quality governs finished feed specifications for fish meal processors. Damietta and Kafr El-Sheikh governorates host expanding compound feed facilities serving cage culture operations in Lake Manzala and Lake Burullus.
Greater Cairo Metropolitan Area
Peri-urban livestock operations and feed distributor networks cluster in Cairo and Giza governorates, bridging Delta production with Upper Egypt consumption. Central Administration of Veterinary Services maintains regional laboratories for residue monitoring and import certification. Obour City and 10th of Ramadan industrial zones concentrate mid-sized compound feed mills serving fragmented poultry and dairy channels.
Upper Egypt
Sohag and Qena governorates remain penetration gaps for technical service networks, with smallholder livestock operations relying on standard premix access through state-affiliated cooperatives. Subsidy program alignment under Egyptian Organization for Standardization and Quality specifications determines access to government-supported feed. Local blending capacity is expanding as import protocol revisions push mills toward domestic sourcing relationships.
Western Desert Oases
Dairy cattle operations in New Valley governorate utilize ionophores and rumen modifiers, though segment scale lags poultry and aquaculture trajectories. Ministry of Agriculture and Land Reclamation extension services promote improved feed conversion practices among date palm-integrated livestock systems. Kharga and Dakhla oases represent emerging demand pockets as groundwater irrigation expands fodder crop production.
Egypt Feed Additives Market Competitive Landscape
European and North American producers anchor the premium formulation tier; Asian manufacturers hold commodity vitamin positions. The vendor base splits between multinational integrators with port terminal assets and specialized enzyme houses competing on technical service depth. Three archetypes dominate: global nutrition conglomerates with full portfolio coverage, amino acid specialists with localized quality certification programs, and domestic blenders capitalizing on regulatory localization mandates. Competitive moves concentrate on strategic partnerships with large poultry integrators and capacity expansion in domestic blending facilities.
Within the global nutrition tier, DSM-Firmenich and Cargill, Incorporated exemplify divergent approaches to Egyptian market access. DSM-Firmenich occupies a position anchored through technical service partnerships with large poultry integrators. Cargill, Incorporated represents scale-driven supply security through Alexandria port terminal operations and local blending infrastructure. Evonik Industries AG sits within the specialty chemicals archetype, differentiated through amino acid portfolio breadth and localized quality certification programs. These three entities collectively illustrate how geographic asset deployment and technical service depth separate competitive positioning in a market restructuring around import protocol localization.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Novozymes A/S |
| Cargill, Incorporated |
| Archer Daniels Midland Co. |
| Danisco A/S |
| Nutreco NV |
| Evonik Industries AG |
| Adisseo France SAS |
| BASF SE |
| Others |
Supply & Pricing Matrix
Egypt's Good Manufacturing Practice compliance mandates for feed additive registration gate both qualified supply access and premium-tier pricing eligibility, forcing mills to absorb certification costs or forfeit government-subsidized feed program participation.
Pricing Analysis
Short lead-time premiums for vitamin premixes delivered through Alexandria port terminal operations command pricing advantages over spot inventory held by domestic blenders facing foreign exchange rationing delays. Three-tier pricing structure across certified-premium, standard-registered, and economy-unverified levels separates government-subsidized program participants from independent mills. Cost compression in enzyme formulations is intensifying because Egyptian heat and humidity conditions degrade activity guarantees, forcing suppliers to absorb replacement risk. Independent feed mills in Dakahlia governorate exhibit highest price sensitivity, while integrated poultry operations in Sharqia prioritize technical service depth over unit cost.
Supply Chain Analysis
Reverse-logistics flows for expired or heat-degraded enzyme shipments create working capital drains for Egyptian distributors lacking climate-controlled warehousing infrastructure. Supply concentrates in the Netherlands, China, and France for vitamin and amino acid precursors, with Egyptian compound feed mills drawing from these hubs through Alexandria port terminal operations. Raw material dependencies center on corn-derived substrates for fermentation-based enzymes, petroleum-derived synthetic antioxidants, and fish meal protein concentrates for aquaculture formulations. Single-source vulnerability pervades vitamin premix supply security given foreign exchange rationing constraints. Distribution runs through registered domestic blenders for government-subsidized program compliance, alongside direct mill-to-manufacturer relationships for technically sophisticated integrated operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's feed additive sector is becoming a vertical-integration race, with control over domestic blending capacity and port terminal assets emerging as the decisive lever for securing government-subsidized feed program contracts.
For Market Incumbents: To counter regulatory localization mandates that favor domestic blenders, Cargill and DSM-Firmenich should deepen backward integration into Alexandria port terminal capacity expansion and in-house production of certified premix formulations. Technical service partnerships with large poultry integrators must evolve toward co-developed substrate-matched enzyme protocols that lock in switching costs. For New Entrants and Emerging Players: Smallholder livestock operations in Sohag and Qena governorates represent the most penetrable buyer archetype currently underserved by international supplier technical service networks. Localized quality certification programs aligned with Egyptian Organization for Standardization and Quality specifications offer a go-to-market angle for state-affiliated cooperative channel access. For Investors and Strategic Acquirers: Pending revisions to maximum permitted levels of synthetic antioxidants is the leading indicator that regulatory compliance burdens will reshape competitive positioning among international and domestic suppliers. Acquisition targets should center on domestic blenders with existing Central Administration of Veterinary Services registration and port-adjacent warehousing assets. Practitioners should monitor enzymatic activity disclosure requirement implementation timelines for early signals of supplier margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Blending Capacity Expansion | Qualifies suppliers for government-subsidized feed program contracts under Ministry of Agriculture protocols. |
| Technical Service Partnership Deepening | Locks in large poultry integrators in Sharqia governorate through co-developed enzyme loading protocols. |
| Port Terminal Asset Control | Secures supply security against foreign exchange rationing and Alexandria terminal bottleneck risks. |
| Localized Quality Certification Investment | Opens state-affiliated cooperative channels in underserved Upper Egypt governorates. |
| Multi-Enzyme Complex R&D Alignment | Addresses persistent protein meal shortages through substrate-matched formulations for sorghum-based rations. |
Research Methodology
Trade databases, Egyptian Organization for Standardization and Quality regulatory filings, and Central Administration of Veterinary Services registration records formed the secondary backbone, supplemented by primary interviews with compound feed mill procurement directors, poultry integrator nutritionists, and domestic premix blender operations managers. Bottom-up and top-down triangulation validated volume estimates across enzyme, vitamin, and acidifier product categories.
Bottom-up modeling anchored forecasts in facility-level production capacity and feed conversion ratio improvement metrics, while top-down analysis cross-checked against Ministry of Agriculture and Land Reclamation import licensing data. Segmentation dimensions included product type, application species, delivery mode physical form, and end-user scale tier. CAGRs were derived from fitted growth curves incorporating protein meal shortage persistence and aquaculture infrastructure buildout trajectories.
Revisions become necessary when foreign exchange rationing intensifies, regulatory disclosure requirements accelerate, or heat-humidity degradation thresholds shift beyond current enzyme stability specifications. Practitioners should monitor Alexandria port terminal throughput rates and domestic blender registration approvals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Cocoglycerides Market
Food Additives and Ingredients
Middle East and Africa Clean Label Ingredients Market
Food Additives and Ingredients
Africa Feed Additives Market
Food Additives and Ingredients
Resistant Dextrin Market
Food Additives and Ingredients
Lactoperoxidase Market
Food Additives and Ingredients
AKD Emulsifier Market
Food Additives and Ingredients
Gum Hydrocolloid Market
Food Additives and Ingredients
Western Europe Food Phosphate Market
Food Additives and Ingredients
Tara Gum Market
Food Additives and Ingredients
Disodium Cocoamphodiacetate Market
Food Additives and Ingredients
Gellan Gum Market
Food Additives and Ingredients
Monoglyceride Market
Food Additives and Ingredients
North America Dehydrated Onion Market
Food Additives and Ingredients
India Food Acidulants Market
Food Additives and Ingredients
Global Wood-Derived Food Additives Market