
 High-Throughput Food Allergen Screening Test Instruments Market | 2026-2036
High-Throughput Food Allergen Screening Test Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
High-Throughput Food Allergen Screening Test Instruments Market Insights
Specialized bioanalytical talent is rotating toward multiplex assay development and automated liquid-handling integration, tightening the labor pool for instrument vendors and service labs alike. Thermo Fisher Scientific leverages its mass spectrometry footprint to anchor high-throughput workflows for major allergen panels. Eurofins Scientific sustains one of the densest contract lab networks globally, competing on turnaround speed for food manufacturer audits. Neogen Corporation specializes in immunoassay platforms that dominate mid-scale processing facilities seeking ELISA-based throughput without capital escalation.
High-throughput food allergen screening test instruments are automated analytical systems designed to detect multiple allergenic proteins or residues simultaneously, typically processing 96 to 384 samples per run with detection thresholds reaching parts per million or lower. These instruments employ fluorescence, chemiluminescence, or mass spectrometry readout modalities to quantify target analytes for commercial food safety verification and regulatory compliance. PCR analyzers and mass spectrometers command premium positioning due to multiplex depth and quantitative precision, while ELISA readers occupy the volume tier where cost-per-test sensitivity drives procurement. Immunoassay systems are gaining fastest in emerging markets that prioritize capital efficiency over methodological expansion.
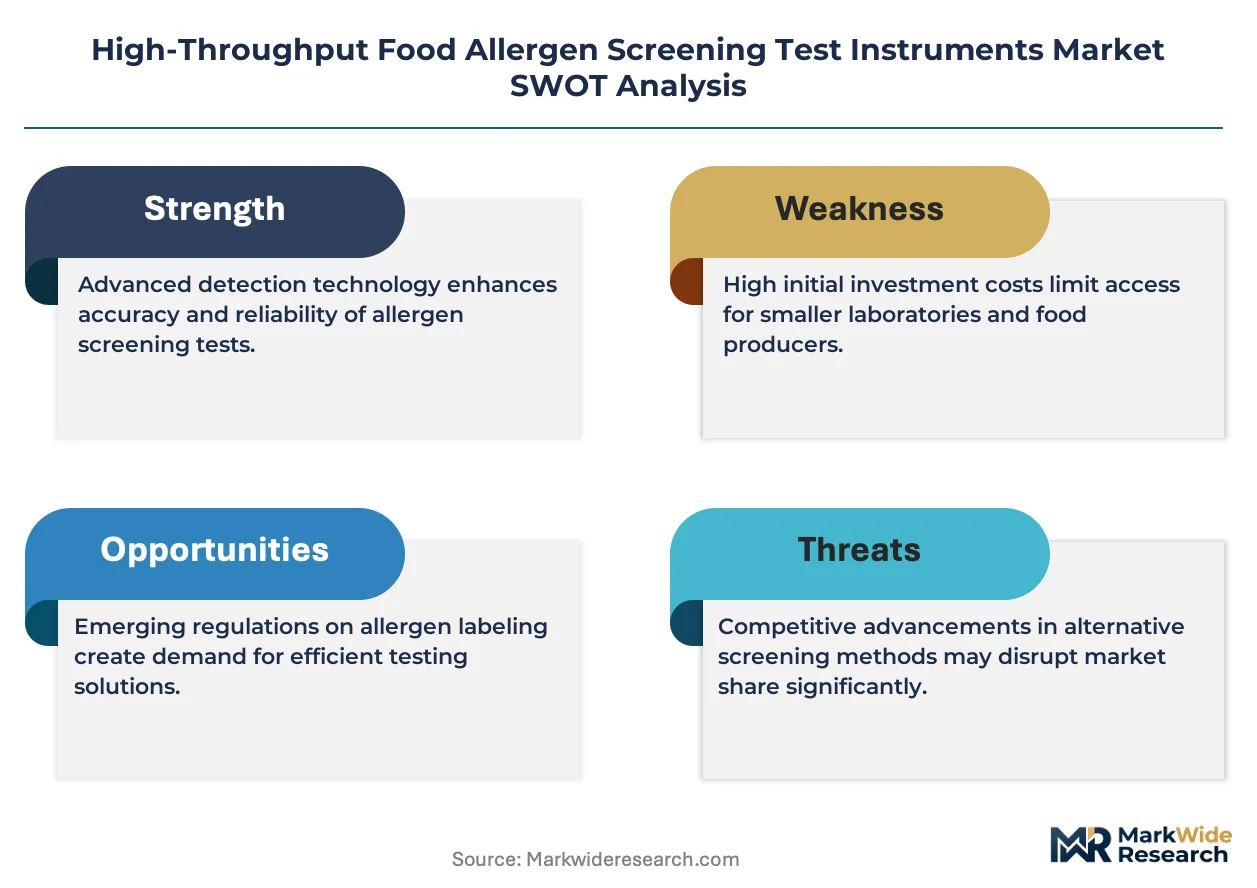
The FDA's Food Safety Modernization Act preventive controls framework and the EU's FIC allergen labeling mandate together compel food manufacturers to maintain documented, validated screening programs with auditable throughput records. ISO 17025 accreditation requirements from certification bodies further shape instrument specifications, particularly for labs serving export markets across multiple regulatory jurisdictions. Stakeholders must weigh capital deployment toward mass spectrometry platforms against the operational flexibility of modular immunoassay systems as regulatory scope broadens to emerging allergens and threshold refinements.
Market Dynamics
Multiplex assay architectures are compressing detection timelines from hours to minutes, forcing incumbent ELISA platforms toward obsolescence while mass spectrometry workflows capture premium validation contracts from export-oriented processors.
Growth Catalysts
- EU FIC Regulation:Mandatory allergen labeling for 14 substance categories compels food manufacturers across Germany, France, and Italy to deploy continuous throughput validation systems for cross-border shipment compliance.
- Fluorescence microplate readers:Mid-scale dairy and bakery clusters in the Netherlands and Belgium are standardizing on 384-well formats to balance capital efficiency against regulatory audit density.
- Contract laboratory consolidation:Pan-European testing networks are centralizing instrument procurement to serve multinational manufacturers facing synchronized FDA and EFSA inspection schedules.
Market Restraints
- Helium scarcity:Mass spectrometry platforms dependent on liquid helium cooling face operational continuity risks as Qatar and Algeria supply concentrates tighten.
- Reference material fragmentation:ISO 17025 accreditation bodies maintain divergent certified reference standards across jurisdictions, forcing duplicate validation runs for multi-market exporters.
- Immunoassay cross-reactivity:ELISA-based systems generate false positives for homologous protein families, limiting deployment in complex matrices like fermented soy or hydrolyzed dairy.
Strategic Opportunities
- Polish meat processing expansion:EU structural funds are modernizing slaughterhouse and prepared-meat facilities, creating first-mover advantage for automated liquid-handling integrators.
- PCR-mass spectrometry convergence:Hybrid platforms combining nucleic acid amplification with exact-mass detection are opening multiplex depth previously unreachable by either modality alone.
- Digital audit trails:CSRD-aligned sustainability reporting is creating demand for instrument-embedded blockchain verification of allergen test batch records.
Industry Challenges
- Bioanalytical talent scarcity:Specialized assay developers with mass spectrometry method validation expertise command premium compensation, stretching R&D budgets at instrument vendors and service labs.
- Legacy LIMS integration:Decade-old laboratory information management systems at established food manufacturers resist API connectivity with modern high-throughput platforms, requiring costly middleware development.
- ISO 17025 recertification velocity:Accelerated scope expansion to emerging allergens like lupin and celery forces labs into continuous accreditation cycles that consume technical management bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Throughput Food Allergen Screening Test Instruments Market |
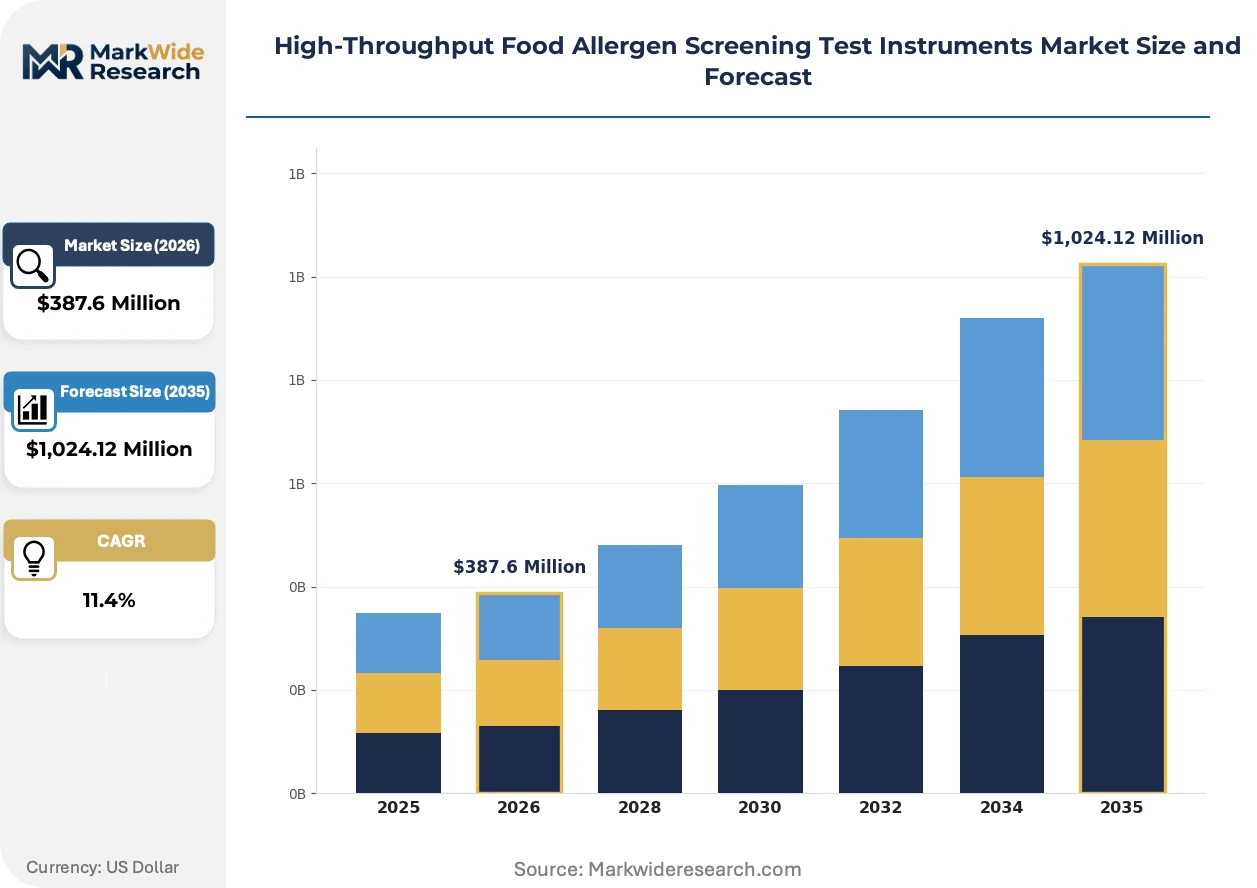
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA Readers, PCR Analyzers, Mass Spectrometers, Microarray Scanners, Immunoassay Systems Technology: Fluorescence, Chemiluminescence, Electrochemical, Optical Biosensors, Mass Spectrometry Application: Food Processing Facilities, Quality Control Labs, Contract Testing Laboratories, Research Institutes End User: Food Manufacturers, Certification Bodies, Regulatory Agencies, Food Safety Consultants |
| Companies Covered | Thermo Fisher Scientific, Eurofins Scientific, SGS, Bureau Veritas, Intertek Group, ALS Limited, Merieux NutriSciences, Neogen Corporation, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Throughput Food Allergen Screening Test Instruments Market Trends and Innovations
Detection modality diversification is fragmenting the previously uniform ELISA-dominated landscape, with chemiluminescence and mass spectrometry architectures capturing distinct performance tiers based on multiplex depth requirements and regulatory stringency.
Digital microfluidics is fragmenting sample preparation workflows by enabling nanoliter-scale reagent consumption and walkaway automation. Large bakery cooperatives in northern Germany are deploying these platforms for inline monitoring of incoming flour shipments. The technology is fragmenting capital deployment patterns, allowing processors to distribute testing nodes across production lines rather than centralizing in quality control laboratories.
REACH substance restriction proposals for per- and polyfluoroalkyl substances are pressuring manufacturers to reformulate assay reagents and consumables. Fluoropolymer-coated microplates face substitution timelines that compress supplier qualification windows. Dairy processors in Denmark and Ireland are accelerating validation of alternative surface chemistries to maintain uninterrupted export certification.
Consolidated procurement by multinational food manufacturers is displacing fragmented instrument purchasing at individual production sites. Pan-European quality directors now mandate standardized platforms across facility networks to harmonize training, maintenance contracts, and data architecture. This concentration is most visible in Swiss and Dutch headquarters operations of global ingredient suppliers managing continent-wide allergen risk matrices.
High-Throughput Food Allergen Screening Test Instruments Market Segmentation
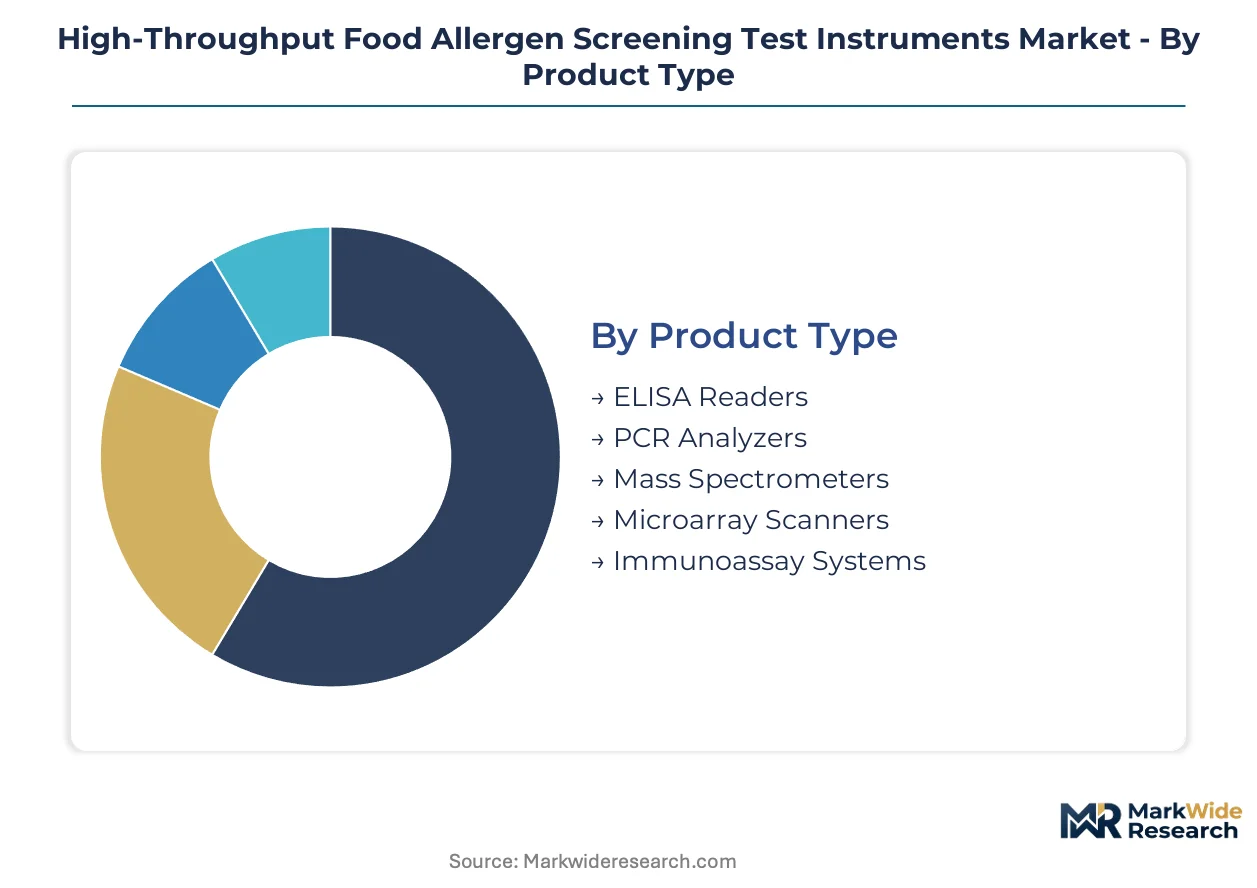
Segmentation in high-throughput allergen screening reveals distinct procurement patterns across capital tiers and regulatory stringency levels. Product type determines channel access, with mass spectrometry flowing through specialized distributors while ELISA platforms reach mid-scale processors via broadline laboratory supply networks.
Product Type:
Channel mix varies sharply by capital intensity and technical complexity, with premium modalities commanding direct vendor relationships and volume-tier products distributing through consolidated laboratory supply contracts.
- Mass Spectrometers:Triple-quadrupole and high-resolution accurate-mass configurations deliver quantitative precision for multi-allergen panels at parts-per-billion thresholds. German dairy exporters and Swiss chocolate manufacturers anchor demand as EU FIC Regulation mandates intensify cross-border audit requirements.
- ELISA Readers:Absorbance and fluorescence microplate systems process 96- to 384-well formats for standardized immunoassay workflows. Mid-scale bakery clusters in Belgium and the Netherlands standardize on these platforms to balance throughput against capital constraints.
- PCR Analyzers:Real-time thermal cyclers with multiplex detection channels target allergen-specific DNA sequences in processed matrices.
- Microarray Scanners:High-density protein arrays enable simultaneous screening of emerging allergen candidates during formulation development.
- Immunoassay Systems:Integrated walkaway platforms combine liquid handling with detection modules for high-volume routine screening.
ELISA readers dominate installed base across European food processing networks. Mass spectrometers represent the fastest-growing trajectory as export-oriented processors face synchronized FDA and EFSA inspection schedules.
Technology:
Cost tier stratification separates premium quantitative methods from rapid qualitative screening, with fluorescence occupying the mid-market sweet spot for dairy and meat processors balancing speed against capital deployment.
- Mass Spectrometry:Electrospray ionization coupled to tandem mass analyzers provides definitive identification with isotope-dilution quantification. Large contract testing networks in Germany and France deploy these systems for ISO 17025-accredited multi-market certification.
- Fluorescence:Time-resolved and polarization-based detection formats reduce background interference in complex food matrices. Dutch ingredient suppliers favor fluorescence microplate readers for inline monitoring of incoming raw materials.
- Chemiluminescence:Enzyme-amplified light emission enables picogram-level sensitivity for trace residue detection.
- Electrochemical:Label-free biosensor platforms target portable and point-of-use deployment scenarios.
- Optical Biosensors:Surface plasmon resonance and interferometric methods support real-time binding kinetics for method development.
Fluorescence platforms anchor volume deployment in quality control laboratories. Mass spectrometry is where expansion concentrates among pan-European testing networks seeking regulatory defensibility.
Application:
Customer type segmentation maps directly to throughput requirements and documentation standards, with contract laboratories demanding highest multiplex depth and food processing facilities prioritizing turnaround velocity.
- Contract Testing Laboratories:Multi-site accreditation networks require auditable throughput records and cross-jurisdictional method validation. Eurofins and similar pan-European operators centralize procurement of mass spectrometry platforms to serve synchronized multinational manufacturer audits.
- Food Processing Facilities:In-house quality control demands rapid batch release with minimal technical staffing. Large dairy cooperatives in northern Germany deploy automated ELISA workflows for continuous incoming material screening.
- Quality Control Labs:Centralized testing nodes at production campuses balance method standardization against site-specific matrix challenges.
- Research Institutes:Method development and emerging allergen characterization drive demand for flexible platform configurations.
Contract testing laboratories dominate premium instrument procurement. Food processing facilities represent the steepest expansion trajectory as preventive controls frameworks deepen in-house screening requirements.
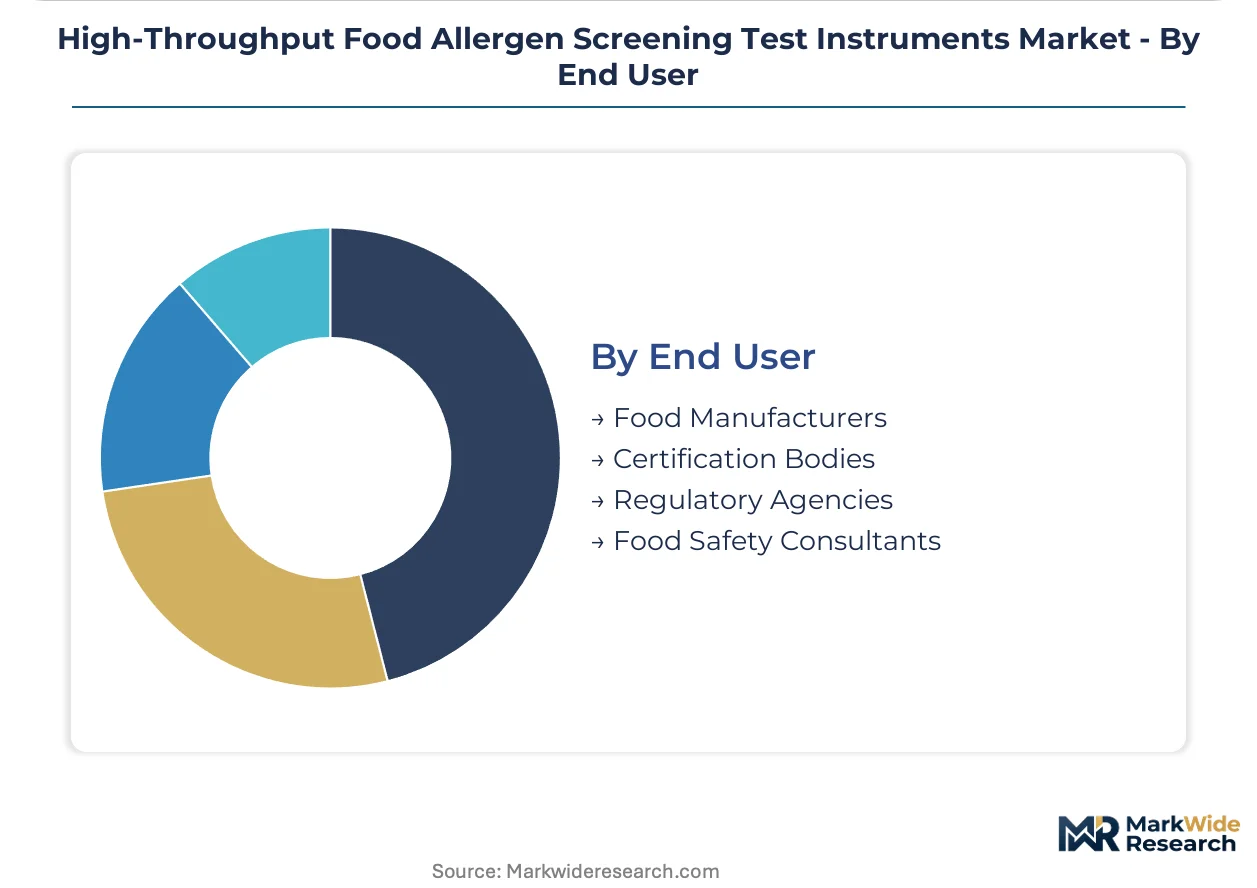
End User:
Procurement authority concentrates with food manufacturers holding direct responsibility for supplier verification, while certification bodies shape specifications through ISO 17025 accreditation requirements.
- Food Manufacturers:Multinational processors with export exposure face compound regulatory obligations from FDA, EFSA, and destination-market authorities. Swiss and Dutch headquarters operations of global ingredient suppliers mandate standardized platforms across facility networks.
- Certification Bodies:Accreditation organizations specify instrument performance criteria and reference material traceability for audit recognition.
- Regulatory Agencies:Government laboratories develop confirmatory methods and conduct surveillance sampling for enforcement.
- Food Safety Consultants:Advisory firms recommend platform configurations during facility design and compliance remediation.
Food manufacturers command the largest capital deployment. Certification bodies are where specification influence concentrates as accreditation scope expands to emerging allergens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA allergen labeling mandates and FDA preventive controls together shape procurement patterns across major food manufacturing geographies. Germany, the United States, France, Switzerland, and the Netherlands concentrate instrument deployment due to export-intensive processing clusters and synchronized multi-jurisdictional audit requirements.
Germany
Dairy cooperatives in Lower Saxony and Bavaria drive demand for continuous throughput validation systems serving EU FIC Regulation compliance. The country's national food safety authority, BfR, coordinates reference material standardization with EFSA, tightening accreditation timelines for cross-border exporters. Large bakery clusters around Hamburg deploy automated liquid-handling platforms for inline flour shipment screening.
United States
Multinational ingredient suppliers headquartered in the Midwest and California face compound obligations under FDA's Food Safety Modernization Act preventive controls framework. The FDA intensifies inspection frequency for allergen-specific preventive controls, forcing processors to maintain auditable batch records. Dairy processors in Wisconsin and California anchor mass spectrometry procurement for multi-allergen panel validation.
France
Cheese and prepared food exporters in the Auvergne-Rhône-Alpes region require ISO 17025-accredited platforms for destination-market certification. ANSM coordinates with EFSA on emerging allergen scope expansion, pressuring labs into continuous recertification cycles. Lyon-based contract testing networks centralize instrument procurement to serve pan-European manufacturer audits.
Switzerland
Global chocolate and ingredient suppliers headquartered around Zurich and Basel mandate standardized platforms across facility networks. Swissmedic maintains stringent reference material traceability requirements that shape instrument specifications for export certification. Nestlé-adjacent testing infrastructure in Vevey drives premium platform deployment for multi-market compliance.
Netherlands
Ingredient suppliers and dairy processors in the Randstad region prioritize fluorescence microplate readers for capital-efficient inline monitoring. The Dutch Food and Consumer Product Safety Authority enforces EU FIC Regulation alignment with accelerated audit schedules for export-oriented facilities. Wageningen University-adjacent research clusters pilot digital microfluidics for distributed testing nodes.
High-Throughput Food Allergen Screening Test Instruments Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in this market. Mass spectrometry platform vendors and pan-European contract laboratory networks occupy distinct competitive layers based on capital intensity and accreditation breadth. Three archetypes dominate: diversified analytical instrumentation conglomerates, specialized food safety testing service providers, and focused immunoassay platform developers. Competitive moves concentrate on strategic partnerships between instrument vendors and contract laboratories, plus portfolio diversification into adjacent contamination detection modalities.
Among diversified analytical instrumentation leaders, Thermo Fisher Scientific exemplifies the integrated conglomerate archetype through its mass spectrometry footprint. Eurofins Scientific occupies a central position within contract laboratory networks, while Neogen Corporation represents the specialized immunoassay platform tier. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Eurofins Scientific |
| SGS |
| Bureau Veritas |
| Intertek Group |
| ALS Limited |
| Merieux NutriSciences |
| Neogen Corporation |
| Bio-Rad Laboratories |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lead times for helium-cooled mass spectrometry components concentrate pricing power with German and Japanese cryogenic suppliers, forcing instrument vendors to absorb cost volatility or pass through to export-oriented dairy processors in northern Europe. This inventory exposure shapes procurement behavior across contract testing networks seeking ISO 17025-compliant platforms.
Pricing Analysis
Price spreads between mass spectrometry and ELISA platforms widen by certification tier, with ISO 17025-accredited systems commanding premium positioning against uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects multiplex depth and regulatory defensibility. Pricing pressure stems from consolidated procurement by multinational food manufacturers standardizing across facility networks. Mid-scale bakery clusters in Belgium and the Netherlands exhibit highest price sensitivity, while pan-European contract labs prioritize throughput validation over unit economics.
Supply Chain Analysis
Strategic stockpiling of reference materials dominates inventory strategy as ISO 17025 recertification cycles accelerate, contrasting with just-in-time consumables management for routine ELISA workflows. Component manufacturing concentrates in Germany, Japan, and the United States for precision optical and mass analyzer subsystems. Supply chains draw from fluoropolymer-coated microplate suppliers facing REACH substitution timelines, rare-earth magnet providers for automated liquid-handling robotics, and certified reference material producers under EFSA coordination. Single-source vulnerability in helium cooling systems for mass spectrometry platforms creates operational continuity exposure. Distribution runs through specialized analytical instrumentation distributors serving accredited laboratories and direct vendor relationships with multinational food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from validation support and ISO 17025 accreditation consulting is expanding faster than hardware sales as contract laboratories face continuous recertification cycles for emerging allergen scope.
For Market Incumbents: Compound defensive positioning through captive supply of certified reference materials and backward integration into automated liquid-handling robotics, neutralizing margin pressure from emerging digital microfluidics entrants. Prioritize certification investment in lupin and celery method validation ahead of EFSA scope expansion timelines. For New Entrants and Emerging Players: ISO 17025 fast-track partnerships with German dairy cooperatives offer lowest barrier to initial revenue, exploiting fragmented legacy LIMS integration pain points at mid-scale processing facilities. Target Polish meat processing modernization funded by EU structural funds with modular fluorescence platforms. Lead with API-native data architecture as primary go-to-market differentiation. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because allergen labeling mandates are structurally irreversible and threshold refinements deepen instrumentation dependency. Acquisition targets should display pan-European accreditation breadth and recurring validation service revenue. Watch helium supply stabilization agreements as inflection signal for mass spectrometry platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Scope Expansion | ISO 17025 accreditation for lupin and celery methods captures EFSA-mandated demand from export-oriented processors. |
| Digital Microfluidics Integration | Nanoliter-scale reagent consumption aligns with CSRD-aligned sustainability reporting requirements from Swiss headquarters operations. |
| Reference Material Backward Integration | Captive supply of certified standards defends margin position against fragmented supplier qualification windows. |
| API-Native LIMS Connectivity | Middleware-free integration resolves legacy system resistance at established food manufacturers in the Netherlands and Belgium. |
| Helium Recovery Infrastructure | Closed-loop cooling systems mitigate operational continuity risk from Qatar and Algeria supply concentration. |
Research Methodology
A standing panel of assay development scientists, quality control directors at dairy cooperatives, procurement leads from pan-European contract testing networks, and regulatory affairs specialists at instrument vendors provided ongoing calibration across the research cycle. Primary interviews combined with secondary validation against EFSA guidance documents, FDA Food Safety Modernization Act preventive controls guidance, ISO 17025 accreditation body bulletins, and customs data for analytical instrumentation trade flows. Bottom-up instrument shipment modeling and top-down food manufacturer compliance spending estimates were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including detection modality, throughput tier, regulatory jurisdiction cluster, and end-user accreditation status. CAGRs were derived from installed base expansion rates and replacement cycle analysis. Industry-specific forecast inputs incorporated EFSA emerging allergen scope expansion timelines and FDA inspection frequency intensification patterns.
Decision-makers should treat outputs as directional under base assumptions of sustained EU FIC Regulation enforcement and helium supply partial recovery; material deviation would warrant model refresh. Forecasts reflect these assumptions alongside secondary risks including REACH substance restriction acceleration and contract laboratory consolidation velocity. Revision becomes warranted when helium supply disruption severity or regulatory scope expansion pace crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Central & South America Food Safety Testing Market
Food Safety Testing
Global Meat Speciation Testing Market
Food Safety Testing
Global Food Authenticity Testing Market
Food Safety Testing
South Africa Food Safety Testing Market
Food Safety Testing
US Food Allergen Testing Market
Food Safety Testing
Food Allergens and Intolerance Testing Market
Food Safety Testing
Allergen Testing Market
Food Safety Testing
Fresh Food Residue Testing Market
Food Safety Testing
Bottled Water Testing Equipment Market
Food Safety Testing
US Legionella Testing Market
Food Safety Testing
Residual Lactose Analyzer Market
Food Safety Testing
Water Quality Testing Market
Food Safety Testing
Food Traceability Solutions Market
Food Safety Testing
Food Pathogen Testing Market
Food Safety Testing
Food and Beverage Protective Cultures Market
Food Safety Testing
Chromatography Food Testing Market