
 Sunset Yellow FCF Market | 2026-2036
Sunset Yellow FCF Market Size, Share, and Industry Trends Forecast 2026-2036
Sunset Yellow FCF Market Analysis
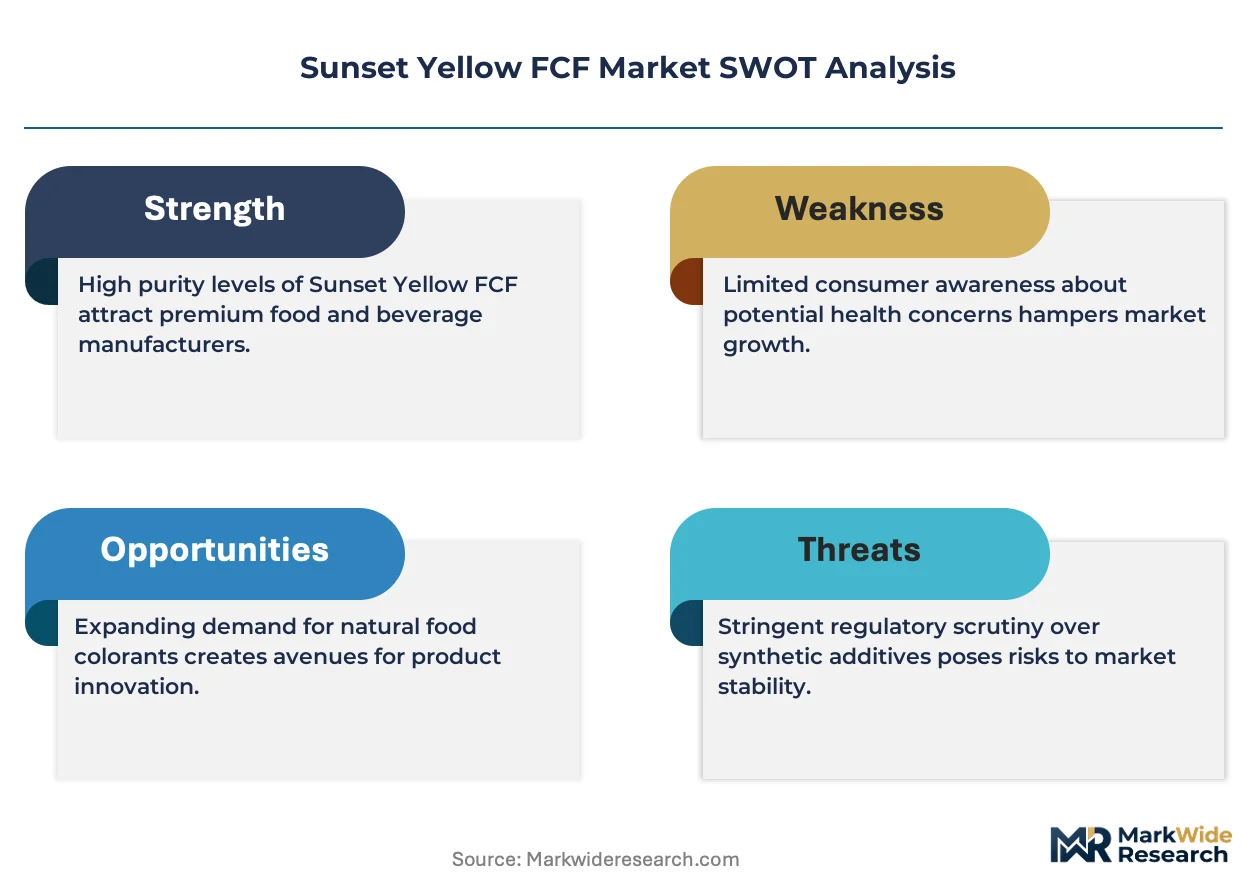
Food manufacturers is collapsing share from pharmaceutical and cosmetic buyers as clean-label pressures reshape procurement priorities. Roha Dyechem leverages backward integration into dye intermediates to protect margin pools. Sensient Technologies anchors North American supply through FDA-certified production facilities. Chr. Hansen Holding A/S competes by specializing in natural-color alternatives that pressure synthetic dye pricing.
Sunset Yellow FCF is a synthetic azo dye, designated E110, with maximum absorption near 480 nm and sulfonate groups conferring water solubility for aqueous food matrices. Manufacturers synthesize it through diazotization of sulfanilic acid coupled with 1-(4-sulfophenylazo)-2-naphthol, then purify to residual aromatic amine limits set by JECFA. The colorant serves primarily to impart yellow-orange hues in processed foods and beverages where visual consistency drives consumer preference. Bakery and confectionery applications lead volume absorption due to heat-stable formulations surviving oven and extrusion conditions. Beverage production represents the fastest-growing application as carbonated and still drinks expand in emerging markets. Direct sales channels dominate bulk transactions while distributors occupy smaller food manufacturer accounts requiring technical service support.
FDA color additive regulations under 21 CFR 74 enforce batch certification and purity specifications that shape US market access conditions. EFSA and JECFA tolerable daily intake thresholds constrain formulation limits across European and export-oriented production. India's FSSAI implements CODEX-aligned standards that domestic manufacturers must satisfy for interstate commerce. Stakeholders should monitor regulatory divergence between permissible daily exposure limits as formulation decisions increasingly hinge on multi-jurisdiction compliance rather than single-market optimization.
Market Dynamics
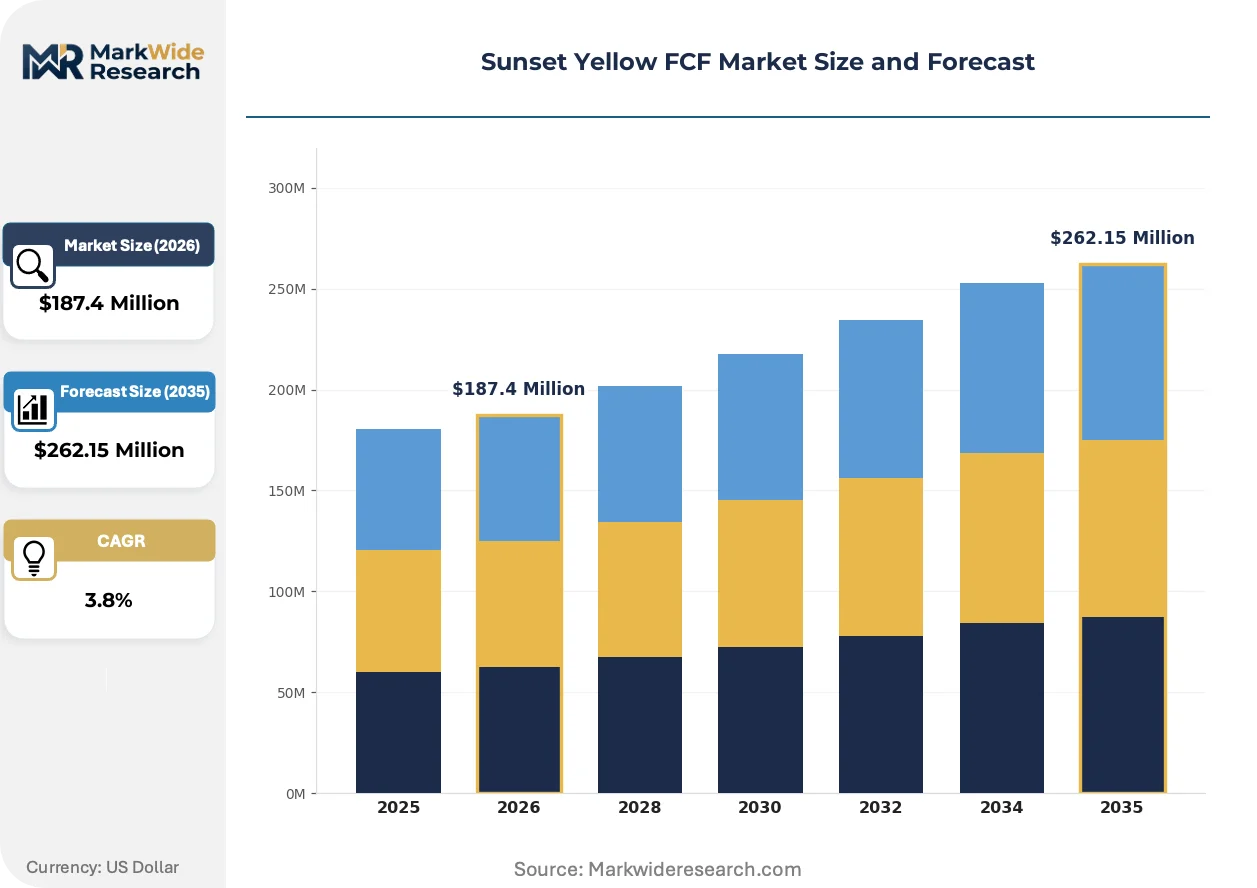
Clean-label pressures are collapsing pharmaceutical and cosmetic demand share as food manufacturers absorb volume, while regulatory divergence between FDA batch certification and EFSA purity thresholds forces multi-jurisdiction compliance architectures.
Growth Catalysts
- Instant Mix Formulation Expansion:Food processors are embedding Sunset Yellow FCF into dry beverage and baking premixes where heat-stable colorants survive reconstitution and oven conditions without degradation.
- REACH Purity Threshold Tightening:ECHA-mandated residual aromatic amine limits are accelerating purification technology upgrades that lock out marginal suppliers and consolidate compliant production capacity.
- Beverage Carbonation Growth:Carbonated and still drink manufacturers across emerging markets are absorbing synthetic dye volumes as visual consistency becomes a non-negotiable quality attribute.
Market Restraints
- Sulfanilic Acid Feedstock Volatility:Diazotization chemistry depends on petrochemical-derived intermediates whose pricing swings compress formulation margins unpredictably.
- Indian Supply Concentration:Roha Dyechem and domestic intermediates producers control upstream dye synthesis, creating single-geography vulnerability for global buyers.
- Natural Colorant Substitution:Chr. Hansen and specialty natural-color houses are displacing synthetic azo dyes in premium confectionery and organic-labeled products.
Strategic Opportunities
- FSSAI-Aligned Export Channels:CODEX-standard production certified by India's food regulator opens interstate and Southeast Asian markets for domestic processors.
- Direct Sales Channel Penetration:Bulk transaction bypass of distributor networks captures margin from mid-size food manufacturers requiring technical service support.
- Extrusion-Compatible Formulation:Heat-stable variants for snack and cereal manufacturing address equipment-intensive applications where natural alternatives fail thermally.
Industry Challenges
- JECFA Certification Timelines:Residual aromatic amine testing and tolerable daily intake documentation create 12-18 month regulatory approval cycles for new production batches.
- Legacy Equipment Integration:Existing diazotization and coupling reactor infrastructure requires capital retrofit to meet tightening CODEX-aligned purity specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sunset Yellow FCF Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Mixes, Dairy Products, Confectionery, Bakery Application: Food Processing, Beverage Production, Cosmetics, Pharmaceuticals End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Retailers Distribution Channel: Direct Sales, Distributors, Online Retail, Specialty Stores |
| Companies Covered | Roha Dyechem Pvt. Ltd., Symrise AG, Chr. Hansen Holding A/S, Cathay Industries, San-Ei Gen F.F.I., Inc., FMC Corporation, Sensient Technologies, GNT International B.V., DDW The Color House, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sunset Yellow FCF Market Emerging Trajectories
Formulation science and regulatory detection methods are compressing acceptable impurity windows while procurement patterns fragment across direct and distributor channels. Three forces are restructuring competitive position.
Microencapsulation technology is miniaturizing colorant particle distribution to improve dispersion stability in aqueous matrices. Beverage manufacturers are adopting these engineered particles for carbonated applications where shelf-life consistency determines brand equity. The structural consequence is compressing formulation tolerance ranges and rewarding suppliers with in-house particle engineering capability.
EFSA is lowering tolerable daily intake thresholds for synthetic azo dyes through revised exposure assessments that incorporate cumulative dietary load calculations. Food manufacturers across the European Union are reformulating at reduced concentration levels or blending with natural alternatives to maintain hue intensity. Bakery and confectionery segments are absorbing the highest compliance burden as these categories dominate children's dietary exposure profiles.
Buyer concentration among multinational food processors is compressing supplier negotiation cycles and unbundling technical service from material procurement. Direct sales teams are displacing distributor networks for accounts above defined volume thresholds while smaller manufacturers remain distributor-dependent. India and Southeast Asian markets exhibit the most pronounced channel bifurcation as domestic processor scale diverges sharply.
Sunset Yellow FCF Market Segmentation
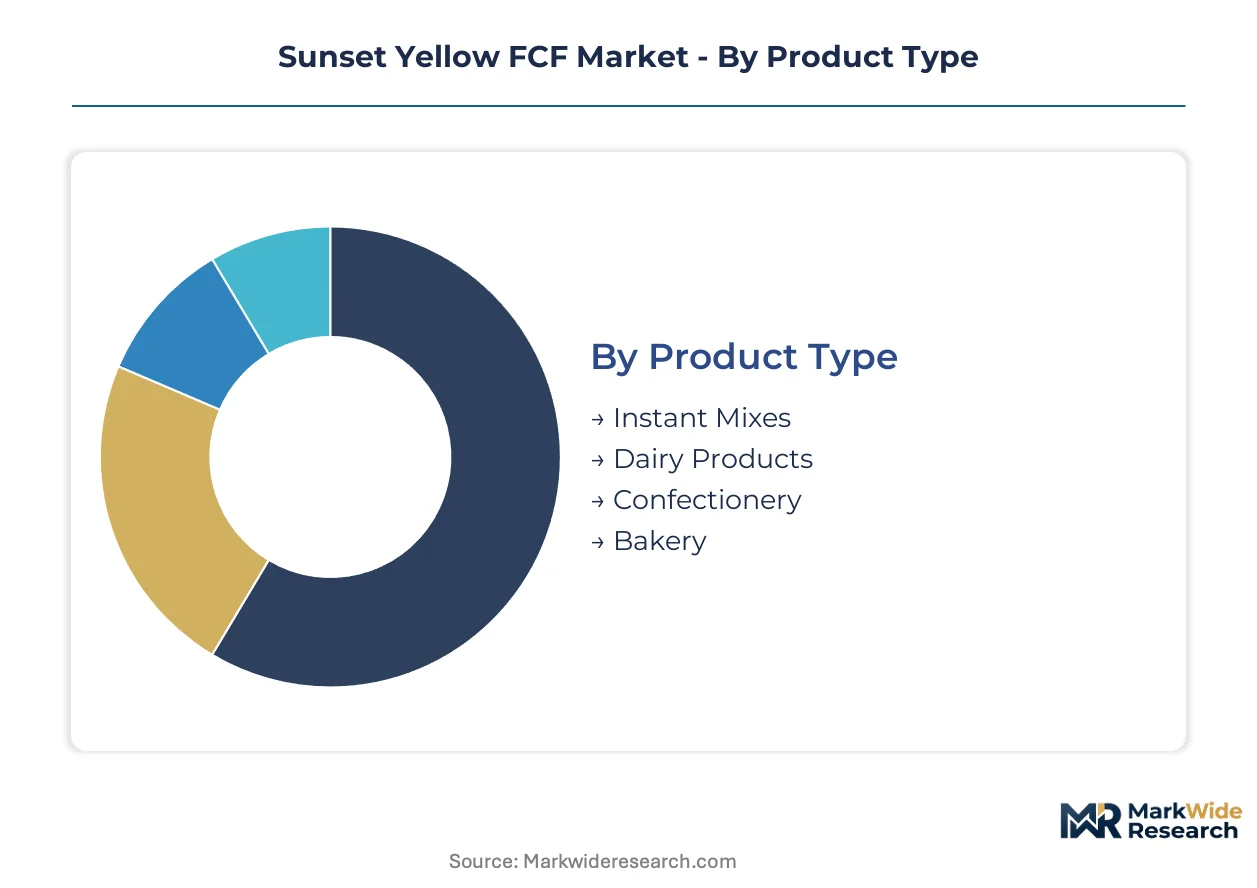
Sunset Yellow FCF procurement patterns fragment sharply across channel tiers, with bulk food processors negotiating direct contracts while smaller manufacturers rely on distributor technical support. Formulation requirements vary dramatically by end-use heat stability and regulatory jurisdiction, creating segment-specific purity grade demands.
Product Type:
Direct sales channels capture the largest volume flows for instant mixes and dairy applications, while distributors handle confectionery and bakery accounts requiring localized technical service.
- Instant Mixes:Dry beverage and baking premixes demand heat-stable formulations that survive reconstitution without hue degradation. Demand concentrates among Indian food processors supplying Southeast Asian export markets where FSSAI certification enables interstate commerce.
- Dairy Products:Ice cream and flavored milk applications require sulfonate-group solubility for uniform dispersion in high-fat matrices. European dairy manufacturers are reformulating at reduced concentrations under EFSA cumulative exposure assessments targeting children's dietary loads.
- Confectionery:Hard candy and coated applications drive volume through distributor networks serving mid-size manufacturers.
- Bakery:Oven-stable variants for cookies and cakes absorb synthetic dye volumes as visual consistency determines shelf appeal.
Instant Mixes dominates installed base. Confectionery is where expansion concentrates.
Application:
Cost tier stratification separates commodity food processing from premium cosmetic and pharmaceutical grades requiring residual aromatic amine documentation.
- Food Processing:Bakery and extruded snack manufacturing leads volume absorption due to heat-stable formulation requirements. Indian processors anchor supply concentration through Roha Dyechem's backward integration into dye intermediates.
- Beverage Production:Carbonated and still drink manufacturers are climbing the fastest as emerging market visual consistency standards harden. Microencapsulation technology adoption compresses supplier qualification to particle engineering specialists.
- Cosmetics:Lipstick and topical applications face clean-label displacement as natural colorant houses capture premium positioning.
- Pharmaceuticals:Tablet coating demand is collapsing under purity documentation burdens and natural alternative substitution.
Food Processing commands current volume share. Beverage Production is where formulation innovation concentrates.
End User:
Customer type determines procurement architecture, with multinational food manufacturers unbundling technical service from material purchasing while smaller accounts remain distributor-captive.
- Food Manufacturers:Instant mix and beverage processors negotiate direct sales contracts above defined volume thresholds. Procurement teams are consolidating supplier panels under multi-jurisdiction compliance requirements spanning FDA batch certification and REACH purity thresholds.
- Cosmetic Companies:Premium confectionery and personal care brands are displacing synthetic azo dyes under clean-label positioning pressures from Chr. Hansen natural alternatives.
- Pharmaceutical Firms:Tablet coating applications face JECFA certification timeline constraints creating 12-18 month approval cycles.
- Retailers:Private-label food and beverage producers access colorants through distributor networks requiring CODEX-aligned documentation.
Food Manufacturers dominates contract value. Cosmetic Companies is where substitution risk concentrates.
Distribution Channel:
Supply concentration in Indian dye intermediates shapes channel viability, with direct sales requiring captive technical resources and distributors absorbing compliance documentation burdens.
- Direct Sales:Bulk transactions bypass distributor margins for accounts with in-house formulation capability. Sensient Technologies anchors North American supply through FDA-certified production facilities serving multinational processors.
- Distributors:Smaller food manufacturers depend on technical service support for JECFA residual aromatic amine documentation and multi-jurisdiction labeling guidance.
- Online Retail:Laboratory and small-batch purchasers access reagent-grade material through specialized chemical supply platforms.
- Specialty Stores:Artisan food producers source small-volume colorants through regional ingredient suppliers with FSSAI-aligned certification.
Direct Sales dominates transaction value. Distributors is where account coverage expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust in Maharashtra underwrites India's dominance in synthetic dye intermediates, handling bulk chemical exports that feed food processing clusters across Southeast Asia. This maritime infrastructure locks in procurement gravity for azo dye manufacturers serving instant mix and beverage formulation demand.
United States
Beverage carbonation expansion and confectionery manufacturing absorb synthetic dye volumes along the Gulf Coast petrochemical corridor. FDA batch certification requirements under 21 CFR 74 enforce purity documentation that shapes import access conditions. Chicago and New Jersey host formulation laboratories serving multinational food processors consolidating supplier panels.
India
Instant mix production for Southeast Asian export markets concentrates in Maharashtra and Gujarat where Roha Dyechem operates backward-integrated dye intermediate facilities. FSSAI CODEX-aligned standards enable interstate commerce certification that unlocks regional distribution. Mumbai-Pune industrial belt anchors technical service capacity for mid-size food manufacturers.
Germany
REACH-mandated residual aromatic amine limits accelerate purification technology upgrades among specialty chemical producers in North Rhine-Westphalia. EFSA cumulative exposure assessments drive reformulation at reduced concentration levels across bakery applications. Leverkusen and Ludwigshafen chemical clusters concentrate compliance-capable production capacity.
Japan
Heat-stable formulation demand from extruded snack manufacturing concentrates in the Kanto region around Tokyo-Yokohama industrial zones. PMDA pharmaceutical-grade documentation requirements constrain tablet coating applications under tightening purity thresholds. Osaka-based food processors source through direct sales channels bypassing distributor margins.
Brazil
Emerging beverage production capacity in São Paulo state absorbs synthetic dye imports for carbonated drink manufacturing serving Mercosur markets. ANVISA color additive regulations align with CODEX standards that facilitate regional trade documentation. Campinas chemical processing hub intermediates between Asian dye suppliers and domestic formulation facilities.
Sunset Yellow FCF Market Vendor Landscape
Listed leaders compete with private specialists across certification tier and geographic coverage dimensions, producing a bifurcated structure where scale-driven multinationals anchor premium-grade supply while regional specialists capture mid-market volume. Three archetypes dominate: backward-integrated dye intermediate producers, natural-color alternative specialists, and FDA-certified North American distributors. Consolidation pressure concentrates through purification technology upgrades that lock out marginal suppliers, while direct sales channel expansion displaces distributor networks above defined volume thresholds.
Within the integrated manufacturing tier, Roha Dyechem Pvt. Ltd. exemplifies captive supply of dye intermediates that protects margin pools against feedstock volatility. Sensient Technologies occupies a position as the North American supply anchor through FDA-certified production infrastructure. Chr. Hansen Holding A/S represents the natural-color alternative archetype that pressures synthetic azo dye pricing across premium confectionery segments. These three entities collectively illustrate the competitive tension between synthetic efficiency and clean-label substitution that structures procurement decision-making.
| Leading Market Players |
|---|
| Roha Dyechem Pvt. Ltd. |
| Symrise AG |
| Chr. Hansen Holding A/S |
| Cathay Industries |
| San-Ei Gen F.F.I., Inc. |
| FMC Corporation |
| Sensient Technologies |
| GNT International B.V. |
| DDW The Color House |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Indian dye intermediate producers and multinational food processors lock in supply access while constraining price visibility against volatile sulfanilic acid feedstock costs. These arrangements concentrate procurement gravity in Maharashtra's chemical belt, where backward-integrated manufacturers capture margin pools that spot-market buyers forfeit.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade certification from food-grade bulk and reagent-laboratory tiers. Pharmaceutical-grade commands premium positioning due to JECFA residual aromatic amine documentation burdens, while food-grade bulk absorbs pricing pressure from natural colorant substitution in premium confectionery. Small-batch laboratory purchasers exhibit highest price sensitivity against contract-anchored multinational processors.
Supply Chain Analysis
Inventory lead-times stretch across 12-18 month JECFA certification cycles that tether downstream formulation decisions to upstream purification batch releases. Supply concentrates in India, China, and Germany, with diazotization chemistry drawing from petrochemical-derived sulfanilic acid and naphthol intermediates. Single-geography vulnerability in Indian intermediate production creates structural risk, while distribution runs through direct sales channels for bulk accounts and distributor networks for technical service-dependent smaller manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Sunset Yellow FCF market sits in a cyclical recovery phase as beverage carbonation expansion across emerging markets restarts formulation procurement cycles paused during clean-label transition pressures.
For Market Incumbents: Shield margin pools through captive dye intermediate production that insulates against sulfanilic acid volatility. Accelerate microencapsulation R&D to defend technical differentiation against natural colorant substitution in beverage applications. Lock in FSSAI-certified export channels before regulatory divergence hardens compliance architectures. For New Entrants and Emerging Players: Lead with extrusion-compatible heat-stable formulations for snack manufacturing, where natural alternatives fail thermally and incumbent technical service coverage remains thin. Target mid-size Indian food processors lacking in-house formulation capability through distributor partnerships bundling JECFA documentation support. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors purification-technology specialists with REACH-compliant production infrastructure. Acquisition targets should demonstrate residual aromatic amine testing capabilities and FSSAI certification relationships. Watch EFSA cumulative exposure assessment revisions as the signal indicating reformulation-driven demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dye Intermediates | Roha Dyechem's captive sulfanilic acid production protects margins against petrochemical feedstock volatility. |
| Microencapsulation Technology Investment | Particle engineering capability qualifies suppliers for carbonated beverage shelf-life consistency requirements. |
| FSSAI Certification Alignment | CODEX-standard production unlocks interstate Indian commerce and Southeast Asian export channels. |
| Direct Sales Channel Expansion | Bulk transaction bypass captures margin from multinational food processors consolidating supplier panels. |
| Natural Colorant R&D Partnership | Blending synthetic and natural alternatives addresses EFSA cumulative exposure reformulation demands. |
Methodological Framework
Operator-level perspectives from dye intermediate plant managers, food processor procurement leads, beverage formulation chemists, and FSSAI regulatory consultants anchored the qualitative base. Primary interview data triangulated against customs trade records, FDA color additive certification databases, EFSA exposure assessment publications, and SEC filings from listed colorant specialists. Bottom-up volume estimates across application segments reconciled with top-down market sizing from trade flow analysis.
Sensitivity analysis tested forecast robustness across regulatory divergence scenarios and feedstock price volatility assumptions. The modeling framework segmented by product grade tier, end-use application heat-stability requirement, distribution channel architecture, and regional regulatory cluster. CAGRs derived from segment-level volume trajectories weighted by purity-grade pricing differentials, incorporating JECFA certification timeline constraints and REACH purity threshold escalation curves.
The analysis sits within stated boundaries; outcomes outside sustained beverage carbonation expansion or accelerated natural colorant substitution would require recalibration. Forecasts reflect assumptions about regulatory alignment between FDA, EFSA, and FSSAI frameworks, with specific risk factors including sulfanilic acid supply disruption and EFSA tolerable daily intake threshold revisions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Canada Food Enzymes Market
Food Additives and Ingredients
Europe Food Colorants Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
Leavening Acids Market
Food Additives and Ingredients
Food Preservatives Market
Food Additives and Ingredients
Africa Food Stabilizers Market
Food Additives and Ingredients
Feed Anti-Caking Agents Market
Food Additives and Ingredients
Sodium Propionate Market
Food Additives and Ingredients
Mexico Anti Caking Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Global Food Bulking Agents Market
Food Additives and Ingredients
Resistant Dextrin Market
Food Additives and Ingredients
Flavor Encapsulation Market
Food Additives and Ingredients
Antimicrobial Packaging Ingredients for Food Packaging Market
Food Additives and Ingredients
Germany Feed Additives Market
Food Additives and Ingredients
Egg Wash Substitute Market