
 Nanoencapsulated Food Additives Market | 2026-2036
Nanoencapsulated Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Nanoencapsulated Food Additives Market Analytics
Modular ingredient bundling is broadening buyer choice as food manufacturers seek turnkey nanoencapsulation systems rather than standalone active compounds. BASF SE leverages its polymer science heritage to supply lipid-based carrier matrices for flavor stabilization. DuPont de Nemours, Inc. anchors North American supply through its integrated nutrition and biosciences division. Royal DSM competes on fermentation-derived encapsulant precursors that reduce synthetic surfactant dependence.
Nanoencapsulated food additives are active ingredients or functional compounds enclosed in nanoscale carriers, typically 10–1000 nm in diameter, using techniques such as high-pressure homogenization, coacervation, or supercritical fluid extraction to protect payloads from oxidation, pH degradation, or thermal breakdown during processing. Their primary commercial purpose is to enable controlled release, mask off-flavors, and boost bioavailability in finished food matrices. Antioxidants dominate current volume as processors seek to replace synthetic preservatives with clean-label alternatives that maintain shelf stability. Emulsions are gaining traction fastest in beverage applications where transparent nano-dispersions preserve visual clarity while delivering lipophilic vitamins. Flavor enhancers occupy concentrated margin pools in confectionery and premium snack segments where taste intensity reduction permits lower sodium or sugar formulations without sensory compromise.
The FDA evaluates nanoencapsulated ingredients under its GRAS notification framework, while EFSA demands comprehensive nanotoxicology dossiers under EU Novel Food Regulation 2015/2283. REACH compliance adds burden for European suppliers using synthetic wall materials such as modified starches or polyethylene glycol derivatives. China's SAMR now requires explicit nanomaterial labeling on prepackaged foods, reshaping export documentation for multinational formulators. Stakeholders must monitor evolving jurisdictional definitions of engineered nanomaterials, as regulatory divergence between FDA case-by-case review and EU blanket precautionary thresholds will determine which carrier technologies achieve cross-border scale.
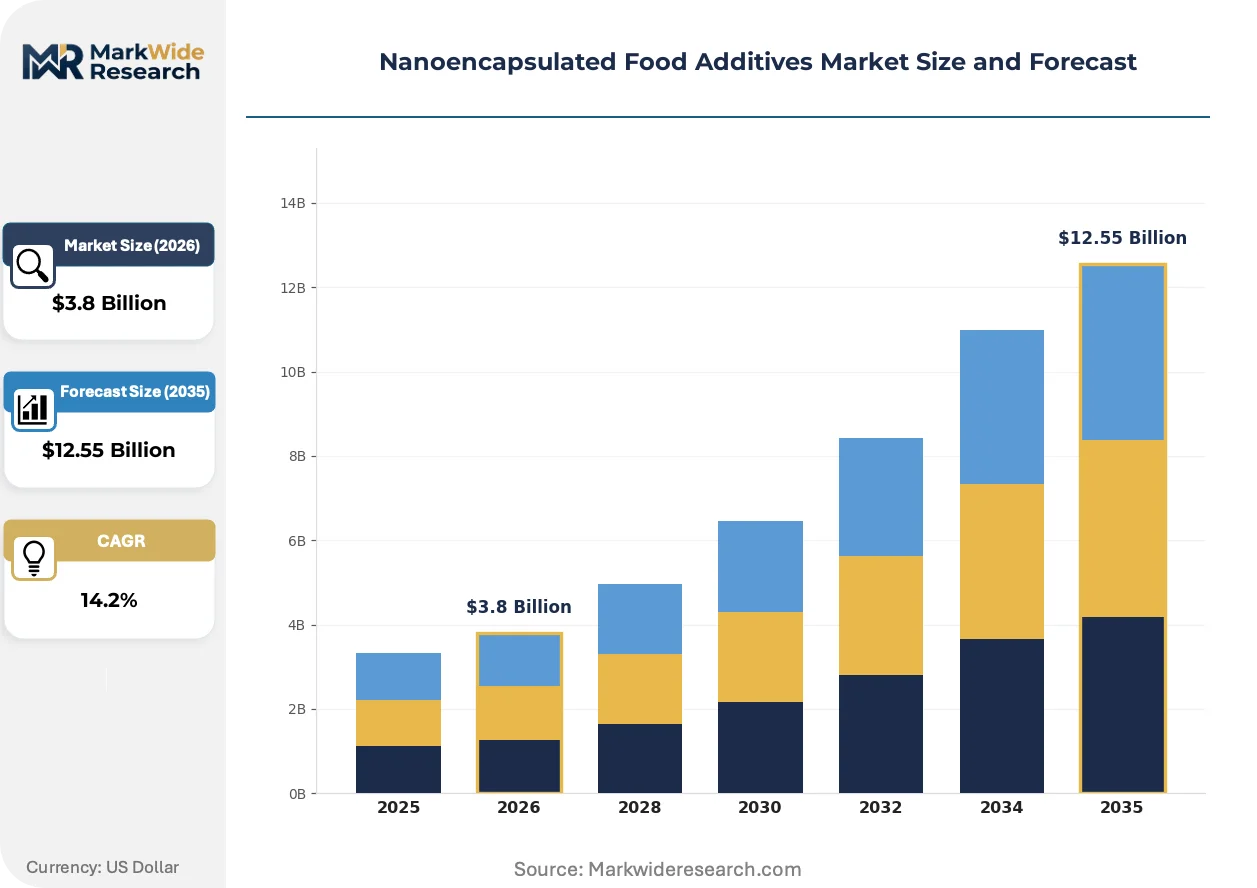
Market Dynamics
Precision fermentation clusters in Germany and the Netherlands are compressing development cycles for lipid-based carrier matrices, while divergent nanomaterial definitions between FDA case-by-case review and EU precautionary thresholds force dual-track regulatory strategies.
Growth Catalysts
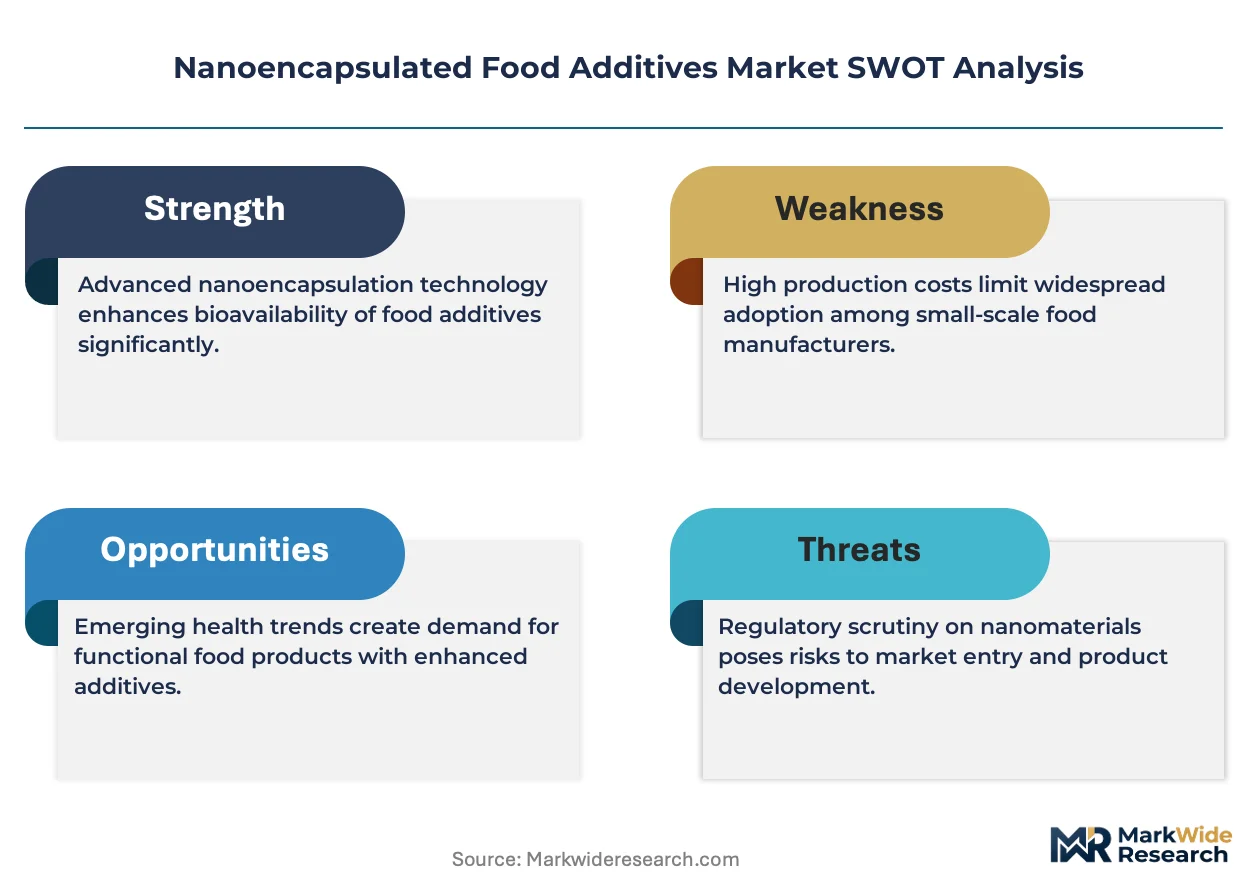
- EU Novel Food Regulation:Mandatory safety dossiers under EFSA guidelines are accelerating investment in standardized toxicology testing infrastructure, creating barrier-to-entry advantages for compliant formulators.
- Beverage transparency demand:Clean-label beverage processors in Germany and Switzerland are adopting nano-emulsion systems to deliver lipophilic vitamins without visual clouding.
- High-pressure homogenization:Equipment cost curves below $500K per production line are democratizing access previously restricted to multinational nutrition houses.
Market Restraints
- Modified starch input volatility:Corn and potato starch prices swing 15-30% seasonally, compressing margins for synthetic wall material producers dependent on agricultural feedstocks.
- REACH compliance burden:European suppliers face extended registration timelines for polyethylene glycol derivatives, delaying commercialization of next-generation carrier chemistries.
- Conventional microencapsulation:Established spray-drying infrastructure in legacy food processing plants creates switching cost friction against nanoscale system adoption.
Strategic Opportunities
- China SAMR labeling mandate:Explicit nanomaterial disclosure requirements are creating first-mover advantages for exporters with pre-validated documentation systems.
- Probiotic stability applications:Controlled-release nano-capsules for heat-sensitive bacterial strains represent unpenetrated white space in ambient-stable functional foods.
- Confectionery sodium reduction:Flavor-enhancer nanoencapsulation enables 20-40% salt reduction in premium chocolate and savory snacks without reformulation of base recipes.
Industry Challenges
- Interdisciplinary formulation talent:Scarcity of chemists cross-trained in food science and nanoscale engineering extends R&D timelines for complex multi-layer carrier designs.
- GRAS notification variability:FDA's case-by-case review approach creates unpredictable approval windows, complicating capital planning for North American market entry.
- Legacy equipment retrofit costs:Integration of nano-dispersion systems with existing high-temperature processing lines demands $2-5M facility modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanoencapsulated Food Additives Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidants, Flavor Enhancers, Colorants, Preservatives Form: Powder, Liquid, Granules, Emulsions End User: Food Manufacturers, Beverage Producers, Snack Companies, Nutraceutical Firms Application: Dairy Products, Bakery Items, Confectionery, Sauces |
| Companies Covered | BASF SE, DuPont de Nemours, Inc., Frutarom Industries Ltd., AQUANOVA AG, GF Fermentech, Evonik Industries AG, Royal DSM, International Flavors & Fragrances, Encapsula NanoSciences LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanoencapsulated Food Additives Market Evolving Landscape
Carrier chemistry convergence with precision fermentation is dissolving the boundary between synthetic and bio-derived encapsulants, while regulatory documentation automation is compressing time-to-market for novel formulations.
Supercritical CO2 extraction is absorbing market share from conventional solvent-based nanoencapsulation as beverage manufacturers seek residue-free carrier production. Premium juice and plant-milk processors in Germany and Denmark are adopting these systems at 25-35% annual equipment procurement rates. The technology is absorbing capital previously allocated to coacervation lines, compressing the installed base of older encapsulation infrastructure.
China's SAMR nanomaterial labeling rules are forcing exporters to rebuild documentation workflows from raw material sourcing through finished goods certification. Multinational formulators are consolidating testing partnerships with Shanghai and Beijing laboratories to preempt customs delays. Prepackaged food categories with transparent packaging are most affected, as visual nano-dispersion detection triggers mandatory disclosure obligations.
Turnkey nanoencapsulation system procurement is displacing standalone active ingredient purchasing among mid-size food manufacturers. Buyers in the Netherlands and Belgium now contract for complete flavor-stabilization or vitamin-delivery modules rather than sourcing carrier matrices and payload compounds separately. This bundling behavior concentrates supplier relationships and compresses negotiation leverage for component-only vendors.
Nanoencapsulated Food Additives Market Segmentation
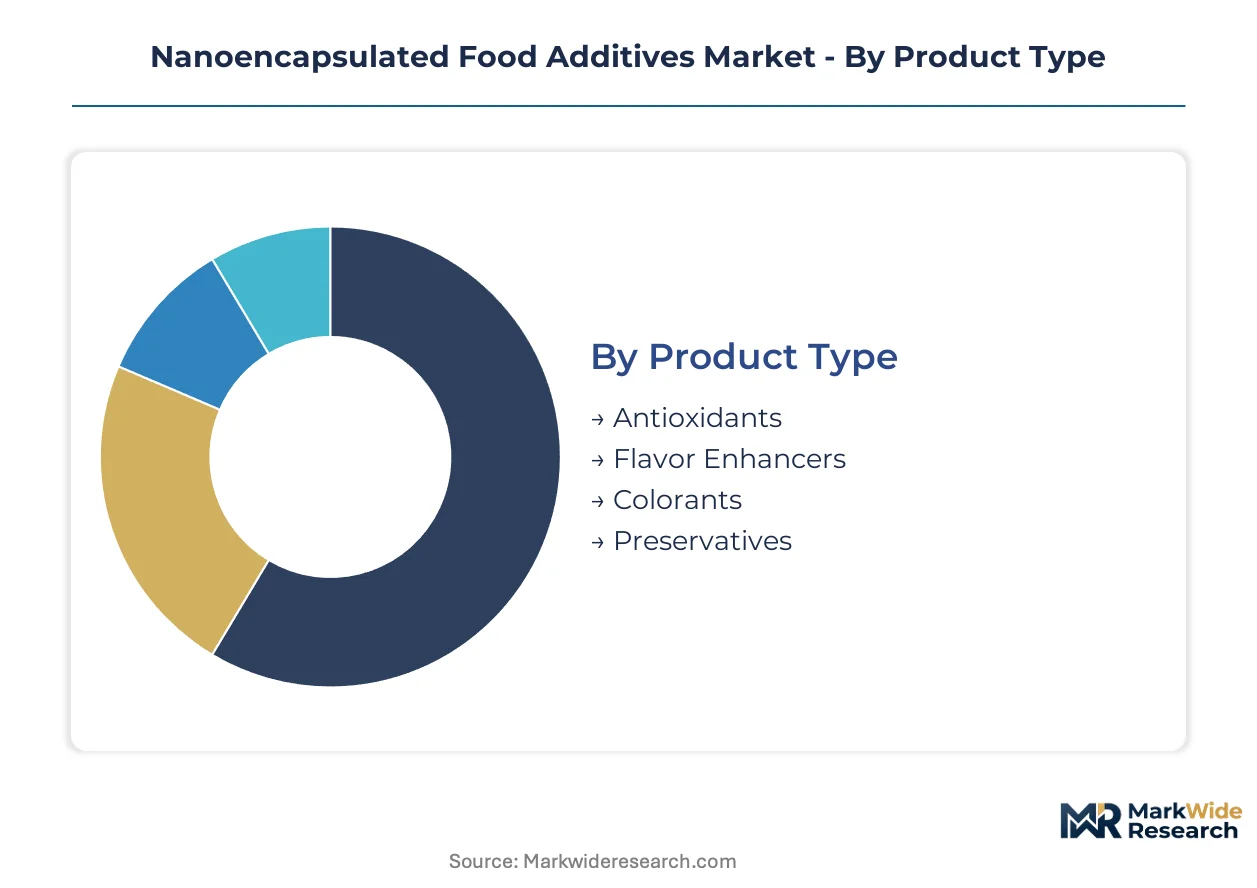
Nanoencapsulated food additives demand fractures across payload chemistry, physical state, buyer sophistication, and thermal processing requirements. Each segmentation axis carries distinct equipment compatibility and regulatory documentation burdens that reshape supplier selection criteria.
Product Type:
Replacement cycles accelerate as clean-label mandates obsolete synthetic preservative portfolios in favor of nanoscale bioactive delivery systems.
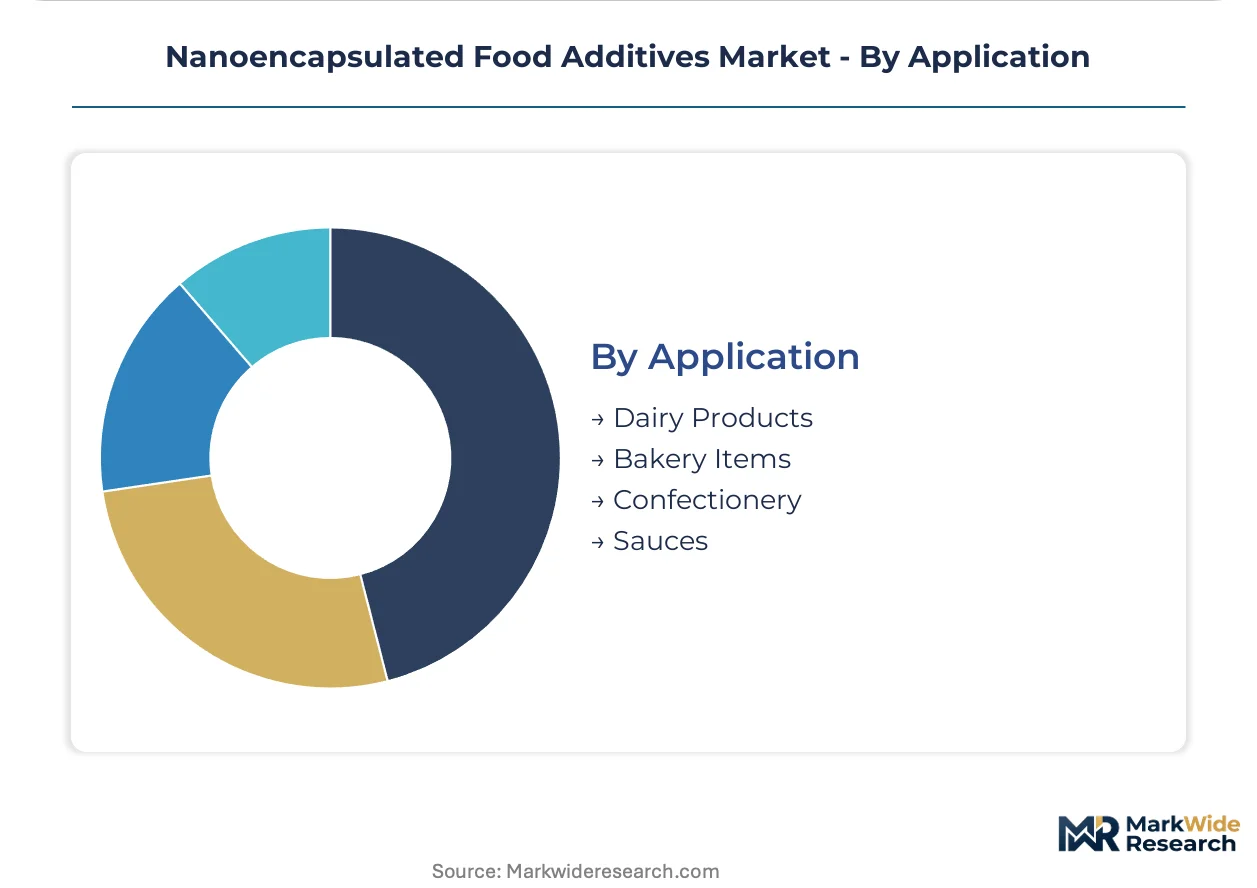
- Antioxidants:Lipid-soluble tocopherols and polyphenols enclosed in phospholipid bilayers resist thermal degradation during UHT milk processing. German dairy cooperatives and Dutch plant-milk processors are standardizing these carriers to replace BHA/BHT in ambient-stable formulations.
- Flavor Enhancers:Salt and sugar reduction without sensory compromise depends on nanoscale taste-modulator dispersion that amplifies receptor activation at lower concentrations. Swiss confectionery houses and Belgian chocolate manufacturers deploy these systems to meet front-of-pack labeling thresholds.
- Colorants:Carotenoid and anthocyanin nano-dispersions stabilize hue intensity across pH fluctuations in beverage matrices.
- Preservatives:Nisin and natamycin nanocapsules extend shelf life in clean-label deli meats and refrigerated pasta.
Volume placements concentrate in Antioxidants; the faster expansion belongs to Flavor Enhancers.
Form:
Physical state selection hinges on downstream processing temperature ceilings and equipment retrofit feasibility rather than payload chemistry alone.
- Emulsions:Transparent nano-dispersions below 100 nm preserve visual clarity in functional waters and clear juices while delivering lipophilic vitamins A, D, E, and K. Danish premium beverage producers and German organic juice bottlers are absorbing capacity at 25-35% annual equipment procurement rates.
- Powder:Spray-dried or lyophilized nano-aggregates suit dry-mix applications where reconstitution stability determines performance. Bakery premix manufacturers in Belgium and the Netherlands favor these for consistent dispersion in automated dough systems.
- Liquid:Ready-to-pump nano-suspensions integrate directly into continuous processing lines without hydration steps.
- Granules:Agglomerated nano-capsules flow freely for seasoning and coating applications in savory snack production.
Emulsions command premium positioning in beverage applications; Powder dominates bakery and dry-mix volume.
End User:
Buyer technical sophistication and in-house R&D capacity determine whether procurement favors turnkey systems or component sourcing.
- Nutraceutical Firms:Precision fermentation clusters in Berlin and Munich are compressing development cycles for probiotic nano-stabilization. These buyers demand multi-layer carriers that protect heat-sensitive bacterial strains through pasteurization while enabling controlled intestinal release.
- Food Manufacturers:Mid-size European processors are consolidating supplier relationships around complete flavor-stabilization modules rather than sourcing carrier matrices and payload compounds separately.
- Beverage Producers:Clean-label transparency requirements drive nano-emulsion adoption for lipophilic vitamin delivery without visual clouding.
- Snack Companies:Sodium reduction targets in savory categories depend on nanoscale salt distribution that maintains taste intensity at 20-40% lower inclusion rates.
Nutraceutical Firms invest most aggressively per unit volume; Food Manufacturers provide the broadest addressable base.
Application:
Thermal processing severity and water activity levels dictate carrier wall material selection and release kinetics engineering.
- Dairy Products:UHT and retort sterilization demands drive multi-layer lipid-polymer carriers that withstand 135-145°C exposure while protecting protein-crosslinking enzymes and probiotic viability. German dairy technology institutes are validating these systems for ambient-stable yogurt drinks.
- Confectionery:Fat-bloom control and flavor burst timing in chocolate and panned candies rely on precise nano-capsule melting-point tuning. Belgian and Swiss manufacturers lead formulation partnerships with encapsulation technology providers.
- Bakery Items:Yeast-raised and chemically leavened matrices require carriers that survive proofing and baking without premature payload release.
- Sauces:Acidic, high-water-activity environments challenge wall material integrity for emulsified dressings and condiments.
Dairy Products anchor current revenue concentration; Confectionery offers the steepest expansion trajectory as premium chocolate houses accelerate sodium and sugar reduction programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in Germany and the Netherlands while consumption spreads across developed markets with stringent clean-label mandates. Regulatory divergence between precautionary European frameworks and case-by-case FDA review shapes cross-border investment flows. Precision fermentation infrastructure in Northern Europe is compressing carrier matrix development cycles faster than scaling can match.
Germany
Berlin and Munich precision fermentation clusters are driving formulation partnerships for probiotic nano-stabilization systems. EFSA's nanotoxicology dossier requirements under EU Novel Food Regulation 2015/2283 are accelerating investment in standardized testing infrastructure. The Bavarian food-tech corridor hosts BASF SE and Royal DSM development facilities where lipid-based carrier matrices undergo commercial validation for UHT dairy applications.
United States
Clean-label beverage processors in California and the Northeast are adopting nano-emulsion systems for lipophilic vitamin delivery without visual clouding. FDA's GRAS notification framework permits faster market entry than European equivalents, though case-by-case review variability complicates capital planning. DuPont de Nemours anchors North American supply through integrated nutrition and biosciences operations in Delaware and Iowa.
China
SAMR's explicit nanomaterial labeling mandate on prepackaged foods is reshaping export documentation workflows for multinational formulators. Shanghai and Beijing laboratories are consolidating testing partnerships to preempt customs delays for transparent packaging categories. The Yangtze River Delta beverage manufacturing belt is absorbing nano-dispersion equipment at rates outpacing domestic carrier chemistry development.
Switzerland
Swiss confectionery houses in the Lake Geneva region deploy flavor-enhancer nanoencapsulation to meet front-of-pack sodium and sugar reduction thresholds. Swissmedic maintains alignment with EFSA guidelines while offering streamlined access to EU market pathways. The Basel pharmaceutical-nutrition corridor transfers controlled-release expertise from drug delivery into functional food carrier design.
Netherlands
Dutch plant-milk processors and bakery premix manufacturers are standardizing phospholipid bilayer carriers to replace synthetic preservatives. REACH compliance for polyethylene glycol derivatives extends registration timelines, delaying next-generation carrier chemistries. The Wageningen food innovation cluster compresses development cycles for fermentation-derived encapsulant precursors that reduce synthetic surfactant dependence.
Nanoencapsulated Food Additives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across carrier chemistry and application-specific formulation tiers. The market structure consolidates around three strategic archetypes: integrated chemical-nutrition houses with polymer science heritage, fermentation-derived encapsulant specialists, and turnkey system providers bundling equipment with active compounds. Dominant competitive moves include backward integration into precision fermentation capacity and geographic expansion through pre-validated regulatory documentation systems.
Within the integrated chemical tier, BASF SE and DuPont de Nemours exemplify diversified conglomerates leveraging polymer science and nutrition-bioscience divisions respectively. Royal DSM occupies a specialist position focused on fermentation-derived encapsulant precursors. These three anchors represent contrasting strategic postures: synthetic carrier matrix supply, integrated North American distribution, and bio-derived surfactant reduction.
| Leading Market Players |
|---|
| BASF SE |
| DuPont de Nemours, Inc. |
| Frutarom Industries Ltd. |
| AQUANOVA AG |
| GF Fermentech |
| Evonik Industries AG |
| Royal DSM |
| International Flavors & Fragrances |
| Encapsula NanoSciences LLC |
| Others |
Value Network & Pricing Analysis
Cross-trained formulation chemists concentrated in Germany's Bavarian corridor and the Netherlands' Wageningen cluster command wage premiums that widen pricing spreads between premium fermentation-derived encapsulants and commodity synthetic alternatives. Labor-cost differentials between these precision fermentation hubs and lower-cost Eastern European manufacturing zones stratify end-product pricing tiers for multinational food manufacturers sourcing nanoencapsulation systems.
Pricing Analysis
Margin tightening in standard-grade synthetic wall materials reflects corn and potato starch price volatility swinging 15-30% seasonally. Pricing stratifies across premium fermentation-derived, standard modified-starch, and economy synthetic-surfactant tiers, with EFSA nanotoxicology dossier compliance costs driving differentiation between validated and non-validated suppliers. Beverage processors in Germany and Switzerland demonstrate lowest price sensitivity due to clean-label transparency mandates, while mid-size bakery premix manufacturers in Belgium face acute cost compression from legacy equipment amortization burdens.
Supply Chain Analysis
Returns and quality-control rework flows from nano-emulsion stability failures concentrate in beverage manufacturing clusters, forcing carriers back to German and Dutch toll processors for re-homogenization. Supply concentrates in Germany, the Netherlands, and Switzerland for lipid-based carrier matrices, with phospholipid feedstocks drawing from Ukrainian sunflower and German rapeseed crushing operations. Single-source vulnerability permeas polyethylene glycol derivative supply under REACH registration delays. Distribution runs through integrated nutrition houses with captive logistics networks rather than merchant chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Novel Food Regulation 2015/2283 erects a cost-of-compliance moat that rewards pre-invested formulators with barrier-to-entry protection against undercapitalized competitors. EFSA's comprehensive nanotoxicology dossier requirements favor incumbents with standardized testing infrastructure already operational.
For Market Incumbents: Deepen backward integration into precision fermentation capacity in Berlin and Munich clusters to secure captive supply of lipid-based carrier matrices against emerging bio-derived specialists. Fortify regulatory documentation automation systems to compress GRAS notification timelines for North American market defense against European competitors seeking FDA pathway arbitrage. For New Entrants and Emerging Players: Begin with probiotic stability applications in ambient-stable functional foods, the most penetrable white space where heat-sensitive bacterial strain protection commands premium pricing and incumbent coverage remains sparse. Pursue turnkey system bundling partnerships with mid-size Dutch and Belgian food manufacturers consolidating supplier relationships away from component-only vendors. For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-derived encapsulant specialists given carrier chemistry convergence dissolving synthetic-bio boundaries and precision fermentation infrastructure scarcity in Northern Europe. Monitor SAMR pre-validated documentation system penetration rates among multinational formulators as inflection signal for China export competitiveness tiering.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Captive lipid-based carrier matrix supply secures margin control against agricultural feedstock volatility. |
| Regulatory Documentation Automation | Pre-validated EFSA and SAMR dossier systems compress time-to-market for novel nanoencapsulation formulations. |
| Turnkey System Bundling Partnerships | Complete flavor-stabilization modules concentrate buyer relationships and displace component-only vendor negotiations. |
| High-Pressure Homogenization Equipment Procurement | Sub-$500K production line democratization enables mid-size processor market entry previously restricted to multinationals. |
| Supercritical CO2 Extraction Technology Adoption | Residue-free carrier production absorbs capital from coacervation lines in German and Danish beverage processing clusters. |
Research Methodology
EFSA guidance documents, FDA GRAS notification databases, and REACH registration filings formed the secondary backbone, cross-referenced with primary interviews spanning nanoencapsulation R&D directors at integrated chemical-nutrition houses, regulatory affairs leads managing Novel Food dossier submissions, procurement officers at German dairy cooperatives, and precision fermentation facility managers in Dutch plant-milk processing clusters. Bottom-up volume modeling from equipment procurement rates and top-down value triangulation from carrier matrix pricing validated convergence points.
Historical trendline analysis of high-pressure homogenization equipment deployment rates and supercritical fluid extraction capacity additions informed projection frameworks across payload chemistry, physical state, buyer sophistication tier, and thermal processing severity segments. CAGRs derived from segmented growth rate differential analysis incorporating probiotic stability application penetration curves and clean-label beverage transparency mandate adoption velocities.
Underlying measurement precision varies by segment; emulsion form factors and antioxidant payload categories carry tighter precision than emerging probiotic applications given commercial validation gaps. Forecasts embed assumptions regarding EFSA dossier approval velocity and SAMR labeling enforcement consistency. Practitioners should monitor precision fermentation cluster expansion announcements and GRAS notification queue lengths for early signals of supply capacity and regulatory timeline shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Monoglyceride Market
Food Additives and Ingredients
Food Grade Stearic Acid Market
Food Additives and Ingredients
Canada Food Colorants Market
Food Additives and Ingredients
United States Anti-Caking Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Carob Bean Gum Market
Food Additives and Ingredients
Polyglycerol Esters of Fatty Acids Market
Food Additives and Ingredients
Food Acidulants Market
Food Additives and Ingredients
Nisin for Food Market
Food Additives and Ingredients
Carmine Alternatives Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Japan Food Enzymes Market
Food Additives and Ingredients
Olestra Market
Food Additives and Ingredients
Australia Feed Additives Market
Food Additives and Ingredients
Ascorbyl Palmitate Market
Food Additives and Ingredients
Non-PHO Emulsifiers Market