
 Food Preservatives Market | 2026-2036
Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Food Preservatives Market Intelligence
Ingredient licensing revenue is fragmenting as food manufacturers internalize formulation capabilities and reduce third-party dependence. Cargill leverages its global supply chain to dominate natural preservative sourcing. Kerry Group differentiates through integrated taste-and-preservation systems that anchor long-term supply contracts.
Food preservatives comprise chemical or biological compounds—such as sorbates, benzoates, nisin, and rosemary extract—added at concentrations typically ranging from 0.01% to 0.3% to inhibit microbial spoilage, oxidative rancidity, and enzymatic degradation in packaged foods. Natural preservatives command premium positioning as consumer label scrutiny intensifies, while biopreservatives represent the fastest-expanding category driven by fermentation-derived antimicrobials. Synthetic variants retain volume leadership in cost-sensitive meat processing applications where EFSA and FDA thresholds permit continued use.
FDA oversight of Generally Recognized As Safe determinations and EFSA's re-evaluation of benzoate exposure limits are constraining synthetic preservative formulations and redirecting R&D budgets toward plant-derived alternatives. India's FSSAI has tightened additive maximum limits in dairy and beverage categories, compelling domestic reformulation. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance-driven supply disruptions.
Market Dynamics
Clean-label mandates from EFSA and FDA are forcing synthetic preservative displacement, while fermentation-derived biopreservatives capture formulation budgets across bakery and dairy chains.
Growth Catalysts
- FSSAI enforcement in India:Tighter additive maximum limits in dairy and beverage categories compel domestic manufacturers toward plant-derived alternatives, expanding local biopreservative production capacity.
- Fermentation technology maturation:Industrial-scale production of nisin and natamycin achieves cost parity with synthetic benzoates in meat and cheese applications, accelerating commercial adoption.
- Bakery chain procurement:Clean-label positioning in European and North American retail bakery segments drives reformulation contracts for rosemary extract and cultured dextrose systems.
Market Restraints
- Natural extract supply concentration:Rosemary and green tea extract sourcing clusters in Mediterranean and Chinese agricultural zones, exposing formulators to climate-driven harvest volatility and price spikes.
- EFSA benzoate re-evaluation:Pending exposure limit reductions for sodium benzoate in beverages create regulatory uncertainty, freezing long-term synthetic formulation investments.
- Technical performance gaps:Natural preservatives exhibit narrower pH efficacy windows and shorter shelf-life extension compared to synthetic sorbates in high-moisture applications, constraining direct substitution.
Strategic Opportunities
- India domestic manufacturing:BIS standards alignment and FSSAI enforcement create captive demand for locally produced biopreservatives, rewarding greenfield fermentation capacity.
- Active packaging convergence:Integration of antimicrobial films with edible coatings enables dual-function preservation systems in ready-to-eat protein segments.
- Direct-to-manufacturer platforms:Digital ingredient marketplaces bypass traditional distributor markups, compressing procurement cycles for mid-size food processors.
Industry Challenges
- Formulation science talent scarcity:Shortage of specialists bridging microbiology, food chemistry, and sensory science delays clean-label reformulation timelines for legacy brands.
- GRAS self-determination complexity:FDA notification requirements for novel plant extracts extend commercialization timelines and elevate legal compliance costs.
- Legacy equipment incompatibility:Existing synthetic dosing infrastructure requires retrofitting for heat-sensitive natural preservative handling, elevating capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Preservatives Market |
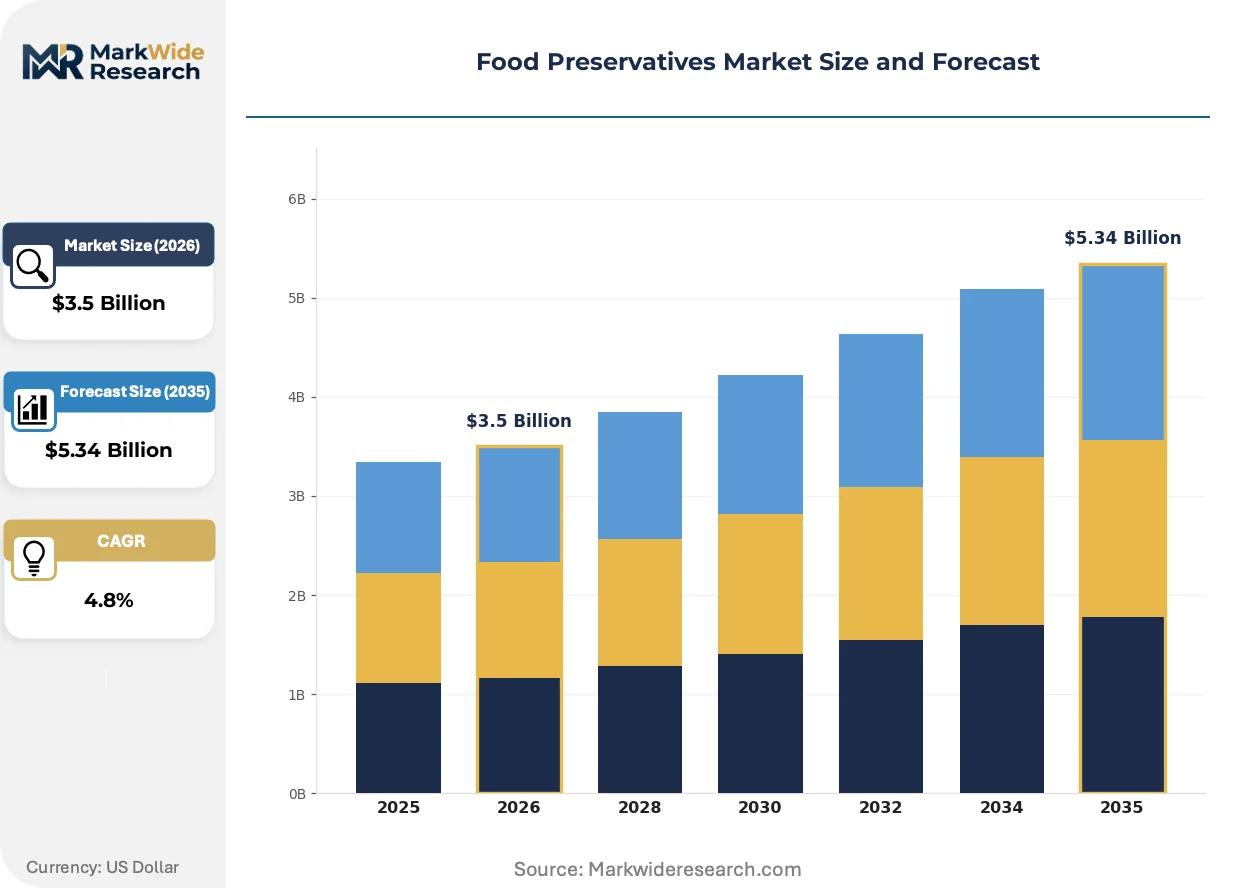
| Market Size in 2026 | $3.5 Billion |
| Market Size in 2035 | $5.34 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Natural, Synthetic, Biopreservatives, Antimicrobial, Antioxidants Application: Dairy Products, Beverages, Baked Goods, Meat Processing, Seafood, Confectionery Packaging Type: Vacuum Sealed, Modified Atmosphere, Aseptic, Canned, Flexible Packaging End User: Food Processing Units, Food Service Providers, Bakery Chains, Beverage Manufacturers, Confectionery Producers |
| Companies Covered | Cargill, DuPont, BASF, Kerry Group, Archer Daniels Midland, Koninklijke DSM, Tate & Lyle, Corbion, Kemin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Preservatives Market Strategic Shifts & Innovations
Digital formulation platforms are compressing R&D cycles while regulatory divergence between FDA and EFSA trajectories forces dual-track compliance architectures.
High-throughput screening of plant antimicrobial peptides is virtualizing traditional extraction-dependent supply chains. Ingredient suppliers deploy AI-driven molecular discovery to identify novel bacteriocins without agricultural cultivation dependencies. North American and European contract manufacturers accelerate adoption, compressing time-to-market for clean-label launches from thirty-six to eighteen months.
REACH authorization requirements for synthetic biocides are tightening preservative substance approvals across EU member states. EFSA's systematic re-evaluation of existing food additives triggers precautionary removals from beverage and infant food categories. German and French formulators redirect R&D expenditure toward fermentation-derived alternatives ahead of anticipated restriction schedules.
Retailer private-label procurement departments consolidate supplier panels, demanding integrated taste-preservation-texture systems rather than commodity ingredients. This bundling displaces standalone preservative vendors from preferred supplier status. The concentration is most pronounced in UK and Scandinavian retail chains, where own-brand penetration exceeds sixty percent of shelf space.
Food Preservatives Market Segmentation
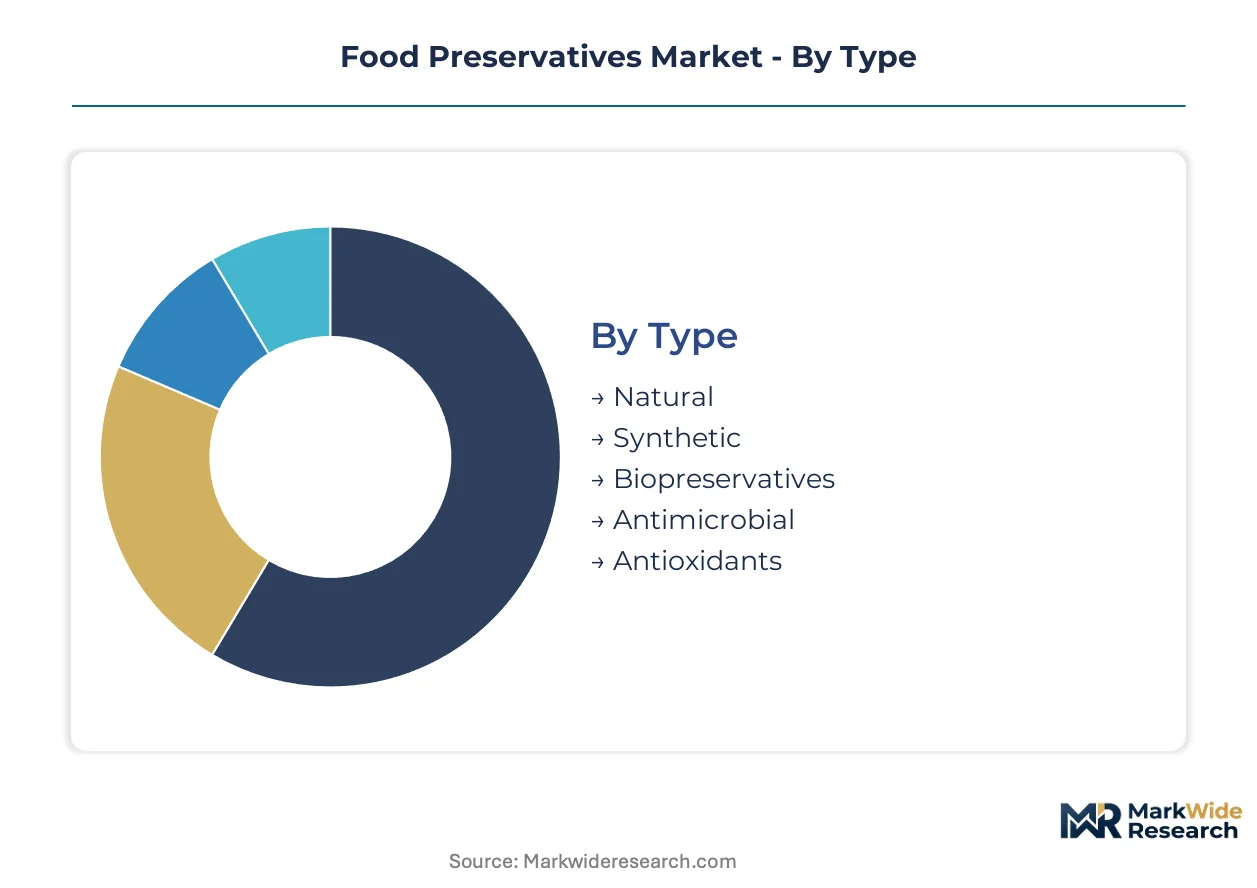
Preservative selection cascades through formulation cost, regulatory compliance, and shelf-life targets. Each segmentation dimension captures distinct procurement behaviors and technical trade-offs that reshape supplier positioning.
Type:
Mature synthetic chemistries coexist with emerging fermentation platforms across price-sensitive and premium formulation tiers.
- Natural:Plant-derived extracts including rosemary oleoresin and green tea polyphenols function as oxidation inhibitors. Bakery chains in France and Germany prioritize these for clean-label positioning despite narrower pH efficacy windows.
- Synthetic:Sorbates and benzoates deliver broad-spectrum antimicrobial performance at low inclusion rates. Meat processors in Brazil and Mexico retain volume concentration here due to cost thresholds and ANVISA permissiveness.
- Biopreservatives:Bacteriocins such as nisin and natamycin derived from controlled fermentation.
- Antimicrobial:Substances targeting specific spoilage organisms through membrane disruption.
- Antioxidants:Compounds interrupting lipid oxidation cascades in high-fat matrices.
Synthetic variants retain volume leadership; biopreservatives hold the steepest expansion curve.
Application:
Moisture content and pH boundaries dictate preservative efficacy across processing environments.
- Dairy Products:Fermented milk matrices require pH-tolerant preservatives. Indian FSSAI enforcement on additive maximum limits is redirecting yogurt and paneer manufacturers toward nisin-based systems in Maharashtra and Gujarat processing clusters.
- Beverages:High-water-activity formulations demand solubility-optimized preservatives. EFSA benzoate re-evaluation is freezing long-term synthetic investments in German and Italian carbonated drink facilities.
- Baked Goods:Intermediate moisture products balance mold inhibition with yeast compatibility.
- Meat Processing:Protein-rich substrates with fat oxidation susceptibility.
- Seafood:Highly perishable matrices with histamine formation risks.
- Confectionery:Low-water-activity environments with fat bloom concerns.
Beverage applications command the most volatile reformulation activity; dairy represents the most regulated conversion pressure.
Packaging Type:
Barrier properties determine whether preservatives function as primary or secondary shelf-life extension mechanisms.
- Vacuum Sealed:Oxygen exclusion reduces aerobic spoilage pressures, permitting lower preservative loadings. Ready-to-eat protein processors in Spain and Poland deploy this combination for chilled distribution.
- Modified Atmosphere:Gas composition manipulation extends lag phases for spoilage flora. UK retail chains specify carbon dioxide-nitrogen blends with cultured dextrose for sandwich and salad applications.
- Aseptic:Commercial sterilization eliminates bioburden before packaging.
- Canned:Thermal processing achieves shelf stability without chemical preservatives.
- Flexible Packaging:Variable barrier films requiring preservative backup for oxygen ingress.
Modified atmosphere systems are gaining share fastest; aseptic packaging anchors the highest absolute preservative displacement.
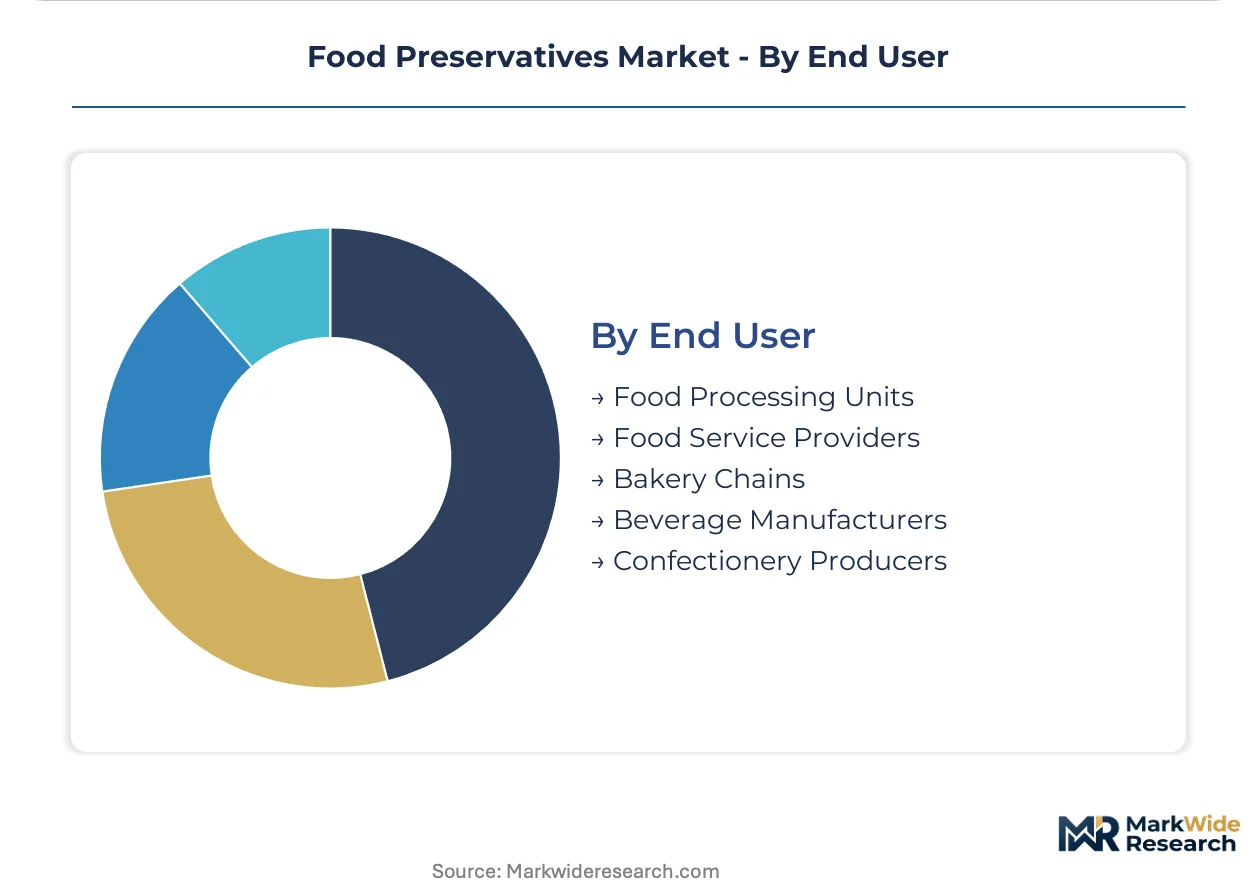
End User:
Scale and formulation autonomy separate captive blending operations from ingredient-dependent processors.
- Food Processing Units:Integrated manufacturing with in-house microbiology capabilities. Large Brazilian beef exporters maintain captive preservative blending operations to bypass distributor markups.
- Bakery Chains:Central commissaries with standardized formulation protocols. Scandinavian retail-owned bakery networks mandate rosemary extract across all private-label bread lines.
- Food Service Providers:Distributed preparation with limited shelf-life extension needs.
- Beverage Manufacturers:High-volume liquid processing with continuous dosing systems.
- Confectionery Producers:Fat-based matrices with oxidation-dominant spoilage modes.
Food processing units retain volume leadership; bakery chains hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys fermentation-derived biopreservatives at scale for dairy reformulation, while Germany and the United States retain synthetic chemistries for cost-sensitive meat processing despite tightening EFSA and FDA exposure limits.
United States
Beverage manufacturers in California and Texas confront FDA GRAS notification delays for novel plant extracts. The agency's systematic re-evaluation of benzoate safety thresholds has frozen long-term synthetic investments in carbonated drink facilities. Chicago-area meat processors maintain captive sorbate blending operations to bypass distributor markups.
Germany
EFSA's REACH authorization tightening for synthetic biocides redirects R&D expenditure toward nisin and natamycin systems. Bavarian dairy cooperatives accelerate cultured dextrose adoption ahead of anticipated restriction schedules. Frankfurt formulation houses consolidate supplier panels to demand integrated taste-preservation systems.
India
FSSAI enforcement on additive maximum limits in yogurt and paneer segments compels Maharashtra and Gujarat processing clusters toward domestic nisin production. BIS standards alignment rewards greenfield fermentation capacity in Hyderabad and Bangalore. Local biopreservative manufacturing captures reformulation budgets from multinational ingredient distributors.
Brazil
ANVISA permissiveness sustains synthetic sorbate concentration in São Paulo beef export facilities. Cost thresholds block natural preservative substitution in commodity meat processing. Campinas and Curitiba industrial zones maintain backward integration into captive preservative blending to compress procurement cycles.
China
SAMR oversight of GB standards for food additives tightens maximum limits in beverage categories. Yangtze River Delta formulation houses deploy rosemary extract systems for bakery chain private-label contracts. Shanghai and Hangzhou processors invest in fermentation technology maturation for cost-competitive biopreservative output.
Food Preservatives Market Key Industry Players
Capability concentration sits with fermentation technology specialists; scale advantage sits with diversified ingredient conglomerates. The vendor base arranges across three tiers: integrated taste-preservation systems providers, commodity synthetic chemical suppliers, and emerging biopreservative pure-plays. Dominant competitive moves include strategic partnerships between fermentation technology licensors and regional distributors, plus capacity expansion in Indian and Chinese domestic manufacturing zones.
Within the integrated systems tier, Kerry Group and Cargill exemplify divergent scale-versus-specialization positioning. Kerry Group anchors formulation partnerships through combined taste-and-preservation platforms, while Cargill leverages upstream agricultural supply chain control. Corbion represents the biopreservative pure-play archetype, occupying a position between fermentation technology maturation and commercial-scale bacteriocin production. These three entities collectively illustrate the market's structural tension between commodity volume leadership and clean-label premium capture.
| Leading Market Players |
|---|
| Cargill |
| DuPont |
| BASF |
| Kerry Group |
| Archer Daniels Midland |
| Koninklijke DSM |
| Tate & Lyle |
| Corbion |
| Kemin Industries |
| Others |
Cost & Logistics Intelligence
Tariff exposure between Mediterranean rosemary extract suppliers and North American bakery chains compresses margin structures across natural preservative tiers while simultaneously forcing dual-sourcing configurations that elevate working capital requirements. This regulatory-trade intersection determines both the premium commanded by fermentation-derived alternatives and the residual viability of synthetic benzoate systems in cost-sensitive meat processing corridors.
Pricing Analysis
Long-term offtake agreements dominate biopreservative procurement as dairy reformulation timelines in India and Germany extend eighteen to thirty-six months. Three-tier pricing structure across premium, standard, and economy levels separates certified organic rosemary extracts from conventional fermentation-derived bacteriocins and commodity sorbate bulk supply. Cost compression in synthetic tiers intensifies because EFSA benzoate re-evaluation freezes capacity expansion commitments. Mid-size Brazilian meat processors exhibit highest price sensitivity; Scandinavian retail bakery chains demonstrate least.
Supply Chain Analysis
Tariff exposure between Chinese green tea polyphenol processors and European beverage manufacturers dominates supply chain risk calculations for antioxidant sourcing. Raw material flows draw from Mediterranean rosemary cultivation zones, Yangtze River Delta fermentation facilities, and Indian nisin production clusters in Hyderabad and Bangalore. Fermentation media and agricultural extraction feedstocks constitute critical input dependencies. Single-source vulnerability concentrates in Mediterranean oleoresin supply. Distribution runs through regional ingredient distributors with formulation technical service attachments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food preservative procurement is evolving toward integrated taste-preservation-texture service contracts where technical formulation support captures recurring revenue streams expanding faster than commodity ingredient sales. This service-attach dynamic rewards suppliers capable of anchoring long-term partnership structures.
For Market Incumbents: Pre-empt displacement by synthetic alternatives through captive fermentation capacity expansion in Indian BIS-aligned manufacturing zones. Anchor formulation partnerships with Scandinavian retail bakery chains before supplier panel consolidation freezes out standalone preservative vendors. Certification investment in FSSAI-compliant production systems represents the critical defensive lever. For New Entrants and Emerging Players: Build out domestic Indian biopreservative manufacturing to capture FSSAI-driven dairy reformulation budgets in Maharashtra and Gujarat processing clusters. White-space concentration sits in fermentation-derived natamycin systems for yogurt applications where import substitution creates procurement urgency. Direct-to-manufacturer digital platforms bypass traditional distributor markups as the preferred go-to-market angle. For Investors and Strategic Acquirers: EFSA's systematic benzoate re-evaluation reshapes the acquisition landscape toward fermentation technology specialists with commercial-scale bacteriocin production capability. Long-term viability frames around regulatory acceleration of natural displacement rather than synthetic retention. Target acquisition archetype: biopreservative pure-plays with Indian or Chinese domestic manufacturing footprints. Monitor FSSAI enforcement intensity as the signal indicating reformulation budget velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captures FSSAI-driven dairy reformulation demand in Indian processing clusters. |
| Backward Integration into Agricultural Extraction | Secures rosemary oleoresin supply against Mediterranean climate volatility. |
| Integrated Taste-Preservation Systems | Locks in Scandinavian retail bakery chain procurement through bundled service contracts. |
| Digital Direct-to-Manufacturer Platform | Compresses procurement cycles for mid-size Brazilian and Mexican meat processors. |
| Regulatory Certification Investment | Accelerates FDA GRAS notification pathways for novel plant-derived antimicrobial peptides. |
Research Approach
The analysis maps natural extract, synthetic chemical, and fermentation-derived biopreservative sub-sectors, each validated through formulation scientists at European bakery chains, procurement directors at Indian dairy cooperatives, and regulatory affairs specialists at multinational ingredient suppliers. Primary interview data triangulates against secondary sources including FDA GRAS notification filings, EFSA additive re-evaluation dossiers, FSSAI maximum limit notifications, and customs trade flow records. Bottom-up segment sizing and top-down market validation ensure cross-verification.
Assumptions held fixed include EFSA benzoate exposure limit trajectories and FSSAI enforcement intensity across the projection horizon; variables tested include fermentation technology cost curves and rosemary harvest yield volatility. Segmentation dimensions modeled encompass preservative type, application matrix moisture content, packaging barrier properties, and end-user formulation autonomy. CAGRs derive from segment-level volume projections calibrated against regulatory-driven reformulation timelines. Industry-specific forecast inputs include fermentation scale-up curves and clean-label procurement penetration rates.
Practitioners should monitor EFSA restriction schedules and FSSAI inspection intensity for early signals of reformulation acceleration or deceleration. Forecasts reflect assumptions about regulatory trajectory continuity and fermentation cost parity achievement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Japan Feed Additives Market
Food Additives and Ingredients
Africa Food Enzymes Market
Food Additives and Ingredients
France Adjuvants Market
Food Additives and Ingredients
Global Cereal Ingredients Market
Food Additives and Ingredients
Global Food Release Agents Market
Food Additives and Ingredients
Argentina Food Colorants Market
Food Additives and Ingredients
South America Brewing Enzymes Market
Food Additives and Ingredients
Wheat & Rice Flour Substitute-Resistant Starch Market
Food Additives and Ingredients
Fat Replacers Salt Reducers and Replacers Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Global Gamma Linolenic Acid Market
Food Additives and Ingredients
Egypt Food Emulsifiers Market
Food Additives and Ingredients
Protective Cultures Market
Food Additives and Ingredients
Distilled Monoglycerides Market
Food Additives and Ingredients
Baking Enzymes Market
Food Additives and Ingredients
Casamino Acids Market