
 Excipients Market | 2026-2036
Excipients Market Size, Share, and Industry Trends Forecast 2026-2036
Excipients Market Intelligence
Specialty chemical production in Germany is shifting toward high-purity pharmaceutical grades as European formulators tighten ingredient specifications. BASF SE anchors its position through backward integration into carbohydrate chemistry for tablet binders. Roquette Frères leverages its plant-based extraction expertise to dominate starch-derived excipient supply. Evonik Industries differentiates via synthetic polymer leadership in controlled-release applications.
Excipients are pharmacologically inactive substances formulated alongside active pharmaceutical ingredients to confer bulk, stability, dissolution, or processability, with specifications typically requiring endotoxin levels below specified thresholds and heavy metal content compliant with pharmacopeial monographs. Binders and fillers constitute the mature volume core where margin compression is acute, while disintegrants capture expanding value as immediate-release formulations dominate generic pipelines. Pharmaceutical companies remain the primary demand anchor, though contract manufacturers are gaining procurement leverage as outsourcing of formulation steps accelerates.
The FDA enforces ICH Q3D elemental impurity limits through drug master file reviews, while the EMA coordinates pharmacopeial harmonization across EU member states via the European Pharmacopoeia Commission, and India's CDSCO mandates excipient registration for imported ingredients used in domestic formulations. These frameworks elevate compliance costs for non-compliant suppliers while creating preferential access for certified manufacturers. Stakeholders must monitor evolving nitrosamine risk assessments and their downstream specification impacts on polymer and lipid excipient categories.
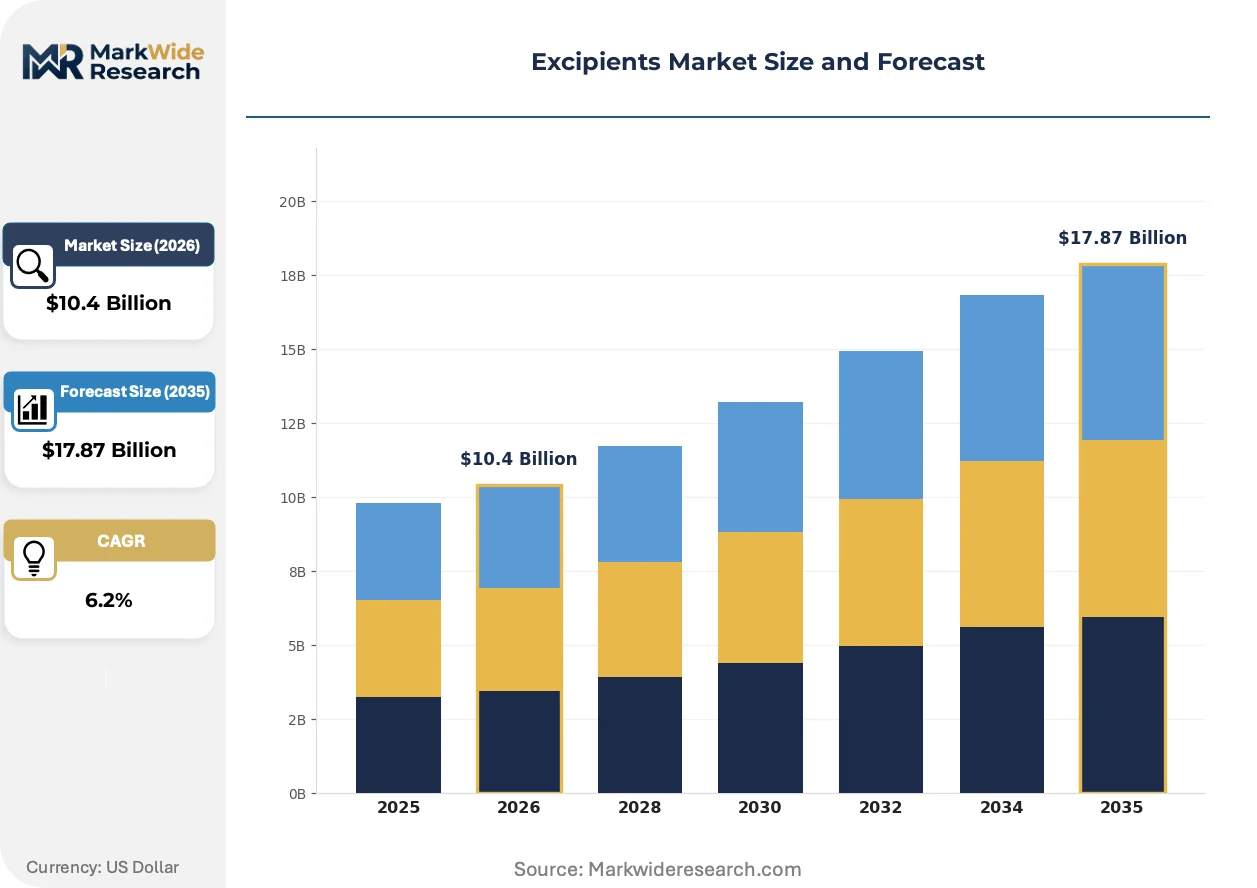
Market Dynamics
Oral solid dosage form expansion is compressing excipient supply chains as pharmaceutical companies consolidate procurement around high-purity carbohydrate and polymer grades compliant with tightening elemental impurity limits.
Growth Catalysts
- ICH Q3D Compliance:The FDA's elemental impurity guideline is forcing supplier upgrades that favor certified manufacturers with validated purification infrastructure.
- India:Contract manufacturing organizations are scaling formulation capacity for export markets, driving bulk excipient consumption in tablet binders and disintegrants.
- Controlled-Release Polymers:Synthetic polymer innovation in sustained-delivery formulations is capturing premium value as generic pipelines prioritize bioequivalence differentiation.
Market Restraints
- Maize Starch Volatility:Agricultural input costs for plant-derived excipients fluctuate with climate patterns and commodity trading, squeezing margin on mature filler grades.
- European Supplier Concentration:Specialty chemical production for pharmaceutical-grade carbohydrates clusters in Germany and France, creating single-source vulnerability for formulators.
- Endotoxin Testing Bottlenecks:Pharmacopeial monograph compliance requires validated LAL testing capacity that smaller suppliers struggle to maintain.
Strategic Opportunities
- Brazil:ANVISA's harmonization with ICH standards is opening import pathways for certified excipient suppliers previously locked out by local registration barriers.
- Biologic Adjuvant Expansion:Lipid and polymer excipients for mRNA delivery systems are penetrating vaccine manufacturing beyond traditional small-molecule applications.
- Direct Distribution Platforms:Digital procurement portals are disintermediating regional distributors for standardized binder and filler grades in mid-volume generic manufacturing.
Industry Challenges
- Pharmaceutical Chemistry Talent Scarcity:Formulation science expertise for excipient-active ingredient compatibility testing is concentrated at legacy manufacturers, constraining new entrant scale-up.
- DMF Amendment Cycles:FDA drug master file updates for specification changes require 12-18 month validation timelines that delay product line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Excipients Market |
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $17.87 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binders, Fillers, Disintegrants, Lubricants Application: Medications, Dietary Supplements, Nutraceuticals, Veterinary Products End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutions, Academic Organizations Form: Granules, Powders, Liquids, Tablets |
| Companies Covered | Evonik Industries, Archer Daniels Midland, BASF SE, International Flavors & Fragrances, Lubrizol Corporation, Roquette Frères, DuPont, Croda International, Ashland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Excipients Market Strategic Shifts & Innovations
Continuous manufacturing adoption is redefining excipient performance specifications as real-time quality assurance replaces batch testing, while sustainability mandates reshape raw material sourcing priorities across supplier bases.
Co-processed excipient systems are integrating multiple functional properties into single-granule platforms that streamline tablet compression workflows. Generic manufacturers in India and Eastern Europe are adopting these pre-engineered blends to reduce qualification overhead. This integration is compressing demand for standalone binders and disintegrants while elevating supplier technical service requirements.
REACH registration deadlines for polymer excipients are compelling European formulators to audit supply chains for SVHC compliance and substitution documentation. The ECHA enforcement framework is accelerating supplier consolidation as mid-tier players lack toxicology data generation capacity. Synthetic polymer categories face the steepest re-registration cost burdens, favoring backward-integrated chemical majors.
Buyer concentration among top-tier contract manufacturers is compressing excipient pricing cycles and unbundling technical service from material supply. Large CMOs in India and North America now negotiate direct supply agreements with carbohydrate and polymer producers, bypassing traditional distribution layers. This disintermediation is most visible in high-volume oral solid dosage applications where specification standardization permits spot-market purchasing.
Excipients Market Segmentation
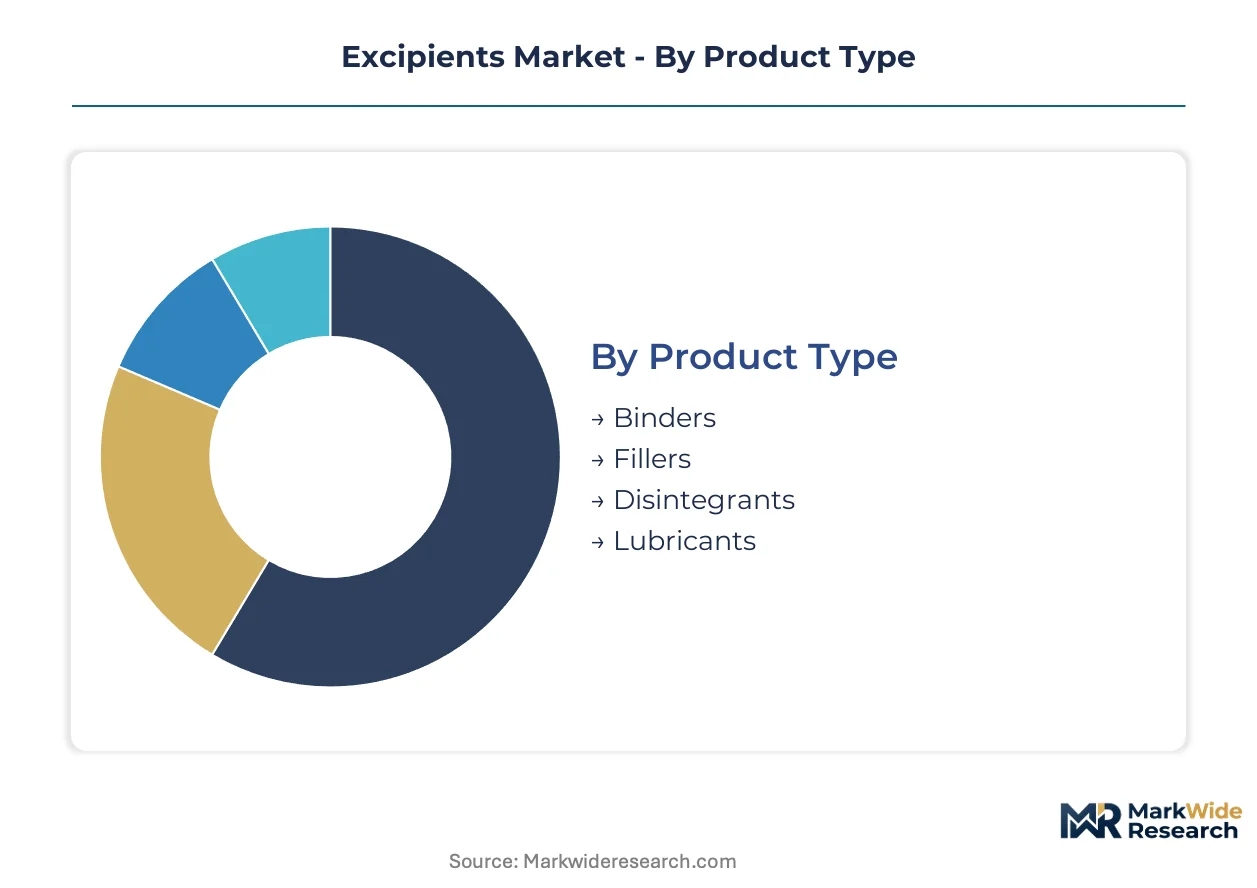
Excipient specifications diverge sharply across dosage forms and regulatory jurisdictions, requiring suppliers to maintain parallel product lines with distinct purity grades and documentation packages. Segmentation clarity enables formulators to match functional requirements with validated supply sources while anticipating compliance burdens from tightening pharmacopeial standards.
Product Type:
Replacement cycles in oral solid dosage manufacturing are accelerating as pharmaceutical companies retire legacy formulations that predate ICH Q3D elemental impurity limits.
- Binders:Carbohydrate and polymer-based adhesion agents ensure tablet structural integrity during compression and handling. Demand concentrates among Indian contract manufacturers scaling export capacity for generic solid dosages, with CDSCO registration requirements favoring suppliers with validated drug master files. Volume placements concentrate in binders; the faster expansion belongs to disintegrants.
- Fillers:Bulking agents including starches, lactose, and microcrystalline cellulose confer mass to low-potency actives. Maize starch supply chains face agricultural volatility that squeezes margin on mature grades, while European formulators tighten specifications around endotoxin thresholds.
- Disintegrants:Superdisintegrant chemistries enable rapid tablet breakup for immediate-release bioequivalence. Croscarmellose sodium and sodium starch glycolate capture premium value as generic pipelines prioritize dissolution profile differentiation.
- Lubricants:Magnesium stearate and stearic acid reduce die wall friction during high-speed compression. EMA pharmacopeial harmonization across EU member states elevates compliance costs for non-certified suppliers.
Margin compression is most acute in mature filler grades where specification standardization permits spot-market purchasing.
Application:
Cost tier differentiation separates premium pharmaceutical grades from commodity nutraceutical specifications, with regulatory documentation burden as the primary price driver.
- Medications:Prescription drug formulations impose the strictest purity requirements, with FDA drug master file reviews enforcing endotoxin and heavy metal limits through ICH Q3D. Synthetic polymer innovation in controlled-release applications captures value as bioequivalence differentiation intensifies.
- Dietary Supplements:Nutraceutical tablets and capsules operate under lighter regulatory frameworks but face rising quality expectations from retail channel consolidation. USP verification programs are displacing unverified suppliers in North American distribution.
- Nutraceuticals:Functional food and beverage applications demand excipient compatibility with diverse active matrices including probiotics and botanical extracts. Plant-derived carbohydrate chemistry from Roquette Frères and BASF SE anchors supply security.
- Veterinary Products:Animal health formulations tolerate broader specification ranges but require species-specific toxicity documentation. Regulatory divergence between FDA Center for Veterinary Medicine and EMA veterinary pathways fragments supplier qualification requirements.
Documentation intensity peaks in medications; nutraceuticals are climbing the fastest as quality expectations converge with pharmaceutical standards.
End User:
Procurement leverage concentrates with large-scale buyers capable of negotiating direct supply agreements that bypass traditional distribution layers.
- Pharmaceutical Companies:Originators and generic houses maintain internal formulation capabilities with dedicated excipient qualification teams. Backward integration into carbohydrate chemistry at BASF SE and synthetic polymer leadership at Evonik Industries serve these accounts through technical service partnerships.
- Contract Manufacturers:CMOs in India and North America are gaining procurement scale as outsourcing of formulation steps accelerates, unbundling technical service from material supply for standardized grades.
- Research Institutions:Preclinical and early-phase development programs require small-batch excipient supply with rapid specification flexibility. Smaller suppliers struggle to maintain validated LAL testing capacity for these fragmented orders.
- Academic Organizations:University-based formulation research operates on constrained budgets with limited regulatory documentation requirements. Digital procurement portals are disintermediating regional distributors for these mid-volume purchases.
Contract manufacturers command the steepest volume growth; pharmaceutical companies retain the specification-setting authority.
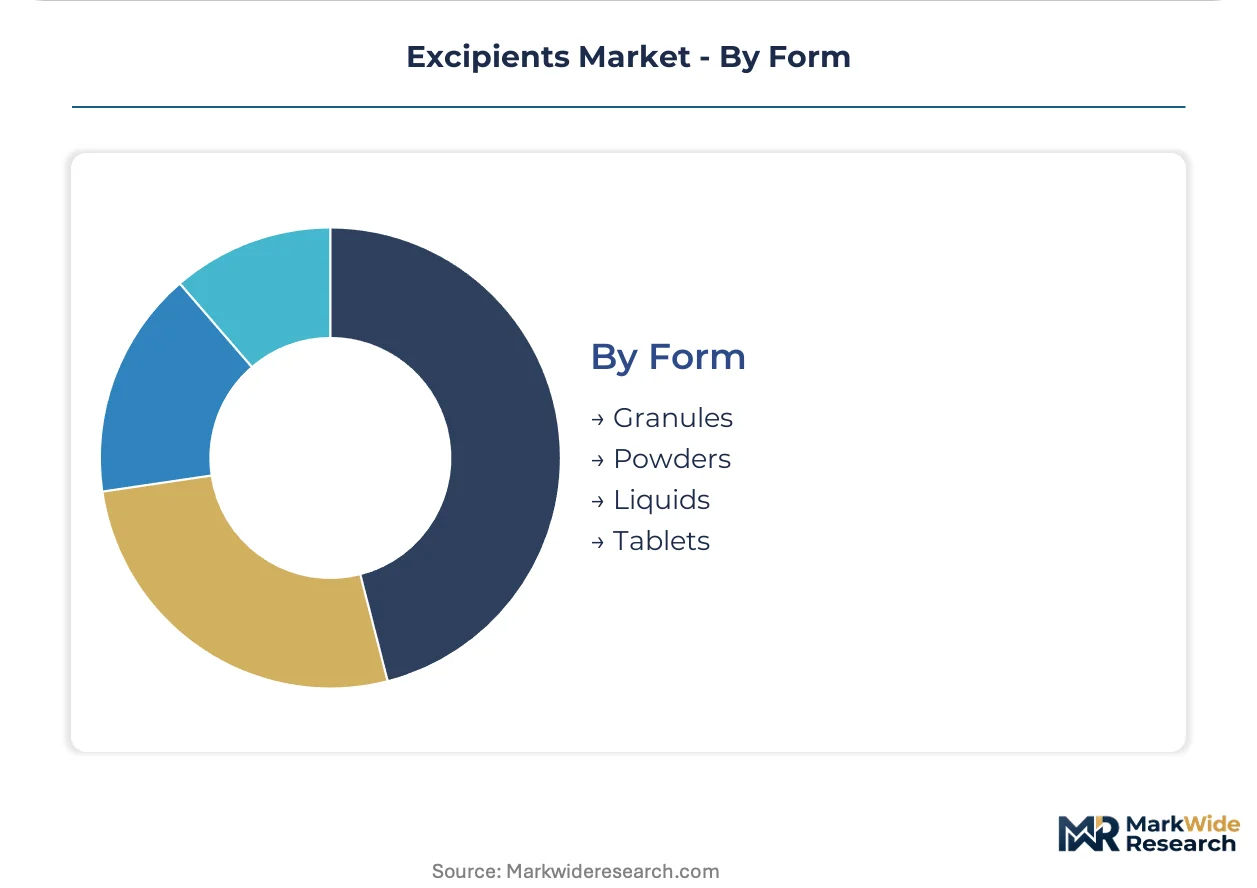
Form:
Physical state determines handling infrastructure requirements, with continuous manufacturing adoption redefining performance specifications across all categories.
- Granules:Co-processed excipient systems integrate multiple functional properties into single-granule platforms that streamline tablet compression workflows. Generic manufacturers in India adopt these pre-engineered blends to reduce qualification overhead.
- Powders:Conventional milled excipients remain the volume foundation for batch-processed solid dosages, though dust containment and flowability challenges elevate handling costs.
- Liquids:Solubilized and suspension-grade excipients serve parenteral and oral liquid formulations with distinct endotoxin and sterility requirements. Lipid excipients for mRNA delivery systems are penetrating vaccine manufacturing beyond traditional small-molecule applications.
- Tablets:Pre-compressed excipient bases enable direct compression of heat-sensitive actives, eliminating granulation steps. Real-time quality assurance in continuous manufacturing lines replaces batch testing for these engineered substrates.
Powder volumes dominate current placements; liquid formulations are expanding most quickly as biologic adjuvant applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maize starch cultivation in the American Midwest and wheat processing clusters across Northern Europe anchor raw material flows for pharmaceutical-grade carbohydrate excipients. Regional demand patterns diverge sharply between mature formulation markets with tightening purity mandates and emerging manufacturing hubs scaling export capacity.
United States
Specialty polymer innovation for controlled-release applications drives demand in New Jersey and Massachusetts pharmaceutical corridors. FDA enforces ICH Q3D elemental impurity limits through drug master file reviews that elevate compliance costs for non-certified suppliers. The Midwest maize belt supplies starch feedstocks to Illinois and Iowa processing facilities where agricultural volatility squeezes margin on mature filler grades.
Germany
Ludwigshafen and Frankfurt chemical clusters anchor European production of synthetic polymer excipients for sustained-delivery formulations. EMA pharmacopeial harmonization via the European Pharmacopoeia Commission tightens endotoxin thresholds for imported ingredients. REACH registration deadlines for polymer categories compel formulators to audit supply chains for SVHC compliance, accelerating consolidation among mid-tier players lacking toxicology data capacity.
India
Contract manufacturing organizations in Maharashtra and Gujarat scale tablet binder and disintegrant consumption for export markets. CDSCO mandates excipient registration for imported ingredients used in domestic formulations, creating preferential access for certified manufacturers with validated drug master files. Ahmedabad and Hyderabad formulation hubs concentrate procurement leverage as large CMOs negotiate direct supply agreements bypassing traditional distribution layers.
China
Pearl River Delta chemical processors expand carbohydrate and polymer output for regional pharmaceutical formulators. NMPA alignment with ICH Q3D standards tightens heavy metal specifications on excipient imports used in domestic medications. Shanghai and Suzhou manufacturing clusters face rising qualification overhead as multinational pharmaceutical companies consolidate procurement around high-purity grades.
Brazil
ANVISA harmonization with ICH standards opens import pathways for certified excipient suppliers previously locked out by local registration barriers. São Paulo and Rio de Janeiro pharmaceutical corridors drive demand for immediate-release disintegrants as generic pipelines prioritize bioequivalence differentiation. Regional formulators increasingly source pre-engineered co-processed excipient blends to reduce qualification timelines.
Excipients Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue biologic adjuvant applications and digital procurement platforms. The vendor base stratifies between backward-integrated chemical majors with captive carbohydrate supply and specialized polymer innovators serving controlled-release niches. Three archetypes dominate: multinational diversified chemical conglomerates, plant-derived extraction specialists, and synthetic polymer technology leaders. Competitive intensity centers on M&A activity consolidating mid-tier carbohydrate processors and capacity expansion in Indian contract manufacturing corridors.
Within the diversified chemical tier, BASF SE and Evonik Industries exemplify multinational conglomerates with integrated pharmaceutical-grade production infrastructure. Roquette Frères occupies a distinct position as a plant-derived extraction specialist leveraging agricultural processing heritage. These three anchors represent divergent strategic postures: synthetic polymer leadership, backward-integrated carbohydrate chemistry, and starch-derived excipient dominance respectively.
| Leading Market Players |
|---|
| Evonik Industries |
| Archer Daniels Midland |
| BASF SE |
| International Flavors & Fragrances |
| Lubrizol Corporation |
| Roquette Frères |
| DuPont |
| Croda International |
| Ashland |
| Others |
Cost & Logistics Intelligence
Family-owned agricultural processors across Northern Europe and the American Midwest anchor raw material supply for pharmaceutical-grade carbohydrates, translating crop ownership into pricing discipline that resists spot-market volatility. Their captive starch production buffers margin compression for downstream formulators while forcing independent distributors to unbundle technical service from material supply.
Pricing Analysis
Technical service bundling separates premium-tier excipient supply from unbundled commodity transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and validated drug master file status. Cost compression in mature filler grades is intensifying because Indian contract manufacturers negotiate direct supply agreements bypassing distribution layers. Research institutions exhibit highest price sensitivity; originator pharmaceutical companies accept premium positioning for controlled-release polymer innovation.
Supply Chain Analysis
Return flows of non-conforming batches and expired inventory require validated destruction protocols that elevate handling costs for carbohydrate and polymer categories. Raw material supply draws from maize cultivation in the United States, wheat processing across Germany and France, and synthetic monomer production in China and India. Single-source vulnerability concentrates in European pharmaceutical-grade carbohydrate clusters. Distribution runs through direct procurement portals for standardized grades and technical service partnerships for specialty polymers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance cost escalation is compressing viable supplier counts, positioning ICH Q3D certification as the consolidation mechanism forcing mid-tier players toward exit or acquisition.
For Market Incumbents: Acquire validated LAL testing infrastructure and drug master file portfolios to defend against disintermediation by Indian contract manufacturers. Deepen backward integration into carbohydrate chemistry to capture margin from agricultural volatility. Prioritize synthetic polymer R&D for controlled-release applications where bioequivalence differentiation sustains premium positioning.
For New Entrants and Emerging Players: Enter via lipid excipient supply for mRNA delivery systems, the most penetrable vector as vaccine manufacturing expands beyond traditional small-molecule boundaries. Target Brazilian formulators through ANVISA harmonization pathways previously blocked by registration barriers. Deploy digital procurement platforms to capture mid-volume generic manufacturing accounts with standardized specification requirements.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier carbohydrate processors in India and Eastern Europe lacking REACH registration capacity. Long-term viability hinges on toxicology data generation infrastructure and pharmacopeial certification depth. Monitor ECHA enforcement actions against SVHC non-compliance as the inflection signal for accelerated supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Drug Master File Portfolio Acquisition | ICH Q3D compliance accelerates valuation premiums for certified suppliers with validated purification infrastructure. |
| Backward Integration into Carbohydrate Chemistry | BASF SE and Roquette Frères demonstrate margin defense through captive maize and wheat processing supply. |
| Co-Processed Excipient System Development | Pre-engineered granule platforms reduce qualification overhead for Indian generic manufacturers compressing procurement cycles. |
| Direct Distribution Platform Launch | Digital procurement disintermediates regional distributors for standardized binder and filler grades in mid-volume manufacturing. |
| Biologic Adjuvant Capacity Expansion | Lipid and polymer excipients for mRNA delivery penetrate vaccine manufacturing beyond traditional small-molecule applications. |
Research Approach
Document review covered FDA drug master file submissions, EMA pharmacopeial harmonization records, and CDSCO registration databases, complemented by interviews with excipient procurement directors at contract manufacturing organizations, technical service leads at synthetic polymer suppliers, and regulatory affairs specialists at carbohydrate processors. Secondary validation drew from customs trade data, SEC filings of diversified chemical conglomerates, and European Pharmacopoeia Commission meeting records. Bottom-up volume modeling triangulated against top-down market sizing across product type and application dimensions.
Historical shipment patterns cross-referenced against panel input from formulation scientists and supply chain executives informed the analytical framework. Segmentation modeling tracked binders, fillers, disintegrants, and lubricants across oral solid dosage and parenteral applications, with regional regulatory cluster as an additional dimension. CAGRs were derived from elasticity-adjusted demand projections incorporating ICH Q3D compliance timelines and contract manufacturing outsourcing intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nitrosamine risk assessment revisions and agricultural commodity price spikes. Practitioners should monitor ECHA SVHC list expansions and FDA warning letter trends for early signals of supplier qualification disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
Lime Oil Market
Food Additives and Ingredients
South America Food Stabilizers Market
Food Additives and Ingredients
Mexico Food Emulsifiers Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
Russia Food Acidulants Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Germany Food Emulsifiers Market
Food Additives and Ingredients
Antimicrobial Packaging Ingredients for Food Packaging Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Egg Stabilizer Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
Organic Food Additives Market
Food Additives and Ingredients
Australia Anti Caking Market
Food Additives and Ingredients
Alpha-Amylase Baking Enzyme Market
Food Additives and Ingredients
South Africa Food Enzymes Market