
 South America Brewing Enzymes Market | 2026-2036
South America Brewing Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
South America Brewing Enzymes Market Insights
Multi-source procurement of specialty enzymes is expanding across South American brewing operations as malt price volatility and supply chain disruptions push facilities toward diversified supplier portfolios. Novozymes A/S leverages its Danish fermentation technology heritage to anchor premium enzyme supply contracts with large-scale Brazilian brewers. Kerry Group plc competes through localized blending operations in São Paulo state, sustaining shorter lead times for liquid amylase formulations. DuPont de Nemours Inc differentiates via granular enzyme stability profiles suited to regional temperature variations during transport.
Brewing enzymes comprise protein-based biocatalysts—primarily amylases, glucoamylases, proteases, and beta-glucanases—typically produced through submerged fermentation of Aspergillus or Bacillus strains, then stabilized in liquid, powder, or granular form for industrial mashing and fermentation control. These biocatalysts accelerate starch conversion, reduce viscosity, and enhance extract yields during beer production and malt processing. Amylase formulations occupy the dominant revenue position given their universal application in liquefaction and saccharification stages across all brewery scales. Liquid form factors lead volume consumption due to dosing precision and blending flexibility, though powder enzymes gain traction among microbreweries seeking extended shelf stability without cold-chain dependency.
ANVISA governs enzyme food additive registrations in Brazil, requiring toxicological dossiers and Good Manufacturing Practice compliance that filter out smaller international suppliers. Argentina's national food safety authority mandates enzymatic activity labeling and origin traceability for imported biocatalysts, shaping procurement documentation burdens. Brazil's PLI scheme for biotechnology inputs indirectly supports domestic enzyme formulation investments, altering cost structures for regional brewers. Stakeholders must monitor regulatory harmonization pressures between Mercosur member states, as divergent approval timelines for novel enzyme variants could fragment supplier access across the continent's largest brewing markets.
Market Dynamics
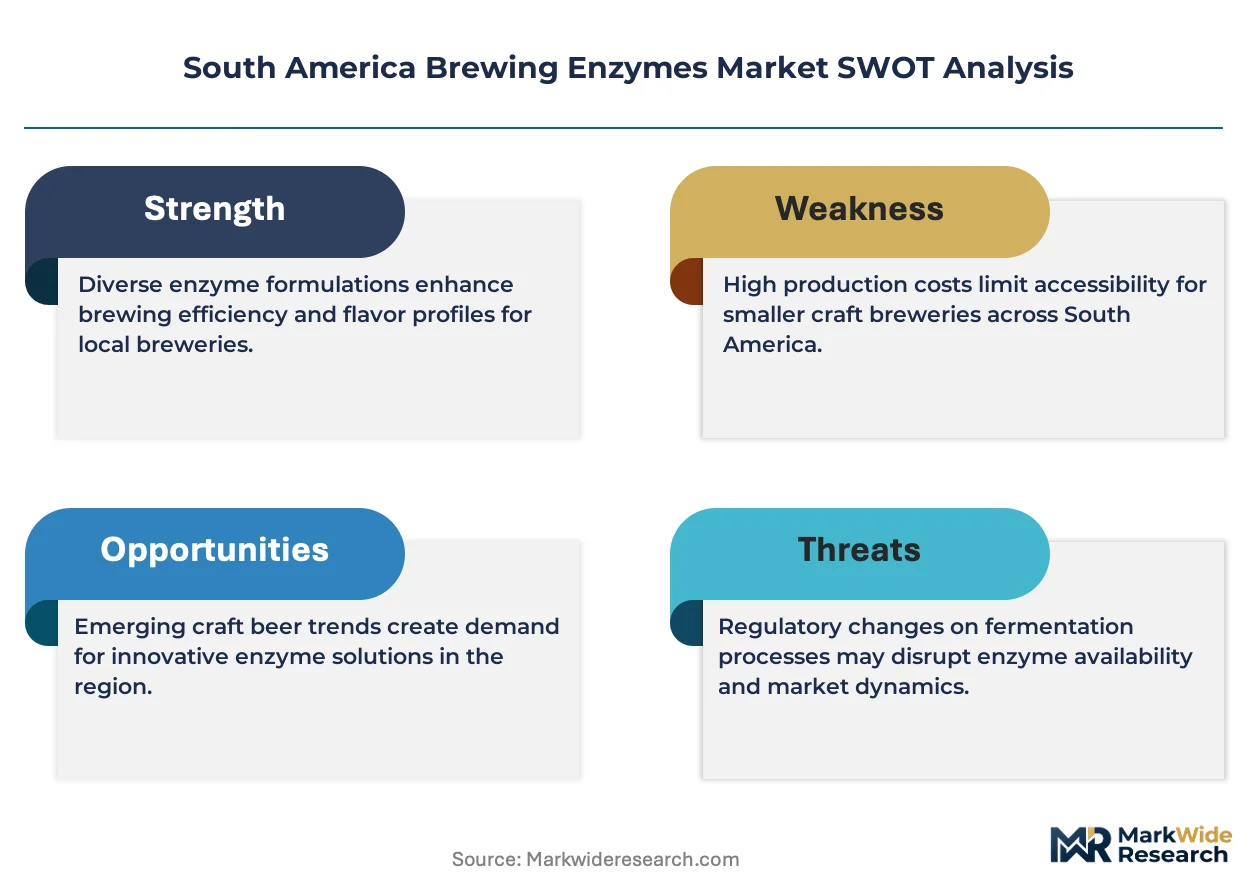
ANVISA's tightening food-grade additive standards are compressing supplier access and forcing Brazilian brewers toward documented traceability systems, reshaping procurement patterns across the continent's largest brewing corridor.
Growth Catalysts
- PLI biotechnology incentives:Brazil's production-linked incentive scheme reduces formulation costs for domestic enzyme investments, lowering barriers for regional brewing operations seeking localized supply.
- Argentina's traceability mandates:Enzymatic activity labeling requirements from the national food safety authority are standardizing quality documentation, filtering out informal suppliers and elevating professional procurement practices.
- Colombian craft brewery expansion:Microbreweries in Bogotá and Medellín are accelerating enzyme adoption for mash efficiency gains, creating demand pull for flexible dosing formats and technical support services.
Market Restraints
- Malt price volatility:Barley and adjunct cost swings force brewers into reactive enzyme purchasing rather than strategic formulation partnerships, compressing margin planning horizons.
- Import concentration risk:Danish and Irish fermentation technology suppliers dominate premium contract positions, exposing Brazilian facilities to currency fluctuation and maritime logistics bottlenecks.
- ANVISA approval timelines:Toxicological dossier requirements for novel enzyme variants create 18-24 month market entry delays, freezing innovation pipelines for international biocatalyst developers.
Strategic Opportunities
- Colombian underpenetration:Industrial brewing capacity outside Bogotá remains enzyme-light, offering first-mover positioning for suppliers establishing regional blending facilities.
- Liquid-to-granular format shift:Temperature-stable granular enzymes address cold-chain gaps in Andean distribution networks, unlocking microbrewery segments previously dependent on powder alternatives.
- Mercosur harmonization pressure:Converging approval frameworks between Brazil, Argentina, and Uruguay could streamline multi-country supplier registrations, reducing compliance fragmentation costs.
Industry Challenges
- Fermentation technologist scarcity:Brazilian universities produce insufficient industrial biochemistry specialists, forcing brewers to import technical talent or rely on supplier field support for enzyme optimization.
- Legacy dosing system incompatibility:Older Brazilian facilities lack precision liquid enzyme injection infrastructure, requiring capital retrofitting or suboptimal manual blending protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Brewing Enzymes Market |
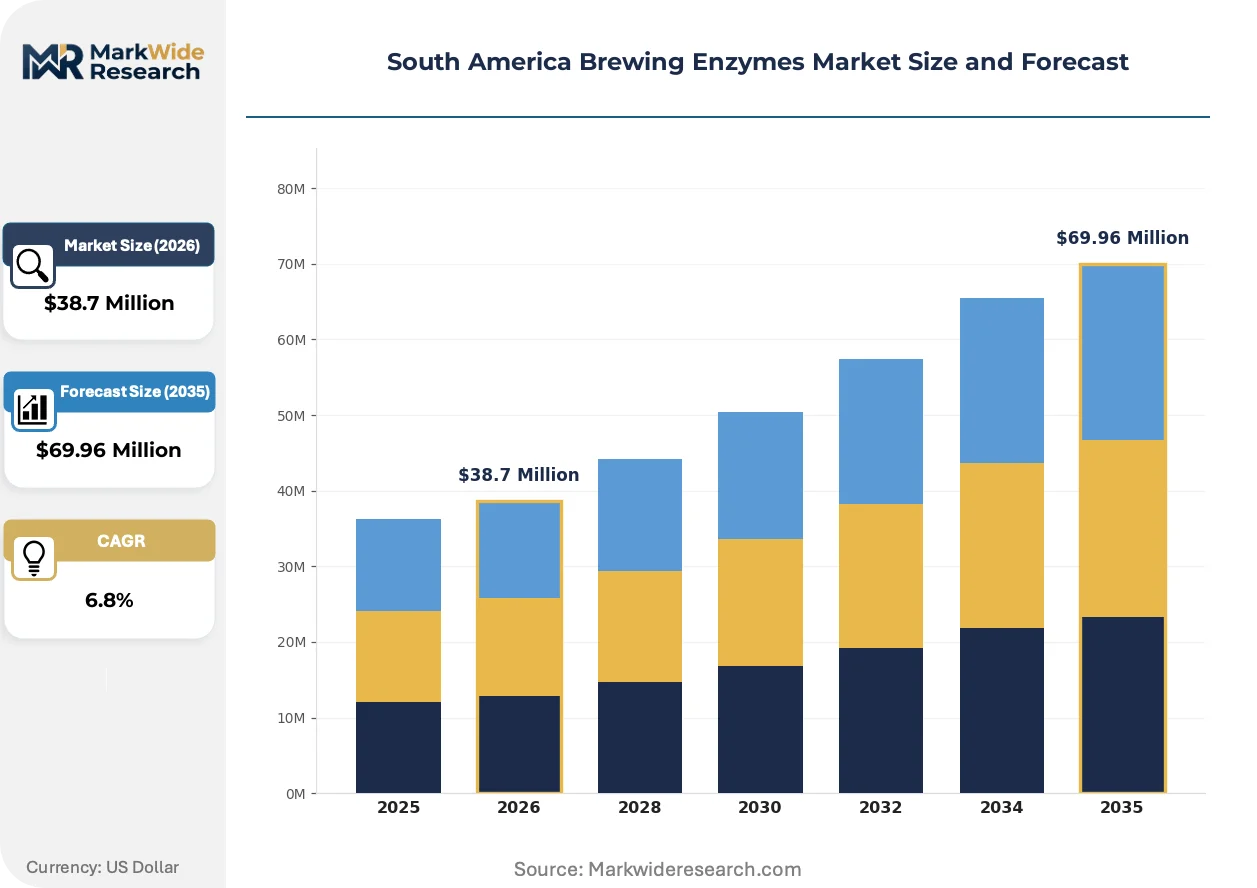
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $69.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Glucoamylase, Protease, Beta-Glucanase End User: Craft Breweries, Large Breweries, Microbreweries, Brewpubs Application: Beer Production, Malt Processing, Carbonation, Flavor Enhancement Form: Liquid, Powder, Granular, Pellets |
| Companies Covered | Kerry Group plc, Merck KGaA, DuPont de Nemours Inc, Associated British Foods plc, Koninklijke DSM N V, The Soufflet Group, Novozymes A/S, BASF SE, AB Enzymes, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Brewing Enzymes Market Trends and Innovations
Enzyme stabilization technologies and regulatory documentation systems are converging to reshape competitive access patterns, with format flexibility and traceability emerging as decisive procurement criteria.
Granular enzyme stabilization is consolidating supply chain resilience for South American brewers operating outside reliable cold-chain networks. Craft breweries in São Paulo's interior and Colombian mountain facilities are adopting temperature-stable formats at accelerating rates. This consolidation is compressing the historical liquid-dominant market structure while opening premium pricing tiers for logistics-advantaged suppliers.
ANVISA's evolving toxicological dossier requirements are tightening purity thresholds for imported Aspergillus-derived formulations. Large-scale Brazilian brewers are responding by qualifying dual-source supply arrangements and accelerating in-house quality documentation capabilities. Smaller Argentine importers face disproportionate compliance burdens, shifting procurement gravity toward established multinational enzyme houses with dedicated regulatory affairs teams.
Multi-source procurement patterns are displacing single-supplier enzyme relationships across Brazilian brewing corridors. Facilities in Minas Gerais and São Paulo states are segmenting amylase, glucoamylase, and protease purchases across specialized suppliers rather than consolidated portfolios. This fragmentation is most visible among mid-scale industrial brewers seeking to mitigate malt price volatility through diversified biocatalyst sourcing strategies.
South America Brewing Enzymes Market Segmentation
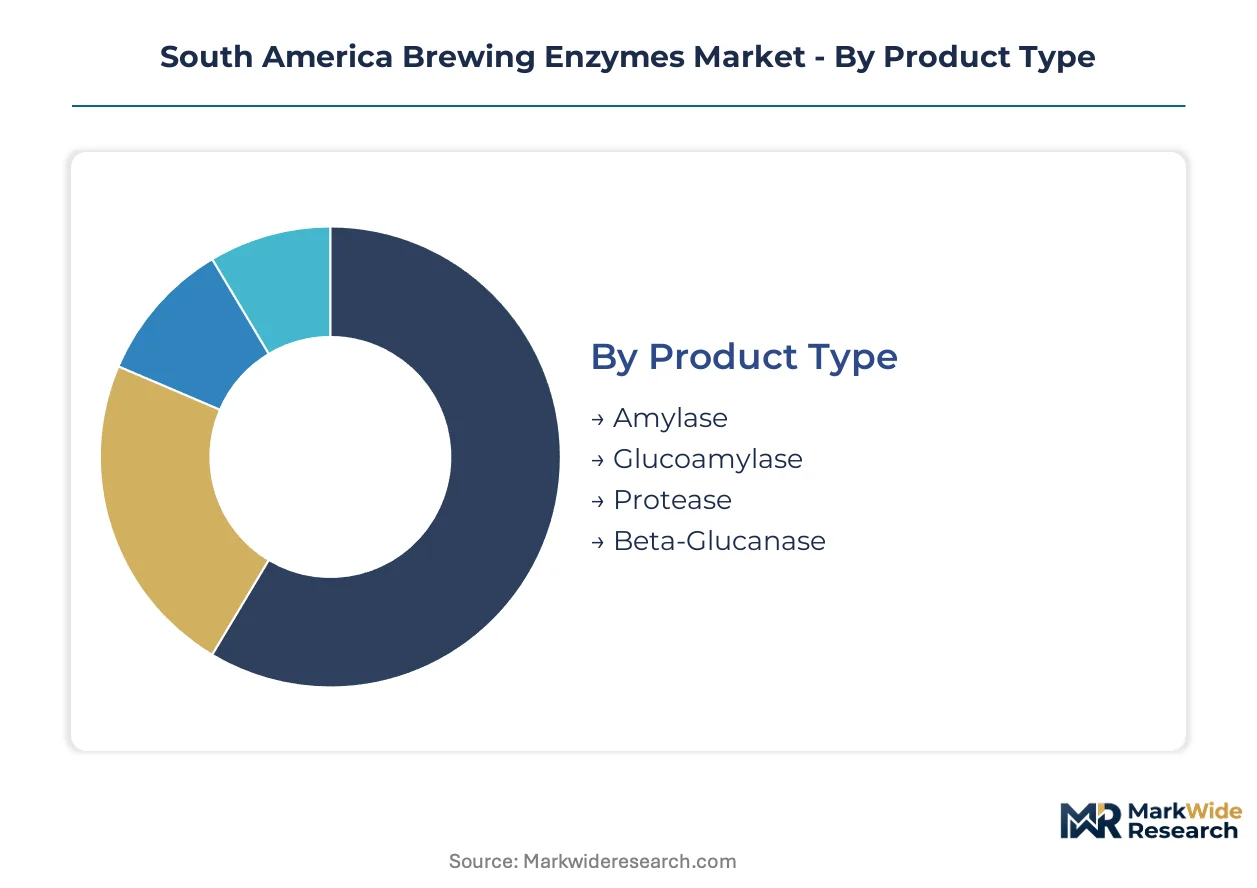
Brewing enzyme procurement in South America fragments across four structural dimensions. Product chemistry determines mash efficiency outcomes, while facility scale dictates dosing precision requirements and format preferences.
Product Type:
Amylase formulations function as standalone liquefaction agents, whereas glucoamylase and protease variants integrate into multi-enzyme blending systems for saccharification and protein modification stages.
- Amylase:Alpha-amylase biocatalysts catalyze starch liquefaction into dextrins during mashing, operating optimally at 70-90°C. Brazilian large breweries in São Paulo state concentrate demand here for extract yield maximization amid volatile malt pricing.
- Glucoamylase:Exo-acting enzymes hydrolyze dextrins to fermentable glucose, completing saccharification. Argentine facilities facing ANVISA-compliant documentation burdens favor these formulations for their established regulatory dossiers and proven toxicological profiles.
- Protease:Endopeptidases reduce haze-forming proteins and improve colloidal stability in finished beer. Colombian craft breweries adopt protease adjuncts to accelerate maturation cycles.
- Beta-Glucanase:Cell wall-degrading enzymes lower wort viscosity when processing high-adjunct grists. Brazilian brewers utilizing local corn and rice adjuncts deploy beta-glucanase to maintain lautering efficiency.
Volume placements concentrate in Amylase; the faster expansion belongs to Beta-Glucanase as adjunct brewing spreads across Brazilian industrial facilities.
End User:
Facility scale tiers separate automated dosing infrastructure requirements from manual blending capabilities, with capital intensity thresholds determining enzyme format accessibility.
- Craft Breweries:Mid-scale operations producing 1,000-15,000 hectoliters annually. Bogotá and Medellín craft breweries drive demand for flexible liquid formulations with technical support attachments.
- Large Breweries:Industrial facilities exceeding 500,000 hectoliters yearly. Southeastern Brazilian brewing corridors anchor contract volumes for standardized amylase supply with volume-tier pricing.
- Microbreweries:Sub-1,000 hectoliter operations. Shelf-stable powder enzymes gain traction here due to cold-chain gaps in Andean distribution networks.
- Brewpubs:On-premise production with consumption colocation. Minimal enzyme adoption due to batch-scale manual mashing without automated dosing infrastructure.
Large breweries command procurement scale; craft breweries generate the steepest adoption trajectory as technical literacy spreads through Brazilian and Colombian brewing associations.
Application:
Process stage integration varies from front-end mash conversion through post-fermentation finishing, with enzyme stability requirements shifting across temperature and pH exposure profiles.
- Beer Production:Encompasses mashing, fermentation, and maturation biocatalysis. São Paulo state industrial brewers dominate consumption for starch liquefaction and attenuation control.
- Malt Processing:Exogenous enzyme supplementation during malting or adjunct processing. Argentine malt houses apply beta-glucanase to improve friability in local barley varieties.
- Carbonation:Glucose liberation for secondary fermentation carbonation. Limited adoption restricted to traditional bottle-conditioning operations in Colombian craft segments.
- Flavor Enhancement:Protease and lipoxygenase modulation of precursor compound profiles. Emerging application among Brazilian premium lager producers seeking differentiated sensory signatures.
Beer production absorbs the dominant enzyme placement; malt processing climbs fastest as Brazilian brewers deepen backward integration into captive malting capacity.
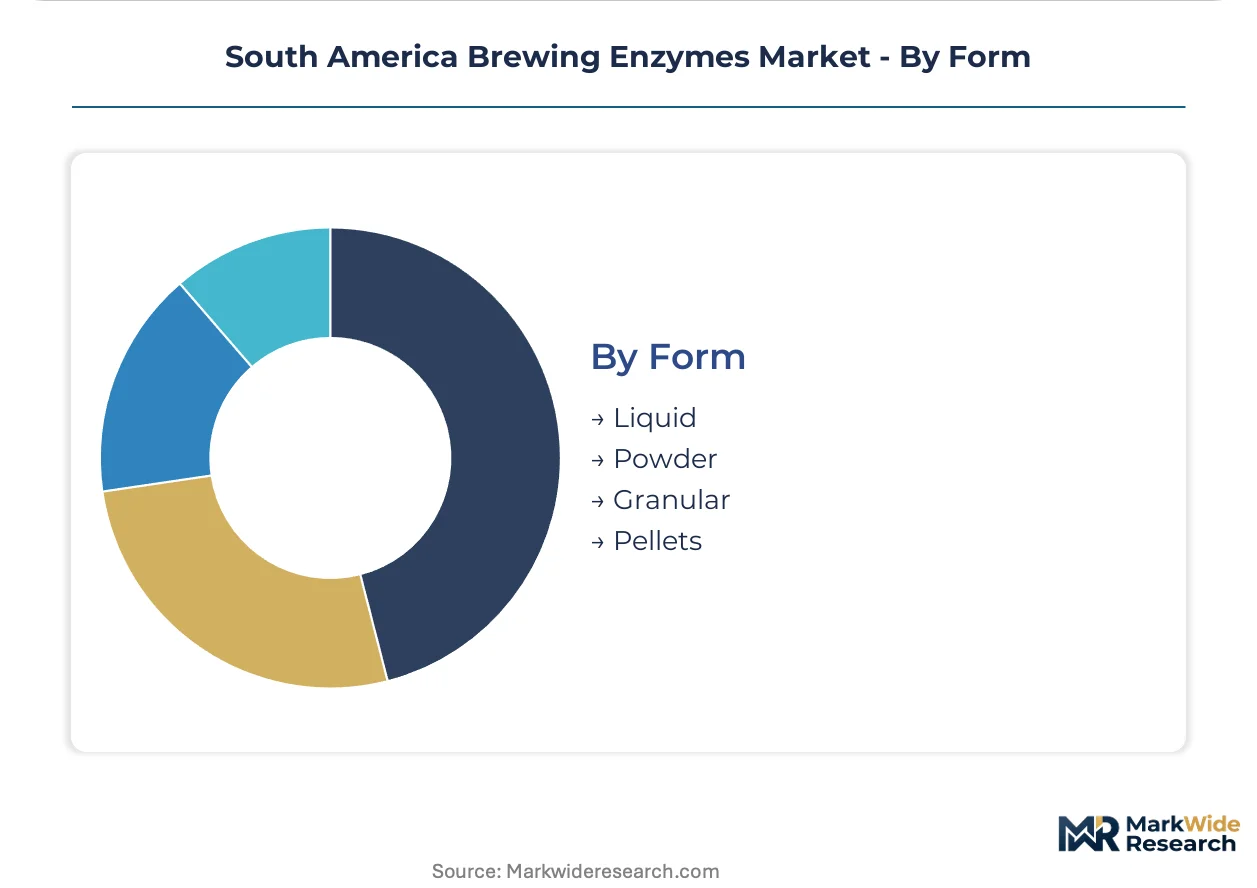
Form:
Physical presentation tiers map directly to cold-chain reliability, dosing precision requirements, and shelf stability demands across distribution geographies.
- Liquid:Aqueous enzyme suspensions with activity standardization for automated injection systems. Brazilian large breweries with precision dosing infrastructure prefer liquid for blending flexibility and rapid dispersion.
- Powder:Spray-dried formulations with extended ambient stability. Microbreweries in São Paulo's interior and Colombian mountain facilities adopt powder where refrigeration is unreliable.
- Granular:Agglomerated particles with controlled release and temperature resilience. Andean distribution networks lacking cold-chain coverage drive granular adoption for supply chain resilience.
- Pellets:Compressed enzyme matrices for slow-release applications. Niche positioning in continuous fermentation systems with extended residence times.
Liquid formats dominate procurement tonnage; granular configurations expand most quickly as suppliers address logistics gaps in secondary Brazilian and Colombian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barley cultivation corridors across the Argentine Pampas and southern Brazilian states anchor raw material flows for the continent's brewing enzyme demand.
Brazil
Southeastern brewing clusters in São Paulo and Minas Gerais states concentrate industrial enzyme consumption for large-scale lager production. ANVISA's toxicological dossier requirements for food-grade additives filter import approvals, compressing supplier access to established multinational houses. São Paulo state's precision dosing infrastructure supports liquid enzyme dominance, while interior craft facilities adopt powder formats to bypass cold-chain gaps.
Argentina
Pampas-region malt houses and Buenos Aires industrial breweries drive demand for beta-glucanase and protease formulations in high-adjunct grist processing. The national food safety authority mandates enzymatic activity labeling and origin traceability, elevating documentation burdens for importers. Córdoba and Santa Fe provinces host expanding craft segments seeking technical support attachments with enzyme supply contracts.
Colombia
Bogotá and Medellín microbreweries accelerate enzyme adoption for mash efficiency gains in mountain production environments. Cold-chain unreliability across Andean distribution networks pushes format preference toward temperature-stable granular configurations. Antioquia department's craft association programs spread technical literacy, reducing reliance on imported field support.
Chile
Santiago metropolitan brewing operations and Valparaíso port logistics clusters shape enzyme procurement patterns for imported biocatalysts. Central Valley malt production supports backward integration into captive enzyme blending. Tarapacá and Antofagasta mining corridor populations sustain demand for standardized industrial lager production with amylase-heavy formulation profiles.
Uruguay
Montevideo industrial facilities and Paysandú malt processing centers concentrate limited but growing enzyme demand. Mercosur regulatory harmonization pressures create compliance pathway efficiencies for Brazilian and Argentine suppliers seeking cross-border market access. Canelones department craft breweries represent emerging demand pockets for flexible dosing formats.
South America Brewing Enzymes Market Competitive Landscape
Global fermentation technology majors compete with regional formulation champions across supply reliability and regulatory navigation capabilities. Market structure tilts toward consolidated premium contract positions held by Danish and Irish technology houses, with mid-tier fragmentation among localized blending operations. Three archetypes dominate: multinational enzyme houses with dedicated regulatory affairs teams, regional formulators leveraging proximity for shortened lead times, and specialty distributors bridging cold-chain gaps in secondary markets. Competitive intensity centers on dual-source qualification strategies and granular format development for logistics-constrained geographies.
Within the multinational tier, Novozymes A/S and Kerry Group plc exemplify divergent geographic anchoring strategies for South American market access. Novozymes occupies a position tied to Danish submerged fermentation heritage, while Kerry Group sits within Irish food ingredient conglomerate structures with localized São Paulo state blending capabilities. DuPont de Nemours Inc represents North American diversified chemical house positioning, with granular enzyme stability profiles addressing regional temperature variation challenges during continental transport.
| Leading Market Players |
|---|
| Kerry Group plc |
| Merck KGaA |
| DuPont de Nemours Inc |
| Associated British Foods plc |
| Koninklijke DSM N V |
| The Soufflet Group |
| Novozymes A/S |
| BASF SE |
| AB Enzymes |
| Others |
Pricing and Supply Chain Analysis
Backward integration into captive malting capacity anchors pricing power for Brazilian industrial brewers, while fragmented enzyme supply forces craft facilities toward spot-market purchasing with limited negotiation leverage. ANVISA's toxicological dossier requirements compress supplier pools, concentrating premium contract positions among Danish and Irish fermentation technology houses.
Pricing Analysis
Technical support bundling separates premium enzyme contracts from commodity spot purchases across South American brewing corridors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale thresholds. Cost compression in economy tiers intensifies because malt price volatility forces reactive purchasing patterns. Craft breweries in Bogotá and Medellín exhibit highest price sensitivity due to limited batch volumes and cold-chain infrastructure gaps.
Supply Chain Analysis
Maritime freight costs from European fermentation facilities to Brazilian southeastern ports constitute the dominant landed cost component for premium enzyme formulations. Supply concentrates in Denmark, Ireland, and domestic Brazilian blending operations for liquid amylase formulations. Raw material dependencies include Aspergillus niger fermentation substrates, Bacillus subtilis culture media, and food-grade stabilizer chemicals. Single-source vulnerability runs through Danish submerged fermentation technology for high-activity glucoamylase variants. Distribution runs through São Paulo state logistics hubs serving Minas Gerais and interior craft segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from ANVISA's tightening purity thresholds is forcing smaller Argentine importers toward exit or acquisition, compressing the supplier base toward multinational enzyme houses with dedicated regulatory affairs capabilities.
For Market Incumbents: Lock in dual-source qualification strategies across amylase, glucoamylase, and protease categories to mitigate malt price volatility exposure. Deepen backward integration into captive malting capacity in São Paulo state to secure input cost control against currency fluctuation. Prioritize granular format R&D for Andean distribution networks lacking cold-chain reliability. For New Entrants and Emerging Players: Temperature-stable enzyme stabilization technologies offer entry positioning into Colombian mountain microbreweries and São Paulo interior craft facilities. Target underpenetrated industrial brewing capacity outside Bogotá with regional blending facilities and technical field support attachments. Pursue white-label formulation partnerships with Brazilian PLI scheme beneficiaries to bypass ANVISA dossier burdens. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to Irish and Danish fermentation technology conglomerates seeking Latin American blending footprints. Five-to-ten year viability favors regional formulators with established ANVISA compliance dossiers and São Paulo state logistics infrastructure. Monitor Mercosur regulatory harmonization progress as inflection indicator for multi-country supplier registration scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Blending Facility Establishment | São Paulo state proximity shortens lead times for liquid amylase formulations serving Minas Gerais breweries. |
| Granular Format Development Program | Temperature-stable configurations unlock Andean microbrewery segments dependent on unreliable cold-chain networks. |
| Dual-Source Supply Qualification | Segmented procurement across specialized amylase and glucoamylase suppliers mitigates malt price volatility exposure. |
| ANVISA Regulatory Affairs Investment | Dedicated toxicological dossier capabilities filter out smaller competitors and anchor premium contract positions. |
| Technical Field Support Expansion | On-site fermentation optimization services differentiate supply relationships in Colombian craft brewery corridors. |
Research Methodology
Multi-period observation of enzyme adoption rates, regulatory approval timelines, and malt price volatility anchored the trend analysis, supplemented by interviews with Brazilian brewery plant managers, Argentine malt house procurement leads, Colombian craft brewery technical directors, and ANVISA regulatory affairs specialists. Secondary validation drew from ANVISA food additive registration databases, Mercosur trade flow statistics, Brazilian PLI scheme disclosure filings, and customs import records for Aspergillus-derived biocatalysts. Bottom-up facility-level consumption estimates triangulated against top-down market sizing from fermentation technology supplier disclosures.
Input-output matrices modeled enzyme demand across product chemistry, facility scale tiers, process stage integration, and physical format preferences throughout the projection horizon. Segmentation dimensions included amylase versus glucoamylase versus protease versus beta-glucanase categories, craft versus large brewery versus microbrewery versus brewpub end users, beer production versus malt processing versus carbonation versus flavor enhancement applications, and liquid versus powder versus granular versus pellet forms. CAGRs were derived from regression analysis of historical adoption curves adjusted for regulatory acceleration effects and supply chain resilience investments.
Several conditions sit outside the modeled scope, including novel enzyme variant toxicological approvals pending ANVISA review, Mercosur regulatory harmonization treaty ratification timelines, and extreme currency fluctuation scenarios beyond historical bands. Forecasts reflect documented assumptions about malt price volatility persistence and cold-chain infrastructure development trajectories. Stakeholders should weight assumptions against their own operating context and procurement risk tolerance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Africa Anti Caking Agent Market
Food Additives and Ingredients
Spain Food Preservatives Market
Food Additives and Ingredients
Calcium Inosinate Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
Food Grade Butyric Acid Market
Food Additives and Ingredients
Latin America Food Enzymes Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
India Food Enzymes Market
Food Additives and Ingredients
France Food Acidulants Market
Food Additives and Ingredients
Antistaling Agent Market
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
Russia Food Enzymes Market
Food Additives and Ingredients
Synthetic Food Preservatives Market
Food Additives and Ingredients
Food Antimicrobial Additives Market
Food Additives and Ingredients
India Food Preservatives Market
Food Additives and Ingredients
China Food Additives Market