
 Wine Fining Agent Market | 2026-2036
Wine Fining Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Fining Agent Market Analytics
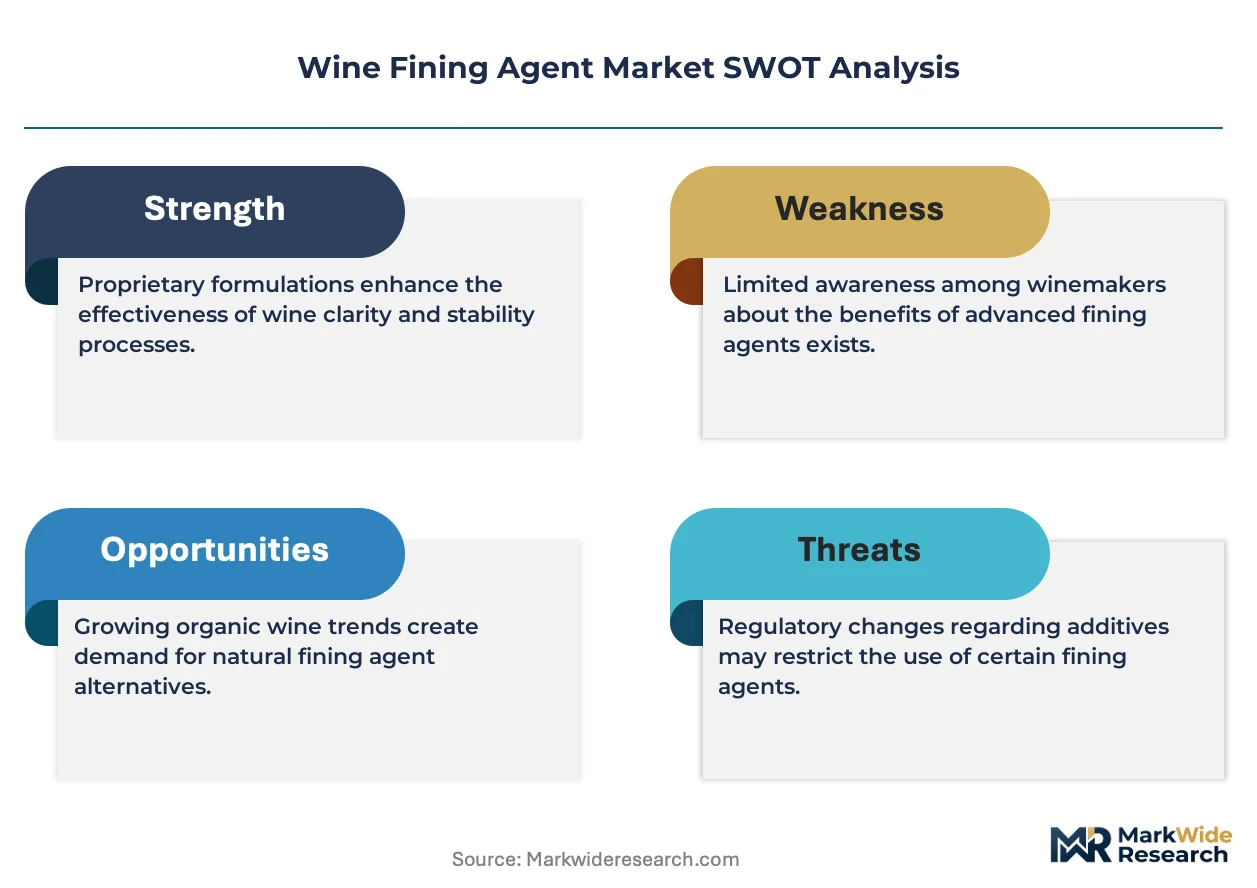
Premium-grade fining specification is rotating through the wine fining agent market as producers seek cleaner-label alternatives to synthetic treatments. AEB Group leverages its Italian heritage and deep enology expertise to sustain formulation leadership across European appellations. Enartis competes through specialized tannin-modulating fining agents tailored to premium red wine programs. BASF SE anchors industrial-scale bentonite supply chains that dominate volume-driven white wine segments.
Wine fining agents are functional additives—typically proteins, clays, or polysaccharides with defined particle size distributions and charge densities—used to precipitate suspended colloids, excess tannins, and unstable proteins from must and finished wine. Gelatin and isinglass remain preferred for red wine tannin management due to their selective binding affinities, while bentonite dominates white wine protein stabilization through its layered aluminosilicate structure and cation-exchange capacity. Among applications, red wines command the largest volume share given their higher tannin loads and longer aging protocols, though sparkling wine producers are driving fastest growth for casein-based agents that preserve delicate aromatic profiles without oxidative stripping.
EU REACH and the EU Organic Regulation constrain synthetic additive approvals and mandate disclosure thresholds that favor plant-derived and certified-organic fining materials. The US FDA governs GRAS status for protein fining agents under the Food Additives Amendment, while California's CCOF and other state-level organic certifiers impose additional processing restrictions that reshape supplier qualification requirements. Stakeholders must monitor evolving allergen labeling mandates for residual fining proteins, as regulatory divergence between European and North American disclosure frameworks threatens to fragment product registration strategies and complicate cross-border formulation standardization.
Market Dynamics
Organic certification mandates under EU Organic Regulation and California CCOF standards are forcing premium winemakers to abandon synthetic fining agents, restructuring supplier qualification requirements across Bordeaux, Burgundy, and Napa Valley production clusters.
Growth Catalysts
- EU Organic Regulation compliance deadlines:Winemakers in France and Italy accelerate plant-derived fining agent procurement to meet disclosure thresholds and avoid certification penalties.
- Sparkling wine production expansion:Casein-based agents capture demand from Champagne and Prosecco houses seeking oxidative stability without aromatic stripping.
- Bentonite cation-exchange capacity:White wine producers leverage aluminosilicate structure advantages for protein stabilization in high-volume Sauvignon Blanc and Chardonnay programs.
Market Restraints
- Gelatin supply concentration:Bovine-derived protein sourcing depends on slaughterhouse byproduct availability concentrated in specific EU member states.
- Isinglass technical limitation:Collagen extraction from sturgeon swim bladders faces yield constraints and aquatic ecosystem sustainability scrutiny.
- Allergen labeling divergence:Residual protein disclosure thresholds differ between FDA GRAS requirements and EU REACH mandates, complicating cross-border formulation.
Strategic Opportunities
- Eastern European wine expansion:Hungarian and Romanian producers adopt precision fining protocols to upgrade export positioning toward Western European retail channels.
- Pea protein convergence:Plant-based fining agents combine with enzymatic clarification to serve vegan-certified wine segments in UK and German markets.
- Direct-to-winery distribution:Specialty suppliers bypass traditional chemical distributors to capture margin from small-lot biodynamic producers in Loire and Willamette Valley.
Industry Challenges
- Enology technician scarcity:Skilled laboratory staff capable of optimizing fining trials and stability testing command premium wages in competitive wine regions.
- Organic certification timeline compression:Three-year conversion periods for vineyard and cellar operations delay revenue recognition for transitioning producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Fining Agent Market |
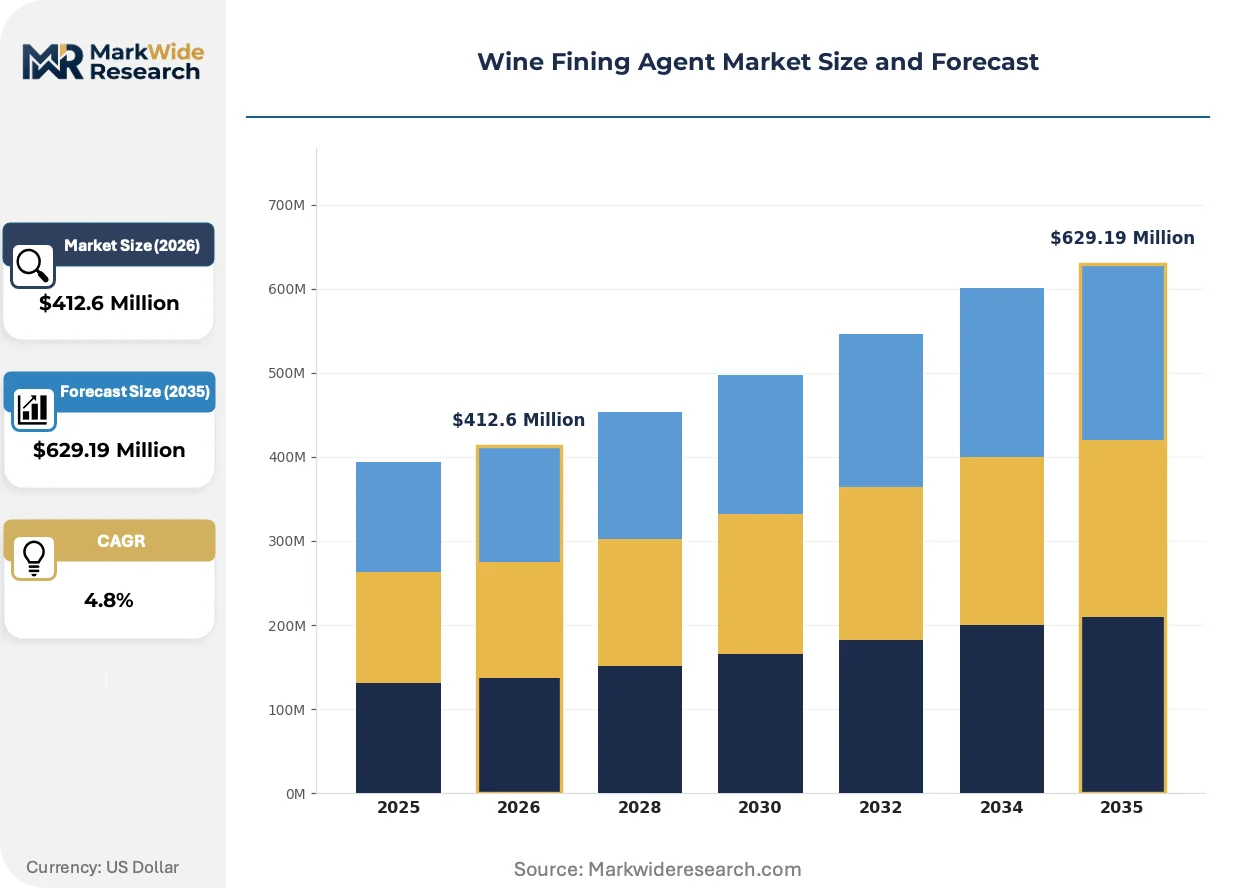
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Isinglass, Bentonite, Casein Application: Red Wines, White Wines, Sparkling Wines, Fortified Wines End User: Winemakers, Wineries, Beverage Manufacturers, Home Brewers Form: Liquid, Powder, Granular, Sheet |
| Companies Covered | AEB Group, BASF SE, Enartis, Kerry Group, Brenntag AG, Erbslöh Geisenheim AG, Agrovin, Eaton Corporation, Scott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Fining Agent Market Evolving Landscape
Precision enology tools and regulatory disclosure automation are compressing traditional fining trial cycles. Winemakers now demand agents with verified performance curves and batch-traceable origin documentation.
Silica sol technology is bifurcating the protein stabilization segment. High-end white wine producers adopt colloidal silica for its selective removal of haze-forming proteins without excessive aroma loss. Champagne houses integrate silica sol protocols into pre-bottling stabilization workflows. The technology is bifurcating supplier tiers between precision-formulation specialists and commodity bentonite distributors.
REACH substance registration deadlines are tightening residual protein thresholds. ECHA disclosure requirements now mandate quantitative reporting of fining agent carryover in finished wine. Sparkling wine producers face the steepest compliance burden given their multi-stage clarification protocols and extended lees contact periods.
Buyers now specify performance-guaranteed supply contracts rather than commodity spot purchases. Large Bordeaux négociants demand lot-specific haze-stability warranties from fining agent suppliers. This specification intensity concentrates most acutely in grand cru classified production where batch failure carries catastrophic reputation risk.
Wine Fining Agent Market Segmentation
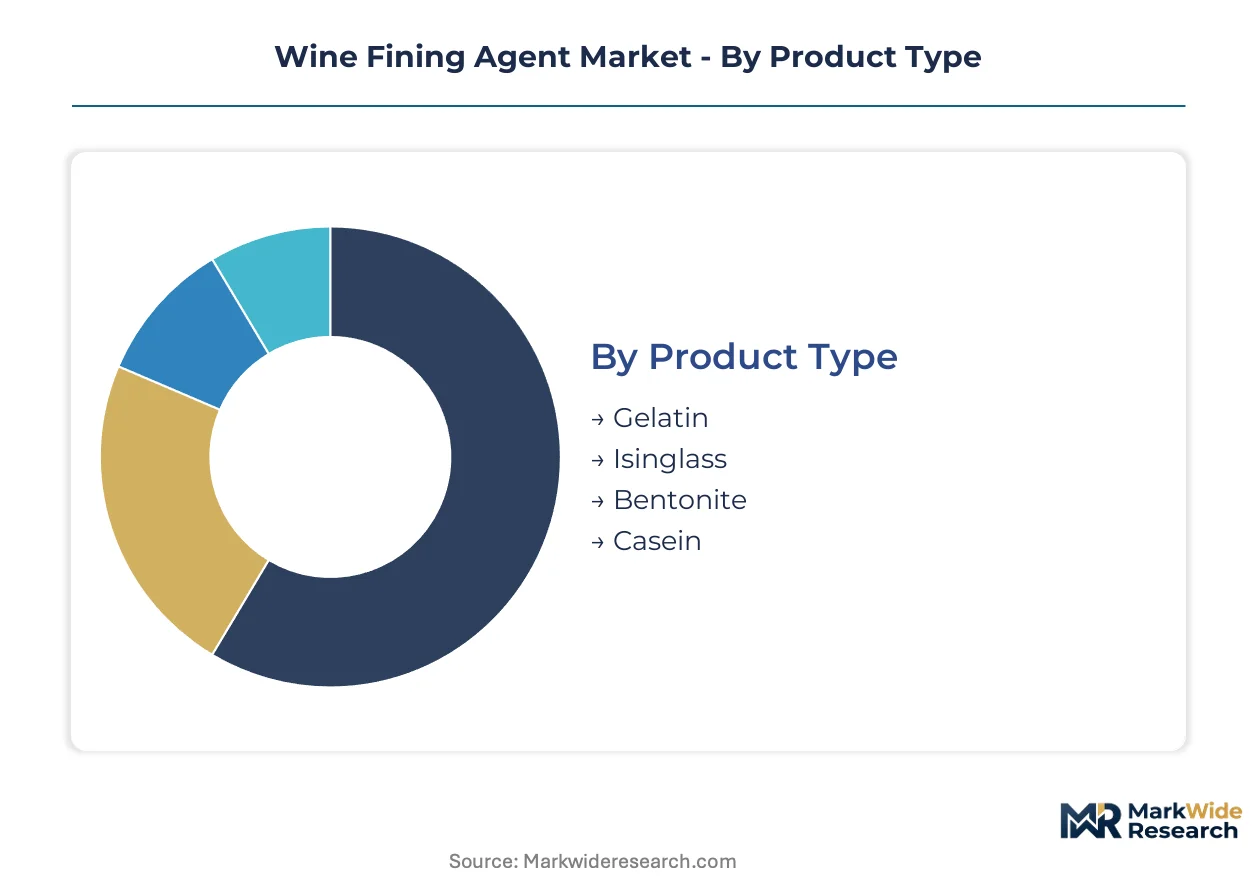
Wine fining agent selection hinges on precise matching between chemical functionality and wine matrix requirements. Regulatory disclosure thresholds under EU REACH and FDA GRAS frameworks segment procurement decisions across production tiers. Each category reveals distinct concentration patterns driven by certification mandates and processing economics.
Product Type:
REACH substance registration deadlines and residual protein carryover mandates differentiate procurement patterns across protein-derived and mineral-based agents.
- Bentonite:Layered aluminosilicate clay with cation-exchange capacity selectively adsorbs haze-forming proteins. Sauvignon Blanc and Chardonnay producers in California's Central Valley and France's Loire Valley specify bentonite for high-volume protein stabilization under CCOF and EU Organic Regulation disclosure requirements. Bentonite handles the majority of throughput; casein is the fastest mover on share.
- Casein:Milk-derived phosphoprotein with selective phenolic binding preserves delicate aromatic profiles. Champagne and Prosecco houses adopt casein-based protocols to manage oxidative stability without stripping esters during extended lees contact periods.
- Gelatin:Bovine collagen hydrolysate with high molecular weight distribution targets condensed tannin precipitation in Cabernet Sauvignon and Nebbiolo programs.
- Isinglass:Sturgeon swim bladder collagen with fine particle selectivity clarifies premium white wines where minimal color loss is specified.
Mineral-based agents dominate volume procurement; protein-derived alternatives command premium positioning for aromatic-sensitive applications.
Application:
Processing complexity and aging protocol duration determine fining agent specification intensity across wine categories.
- Red Wines:Extended maceration and barrel aging protocols demand sequential fining with gelatin and egg white alternatives to manage polymerized tannin structures. Bordeaux négociants and Napa Valley cult producers specify multiple fining stages for Cabernet-dominant blends with 18-24 month aging programs.
- Sparkling Wines:Multi-stage clarification requirements and pre-bottling stabilization workflows drive casein and silica sol adoption. Champagne houses face steepest ECHA disclosure burdens given extended lees contact and secondary fermentation complexity.
- White Wines:Bentonite remains standard for protein stabilization in high-throughput Sauvignon Blanc and Pinot Grigio operations.
- Fortified Wines:Port and Sherry producers employ specialized protocols for alcohol-adjusted matrix stability.
Red wine applications absorb the largest absolute volumes; sparkling wine segments show the steepest specification escalation.
End User:
Scale economies and certification status bifurcate procurement patterns between industrial wineries and artisanal operations.
- Wineries:Integrated production facilities with captive laboratory capabilities conduct in-house fining trials and stability testing. Large Bordeaux châteaux and Napa Valley estate producers demand batch-traceable origin documentation and lot-specific performance warranties from qualified suppliers.
- Winemakers:Independent consulting enologists serving multiple clients standardize on portable fining protocols adaptable across terroir conditions. Burgundy négociant-éléveurs and Willamette Valley custom crush facilities prioritize flexible agent formats.
- Beverage Manufacturers:Multi-category producers leverage centralized procurement for wine-based ready-to-drink formulations.
- Home Brewers:Small-scale enthusiasts drive demand for pre-measured single-use sachets through specialty retail channels.
Commercial wineries concentrate procurement volumes; independent winemakers represent the most specification-intensive customer tier.
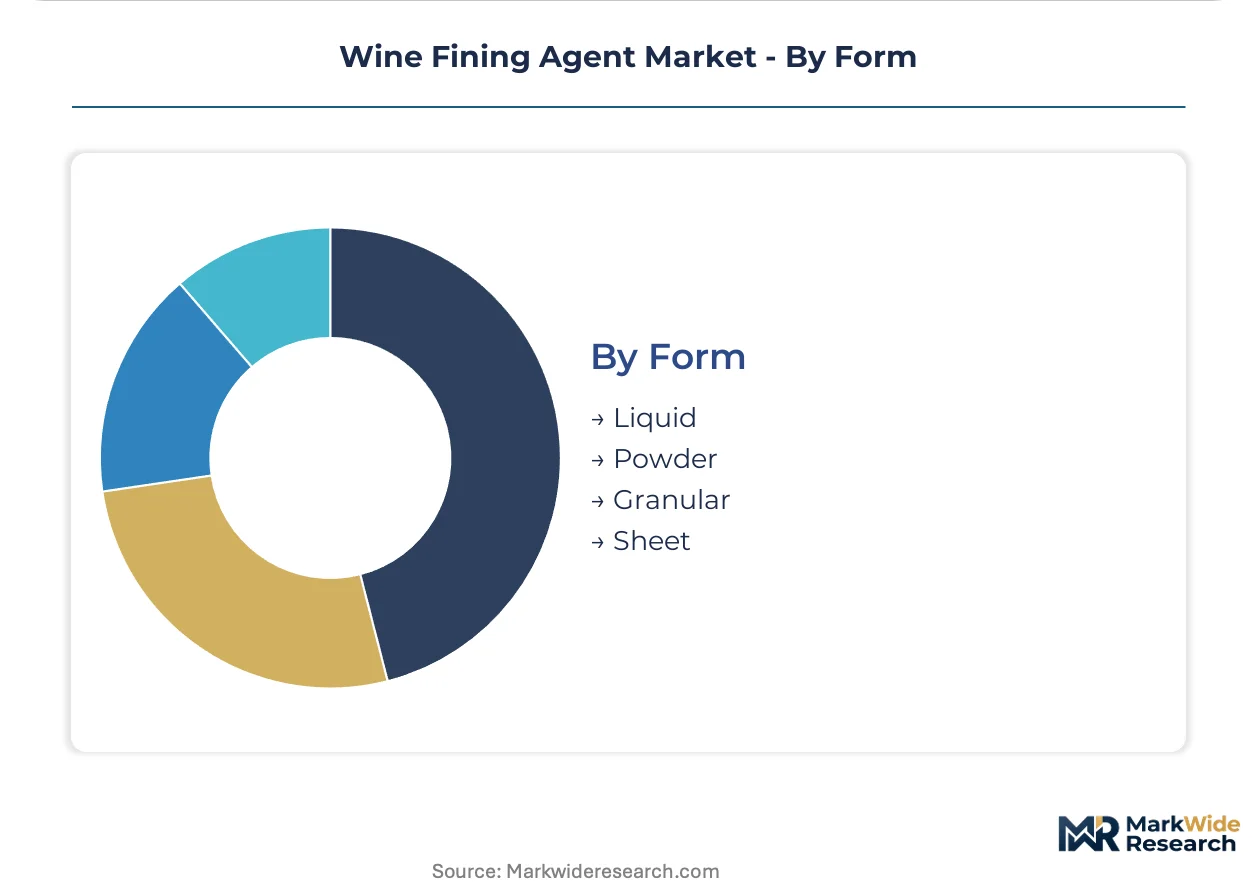
Form:
Dosing precision and storage logistics determine format preference across production scales and climatic conditions.
- Liquid:Ready-to-dose suspensions eliminate hydration variables and enable automated injection systems. Large Prosecco and Cava facilities specify liquid casein and isinglass preparations for continuous processing lines.
- Powder:Concentrated dry formulations reduce transport costs and extend shelf stability for remote winery locations. Australian and South African producers favor powder bentonite given supply chain distances from major manufacturing centers.
- Granular:Controlled dissolution kinetics suit small-batch artisanal operations with manual dosing protocols.
- Sheet:Pre-formed gelatin sheets enable precise portion control for traditional red wine programs in Burgundy and Barolo.
Liquid formats dominate high-throughput installations; powder formulations retain share in cost-sensitive and geographically dispersed markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented producers in France and Italy drive fining agent procurement volumes, while import-dependent markets in the United States and Australia concentrate demand for certified-organic alternatives. Trade flows reflect terroir-specialization premiums and regulatory disclosure requirements.
France
Bordeaux and Burgundy châteaux command premium-grade gelatin and casein formulations for grand cru production. EU REACH mandates quantitative residual protein reporting that reshapes supplier qualification. Champagne houses in Reims and Épernay deploy silica sol protocols for pre-bottling stabilization.
Italy
Prosecco facilities in Veneto specify liquid casein preparations for continuous processing lines. EU Organic Regulation disclosure thresholds accelerate plant-derived fining agent adoption. Tuscan estates in Chianti Classico prioritize tannin-modulating formulations for Sangiovese programs.
United States
Napa Valley cult producers demand batch-traceable origin documentation for Cabernet-dominant blends. California CCOF standards impose processing restrictions that favor certified-organic fining materials. Central Valley Sauvignon Blanc operations specify bentonite for high-volume protein stabilization.
Germany
Pfalz and Mosel producers balance Riesling aromatic preservation with protein stability requirements. ECHA registration deadlines tighten residual thresholds for sparkling wine protocols. Baden-Württemberg cooperatives source precision-formulation specialists for small-lot Pinot Noir.
Australia
Barossa Valley and Margaret River wineries favor powder bentonite formulations given supply chain distances from manufacturing centers. The country's national food standards regulator mandates allergen labeling for residual fining proteins. South Australian bulk wine exporters standardize on portable fining protocols adaptable across harvest conditions.
Wine Fining Agent Market Competitive Landscape
Listed leaders compete with private specialists across formulation tiers and geographic coverage. BASF SE anchors industrial-scale mineral supply chains while family-owned enology houses sustain premium protein-based portfolios. Three archetypes dominate: diversified chemical conglomerates with captive bentonite mining, Italian and German enology specialists with terroir-specific formulation libraries, and regional distributors with direct-to-winery logistics networks. Competitive moves concentrate on backward integration into raw material sourcing and technology licensing for silica sol processing.
Within the enology specialist tier, AEB Group exemplifies heritage-driven formulation leadership anchored in Italian appellation knowledge. Enartis occupies a position among precision-application developers with tannin-focused portfolios. BASF SE represents the scale-driven archetype with aluminosilicate supply chain dominance. Kerry Group and Brenntag AG sit within the distribution-integrated segment, connecting specialty manufacturers to cellar operations across multiple wine regions.
| Leading Market Players |
|---|
| AEB Group |
| BASF SE |
| Enartis |
| Kerry Group |
| Brenntag AG |
| Erbslöh Geisenheim AG |
| Agrovin |
| Eaton Corporation |
| Scott Laboratories |
| Others |
Value Network & Pricing Analysis
Pea protein displacement of bovine gelatin is redrawing raw material procurement maps from EU slaughterhouse clusters toward Canadian and Ukrainian pulse processing hubs, compressing premium-tier pricing premiums as plant-derived alternatives achieve functional parity in tannin management applications.
Pricing Analysis
Industrial white wine producers anchor contract-based long-term offtake structures for bentonite volumes, while premium red wine programs sustain spot-market premiums for isinglass and specialized casein formulations. Three-tier pricing structure across organic-certified, conventional premium, and commodity standard levels reflects EU REACH disclosure burden and California CCOF compliance costs as primary differentiation drivers. Cost compression in mineral-based segments is intensifying because Central Valley scale operators are consolidating procurement through cooperative purchasing alliances. Small-lot biodynamic producers in Burgundy and Willamette Valley exhibit lowest price sensitivity, prioritizing batch-traceable origin documentation over per-kilogram economics.
Supply Chain Analysis
Sturgeon swim bladder sourcing from Caspian Sea aquaculture operations and Black Sea wild harvest channels constitutes a single-species chokepoint for isinglass supply, with yield volatility compounded by aquatic ecosystem sustainability moratoria. Bentonite draws from Wyoming sodium deposits, Greek calcium sources, and Australian alternative clay beds, while gelatin production rests on Spanish, French, and German slaughterhouse byproduct flows. Tariff exposure runs through post-Brexit UK-EU customs friction for protein-derived agents. Distribution runs through specialty chemical distributors with direct-to-winery logistics networks bypassing traditional wholesale channels for qualified biodynamic producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large Bordeaux négociants and Napa Valley estate producers, with procurement consolidation through cooperative purchasing alliances fragmenting pricing leverage for mid-tier suppliers.
For Market Incumbents: Secure captive supply agreements for organic-certified bentonite deposits and pea protein processing capacity before REACH registration deadlines tighten further. Invest in silica sol formulation R&D to defend premium positioning against colloidal technology specialists. Channel control through direct-to-winery distribution networks protects margin from distributor disintermediation. For New Entrants and Emerging Players: Custom crush facility technical support gaps in Willamette Valley and Loire present immediate white-space opportunity, as incumbent suppliers under-serve small-lot producers with flexible dosing formats and on-site enology consultation. Target Eastern European export-oriented wineries in Hungary and Romania seeking precision fining protocols for Western European retail positioning. Lead with portable fining trial kits bundled with stability testing services. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Italian enology specialists holding terroir-specific formulation libraries but lacking North American distribution infrastructure. Five-to-ten year viability hinges on organic certification convergence across EU and North American regulatory frameworks. Watch for ECHA residual protein threshold tightening as signal for accelerated plant-derived agent substitution and corresponding valuation repricing of protein-based agent portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Bentonite Mining | Wyoming and Greek deposit control secures CCOF-compliant supply for California white wine programs. |
| Silica Sol Technology Licensing | Champagne house adoption of colloidal protocols creates premium tier separation from commodity bentonite distributors. |
| Direct-to-Winery Distribution Expansion | Bypassing Brenntag and Kerry networks captures margin from Loire biodynamic producers. |
| Pea Protein Formulation Partnership | Canadian pulse processor alliances address vegan-certified wine segment demand in UK and German markets. |
| Enology Technician Training Program | Addressing laboratory staff scarcity in competitive wine regions protects customer retention for precision fining services. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU REACH registration databases, ECHA disclosure filings, FDA GRAS petitions, and customs trade data for protein-derived and mineral-based fining agents. Enology directors at Bordeaux châteaux, Champagne houses, and Napa Valley estates provided procurement protocol detail, supplemented by technical service managers at bentonite mining operations and pea protein processors. Bottom-up volume estimates from winery consumption surveys triangulate against top-down trade flow analysis.
Segmentation dimensions modeled include agent chemistry (protein-derived versus mineral-based), wine application matrix (red, white, sparkling, fortified), certification tier (organic-certified, conventional premium, commodity standard), and geographic production cluster. CAGRs derive from shipment volume trajectories across the projection horizon, with price evolution informed by raw material cost indices and regulatory compliance burden estimates. Industry-specific inputs capture EU Organic Regulation conversion timeline compression and sparkling wine production expansion rates.
Underlying assumptions cover sustained organic certification adoption in premium wine segments, with deviation risk concentrated in REACH residual protein threshold tightening pace and sturgeon aquaculture yield recovery. Practitioners should keep alternative scenarios live as regulatory divergence between European and North American disclosure frameworks evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Argentina Food Emulsifiers Market
Food Additives and Ingredients
Lecithin Market
Food Additives and Ingredients
Dairy Stabilizer Market
Food Additives and Ingredients
Natural Solubilizers Market
Food Additives and Ingredients
Natural Ferulic Acid Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Brazil Food Preservatives Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
South America Food Preservatives Market
Food Additives and Ingredients
Food Emulsifiers Market
Food Additives and Ingredients
Egg Wash Substitute Market
Food Additives and Ingredients
Ammonia Caramel Market
Food Additives and Ingredients
Phytogenic Feed Additives Market
Food Additives and Ingredients
Italy Food Preservatives Market
Food Additives and Ingredients
Russia Food Emulsifiers Market
Food Additives and Ingredients
Oxygen Absorbers Market