
 Europe Food Additives Market | 2026-2036
Europe Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Additives Market Foresight
Premium-grade additive specifications is bifurcating the competitive landscape as buyers demand cleaner labels with equivalent shelf-life performance. Cargill leverages its European sweetener infrastructure to serve reformulation mandates. DSM anchors its position through enzyme and culture specialization for dairy applications. Kerry Group competes via integrated taste and nutrition platforms that span multiple application categories.
Food additives encompass substances added to food products to preserve flavor, enhance taste, improve appearance, or maintain safety through controlled pH, water activity, or oxidative stability, typically dosed at parts-per-million to low-percentage levels depending on functional class and regulatory maximum limits. Preservatives and sweeteners occupy mature volume positions with stable margin pools, while flavor enhancers and naturally derived colorants represent faster-growing segments as manufacturers respond to consumer preference shifts. Application demand clusters heavily in beverages and dairy products, where clean-label reformulation complexity creates technical barriers for new entrants.
EFSA, the EU Green Deal framework, and REACH collectively govern additive safety assessments, sustainability claims, and chemical substance registration across member states. EFSA's re-evaluation cycles for authorized additives periodically remove or restrict legacy compounds, forcing manufacturers to reformulate with alternative technologies. Stakeholders must monitor regulatory divergence between EU harmonized standards and emerging national sustainability labeling schemes that could fragment compliance requirements.
Market Dynamics
Clean-label reformulation mandates are compressing technical tolerance windows across European food manufacturing, forcing additive suppliers to deliver equivalent functional performance with reduced ingredient complexity and shorter declaration lists.
Growth Catalysts
- EU Green Deal sustainability targets:Member states are accelerating carbon-neutral production mandates that favor bio-based additive manufacturing processes and renewable feedstock sourcing.
- Bakery sector reformulation urgency:Industrial bakeries in Germany and France are replacing synthetic preservatives with cultured wheat and fermented vinegars to meet retailer clean-label requirements.
- Precision fermentation scale-up:Dutch biotech clusters are deploying novel enzyme production platforms that reduce additive dosage rates while maintaining shelf-life extension.
Market Restraints
- Natural extract input volatility:Botanical colorant and antioxidant suppliers face concentrated sourcing risk from Mediterranean crop regions exposed to climate-induced harvest variability.
- EFSA re-evaluation cycles:The regulator's systematic safety reassessments of legacy additives create formulation uncertainty and forced product withdrawals without replacement timelines.
- Plant protein off-flavor masking costs:Meat alternative manufacturers require elevated flavor enhancer loadings that compress margin structures and complicate clean-label positioning.
Strategic Opportunities
- Poland and Romania processing expansion:Central European markets show underpenetrated demand for mid-tier clean-label preservatives as local retail chains adopt Western formulation standards.
- Upcycled ingredient valorization:Fruit and vegetable processing waste streams are yielding novel fiber and pectin-based texturizers aligned with circular economy incentives under EU Green Deal frameworks.
- Direct-to-manufacturer digital platforms:Specialty additive distributors are bypassing traditional ingredient brokers to offer formulation technical support and rapid sample logistics.
Industry Challenges
- Regulatory affairs specialist scarcity:EFSA dossier preparation and novel food consultations require toxicology and regulatory science expertise that outpaces European university program output.
- Multi-site audit coordination:Suppliers serving pan-European food manufacturers must synchronize FSSC 22000 and BRC certification renewals across production facilities in different member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Additives Market |
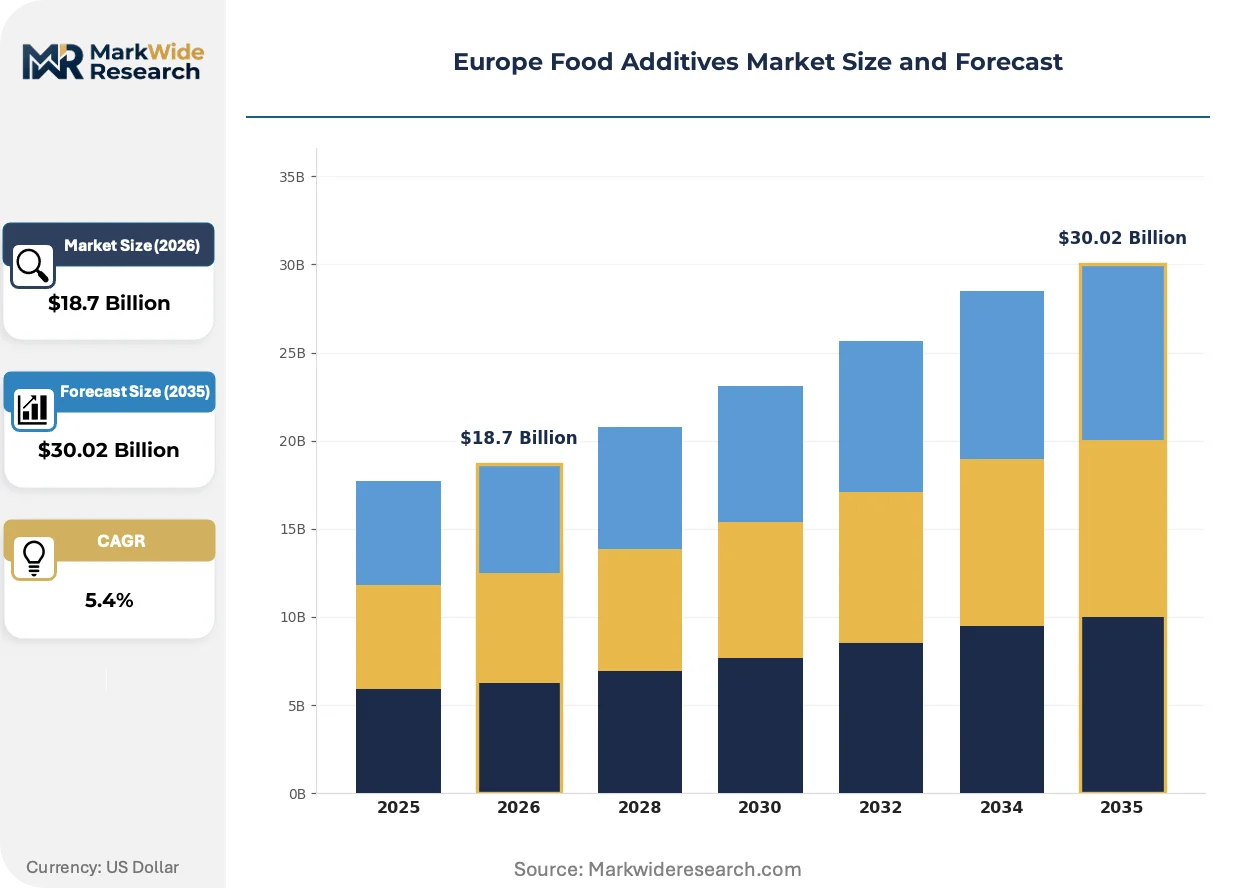
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservatives, Colorants, Flavor Enhancers, Sweeteners Application: Dairy Products, Bakery Goods, Beverages, Snacks Ingredient Source: Naturally Derived, Synthetic, Organic, Conventional End User: Food Manufacturers, Retailers, Restaurants, Catering Services |
| Companies Covered | Cargill, DSM, BASF SE, Symrise AG, Givaudan, Kerry Group, Archer Daniels Midland Company, Corbion, Tate & Lyle, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Additives Market Shifts & Advancements
Enzymatic processing technologies and biosynthetic production routes are displacing conventional chemical synthesis across multiple additive categories, compressing cost differentials between natural-identical and petrochemical-derived ingredients.
Cell-culture-derived flavor precursors are bifurcating the savory taste modulator segment. Premium-positioned plant-based meat manufacturers in the Netherlands and UK are adopting these ingredients to achieve depth without yeast extract labeling. The technology is compressing demand for traditional hydrolyzed vegetable proteins while creating parallel supply chains with distinct regulatory dossier requirements.
EFSA's evolving guidance on novel enzyme safety assessments is tightening industrial consequence for developers. Companies seeking food enzyme authorizations now face extended toxicological data requirements and post-market monitoring obligations. Dairy culture suppliers are responding by pre-submission engagement with EFSA working groups and parallel dossier development for US FDA GRAS pathways.
Retail procurement teams are consolidating supplier relationships around integrated taste-and-texture solution providers rather than discrete ingredient vendors. French and German supermarket private-label divisions are awarding multi-year contracts to additive houses capable of co-developing finished product prototypes. This consolidation is most visible in the ready-meal and beverage categories where speed-to-shelf determines commercial success.
Europe Food Additives Market Segmentation
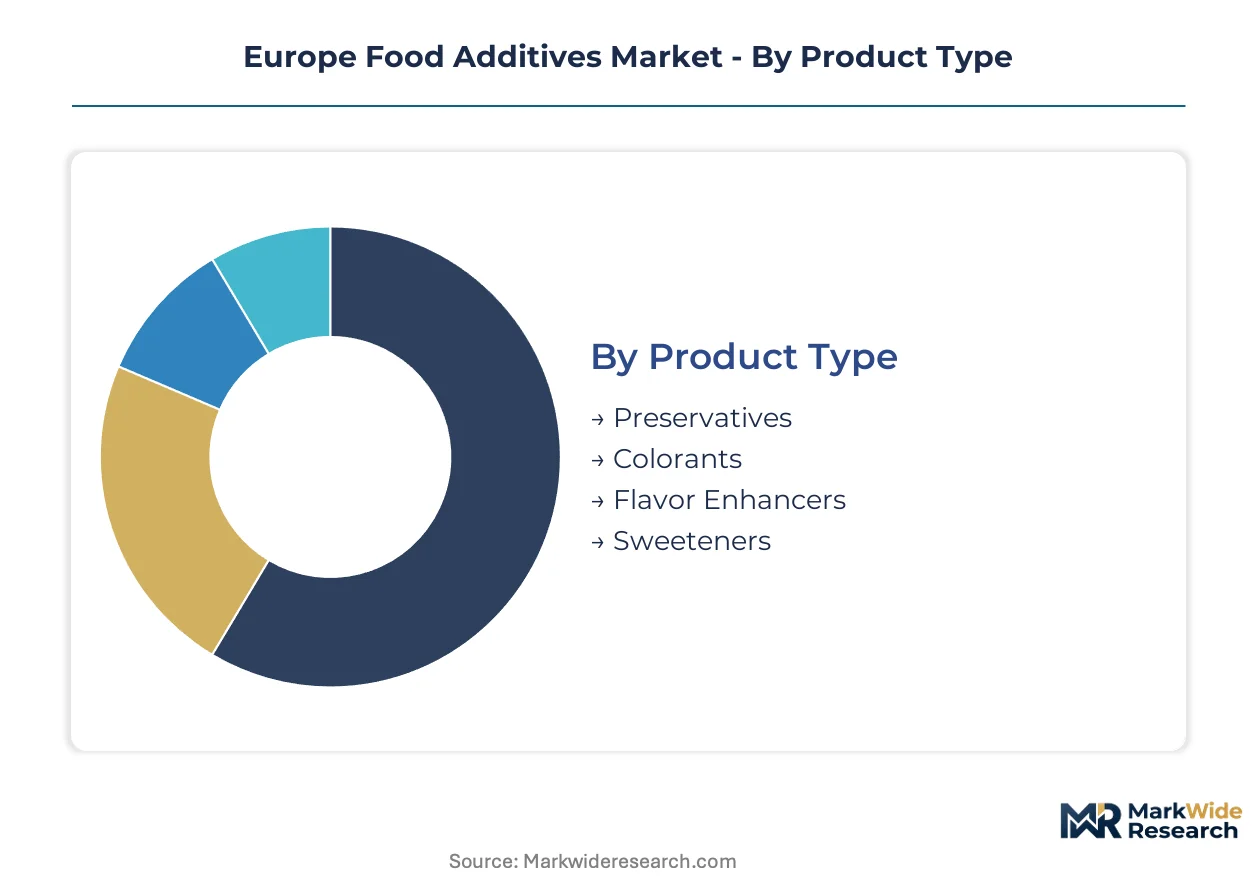
Segmentation reveals how clean-label mandates and EFSA regulatory pressure are reshaping purchasing priorities across European food manufacturing. Suppliers must align product portfolios with distinct technical requirements and compliance thresholds that vary by application and customer scale.
Product Type:
Preservatives and sweeteners dominate domestic formulation demand in Germany and France, while colorants and flavor enhancers show stronger export-led growth into Central European processing hubs.
- Preservatives:These compounds control microbial spoilage through pH modulation, water activity reduction, or antioxidant action. German industrial bakeries are replacing calcium propionate with fermented wheat flour and cultured vinegars to meet retailer clean-label mandates without shelf-life sacrifice.
- Sweeteners:Caloric and non-caloric variants span bulk polyols to high-intensity steviol glycosides. Dutch beverage formulators are driving demand for natural-identical production routes that satisfy EU Green Deal bio-based sourcing requirements.
- Colorants:Anthocyanins, carotenoids, and caramel classes provide visual differentiation. Mediterranean climate volatility in Spanish and Italian beetroot and grape sourcing is forcing inventory hedging strategies.
- Flavor Enhancers:Nucleotides, yeast extracts, and amino acid derivatives intensify taste perception. Precision fermentation-derived alternatives are gaining traction in Netherlands-based plant protein applications.
Preservatives hold the largest share; momentum sits with flavor enhancers as meat alternative manufacturers seek off-flavor masking solutions.
Application:
Cost tier stratification separates premium-positioned dairy innovators from price-sensitive snack commodity producers.
- Dairy Products:Cultures, enzymes, and stabilizers manage fermentation, texture, and shelf-life in cheese and yogurt. French dairy cooperatives are consolidating additive procurement around integrated culture-and-enzyme suppliers capable of rapid strain customization.
- Bakery Goods:Emulsifiers, enzymes, and mold inhibitors govern dough handling and freshness retention. Clean-label reformulation urgency in German and French industrial channels is accelerating demand for enzyme-based shelf-life extension without chemical preservatives.
- Beverages:Acidulants, sweeteners, and stabilizers control taste balance and visual clarity. Carbonated and functional drink manufacturers in the Netherlands prioritize rapid sample turnaround from additive houses with in-house application labs.
- Snacks:Seasonings, colorants, and antioxidants deliver sensory impact and oxidative stability. Eastern European private-label expansion is creating mid-tier demand for cost-optimized natural colorant blends.
Dairy products command premium pricing tiers; snacks are climbing fastest as Central European retail chains upgrade formulation standards.
Ingredient Source:
Supply concentration differs sharply: naturally derived additives depend on Mediterranean agricultural clusters, while synthetic production anchors in German and Belgian chemical manufacturing corridors.
- Naturally Derived:Botanical extracts, fermentation metabolites, and enzymatic modifications. EFSA's tightening novel food consultation timelines are extending commercialization cycles for new natural sources.
- Synthetic:Petrochemical-derived antioxidants, artificial colorants, and chemically synthesized sweeteners. Regulatory pressure through EFSA re-evaluation cycles is systematically constraining approved substance lists.
- Organic:Certified inputs meeting EU organic regulation standards for additive processing aids. Supply scarcity for certified organic acids and pectins is inflating procurement costs for dedicated organic product lines.
- Conventional:Non-certified inputs spanning both natural and synthetic origins without organic claim eligibility. Volume concentration in conventional sourcing supports cost-competitive positioning for mass-market retail.
Conventional sourcing retains volume dominance; organic is expanding most quickly as sustainability-committed retailers enforce procurement quotas.
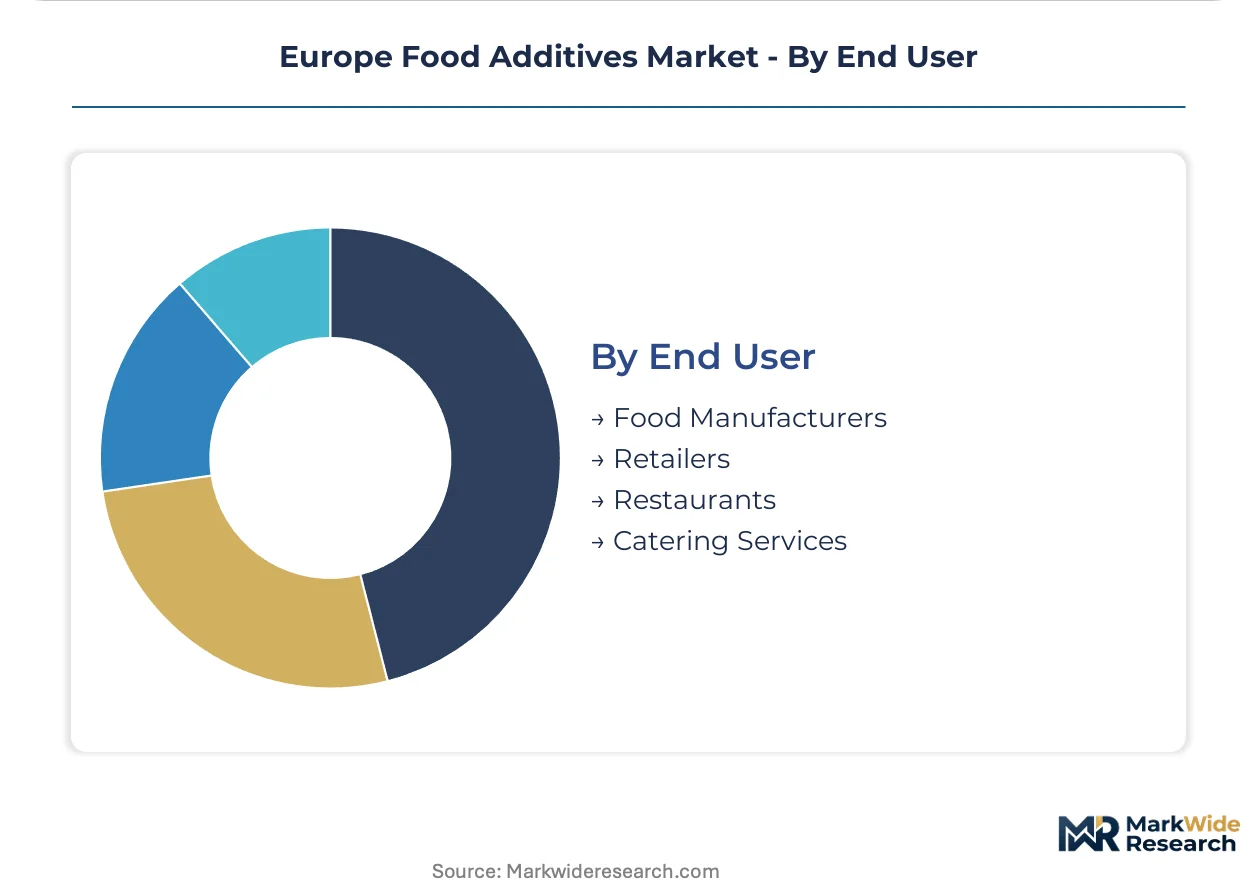
End User:
Customer type determines service intensity: food manufacturers demand technical co-development, while retailers and foodservice prioritize logistics reliability and cost containment.
- Food Manufacturers:Industrial processors of packaged goods requiring precise functional performance specifications. Multinational manufacturers with pan-European production footprints are consolidating supplier relationships around houses with multi-site certification coverage.
- Retailers:Supermarket private-label divisions and ingredient trading desks. French and German retail procurement teams are awarding multi-year contracts to additive suppliers capable of finished product prototype co-development.
- Restaurants:Chain operators and independent establishments sourcing prepared sauces and seasoning blends. Menu labeling transparency requirements are filtering down to additive selection for house-made components.
- Catering Services:Institutional and contract foodservice operations with volume-scale procurement needs. Cost pressure in public sector catering is limiting additive specification flexibility despite clean-label preferences.
Food manufacturers represent the largest demand pool; retailers are gaining share fastest as private-label formulation capabilities deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Netherlands-based enzyme and fermentation specialists supply precision-derived additives to German and French food manufacturers seeking clean-label reformulation pathways.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia drive demand for fermented wheat flour and cultured vinegars replacing synthetic preservatives. EFSA re-evaluation cycles for calcium propionate accelerate reformulation timelines. The Frankfurt-Rhine-Main corridor concentrates biotech enzyme production facilities serving pan-European dairy applications.
France
Dairy cooperatives in Brittany and Normandy consolidate procurement around integrated culture-and-enzyme suppliers for yogurt and cheese innovation. EU Green Deal bio-based sourcing mandates favor fermentation-derived texturizers. The Paris-Saclay biocluster hosts precision fermentation startups developing novel savory taste modulators for plant protein masking.
Netherlands
Dutch beverage formulators prioritize rapid sample turnaround from additive houses with in-house application laboratories. REACH chemical registration requirements constrain novel synthetic additive introductions. The Wageningen-Eindhoven axis anchors cell-culture-derived flavor precursor development for meat alternative manufacturers.
Poland
Central European retail chains adopt Western clean-label standards, creating underpenetrated demand for mid-tier natural preservatives. National sustainability labeling schemes diverge from EU harmonized frameworks. The Łódź-Warsaw manufacturing belt expands processed food capacity requiring imported enzyme and stabilizer inputs.
Italy
Mediterranean botanical colorant suppliers face concentrated sourcing risk from climate-induced harvest variability in Emilia-Romagna and Sicily. EFSA novel food consultation timelines extend commercialization cycles for new natural extracts. The Milan-Turin industrial corridor processes imported beetroot and grape concentrates for pan-European distribution.
Europe Food Additives Market Competitive Landscape
Listed leaders compete with private specialists across capital access and R&D agility dimensions, producing a tiered structure where scale-driven multinationals face nimble fermentation-focused challengers. The vendor base clusters around three strategic archetypes: integrated agricultural processors with captive raw material streams, enzyme and culture specialists with deep strain libraries, and taste-and-texture solution providers spanning multiple application categories. Dominant competitive moves include backward integration into fermentation capacity and geographic expansion through multi-site certification coverage serving pan-European manufacturers.
Within the integrated processor tier, Cargill and Archer Daniels Midland Company occupy positions anchored by European sweetener infrastructure and oilseed processing networks. DSM and Corbion exemplify the enzyme-specialist archetype through dairy culture and fermentation platform concentration. Kerry Group sits within the integrated taste-and-texture solution provider category, competing via multi-category formulation capabilities spanning beverages, dairy, and savory applications.
| Leading Market Players |
|---|
| Cargill |
| DSM |
| BASF SE |
| Symrise AG |
| Givaudan |
| Kerry Group |
| Archer Daniels Midland Company |
| Corbion |
| Tate & Lyle |
| Others |
Supply & Pricing Matrix
Fermented wheat flour and cultured vinegars displacing calcium propionate in German and French industrial bakeries simultaneously redistributes supply geography toward Dutch biotech fermentation clusters and compresses pricing premiums for synthetic preservatives. This substitution dynamic tightens margin structures for petrochemical-derived additives while elevating procurement costs for bio-based alternatives tethered to agricultural input volatility.
Pricing Analysis
Next-generation precision fermentation platforms command 15-40% premiums over conventional chemical synthesis routes, while legacy synthetic preservatives face accelerating price erosion. Three-tier pricing structure across premium bio-based, standard natural-identical, and economy synthetic tiers separates EFSA-certified novel enzymes from grandfathered additives facing re-evaluation risk. Pricing pressure stems from Mediterranean climate volatility inflating botanical extract costs, with German industrial bakeries exhibiting highest price sensitivity and Dutch dairy innovators least sensitive due to co-development contract structures.
Supply Chain Analysis
Inventory hedging cycles for Spanish beetroot and Italian grape concentrates now extend 6-9 months ahead of harvest seasons as climate-induced variability intensifies. Supply concentrates in Germany, the Netherlands, and Belgium for enzyme and fermentation-derived additives, while Mediterranean countries anchor botanical extract sourcing. Raw material dependencies include wheat feedstocks for cultured vinegars, sugar beet for natural-identical sweeteners, and specialty yeasts for nucleotide production. Single-source vulnerability concentrates in Emilia-Romagna carotenoid cultivation. Distribution runs through integrated additive houses with in-house application laboratories serving pan-European food manufacturers directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical formulation services and rapid sample turnaround capabilities now generate recurring revenue streams expanding faster than discrete ingredient sales, as French and German retail procurement teams consolidate around solution providers capable of finished product prototype co-development.
For Market Incumbents: Secure multi-site FSSC 22000 and BRC certification coverage across Dutch, German, and Polish production facilities to defend against emerging fermentation specialists lacking pan-European audit coordination capabilities. Deepen backward integration into precision fermentation capacity in the Wageningen-Eindhoven corridor to capture margin from cell-culture-derived flavor precursors displacing traditional hydrolyzed vegetable proteins.
For New Entrants and Emerging Players: EFSA novel food consultation fast-tracks offer entry pathways for botanical extract suppliers with pre-submission dossier preparation capabilities. Target Polish and Romanian mid-tier clean-label preservative demand as Western retail chains upgrade Central European formulation standards. Deploy direct-to-manufacturer digital platforms with formulation technical support to bypass traditional ingredient broker markups.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed enzyme specialists holding deep strain libraries but lacking integrated taste-and-texture platforms. Five-to-ten year viability hinges on regulatory affairs capabilities scaling faster than EFSA re-evaluation cycles force product withdrawals. Monitor EFSA working group pre-submission engagement rates as inflection indicator for novel enzyme authorization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Dutch biotech clusters reduce additive dosage rates while maintaining shelf-life extension for German bakery applications. |
| Backward Integration into Fermentation Capacity | Captures margin compression between natural-identical and petrochemical-derived ingredient cost differentials. |
| Multi-Site Certification Coverage | FSSC 22000 and BRC synchronization across member states meets pan-European manufacturer procurement consolidation. |
| Direct-to-Manufacturer Digital Platforms | Bypasses traditional ingredient brokers with rapid sample logistics and formulation technical support. |
| Upcycled Ingredient Valorization | Fruit and vegetable processing waste streams yield novel fiber texturizers aligned with EU Green Deal circular economy incentives. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs specialists at EFSA-authorized additive houses, procurement directors at French and German retail private-label divisions, and application technologists at Dutch beverage formulators, then refined through secondary validation against EFSA re-evaluation dossiers, REACH chemical registration databases, and EU Green Deal framework documentation. Bottom-up segment sizing triangulated with top-down market reconstruction across product type, application, ingredient source, and end-user dimensions.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each segmentation layer. Modeled dimensions span preservative and sweetener maturity curves, flavor enhancer acceleration in meat alternative applications, and organic certification tier expansion. CAGRs derive from segment-level growth rate reconciliation with macroeconomic consumption elasticity assumptions. Industry-specific inputs include EFSA novel food consultation timeline probabilities and Mediterranean agricultural yield variance projections.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal bio-based sourcing mandate enforcement or accelerated EFSA re-evaluation cycles would require recalibration. Forecasts reflect documented assumptions regarding clean-label adoption velocity and precision fermentation cost reduction trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Africa Feed Additives Market
Food Additives and Ingredients
Excipients Market
Food Additives and Ingredients
Potassium Polymetaphosphate Food Additives Market
Food Additives and Ingredients
India Food Colorants Market
Food Additives and Ingredients
Middle East and Africa Food Anti Caking Agents Market
Food Additives and Ingredients
Salt Substitutes Market
Food Additives and Ingredients
Sodium Propionate Market
Food Additives and Ingredients
Potassium Lactate Market
Food Additives and Ingredients
Global Wood-Derived Food Additives Market
Food Additives and Ingredients
Europe Food Micronized Salt Market
Food Additives and Ingredients
Lactoperoxidase Market
Food Additives and Ingredients
Food Grade Calcium Lactate Market
Food Additives and Ingredients
Beverages Additives Market
Food Additives and Ingredients
Yeast Extract and Beta Glucan Market
Food Additives and Ingredients
Fat Replacers Salt Reducers and Replacers Market
Food Additives and Ingredients
Sucroglycerides Market