
 India Food Colorants Market | 2026-2036
India Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
India Food Colorants Market Foresight
Multi-source procurement of botanical extracts and fermentation-derived pigments is recalibrating how Indian food manufacturers secure colorant supply. Chr. Hansen Holding A/S leverages its microbial fermentation expertise to anchor natural colorant supply chains for dairy applications across South India. Roha Dyechem competes on synthetic and lake color portfolios, while Kancor Ingredients Private Limited specializes in oleoresin-based natural colors for savory and snack segments.
Food colorants comprise dyes, pigments, and lakes that impart, restore, or enhance visual appeal in edible products, with natural variants derived from anthocyanins, carotenoids, and chlorophyllins requiring pH-stable formulation between 2.5 and 8.0 for beverage compatibility. Their primary purpose spans identification, flavor expectation setting, and shelf-appeal maintenance across packaged food systems. The natural colorant segment leads value contribution as clean-label mandates intensify, while liquid formulations dominate beverage processing for dosing precision and dispersion uniformity. Powder and granular forms sustain bakery and confectionery demand where heat stability and moisture resistance determine specification compliance.
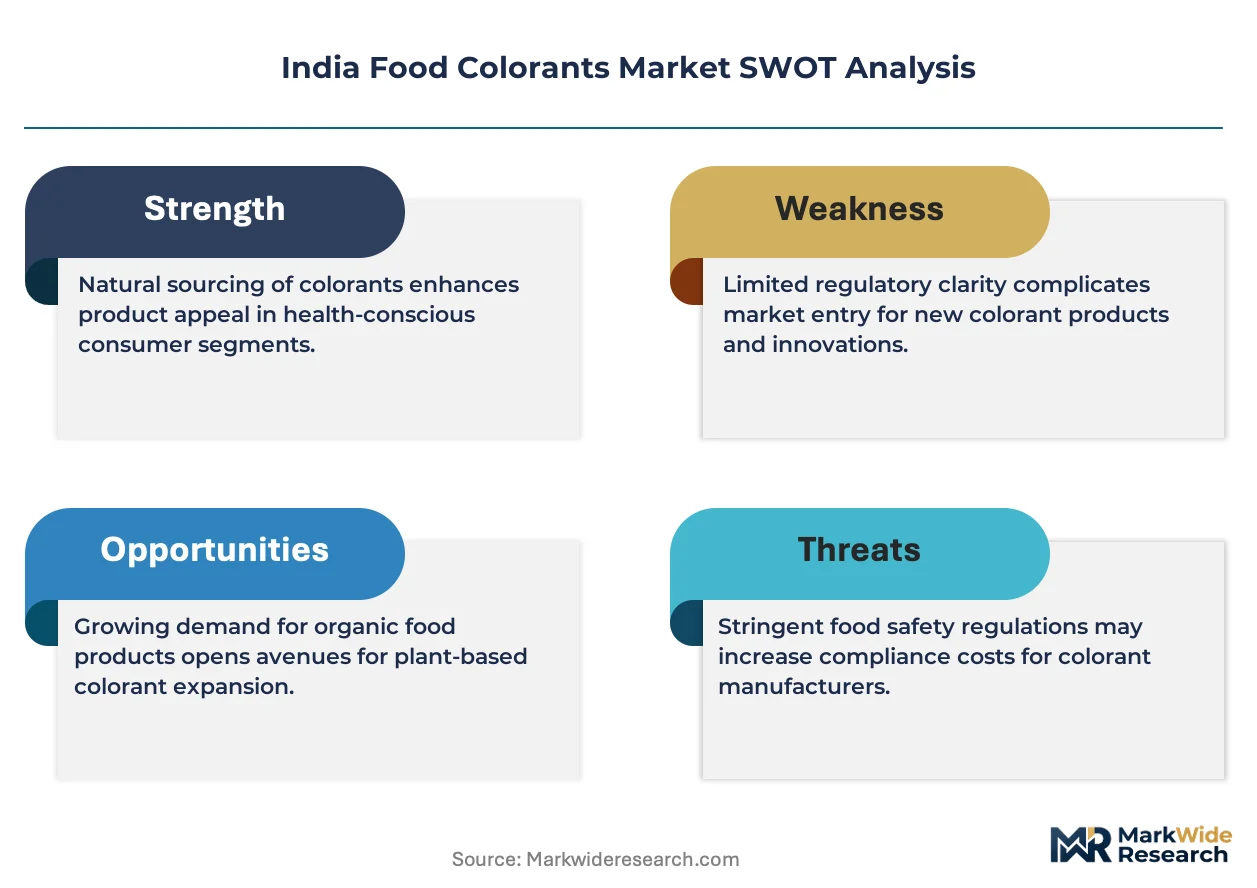
FSSAI labeling requirements and BIS quality standards govern permissible additive lists, maximum usage levels, and declaration protocols for synthetic and natural colorants distributed across Indian states. The FSSAI's draft amendments on artificial color restrictions in children's food products are reshaping reformulation roadmaps for domestic manufacturers and multinational subsidiaries alike. Stakeholders must monitor regulatory divergence between central FSSAI notifications and state-level enforcement intensity to anticipate compliance cost trajectories and procurement specification shifts.
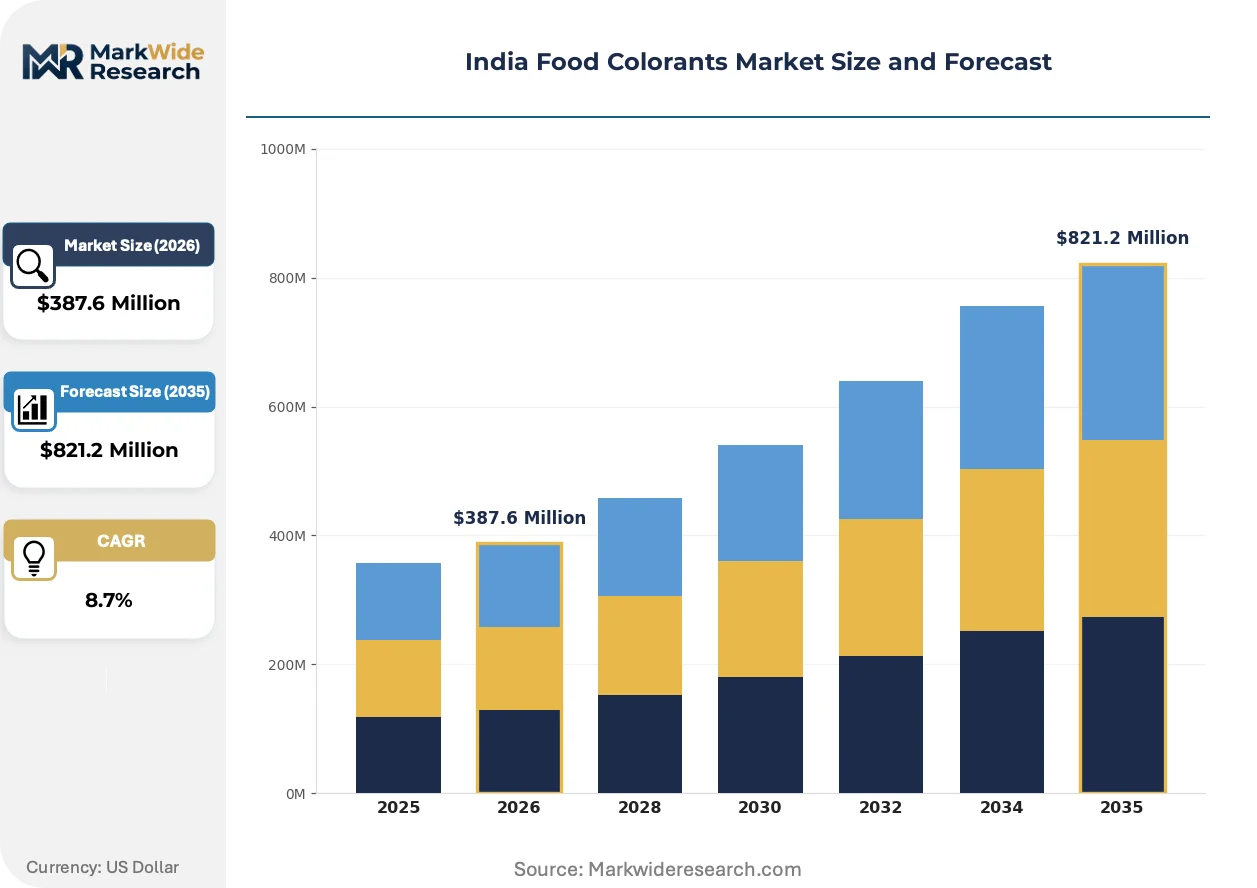
Market Dynamics
FSSAI's tightening labeling norms for artificial additives are forcing processed food manufacturers across Maharashtra and Gujarat to accelerate synthetic-to-natural conversion timelines, recalibrating procurement specifications and supplier qualification protocols throughout the value chain.
Growth Catalysts
- Clean-label mandates:Dairy and confectionery clusters in western and northern states are driving specification shifts toward anthocyanin and carotenoid-based alternatives as consumer scrutiny intensifies.
- FSSAI draft amendments:Proposed restrictions on artificial colors in children's food products are compelling reformulation investments across domestic manufacturers and multinational subsidiaries.
- Fermentation-derived pigments:Microbial production platforms are expanding supply security for heat-stable natural colorants in beverage applications requiring pH tolerance between 2.5 and 8.0.
Market Restraints
- Botanical input volatility:Turmeric, beetroot, and spirulina harvest fluctuations in Karnataka and Madhya Pradesh create pricing instability for oleoresin extractors.
- Import dependence for specialized strains:Starter cultures for fermentation-derived carotenoids concentrate with Danish and Dutch suppliers, exposing buyers to currency and shipping cost swings.
- Technical stability gaps:Chlorophyllin degradation under UV exposure and thermal processing limits substitution rates in extruded snack applications.
Strategic Opportunities
- Underpenetrated eastern markets:Odisha and West Bengal dairy cooperatives remain underserved by natural colorant technical service teams, creating first-mover positioning for formulation-support capabilities.
- PLI scheme alignment:Food processing infrastructure incentives under India's Production Linked Incentive scheme reduce capital barriers for captive extraction facilities.
- Direct-to-manufacturer digital platforms:B2B marketplaces are compressing distributor layers, enabling smaller confectionery units in Rajasthan and Punjab to access technical-grade natural colors previously locked behind minimum order thresholds.
Industry Challenges
- Formulation chemist scarcity:pH-stable natural colorant application expertise concentrates with legacy synthetic color technicians, creating knowledge transfer bottlenecks during plant conversions.
- BIS-FSSAI compliance synchronization:Divergent testing protocols between central notifications and state-level enforcement in Gujarat versus Tamil Nadu generate certification timeline uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Food Colorants Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Naturals, Synthetic, Lake Colors, Caramel Application: Beverages, Bakery, Dairy, Confectionery End User: Food Manufacturers, Beverage Producers, Culinary Industries, Retailers Form: Liquid, Powder, Gel, Granular |
| Companies Covered | Sensient Technologies Corp., Döhler Group, Chr. Hansen Holding A/S, ADM, BASF SE, Kancor Ingredients Private Limited, Roha Dyechem, GNT Group, DDW The Color House, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Food Colorants Market Shifts & Advancements
Microbial fermentation platforms and precision extraction technologies are compressing cost premiums between natural and synthetic colorants, while regulatory pressure on artificial additives accelerates specification migration across dairy, beverage, and savory processing verticals.
Encapsulation technology using modified starch and gum arabic matrices is consolidating performance parity for natural colorants in UHT-treated dairy and retort-processed savory applications. Mid-sized dairy cooperatives in Gujarat and Karnataka are adopting these systems at accelerating rates. The technology is consolidating supplier power toward integrated formulation houses that combine colorant supply with application engineering.
FSSAI's 2023 draft notification on artificial color restrictions in foods targeted at children is compressing reformulation timelines for domestic confectionery and RTE snack manufacturers. The regulation mandates declaration thresholds and permissible limits that diverge from Codex Alimentarius standards, creating India-specific specification complexity. Children's food specialists in Mumbai and Delhi NCR are responding by pre-qualifying dual-source natural colorant suppliers ahead of final rule promulgation.
Buyer concentration among organized retail private labels and QSR chains is compressing supplier negotiation leverage and accelerating specification standardization. Direct contracting between Reliance Retail, Tata Consumer, and specialty colorant houses is displacing traditional distributor-mediated procurement in Maharashtra and Karnataka. This pattern is most visible in the western states where dairy and confectionery cluster density supports volume-commitment economics.
India Food Colorants Market Segmentation
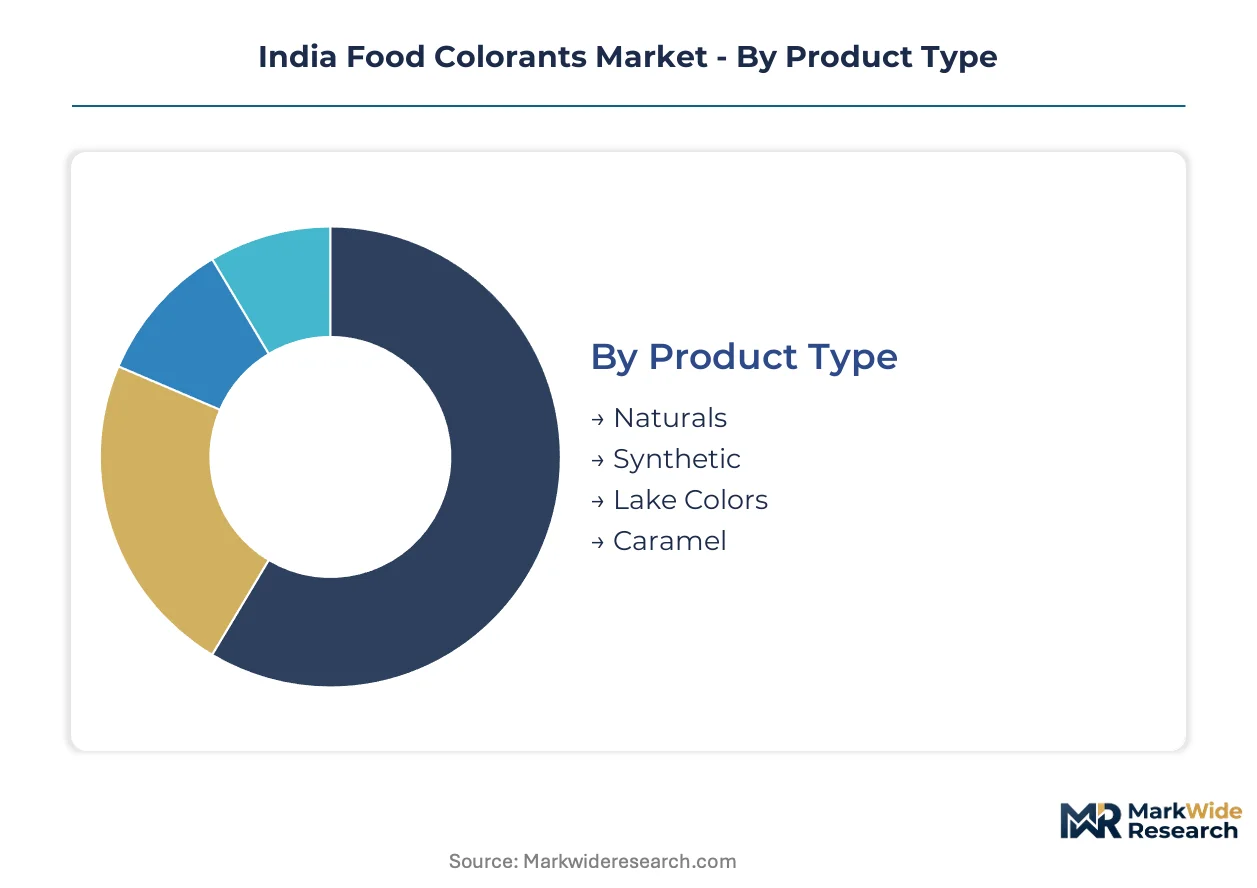
Food colorant procurement in India diverges sharply across product chemistry, application heat-stability requirements, and customer scale. Specification decisions hinge on FSSAI compliance thresholds, reformulation timelines, and clean-label positioning against organized retail audit standards.
Product Type:
Cost tier determines supplier qualification depth and technical service intensity.
- Naturals:Anthocyanin, carotenoid, and chlorophyllin extracts from turmeric, beetroot, and spirulina. Dairy clusters in Gujarat and Maharashtra are driving specification migration here as clean-label mandates harden.
- Synthetic:Tartrazine, sunset yellow, and allura red azo dyes deliver cost efficiency and heat stability. Reformulation pressure from FSSAI draft amendments on children's food products is compressing volume outlook in confectionery.
- Lake Colors:Water-insoluble pigment complexes formed by precipitating dyes onto aluminum hydrate substrates. Fat-based confectionery applications in northern states sustain procurement.
- Caramel:Heat-treated carbohydrate solutions delivering brown hues across beverage and bakery segments. Class I through IV classifications align with label declaration requirements.
Volume sits with Synthetic; growth tilts toward Naturals.
Application:
Heat exposure and pH tolerance requirements segment formulation expertise and supplier matching.
- Beverages:Liquid natural colorants requiring pH stability between 2.5 and 8.0 dominate procurement. Fermentation-derived carotenoids from microbial platforms are expanding supply security for acidic fruit drinks.
- Bakery:Powder and granular forms sustain demand where oven temperatures demand heat-stable caramel and encapsulated natural variants. Rajasthan and Punjab processing units are scaling procurement.
- Dairy:UHT-treated milk and flavored yogurt applications concentrate in western state cooperatives. Encapsulation technology using modified starch matrices is consolidating supplier power toward integrated formulation houses.
- Confectionery:Lake colors and natural alternatives compete across hard-boiled candies and chocolate coatings. Mumbai and Delhi NCR manufacturers are pre-qualifying dual-source natural suppliers ahead of final FSSAI rule promulgation.
Dairy captures current procurement volume; beverage reformulation is climbing the fastest.
End User:
Customer scale dictates technical service access and minimum order threshold exposure.
- Food Manufacturers:Processed food producers across Maharashtra and Gujarat are accelerating synthetic-to-natural conversion timelines. Direct contracting with specialty colorant houses is displacing distributor-mediated procurement.
- Beverage Producers:Organized juice and soft drink bottlers in Karnataka demand pH-stable natural solutions with batch-to-batch consistency guarantees.
- Culinary Industries:Restaurant chains and cloud kitchen operators require oil-dispersible and water-soluble formats for sauce and dessert applications.
- Retailers:Reliance Retail and Tata Consumer private labels are compressing supplier negotiation leverage through volume-commitment economics and specification standardization.
Food Manufacturers anchor volume; Retailers are gaining share fastest on private label expansion.
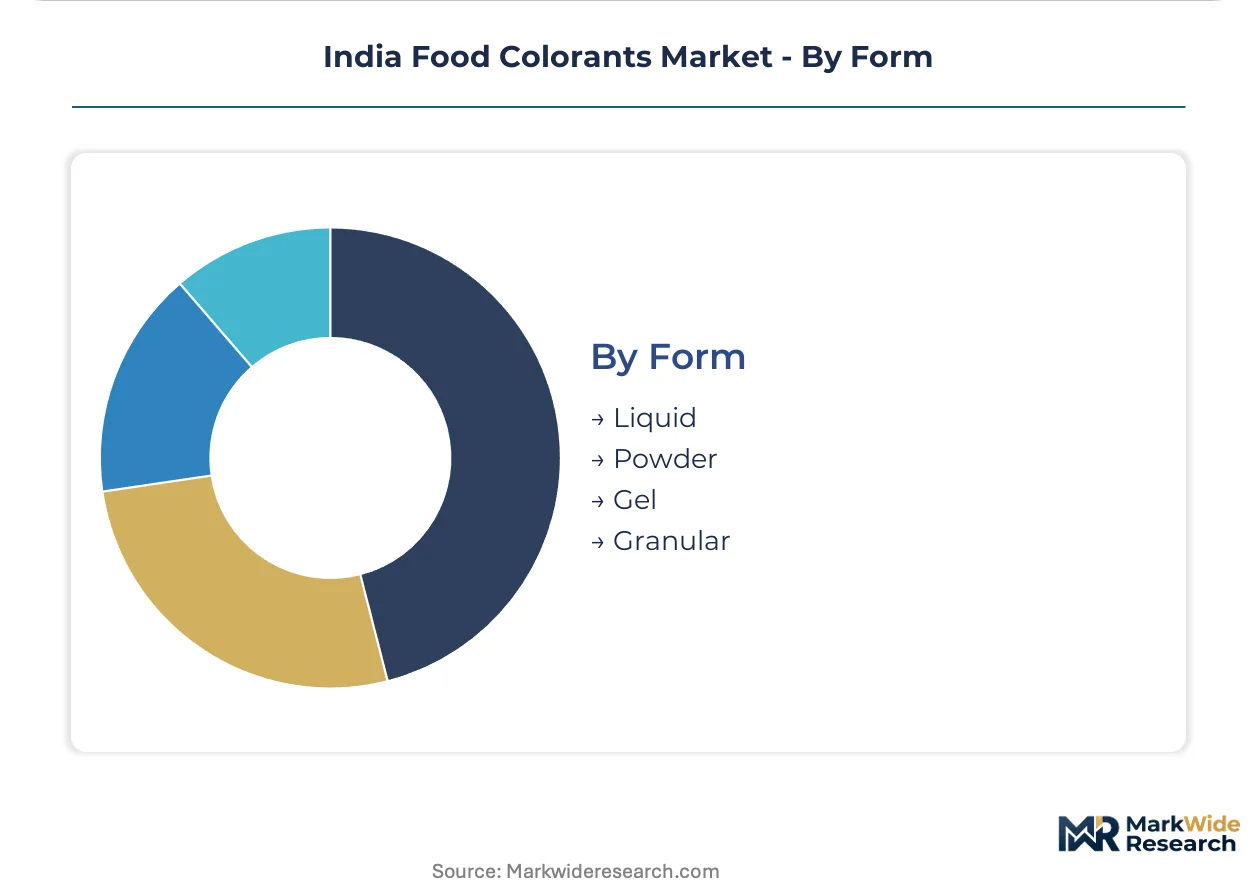
Form:
Dispersion precision and moisture resistance determine processing compatibility.
- Liquid:Preferred for beverage dosing precision and uniform dispersion. Standard concentration formats reduce weighing error in high-speed bottling lines.
- Powder:Dominates bakery and dry mix applications where moisture resistance determines shelf stability. Heat stability during oven exposure drives specification compliance.
- Gel:Concentrated suspensions for fat-based confectionery and compound coating applications requiring controlled viscosity.
- Granular:Low-dust handling properties suit large-scale dairy powder fortification and industrial bakery premix operations.
Liquid holds volume leadership; Powder maintains steepest expansion trajectory on bakery cluster growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turmeric cultivation in Karnataka and spirulina harvesting in Madhya Pradesh anchor the upstream botanical supply base for India's natural colorant conversion wave.
Maharashtra
Mumbai and Pune dairy cooperatives are accelerating synthetic-to-natural reformulation timelines ahead of FSSAI draft amendments on children's food products. The state's food processing PLI scheme beneficiaries are installing captive extraction capacity for anthocyanin-based colorants. Nashik-based confectionery clusters are pre-qualifying dual-source natural suppliers to secure compliance-ready procurement pipelines.
Gujarat
Anand and Vadodara dairy processing belts concentrate demand for encapsulated natural colorants in UHT milk applications. FSSAI labeling norm tightening is forcing Ahmedabad-based snack manufacturers to migrate from tartrazine toward carotenoid alternatives. Surat's confectionery exporters are aligning specifications with Reliance Retail private label audit standards.
Karnataka
Bengaluru beverage bottlers are demanding pH-stable natural solutions with batch-to-batch consistency for acidic fruit drink portfolios. The state's spirulina and turmeric harvest volatility creates pricing instability for oleoresin extractors. Mysuru-based bakery clusters are scaling powder-form natural colorant procurement for oven-stable applications.
Tamil Nadu
Chennai's organized retail private label manufacturers are compressing supplier negotiation leverage through direct contracting with specialty colorant houses. State-level FSSAI enforcement intensity diverges from Gujarat protocols, generating certification timeline uncertainty for multi-state processors. Coimbatore dairy cooperatives are adopting fermentation-derived pigment platforms for heat-stable formulations.
West Bengal
Kolkata dairy cooperatives remain underserved by natural colorant technical service teams, creating first-mover positioning for formulation-support capabilities. The state's confectionery tradition in hard-boiled candy production sustains lake color demand even as natural alternatives penetrate. BIS quality standard compliance gaps between central notifications and local enforcement complicate procurement specification alignment.
India Food Colorants Market Competitive Landscape
Portfolio diversification dominates the current landscape as synthetic specialists accelerate natural colorant capability builds and fermentation platforms expand supply security. The vendor base stratifies across integrated multinational houses, domestic extraction specialists, and regional distributor-assemblers. Three archetypes anchor positioning: microbial fermentation platforms, botanical oleoresin extractors, and lake color legacy manufacturers. Capacity expansion in western state extraction facilities and strategic partnerships with dairy cooperative technical service teams represent the dominant competitive vectors.
Within the fermentation-platform tier, Chr. Hansen Holding A/S anchors microbial-derived pigment supply for dairy applications, while Roha Dyechem exemplifies the synthetic-to-natural transition archetype with dual-portfolio positioning. Kancor Ingredients Private Limited represents the botanical extraction specialist model focused on oleoresin-based natural colors. These three occupy distinct competitive spaces without direct overlap in core technology platforms.
| Leading Market Players |
|---|
| Sensient Technologies Corp. |
| Döhler Group |
| Chr. Hansen Holding A/S |
| ADM |
| BASF SE |
| Kancor Ingredients Private Limited |
| Roha Dyechem |
| GNT Group |
| DDW The Color House |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap extraction specialists across Karnataka and Madhya Pradesh anchor India's natural colorant supply base, translating harvest volatility into spot-price premiums that compress margins for downstream formulation houses while forcing long-term contract structures.
Pricing Analysis
Technical service bundling separates premium-tier suppliers from commodity traders, with pH-stability guarantees and formulation support commanding 15-25% markups over unbundled pigment sales. Three-tier pricing structure across premium certified-organic, standard FSSAI-compliant, and economy synthetic-replacement tiers reflects certification depth and volume scale. Cost compression in the economy tier is intensifying because Reliance Retail and Tata Consumer private labels are consolidating procurement through direct-contract volume commitments. Small confectionery units in Rajasthan and Punjab exhibit highest price sensitivity, while organized dairy cooperatives in Gujarat prioritize batch consistency over unit cost.
Supply Chain Analysis
FSSAI certification and BIS quality standard compliance gating restricts supplier qualification to a narrow tier of integrated houses with in-house testing infrastructure. Raw material sourcing draws from turmeric cultivation in Karnataka, spirulina harvesting in Madhya Pradesh, and imported starter cultures for fermentation-derived carotenoids from Denmark and the Netherlands. Single-source vulnerability concentrates in microbial strain supply, where Danish suppliers control proprietary production platforms. Distribution runs through specialty chemical distributors in western states, with direct-to-manufacturer digital platforms emerging as secondary channels for smaller processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's food colorant sector is consolidating into a vertical-integration race where captive extraction capacity and fermentation-platform control determine cost parity against synthetic alternatives.
For Market Incumbents: Anticipate FSSAI final rule promulgation on children's food color restrictions by pre-qualifying dual-source natural suppliers and locking multi-year botanical offtake agreements with Karnataka turmeric cooperatives. Backward integration into spirulina cultivation in Madhya Pradesh secures supply continuity against harvest volatility that threatens margin stability. For New Entrants and Emerging Players: Begin with technical service deployment to underserved eastern state dairy cooperatives in Odisha and West Bengal, where formulation-support capabilities remain scarce and first-mover positioning is achievable. Target pH-stable natural colorant development for acidic beverage applications, leveraging fermentation-derived pigment platforms to bypass botanical input volatility. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap oleoresin extractors with FSSAI-certified facilities in Maharashtra and Gujarat, where regulatory compliance costs are filtering out unqualified competitors. Watch for inflection signals in Reliance Retail private label audit standard adoption rates, which accelerate specification standardization and compress supplier negotiation leverage.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Extraction Facility Buildout | PLI scheme alignment reduces capital barriers for turmeric and spirulina processing in Karnataka. |
| Fermentation Platform Partnership | Microbial-derived pigment supply agreements with Danish technology providers secure heat-stable natural alternatives. |
| Direct-to-Manufacturer Digital Channel | B2B marketplace deployment compresses distributor layers for Rajasthan and Punjab confectionery units. |
| Encapsulation Technology Licensing | Modified starch matrix adoption consolidates supplier power in Gujarat UHT dairy applications. |
| Dual-Source Supplier Pre-Qualification | Mumbai and Delhi NCR manufacturers secure compliance-ready pipelines ahead of FSSAI children's food rule finalization. |
Research Methodology
Multi-period observation of FSSAI notification drafts, BIS standard amendments, and state-level enforcement intensity anchored the trend analysis, supplemented by interviews with formulation chemists at dairy cooperatives, procurement leads at confectionery manufacturers, technical directors at extraction facilities, and regulatory affairs specialists. Secondary validation drew from FSSAI gazette notifications, BIS quality standard publications, customs import records for fermentation starter cultures, and Production Linked Incentive scheme beneficiary disclosures. Bottom-up volume aggregation across western and northern state clusters triangulated against top-down market sizing.
Input-output matrices modeled colorant demand by application heat-stability requirements, pH tolerance specifications, and customer scale tiers across the projection horizon. Segmentation dimensions included product chemistry, formulation format, end-user procurement sophistication, and regional cluster density. CAGRs were derived from regression analysis of historical procurement volumes against regulatory milestone timing and clean-label adoption curves. Forecast inputs incorporated botanical harvest yield volatility indices and fermentation-platform capacity expansion timelines.
Underlying measurement precision varies by segment; synthetic colorant procurement volumes carry tighter precision than emerging natural alternatives where supplier qualification is incomplete. Forecasts reflect assumptions about FSSAI rule finalization timing and PLI scheme disbursement continuity. A model refresh is warranted upon material change in central-state regulatory enforcement divergence or spirulina harvest disruption events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Wheat & Rice Flour Substitute-Resistant Starch Market
Food Additives and Ingredients
Italy Food Enzymes Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Argentina Food Preservatives Market
Food Additives and Ingredients
Glandular Ingredients Market
Food Additives and Ingredients
Feed Anti-Caking Agents Market
Food Additives and Ingredients
Modified Milk Ingredients Market
Food Additives and Ingredients
Ammonia Caramel Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Seitan Powder Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
Carob Gum Market
Food Additives and Ingredients
Egg Wash Substitute Market
Food Additives and Ingredients
Low Methoxyl Pectin Market
Food Additives and Ingredients
Dairy Enzymes Market
Food Additives and Ingredients
Australia Anti Caking Market