
 Leavening Agents Market | 2026-2036
Leavening Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Leavening Agents Market Intelligence
The proliferation of clean-label and non-GMO certified leavening agents is redrawing the competitive landscape for ingredient suppliers. Kerry Group leverages its extensive portfolio to offer integrated bakery and snack food solutions. Corbion specializes in advanced fermentation and acid-based leaveners for improved texture and shelf-life. Global yeast leader Lesaffre sustains its market position through massive production scale and a deep distribution network.
Leavening agents are substances that produce gas, typically carbon dioxide, causing doughs and batters to rise and become light in texture. These agents function through biological reactions, as with yeast, or chemical reactions involving an acid and a base like sodium bicarbonate. Yeast remains the dominant product type by volume, particularly for commercial bakeries. However, enzyme-based agents are gaining share, driven by demand from the health-conscious snack foods segment.
Food safety regulations from bodies like the US FDA and the European Food Safety Authority (EFSA) dictate permissible ingredients and purity levels. In China, compliance with GB standards for food additives is mandatory for market access, influencing formulation choices for both domestic and foreign producers. Navigating these varied international standards while managing raw material costs remains a central strategic challenge for manufacturers.
Market Dynamics
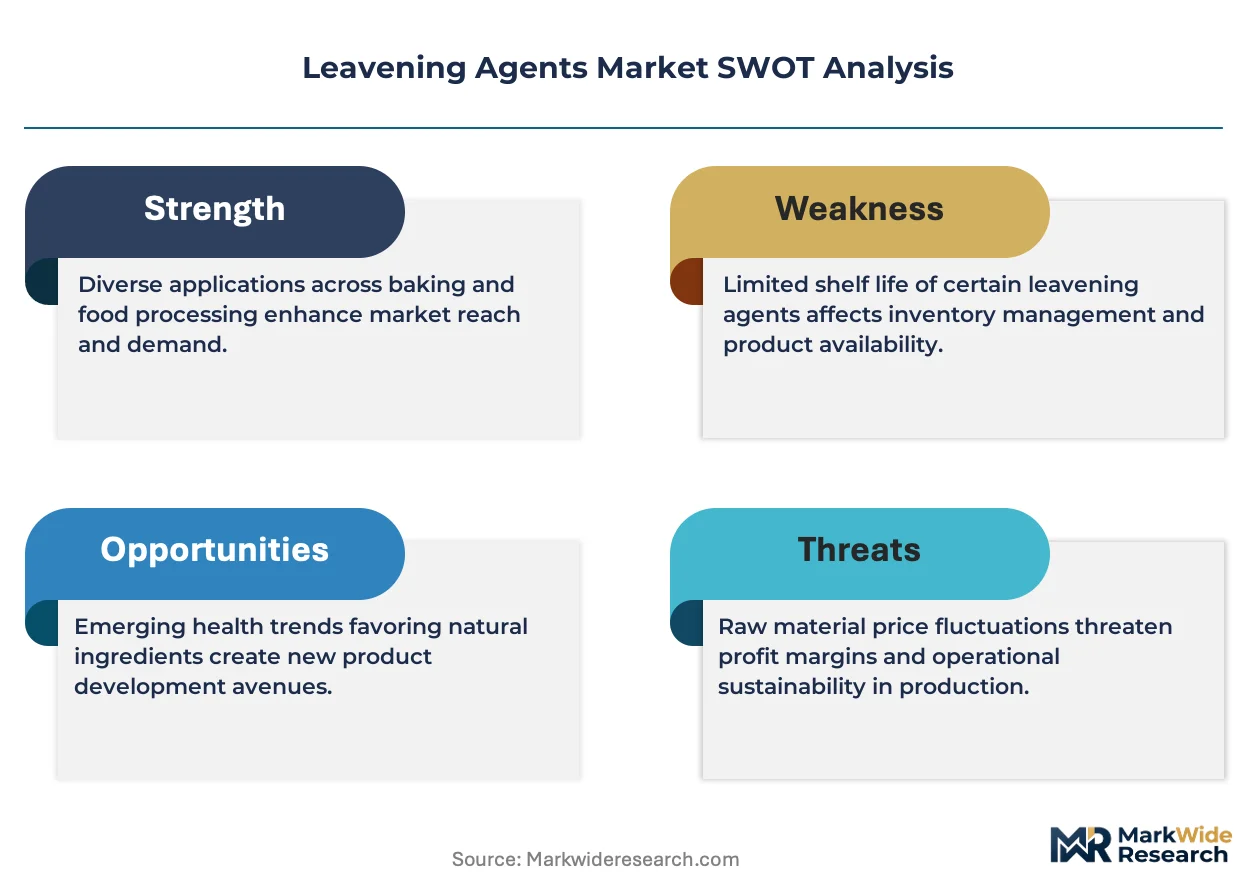
The central tension shaping the leavening agents market is the divergence between high-volume, price-sensitive demand for commodity yeast and the growing requirement for specialized, functional leavening systems driven by the global clean-label movement in processed foods.
Growth Catalysts
- Snack Food Expansion:The proliferation of the global snack foods industry, particularly in ready-to-eat and convenience formats, creates consistent demand for specialized leavening agents that ensure product consistency and shelf stability.
- Clean-Label Consumerism:Consumer preference for products with simple, recognizable ingredients, especially in North America and Europe, is fueling the adoption of non-GMO certified yeast and enzyme-based leaveners over traditional chemical agents.
- Baking Technology Advances:Development of microencapsulation techniques for chemical leaveners allows for controlled gas release during baking, improving texture and volume in products like frozen doughs and pre-packaged cake mixes.
Market Restraints
- Raw Material Volatility:Fluctuating costs of key inputs for chemical leaveners, such as food-grade phosphates and sodium bicarbonate derived from commodity mineral markets, create margin pressure for manufacturers.
- Regulatory Scrutiny:Strict limits on additives like aluminum compounds, enforced by regulators such as the European Food Safety Authority (EFSA), restrict formulation options and increase the cost of compliance for market access.
- Yeast Dominance:The entrenched use of traditional yeast in the high-volume commercial bread sector presents a significant substitution barrier for alternative leavening agents, limiting their overall market penetration by volume.
Strategic Opportunities
- Emerging Market Bakeries:Commercial baking industries in Southeast Asia and Latin America are expanding rapidly, presenting an opportunity for suppliers to introduce advanced leavening systems beyond basic yeast and baking soda.
- Plant-Based Formulations:The growing plant-based food segment requires novel leavening solutions to mimic the texture and rise of traditional baked goods, creating a new market for customized agent blends.
- Fermentation-Derived Acids:Developing and marketing leavening systems that utilize fermentation-derived organic acids as the acid component can appeal to clean-label trends and offer unique flavor and texture profiles.
Industry Challenges
- Navigating Global Standards:Manufacturers face significant operational friction in aligning product formulations with the divergent requirements of national food additive regulations, such as China's GB standards versus US FDA guidelines.
- Biological Agent Logistics:Ensuring the stability and viability of live yeast cultures and temperature-sensitive enzymes throughout the global supply chain requires specialized, costly cold-chain infrastructure and handling protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leavening Agents Market |
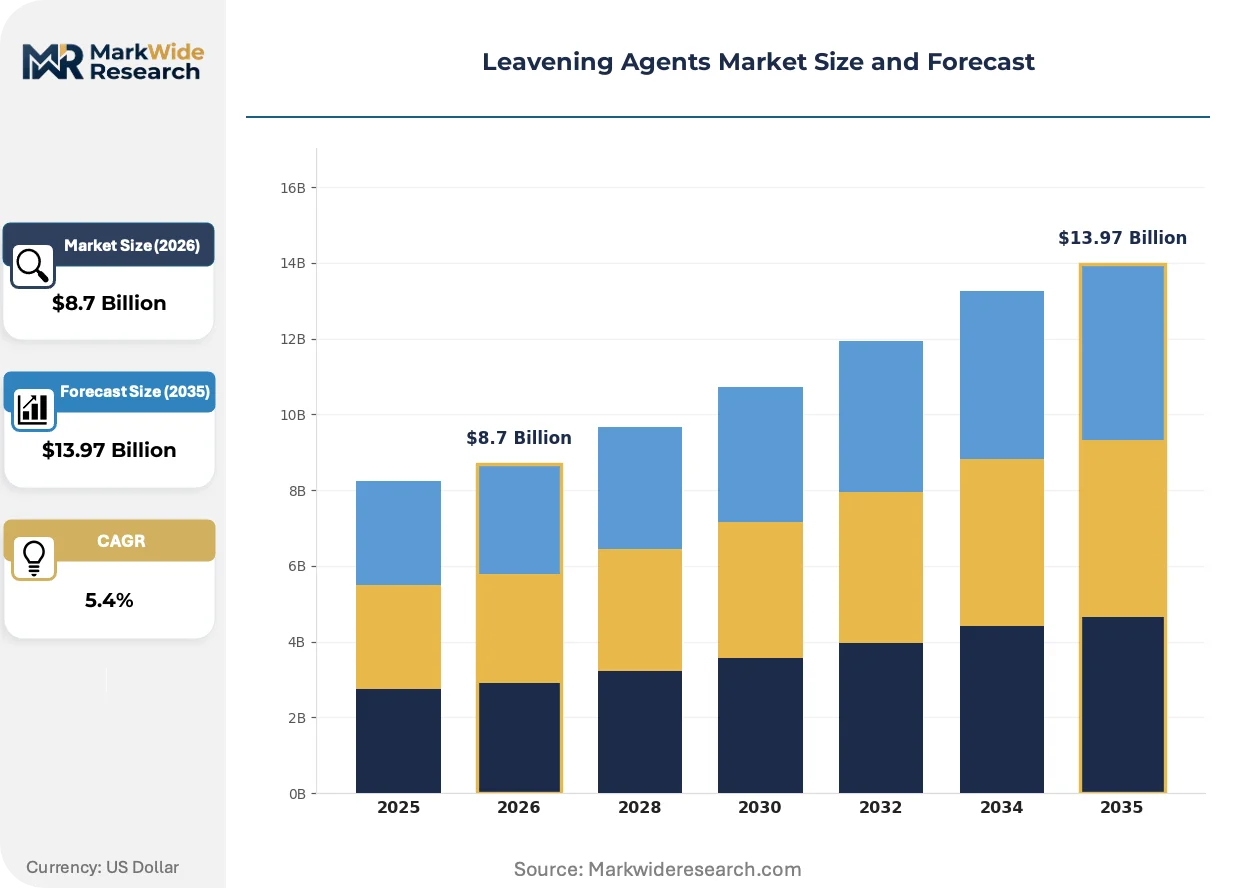
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baking Powder, Yeast, Baking Soda, Ammonium Bicarbonate, Enzyme-based Agents Application: Bakery Products, Confectionery, Meat Processing, Beverage Industry, Snack Foods Form: Powder, Granules, Liquid, Tablet, Paste End User: Commercial Bakeries, Food Service Providers, Meat Processors, Beverage Manufacturers, Snack Producers |
| Companies Covered | Kerry Group, Angel Yeast, Lesaffre, Corbion, DSM, AB Mauri, Cargill, Puratos, Lallemand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leavening Agents Market Strategic Shifts & Innovations
The market's evolution is defined by the application of food science to meet specific consumer demands for both health and convenience. This is transforming leavening agents from simple commodities into functional ingredients that deliver targeted performance benefits like improved texture or a cleaner ingredient declaration.
Enzyme-based leavening agents act on substrates within dough, such as starches or proteins, to generate gas and modify texture. The health-focused snack food and artisanal bakery segments are adopting these systems to enhance product quality without chemical additives. This technology is supplanting conventional chemical leaveners in premium applications where a clean label and superior crumb structure are critical market differentiators.
China's rigorous enforcement of its GB standards for food additives mandates very low or zero aluminum content in baked goods. This regulation compels producers targeting the vast Chinese market to reformulate their products, accelerating the switch to non-aluminum chemical systems or enzyme-based alternatives. The industrial bakery sector, a major consumer of leavening agents in China, is the most affected and is actively seeking compliant solutions to maintain market access.
Large-scale commercial bakeries are progressively moving away from purchasing individual commodity ingredients. Instead, they are seeking customized, pre-blended leavening systems from suppliers that are optimized for specific product lines, like frozen pizzas or gluten-free bread. This demand for bespoke solutions is most evident in the sophisticated North American and European food processing markets, where product differentiation and process efficiency are paramount.
Leavening Agents Market Segmentation
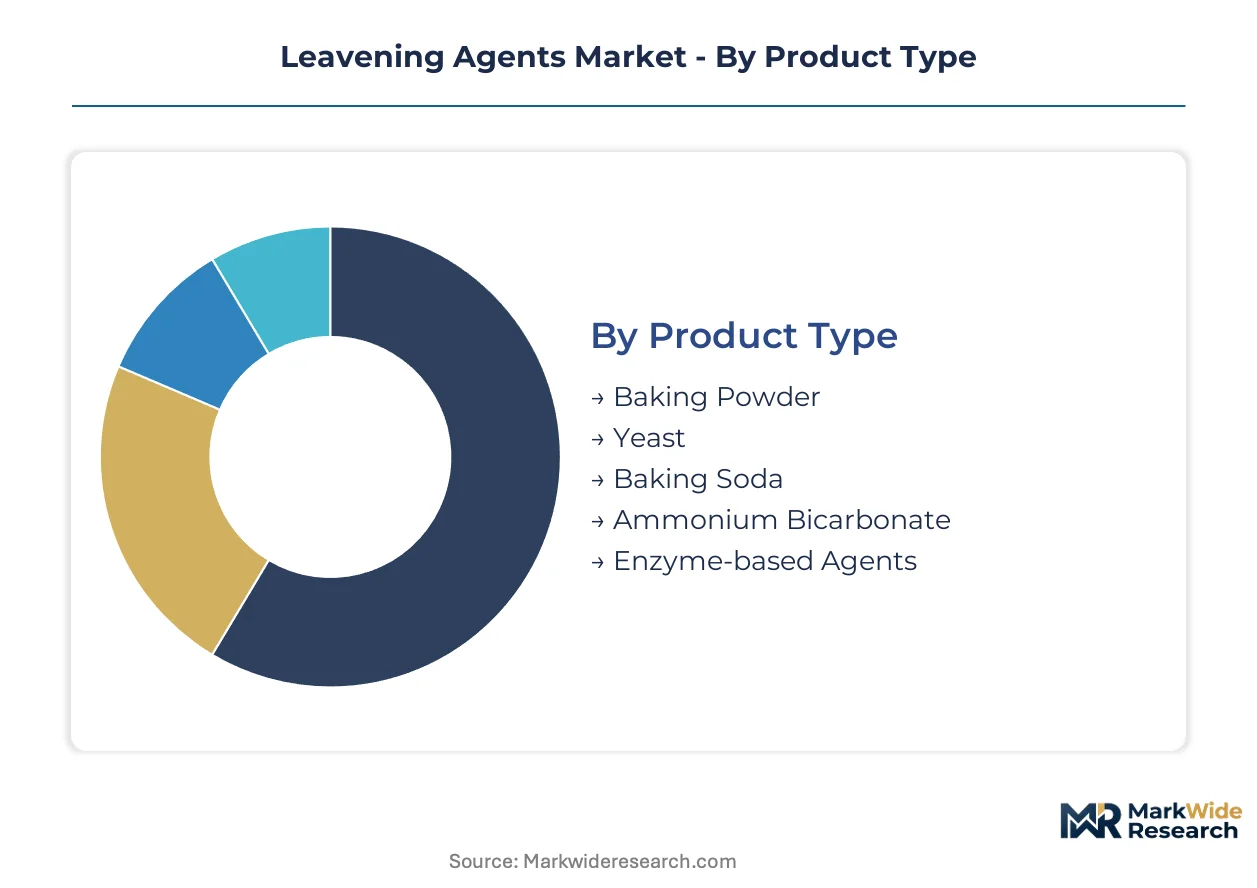
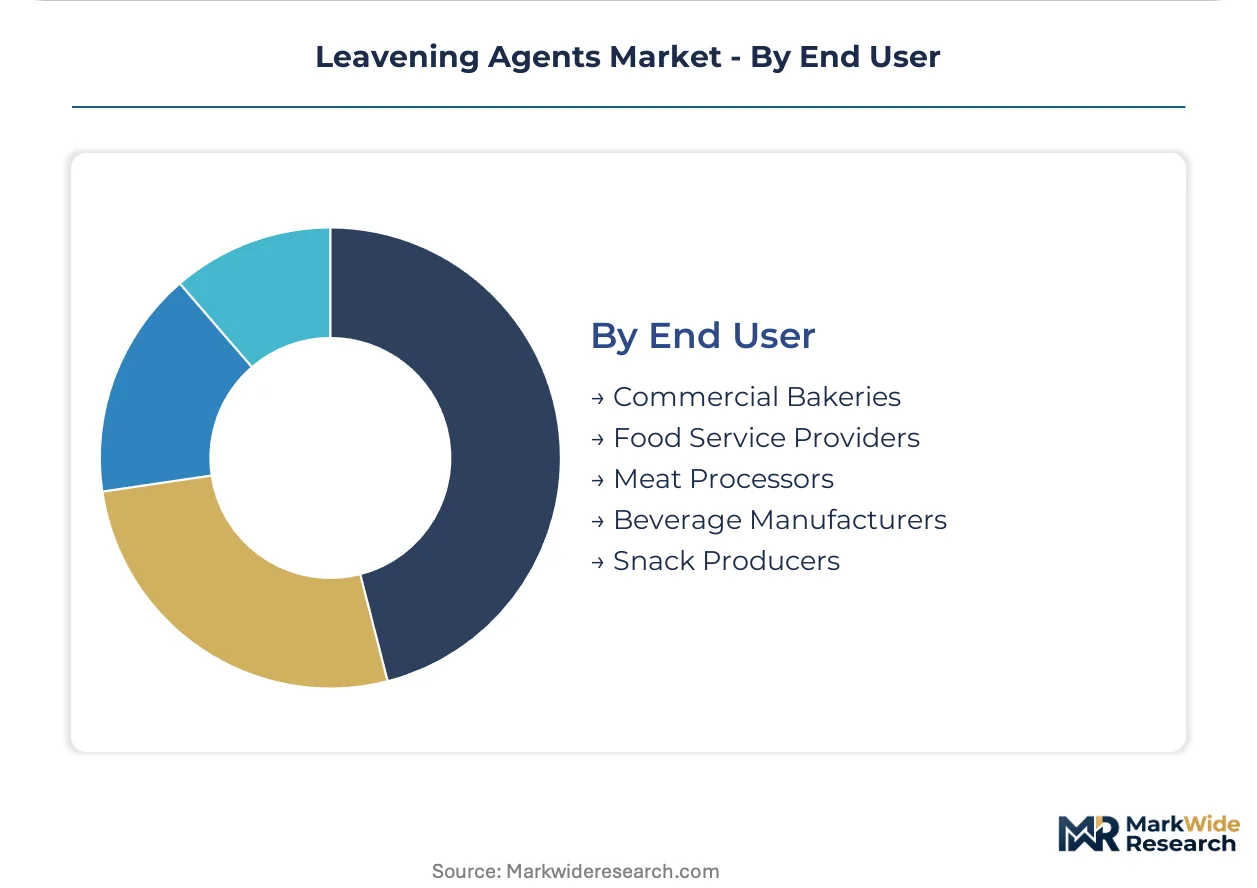
Understanding the Leavening Agents Market through segmentation reveals distinct demand patterns and regulatory influences. Product types vary in gas generation mechanisms, impacting their suitability for diverse food applications. End-user requirements drive specific formulation choices, from large-scale commercial bakeries to specialized snack producers.
Product Type:
Regulatory bodies like the US FDA and China's GB standards significantly differentiate acceptable ingredients, influencing product type usage across regions.
- Yeast:This biological leavener, primarily Saccharomyces cerevisiae, ferments sugars to produce carbon dioxide, providing rise and characteristic flavor. Demand concentrates heavily within large-scale commercial bakeries in Europe, driven by traditional bread production volumes.
- Enzyme-based Agents:These systems utilize enzymes to break down dough components, generating gas and improving texture without chemical residues. The health-conscious snack foods segment in North America shows strong adoption, seeking cleaner labels and enhanced product quality.
- Baking Powder:A chemical leavener combining an acid, a base (sodium bicarbonate), and a starch, it releases CO2 upon moisture and heat exposure for quick breads.
- Baking Soda:Pure sodium bicarbonate, this base requires an acidic ingredient in the recipe to produce carbon dioxide for leavening.
- Ammonium Bicarbonate:This leavener decomposes entirely into gaseous products during baking, suitable for thin, crispy products like crackers and cookies.
Yeast handles the majority of throughput; enzyme-based agents are the fastest mover on share.
Application:
Leavening agents find diverse utility across the food industry, with each application demanding specific functional properties for optimal product outcomes.
- Bakery Products:This segment encompasses bread, cakes, pastries, and rolls, requiring leavening for volume, texture, and crumb structure. Commercial bakeries in China exhibit high demand for consistent, cost-effective leavening solutions to meet mass consumption.
- Snack Foods:This category includes crackers, cookies, and extruded snacks, where leavening contributes to crispness, lightness, and uniform expansion. Consumer preference for convenient, health-oriented snacks in the US drives innovation in specialized leavening systems.
- Confectionery:Leavening agents provide aeration and texture to products like biscuits, wafers, and some candies, influencing mouthfeel and appearance.
- Meat Processing:Certain leavening compounds can be used in processed meats to improve texture and moisture retention, though their application is niche.
- Beverage Industry:While less common, some specialized beverage applications might use leavening-related ingredients for texture or effervescence, particularly in powdered mixes.
Bakery products consume the largest volume of leavening agents, while the snack foods segment requires increasingly specialized and functional formulations.
Form:
The physical form of leavening agents significantly impacts handling, storage stability, and integration into diverse manufacturing processes.
- Powder:The most common form, powders offer ease of measurement, blending, and distribution for both industrial and home baking. Large-scale food processors in Germany prefer powdered chemical leaveners for their consistent performance and extended shelf life.
- Liquid:Liquid leavening systems provide precise dosing and can facilitate uniform dispersion in specific batter or dough formulations. Industrial bakeries producing gluten-free products in the UK increasingly adopt liquid enzyme blends for enhanced texture control.
- Granules:Granular forms reduce dusting and improve flowability, often preferred in automated dispensing systems within commercial food manufacturing.
- Tablet:Tabletized leaveners offer pre-portioned convenience for small-batch or home baking applications, ensuring consistent ingredient ratios.
- Paste:Paste forms are less common but can offer specific textural or functional benefits in highly viscous doughs or specialized confectionery items.
Powdered leavening agents dominate the market in terms of volume, while liquid forms are gaining traction in specialized industrial applications.
End User:
The end-user landscape dictates both the scale of demand and the specific performance requirements for leavening agent formulations.
- Commercial Bakeries:These large-scale operations require high-volume, consistent, and cost-effective leavening agents for mass production of bread, rolls, and pastries. Bakeries in India prioritize robust yeast strains and baking powders for their extensive product lines.
- Snack Producers:Manufacturers of crackers, chips, and extruded snacks seek specialized leavening solutions for uniform expansion, texture, and crispness. The rapidly expanding snack market in Brazil drives demand for innovative enzyme-based and non-aluminum leaveners.
- Food Service Providers:This segment includes restaurants and catering, often using convenient, pre-portioned, or easy-to-use leavening products for in-house preparation.
- Meat Processors:A smaller segment, they may use specific leavening components as functional ingredients to enhance texture or binding in certain meat products.
- Beverage Manufacturers:This segment has limited direct use but might incorporate leavening-related ingredients in powdered drink mixes or specialized functional beverages.
Commercial bakeries represent the largest end-user segment by volume, but snack producers are increasingly demanding customized and high-performance leavening systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leavening agents market dynamics often hinge on a delicate balance between local production capabilities and the import of specialized ingredients. This interplay shapes regional supply chains and influences ingredient availability across diverse food manufacturing hubs. Regulatory frameworks further dictate the types of leavening solutions permissible within national borders.
China
Demand from large-scale commercial bakeries and food processing hubs drives significant consumption of leavening agents. China's rigorous enforcement of GB standards for food additives mandates very low or zero aluminum content in baked goods. The industrial bakery sector in the Yangtze River Delta actively seeks compliant solutions to maintain market access.
United States
The United States market sees strong adoption of enzyme-based and clean-label agents, driven by the health-conscious snack foods segment. US FDA regulations influence permissible ingredients and purity levels for all food additives. Food processing clusters in the Midwest adopt specialized leavening systems for product consistency and enhanced shelf stability.
Germany
German commercial bakeries prefer powdered chemical leaveners for their consistent performance and extended shelf life in mass production. The European Food Safety Authority (EFSA) limits additives like aluminum compounds, influencing formulation choices. Automated dispensing systems in Bavarian food manufacturers utilize efficient powdered forms for precision and integration.
India
India's commercial bakeries prioritize robust yeast strains and baking powders for their extensive product lines and high-volume throughput. The Food Safety and Standards Authority of India (FSSAI) governs food additive usage and ingredient quality. Delhi-NCR's growing bakery sector requires consistent, cost-effective leavening solutions to meet mass consumption.
Brazil
The rapidly expanding snack market in Brazil drives demand for innovative enzyme-based and non-aluminum leaveners. ANVISA regulations influence product formulation and market entry for new ingredients. São Paulo's snack producers adopt specialized systems for uniform expansion and texture in new product development.
Leavening Agents Market Key Industry Players
Concentration sits with established global ingredient suppliers offering integrated solutions. The leavening agents market exhibits a tiered structure, with high-volume commodity producers alongside specialized functional ingredient providers. Key archetypes include large-scale yeast manufacturers, fermentation technology specialists, and diversified food ingredient conglomerates. Dominant competitive moves involve strategic partnerships for market access and continuous portfolio diversification to meet evolving clean-label demands.
At the scale-driven end, Lesaffre exemplifies a global yeast leader with massive production scale and a deep distribution network. Corbion occupies a position as a specialist in advanced fermentation and acid-based leaveners for improved texture and shelf-life. Kerry Group represents a diversified food ingredient conglomerate, leveraging its extensive portfolio to offer integrated bakery and snack food solutions.
| Leading Market Players |
|---|
| Kerry Group |
| Angel Yeast |
| Lesaffre |
| Corbion |
| DSM |
| AB Mauri |
| Cargill |
| Puratos |
| Lallemand |
| Others |
Cost & Logistics Intelligence
China's GB standards for food additives, particularly regarding aluminum content, gate supply qualification and drive price differentiation for leavening agents. This regulatory framework compels manufacturers to invest in compliant formulations, impacting both production costs and market access. The shift towards enzyme-based and non-aluminum chemical systems reflects these compliance-driven pricing pressures.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for consistent leavening agent supply. Price differentiation stems from quality grade and certification level, particularly for non-GMO or clean-label offerings. Pricing pressure stems from volatile raw material costs for chemical leaveners, impacting commodity segments. Commercial bakeries exhibit high price sensitivity for bulk yeast, while health-conscious snack producers prioritize specialized functional agents regardless of cost.
Supply Chain Analysis
Inventory levels for biological leavening agents like yeast require careful cold-chain management, influencing lead times for global distribution. Geographic supply concentration for yeast centers on Europe and China, while enzyme-based production is more distributed, including North America. Raw material dependencies include sugar for yeast fermentation and food-grade phosphates for chemical leaveners. Commodity price volatility presents a structural risk across the supply chain. Distribution runs through a mix of specialized ingredient distributors and direct sales to large commercial food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a high-growth disruption driven by the clean-label consumer movement, fundamentally reshaping ingredient formulation and supply dynamics.
For Market Incumbents: Fortify core market share in traditional bakery segments through efficiency gains and strategic capacity expansion in emerging markets. Diversify product portfolios with enzyme-based and fermentation-derived solutions to counter the threat from clean-label alternatives. Invest heavily in R&D for next-generation leavening systems and secure raw material supply chains to mitigate commodity price volatility.
For New Entrants and Emerging Players: Service-layer gaps exist in customized, application-specific leavening blends for niche food categories. Target the rapidly expanding plant-based food segment and specialized snack producers in Southeast Asia with bespoke, clean-label solutions. A go-to-market angle focusing on sustainable sourcing and transparent ingredient declarations can differentiate offerings effectively.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap specialized ingredient firms possessing proprietary enzyme technologies or advanced fermentation capabilities. The long-term viability of the leavening agents market, over a 5-10 year window, remains strong due to fundamental food consumption trends. Watch for regulatory shifts in major markets, particularly new clean-label mandates, as an inflection indicator for acquisition targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme Technology Licensing | Expands product capabilities for incumbents and addresses clean-label demands in North America. |
| Capacity Expansion in Southeast Asia | Captures demand from rapidly growing commercial bakeries in Indonesia and Vietnam. |
| Fermentation-Derived Acid Development | Offers clean-label compliant alternatives for chemical leavening systems in Europe. |
| Customized Blends for Plant-Based Foods | Addresses specific texture challenges within the expanding plant-based food segment. |
| Cold-Chain Logistics Optimization | Enhances stability and viability of biological agents across global distribution networks, especially for Lesaffre. |
Research Approach
A spread of perspectives from R&D directors, procurement leads, food scientists, and commercial bakery owners converged on the working assumptions. This primary research was validated through extensive secondary data, including trade association reports, regulatory filings from the US FDA and EFSA, academic journals, and company financial reports. The analysis employed both bottom-up and top-down triangulation to ensure robust data integrity.
The analytical framework modeled segmentation dimensions including product type, application, form, end-user, and regional regulatory frameworks across the analysis window. Compound annual growth rates were derived through a combination of regression analysis on historical data and projected market share shifts. Forecast inputs included global snack food consumption growth rates and clean-label ingredient adoption trends in Western markets.
Forecasts assume regulatory continuity in key regimes like China's GB standards and US FDA guidelines; material policy shifts would require re-modeling. The analysis acknowledges that raw material price volatility and unforeseen supply chain disruptions could impact market outcomes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Natural Food Additives Market
Food Additives and Ingredients
Sunset Yellow FCF Market
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
Mexico Food Enzymes Market
Food Additives and Ingredients
Beverage Acidulants Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
South America Food Acidulants Market
Food Additives and Ingredients
Food Fungal Enzyme Market
Food Additives and Ingredients
Locust Bean Gum Market
Food Additives and Ingredients
Mexico Food Acidulants Market
Food Additives and Ingredients
Sugar Reduction Technology Market
Food Additives and Ingredients
Brazil Food Enzymes Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
Alpha-Linolenic Acid Market
Food Additives and Ingredients
Acetylated Distarch Phosphate Market