
 Bakery Contract Manufacturing Market | 2026-2036
Bakery Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Bakery Contract Manufacturing Market Intelligence
The unbundling of manufacturing, packaging, and logistics services is decoupling production scale from brand ownership for food companies. Hearthside Food Solutions LLC specializes in large-scale, complex production runs for major retailers and CPG brands. Aryzta AG leverages its international footprint to serve foodservice clients with specialized baked goods. Dawn Food Products, Inc. differentiates through its strong focus on ingredient supply and product development support.
Bakery contract manufacturing involves outsourcing the production of baked goods to a third-party facility. These operations utilize industrial-scale equipment, including continuous mixers and tunnel ovens, to ensure product consistency and safety. While breads and cookies for the retailer end-user segment constitute the largest volume, higher margins are found elsewhere. The gluten-free and organic quality grades represent the fastest-growing categories, demanding strict production segregation and certified ingredient sourcing.
Compliance with food safety standards is non-negotiable, governed by bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA). Regulations concerning allergen declarations and nutritional labeling, such as those from India's FSSAI, directly influence production processes and packaging claims. Contract manufacturers face a strategic choice between investing in flexible lines for product variety and dedicated lines for cost efficiency.
Market Dynamics
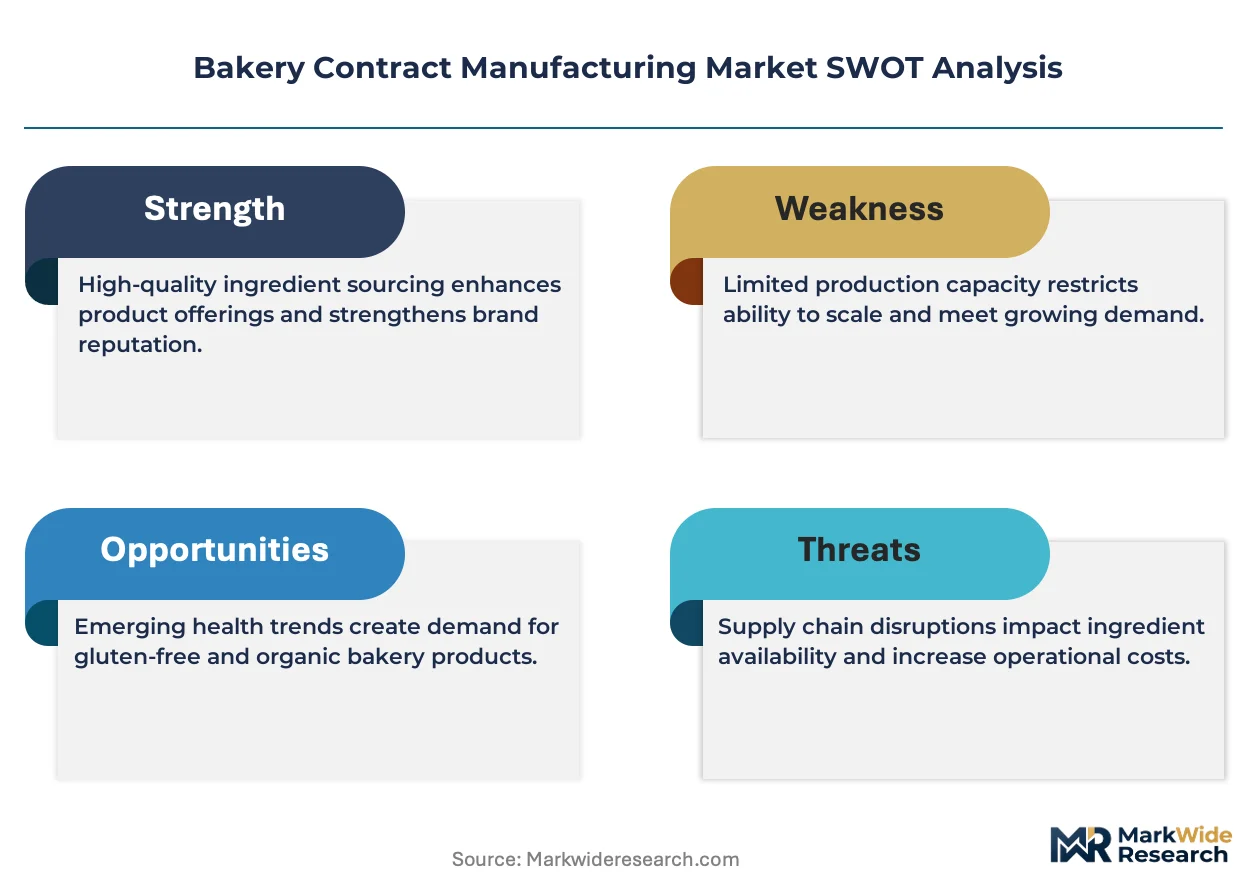
Stricter food safety and allergen labeling regulations from bodies like the FDA and EFSA are a central force shaping the market. This pressure mandates specialized production capabilities, driving food brands to outsource manufacturing to compliant third-party facilities to mitigate risk and access certified capacity.
Growth Catalysts
- Private-Label Proliferation:Expansion of retailer-owned brands in European grocery creates stable, high-volume demand for manufacturers meeting strict quality and cost targets.
- Specialty Diet Needs:Consumer demand for gluten-free and organic products requires certified, segregated production lines, which brands find more economical to outsource.
- Foodservice Outsourcing:Restaurant chains outsource baking to ensure product consistency across locations, driving demand for specialized contract manufacturing for their signature items.
Market Restraints
- Commodity Price Volatility:Fluctuations in prices for core ingredients like wheat, sugar, and cocoa directly impact margins and complicate long-term contract pricing.
- High Capital Expenditure:Industrial-scale equipment, including tunnel ovens and automated packaging lines, represents a significant financial barrier to entry and capacity expansion.
- Regulatory Compliance Burden:Adhering to different food safety standards from the FDA, EFSA, and FSSAI increases operational complexity and compliance costs for manufacturers.
Strategic Opportunities
- Plant-Based Formulations:Developing expertise in producing plant-based and vegan baked goods opens a high-growth avenue aligned with shifting dietary preferences.
- Functional Ingredients:Incorporating ingredients like probiotics or added fiber into baked goods allows entry into the high-margin health and wellness food segment.
- Emerging Market Entry:Establishing facilities in Asia-Pacific nations caters to rising middle-class demand for packaged baked goods, representing a geographic expansion opportunity.
Industry Challenges
- Skilled Labor Scarcity:A shortage of technicians trained to operate and maintain automated baking systems and packaging machinery constrains production efficiency and uptime.
- Supply Chain Traceability:Maintaining traceability for certified ingredients like organic flour adds significant logistical complexity and cost, especially for gluten-free or non-GMO products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakery Contract Manufacturing Market |
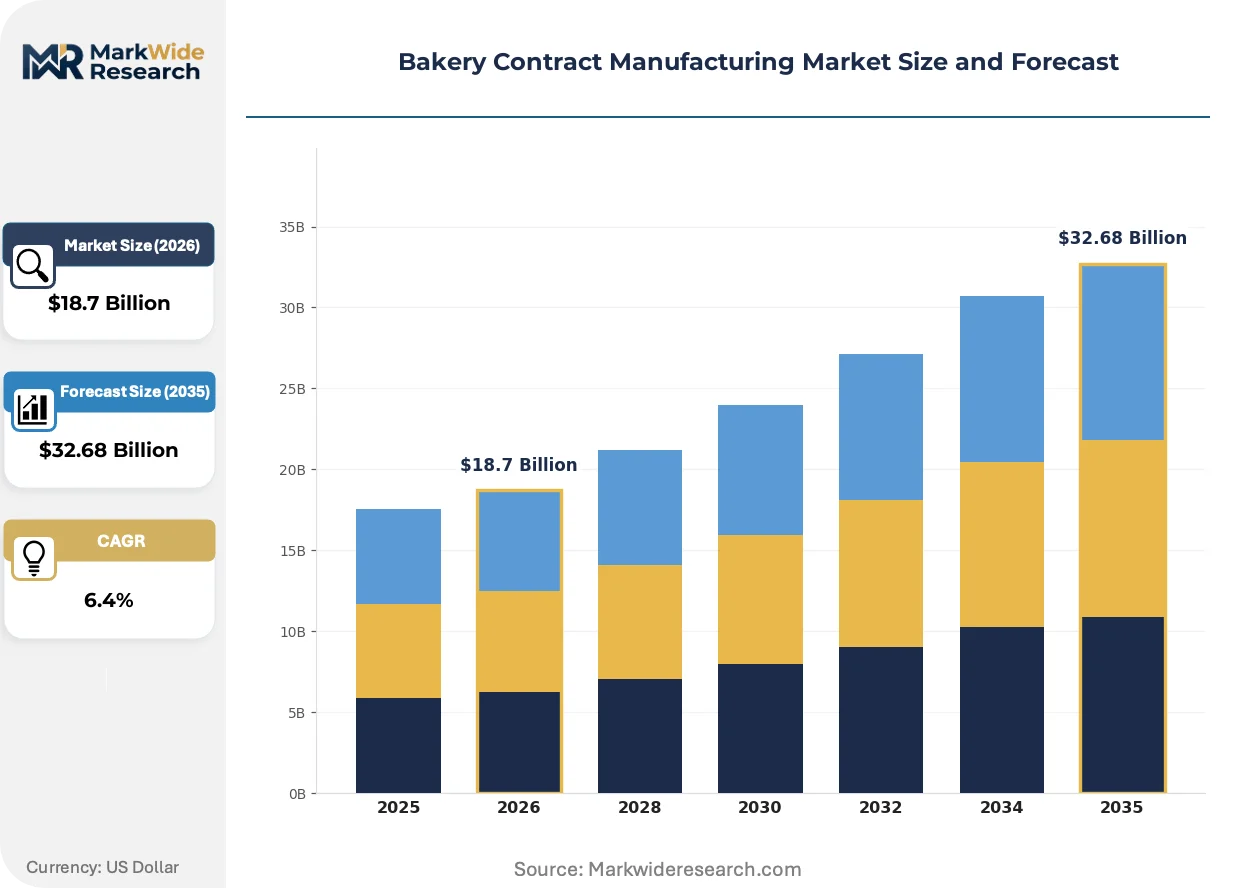
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Pastries, Cakes, Cookies End User: Retailers, Food Service, Wholesalers, Distributors Packaging Type: Boxed, Bagged, Tray, Bulk Quality Grade: Organic, Gluten-Free, Premium, Standard |
| Companies Covered | Flowers Foods, Inc., Pacmoore Products Inc., Dawn Food Products, Inc., TreeHouse Foods, Inc., Rich Products Corporation, Aryzta AG, General Mills, Inc., CSM Bakery Solutions, Hearthside Food Solutions LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakery Contract Manufacturing Market Strategic Shifts & Innovations
The industrialization of niche bakery production is accelerating, driven by technology that enables efficiency at scale. This allows contract manufacturers to meet CPG and retailer demand for specialized, high-variety product lines without sacrificing cost-effectiveness.
Digital twin technology creates virtual replicas of production lines, allowing simulation of process changes to optimize equipment settings. Large-scale manufacturers adopt this to reduce downtime during product changeovers. Originally for aerospace, this simulation capability is expanding into food processing to manage high-mix bakery production.
Implementation of the US FDA's FASTER Act designates sesame as a major food allergen requiring label declaration. This regulation compels manufacturers to re-evaluate production flows and sanitation to prevent cross-contamination. The bread category is most impacted, with many dedicating facilities to sesame-free production.
A behavioral shift is underway as food brands move from single-supplier contracts toward project-based procurement for new product launches. This model disrupts traditional volume commitments, favoring manufacturers with flexible platforms for shorter, innovative runs. This trend is prominent in the North American and European snack cake segments.
Bakery Contract Manufacturing Market Segmentation
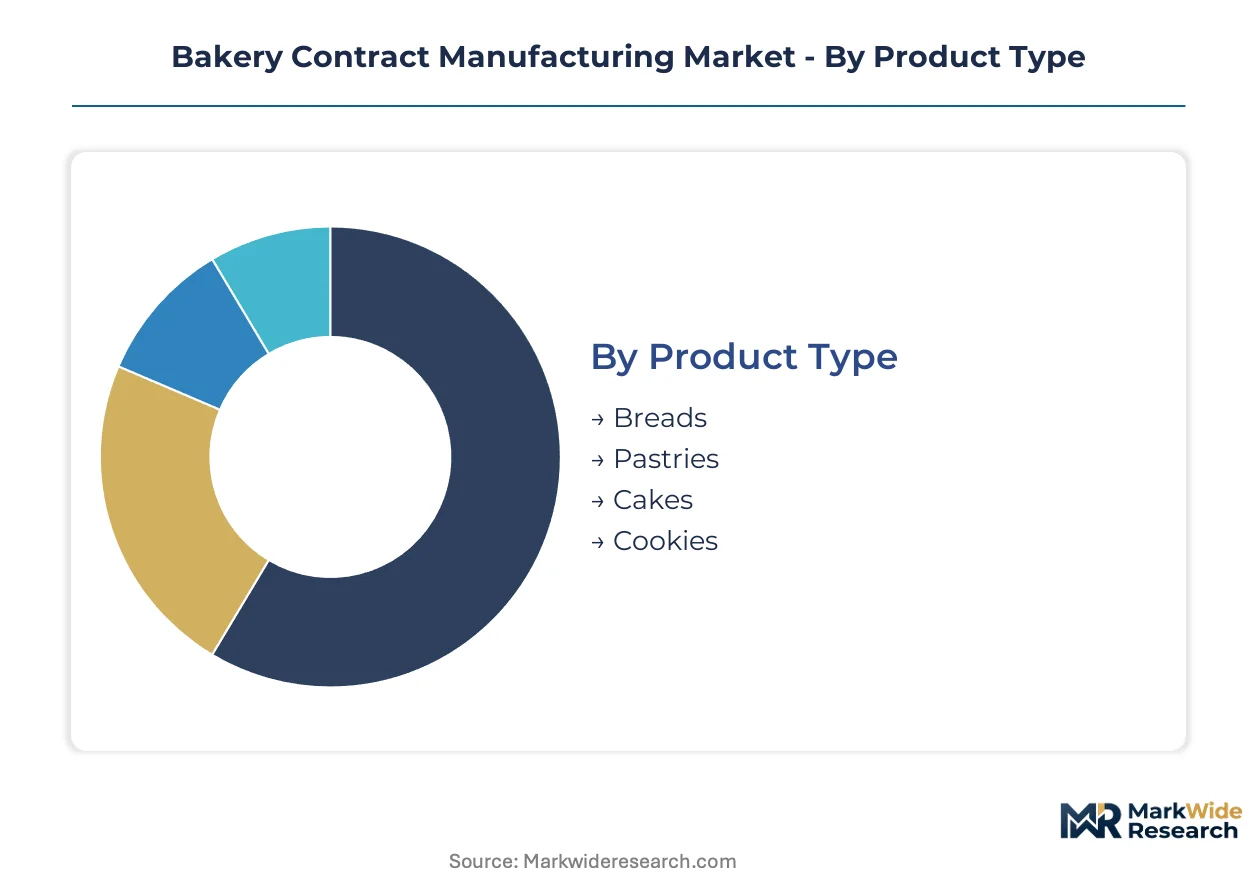
Segmentation analysis provides a granular understanding of the Bakery Contract Manufacturing Market, revealing the distinct characteristics and growth drivers across various product types, end-user categories, packaging formats, and quality grades. This detailed breakdown allows manufacturers to strategically align their production capabilities with specific market demands and regulatory requirements.
Product Type:
Supply concentration in bakery contract manufacturing often dictates the specialization of production lines, influencing the product types that can be efficiently scaled.
- Breads:This segment involves the industrial-scale production of various loaves, rolls, and flatbreads, frequently utilizing continuous mixing and high-capacity tunnel ovens. Demand concentrates in established European retail markets like Germany and the United Kingdom, driven by sustained private-label expansion.
- Cookies:Production requires precise ingredient dosing and controlled baking cycles to achieve consistent texture and flavor profiles, ranging from soft-baked to crisp varieties. North American consumer packaged goods (CPG) brands drive demand for innovative cookie formulations and diverse flavor offerings.
- Pastries:These products include croissants, Danish pastries, and other laminated dough items, often requiring specialized proofing and baking conditions.
- Cakes:Production in this segment ranges from individual portion sizes to large sheet cakes, with an emphasis on consistent texture and decorative application.
Today's leader: Breads. Tomorrow's challenger: Cookies.
End User:
Customer type segmentation reveals distinct procurement behaviors and volume requirements across the bakery contract manufacturing landscape.
- Retailers:This segment encompasses private-label baked goods and store-brand items, demanding stringent quality control and high-volume production capabilities. Demand concentrates in established European grocery chains, driven by their private-label proliferation strategies.
- Food Service:Catering to restaurants, cafes, and institutional clients, this segment involves specialized formulations and consistent product delivery for signature menu items. Restaurant chains outsource baking to ensure product consistency across their various locations.
- Wholesalers:These entities purchase baked goods in bulk for redistribution to smaller businesses or independent retailers.
- Distributors:These companies manage logistics and supply chain for baked goods, connecting manufacturers with diverse end-points.
The segment expanding most quickly is Food Service, driven by restaurant chains seeking consistent product quality.
Packaging Type:
Packaging type segmentation reflects specific product protection needs and consumer presentation requirements for various baked goods.
- Bagged:This involves flexible film packaging for items like bread, rolls, and cookies, often utilizing modified atmosphere packaging to extend shelf life. This packaging type is widely adopted for high-volume, cost-effective distribution of everyday bakery items.
- Boxed:Often used for cakes, pastries, and premium cookie assortments, this packaging provides structural integrity and aesthetic appeal for product presentation. Consumer demand for giftable and visually appealing baked goods drives this segment, particularly in seasonal markets.
- Tray:This packaging type supports delicate items like cupcakes or individual pastries, preventing damage during transport and display.
- Bulk:Large-format packaging for ingredients or semi-finished products destined for further processing or institutional use.
The dominant packaging format remains Bagged, while Boxed is gaining traction for its specialized applications in premium segments.
Quality Grade:
Margin profiles in bakery contract manufacturing are significantly differentiated by the quality grade of the products, reflecting varying input costs and production complexities.
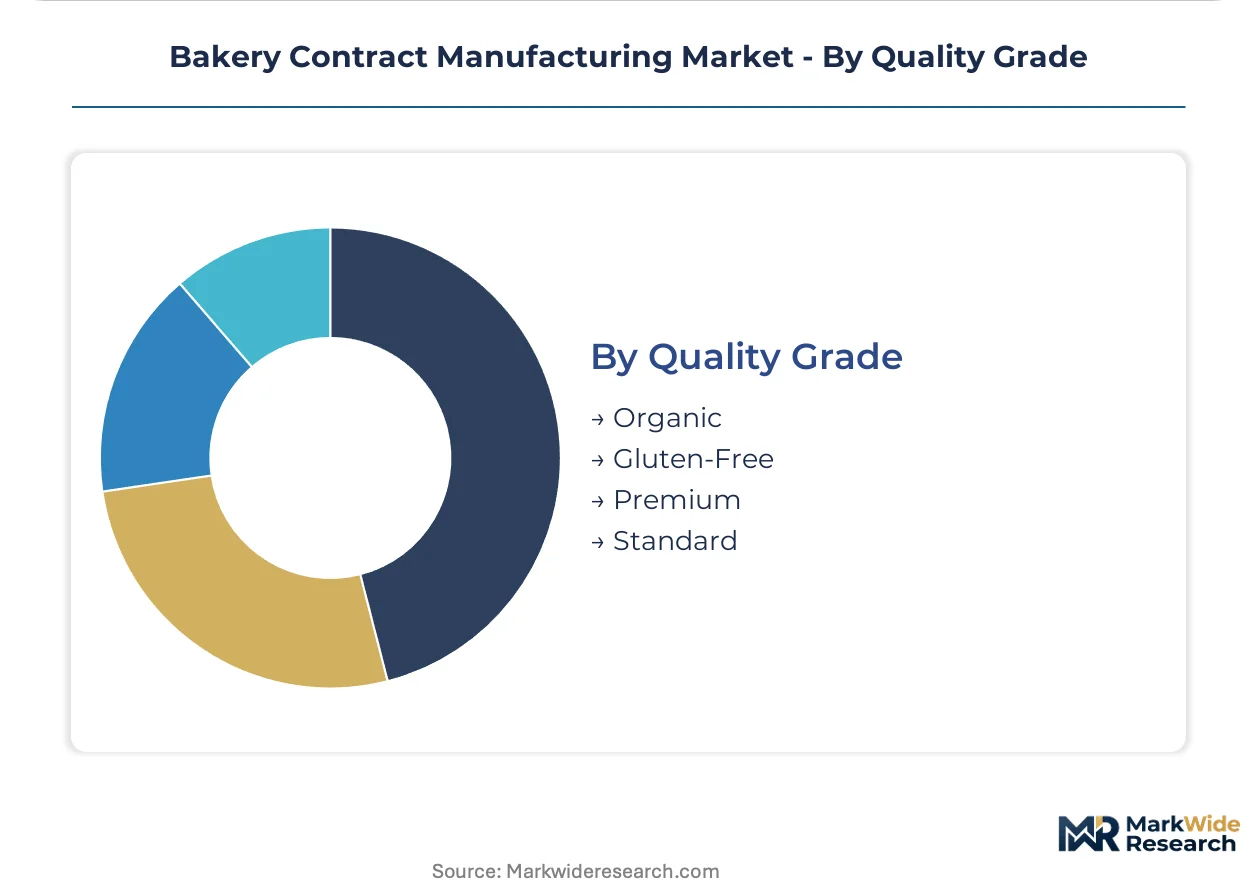
- Gluten-Free:This grade requires strict segregation of production lines and certified ingredient sourcing to prevent cross-contamination, adhering to regulatory standards like those from the US Food and Drug Administration (FDA). Consumer demand for specialty diet needs makes this segment one of the fastest-growing categories in the market.
- Organic:This involves sourcing certified organic ingredients and maintaining dedicated production processes to meet standards set by bodies like the US Department of Agriculture (USDA) or the European Food Safety Authority (EFSA). This segment commands higher price points due to specialized sourcing and certification requirements.
- Premium:These products often feature high-quality ingredients, artisanal techniques, and sophisticated flavor profiles, targeting discerning consumers.
- Standard:This grade represents conventional baked goods produced for mass markets, prioritizing cost-efficiency and consistent availability.
The segments with the steepest expansion trajectory are Organic and Gluten-Free, driven by evolving consumer preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The bakery contract manufacturing industry initially scaled in industrialized economies with established food processing infrastructure. These regions, particularly in Western Europe and North America, developed advanced capabilities for consistent, high-volume baked goods production for both retail and foodservice channels.
Germany
German retailers drive demand for private-label breads, emphasizing cost efficiency and consistent quality. The European Food Safety Authority (EFSA) regulations on allergen labeling shape production processes for contract manufacturers. Industrial bakeries in North Rhine-Westphalia focus on high-volume production for major grocery chains.
United Kingdom
The UK market shows strong demand for specialty baked goods, including gluten-free and organic options, driven by evolving consumer preferences. Food Standards Agency (FSA) guidelines on nutritional declarations influence product development and packaging. Large-scale facilities in the Midlands cater to both national retailers and foodservice clients.
United States
US consumer packaged goods (CPG) brands seek contract manufacturers for innovative cookie formulations and snack cake production. The US Food and Drug Administration (FDA) mandates for allergen declarations, especially the FASTER Act, compel specialized production lines. Major food manufacturing hubs in the Midwest specialize in large-scale, automated bakery operations.
Canada
Canadian consumers increasingly demand plant-based and functional baked goods, creating opportunities for specialized contract manufacturing. Health Canada regulations on ingredient transparency and health claims influence product development. Production facilities in Ontario serve both domestic retail and export markets, leveraging proximity to the US.
India
India's rising middle class fuels demand for packaged baked goods, presenting a significant geographic expansion opportunity for manufacturers. The Food Safety and Standards Authority of India (FSSAI) sets stringent standards for food safety and nutritional labeling. Processing zones near Mumbai and Delhi are attracting investment for new bakery production capacities.
Bakery Contract Manufacturing Market Key Industry Players
Premium-margin players sit above commodity-margin players across product complexity and specialization. The market exhibits a tiered structure, with large-scale integrators serving high-volume, standard product needs and specialized manufacturers focusing on niche categories. Companies pursue capacity expansion to meet growing demand and engage in strategic partnerships to access new markets or technologies.
At the scale-driven end, Hearthside Food Solutions LLC exemplifies large-scale, complex production runs for major retailers and CPG brands. Aryzta AG occupies a position as an international player, leveraging its global footprint to serve foodservice clients with specialized baked goods. Dawn Food Products, Inc. sits within the ingredient-focused archetype, differentiating through its strong focus on ingredient supply and product development support for its partners.
| Leading Market Players |
|---|
| Flowers Foods, Inc. |
| Pacmoore Products Inc. |
| Dawn Food Products, Inc. |
| TreeHouse Foods, Inc. |
| Rich Products Corporation |
| Aryzta AG |
| General Mills, Inc. |
| CSM Bakery Solutions |
| Hearthside Food Solutions LLC |
| Others |
Cost & Logistics Intelligence
Retailers' demand for private-label goods concentrates the dominant pricing model around long-term contract agreements. These contracts often feature pre-negotiated terms, but commodity price volatility remains a significant challenge for both manufacturers and buyers.
Pricing Analysis
Contract-based long-term pricing structures underpin most bakery contract manufacturing agreements. Price differentiation stems from specialized quality grades like gluten-free or organic certification, and the sheer volume scale of production runs. Pricing pressure arises from fluctuating commodity prices for core ingredients such as wheat and sugar, impacting manufacturer margins. Retailers, especially for private-label products, represent the most price-sensitive segment, while foodservice clients may tolerate higher costs for consistent, signature items.
Supply Chain Analysis
Skilled labor availability for operating automated baking systems is constrained in established manufacturing geographies like Germany and the United States Midwest. The supply chain draws heavily on raw materials such as wheat, sugar, and cocoa, with specialized flours for organic and gluten-free products. Commodity price volatility presents a structural supply chain risk, complicating long-term ingredient procurement. Distribution runs through direct channels to major retailers and foodservice operators, alongside bulk sales to wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market presents a geographic-arbitrage play, as manufacturing in regions like India offers lower operational costs compared to Western European markets, despite varying regulatory compliance burdens.
For Market Incumbents:
Anticipate continued pressure from stricter allergen labeling regulations like the US FDA's FASTER Act, necessitating investment in dedicated production lines. Consolidate market share by expanding capacity for high-volume standard baked goods in established European retail markets. Invest in R&D for plant-based formulations to counter shifting consumer dietary preferences. Secure long-term ingredient contracts to mitigate commodity price volatility risks.
For New Entrants and Emerging Players:
Ingredient suppliers can partner with contract manufacturers to co-develop functional baked goods, accessing the high-margin health and wellness segment. Target underpenetrated emerging markets like India, leveraging rising middle-class demand for packaged baked goods. Focus on project-based procurement for innovative, shorter runs in niche categories such as specialty snack cakes. Offer flexible production platforms to meet diverse CPG brand requirements.
For Investors and Strategic Acquirers:
Mid-sized contract manufacturers with specialized capabilities are the most active acquirers in this space, seeking to expand their certified gluten-free or organic production lines. Long-term viability rests on the sustained trend of food brands outsourcing complex manufacturing requirements. Target companies with strong compliance records and flexible manufacturing assets. The signal to watch for inflection is the widespread adoption of digital twin technology for production optimization.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Emerging Markets | Capture rising middle-class demand for packaged baked goods in Asia-Pacific nations. |
| Specialized Line Investment | Meet stringent allergen and quality grade requirements for gluten-free products. |
| Plant-Based Formulation R&D | Align production with shifting consumer dietary preferences towards vegan options. |
| Digital Twin Technology Adoption | Optimize production efficiency and reduce downtime during product changeovers. |
| Strategic Partnerships with Retailers | Secure stable, high-volume contracts for private-label baked goods. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative modeling — were reconciled to construct a comprehensive market view. Industry stakeholders included contract manufacturing executives, CPG brand managers, and retail procurement specialists. Secondary data sources comprised regulatory filings from the FDA and EFSA, company annual reports, and relevant trade association publications. This data informed both bottom-up and top-down triangulation efforts.
This data-stream reconciliation informed the analytical framework applied across the analysis window. Segmentation dimensions modeled included product type, end user, packaging type, and quality grade, alongside regional production capacity. Compound annual growth rates were derived from historical data analysis and projected market dynamics. Key forecast inputs included commodity ingredient prices and evolving consumer dietary trend shifts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unforeseen regulatory changes or significant economic downturns. Forecasts reflect assumptions documented through rigorous industry analysis and expert validation. Practitioners should monitor investment in automation, new market entries, and evolving consumer dietary preferences for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Asia-Pacific Frozen Bakery Market
Bakery Products
Global Rice Cakes Market
Bakery Products
Bread Crumbs Market
Bakery Products
United States Bread Market
Bakery Products
Bakery Cases Market
Bakery Products
Dough Whitener Market
Bakery Products
Ice Cream Market
Bakery Products
United States Cookies Market
Bakery Products
Gluten-Free Baking Mixes Market
Bakery Products
South America Ice Cream Market
Bakery Products
GCC Bakery Products Market
Bakery Products
Low-Carb Low-Fat Bread Market
Bakery Products
Premix Bread Flour Market
Bakery Products
Flour Mixes Market
Bakery Products
Organic Frozen Bakery Market
Bakery Products
Gluten-Free Bakery Market