
 Natural Taste Enhancers and Modifiers Market | 2026-2036
Natural Taste Enhancers and Modifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Taste Enhancers and Modifiers Market Foresight
Modular flavor systems is shifting how beverage companies and food manufacturers configure their procurement, moving from single-ingredient purchasing to bundled taste solutions that integrate sweetness, mouthfeel, and aroma in one platform. Givaudan leverages its integrated creation centers to anchor large-scale supply partnerships with multinational food manufacturers. Kerry Group plc competes through its taste and nutrition division, which specializes in clean-label modulation technologies for sodium and sugar reduction.
Natural taste enhancers and modifiers comprise botanical extracts, fermentation-derived compounds, and protein-based flavor potentiators formulated to amplify sweetness, umami, or salt perception without adding corresponding caloric or sodium loads. These substances typically achieve perceptual enhancement at concentrations below one percent by weight, functioning through receptor modulation rather than direct flavor contribution. Flavor extracts and natural sweeteners lead current value generation due to established supply chains and broad regulatory acceptance, while flavoring agents represent the fastest-expanding margin pool as precision fermentation and enzymatic modification unlock novel molecular entities. Seasoning blends occupy a mature position in food processing applications where standardization and cost efficiency dominate buyer criteria.
FDA oversight of natural flavor labeling substantiation and EU Green Deal sustainability reporting requirements through CSRD are reshaping how suppliers document sourcing and environmental claims across the Atlantic. EFSA evaluations of novel botanical extracts determine market access timelines for European food manufacturers seeking clean-label positioning. Stakeholders must monitor evolving definitions of natural status in multiple jurisdictions to anticipate reformulation obligations and procurement specification changes.
Market Dynamics
Modular flavor systems are consolidating procurement decisions across beverage and food manufacturing, bundling sweetness modulation, mouthfeel enhancement, and aroma delivery into single-platform contracts that compress supplier rosters and elevate technical partnership requirements.
Growth Catalysts
- EU Green Deal sustainability mandates:CSRD reporting obligations are accelerating clean-label reformulation across European food manufacturers, driving premium sourcing of botanical extracts with verifiable supply chain documentation.
- Precision fermentation advances:Enzymatic modification platforms are unlocking novel molecular entities for flavor potentiation, expanding the addressable toolkit for sodium and sugar reduction without sensory compromise.
- German plant-based product development:Concentrated R&D investment by food manufacturers in Germany is generating outsized demand for premium natural extracts that replicate traditional taste profiles in alternative protein matrices.
Market Restraints
- Botanical raw material volatility:Climate-sensitive harvests of vanilla, citrus, and spice botanicals create input cost instability that compresses margin predictability for extract-dependent formulations.
- EFSA novel extract evaluation timelines:Extended safety assessment protocols for new botanical submissions delay European market access by 18-36 months, freezing commercialization of innovative clean-label ingredients.
- Established synthetic flavor substitution:Cost-optimized processed food segments retain preference for artificial taste solutions that undercut natural modifier pricing by 40-60 percent at equivalent performance thresholds.
Strategic Opportunities
- Indian functional beverage expansion:FSSAI regulatory modernization and urban consumption upgrading are creating first-mover positioning for natural sweetness modulation in India's emerging clean-label soft drink segment.
- Protein-fermentation convergence:Integration of precision fermentation with alternative protein production enables co-location of taste modifier synthesis and base ingredient manufacturing, collapsing logistics costs.
- FDA natural claim guidance clarification:Anticipated substantiation frameworks for natural flavor labeling will reward early compliance investments with preferred supplier status to US beverage multinationals.
Industry Challenges
- Cross-functional formulation expertise scarcity:Shortage of scientists combining receptor biology, food chemistry, and regulatory navigation skills constrains speed-to-market for complex modulation platforms.
- Legacy ERP integration friction:Food manufacturers' entrenched procurement systems resist seamless adoption of bundled flavor platforms, requiring costly customization to enable consolidated supplier management.
- Multi-jurisdiction natural definition divergence:Inconsistent FDA, EFSA, and FSSAI standards for natural status force parallel documentation tracks and redundant substantiation expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Taste Enhancers and Modifiers Market |
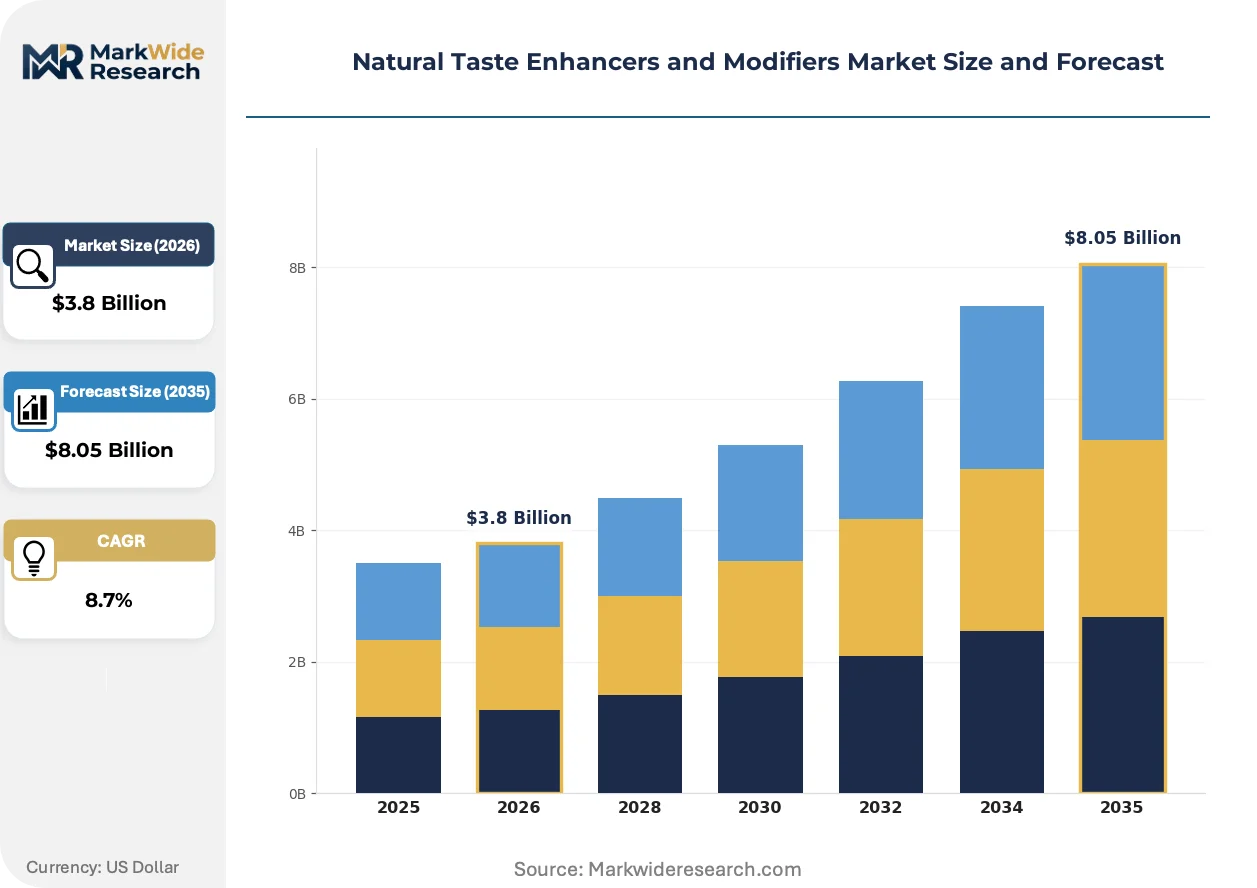
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavor Extracts, Natural Sweeteners, Seasoning Blends, Flavoring Agents Application: Food Processing, Beverage Industry, Bakery Products, Dairy Products End User: Food Manufacturers, Beverage Companies, Retail Consumers, Restaurants Distribution Channel: Online Retail, Hypermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Givaudan, International Flavors & Fragrances Inc., Symrise AG, DSM-Firmenich, Kerry Group plc, Firmenich SA, Sensient Technologies Corporation, Ingredion Incorporated, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Taste Enhancers and Modifiers Market Shifts & Advancements
Bioprocessing advances and regulatory precision are compressing development cycles for taste modulation, while procurement centralization among multinational food manufacturers is elevating technical partnership requirements over transactional ingredient supply.
Precision fermentation platforms for flavor molecule production are modularizing how taste modifiers reach formulation teams. Beverage companies in North America and Europe are adopting these biomanufactured inputs at accelerated qualification schedules. This technology is modularizing supply relationships by collapsing the traditional separation between ingredient production and flavor house compounding into integrated bioprocessing partnerships.
EFSA's evolving novel food evaluation protocols under EU Green Deal implementation timelines are extending safety documentation requirements for botanical extracts. Food manufacturers seeking clean-label positioning in European markets face reformulation delays or sourcing switches to grandfathered ingredients. Fermentation-derived modifiers with established safety profiles are capturing displaced demand from novel botanical submissions.
Buyer concentration among multinational beverage and food manufacturers is compressing supplier negotiation leverage. Tier-one manufacturers are consolidating procurement through integrated creation center partnerships that bundle technical service with ingredient supply. Germany and the Netherlands exhibit the most advanced procurement centralization, where three to four manufacturers control majority volume allocation decisions for natural taste modifiers.
Natural Taste Enhancers and Modifiers Market Segmentation
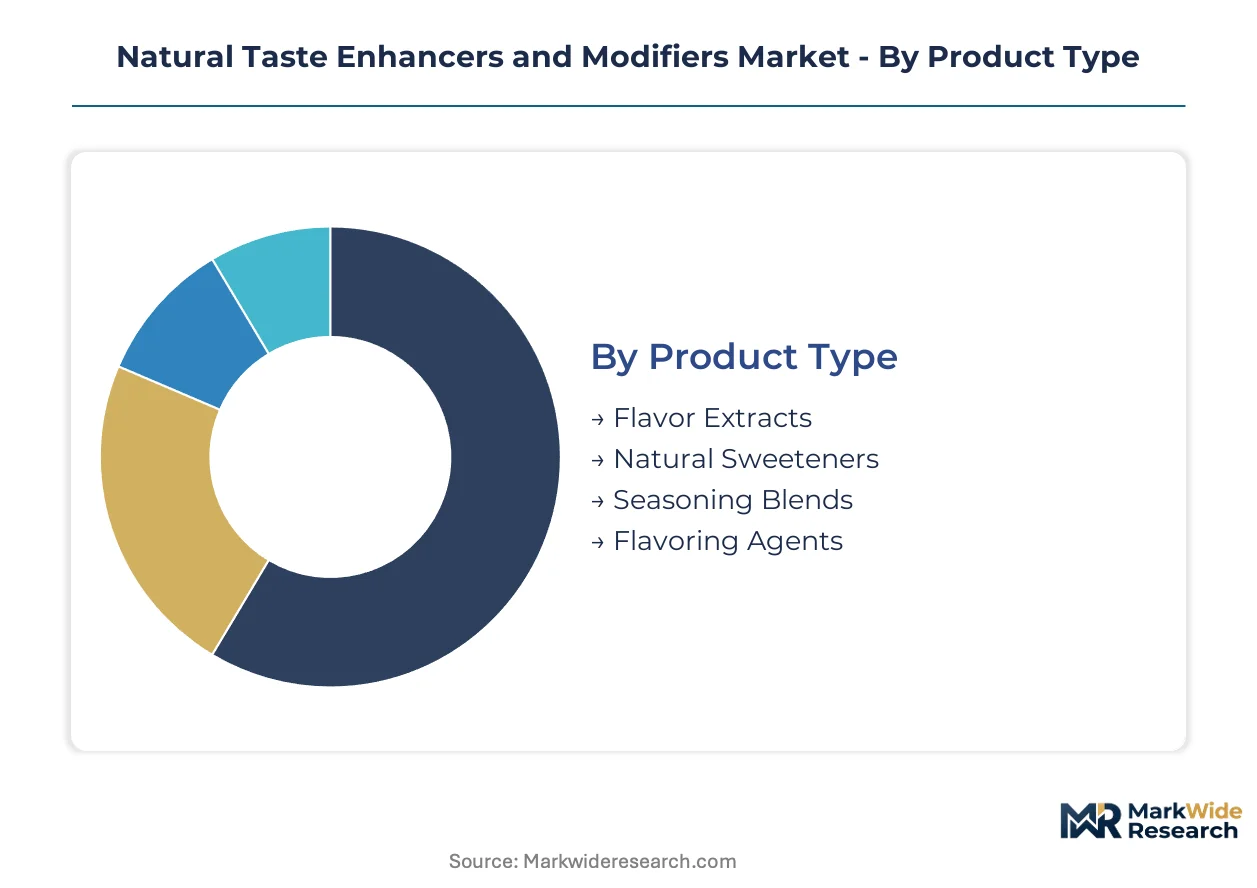
Segmentation in the natural taste enhancers market determines procurement pathways and margin structures. Product type dictates technical service intensity, while application shapes regulatory compliance requirements across food and beverage manufacturing.
Product Type:
Upgrade cycles in taste modifier procurement favor integrated platforms over single-ingredient sourcing, compressing supplier relationships and elevating technical partnership requirements.
- Flavor Extracts:Botanical-derived concentrates from vanilla, citrus, and spice sources deliver standardized aromatic profiles at sub-one-percent usage rates. Demand concentrates in Germany, where plant-based product development by food manufacturers drives premium extract sourcing with verifiable supply chain documentation under EU Green Deal mandates.
- Natural Sweeteners:Steviol glycosides, monk fruit extracts, and allulose formulations enable sugar reduction without caloric compromise. Beverage companies in North America and Europe are accelerating qualification schedules for these biomanufactured inputs, displacing synthetic alternatives in clean-label portfolios.
- Seasoning Blends:Standardized spice and herb combinations serve cost-optimized food processing segments where batch consistency dominates procurement criteria.
- Flavoring Agents:Precision fermentation-derived molecular entities unlock novel taste potentiation mechanisms.
Volume placements concentrate in Flavor Extracts; the faster expansion belongs to Flavoring Agents.
Application:
Cost tier differentiation separates premium clean-label positioning from commodity taste optimization across manufacturing segments.
- Food Processing:Industrial-scale seasoning and taste modulation for packaged goods manufacturers prioritizes batch-to-batch consistency and cost efficiency. EFSA novel extract evaluation timelines delay European market access by 18-36 months, freezing commercialization of innovative clean-label ingredients for reformulation projects.
- Beverage Industry:Sweetness modulation and mouthfeel enhancement for soft drink, functional drink, and alternative dairy applications demands rapid flavor system integration. FDA guidance on natural claims substantiation is tightening documentation requirements for US beverage multinationals sourcing botanical extracts.
- Bakery Products:Heat-stable taste modifiers that survive baking temperatures while maintaining flavor release profiles.
- Dairy Products:Fermentation-compatible enhancers for yogurt, cheese, and plant-based dairy alternatives.
Procurement scale peaks in Food Processing; margin expansion accelerates most quickly in Beverage Industry applications.
End User:
Customer type stratification separates multinational manufacturers with integrated creation center partnerships from fragmented foodservice operators.
- Food Manufacturers:Tier-one packaged goods producers consolidate procurement through bundled flavor platforms that integrate sweetness, mouthfeel, and aroma delivery. Legacy ERP integration friction constrains adoption speed, requiring costly customization to enable consolidated supplier management.
- Beverage Companies:Multinational soft drink and functional beverage producers drive clean-label reformulation with premium natural extract sourcing.
- Restaurants:Chain operators and contract foodservice providers seeking standardized taste profiles across distributed kitchen networks.
- Retail Consumers:Direct purchasers of natural seasoning and sweetener products through retail channels.
Contract value concentrates with Food Manufacturers; technical service intensity climbs fastest among Beverage Companies.
Distribution Channel:
Supply concentration patterns favor direct technical relationships over transactional retail pathways for complex modulation platforms.
- Direct Sales:Technical partnership models embedding flavor scientists within customer R&D facilities dominate high-value natural modifier procurement. Givaudan leverages integrated creation centers to anchor large-scale supply partnerships with multinational food manufacturers.
- Specialty Stores:Curated retail channels serving artisan food producers and premium restaurant operators seeking small-batch botanical extracts.
- Hypermarkets:Mass retail distribution for standardized seasoning blends and consumer-packaged natural sweeteners.
- Online Retail:Digital procurement platforms for sample qualification and small-volume ingredient sourcing.
Revenue concentration sits with Direct Sales; channel expansion proceeds most rapidly through Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Switzerland and the Netherlands, while consumption concentrates in Germany and the United States where beverage reformulation accelerates. This geographic split creates procurement friction as European extract suppliers navigate transatlantic logistics to serve North American clean-label demand.
United States
FDA guidance on natural claims substantiation drives documentation investments by beverage multinationals sourcing botanical extracts. The agency's evolving enforcement posture pressures flavor houses to verify supply chain integrity. Chicago and New Jersey host concentrated R&D facilities where integrated creation centers bundle technical service with ingredient procurement.
Germany
Plant-based product development by food manufacturers generates outsized demand for premium natural extracts in alternative protein matrices. EU Green Deal CSRD reporting obligations accelerate clean-label reformulation across packaged goods producers. Hamburg anchors North Sea logistics corridors for botanical raw material imports from African and Asian sourcing regions.
Switzerland
Precision fermentation platforms for flavor molecule production concentrate near Basel's pharmaceutical-industrial complex. Swissmedic oversight of novel food ingredients provides regulatory predictability absent from EFSA's extended evaluation timelines. Geneva-based flavor houses leverage neutral trade positioning to serve both EU and Middle Eastern markets.
India
FSSAI regulatory modernization enables first-mover positioning for natural sweetness modulation in emerging clean-label soft drinks. Urban consumption upgrading in Mumbai and Bangalore drives premium extract demand from domestic beverage startups. Gujarat's botanical processing infrastructure supplies standardized spice extracts to European flavor houses.
Netherlands
Rotterdam's port logistics dominate EU entry points for tropical botanical raw materials including vanilla and citrus extracts. EFSA novel food evaluation timelines delay market access for innovative ingredients, redirecting demand toward grandfathered fermentation-derived modifiers. Wageningen University's food science cluster anchors applied research partnerships between suppliers and multinational manufacturers.
Natural Taste Enhancers and Modifiers Market Competitive Landscape
The competitive structure tilts toward integrated flavor houses with captive biotechnology capabilities. Tier-one multinational food manufacturers consolidate procurement through bundled platform contracts that compress supplier rosters from dozens to single-digit preferred partners. Two archetypes dominate: precision fermentation specialists with modular biomanufacturing assets, and integrated creation centers embedding flavor scientists within customer R&D facilities. Competitive moves concentrate on strategic partnerships for co-development of clean-label modulation systems and backward integration into botanical raw material sourcing.
Among Swiss-dominant integrated players, Givaudan and DSM-Firmenich occupy positions exemplifying the creation-center archetype, anchoring large-scale supply relationships through technical co-location models. Kerry Group plc represents the taste-modulation specialization vector, with its corporate structure signaling nutrition-integrated positioning distinct from pure-play flavor houses. These three entities collectively illustrate how geographic clustering around Basel and Geneva correlates with regulatory predictability and biotechnology infrastructure access.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances Inc. |
| Symrise AG |
| DSM-Firmenich |
| Kerry Group plc |
| Firmenich SA |
| Sensient Technologies Corporation |
| Ingredion Incorporated |
| Cargill Incorporated |
| Others |
Supply & Pricing Matrix
Vanilla bean futures volatility cascades through botanical extract supply chains into three distinct pricing tiers: premium single-origin extracts with EU Green Deal traceability certification, standard blended concentrates for cost-sensitive food processors, and economy-grade fermentation-derived alternatives displacing botanical inputs.
Pricing Analysis
Margin tightening in standard-grade flavor extracts reflects climate-driven harvest instability across Madagascar and Indonesia sourcing regions. Contract-based long-term offtake dominates procurement between multinational beverage companies and integrated flavor houses, with price differentiation hinging on organic certification tier and volume scale commitments. Cost-down pressure on economy-tier synthetic alternatives accelerates because natural modifier suppliers undercut artificial pricing by narrowing the 40-60 percent historical gap. Food manufacturers exhibit highest price sensitivity due to batch-standardization requirements, while beverage companies absorb premium pricing for clean-label positioning.
Supply Chain Analysis
Specialized fermentation technician shortages in Basel and Rotterdam biomanufacturing clusters constrain precision-flavor output expansion. Supply concentrates in Switzerland, the Netherlands, and Germany, with raw material dependencies on Madagascan vanilla, Indonesian spice botanicals, and Indian citrus extracts. Single-source vulnerability pervades tropical botanical procurement, where climate shocks disrupt harvest predictability. Distribution runs through integrated creation centers embedding technical staff within customer R&D facilities, collapsing traditional ingredient-producer and flavor-house boundaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural taste enhancers and modifiers represent a vertical-integration race where backward control over precision fermentation capacity and tropical botanical sourcing separates consolidators from commodity suppliers.
For Market Incumbents: Extend captive biomanufacturing assets through modular fermentation platform investments in Swiss and Dutch clusters. Anchor supply security via long-term offtake agreements with Madagascan and Indonesian agricultural cooperatives. Precision fermentation specialists threaten extract-dependent incumbents by collapsing production costs for molecular-identical flavor compounds.
For New Entrants and Emerging Players: Begin with white-space positioning in India's FSSAI-modernizing functional beverage segment, where domestic clean-label demand outpaces multinational supplier presence. Target precision-fermented flavoring agents for alternative protein matrices in German plant-based product development pipelines. Co-development partnerships with Wageningen University's food science cluster offer technical credibility acceleration.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap botanical extract houses with grandfathered EFSA safety profiles in Netherlands and Germany, where extended novel food evaluation timelines freeze competitor market access. Monitor EFSA novel extract approval velocity as inflection indicator; accelerated clearance protocols would erode competitive moats of established ingredient suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Fermentation | Captive biomanufacturing collapses flavor molecule production costs for sugar-reduction platforms. |
| Long-term Botanical Sourcing Agreements | Direct agricultural partnerships in Madagascar secure vanilla supply chain documentation for EU CSRD compliance. |
| Integrated Creation Center Expansion | Technical co-location in Chicago and Hamburg embeds flavor scientists within multinational beverage R&D facilities. |
| Novel Extract Regulatory Pre-submission | Early EFSA engagement compresses 18-36 month safety evaluation timelines for botanical innovation pipelines. |
| Alternative Protein Matrix Co-development | Partnerships with German plant-based food manufacturers unlock premium extract demand for taste replication. |
Research Methodology
Trade databases, EFSA novel food submission registries, and FDA guidance documentation formed the secondary backbone for supply chain and regulatory mapping. Primary interviews with flavor house R&D directors, beverage company procurement leads, botanical extract importers, and precision fermentation platform engineers validated demand assumptions and pricing dynamics. Bottom-up volume modeling across product type and application segments triangulated against top-down macroeconomic drivers.
Bottom-up segment sizing by flavor extract, natural sweetener, seasoning blend, and flavoring agent categories anchored the analytical framework across the projection horizon. Modeled dimensions included clean-label certification tier, end-use application intensity, and regional regulatory cluster alignment. CAGRs derived from historical trajectory analysis adjusted for precision fermentation penetration rates and EU Green Deal compliance acceleration.
Underlying measurement precision varies by segment; fermentation-derived flavoring agents carry tighter precision than novel botanical extracts pending EFSA evaluation. Forecasts reflect documented assumptions regarding regulatory clearance timelines and climate stability in tropical sourcing regions. Material deviation in EFSA novel food approval velocity or Madagascan harvest yields warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Cake Softener Market
Food Enhancers and Additives
North America Vinegar Market
Food Enhancers and Additives
Japan Water Enhancer Market
Food Enhancers and Additives
Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Feed Palatability Enhancers and Modifiers Market
Food Enhancers and Additives
Emulsifier Enhancers Market
Food Enhancers and Additives
Isomalt Market
Food Enhancers and Additives
Fortified Salts Market
Food Enhancers and Additives
Used Cooking Oil Market
Food Enhancers and Additives
United Kingdom Interesterified Fats Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
Resveratrol Market
Food Enhancers and Additives
Africa Water Enhancer Market
Food Enhancers and Additives
Browning Enhancers Market
Food Enhancers and Additives
Emulsifier Alternatives Market
Food Enhancers and Additives
North America Water Enhancer Market