
 Food Emulsifiers Market | 2026-2036
Food Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Food Emulsifiers Market Analysis
Modular emulsifier blending is broadening buyer choice as food manufacturers seek tailored hydrophilic-lipophilic balance solutions rather than one-size-fits-all additives. Cargill Incorporated leverages its integrated oilseed processing network to sustain cost-competitive lecithin supply chains. Kerry Group plc anchors its position through specialized bakery application labs in Europe and North America. Palsgaard differentiates via in-house production of polyglycerol polyricinoleate for chocolate confectionery.
Food emulsifiers are surface-active agents with amphiphilic molecular structures—typically possessing a hydrophilic head and lipophilic tail—that reduce interfacial tension between immiscible phases such as oil and water, with hydrophilic-lipophilic balance values generally ranging from 3 to 16 depending on functional target. Their primary commercial purpose centers on stabilizing emulsions, controlling crystallization, and extending shelf life in processed foods. Lecithin dominates volume flows due to its plant-derived positioning and broad regulatory acceptance, while sorbitan esters command premium positioning in fat-based confectionery where thermal stability requirements are stringent. Mono- and diglycerides remain the workhorse segment across bakery and dairy applications, though plant-based source claims are reshaping procurement criteria for this category.
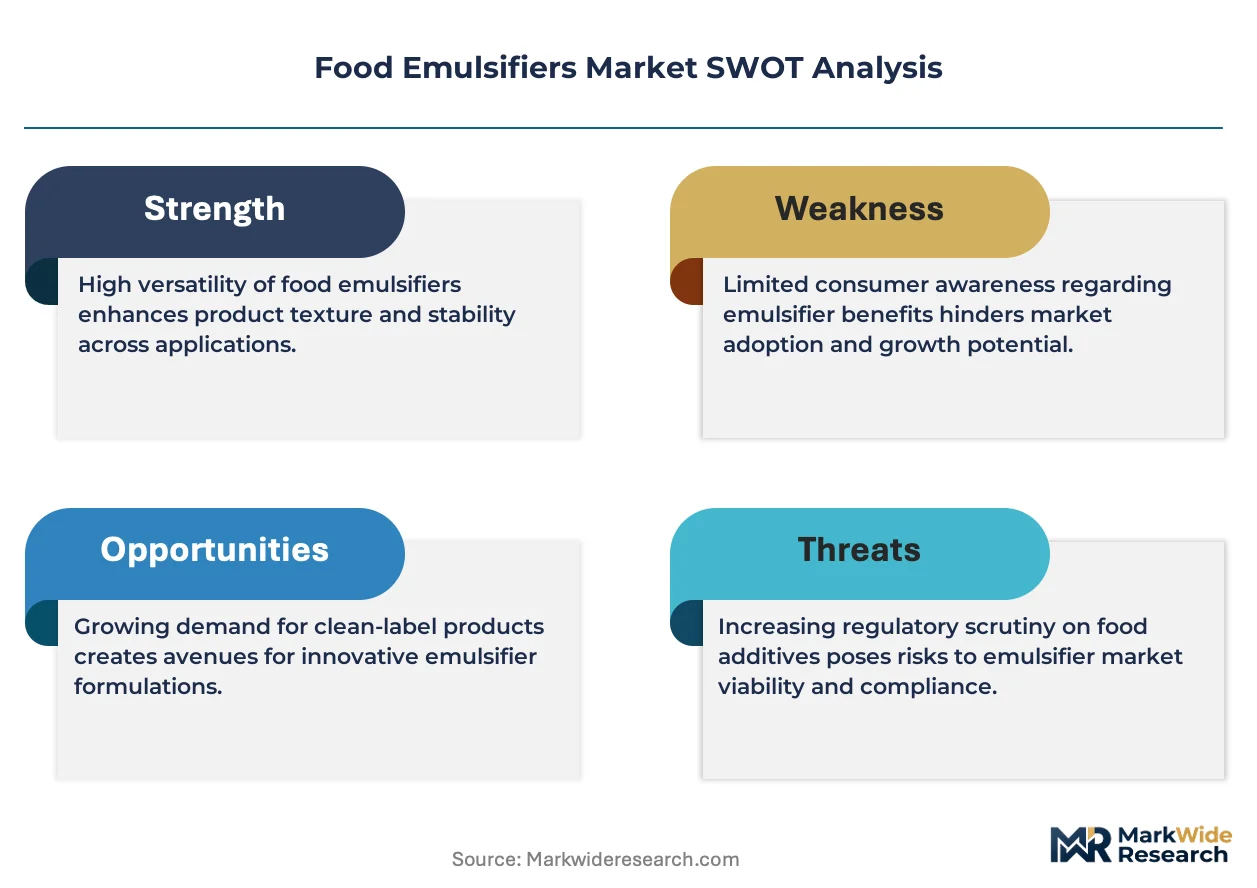
EFSA maintains active re-evaluation programs for food additives including emulsifiers under Regulation (EC) No 1333/2008, with recent opinion shifts on certain polyethylene glycol derivatives prompting reformulation mandates. FDA's GRAS notification framework and FSMA preventive controls collectively shape market access requirements for emulsifier suppliers targeting the United States. BIS certification requirements for food-grade additives in India add another compliance layer for multinational ingredient portfolios. Stakeholders must monitor accelerating regulatory divergence between jurisdictions as clean-label pressures interact with divergent safety assessment methodologies.
Market Dynamics
Clean-label reformulation mandates from EFSA are forcing European food manufacturers to accelerate emulsifier substitution cycles, compressing ingredient validation timelines and redrawing procurement specifications across bakery and confectionery verticals.
Growth Catalysts
- EFSA Re-evaluation Mandates:Accelerated safety reviews under Regulation (EC) No 1333/2008 are pulling replacement demand for synthetic emulsifiers in processed foods.
- Plant-Based Lecithin Sourcing:Oilseed processing capacity expansion in sunflower and rapeseed variants is broadening label-friendly supply chains for dairy alternatives.
- Industrial Bakery Clusters:Concentrated manufacturing zones in Germany and the Netherlands are anchoring regional procurement volumes for mono- and diglyceride blends.
Market Restraints
- Phospholipid Feedstock Volatility:Soybean and sunflower oil price swings directly compress lecithin margin structures for European compounders.
- Specialized PGPR Supply Concentration:In-house production capabilities for polyglycerol polyricinoleate remain concentrated among a handful of integrated chocolate ingredient suppliers.
- Clean-Label Performance Gap:Natural emulsifiers frequently fail to match synthetic alternatives on thermal stability in high-fat confectionery applications.
Strategic Opportunities
- Modular HLB Blending Services:Tailored hydrophilic-lipophilic balance formulations are opening premium service contracts with mid-sized European bakery manufacturers.
- FSSAI Compliance Pathways:India's BIS certification requirements for food-grade additives create first-mover advantages for suppliers establishing local technical documentation.
- Precision Fermentation Lipids:Microbial-derived phospholipids are converging with sustainability claims to unlock novel positioning in plant-based dairy.
Industry Challenges
- Application-Specific Reformulation Cycles:Each clean-label switch demands 12-18 months of stability testing, sensory validation, and regulatory dossier preparation.
- Cross-Jurisdictional Labeling Divergence:EFSA's evolving additive classifications frequently misalign with FDA GRAS determinations, complicating multinational product platform strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Emulsifiers Market |
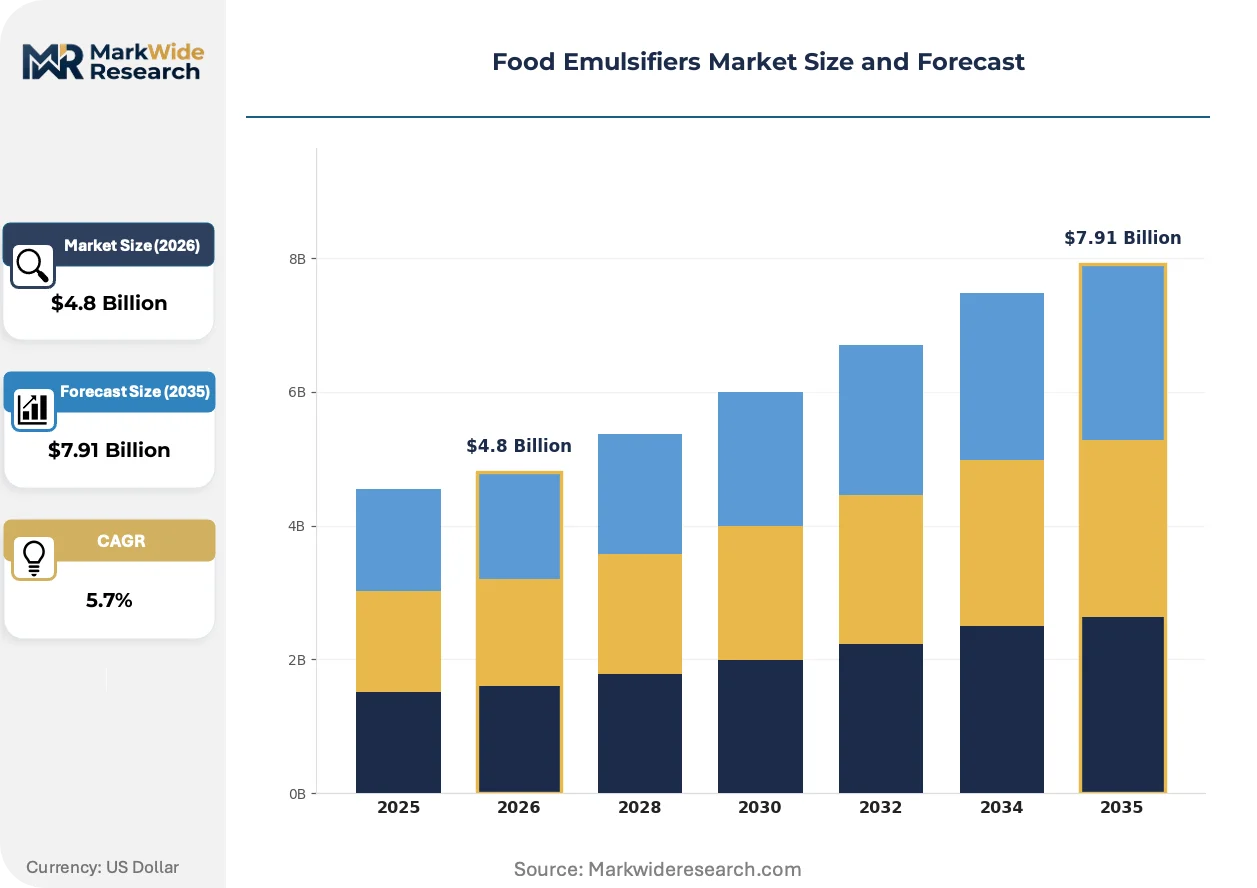
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lecithin, Mono- and Diglycerides, Sorbitan Esters, Polysorbates Application: Bakery, Dairy Products, Sauces, Beverages Source: Plant-based, Animal-based, Synthetic, Others End User: Food Manufacturers, Catering Services, Retailers, Confectioners |
| Companies Covered | ADM, Cargill Incorporated, International Flavors & Fragrances, Ingredion Incorporated, Kerry Group plc, Corbion, BASF SE, Tate & Lyle, Palsgaard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Emulsifiers Market Emerging Trajectories
Emulsifier functionality is decoupling from commodity chemical supply toward engineered biological systems and precision-blended solutions, restructuring how food manufacturers source, specify, and validate their ingredient portfolios.
Enzymatic interesterification is converging with structured lipid design to enable position-specific fatty acid placement in mono- and diglyceride production. European margarine and shortening manufacturers are adopting these enzymatic routes at pilot scale. The technology is compressing reliance on chemical glycerolysis and opening cleaner-process claims for retail-facing brands.
EFSA's tightened exposure assessments for polyethylene glycol derivatives are disqualifying several established emulsifiers from renewal approvals under the 2008 additives regulation. Reformulation mandates are cascading through frozen dough and whipped topping segments. German and French manufacturers are accelerating substitution timelines to maintain distribution access.
Ingredient specification is migrating from individual additive procurement toward pre-validated emulsifier systems bundled with technical support. Mid-sized North American bakeries are displacing spot purchasing with annual formulation service agreements. This bundling is most visible in clean-label bread and viennoiserie applications where stability failure carries high batch cost.
Food Emulsifiers Market Segmentation
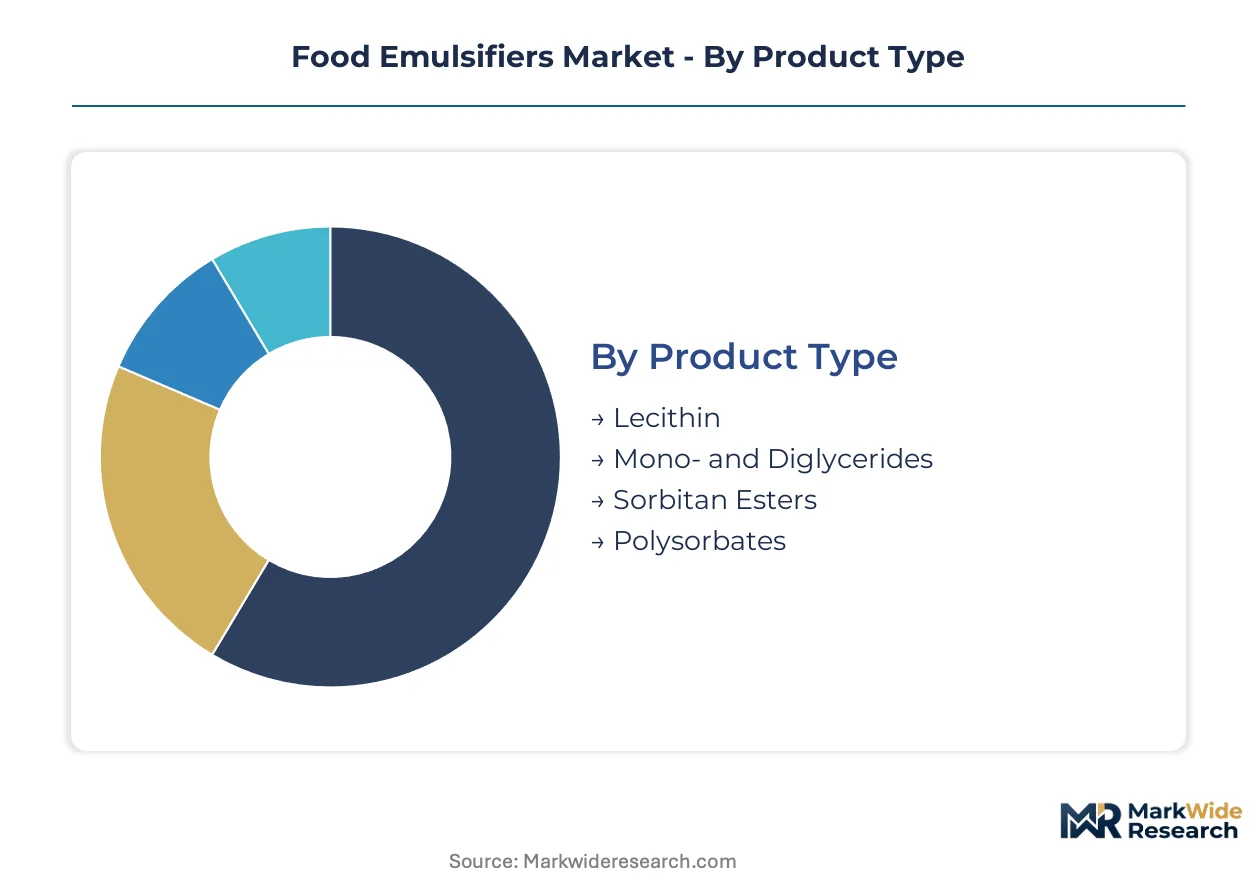
Emulsifier specification patterns diverge sharply across product chemistry, application stress conditions, and end-user scale requirements. Procurement decisions in this market hinge on matching hydrophilic-lipophilic balance values to specific process constraints rather than selecting generic additive categories.
Product Type:
Supply concentration varies dramatically by molecular complexity, with phospholipid extraction capacity dominating volume economics while specialized ester chemistry commands premium positioning in narrow application windows.
- Lecithin:Phospholipid mixtures extracted from soybean, sunflower, or rapeseed oil processing streams anchor global volume flows. German and Dutch oilseed crushing clusters sustain cost-competitive supply chains for dairy alternative manufacturers seeking label-friendly positioning.
- Mono- and Diglycerides:Glycerolysis-derived emulsifiers with HLB values spanning 3 to 8 serve as the workhorse stabilizers across industrial bakery operations. Concentrated manufacturing zones in Germany generate procurement pull from frozen dough and margarine compounders requiring consistent crystallization control.
- Sorbitan Esters:Fatty acid esters of sorbitol deliver thermal stability in high-fat confectionery where synthetic alternatives face EFSA scrutiny.
- Polysorbates:Ethoxylated derivatives extend functionality into beverage emulsions and aerated dessert systems.
Today's leader: Lecithin. Tomorrow's challenger: Mono- and Diglycerides.
Application:
Process temperature regimes and shelf stability requirements create distinct specification tiers that reshape ingredient selection logic across food manufacturing verticals.
- Bakery:Bread, viennoiserie, and frozen dough applications demand emulsifiers that retard starch retrogradation and extend crumb softness over distribution cycles. Clean-label reformulation mandates from EFSA are compressing validation timelines for mono- and diglyceride alternatives in French and German industrial bakeries.
- Dairy Products:Ice cream, processed cheese, and dairy alternative formulations require precise fat globule stabilization and whipping properties. Plant-based lecithin sourcing is climbing fastest here as oat and almond milk processors seek non-GMO label claims.
- Sauces:Mayonnaise and dressing emulsions depend on high-HLB systems for oil-in-water stability under refrigerated distribution.
- Beverages:Clouding agents and flavor emulsions in soft drinks and nutritional beverages demand polysorbate functionality for long-term dispersion stability.
Bakery commands current procurement volumes. Dairy alternatives present the steepest expansion trajectory.
Source:
Raw material provenance has migrated from technical specification to primary purchasing criterion as clean-label positioning reshapes buyer decision frameworks.
- Plant-based:Sunflower and rapeseed lecithin variants command procurement preference in European markets where non-GMO and allergen-free claims drive retail differentiation. Oilseed processing capacity expansion in Eastern Europe is broadening supply security for manufacturers.
- Animal-based:Egg yolk phospholipids retain niche positioning in premium mayonnaise and hollandaise applications where flavor authenticity outweighs cost considerations.
- Synthetic:Petrochemical-derived emulsifiers face accelerating substitution pressure under EFSA re-evaluation programs.
- Others:Microbial and enzymatically modified phospholipids represent emerging supply categories.
Plant-based sourcing dominates current specifications. Precision fermentation lipids emerge as the technical challenger.
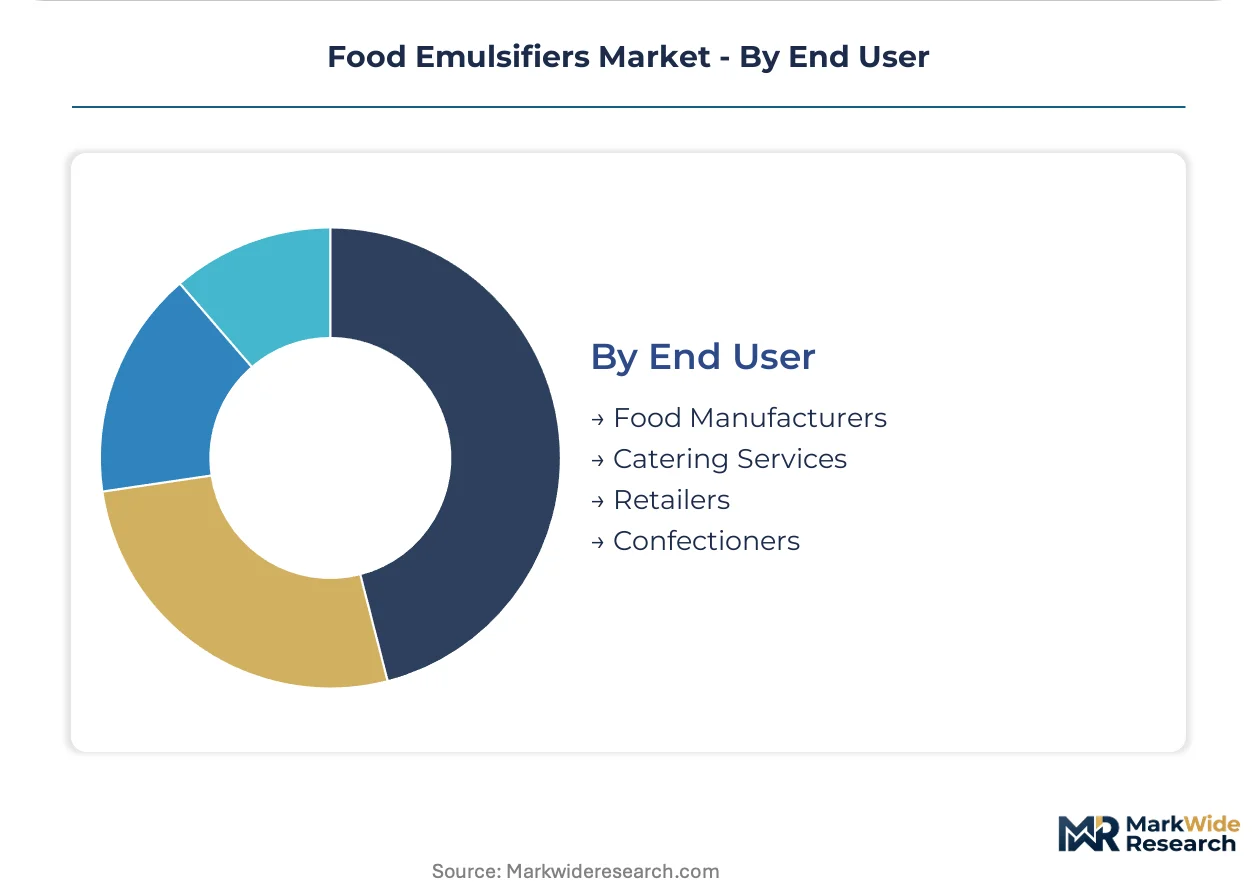
End User:
Scale and technical capability gaps fragment procurement patterns, with large compounders demanding bundled formulation services while smaller operators rely on distributor spot purchasing.
- Food Manufacturers:Industrial bakeries and dairy processors in Germany and the Netherlands anchor regional emulsifier procurement through annual volume contracts with technical support provisions. Modular HLB blending services are displacing spot purchasing among mid-sized European operators.
- Catering Services:Institutional foodservice channels prioritize cost-stable supply over functional sophistication.
- Retailers:Private-label bakery and dairy specifications increasingly mandate plant-derived emulsifier systems.
- Confectioners:Chocolate manufacturers depend on specialized PGPR supply for viscosity control in coating applications.
Food manufacturers control current procurement gravity. Confectioners present concentrated premium opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial emulsifier production first scaled in European oilseed processing corridors during the mid-twentieth century. Germany and the Netherlands built the foundational crushing and refining infrastructure that still anchors global phospholipid supply chains today.
Germany
Industrial bakery clusters in Lower Saxony and North Rhine-Westphalia drive concentrated procurement of mono- and diglyceride blends. EFSA's additive re-evaluation programs under Regulation (EC) No 1333/2008 are compressing reformulation timelines for frozen dough manufacturers. Hamburg's port infrastructure facilitates sunflower and rapeseed lecithin imports from Eastern European oilseed processors.
United States
Plant-based dairy alternatives in California and the Midwest are accelerating non-GMO lecithin sourcing from domestic sunflower processors. FDA's GRAS notification framework and FSMA preventive controls shape market access requirements for emulsifier suppliers. Chicago's food ingredient distribution hub connects mid-sized bakeries to modular HLB blending services.
China
Expanding confectionery production in the Yangtze River Delta and Pearl River Delta is pulling specialized emulsifier demand for chocolate viscosity control. SAMR's evolving food additive standards are converging with international safety benchmarks. Shanghai's technical service centers support local bakery manufacturers adopting enzymatic interesterification routes.
India
Dairy alternative processors in Maharashtra and Gujarat are scaling plant-based lecithin procurement for oat and almond milk formulations. FSSAI's BIS certification requirements for food-grade additives create compliance pathways for multinational suppliers. Mumbai's ingredient trading networks are consolidating procurement for mid-sized food manufacturers.
Netherlands
Oilseed crushing capacity in Rotterdam's port zone sustains cost-competitive lecithin supply chains for European dairy alternative manufacturers. REACH registration requirements for chemical additives influence emulsifier import specifications. Wageningen's food research cluster supports clean-label reformulation validation for bakery applications.
Food Emulsifiers Market Vendor Landscape
The competitive structure tilts toward integrated agribusiness conglomerates with captive oilseed processing assets. These players leverage upstream control over phospholipid feedstocks to sustain margin structures against commodity volatility. Three archetypes dominate: multinational ingredient conglomerates with broad portfolio diversification, specialized emulsifier houses with application-specific technical services, and regional oilseed processors with lecithin extraction capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing sunflower and rapeseed sourcing agreements to support clean-label positioning.
Among the integrated conglomerates, Cargill Incorporated and ADM exemplify the upstream-anchored archetype through their oilseed processing networks. Kerry Group plc occupies a position within the specialized technical services tier, while Palsgaard represents the application-focused specialist model with concentrated expertise in confectionery systems. BASF SE and Tate & Lyle sit within the diversified chemical and ingredient conglomerate category, leveraging broad regulatory dossier capabilities across multiple jurisdictions.
| Leading Market Players |
|---|
| ADM |
| Cargill Incorporated |
| International Flavors & Fragrances |
| Ingredion Incorporated |
| Kerry Group plc |
| Corbion |
| BASF SE |
| Tate & Lyle |
| Palsgaard |
| Others |
Supply Flow & Price Mechanics
EFSA's clean-label additive re-evaluation under Regulation (EC) No 1333/2008 gates qualified supply for European food manufacturers and simultaneously unlocks premium-tier pricing access for plant-derived emulsifier systems that meet reformulation mandates. Buyers without validated natural alternatives face compressed procurement timelines and elevated input costs as synthetic options lose regulatory standing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified plant-based lecithin from conventional soy-derived grades and synthetic mono-diglyceride commodity offerings. Price differentiation hinges on non-GMO certification tier and volume scale, with German industrial bakeries commanding favorable contract terms through annual offtake commitments. Cost compression in synthetic emulsifiers is intensifying because EFSA disqualification is shrinking addressable demand. Mid-sized European confectioners exhibit highest price sensitivity due to reformulation validation burdens, while multinational dairy alternative processors absorb premiums for sunflower and rapeseed provenance claims.
Supply Chain Analysis
India's BIS certification requirements for food-grade additives and FSSAI technical documentation mandates are reshaping sourcing decisions for multinational suppliers establishing local production footprints. Phospholipid feedstock extraction concentrates in Germany, the Netherlands, and India, drawing from soybean, sunflower, and rapeseed oil processing streams. Supply chain risk centers on single-source vulnerability for specialized polyglycerol polyricinoleate production in chocolate confectionery applications. Distribution runs through Rotterdam's port infrastructure for European dairy alternative manufacturers and Chicago's ingredient trading hub for North American mid-sized bakeries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EFSA's accelerated safety review timelines under the 2008 additives regulation continuously generate replacement demand cycles and reshape competitive positioning.
For Market Incumbents: Anchor backward integration into Eastern European sunflower and rapeseed crushing capacity to secure non-GMO feedstock streams ahead of clean-label procurement mandates. Defend margin structures by expanding modular HLB blending service contracts with German and Dutch industrial bakeries facing compressed reformulation timelines. The threat of precision fermentation lipids from biotechnology entrants demands accelerated technical validation partnerships with Wageningen's food research cluster. For New Entrants and Emerging Players: Precision fermentation-derived phospholipids offer a technology-first wedge into plant-based dairy alternative formulations where thermal stability requirements outmatch conventional lecithin performance. Target India's Maharashtra and Gujarat dairy processor clusters where FSSAI compliance pathways remain underdeveloped and first-mover documentation advantages persist. A go-to-market angle bundling BIS certification support with technical formulation services addresses the capability gap among regional compounders. For Investors and Strategic Acquirers: Roll-up economics work for specialized emulsifier houses with confectionery application expertise because PGPR production capabilities remain concentrated among a handful of integrated chocolate ingredient suppliers. The five-to-ten year viability window favors acquisition of European mid-cap technical service providers with validated clean-label portfolios. Watch EFSA's exposure assessment methodology evolution as the inflection signal for substitution cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill and ADM leverage captive sunflower and rapeseed processing to secure non-GMO lecithin supply chains. |
| Modular HLB Blending Service Expansion | Kerry Group's European bakery application labs displace spot purchasing with annual formulation agreements. |
| Precision Fermentation Lipid Development | Microbial-derived phospholipids converge with sustainability claims to unlock novel positioning in oat milk processing. |
| FSSAI Technical Documentation Investment | Multinational suppliers establishing Mumbai service centers capture first-mover advantages in India's dairy alternative sector. |
| Enzymatic Interesterification Scale-Up | European margarine manufacturers adopt cleaner-process routes to displace chemical glycerolysis for retail-facing brands. |
Methodological Framework
Direct dialogue with oilseed processing plant managers, food manufacturer procurement leads, bakery application R&D directors, and FSSAI regulatory consultants grounded the qualitative assessment, combined with secondary validation from EFSA additive re-evaluation opinions, FDA GRAS notification filings, customs and trade flow data, and SEC 10-K disclosures from integrated agribusiness conglomerates. Bottom-up emulsifier volume estimates triangulated against top-down food manufacturing output projections.
Market sizing outputs reflect a demand-side analytical framework spanning product chemistry, application stress conditions, and end-user scale requirements across the projection horizon. Segmentation modeling incorporated hydrophilic-lipophilic balance value tiers, source provenance categories, and regional regulatory cluster variations. CAGRs derived from regression analysis against food manufacturing value-added growth and substitution cycle velocity assumptions, with lecithin price elasticity and enzymatic process adoption curves as industry-specific forecast inputs.
The model holds under stable EFSA re-evaluation timelines and continued clean-label procurement mandate expansion; deviation in regulatory acceleration or feedstock commodity volatility would shift volume trajectories. Forecasts reflect documented assumptions about reformulation cycle duration and technical validation success rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Glycerin Market
Food Additives and Ingredients
Food Grade Calcium Lactate Market
Food Additives and Ingredients
Biscuit Shortening Flakes Market
Food Additives and Ingredients
Egg Stabilizer Market
Food Additives and Ingredients
Flour Whiteners Market
Food Additives and Ingredients
Pet Food Emulsifier Market
Food Additives and Ingredients
France Food Emulsifiers Market
Food Additives and Ingredients
North America Food Anti Caking Agents Market
Food Additives and Ingredients
Australia Food Colorants Market
Food Additives and Ingredients
Germany Food Acidulants Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Australia Food Enzymes Market
Food Additives and Ingredients
Gum Hydrocolloid Market
Food Additives and Ingredients
Cream of Tartar Market
Food Additives and Ingredients
Clean Label Food Ingredient Market
Food Additives and Ingredients
Gelatin Films Market