
 China Food Acidulants Market | 2026-2036
China Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
China Food Acidulants Market Outlook
Precision fermentation and enzymatic conversion is reconfiguring acidulant manufacturing economics across China. Cargill, Incorporated leverages its corn-processing infrastructure in Jilin province to sustain captive citric acid supply chains. Henan Tianguan Enterprise Group anchors central China's lactic acid capacity through starch-based fermentation platforms. Corbion NV differentiates with bio-based preservation-grade acidulants targeting clean-label beverage contracts.
Food acidulants comprise organic acids—citric, malic, lactic, and tartaric—typically produced via submerged fermentation of carbohydrate feedstocks, with purity grades ranging from food-additive to pharmaceutical specification. These compounds regulate pH, enhance flavor profiles, and extend shelf stability in processed foods and beverages. Citric acid dominates volume flows given its ubiquity in soft drinks and sauce formulations, while malic acid captures premium positioning in sugar-reduced beverage applications where tartness modulation replaces sweetness. Powder and granular forms command logistics advantages for large-scale food manufacturers, though liquid acidulants gain traction among beverage producers seeking direct-injection processing efficiency.
SAMR enforces GB 1886 food additive standards that mandate residual solvent limits and microbial specifications, compelling domestic producers to upgrade refining equipment. NMPA alignment with CODEX Alimentarius frameworks shapes export qualification protocols for acidulants bound for Southeast Asian and Middle Eastern markets. BIS-equivalent conformity assessment pressures from India's import regulations further filter supplier eligibility. Stakeholders must monitor fermentation yield improvements and regulatory reciprocity negotiations to secure positioning ahead of capacity expansions in Shandong and Jiangsu provinces.
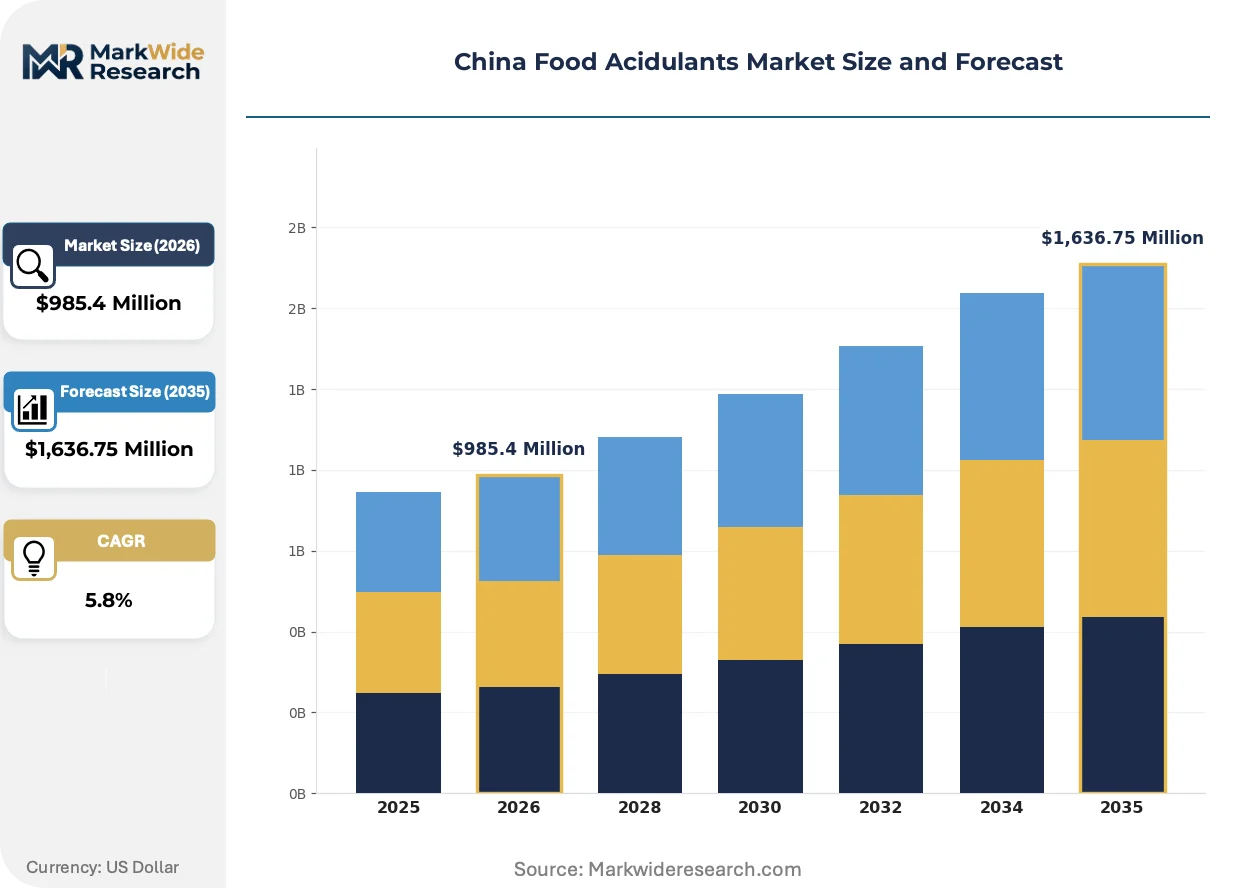
Market Dynamics
Fermentation yield improvements are compressing unit economics for citric acid manufacturers while SAMR purity mandates force capital-intensive refining upgrades across Shandong and Jiangsu production bases.
Growth Catalysts
- Carbonated beverage expansion:Functional drink producers in Guangdong province are scaling acidulant volumes for pH-stabilized formulations targeting shelf-life extension.
- GB 1886 alignment:SAMR enforcement of residual solvent limits is filtering subscale producers and consolidating qualified supplier pools for export-bound manufacturers.
- Coastal manufacturing clustering:Shanghai port logistics and bonded zone infrastructure concentrate acidulant demand from sauce and condiment processors.
Market Restraints
- Corn feedstock volatility:Starch price fluctuations in Jilin province transmit directly to fermentation cost structures, squeezing margin stability for citric acid producers.
- Single-source supply risk:Concentration of pharmaceutical-grade malic acid capacity among three domestic producers creates bottleneck exposure for clean-label beverage contracts.
- CODEX reciprocity gaps:NMPA alignment delays with Southeast Asian import protocols block qualification pathways for medium-purity acidulant grades.
Strategic Opportunities
- Central China penetration:Henan province starch processing infrastructure supports lactic acid capacity expansion for dairy and bakery applications.
- Dual carbon compliance:MEE carbon intensity benchmarks favor fermentation-based citric acid over petrochemical alternatives in procurement scoring.
- Direct-injection liquid formats:Beverage bottlers are bypassing powder handling for liquid acidulant delivery systems that reduce processing steps.
Industry Challenges
- Pharmaceutical-grade certification timelines:NMPA GMP compliance for acidulant excipients requires 18-24 month validation cycles that delay contract qualification.
- Legacy equipment retrofit costs:Membrane filtration and crystallization upgrades to meet microbial specifications demand capex outlays that strain mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Food Acidulants Market |
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $1,636.75 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Malic Acid, Lactic Acid, Tartaric Acid Application: Beverages, Confectionery, Dairy Products, Bakery End User: Food Manufacturers, Beverage Producers, Retail Chains, Food Service Form: Liquid, Powder, Granular, Crystalline |
| Companies Covered | COFCO, Henan Tianguan Enterprise Group, RP International Limited, Nanjing Xiangshengtai Industry Co Ltd., Tate & Lyle PLC, Corbion NV, Galactic SA/NV, Cargill, Incorporated, Archer Daniels Midland Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Food Acidulants Market Strategic Shifts
Precision fermentation platforms are reconfiguring acidulant manufacturing economics while regulatory tightening and procurement model evolution reshape competitive positioning across China's food additive supply base.
Enzymatic conversion technology is hybridizing with traditional submerged fermentation to boost citric acid yields from carbohydrate feedstocks. Beverage manufacturers in Zhejiang province are qualifying these bio-processed grades for clean-label product lines. The technology is hybridizing cost structures between established chemical producers and emerging biotech specialists, compressing historical margin premiums on fermentation-derived acidulants.
SAMR's phased implementation of GB 1886.235-2016 updates is tightening residual protein limits in lactic acid specifications. Domestic producers are investing in chromatographic purification to maintain food-additive licensing. Pharmaceutical-grade acidulant segments face the steepest compliance burden, with NMPA cross-referencing EMA impurity profiles for export qualification.
Consolidated procurement through coastal beverage conglomerates is displacing fragmented distributor networks. Direct supplier contracts now govern acidulant volumes for carbonated drink producers in Guangdong. This concentration is most visible in Shanghai's bonded logistics zones, where tier-one manufacturers negotiate annual supply agreements bypassing regional traders.
China Food Acidulants Market Segmentation
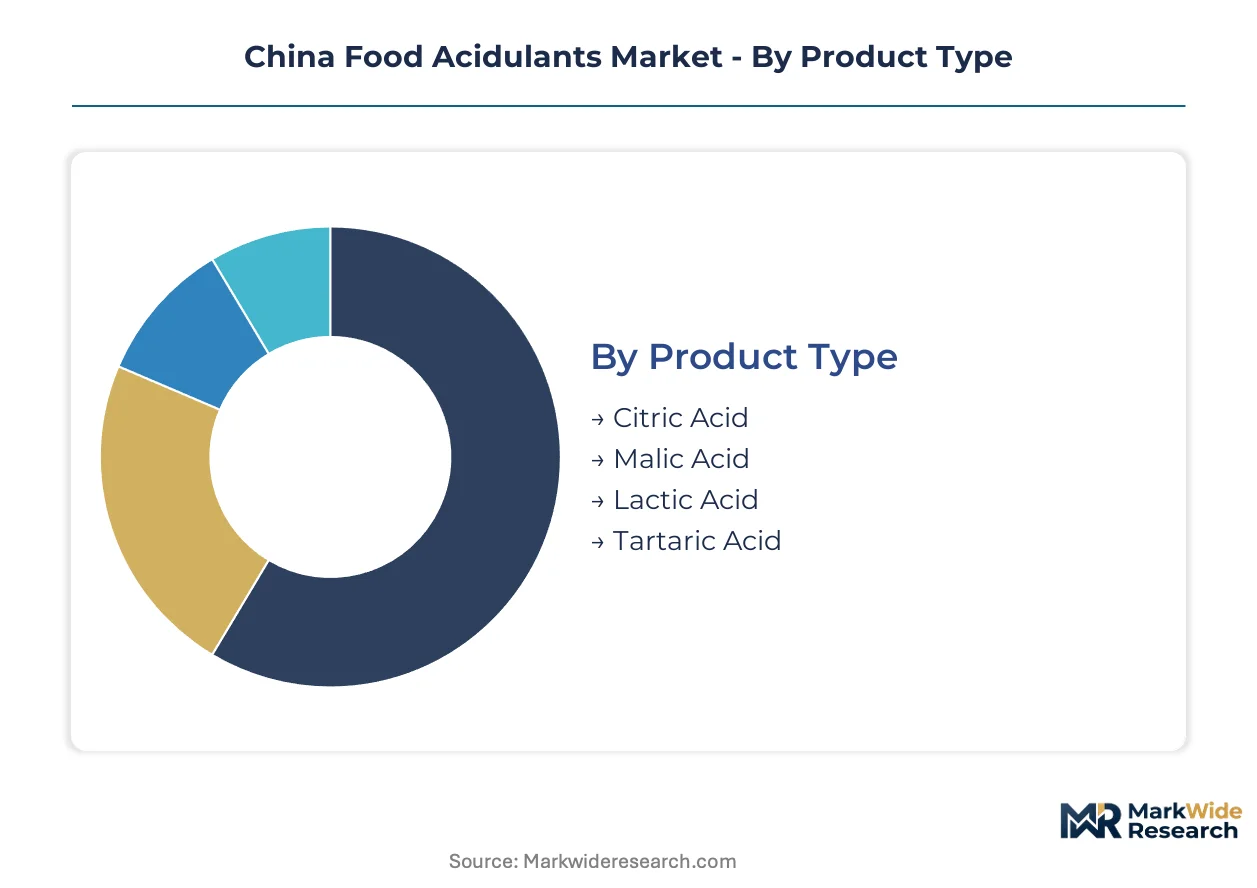
Acidulant procurement patterns diverge sharply across product chemistry, application intensity, and delivery format. Manufacturers in Shanghai and Guangdong calibrate specifications to GB 1886 purity tiers while optimizing logistics around coastal bonded infrastructure.
Product Type:
After-sales technical support intensity varies dramatically by acidulant chemistry, with fermentation-derived grades demanding sustained yield optimization consulting.
- Citric Acid:Submerged fermentation of corn starch yields this tricarboxylic acid in food-additive and pharmaceutical grades. Beverage bottlers in Guangdong province consume bulk volumes for carbonated drink pH stabilization, with SAMR residual solvent limits forcing chromatographic purification upgrades among Shandong suppliers.
- Malic Acid:This dicarboxylic acid delivers sharper tartness profiles at lower usage rates than citric alternatives. Sugar-reduced beverage formulators in Zhejiang province specify malic acid for clean-label tartness modulation, though pharmaceutical-grade capacity bottlenecks among three domestic producers create contract qualification delays.
- Lactic Acid:Starch-based fermentation platforms in Henan province supply this alpha-hydroxy acid for dairy and bakery applications.
- Tartaric Acid:Grape-derived production dominates this stereoisomeric acid for confectionery and wine adjunct applications.
Citric acid holds the largest share; momentum sits with malic acid.
Application:
Cost tier stratification separates commodity acidulant volumes from premium preservation-grade contracts.
- Beverages:Carbonated and functional drink producers anchor acidulant demand through direct-injection liquid systems. Shanghai port logistics clusters concentrate procurement for pH-stabilized formulations targeting extended shelf stability.
- Confectionery:Hard candy and gummy manufacturers utilize acidulants for flavor enhancement and crystallization control.
- Dairy Products:Fermented milk and processed cheese applications specify lactic acid for pH adjustment and microbial stabilization.
- Bakery:Leavening acidulants and mold inhibitors drive tartaric and citric acid incorporation in industrial bread production.
Beverages command the dominant volume position; bakery applications are climbing the fastest.
End User:
Customer type determines specification stringency, with pharmaceutical-grade contracts imposing 18-24 month NMPA validation cycles.
- Food Manufacturers:Sauce and condiment processors in coastal manufacturing clusters specify powder and granular acidulants for dry-blend compatibility.
- Beverage Producers:Guangdong carbonated drink conglomerates negotiate annual supply agreements bypassing regional distributor networks.
- Retail Chains:Private-label food and beverage programs drive medium-purity acidulant procurement with CODEX-aligned specifications.
- Food Service:Institutional catering and quick-service restaurant supply chains utilize liquid acidulant formats for direct-injection processing efficiency.
Food manufacturers represent the anchor demand base; beverage producers are gaining share fastest.
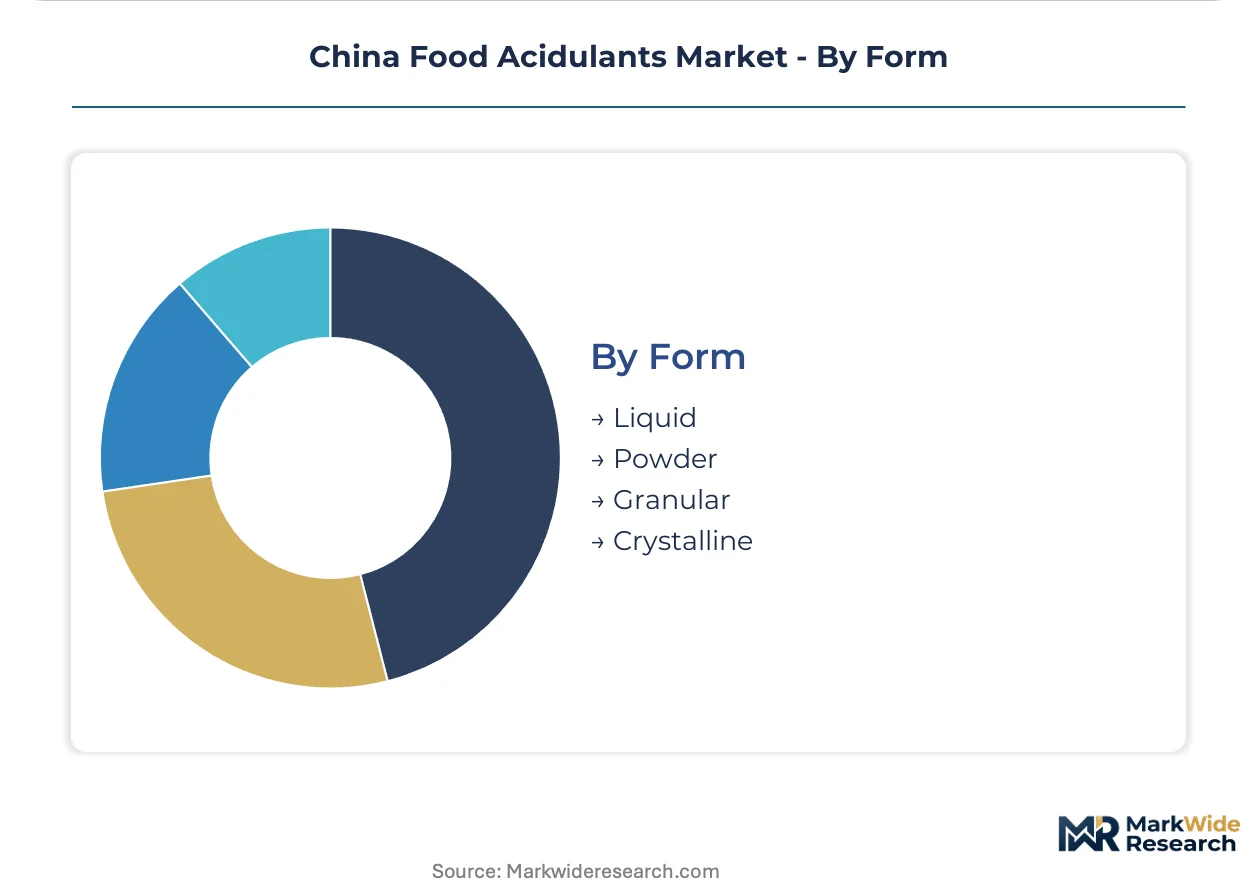
Form:
Supply concentration in crystalline and powder processing shapes logistics economics for long-haul distribution.
- Liquid:Direct-injection delivery systems eliminate powder handling steps for high-volume beverage bottlers. Guangdong producers are qualifying liquid citric acid for continuous processing lines.
- Powder:Dry-blend compatibility dominates sauce and seasoning manufacturer specifications across Jiangsu production bases.
- Granular:Anti-caking formulations support bulk storage for industrial food manufacturers with automated dosing equipment.
- Crystalline:Pharmaceutical-grade purification yields this high-purity format for excipient and preservation applications.
Powder forms retain the largest share; liquid formats show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports fermentation-derived acidulants through Shanghai port corridors to Southeast Asian beverage manufacturers and Middle Eastern food processors. These trade flows concentrate procurement decisions in coastal manufacturing clusters where GB standard compliance intersects with CODEX-aligned export protocols.
Shanghai and Yangtze River Delta
Beverage conglomerates in Shanghai's bonded zones negotiate direct supplier contracts for liquid citric acid injection systems. SAMR enforces GB 1886 residual solvent limits that filter subscale producers from qualified supplier pools. Zhejiang province sugar-reduced beverage formulators specify malic acid for clean-label tartness modulation.
Guangdong and Pearl River Delta
Carbonated drink producers anchor acidulant demand through annual supply agreements bypassing regional distributor networks. MEE dual carbon benchmarks favor fermentation-based citric acid over petrochemical alternatives in procurement scoring. Shenzhen and Guangzhou logistics hubs concentrate pH-stabilized formulation volumes for shelf-life extension applications.
Shandong Peninsula
Corn starch fermentation infrastructure in Jilin province feeds citric acid capacity with direct cost transmission from feedstock volatility. NMPA pharmaceutical-grade certification timelines extend 18-24 months for acidulant excipients bound for export markets. Qingdao port facilities handle bulk crystalline acidulant shipments to Southeast Asian confectionery manufacturers.
Jiangsu Province
Sauce and condiment processors specify powder acidulants for dry-blend compatibility in industrial food production. SAMR microbial specifications compel membrane filtration and crystallization equipment upgrades among mid-tier producers. Nanjing and Suzhou manufacturing bases supply granular formats to automated dosing operations across coastal food manufacturers.
Henan Province
Central China starch processing infrastructure supports lactic acid expansion for dairy and bakery applications. Henan Tianguan Enterprise Group anchors regional fermentation platform capacity through backward integration into agricultural feedstocks. Zhengzhou logistics corridors distribute alpha-hydroxy acid volumes to processed cheese and fermented milk producers.
China Food Acidulants Market Competitive Environment
On the supply side, the industry is consolidating around fermentation specialists with captive agricultural feedstock access and refining capabilities meeting pharmaceutical-grade specifications. The vendor base stratifies into three tiers: multinational agribusiness conglomerates with corn-processing infrastructure, domestic fermentation platforms with provincial starch supply chains, and regional traders displaced by direct procurement contracts. Dominant competitive moves include backward integration into carbohydrate feedstock cultivation and chromatographic purification capacity additions for GB 1886 compliance.
Within the multinational tier, Cargill, Incorporated and Tate & Lyle PLC exemplify agribusiness archetypes leveraging global corn-processing networks for acidulant supply security. Among domestic fermentation specialists, Henan Tianguan Enterprise Group occupies a position representing central China's starch-based platform expansion. Corbion NV sits within the bio-based preservation-grade segment targeting clean-label beverage contract qualification.
| Leading Market Players |
|---|
| COFCO |
| Henan Tianguan Enterprise Group |
| RP International Limited |
| Nanjing Xiangshengtai Industry Co Ltd. |
| Tate & Lyle PLC |
| Corbion NV |
| Galactic SA/NV |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Others |
Value Chain & Pricing Dynamics
Shandong Peninsula fermentation clusters anchor citric acid capacity that transmits feedstock volatility directly into downstream contract negotiations. Corn starch price swings from Jilin province suppliers compress margin buffers for acidulant producers serving Guangdong beverage conglomerates, forcing annual renegotiation cycles that favor buyers with volume scale.
Pricing Analysis
Fermentation-generation pricing gaps separate legacy submerged-process citric acid from precision-enzymatic conversion grades now qualifying for clean-label beverage contracts. Three-tier pricing structure across pharmaceutical-grade, food-additive, and industrial specification levels tracks GB 1886 purity tier compliance costs. Pricing pressure stems from chromatographic purification capex requirements for SAMR residual solvent limits. Small-scale sauce manufacturers in Jiangsu province exhibit highest price sensitivity, while pharmaceutical excipient buyers absorb premium tiers for NMPA certification security.
Supply Chain Analysis
Contract-manufacturing concentration rests with Henan Tianguan Enterprise Group and Cargill's Jilin corn-processing infrastructure for captive citric acid supply. Geographic supply concentrates in China, with secondary fermentation capacity in Thailand and Indonesia serving Southeast Asian beverage markets. Raw material dependencies center on corn starch from Jilin, molasses substrates from Guangxi, and chromatographic resins for purification upgrades. Single-source vulnerability runs through pharmaceutical-grade malic acid capacity concentrated among three domestic producers. Distribution runs through Shanghai bonded logistics zones for direct supplier contracts with carbonated drink manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's food acidulants sector sits in early-cycle expansion as clean-label beverage adoption accelerates fermentation-platform qualification for pH-stabilized formulations.
For Market Incumbents: Build regulatory certification moats through NMPA pharmaceutical-grade validation cycles that extend 18-24 months and filter subscale competitors. Anchor backward integration into Jilin corn starch supply chains to buffer feedstock volatility transmission. Expand chromatographic purification capacity in Shandong to capture GB 1886 compliance premiums from export-bound manufacturers facing CODEX reciprocity gaps. For New Entrants and Emerging Players: Pursue white-space positioning in liquid acidulant direct-injection systems for Guangdong beverage bottlers seeking processing efficiency gains. Target central China penetration through Henan province lactic acid capacity for dairy and bakery applications underserved by coastal suppliers. Qualify enzymatic conversion technology platforms with Zhejiang sugar-reduced beverage formulators as a clean-label differentiation angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation specialists with captive agricultural feedstock access and pharmaceutical-grade refining capabilities. Long-term viability over a 5-10 year horizon rests on dual carbon compliance credentials and SAMR regulatory alignment depth. Acquisition focus should center on central China starch-based platforms with unexploited lactic acid expansion potential. Monitor NMPA-CODEX reciprocity negotiation progress as the critical inflection signal for medium-purity acidulant export qualification pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Starch Supply | Cargill's Jilin infrastructure demonstrates captive feedstock control buffers margin volatility for citric acid output. |
| Chromatographic Purification Capacity Addition | Shandong producers meeting GB 1886 residual solvent limits capture pharmaceutical-grade contract premiums from NMPA-aligned buyers. |
| Liquid Acidulant Format Expansion | Guangdong bottlers adopting direct-injection systems reduce powder handling steps and secure annual supply agreement concentration. |
| Dual Carbon Compliance Certification | MEE carbon intensity benchmarks favor fermentation-based citric acid in procurement scoring for export-bound manufacturers. |
| Central China Lactic Acid Capacity Buildout | Henan Tianguan leverages regional starch processing infrastructure to supply dairy and bakery applications with alpha-hydroxy acid volumes. |
Study Parameters
The analysis maps citric acid, malic acid, lactic acid, and tartaric acid sub-sectors, each validated through fermentation platform operators, beverage formulation technologists, and SAMR regulatory consultants. Primary interviews with plant managers at Shandong and Jiangsu production bases, procurement leads at Guangdong carbonated drink conglomerates, and distribution channel partners in Shanghai bonded zones combined with secondary validation from NMPA filing databases, GB standards documentation, and customs/trade flow records. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates across the analysis window.
Forecast assumptions held fixed the current SAMR enforcement trajectory for GB 1886 purity mandates while varying corn feedstock price scenarios and CODEX reciprocity negotiation outcomes. Segmentation dimensions modeled include acidulant chemistry type, application intensity across beverages and bakery, delivery format preference between liquid and powder, and end-user procurement scale from direct contracts to distributor networks. CAGRs derived from fermentation yield improvement curves and regulatory compliance cost trajectories, with carbon intensity benchmarking and clean-label adoption velocity as industry-specific forecast inputs.
Sensitivities concentrate around NMPA certification timeline extensions, corn starch price volatility from Jilin harvest cycles, and CODEX alignment delays blocking Southeast Asian export pathways. Quarterly review of SAMR enforcement bulletins, MEE dual carbon benchmark updates, and NMPA pharmaceutical-grade approval queues is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
South America Food Enzymes Market
Food Additives and Ingredients
Sunset Yellow FCF Market
Food Additives and Ingredients
Bulking Agents Market
Food Additives and Ingredients
Starch-Based Edible Coatings Market
Food Additives and Ingredients
Acetylated Distarch Phosphate Market
Food Additives and Ingredients
Europe Clean Label Ingredient Market
Food Additives and Ingredients
Natural Solubilizers Market
Food Additives and Ingredients
Food and Beverages Color Fixing Agents Market
Food Additives and Ingredients
Mediterranean Sourdough Starter Cultures Market
Food Additives and Ingredients
Carob Gum Market
Food Additives and Ingredients
China Emulsifiers Market
Food Additives and Ingredients
Food Grade Magnesium Derivatives Market
Food Additives and Ingredients
Methyl Oleate Market
Food Additives and Ingredients
Global Natamycin Market