
 Bakery Enzymes Market | 2026-2036
Bakery Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Bakery Enzymes Market Analysis
A shortage of trained enzymologists in Western Europe is unwinding capacity expansion plans at several specialty ingredient houses. Novozymes A/S leverages its Copenhagen-based fermentation expertise to dominate microbial amylase supply. DSM-Firmenich anchors its position through integrated biotechnology platforms spanning enzyme and vitamin production. AB Enzymes GmbH specializes in fungal enzyme systems for craft bakeries across Central Europe.
Bakery enzymes are protein-based biocatalysts, typically derived from microbial fermentation or fungal cultures, that accelerate dough conditioning, extend shelf life, and replace chemical additives in baked goods. These catalysts operate at specific temperature and pH ranges, with fungal amylases activating between 50-70°C to modify starch structure for improved crumb softness. Amylase formulations command the largest volume share due to their bread-making ubiquity, though lipase adoption is accelerating fastest among clean-label pastry producers seeking emulsification without synthetic additives. Protease applications remain concentrated in cracker and biscuit manufacturing where gluten modification controls texture and reduces mixing energy.
EFSA and FDA both enforce strict allergen labeling and GRAS certification requirements that determine which enzyme preparations enter commercial bakery supply chains. REACH compliance in Europe and EPA oversight of microbial strain safety in the United States create divergent approval timelines that fragment product portfolios by geography. Stakeholders must monitor evolving enzyme classification debates between food additive and processing aid designations, as regulatory reclassification would trigger reformulation costs and label changes across multiple jurisdictions.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing formulation timelines for clean-label bakery enzymes, forcing specialty ingredient houses to accelerate microbial strain development and relocate fermentation capacity toward renewable energy clusters.
Growth Catalysts
- Clean-label mandates:The EU Green Deal drives replacement of chemical emulsifiers with lipase enzymes in premium pastry applications across Germany and France.
- Artisan bakery expansion:Craft bread producers in Hamburg and Frankfurt are adopting fungal amylase systems to standardize crumb texture without additives.
- Fermentation platform advances:Copenhagen-based biotechnology clusters are scaling microbial amylase output through continuous bioprocessing.
Market Restraints
- Input cost volatility:Specialized fungal culture media prices fluctuate with agricultural substrate markets, squeezing margin structures for enzyme formulators.
- Supply concentration risk:Western European enzymologist talent pools cluster around Denmark and southern Germany, creating hiring bottlenecks for capacity expansion.
- Regulatory friction:Divergent EFSA and FDA classification timelines for novel microbial strains fragment product portfolios and delay commercialization.
Strategic Opportunities
- Eastern European underpenetration:Polish and Romanian industrial bakeries remain below Western European enzyme adoption rates, offering volume expansion potential.
- Enzyme-vitamin convergence:Integrated biotechnology platforms can bundle dough conditioning enzymes with fortification ingredients for co-manufacturing contracts.
- Direct distribution channels:Specialty ingredient houses are bypassing traditional distributors to supply craft bakeries through digital procurement portals.
Industry Challenges
- Enzymologist scarcity:Trained fermentation specialists are concentrated at Copenhagen and Frankfurt research clusters, forcing competitors to poach talent or outsource strain development.
- GRAS certification timelines:Novel microbial amylase preparations face 18-24 month FDA safety reviews that compress product launch windows.
- Legacy equipment integration:Central European craft bakeries operate decades-old mixing systems that require enzyme dosage recalibration for optimal performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakery Enzymes Market |
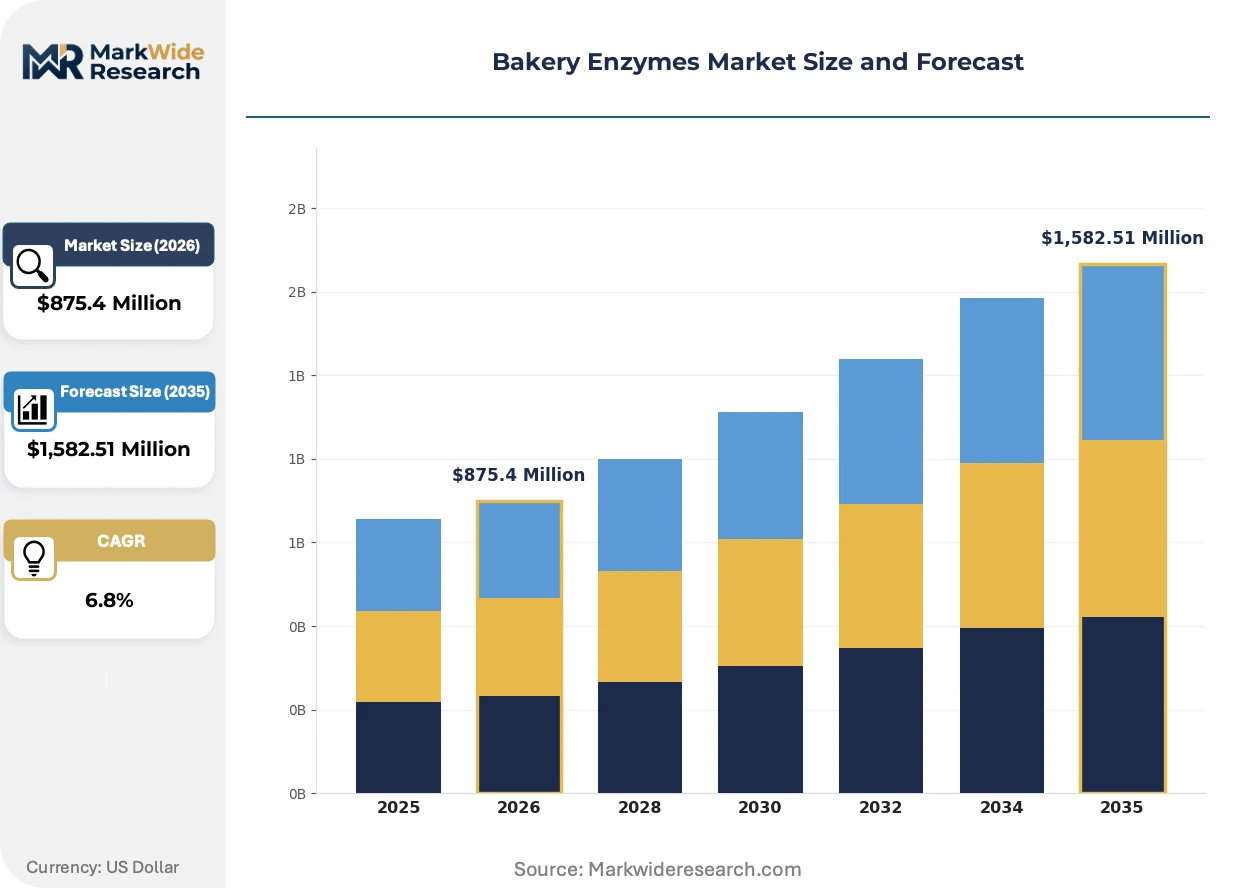
| Market Size in 2026 | $875.4 Million |
| Market Size in 2035 | $1,582.51 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Lipase, Protease, Glucose Oxidase Application: Bread, Pastries, Cookies, Pizza Dough End User: Bakeries, Food Manufactures, Retailers, Restaurants Distribution Channel: Online, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Novozymes A/S, DSM-Firmenich, AB Enzymes GmbH, International Flavors & Fragrances Inc., Kerry Group plc, Amano Enzyme Inc., Associated British Foods plc, BASF SE, Corbion N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakery Enzymes Market Emerging Trajectories
Biotechnology platforms are fragmenting the competitive landscape as integrated producers bundle enzymes with adjacent ingredients, while regulatory pressure accelerates strain development cycles and procurement patterns shift toward direct supplier relationships.
Precision fermentation for microbial amylase production is bifurcating the supply base. Continuous bioprocessing systems reduce batch-to-batch variability for industrial bakeries demanding consistent dough conditioning. Copenhagen-based facilities now supply standardized fungal enzyme concentrates that displace traditional batch fermentation for high-volume bread manufacturers.
REACH compliance deadlines for novel microbial strains are compressing R&D timelines across European enzyme houses. The F-Gas Regulation's phase-down of synthetic refrigerants forces fermentation facilities to retrofit cooling systems or relocate to districts with district heating infrastructure. German industrial bakeries are prioritizing suppliers with verified renewable energy certificates in their vendor scorecards.
Ingredient procurement is consolidating through digital platforms that connect craft bakeries directly to enzyme formulators. Traditional distributors in Hamburg and Frankfurt are losing share to specialized e-procurement channels offering technical dosing support. Artisan bread producers now specify enzyme blends through online configurators rather than relying on distributor recommendations.
Bakery Enzymes Market Segmentation
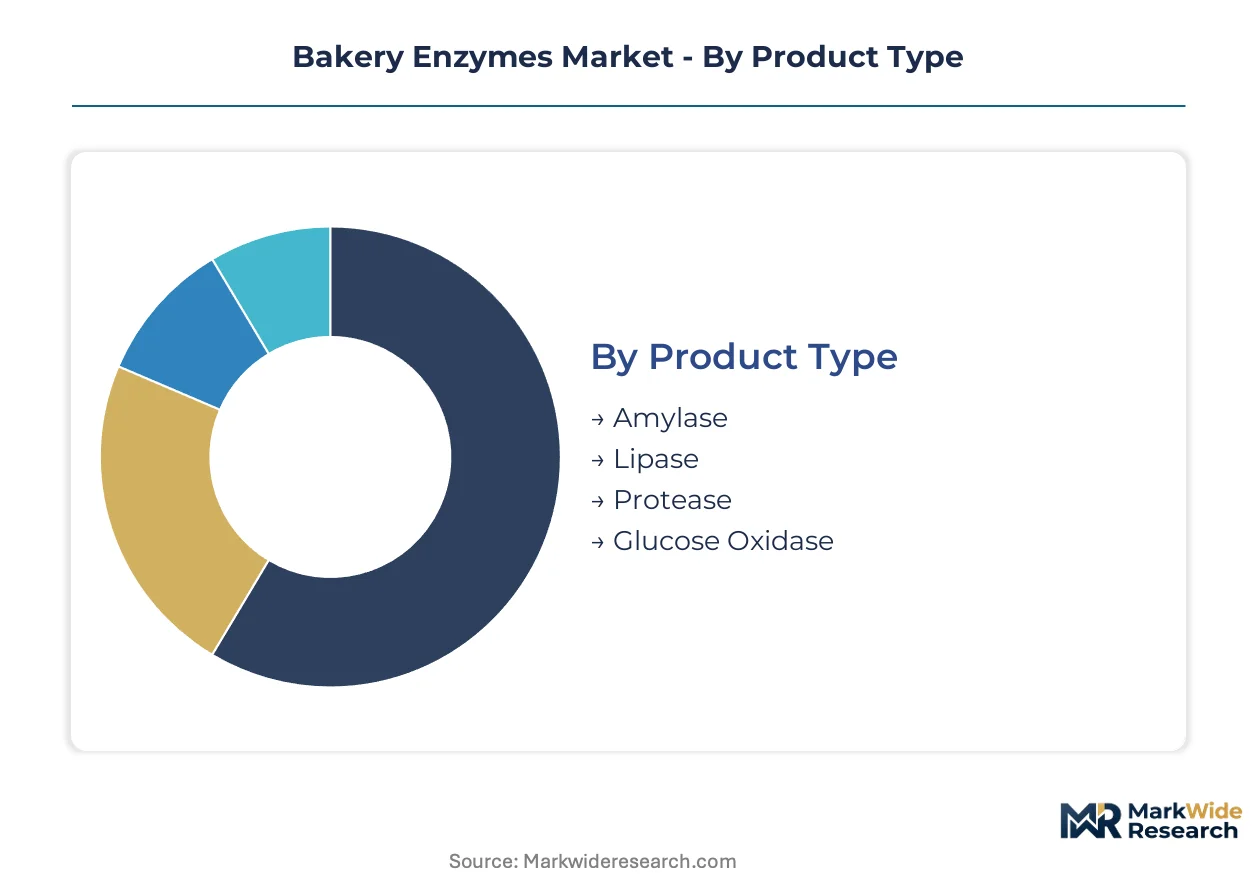
Bakery enzyme procurement varies sharply by segment, with industrial bread manufacturers prioritizing bulk amylase contracts while craft pastry producers seek specialized lipase formulations through direct channels. Understanding these segment boundaries clarifies where formulation investments concentrate and which distribution pathways command margin premiums.
Product Type:
Amylase and lipase formulations dominate export-led supply chains serving multinational bread manufacturers, while protease and glucose oxidase shipments remain concentrated in domestic craft bakery clusters across Germany and France.
- Amylase:Fungal and bacterial amylase preparations hydrolyze starch molecules to improve crumb softness and extend shelf life in packaged bread. Demand concentrates in Hamburg and Frankfurt industrial bakery corridors where continuous mixing operations require standardized dough conditioning at scale.
- Lipase:These enzymes catalyze lipid hydrolysis to generate natural emulsifiers, replacing DATEM and SSL in clean-label pastry applications. French premium croissant manufacturers in the Ile-de-France region drive adoption fastest as EFSA scrutiny intensifies on synthetic additive approvals.
- Protease:Gluten-modifying enzymes reduce mixing energy requirements and control extensibility in cracker and biscuit production lines.
- Glucose Oxidase:This oxidoreductase strengthens gluten networks in frozen dough applications, particularly among pizza chain suppliers.
Amylase holds the largest share; momentum sits with lipase as clean-label mandates tighten across EU member states.
Application:
Cost tiering separates commodity bread enzymes from premium pastry formulations, with price differentials reflecting fermentation complexity and dosage precision requirements.
- Bread:Industrial pan bread and artisan loaf production consumes the highest enzyme volumes, with fungal amylase systems standardizing crumb structure across high-speed lines.
- Pastries:Danish, croissant, and puff pastry applications demand lipase-dominated formulations for fat stabilization without chemical emulsifiers. German premium bakery chains in Bavaria specify these blends for clean-label positioning against discounter competition.
- Cookies:Protease-treated doughs enable precise texture control in shortbread and biscuit manufacturing where gluten network modification determines snap and mouthfeel.
- Pizza Dough:Frozen pizza manufacturers rely on glucose oxidase and amylase combinations to maintain dough integrity through freeze-thaw cycles.
Bread commands volume leadership; pastries are climbing the fastest as premiumization accelerates in France and Germany.
End User:
Customer type determines technical service intensity, with food manufacturers requiring integrated biotechnology platforms while restaurants prioritize single-enzyme convenience formats.
- Bakeries:Industrial and craft bread producers constitute the core demand base, with Hamburg-area facilities sourcing through direct procurement portals. These buyers specify enzyme blends by dough rheology targets rather than generic product codes.
- Food Manufacturers:Integrated snack and frozen dough producers bundle enzyme procurement with vitamin fortification contracts, favoring suppliers with Copenhagen-based fermentation platforms.
- Retailers:Private-label bakery program managers source enzyme systems through consolidated ingredient distributors.
- Restaurants:Chain pizza and bakery-cafe operators purchase pre-calibrated enzyme packets for in-house dough preparation.
Food manufacturers hold the largest share; momentum sits with bakeries as digital procurement disintermediates traditional distributors.
Distribution Channel:
Supply concentration in Denmark and southern Germany shapes channel viability, with proximity to fermentation clusters determining direct sales economics versus distributor markup requirements.
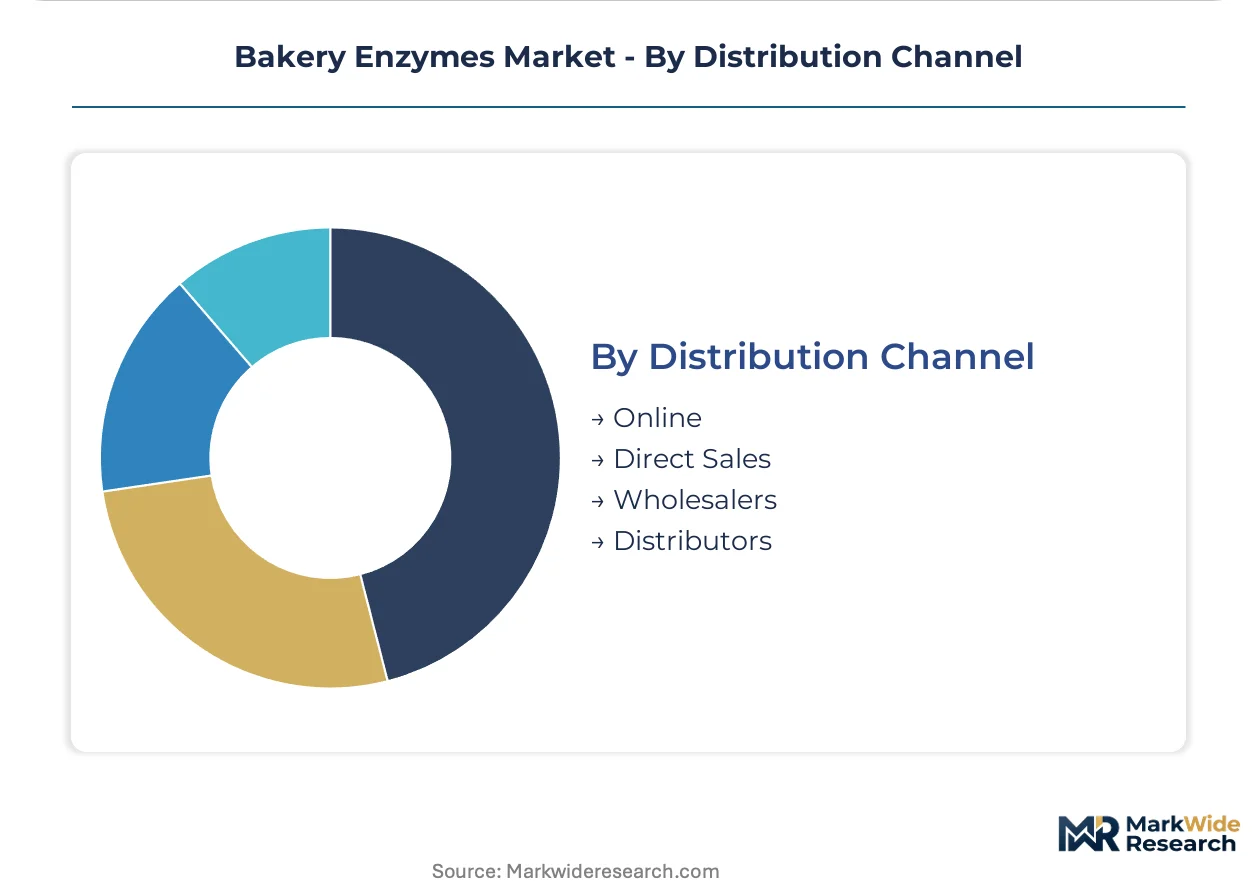
- Online:Digital procurement portals now connect craft bakeries directly to enzyme formulators, displacing traditional Hamburg and Frankfurt distributors. These platforms embed dosing calculators and technical support chat functions.
- Direct Sales:Large industrial bakeries negotiate annual contracts with Novozymes A/S and DSM-Firmenich for customized amylase formulations. Copenhagen-based technical teams provide on-site fermentation optimization.
- Wholesalers:Regional ingredient wholesalers stock standard enzyme concentrates for mid-sized bakeries without volume thresholds for direct supply.
- Distributors:Traditional food ingredient distributors retain share in Eastern European markets where digital procurement infrastructure remains underdeveloped.
Direct sales hold the largest share; online channels are gaining share fastest as artisan bakeries bypass intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes bakery enzymes at industrial scale for standardized bread production, while France and Italy concentrate demand in premium pastry applications requiring clean-label emulsification systems.
Germany
Industrial bakeries in Hamburg and Frankfurt corridors drive bulk amylase procurement for high-speed pan bread lines. The EU Green Deal accelerates chemical emulsifier replacement with lipase enzymes in Bavarian premium bakery chains. Berlin-Brandenburg facilities retrofit fermentation cooling systems to comply with F-Gas Regulation phase-down timelines.
France
Premium croissant manufacturers in Île-de-France dominate lipase adoption for DATEM-free fat stabilization. EFSA scrutiny on synthetic additive approvals tightens formulation requirements across Auvergne-Rhône-Alpes industrial zones. Provence-Alpes-Côte d'Azur artisan bakeries source specialized enzyme blends through digital procurement portals bypassing traditional distributors.
Italy
Specialty pasta and frozen dough producers in Lombardy integrate glucose oxidase for gluten network strengthening through freeze-thaw cycles. REACH compliance deadlines compress R&D timelines for novel microbial strains at Emilia-Romagna biotechnology clusters. Piedmont-based ingredient distributors lose share to direct supplier relationships with enzyme formulators.
United States
Frozen pizza manufacturers rely on amylase-glucose oxidase combinations for dough integrity in Chicago and Midwest production hubs. FDA GRAS certification timelines extend 18-24 months for novel microbial amylase preparations. EPA oversight of microbial strain safety fragments product portfolios versus European approval pathways.
Denmark
Copenhagen-based fermentation platforms anchor microbial amylase supply for export-led industrial bakery contracts. Continuous bioprocessing systems reduce batch-to-batch variability for high-volume bread manufacturers. Zealand-region facilities leverage district heating infrastructure to meet renewable energy certificate requirements from German vendor scorecards.
Bakery Enzymes Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with biotechnology platforms bundling enzymes with adjacent ingredients while regional formulators compete on technical service intensity. Consolidation concentrates around Copenhagen and southern Germany fermentation clusters. Three archetypes dominate: integrated biotechnology conglomerates with vitamin-enzyme convergence capabilities, fungal enzyme specialists serving craft bakery segments, and diversified ingredient houses leveraging distribution scale. Competitive moves center on M&A for fermentation capacity and strategic partnerships for direct digital procurement channels.
Among Northern European integrated leaders, Novozymes A/S and DSM-Firmenich exemplify the biotechnology platform archetype, while AB Enzymes GmbH represents the specialist tier focused on fungal enzyme systems. Novozymes A/S occupies a position anchored in Copenhagen-based fermentation expertise, DSM-Firmenich sits within the diversified life sciences conglomerate structure, and AB Enzymes GmbH exemplifies the regional specialist model concentrated in Central European craft bakery supply.
| Leading Market Players |
|---|
| Novozymes A/S |
| DSM-Firmenich |
| AB Enzymes GmbH |
| International Flavors & Fragrances Inc. |
| Kerry Group plc |
| Amano Enzyme Inc. |
| Associated British Foods plc |
| BASF SE |
| Corbion N.V. |
| Others |
Supply Flow & Price Mechanics
REACH compliance deadlines for novel microbial strains gate both supplier qualification and price tiering simultaneously, forcing enzyme houses to amortize certification costs across premium formulations while spot-market buyers absorb residual regulatory risk.
Pricing Analysis
Long-term offtake contracts dominate industrial bakery procurement, with annual volume commitments securing fungal amylase supply at standardized rates. Price differentiation rests on GRAS certification tier and fermentation platform scale, with Copenhagen-based producers commanding premiums over regional formulators. Cost compression in commodity amylase grades is intensifying because substrate volatility squeezes margin structures. Industrial bread manufacturers exhibit highest price sensitivity, while premium pastry producers prioritize clean-label positioning over unit economics.
Supply Chain Analysis
Denmark and Germany anchor microbial fermentation capacity, with Copenhagen facilities supplying standardized concentrates and southern German clusters serving craft bakery customization demands. Raw material dependencies draw from agricultural substrate markets, specialized fungal culture media, and renewable energy certificates. Single-source vulnerability concentrates around Denmark-based enzymologist talent pools. Distribution runs through direct sales channels for industrial accounts and digital procurement portals for artisan producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where GRAS certification timelines and REACH compliance costs create structural barriers that protect incumbent fermentation platforms from rapid competitive displacement.
For Market Incumbents: Secure enzymologist talent pools through Copenhagen and Frankfurt research cluster partnerships, insulating proprietary strain development from poaching cycles. Deepen backward integration into agricultural substrate supply to buffer margin compression from commodity volatility. The priority lever sits with renewable energy certification investments that satisfy German vendor scorecard requirements. For New Entrants and Emerging Players: Anchor in Polish and Romanian industrial bakery corridors where enzyme adoption rates trail Western European benchmarks. White-space concentration appears in lipase formulations for clean-label pastry applications, where EFSA scrutiny on synthetic additives accelerates substitution demand. A direct digital procurement channel with embedded dosing support functions offers the clearest go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty ingredient houses possessing Copenhagen-adjacent fermentation infrastructure but lacking integrated vitamin-enzyme bundling capabilities. The five-to-ten year viability window favors platforms with verified renewable energy certificates and established GRAS dossiers. Watch for FDA-EU regulatory harmonization signals as inflection indicators that would compress novel strain commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Copenhagen-based facilities scale continuous bioprocessing to reduce batch variability for industrial bread contracts. |
| Renewable Energy Certification | German vendor scorecards now require verified certificates, forcing facility retrofits or relocations to district heating zones. |
| Direct Digital Procurement Channel | Specialized portals displace Hamburg distributors by embedding technical dosing calculators for craft bakery buyers. |
| Novel Microbial Strain Development | REACH compliance deadlines compress R&D cycles, favoring houses with established regulatory affairs infrastructure. |
| Enzyme-Vitamin Bundling Platform | Integrated biotechnology contracts attract food manufacturers seeking consolidated fortification and conditioning supply. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with fermentation platform directors, regulatory affairs specialists at enzyme houses, procurement managers at industrial bakeries, and craft bakery operations heads; and secondary validation through EFSA additive approval databases, FDA GRAS notification filings, REACH registration dossiers, and customs trade flow records. Bottom-up volume estimates triangulated against top-down market sizing.
Across the analysis window, the forecasting framework modeled product type, application, end-user category, and distribution channel dimensions. CAGRs derived from segment-level growth rate reconciliation against macro bakery production indices and enzyme penetration assumptions. Industry-specific inputs included EFSA regulatory timeline probabilities and renewable energy certificate adoption curves in German vendor qualification data.
Material uncertainties — regulatory reclassification of enzymes as food additives rather than processing aids, strain safety review delays, and agricultural substrate price shocks — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification pathway efficiency and clean-label mandate enforcement intensity. Recalibration cycles align with material shifts in EFSA additive approval schedules and EU Green Deal implementation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Russia Food Enzymes Market
Food Additives and Ingredients
Pea Starch Concentrate Market
Food Additives and Ingredients
Carrageenan Gum Market
Food Additives and Ingredients
Monostarch Phosphate Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
Australia Food Preservatives Market
Food Additives and Ingredients
Caramel Food Colors Market
Food Additives and Ingredients
Europe Food Acidulants Market
Food Additives and Ingredients
Global Crystalline Maltitol Market
Food Additives and Ingredients
North America Food Starch Market
Food Additives and Ingredients
South America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Food Texturing Agents Market
Food Additives and Ingredients
Food Grade Glycerin Market
Food Additives and Ingredients
Global Lactase Market
Food Additives and Ingredients
Africa Food Emulsifiers Market
Food Additives and Ingredients
Cake Enzyme Market